
 Foaming Creamer Market | 2026-2036
Foaming Creamer Market Size, Share, and Industry Trends Forecast 2026-2036
Foaming Creamer Market Analysis
The EU Green Deal is restructuring formulation priorities across the foaming creamer supply base, compelling suppliers to eliminate palm oil derivatives and synthetic emulsifiers from standard recipes. Mokate Group leverages its Central European manufacturing footprint to supply reformulated, plant-based foaming systems to branded coffee chains. Royal FrieslandCampina N.V. anchors its position through backward integration into dairy protein streams, securing consistent foaming stability across temperature variations. Custom Food Group specializes in spray-dried lipid systems for Southeast Asian instant coffee manufacturers, competing on cost-adjusted performance metrics.
Foaming creamer denotes a spray-dried or liquid lipid-protein emulsion engineered to generate stable microfoam when agitated with hot or cold aqueous solutions, typically containing 35-50% vegetable fat, glucose syrup solids, and sodium caseinate or plant protein isolates. Its primary commercial purpose is to replicate the sensory and visual properties of dairy foam in non-dairy or hybrid coffee and beverage applications. Powdered creamer dominates volume throughput in emerging markets due to extended shelf stability and lower logistics costs, while liquid creamer captures premium placement in chained café environments where equipment integration and pour consistency matter. Non-dairy creamer is accelerating fastest as lactose intolerance prevalence and vegan positioning reshape menu development across Asian and European food service channels.
FDA oversight of GRAS self-affirmations and labeling requirements shapes U.S. market entry for novel protein bases and emulsifier blends, while EFSA and REACH compliance in Europe enforce strict thresholds on residual solvents and allergen declarations in spray-dried formulations. BIS standards in India mandate fat content disclosures that influence local procurement specifications for hotel and restaurant supply contracts. Stakeholders must monitor evolving protein diversification strategies—pea, oat, and chickpea isolates—as these raw material shifts will determine which suppliers retain formulation partnerships with major beverage brands.
Market Dynamics
Clean-label regulatory mandates from the EU Green Deal are dismantling legacy hydrogenated oil formulations, forcing manufacturers to rebuild emulsion architectures around plant-based lipid systems and natural stabilizers.
Growth Catalysts
- EU Green Deal compliance deadlines:Reformulation mandates are pulling investment into palm-free lipid sourcing and clean-label emulsifier development.
- Southeast Asian café expansion:Specialty coffee chains in Indonesia, Vietnam, and Thailand are scaling cold-foam beverage menus that require high-performance foaming creamers.
- Spray-dried protein stabilization:Advances in sodium caseinate and pea protein encapsulation are extending foam stability across temperature variations in instant coffee applications.
Market Restraints
- Palm oil price volatility:Reformulation away from hydrogenated oils has concentrated demand on coconut and shea butter alternatives, exposing margins to tropical commodity swings.
- EU supply concentration:REACH-compliant spray-drying capacity clusters in Germany and Poland, creating bottlenecks for clean-label volume scaling.
- Technical foam decay:Plant-based emulsifiers currently deliver 15-30% shorter foam persistence than dairy-caseinate benchmarks in cold applications.
Strategic Opportunities
- Indonesia domestic processing:Local dairy and lipid processing infrastructure expansion creates captive supply opportunities for ASEAN-market formulations.
- Chickpea protein convergence:Blending chickpea isolates with oat protein is opening neutral-flavor foaming systems for vegan-positioned beverage brands.
- Direct-to-café distribution:Liquid creamer equipment-lease programs are bypassing traditional foodservice distributors in chained coffee environments.
Industry Challenges
- Emulsion chemistry talent scarcity:Formulation expertise spanning lipid-protein interactions and spray-drying physics concentrates in aging technical workforces at European suppliers.
- GRAS self-affirmation timelines:FDA novel protein notifications for pea and oat isolates are extending market entry schedules by 18-24 months.
- Legacy equipment retrofit costs:Cold-foam dispensing systems require reconfigured storage and handling infrastructure incompatible with standard hot-beverage setups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foaming Creamer Market |
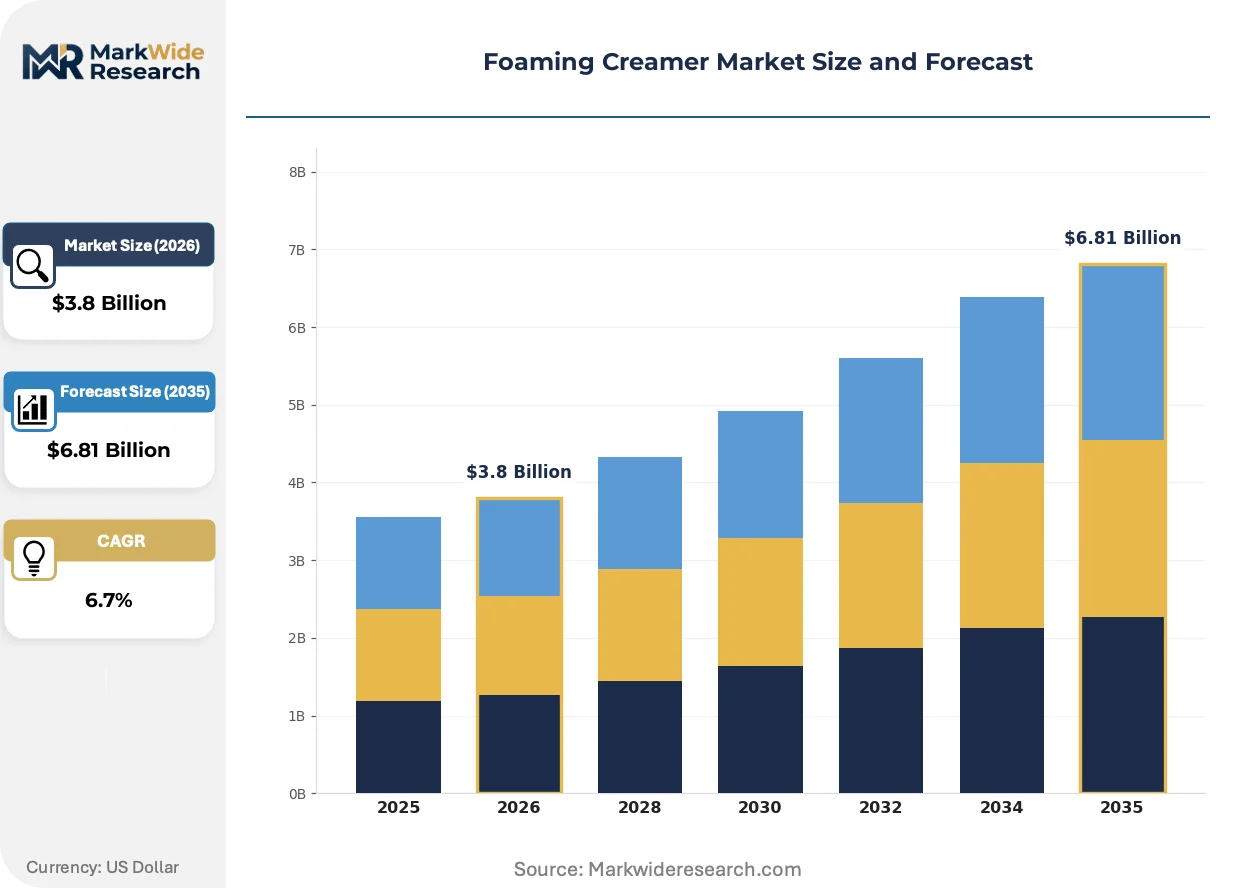
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Creamer, Liquid Creamer, Non-Dairy Creamer, Specialty Creamer End User: Cafes, Restaurants, Hotels, Households Usage Occasion: Coffee, Dessert, Baking, Beverages Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Food Service |
| Companies Covered | Mokate Group, Santho Holland Food BV, Royal FrieslandCampina N.V., Viceroy Holland B.V., Custom Food Group, Molkerei MEGGLE Wasserburg GmbH & Co.KG, Super Group Ltd., FrieslandCampina Kievit, PT Lautan Natural Krimerindo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foaming Creamer Market Emerging Trajectories
Formulation science is pivoting toward protein-lipid architectures that deliver dairy-equivalent foam performance without hydrogenated oils or synthetic emulsifiers. This shift is compressing traditional supply relationships and redrawing competitive boundaries.
Microencapsulation technology for plant protein isolates is modularizing across the supplier base. European ingredient houses are adopting twin-screw extrusion and fluidized bed coating systems to protect protein functionality through spray-drying heat exposure. The technology is modularizing supply chains by enabling regional toll manufacturers to enter clean-label foaming creamer production without captive R&D infrastructure.
REACH enforcement on residual solvent thresholds is tightening specification windows for spray-dried lipid carriers. ECHA monitoring of hexane and acetone traces in vegetable oil processing is forcing reformulation of standard glucose syrup solid carriers. European instant coffee manufacturers are responding by qualifying alternative carriers like maltodextrin blends that maintain powder flowability while meeting residual limits.
Café procurement patterns are compressing supplier qualification cycles from multi-year frameworks to annual performance reviews. Chained coffee operators in Southeast Asia are unbundling equipment, creamer supply, and technical service into separate vendor relationships. Indonesia and Vietnam represent the most visible markets for this disaggregation, with domestic brands leveraging local manufacturing partnerships to displace integrated multinational supply contracts.
Foaming Creamer Market Segmentation
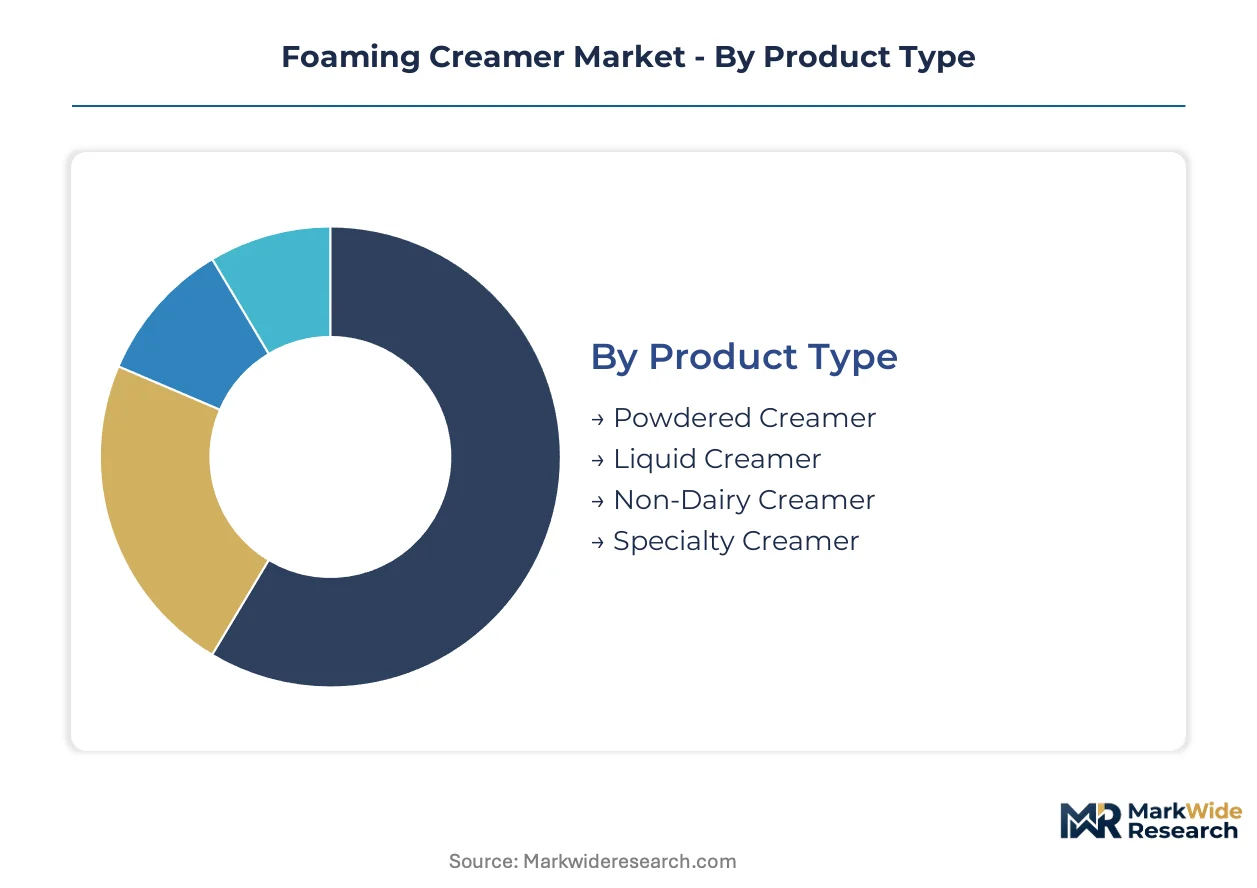
Foaming creamer segmentation reflects divergent supply chain economics across powder versus liquid formats, while end-use fragmentation forces manufacturers to balance foodservice scale against retail margin complexity. Category boundaries are blurring as plant-based reformulation and clean-label mandates reshape traditional product definitions.
Product Type:
Supply concentration clusters around spray-dried powder capacity in Germany and Poland, with liquid formulation expertise concentrating in Dutch and Belgian dairy processing corridors.
- Powdered Creamer:Spray-dried lipid-protein emulsions containing 35-50% vegetable fat, glucose syrup solids, and sodium caseinate. Demand concentrates in Indonesia and Vietnam where instant coffee manufacturers prioritize shelf stability and containerized logistics efficiency over cold-chain infrastructure.
- Liquid Creamer:Aseptically packaged emulsions with integrated foaming systems for chained café dispensing equipment. European specialty coffee operators in Amsterdam and Berlin are scaling cold-foam menu applications that require temperature-stable liquid formats incompatible with powder reconstitution.
- Non-Dairy Creamer:Plant-protein formulations using pea, oat, or chickpea isolates replacing sodium caseinate. Clean-label positioning accelerates fastest in German and French retail channels under EU Green Deal reformulation deadlines.
- Specialty Creamer:High-performance foaming systems with microencapsulated proteins for artisanal beverage applications. Premium placement in Scandinavian café chains drives specification development.
Today's leader: Powdered Creamer. Tomorrow's challenger: Non-Dairy Creamer.
End User:
Margin tiering separates equipment-integrated supply contracts from commodity wholesale, with hospitality procurement consolidating around performance-based annual reviews rather than multi-year frameworks.
- Cafes:Chained coffee operators in Jakarta, Bangkok, and Ho Chi Minh City are unbundling equipment, creamer supply, and technical service into separate vendor relationships. Cold-foam menu expansion creates specification pressure for 30-second foam stability benchmarks.
- Restaurants:Full-service dining in European capitals adopts liquid creamer for dessert plating and beverage finishing. REACH-compliant spray-dried alternatives face substitution pressure from fresh dairy in premium positioning.
- Hotels:In-room coffee service and breakfast buffet operations in Indonesian resort corridors drive bulk powder procurement. BIS fat content disclosure mandates shape Indian hotel supply contract specifications.
- Households:Retail shelf-stable formats dominate Southeast Asian supermarket penetration. E-commerce direct-to-consumer trials in European urban markets test subscription-based liquid creamer logistics.
Cafes command volume concentration. Households offer the steepest expansion trajectory.
Usage Occasion:
Application diversification is stretching formulation portfolios beyond traditional coffee adjacency into dessert and baking verticals with distinct emulsion stability requirements.
- Coffee:Primary application spanning instant, espresso, and cold-foam preparations. Indonesian domestic brands leverage local manufacturing partnerships to displace integrated multinational supply contracts in instant coffee.
- Dessert:Foamed cream toppings for pastry and plated applications. European artisanal producers specify non-dairy alternatives for vegan menu positioning.
- Baking:Fat and protein enrichment in commercial bakery formulations. Powdered formats dominate industrial scale procurement.
- Beverages:Expansion into tea, cocoa, and functional drink categories. Chained operators in Thai and Vietnamese markets test cross-category foam standardization.
Coffee anchors current revenue. Dessert applications are gaining share fastest.
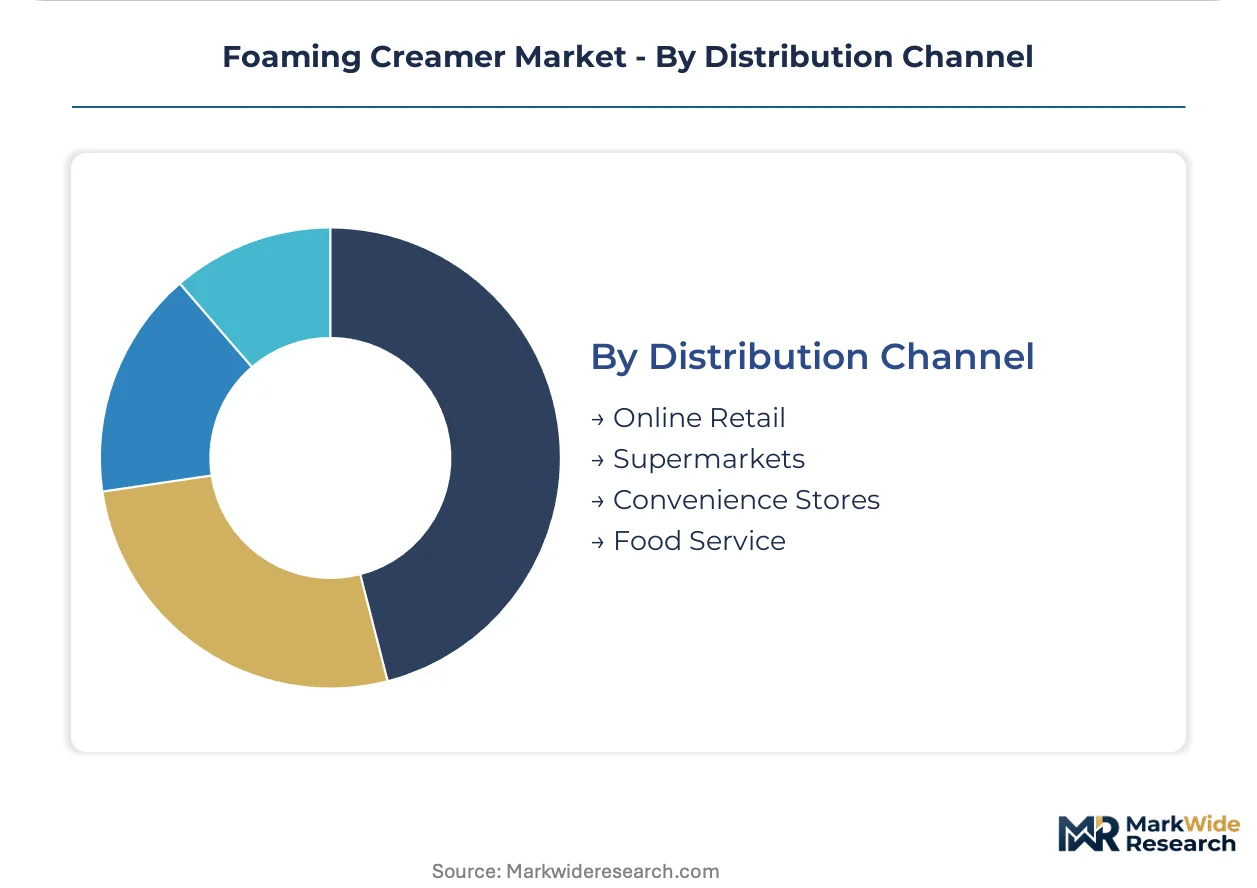
Distribution Channel:
Channel fragmentation reflects divergent service intensity requirements, with foodservice demanding technical integration while retail prioritizes shelf-turn velocity.
- Online Retail:Direct-to-consumer subscription models test liquid creamer cold-chain logistics in European urban corridors. Platform algorithms favor clean-label certification badges in search ranking.
- Supermarkets:Mass retail placement in Indonesian and Vietnamese cities concentrates powdered creamer volume. Private label penetration pressures branded margin structures.
- Convenience Stores:Grab-and-go single-serve formats for immediate consumption. Urban density in Jakarta and Manila drives cooler placement investment.
- Food Service:Equipment-lease programs bypass traditional distributors in chained coffee environments. Technical service bundling creates vendor stickiness.
Food Service leads contract value. Online Retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The foaming creamer industry traces its commercial origins to Dutch dairy processing corridors, where spray-drying technology for lipid-protein emulsions first achieved industrial scale in the mid-twentieth century. European formulation expertise subsequently diffused to Southeast Asian markets, where instant coffee culture created volume demand for shelf-stable powdered formats. Today, regulatory divergence between EU clean-label mandates and ASEAN café expansion is redrawing regional supply priorities.
Germany
REACH-compliant spray-drying capacity clusters in North Rhine-Westphalia and Lower Saxony, serving reformulation demand from EU Green Deal deadlines. ECHA enforcement on residual solvent thresholds in vegetable oil processing is forcing maltodextrin carrier substitutions in standard glucose syrup solid formulations. The Cologne-Düsseldorf industrial corridor anchors clean-label emulsifier development for branded coffee chains.
Netherlands
Liquid creamer formulation expertise concentrates in Dutch dairy processing corridors, supplying temperature-stable foaming systems for European specialty café cold-foam menus. EFSA allergen declaration requirements shape specification windows for spray-dried exports to Asian markets. FrieslandCampina Kievit and Viceroy Holland B.V. occupy positions within the Rotterdam-Antwerp chemical processing cluster.
Indonesia
Domestic dairy and lipid processing infrastructure expansion in Java and Sumatra is accelerating captive supply opportunities for ASEAN-market formulations. BIS fat content disclosure mandates influence cross-border procurement specifications for hotel and restaurant supply contracts. Jakarta and Surabaya café chains are unbundling equipment, creamer supply, and technical service into separate vendor relationships.
Vietnam
Instant coffee manufacturers in the Central Highlands prioritize powdered creamer volume for containerized logistics efficiency over cold-chain infrastructure. Local brand development is displacing integrated multinational supply contracts through domestic manufacturing partnerships. Ho Chi Minh City specialty coffee operators are scaling cold-foam beverage menus requiring high-performance foaming formulations.
Poland
Central European manufacturing footprints leverage proximity to German formulation R&D while maintaining cost-adjusted production economics for export markets. Mokate Group exemplifies this positioning, supplying reformulated plant-based foaming systems from Silesian production assets. EU Green Deal compliance timelines are pulling investment into palm-free lipid sourcing and clean-label emulsifier development.
Foaming Creamer Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory compliance capability. The vendor base stratifies between integrated dairy processors with backward protein control, specialized spray-dried lipid houses, and regional toll manufacturers adopting modular microencapsulation technology. Three archetypes dominate: European clean-label specialists, Southeast Asian cost-optimized formulators, and multinational dairy cooperatives with captive ingredient streams. Competitive moves concentrate on geographic licensing partnerships and equipment-lease program expansion in chained café channels.
Within the European clean-label tier, Mokate Group and Royal FrieslandCampina N.V. occupy anchor positions. Santho Holland Food B.V. and Viceroy Holland B.V. exemplify Dutch liquid creamer specialization. Custom Food Group and Super Group Ltd. represent Southeast Asian cost-adjusted performance competitors. Molkerei MEGGLE Wasserburg GmbH & Co.KG anchors German dairy-protein backward integration. PT Lautan Natural Krimerindo exemplifies Indonesian domestic brand development leveraging local processing infrastructure.
| Leading Market Players |
|---|
| Mokate Group |
| Santho Holland Food BV |
| Royal FrieslandCampina N.V. |
| Viceroy Holland B.V. |
| Custom Food Group |
| Molkerei MEGGLE Wasserburg GmbH & Co.KG |
| Super Group Ltd. |
| FrieslandCampina Kievit |
| PT Lautan Natural Krimerindo |
| Others |
Supply Flow & Price Mechanics
Microencapsulation technology for plant protein isolates simultaneously compresses production costs and fragments supplier concentration by enabling regional toll manufacturers to enter clean-label foaming creamer production without captive R&D infrastructure. This modularization of spray-drying capability redistributes pricing power from integrated European specialists toward cost-optimized ASEAN formulators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates equipment-integrated specialty formulations from commodity powdered alternatives. Price differentiation rests on clean-label certification grade and volume scale, with EU Green Deal-compliant reformulations commanding premiums over legacy hydrogenated oil recipes. Cost compression in economy-tier powdered creamers is intensifying because Indonesian domestic brands leverage local manufacturing partnerships to undercut multinational supply contracts. Small independent cafés in Southeast Asian cities exhibit highest price sensitivity, while chained European coffee operators prioritize foam stability benchmarks over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with REACH-compliant spray-drying capacity concentrated in Germany and Poland, creating bottlenecks for clean-label volume scaling. Raw material dependencies draw from coconut and shea butter alternatives substituting for palm oil derivatives, alongside sodium caseinate and emerging pea protein isolates. Supply chain risk centers on tropical commodity price volatility as reformulation concentrates demand on limited lipid alternatives. Distribution runs through equipment-lease programs in chained café environments, bypassing traditional foodservice distributors and creating direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The foaming creamer market functions as a stable compounder anchored by structural beverage menu expansion across Southeast Asian café chains. Regulatory reformulation mandates in Europe ensure sustained ingredient innovation demand.
For Market Incumbents: Acquire spray-dried lipid processing assets in Central Europe to secure REACH-compliant capacity ahead of EU Green Deal deadlines. Consolidate backward integration into dairy protein streams to defend against chickpea and oat protein substitution threats. Expand captive supply relationships with Indonesian domestic brands before local processing infrastructure matures. For New Entrants and Emerging Players: Artisanal dessert producers in Scandinavian and German urban markets represent an underserved buyer archetype seeking neutral-flavor vegan foaming systems. Penetrate through direct-to-café technical service partnerships rather than distributor relationships. Qualify chickpea-oat protein blends under EFSA allergen frameworks to unlock premium positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among regional toll manufacturers adopting modular microencapsulation technology without brand equity. Long-term viability over the next decade hinges on formulation chemistry talent retention and regulatory compliance capability. Monitor FDA GRAS self-affirmation timelines for novel protein bases as the inflection signal for plant-based segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Partnership | EU Green Deal deadlines force maltodextrin carrier substitutions in glucose syrup solid formulations. |
| Indonesia Domestic Processing Expansion | Java and Sumatra infrastructure builds captive supply for ASEAN-market powdered creamer demand. |
| Chickpea Protein Blend Development | EFSA-compliant neutral-flavor systems unlock vegan-positioned beverage brand partnerships. |
| Equipment-Lease Program Rollout | Cold-foam dispensing systems in Jakarta and Ho Chi Minh City bypass traditional distributors. |
| Backward Integration into Dairy Proteins | FrieslandCampina-style protein stream control secures foam stability across temperature variations. |
Methodological Framework
Coverage spans Europe, Southeast Asia, and North America, with primary inputs from each region combining structured interviews with spray-drying plant managers, procurement leads at instant coffee manufacturers, distribution channel partners, and technical R&D directors at emulsifier houses. Secondary validation draws from ECHA residual solvent monitoring reports, BIS fat content disclosure filings, FDA GRAS notification databases, and customs trade data on lipid-protein emulsion flows. Bottom-up volume modeling triangulates against top-down category spend analysis.
Rate-of-change decomposition separates volume growth from value mix shift across the projection horizon. The analytical framework models segmentation dimensions including product format, end-use channel, protein source type, and regional regulatory cluster. CAGRs derive from trend extrapolation of café menu expansion rates and reformulation investment cycles, cross-referenced with spray-drying capacity utilization and plant protein isolate qualification timelines.
Underlying measurement precision varies by segment; REACH-compliant clean-label formulations carry tighter precision than emerging economy-tier alternatives due to regulatory documentation density. Forecasts reflect assumptions on EU Green Deal enforcement timing and ASEAN café chain expansion rates. Palm oil price volatility and FDA novel protein notification delays constitute primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Premium Bottled Water Market
Beverages
Powdered Soft Drinks Market
Beverages
Dairy Based Beverages Market
Beverages
Plant-Based Energy Drink Market
Beverages
Nitro-Infused Beverages Market
Beverages
Apple Juice Concentrate Market
Beverages
Soft Serves Market
Beverages
Milk Tea Powder Market
Beverages
Flavored Powder Drinks Market
Beverages
Global Beverage Emulsion Market
Beverages
Crystal Boba Market
Beverages
Aloe Vera Drinks Market
Beverages
Carbonated Beverages Market
Beverages
North America Fruits and Vegetables Juice Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Fruit and Vegetable Juice Market