
 Italy Food Additives Market | 2026-2036
Italy Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Food Additives Market Foresight
The EU Green Deal is decoupling legacy additive portfolios from future market access by mandating pesticide reduction targets and stricter clean-label thresholds. Cargill Incorporated leverages its integrated supply chain across Italian sweetener and texturizer categories to sustain volume leadership in bakery and dairy applications. Kerry Inc. anchors its position through specialized taste and nutrition solutions tailored to Mediterranean flavor profiles, while Chr. Hansen Holding AS dominates the natural color and culture segments with fermentation-derived alternatives that bypass synthetic restrictions.
Food additives encompass substances added to food products to preserve flavor, enhance taste, improve visual appeal, or maintain safety and shelf stability through controlled pH, antioxidant activity, or emulsification at specified inclusion rates typically ranging from 0.01% to 2% by weight. Preservatives and natural color additives now command the strongest margin pools as Italian manufacturers reformulate away from synthetic benzoates and azo dyes under consumer and regulatory pressure. Emulsifiers in powder and liquid forms see accelerating demand from plant-based dairy alternatives and clean-label spreads, while flavor enhancers face slower growth as sodium reduction campaigns restrict MSG and yeast extract positioning in snacks and processed meats.
EFSA maintains centralized scientific assessments of additive safety across the EU, while Italy's Ministry of Health enforces national implementation through decrees that often exceed baseline European stringency, particularly for colorants in children's foods. The EU AI Act and broader digital compliance frameworks are beginning to shape traceability requirements for additive supply chains, forcing documentation upgrades. Stakeholders must monitor how the forthcoming revision of EU food additive legislation interacts with Italy's regional enforcement variations to anticipate reformulation costs and certification timelines.
Market Dynamics
The EU Green Deal and Farm to Fork Strategy are forcing additive reformulation across Italian pasta sauce, dairy, and ready-to-eat manufacturing clusters, compressing synthetic preservative tolerances and accelerating clean-label migration timelines.
Growth Catalysts
- EFSA threshold tightening:Stricter scientific assessments of synthetic colorants and preservatives are pushing Italian manufacturers toward fermentation-derived alternatives, expanding the addressable market for natural substitutes.
- Plant-based dairy expansion:Emulsifier demand from oat and almond milk production lines in Lombardy is pulling clean-label stabilizer volumes upward.
- Emilia-Romagna processing concentration:Dense food manufacturing clusters in northern Italy create localized economies of scale for additive distribution and technical service deployment.
Market Restraints
- Natural extract input volatility:Botanical colorant feedstocks face climate-driven harvest variability, compressing margin predictability for reformulated product lines.
- Single-source fermentation capacity:Limited Italian bioreactor infrastructure for culture-derived additives creates supply concentration risk during equipment maintenance cycles.
- Reformulation capex burden:Production line recalibration for reduced-additive thresholds demands capital allocation that mid-tier sauce manufacturers struggle to absorb.
Strategic Opportunities
- Southern Italy underpenetration:Campania and Sicily food processors lag northern counterparts in clean-label adoption, creating whitespace for technical service expansion.
- EU AI Act traceability mandates:Digital compliance requirements for additive supply chain documentation open consulting and software integration revenue streams.
- Functional beverage convergence:Collagen-enhanced and protein-fortified drink formulations in Milan and Turin are pulling novel texture modifiers into new application categories.
Industry Challenges
- Fermentation technologist scarcity:Italian universities produce insufficient industrial microbiology graduates to staff expanding bioprocess facilities in the natural additive segment.
- Dual certification timelines:Products requiring both organic and kosher validation face extended approval windows that delay regional distribution launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Food Additives Market |
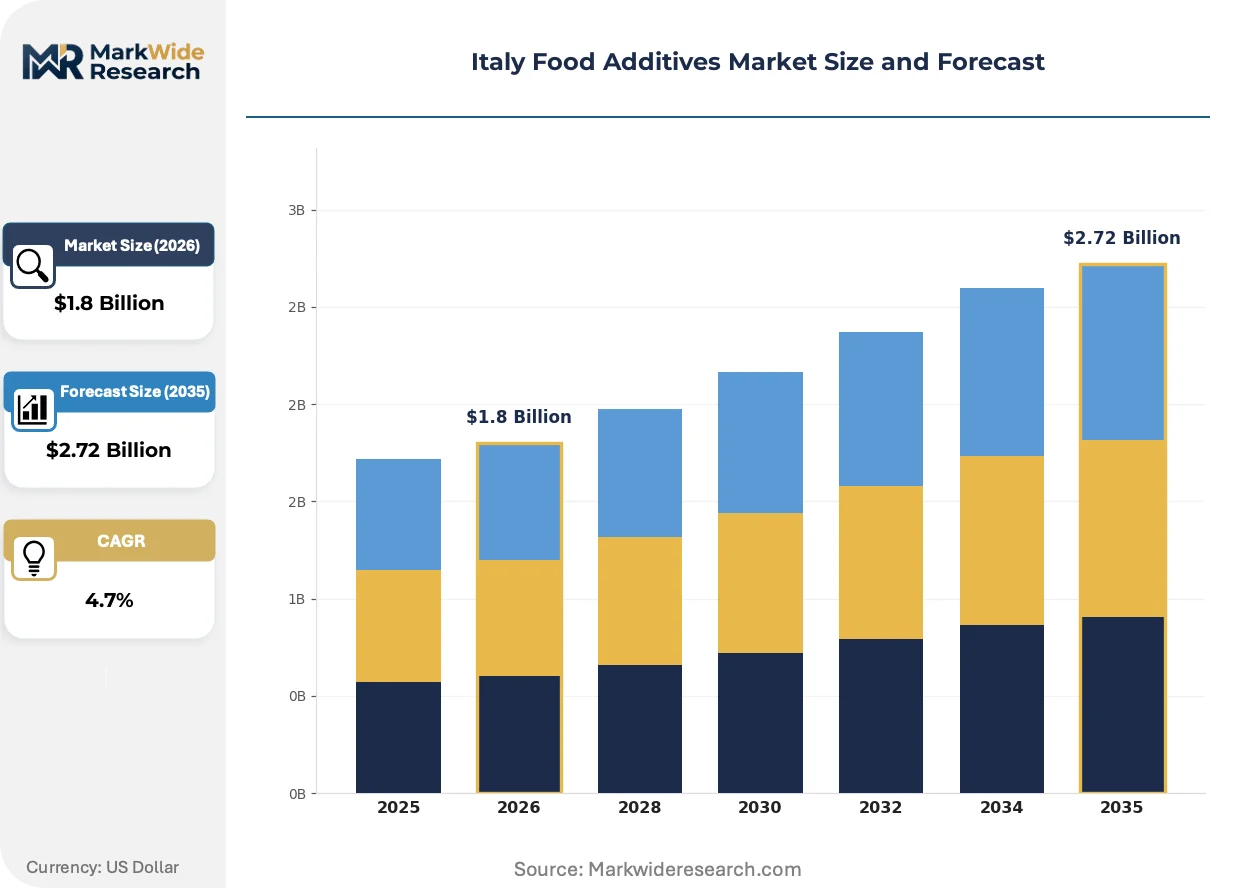
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
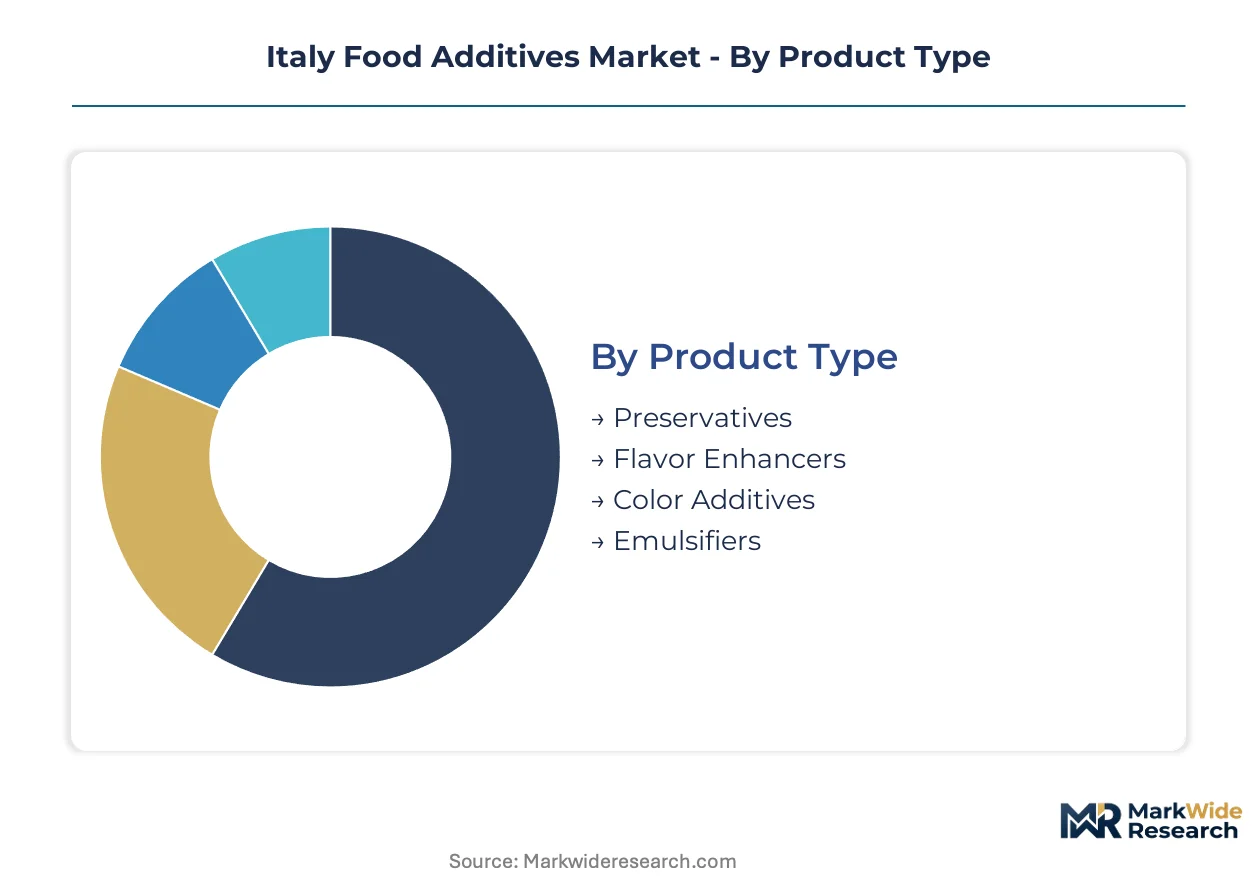
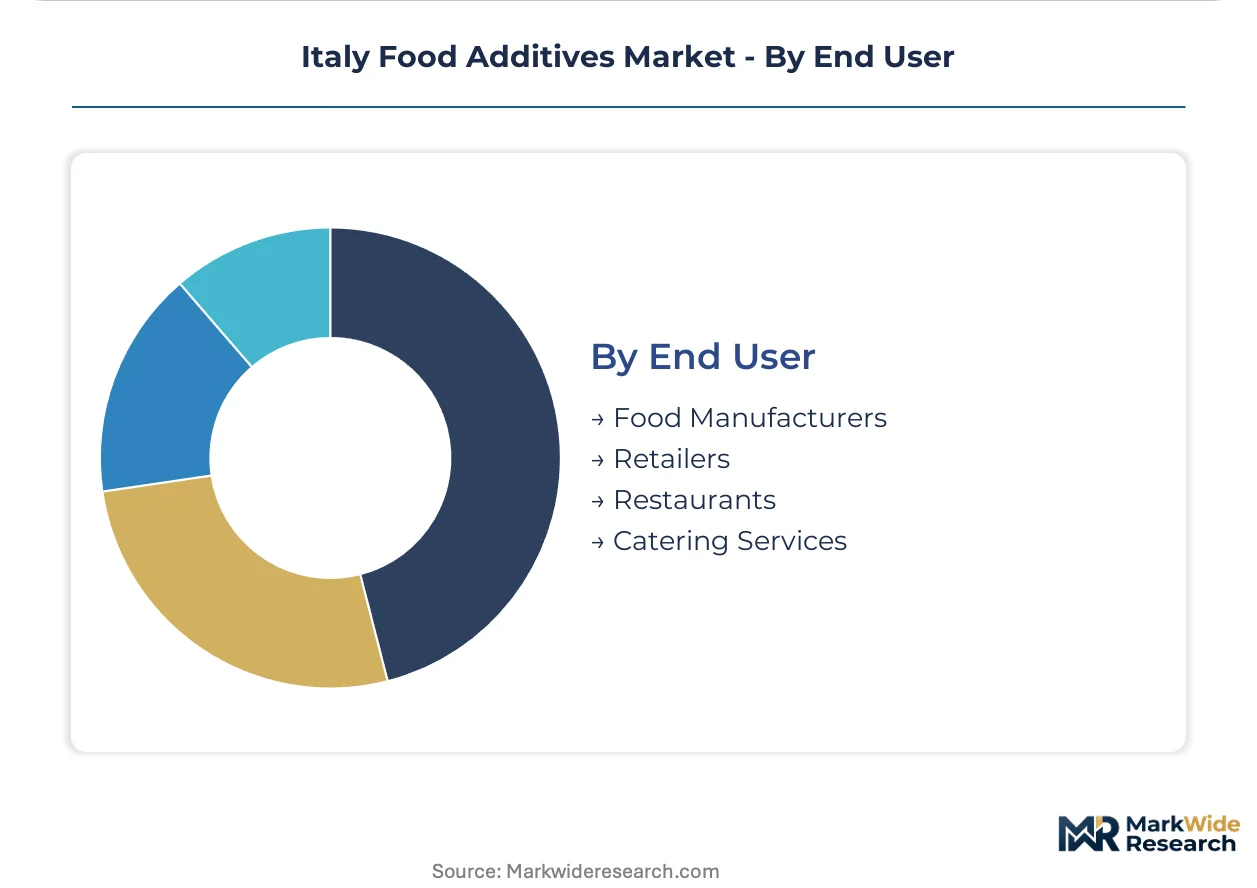
| Segmentation | Product Type: Preservatives, Flavor Enhancers, Color Additives, Emulsifiers Application: Beverages, Bakery Products, Dairy Products, Snacks Form: Powder, Liquid, Granular, Paste End User: Food Manufacturers, Retailers, Restaurants, Catering Services |
| Companies Covered | Cargill Incorporated, Kerry Inc., Koninklijke DSM NV, Chr. Hansen Holding AS, Brenntag AG, Symrise AG, Givaudan, Archer Daniels Midland Company, Ingredion Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Food Additives Market Shifts & Advancements
Clean-label migration is compressing synthetic additive shelf life while digital traceability mandates and regional procurement consolidation reshape competitive positioning across Italian food manufacturing.
Precision fermentation for natural colorants is decentralizing production economics by enabling smaller-batch, higher-potency pigment outputs that bypass agricultural growing seasons. Artisanal pasta sauce manufacturers in Bologna and Parma are piloting these systems to secure supply independence from tropical extract imports. The technology is decentralizing colorant procurement from commodity traders toward captive bioreactor operations within processing facilities.
Italy's Ministry of Health is enforcing children's food colorant restrictions that exceed baseline EFSA thresholds, forcing reformulation of snack and confectionery lines ahead of broader EU harmonization. Domestic decrees now mandate earlier phase-out schedules for azo dyes in school-targeted products. Southern Italian processors face compressed compliance windows compared to northern competitors with established clean-label pipelines.
Buyer consolidation among Italian private-label retailers is shortening supplier qualification cycles and demanding consolidated additive portfolios from fewer vendor relationships. Large-scale distributors like Coop and Conad are unbundling technical service from product supply, forcing additive houses to compete on formulation support rather than volume pricing alone. This pattern concentrates most visibly in Lombardy, where retail headquarters procurement teams centralize national sourcing decisions.
Italy Food Additives Market Segmentation
Italian food additive procurement patterns diverge sharply between cost-driven commodity buyers and premium reformulators chasing clean-label certifications. Manufacturers in Emilia-Romagna and Lombardy anchor volume demand while dictating technical specifications that cascade to smaller processors nationwide.
Product Type:
Preservation efficacy and label transparency now dominate supplier selection conversations among pasta sauce and ready-to-eat meal producers.
- Preservatives:Natural fermentation-derived alternatives displace synthetic benzoates under EU Green Deal timelines. Northern Italian dairy and sauce manufacturers absorb premium pricing to maintain retail shelf placement with major distributors.
- Emulsifiers:Powder and liquid stabilizers enable plant-based dairy texturization in Lombardy's oat and almond milk production corridors. Clean-label positioning demands are compressing synthetic lecithin volumes toward botanical alternatives.
- Flavor Enhancers:Yeast extracts and reduced-sodium systems face constrained positioning from national salt reduction campaigns.
- Color Additives:Natural pigments from agricultural extraction or precision fermentation bypass azo dye restrictions in children's food applications.
Volume sits with preservatives; growth tilts toward emulsifiers.
Application:
Reformulation urgency varies by processing category, with shelf-stable segments facing compressed additive transition windows versus fresh channels.
- Dairy Products:Plant-based alternatives in Lombardy pull hydrocolloid and stabilizer demand upward. Fermentation-derived cultures replace synthetic preservatives in premium yogurt and cheese lines targeting export markets.
- Bakery Products:Clean-label emulsifiers and natural mold inhibitors address extended shelf-life requirements without azodicarbonamide or calcium propionate labeling.
- Beverages:Functional drink formulations in Milan and Turin incorporate novel texture modifiers for protein fortification and suspension stability.
- Snacks:Sodium reduction mandates restrict MSG deployment, forcing umami reconstruction through yeast autolysates and vegetable extracts.
Dairy commands current procurement scale; beverages are climbing the fastest.
Form:
Production line integration costs and dispersion requirements determine physical specification preferences across Italian processing facilities.
- Powder:Dry-blend compatibility and extended stability dominate bakery and dry-mix applications. Emilia-Romagna pasta manufacturers prefer powder preservatives for sauce sachet incorporation.
- Liquid:Pumpable delivery systems reduce dust exposure and enable automated dosing in high-volume beverage and dairy plants.
- Granular:Controlled dissolution rates suit meat processing and coarse-textured applications where uniform distribution challenges persist.
- Paste:High-concentration formats minimize storage footprint for specialized colorant and flavor systems in artisanal production settings.
Powder retains manufacturing share; liquid is gaining ground fastest.
End User:
Scale concentration and technical capability stratification create divergent service requirements across the buyer base.
- Food Manufacturers:Large processors in northern Italy demand integrated formulation support and regulatory documentation packages. Direct supplier relationships bypass distributor margins for volume commitments.
- Retailers:Private-label consolidation among Coop and Conad procurement teams compresses supplier qualification cycles toward consolidated additive portfolios.
- Restaurants:Foodservice operators prioritize cost stability over clean-label positioning, maintaining synthetic additive tolerance in bulk procurement.
- Catering Services:Institutional buyers face limited reformulation pressure compared to branded retail channels, preserving legacy additive specifications.
Food manufacturers concentrate volume; retailers are expanding specifications fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Emilia-Romagna food processing cluster anchors northern Italian additive demand through tax-advantaged industrial zones concentrated around Bologna and Parma. Southern regions lag in clean-label adoption despite comparable agricultural output.
Lombardy
Milan's plant-based dairy corridor pulls hydrocolloid and stabilizer volumes upward as oat and almond milk production scales. EFSA threshold tightening accelerates reformulation timelines for synthetic preservative displacement. The Pavia-Lodi manufacturing belt concentrates bioreactor infrastructure for fermentation-derived colorants.
Emilia-Romagna
Parma's pasta sauce manufacturers drive natural preservative procurement as private-label retailers compress supplier qualification cycles. Italy's Ministry of Health enforces children's food colorant restrictions exceeding baseline EFSA thresholds. Bologna's precision fermentation pilots decentralize colorant procurement from tropical extract imports.
Veneto
Verona's wine and beverage processing cluster generates demand for clean-label stabilizers in functional drink formulations. EU Green Deal pesticide reduction targets force earlier phase-out schedules for synthetic additives. The Treviso-Prosecco corridor anchors natural preservative adoption in sparkling wine production.
Piedmont
Turin's confectionery and chocolate manufacturers reformulate azo dye formulations ahead of school-targeted product mandates. Farm to Fork Strategy timelines compress legacy additive tolerances across shelf-stable segments. The Alessandria-Asti food processing zone concentrates mid-tier sauce manufacturers facing reformulation capex burdens.
Lazio
Rome's institutional catering and foodservice procurement preserves synthetic additive tolerance in bulk channels compared to northern retail. EU AI Act traceability mandates force documentation upgrades for additive supply chains. The Frosinone-Latina industrial corridor hosts emerging distribution infrastructure serving central Italian processors.
Italy Food Additives Market Competitive Landscape
Benelux and Swiss producers anchor the premium fermentation-derived tier; German distributors hold commodity chemical consolidation. The market structures around three tiers: integrated agricultural processors with captive supply chains, specialized biotech houses with precision fermentation capabilities, and regional distributors with formulation service bundling. M&A activity concentrates on bioreactor capacity acquisition; strategic partnerships link colorant specialists with pasta sauce manufacturers seeking supply independence.
Within the integrated agricultural processor tier, Cargill Incorporated and Archer Daniels Midland Company represent archetypal volume leaders with upstream crop origination control. Among fermentation-derived specialists, Chr. Hansen Holding AS and Koninklijke DSM NV exemplify biotech houses bypassing synthetic restrictions through culture-based alternatives. Kerry Inc. occupies a position bridging formulation support with Mediterranean flavor profile specialization. These three archetypes—integrated processors, fermentation specialists, and technical service integrators—capture divergent margin pools as clean-label migration accelerates.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Kerry Inc. |
| Koninklijke DSM NV |
| Chr. Hansen Holding AS |
| Brenntag AG |
| Symrise AG |
| Givaudan |
| Archer Daniels Midland Company |
| Ingredion Inc |
| Others |
Supply & Pricing Matrix
Precision fermentation for natural colorants is compressing production economics while concentrating supply among bioreactor-equipped facilities in northern Italy. This technological shift simultaneously elevates capital barriers for new entrants and transfers pricing power toward fermentation specialists with captive culture banks.
Pricing Analysis
Short lead-time premiums dominate additive procurement as Emilia-Romagna pasta manufacturers pay markups for rapid reformulation support ahead of Ministry of Health decree deadlines. Contract-based long-term offtake structures anchor volume relationships with Cargill and Kerry, while spot purchases from distributors serve mid-tier processors with irregular demand. Price differentiation hinges on organic certification grade and technical service bundling. Pricing pressure stems from botanical extract feedstock volatility following climate-driven harvest shortfalls in southern Europe. Foodservice operators exhibit highest price sensitivity, accepting synthetic additive specifications to preserve margin; premium branded manufacturers absorb cost premiums for clean-label positioning.
Supply Chain Analysis
Regional distribution centers in Milan and Bologna operate hub-and-spoke patterns radiating toward Emilia-Romagna processing clusters and southern Italian catchment areas. Supply concentrates in Italy, Germany, and the Netherlands for fermentation-derived additives; tropical botanical extracts draw from India, Peru, and Madagascar. Raw material dependencies include molasses feedstocks for culture propagation, specialized fermentation media, and agricultural colorant crops. Single-source bioreactor vulnerability creates supply concentration risk during maintenance cycles. Distribution runs through Brenntag AG's consolidated chemical logistics network and specialized food ingredient distributors with formulation laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained. Limited Italian bioreactor infrastructure for culture-derived additives props pricing for fermentation specialists with operational capacity.
For Market Incumbents: Anticipate EFSA threshold tightening by accelerating precision fermentation capacity additions in Lombardy before competitor bioreactor commissioning. Secure backward integration into molasses and agricultural extract supply through long-term offtake agreements with Emilia-Romagna crop cooperatives. Defend against German and Benelux fermentation specialists by embedding technical service teams within Conad and Coop procurement headquarters. For New Entrants and Emerging Players: Launch via specialized distributor partnerships targeting Campania and Sicily food processors lagging in clean-label adoption. Exploit whitespace in southern Italy's artisanal cheese and preserved vegetable segments where natural preservative penetration remains below northern benchmarks. Prioritize kosher and organic dual-certification capabilities to differentiate from commodity distributors serving institutional channels. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation specialists given EU Green Deal acceleration of synthetic additive phase-outs. Long-term viability favors biotech houses with captive culture libraries and existing Italian regulatory relationships over commodity chemical distributors. Monitor EFSA additive safety reassessment announcements as inflection signals for reformulation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Captures margin migration from synthetic to natural colorants under EU Green Deal timelines. |
| Backward Integration into Agricultural Extract Supply | Secures feedstock independence from climate-volatile tropical botanical harvests. |
| Technical Service Laboratory Deployment | Meets Coop and Conad demands for formulation support unbundled from product supply. |
| Dual Certification Investment (Organic/Kosher) | Unlocks premium positioning in children's food segments with compressed compliance windows. |
| Southern Italy Distribution Infrastructure | Addresses underpenetration in Campania and Sicily processing corridors. |
Research Methodology
Document review covered EFSA safety assessments, Italy's Ministry of Health decrees, and EU Farm to Fork Strategy implementation guidelines, complemented by interviews with food additive procurement managers at Emilia-Romagna pasta manufacturers, regulatory affairs directors at fermentation specialists, technical service heads at distributor laboratories, and category buyers at Coop and Conad. Secondary sources included customs trade data for additive imports, SEC filings of listed ingredient suppliers, and Cefic chemical industry reports. Bottom-up demand modeling triangulated against top-down market sizing from production capacity and consumption intensity benchmarks.
Segment-level outputs across the projection horizon reflect discrete modeling of preservatives, emulsifiers, flavor enhancers, and color additives by powder, liquid, granular, and paste formats. The analytical framework incorporated end-use intensity variations across dairy, bakery, beverage, and snack applications plus regional adoption differentials between northern and southern Italian processing clusters. CAGRs were derived from elasticity-adjusted volume projections calibrated to documented reformulation timelines and regulatory phase-out schedules.
EFSA reassessment delays, Ministry of Health decree acceleration, and precision fermentation yield improvements are the dominant revision risks for additive demand forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
Food Grade Ammonium Bicarbonate Market
Food Additives and Ingredients
Germany Food Enzymes Market
Food Additives and Ingredients
Banana Powder Market
Food Additives and Ingredients
Food Grade Sodium Hydroxide Market
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
North America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
Mexico Food Additives Market
Food Additives and Ingredients
Global Food Bulking Agents Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Cook-Up Starch Market
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
Erythorbic Acid Market