
 Ice Maker Machines Market | 2026-2036
Ice Maker Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Maker Machines Market Foresight
Market Context with Strategic Players
Foodservice equipment distribution is reshaping how ice maker machines reach end users, with regional dealer networks consolidating and direct-to-operator digital platforms gaining share. Hoshizaki Corporation leverages its vertical integration in compressor technology to sustain margin advantages across premium commercial installations. Manitowoc Ice anchors North American supply through extensive service infrastructure and rapid parts fulfillment. Scotsman Ice Systems differentiates via specialized ice form portfolios spanning nugget, flake, and gourmet crystalline structures for distinct buyer segments.
Technical Definition and Structural Segments
Ice maker machines are electromechanical appliances that freeze potable water into discrete ice forms through vapor-compression or thermoelectric cooling cycles, typically producing outputs from 50 to 2,000-plus pounds per day for commercial and institutional consumption. Modular units dominate installed base value due to scalable configurations paired with separate storage bins, while portable systems represent the fastest-expanding product type as residential and outdoor entertainment applications multiply. Air-cooled technology leads deployment share by avoiding water consumption penalties, though water-cooled variants persist in high-ambient-temperature environments where thermal efficiency mandates override operating cost concerns.
Regulatory Frame and Forward-Looking Close
The U.S. Department of Energy, EPA through SNAP refrigerant phasedown protocols, and California Air Resources Board shape equipment design trajectories via efficiency minimums and low-global-warming-potential refrigerant transitions. European REACH compliance and F-Gas Regulation restrictions further constrain refrigerant selection and material composition for manufacturers serving cross-border markets. Stakeholders must monitor refrigerant chemistry patent cliffs and regional efficiency tier upgrades to time platform redesigns and avoid stranded inventory positions.
Market Dynamics
The U.S. Department of Energy's commercial refrigeration efficiency standards are compressing replacement cycles and forcing rapid platform redesigns across the installed base. Equipment operators now face stranded asset risk from aging refrigerant chemistries and non-compliant energy profiles.
Growth Catalysts
- Healthcare Facility Upgrades:Hospital and long-term care construction is accelerating demand for flake and nugget ice systems in clinical hydration and therapeutic applications.
- SNAP Refrigerant Phasedown:The EPA's hydrofluorocarbon reduction mandates are pulling forward replacement demand as operators preempt obsolescence of R-404A and R-134a equipment.
- Outdoor Entertainment Expansion:Residential outdoor kitchen installations are multiplying demand for portable undercounter units with weatherized compressor housings.
Market Restraints
- Copper and Aluminum Volatility:Compressor coil and heat exchanger input costs swing with commodity markets, squeezing margin predictability for mid-tier manufacturers.
- Refrigerant Patent Concentration:Low-global-warming-potential blend formulations remain concentrated among three chemical suppliers, creating supply bottleneck risk.
- Water-Cooled System Decline:Municipal water use restrictions in drought-prone states are rendering water-cooled architectures economically unviable outside industrial zones.
Strategic Opportunities
- Remote Monitoring Integration:IoT-enabled predictive maintenance platforms are opening recurring revenue streams for OEMs with captive service networks.
- India Foodservice Modernization:Quick-service restaurant rollout in Tier-2 cities is creating first-time equipment demand beyond legacy hospitality corridors.
- California CARB Incentives:State-level rebates for ultra-low-emission refrigeration are accelerating premium equipment penetration in the largest U.S. state market.
Industry Challenges
- EPA Certification Timelines:New equipment approvals under SNAP and Significant New Alternatives Policy protocols extend time-to-market by 8-14 months.
- Legacy Control System Integration:Building management system interoperability demands are fragmenting R&D resources across BACnet, Modbus, and proprietary protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Maker Machines Market |
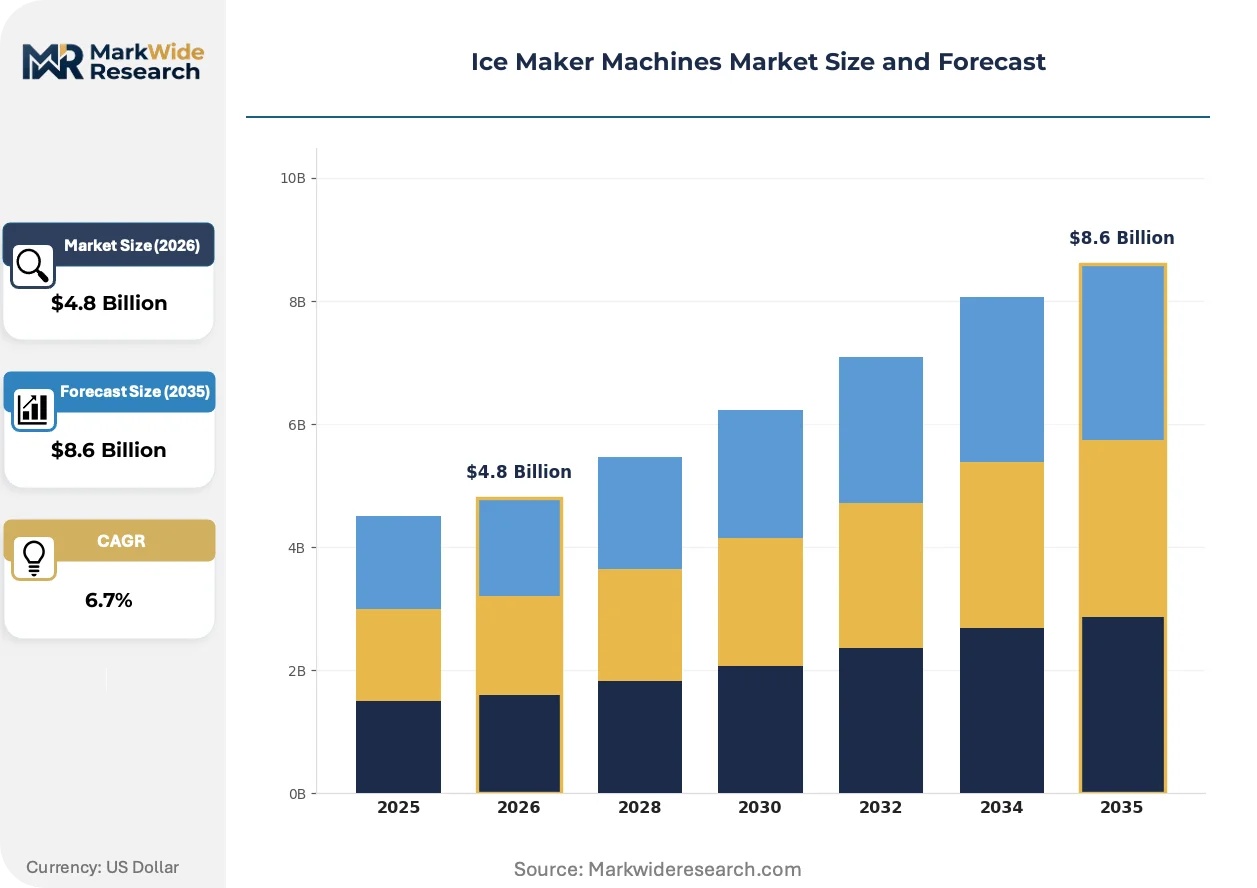
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial, Portable, Undercounter, Modular Technology: Air-Cooled, Water-Cooled, Batch, Continuous End User: Restaurants, Bars, Hotels, Healthcare Facilities Deployment: Freestanding, Built-In, Countertop, Outdoor |
| Companies Covered | Hoshizaki Corporation, Manitowoc Ice, Scotsman Ice Systems, Follett Ice, Cornelius, Inc., Ice-O-Matic, Kold-Draft, Brema Ice Makers, Grant Ice Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Maker Machines Market Shifts & Advancements
Equipment intelligence and refrigerant chemistry transitions are converging to redefine competitive differentiation. Vendors now compete on data-enabled uptime guarantees rather than pure ice output metrics.
Smart diagnostics hardware is digitizing service relationships between manufacturers and multi-site foodservice operators. Chains with 50-plus locations are mandating cloud-connected units that flag compressor stress and scale buildup before failure. This capability is compressing the advantage of independent service contractors who lack telemetry access.
The EPA's SNAP refrigerant phasedown protocols are forcing chemistry transitions toward R-448A and R-449A blends with lower global warming potential. Equipment redesigns to accommodate pressure and lubricant compatibility differences are absorbing engineering capacity through 2027. Air-cooled system manufacturers serving the southern United States are most exposed due to higher compressor duty cycles.
Multi-site operators are consolidating procurement through national account structures that unbundle equipment from installation and maintenance. Foodservice management companies with centralized capital planning are bypassing regional dealer networks to negotiate direct factory pricing. This concentration is most visible in the quick-service and casual dining verticals where equipment standardization across locations is feasible.
Ice Maker Machines Market Segmentation
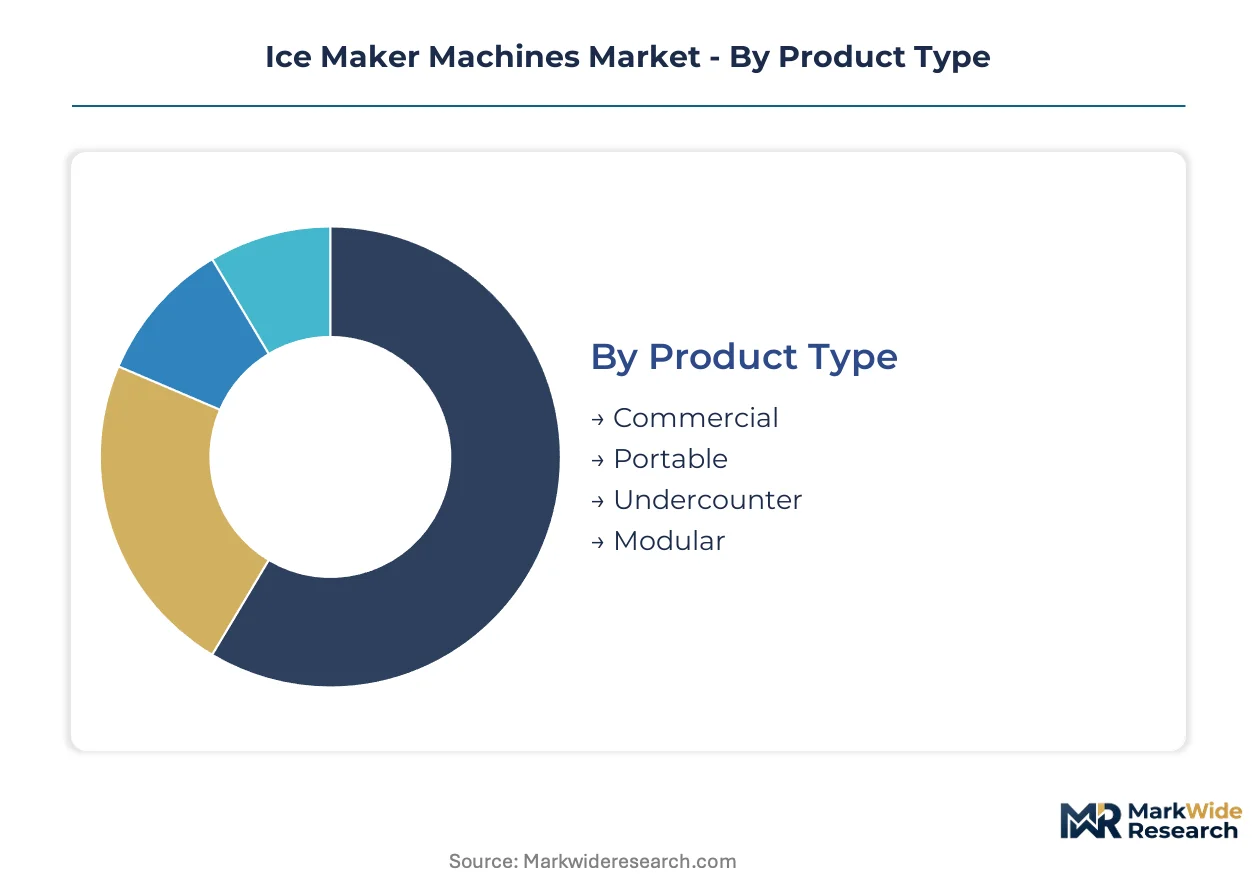
Ice maker machine configurations diverge sharply across foodservice, healthcare, and residential contexts. Equipment specifications must align with installation constraints, thermal loads, and regulatory compliance tiers that vary by operating environment.
Product Type:
Use-case spectrum spans institutional-scale production to residential convenience, with each tier demanding distinct form factors and service architectures.
- Commercial:High-capacity vapor-compression systems producing 500-2,000+ pounds daily through stainless steel evaporator plates. Restaurant chains in the United States anchor replacement demand as operators retire R-404A equipment ahead of EPA phasedown deadlines.
- Modular:Scalable head units paired with separate storage bins enabling 48-hour ice reserves. Healthcare facilities in California favor this architecture for flake ice production in clinical hydration protocols.
- Portable:Self-contained units with integrated storage, typically 26-50 pound daily output. Residential outdoor kitchen installations across Arizona and Texas are expanding most quickly for weatherized entertainment spaces.
- Undercounter:Front-venting compact systems designed for bar and cafe footprints with limited mechanical space. Front-of-house beverage stations in boutique hotels specify these for aesthetic integration.
Established volume favors commercial; emerging adoption favors portable.
Technology:
Cooling architecture selection hinges on water availability, ambient temperature profiles, and municipal efficiency regulations.
- Air-Cooled:Refrigerant-to-air heat rejection eliminating water consumption penalties. The U.S. Department of Energy's tightened commercial refrigeration standards are compressing deployment share toward this architecture in southern states.
- Water-Cooled:Shell-and-tube or plate heat exchangers using municipal water as thermal sink. Drought restrictions in California and Nevada are rendering this technology economically unviable outside industrial zones with recirculating towers.
- Batch:Cyclical freezing and harvest sequences producing discrete cube forms. Full-service restaurants specify these for beverage clarity and controlled melt rates.
- Continuous:Non-stop flake or nugget extrusion for high-turnover applications. Hospital dietary departments and seafood display cases in Florida and Louisiana require uninterrupted ice availability.
Air-cooled systems dominate new installations; water-cooled architectures retreat to specialized industrial contexts.
End User:
Buyer procurement patterns fragment across capital planning cycles, maintenance capabilities, and ice form specifications.
- Restaurants:Full-service and quick-service operators with standardized equipment programs across location portfolios. Chains with 50-plus units are mandating IoT-connected platforms for predictive maintenance.
- Healthcare Facilities:Hospitals and long-term care centers requiring flake and nugget ice for patient hydration and therapeutic applications. Construction of new medical campuses in Texas and Florida is accelerating specification activity.
- Bars:Independent and multi-unit operators prioritizing clear cube aesthetics and rapid recovery rates. Craft cocktail venues in New York and Chicago specify gourmet crystalline forms at premium price points.
- Hotels:Full-service properties with distributed ice needs across guest floors, banquet kitchens, and pool amenities. Brand standards from major hospitality groups are consolidating around modular architectures with remote monitoring.
Restaurant procurement concentrates volume; healthcare construction drives specification innovation.
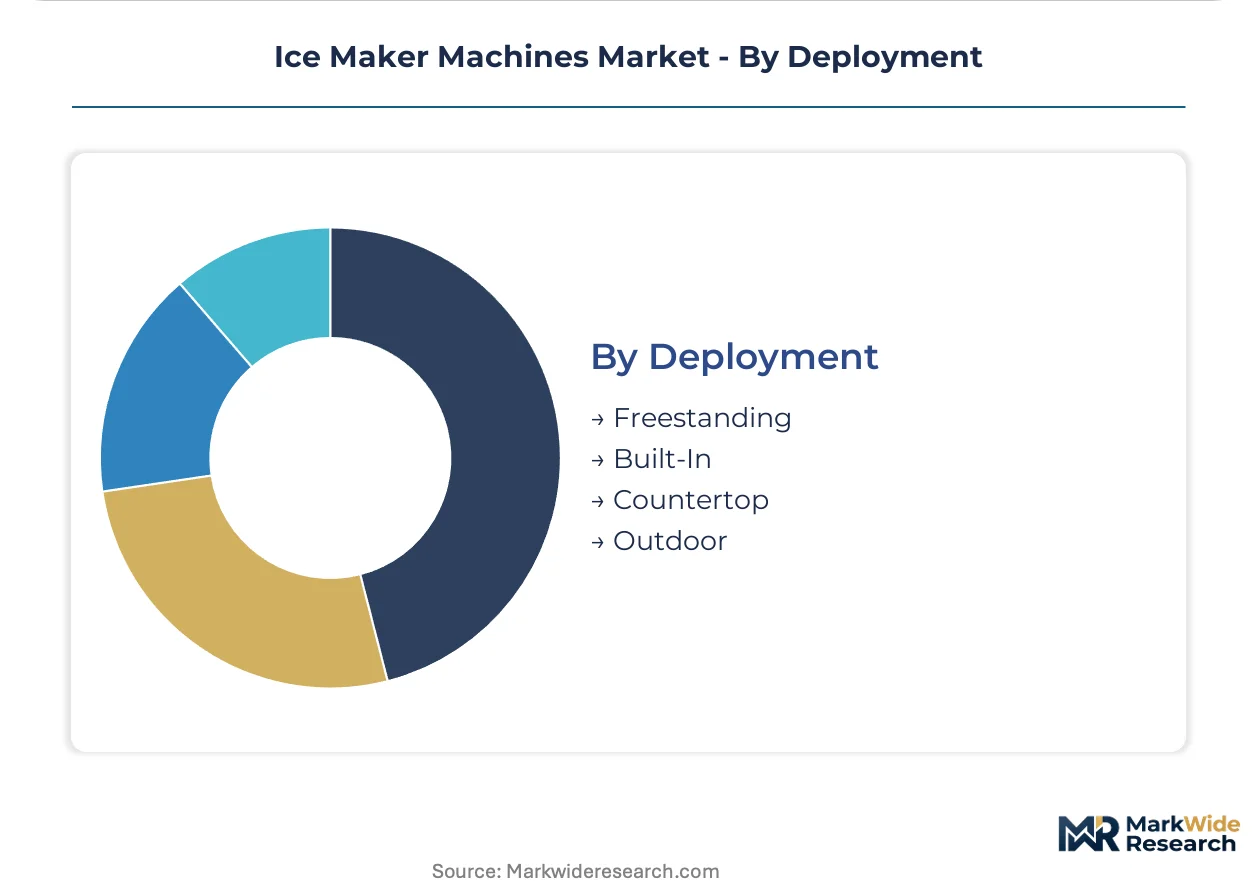
Deployment:
Physical installation constraints dictate ventilation clearances, structural loading, and weatherization requirements.
- Freestanding:Self-supporting units with caster mobility for flexible kitchen layouts. Catering operations and event venues in California specify these for rapid reconfiguration.
- Built-In:Panel-ready enclosures integrating with custom millwork for front-of-house concealment. Upscale hotel bars in Miami and Los Angeles demand seamless aesthetic integration.
- Countertop:Compact dispensers for office breakrooms and limited-service cafes. Corporate campus renovations in Texas are expanding specification of touchless dispensing variants.
- Outdoor:Weatherized compressor housings with enhanced coil protection for exterior kitchen installations. Residential poolside kitchens in Arizona and Florida represent the steepest expansion trajectory.
Freestanding architectures retain installed base dominance; outdoor configurations climb fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level rebates for ultra-low-emission refrigeration are accelerating premium equipment penetration across multiple jurisdictions. The U.S. Department of Energy's tightened commercial refrigeration standards are compressing replacement cycles and forcing rapid platform redesigns. Municipal water use restrictions in drought-prone states are rendering water-cooled architectures economically unviable.
United States
Foodservice expansion and healthcare facility upgrades sustain replacement cycles in Texas and Florida. The EPA's SNAP refrigerant phasedown protocols mandate transitions toward R-448A and R-449A blends. Hospital construction in Houston and Miami is accelerating specification activity for flake ice systems in clinical hydration applications.
Canada
Healthcare facility modernization and commercial kitchen renovations drive equipment turnover in Ontario and Quebec. Health Canada's PMRA regulates refrigerant chemistry transitions under aligned North American protocols. Toronto's hospital network is consolidating procurement through national account structures for modular ice architectures.
Germany
Precision brewing and pharmaceutical cold-chain applications sustain demand for specialized ice forms in Bavaria and Baden-Württemberg. The EU F-Gas Regulation restricts refrigerant selection and material composition for cross-border equipment. Munich's craft beverage cluster is specifying gourmet crystalline ice forms at premium price points.
Japan
Convenience store modernization and seafood display requirements anchor replacement demand in Kanto and Kansai regions. METI efficiency standards and JIS certification protocols shape equipment design trajectories. Osaka's fish market operators require continuous flake ice extrusion for uninterrupted cold-chain availability.
India
Quick-service restaurant rollout in Tier-2 cities creates first-time equipment demand beyond legacy hospitality corridors. BIS certification and FSSAI food safety protocols govern commercial refrigeration deployment. Bengaluru's foodservice management companies are consolidating procurement through centralized capital planning structures.
Ice Maker Machines Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes with distinct capability profiles. Premium-tier specialists leverage captive compressor technology and vertical integration to sustain margin advantages across commercial installations. Mid-scale fabricators compete on regional service density and rapid parts fulfillment networks. Emerging specialists differentiate via specialized ice form portfolios for distinct buyer segments. Dominant competitive moves include IoT-enabled predictive maintenance platform development and direct-to-operator digital channel expansion.
Within the premium-tier specialist archetype, Hoshizaki Corporation and Manitowoc Ice occupy anchor positions representing distinct geographic and capability emphases. Scotsman Ice Systems exemplifies the specialization vector with its focused portfolio approach. These three entities collectively illustrate how competitive differentiation now converges on refrigerant chemistry transitions and equipment intelligence rather than pure output metrics.
| Leading Market Players |
|---|
| Hoshizaki Corporation |
| Manitowoc Ice |
| Scotsman Ice Systems |
| Follett Ice |
| Cornelius, Inc. |
| Ice-O-Matic |
| Kold-Draft |
| Brema Ice Makers |
| Grant Ice Systems |
| Others |
Supply & Pricing Matrix
Copper and aluminum commodity volatility cascades through compressor coil and heat exchanger procurement, widening the spread between premium air-cooled systems and mid-tier alternatives while forcing manufacturers toward captive sourcing or long-term offtake arrangements. This input cost instability compresses margin predictability for fabricators lacking backward integration into metals, reshaping competitive positioning around supply security rather than pure manufacturing scale.
Pricing Analysis
Certification level creates the primary spread between EPA SNAP-compliant R-448A/R-449A systems and legacy refrigerant equipment nearing obsolescence. Three-tier pricing structure across premium, standard, and economy levels reflects energy efficiency tier, IoT connectivity bundling, and after-sales service density. Pricing pressure stems from copper and aluminum volatility squeezing mid-tier manufacturers without captive coil production. Quick-service restaurant chains with national account structures exhibit highest price sensitivity, while healthcare facilities prioritize uptime guarantees over capital expenditure.
Supply Chain Analysis
Contract manufacturing concentration sits with specialized refrigeration OEMs in China, Mexico, and the United States holding compressor assembly and coil fabrication capacity. Supply chains draw from copper cathode sources in Chile, aluminum smelters in Canada, and refrigerant blend suppliers concentrated among three chemical producers. Single-source vulnerability in low-global-warming-potential refrigerant formulations creates bottleneck risk ahead of EPA phasedown deadlines. Distribution runs through consolidating regional dealer networks and emerging direct-to-operator digital platforms serving multi-site foodservice operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ice maker equipment demand sits at an early-cycle expansion phase as healthcare construction and outdoor residential kitchen installation accelerate first-time specification and replacement pull-forward.
For Market Incumbents: Harden service infrastructure density in Texas and Florida where hospital construction and foodservice expansion concentrate replacement demand. Deepen captive compressor technology control to offset copper and aluminum volatility squeezing mid-tier competitors. Lock in national account structures with quick-service chains mandating IoT-connected platforms before independent service contractors develop telemetry capabilities. For New Entrants and Emerging Players: Tier-2 Indian cities present the most penetrable white-space as quick-service restaurant rollout creates first-time equipment demand beyond legacy hospitality corridors. Target flake and nugget ice specialization for healthcare facilities in California and Texas where clinical hydration protocols drive specification innovation. Pursue direct digital channel partnerships with foodservice management companies consolidating procurement through centralized capital planning. For Investors and Strategic Acquirers: The market sits at a replacement-cycle acceleration phase that favors premium-tier specialists with refrigerant chemistry transition readiness and captive IoT platform development. Acquisition candidates should demonstrate vertical integration into compressor technology or established service density in high-growth geographies. Watch EPA certification timeline delays and refrigerant patent cliff dynamics as signals for stranded inventory risk and platform redesign timing.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Development | Cloud-connected diagnostics compress independent service contractor advantages for multi-site operators. |
| Refrigerant Chemistry Transition | R-448A and R-449A blend compatibility redesigns absorb engineering capacity through platform overhauls. |
| Healthcare Facility Partnership | Hospital construction in Houston and Miami accelerates flake ice specification for clinical hydration protocols. |
| Direct-to-Operator Channel | Digital platforms bypass regional dealer networks serving foodservice management companies with centralized procurement. |
| Service Infrastructure Expansion | Rapid parts fulfillment networks defend market position in Texas and Florida replacement cycles. |
Research Methodology
Cross-validation between regulatory filing analysis and equipment shipment data anchors the qualitative findings on refrigerant transition timelines and replacement cycle acceleration. Primary interviews with foodservice equipment procurement directors, healthcare facility maintenance managers, OEM product development executives, and regional dealer network operators combined with secondary validation from EPA SNAP protocols, DOE efficiency standard dockets, and AHRI certification databases. Bottom-up unit shipment modeling triangulates against top-down foodservice construction spending and healthcare capital expenditure forecasts.
Calibration against historical replacement cycle patterns and refrigerant phasedown precedent in adjacent commercial refrigeration categories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, cooling technology, end-user vertical, and geographic regulatory cluster. CAGRs derived from installed base turnover rates, construction pipeline data, and efficiency standard compliance deadlines. Industry-specific forecast inputs incorporate copper and aluminum price trajectory assumptions and municipal water restriction expansion patterns.
Practitioners should monitor refrigerant chemistry patent cliffs, EPA certification backlog durations, and copper futures volatility for early signals of platform redesign timing and margin compression. Forecasts reflect assumptions on healthcare construction permit issuance and quick-service restaurant unit expansion trajectories. Quarterly review of DOE efficiency standard update schedules and CARB incentive program modifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Cider Brewing Equipment Market
Food Processing Equipment
Granular Ice Machine Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
High-Pressure Processing Equipment Market
Food Processing Equipment
Fish Cutting Machine Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Commercial Wood Fired Pizza Oven Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Food Recycler Market
Food Processing Equipment
Used Commercial Freezer Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Blast Chillers Market
Food Processing Equipment
Soda Production Machine Market
Food Processing Equipment
Flakes Making Machine Market