
 Global Soft Tissue Allografts Market | 2026-2036
Global Soft Tissue Allografts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Soft Tissue Allografts Market Intelligence
American Association of Tissue Banks (AATB) accreditation is rotating the competitive landscape, setting a high bar for tissue processing and safety protocols. AlloSource leverages its non-profit, donor-centric model to secure a consistent supply of high-quality tissue. Stryker Corporation competes by integrating allografts within its broader orthopedic solutions portfolio. Arthrex Inc. differentiates through its focus on minimally invasive surgical products designed for sports medicine applications.
Soft tissue allografts are sterile, non-viable tissues, such as tendons or ligaments, harvested from a human donor for transplantation. These grafts undergo rigorous processing, including decellularization, to minimize immunogenic response and are used to reconstruct damaged soft tissues. Tendon allografts command a significant share due to high-volume use in orthopedic surgery. Applications in dental surgery represent a rapidly expanding segment for dermis and fascia allografts.
Regulatory oversight from bodies like the U.S. FDA and the European Medicines Agency (EMA) governs tissue procurement, processing, and distribution. Compliance with ISO 13485 for medical device quality management systems is critical for market access and demonstrates adherence to safety standards. Future market evolution will hinge on the development of next-generation sterilization techniques that better preserve the biomechanical properties of the graft tissue.
Market Dynamics
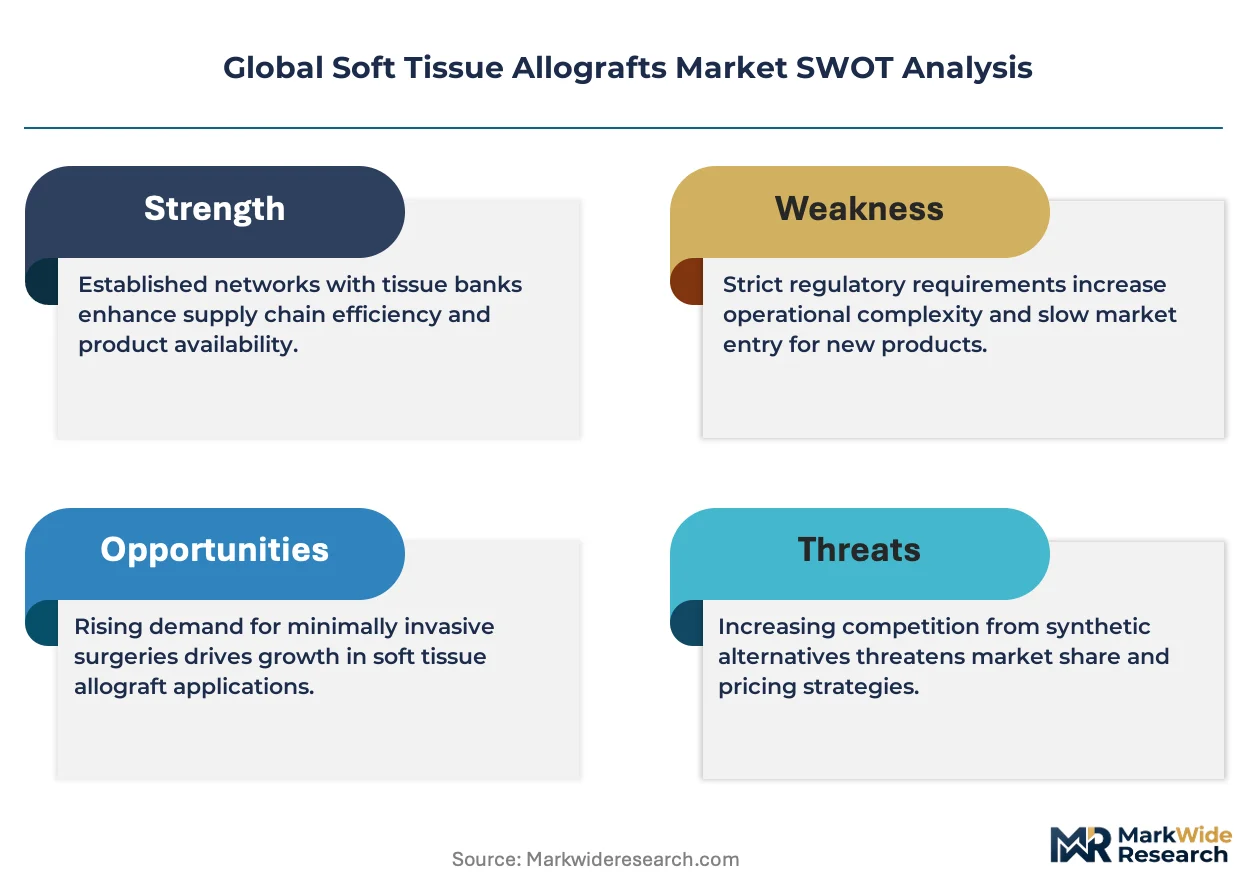
A central tension between the demand for advanced, biomechanically superior allografts and the increasing stringency of global regulatory frameworks defines the market. The push for innovations that better preserve tissue integrity runs directly into higher compliance costs and extended timelines imposed by bodies like the U.S. FDA and EMA.
Growth Catalysts
- Advanced Sterilization Methods:Innovations like low-dose gamma irradiation and proprietary chemical sterilization processes enhance graft safety by inactivating pathogens while better preserving the tissue's biomechanical properties, increasing surgeon confidence and adoption.
- Expanding Surgical Applications:The use of dermis and fascia allografts is expanding rapidly in dental procedures for guided bone and tissue regeneration, representing a significant new avenue of demand beyond traditional orthopedics.
- Aging Demographics:In developed nations such as Japan and Germany, aging populations are leading to a higher prevalence of degenerative conditions like osteoarthritis, which in turn fuels the volume of joint reconstruction and repair surgeries utilizing allografts.
Market Restraints
- Donor Tissue Scarcity:The supply of human donor tissue is fundamentally limited by ethical considerations, logistical complexities in procurement, and sociocultural factors, creating an inherent bottleneck on market growth that cannot be solved by manufacturing scale alone.
- Risk of Immunogenic Rejection:Despite decellularization and sterilization, a residual risk of host immunogenic response or disease transmission remains, which can deter adoption in favor of autografts where no such risk exists.
- Competition from Autografts:For many procedures, particularly ACL reconstruction in young athletes, the patient's own tissue (autograft) remains the clinical gold standard, directly competing with and limiting the use of allografts.
Strategic Opportunities
- Emerging Market Penetration:Countries like Brazil and Mexico, with their growing middle classes and expanding access to advanced healthcare, represent significant untapped markets for orthopedic and dental allograft procedures.
- Bio-inductive Graft Development:There is a substantial opportunity in creating next-generation allografts that are not just structural scaffolds but are processed to retain or be seeded with growth factors to actively promote and accelerate tissue regeneration.
- Urogynecological Reconstruction:Applications in pelvic floor repair and sling procedures for stress urinary incontinence offer a nascent but high-potential area for specialized soft tissue allografts, moving beyond established orthopedic uses.
Industry Challenges
- Regulatory Compliance Burden:Navigating and maintaining compliance with the divergent and evolving requirements of the U.S. FDA's HCT/P regulations and the EU's MDR is a complex and costly operational challenge for tissue banks.
- Standardization of Biomechanics:A lack of industry-wide standards for testing and reporting the biomechanical properties of processed grafts makes it difficult for surgeons to compare products and can lead to inconsistent clinical outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Soft Tissue Allografts Market |
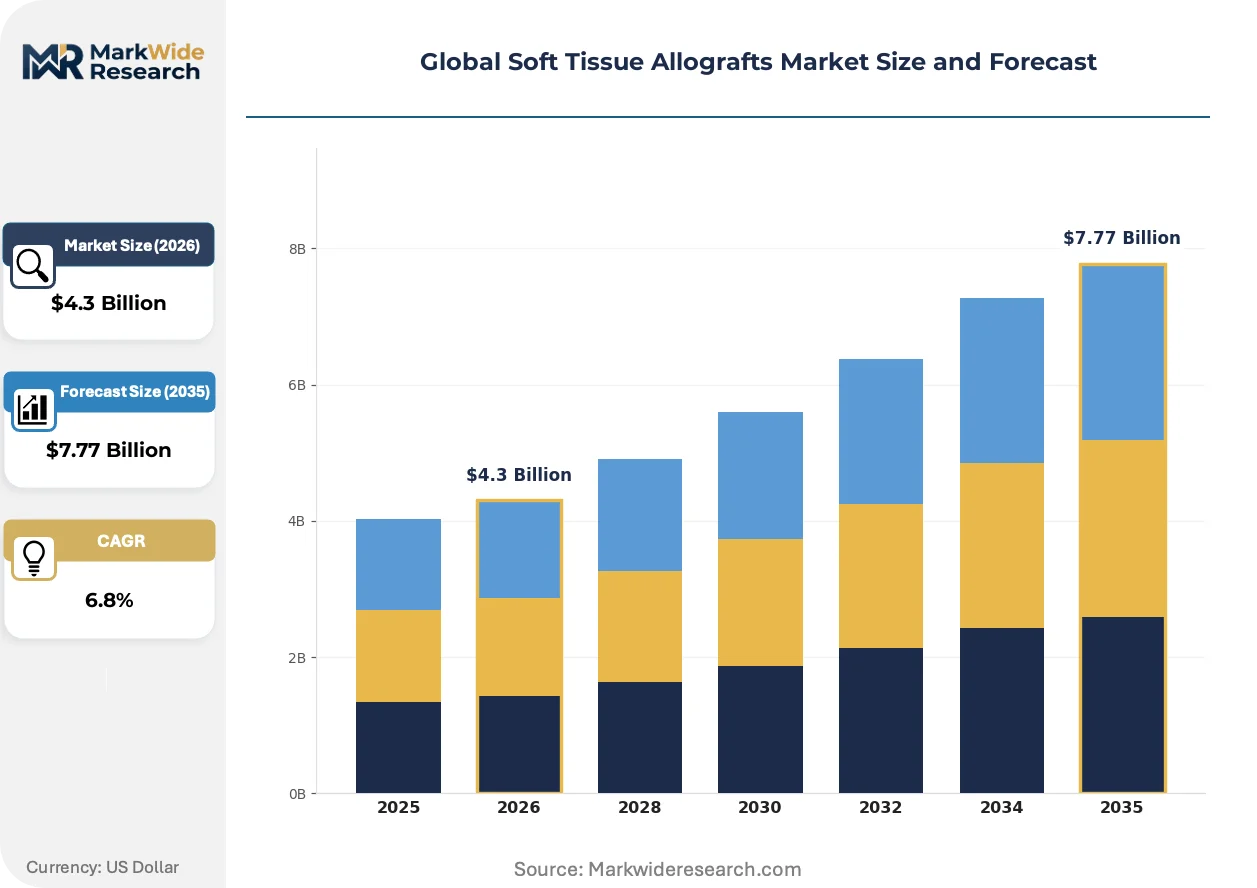
| Market Size in 2026 | $4.3 Billion |
| Market Size in 2035 | $7.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tendon Allografts, Ligament Allografts, Fascia Allografts, Dermis Allografts, Periosteum Allografts Application: Orthopedic Surgery, Sports Medicine, Dental Surgery, Spinal Fusion, Soft Tissue Repair End User: Surgical Centers, Ambulatory Clinics, Specialty Clinics, Rehabilitation Facilities, Academic Hospitals Distribution Channel: Direct Sales, Medical Distributors, Online Pharmacies, Hospital Procurement, Third-Party Suppliers |
| Companies Covered | Stryker Corporation, AlloSource, Arthrex Inc., RTI Surgical Inc., CONMED Corporation, Integra LifeSciences Corporation, Organogenesis Inc., MiMedx Group Inc., Globus Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Soft Tissue Allografts Market Strategic Shifts & Innovations
A concerted effort to enhance the biological functionality of allografts is underway, moving beyond simple structural replacement. This involves developing processing techniques that preserve the native extracellular matrix, aiming to improve graft integration and long-term performance in vivo.
Supercritical CO2 is an advanced terminal sterilization technology used to inactivate pathogens in soft tissue grafts. Orthopedic surgeons are increasingly requesting grafts processed with such methods for sports medicine repairs, valuing the preservation of biomechanical integrity. This focus on gentler processing is miniaturizing the cellular-level damage caused by sterilization, which improves the potential for host cell repopulation and tissue remodeling.
The European Union's Medical Device Regulation (MDR) now classifies many allografts as medical devices, demanding more rigorous clinical evidence and post-market surveillance. This has substantially increased the burden of proof for manufacturers to demonstrate safety and efficacy. Tissue processors targeting the European market are most affected, needing to invest heavily in clinical studies to maintain market access for their products.
Hospitals are modifying their procurement criteria for allografts, shifting from a focus on individual surgeon preference to a value analysis model that prioritizes clinical evidence of reduced complication and revision rates. This change disrupts the traditional sales channel, putting pressure on suppliers to provide robust clinical data supporting long-term outcomes. This trend is most pronounced in the United States, driven by large hospital networks and Group Purchasing Organizations.
Global Soft Tissue Allografts Market Segmentation
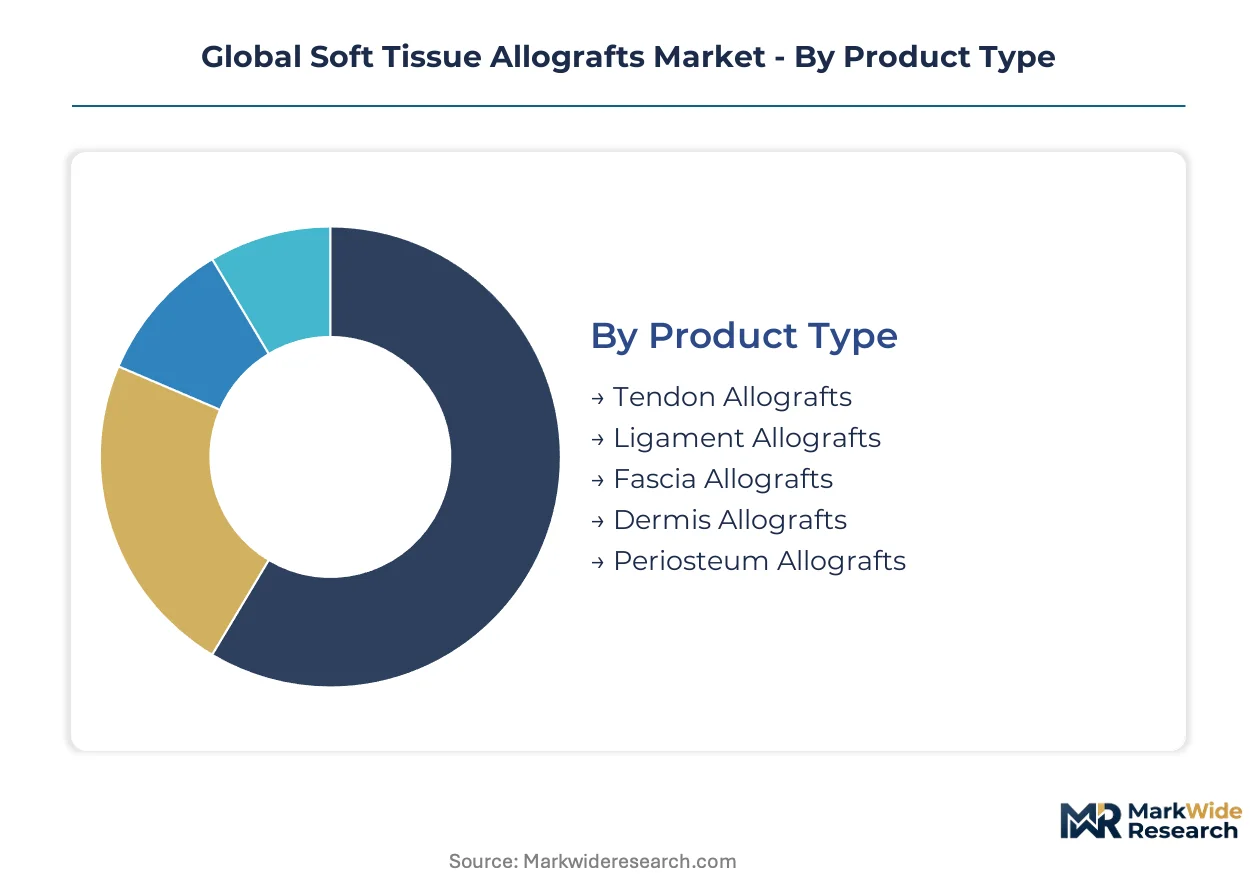
The global soft tissue allografts market is analyzed across key dimensions to understand its intricate structure and operational dynamics. This segmentation provides a granular view of product types, their applications, end-user adoption patterns, and the channels through which these critical medical devices are distributed. Understanding these divisions is essential for strategic planning and market penetration.
Product Type:
The product type segmentation reveals how different allograft forms flow through varied distribution channels to reach specific clinical settings.
- Tendon Allografts:These sterile, non-viable connective tissues, primarily from human donors, are processed to retain biomechanical strength. Demand concentrates in orthopedic surgery, particularly for ligament and tendon repairs in sports medicine settings across countries like the United States and Germany.
- Dermis Allografts:Comprising acellular dermal matrix, these grafts provide a structural scaffold for tissue regeneration without immunogenic response. Their utilization is expanding rapidly in dental surgery for guided bone and tissue regeneration, especially in developed markets with high aesthetic procedure volumes.
- Ligament Allografts:These grafts, often used in cruciate ligament reconstruction, offer structural support in joint repair procedures.
- Fascia Allografts:Derived from connective tissue, these grafts find use in reconstructive surgeries and hernia repairs.
- Periosteum Allografts:These thin membrane grafts, rich in progenitor cells, support bone regeneration in complex orthopedic cases.
By volume, Tendon Allografts lead. By growth pace, Dermis Allografts are ahead.
Application:
The application segments highlight the primary clinical areas driving allograft consumption volumes across diverse healthcare systems.
- Orthopedic Surgery:This segment encompasses a broad range of procedures, including ACL reconstruction, rotator cuff repair, and joint stabilization. High volumes are recorded in countries with active sports populations and aging demographics, such as the United States and Japan.
- Dental Surgery:Utilizing dermis and fascia allografts, this segment focuses on guided tissue regeneration, periodontal reconstruction, and soft tissue augmentation. Demand is particularly strong in markets with advanced dental care infrastructure, like Germany and the United Kingdom.
- Sports Medicine:Allografts are critical for repairing sports-related injuries, including ligament and tendon tears, enabling faster patient recovery.
- Spinal Fusion:These procedures use allografts as structural spacers or biological scaffolds to promote vertebral fusion and stability.
- Soft Tissue Repair:This broad category includes various reconstructive procedures beyond orthopedics, addressing defects in skin, muscle, and fascia.
Orthopedic Surgery commands the largest market share, while Dental Surgery exhibits the steepest expansion trajectory.
End User:
The end-user segmentation delineates the types of healthcare facilities that procure and utilize soft tissue allografts for patient care.
- Surgical Centers:These specialized facilities perform a high volume of elective procedures, including orthopedic and sports medicine surgeries. They prioritize efficient procurement and quick turnaround times for allograft delivery, particularly in the United States.
- Academic Hospitals:These institutions combine patient care with medical education and research, often handling complex cases requiring advanced allograft solutions. Their procurement decisions are often influenced by clinical trial data and long-term outcome studies.
- Ambulatory Clinics:These outpatient settings increasingly perform minor surgical procedures requiring readily available allograft products.
- Specialty Clinics:Focused on areas like dentistry or sports medicine, these clinics require specific allograft types tailored to their procedures.
- Rehabilitation Facilities:While not primary implanters, these facilities may influence post-surgical allograft choices through long-term patient management.
Procurement by Surgical Centers emphasizes speed and volume, whereas Academic Hospitals prioritize clinical evidence and innovation.
Distribution Channel:
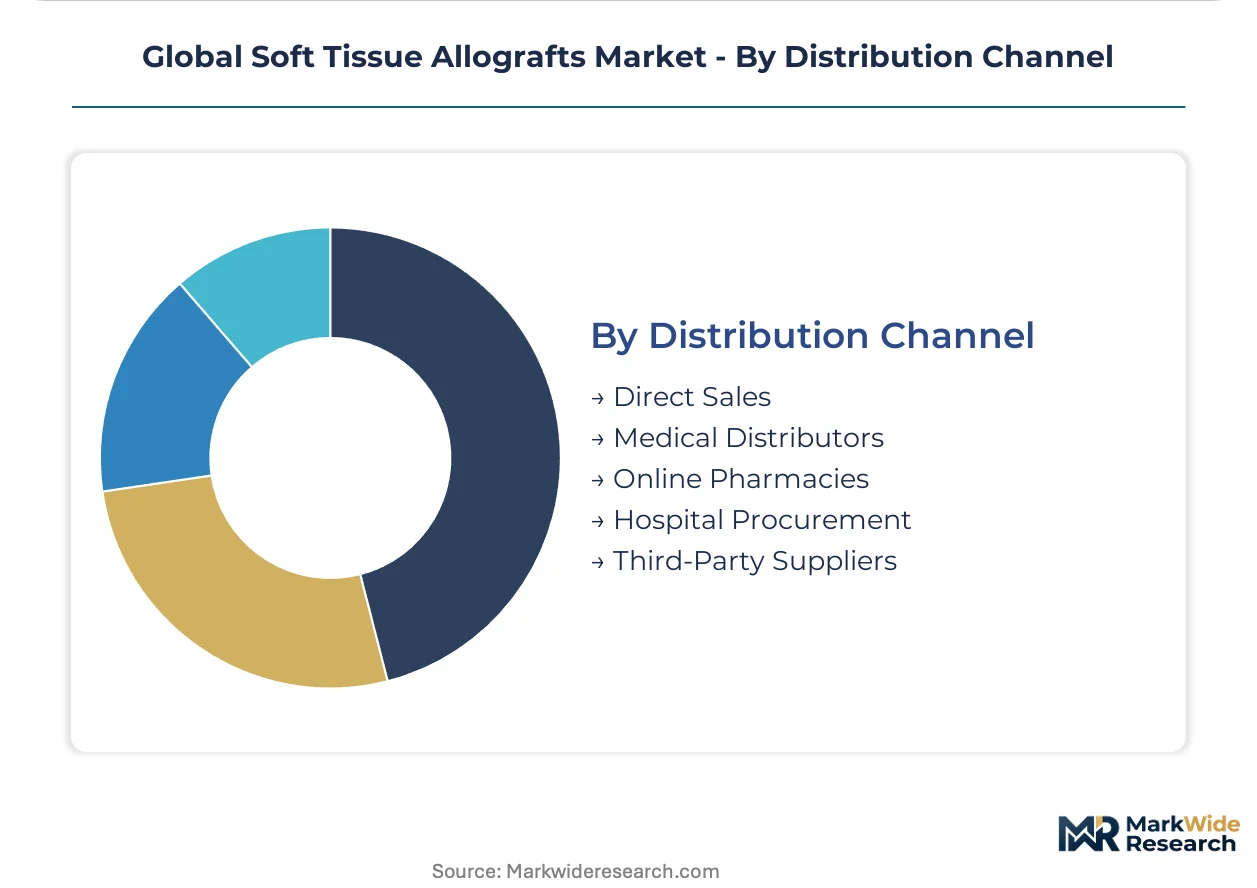
The distribution channel analysis reveals the primary pathways through which soft tissue allografts reach end-users, influencing supply chain concentration.
- Direct Sales:Manufacturers engage directly with hospitals and surgical centers, offering specialized product knowledge and tailored support. This channel allows for close customer relationships and direct feedback, particularly for innovative or niche allograft products.
- Medical Distributors:These intermediaries manage logistics, warehousing, and sales for multiple manufacturers, reaching a broad network of healthcare providers. They are crucial for market penetration in geographically diverse regions like Brazil and Mexico.
- Online Pharmacies:A nascent channel for certain medical supplies, offering convenience but limited for complex allograft procurement due to stringent regulations.
- Hospital Procurement:Large hospital networks and Group Purchasing Organizations often manage their own procurement, leveraging scale for better pricing and standardized product selection.
- Third-Party Suppliers:These providers offer specialized services, often managing inventory and just-in-time delivery for specific surgical needs.
Direct Sales offers specialized engagement, while Medical Distributors provide broad market reach and logistical efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks, such as those from the U.S. FDA and European Medicines Agency (EMA), significantly shape the global soft tissue allografts market. These stringent guidelines ensure product safety and efficacy, which in turn builds surgeon confidence and patient trust. The demand for advanced regenerative solutions drives innovation across various geographies.
United States
The United States exhibits strong demand for allografts, driven by high volumes of orthopedic and dental surgeries, especially in sports medicine. Compliance with the U.S. FDA's HCT/P regulations is a critical market entry requirement for tissue banks. Large hospital networks in major metropolitan areas like New York actively influence procurement criteria through value analysis models.
Germany
Germany's aging population fuels demand for allografts in joint reconstruction, complemented by a sophisticated dental care infrastructure. The European Medical Device Regulation (MDR) imposes rigorous clinical evidence requirements on manufacturers. Academic hospitals in cities like Munich and Berlin are at the forefront of adopting advanced allograft solutions and conducting research.
Japan
Aging demographics in Japan contribute to sustained demand for allografts in orthopedic surgery, particularly for degenerative conditions. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees tissue procurement and processing, ensuring strict safety standards. Major orthopedic surgery centers in Tokyo integrate allografts into advanced joint repair and reconstruction procedures.
Brazil
Brazil represents a significant untapped market, with a growing middle class and expanding access to advanced orthopedic and dental healthcare services. The country's National Health Surveillance Agency (ANVISA) regulates medical devices and tissue products. Private surgical centers in São Paulo are increasingly adopting allografts for sports medicine and reconstructive procedures.
Mexico
Mexico's healthcare expansion supports rising demand for allografts in orthopedic and dental applications. The Federal Commission for the Protection against Sanitary Risks (COFEPRIS) governs import and distribution of allograft products. Medical distributors in Mexico City facilitate broad market penetration of allograft solutions across various healthcare providers.
Global Soft Tissue Allografts Market Key Industry Players
Listed leaders compete with private specialists across tissue processing innovation and market reach in the soft tissue allografts sector. The market structure features large diversified orthopedic solution providers alongside specialized tissue banks and innovators focusing on minimally invasive surgical products. Strategic partnerships between tissue processors and medical device companies are common. Portfolio diversification into advanced graft types, like bio-inductive options, represents a key competitive move.
Within the specialized segment, Stryker Corporation occupies a significant position, representing a large diversified orthopedic solutions provider that integrates soft tissue allografts within its broader product portfolio. AlloSource exemplifies a non-profit, donor-centric model, anchoring a consistent supply of high-quality tissue, leveraging its unique structure to maintain donor relationships. Arthrex Inc. sits within the innovator archetype, focusing on minimally invasive surgical products designed primarily for sports medicine applications, differentiating its offering through specialized delivery systems and procedural solutions. These entities collectively influence market dynamics through their distinct operational and strategic approaches.
| Leading Market Players |
|---|
| Stryker Corporation |
| AlloSource |
| Arthrex Inc. |
| RTI Surgical Inc. |
| CONMED Corporation |
| Integra LifeSciences Corporation |
| Organogenesis Inc. |
| MiMedx Group Inc. |
| Globus Medical Inc. |
Cost & Logistics Intelligence
U.S. FDA HCT/P regulations gate both supply qualification and price differentiation simultaneously for soft tissue allografts. These stringent guidelines ensure product safety and efficacy, directly influencing processing costs and market access for manufacturers.
Pricing Analysis
Certification level (AATB accreditation, ISO 13485 compliance) creates the primary spread in allograft pricing. The dominant pricing model is per-unit transactional, reflecting the specialized nature of each processed tissue. Price differentiation stems from the quality grade, proprietary sterilization methods, and the level of after-sales support provided through direct sales channels. Pricing pressure arises from hospital value analysis models, which prioritize clinical evidence of reduced complication rates. Academic Hospitals, seeking advanced solutions, exhibit lower price sensitivity compared to Surgical Centers focused on high-volume efficiency.
Supply Chain Analysis
Strategic stockpiling of processed tissue is crucial for managing donor tissue variability and demand fluctuations in the allografts market. Geographic supply concentration for processing and distribution centers exists in the United States, Germany, and Japan. The supply chain fundamentally depends on the availability of human donor tissue, which remains a primary raw material dependency. Regulatory restrictions on tissue procurement and processing, coupled with donor scarcity, present a structural supply chain risk. Distribution runs through a hybrid model combining direct sales for specialized support and medical distributors for broad market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soft tissue allografts market presents a service-attach opportunity, with clinical education and long-term outcome tracking expanding faster than the initial graft sales.
For Market Incumbents: Secure sustained donor tissue supply through ethical procurement partnerships and efficient processing. Invest in next-generation sterilization techniques, such as Supercritical CO2, to preserve biomechanical integrity and enhance graft performance. Counter competition from autografts by generating robust clinical evidence demonstrating superior long-term outcomes and reduced revision rates. Expand direct sales channels to offer specialized product knowledge and tailored support to large hospital networks.
For New Entrants and Emerging Players: Anchor in specialized niches like urogynecological reconstruction or bio-inductive graft development. Target emerging markets such as Brazil and Mexico, leveraging expanding healthcare access and growing demand for orthopedic and dental procedures. Focus on developing minimally invasive surgical products that integrate seamlessly with allograft solutions. A go-to-market angle emphasizing superior graft integration and accelerated tissue regeneration offers a distinct competitive advantage.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting in an upward direction across advanced processing technologies. The market demonstrates long-term viability, driven by aging demographics and sustained sports medicine demand. Target acquisition archetypes include specialized tissue banks with proprietary sterilization methods or unique bio-inductive graft portfolios. The signal to watch is increasing reimbursement for allograft procedures supported by strong clinical evidence, indicating broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Sterilization R&D | Enhance graft safety and biomechanical integrity, increasing surgeon confidence and patient trust. |
| Bio-inductive Graft Development | Promote active tissue regeneration and integration, improving long-term patient outcomes. |
| Emerging Market Expansion | Tap into growing demand in countries like Brazil and Mexico with expanding healthcare infrastructure. |
| Clinical Evidence Generation | Meet rigorous regulatory requirements, particularly the EU MDR, ensuring market access. |
| Strategic Partnerships | Combine tissue processing expertise with device delivery systems for comprehensive solutions. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary data involved conversations with orthopedic surgeons, dental specialists, tissue bank executives, and hospital procurement managers. Secondary sources included U.S. FDA guidance documents, European Medicines Agency reports, AATB accreditation standards, ISO 13485 certifications, and company annual reports. This approach ensured a balanced perspective through bottom-up market insights and top-down industry trends.
The analytical framework projected market dynamics over the analysis window, segmenting by product type, application, end-user, distribution channel, and regional regulatory compliance. CAGRs were derived from historical trends, validated against future demand projections, and influenced by key market drivers. Industry-specific forecast inputs included aging population data, sports injury prevalence, and dental procedure volumes, providing a robust basis for market sizing.
Material uncertainties — unforeseen regulatory changes, shifts in donor tissue availability, or breakthroughs in competing regenerative therapies — sit outside the modeled envelope. Forecasts reflect assumptions based on current market conditions and anticipated developments. Revision becomes warranted when major policy shifts or clinical practice guidelines cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Patient-Controlled Analgesic Pumps Market
Medical Devices
Global Blood Banking Devices Market
Medical Devices
Electroceutical Devices Market
Medical Devices
Drug Delivery Solutions Market
Medical Devices
Elastomeric Infusion Pump Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Chest Drainage System Market
Medical Devices
Global Transcatheter Embolization and Occlusion Devices Market
Medical Devices
Feeding Tubes Market
Medical Devices
At-Home Laser Hair Removal Devices Market
Medical Devices
Radial Access Catheter Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
France Respiratory Devices Market
Medical Devices
Global Electromyography Devices Market
Medical Devices
North America Ablation Devices Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market