
 United Kingdom Minimally Invasive Surgery Devices Market | 2026-2036
United Kingdom Minimally Invasive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Minimally Invasive Surgery Devices Market Analytics
Premium CE-marked surgical instrument tiers is bifurcating the United Kingdom minimally invasive surgery devices landscape into high-specification and standard-performance supply channels. Medtronic PLC leverages its integrated laparoscopic portfolio to dominate procurement frameworks across NHS England. Smith & Nephew differentiates through specialized suturing and advanced wound closure systems. Stryker Corporation anchors its position via energy devices and surgical navigation platforms deployed in teaching hospitals.
Minimally invasive surgery devices encompass precision-engineered instruments, visualization systems, and powered equipment designed for insertion through small incisions under endoscopic or laparoscopic guidance, typically manufactured from surgical-grade stainless steel, titanium alloys, or polymer composites with tolerances measured in micrometers to ensure tissue manipulation without open-field exposure. Robotic surgery systems capture premium value pools as capital-intensive installations require dedicated maintenance contracts and specialist training pathways, while laparoscopic instruments constitute the volume base with recurring replacement cycles driven by sterilization wear. Energy devices within the technology dimension represent the fastest-expanding margin segment as bipolar and ultrasonic platforms displace conventional monopolar units in gynecological and general surgery applications.
The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements for all surgical devices post-Brexit, with MHRA vigilance protocols mandating adverse event reporting that shapes product liability exposure and design modification cycles for manufacturers. NHS Supply Chain framework agreements further constrain market access through centralized tendering that favors suppliers demonstrating compliance with ISO 13485 quality management systems and transparent device traceability. Stakeholders must monitor evolving MHRA recognition routes for EU-approved devices and the pace of NHS capital allocation toward robotic-assisted surgical suites.
Market Dynamics
NHS Supply Chain framework agreements are consolidating purchasing power across England's hospital trusts, squeezing margins for device manufacturers while favoring suppliers with comprehensive laparoscopic portfolios and transparent UKCA marking compliance.
Growth Catalysts
- MHRA Post-Market Surveillance Mandates:Tightened adverse event reporting requirements are accelerating replacement cycles for aging surgical implants as trusts preemptively upgrade device inventories to meet vigilance protocols.
- Robotic-Assisted Surgery Adoption:Teaching hospitals in Greater London are expanding dedicated surgical suites, creating pull-through demand for complementary laparoscopic instruments and energy devices.
- Specialist Center Clustering:Concentration of gynecological and colorectal surgical hubs in the South East is generating localized demand spikes for bipolar and ultrasonic energy platforms.
Market Restraints
- Sterilization-Induced Instrument Degradation:Repeated autoclave cycles degrade polymer composite instrument tolerances, forcing premature replacement and inflating lifetime ownership costs for NHS trusts.
- UKCA Transition Friction:Manufacturers face dual compliance burdens as MHRA recognition routes for EU-approved devices remain in flux, delaying product launches and extending certification timelines.
- Capital Intensity of Robotic Platforms:Da Vinci and comparable systems require dedicated maintenance contracts and specialist training pathways, limiting deployment to tertiary centers with secured capital allocation.
Strategic Opportunities
- Underpenetrated Regions:NHS trusts in the North East and Yorkshire show lower laparoscopic surgery penetration rates, presenting expansion targets for instrument suppliers with regional service networks.
- Energy Device Convergence:Integration of bipolar and ultrasonic modalities into single handheld platforms is opening premium pricing tiers in general surgery applications.
- Framework Agreement Optimization:Suppliers demonstrating ISO 13485 compliance and device traceability systems can secure preferred supplier status under NHS Supply Chain centralized tendering.
Industry Challenges
- Specialized Surgical Training Bottlenecks:Robotic-assisted procedures require credentialed surgeons, and NHS training pipeline capacity constrains adoption velocity regardless of capital availability.
- Legacy System Integration Complexity:New visualization and navigation platforms must interface with existing hospital IT infrastructure, complicating deployment in older NHS facilities.
- Supply Chain Reconfiguration Post-Brexit:Customs friction and regulatory divergence are forcing manufacturers to establish UK-based distribution and servicing capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Minimally Invasive Surgery Devices Market |
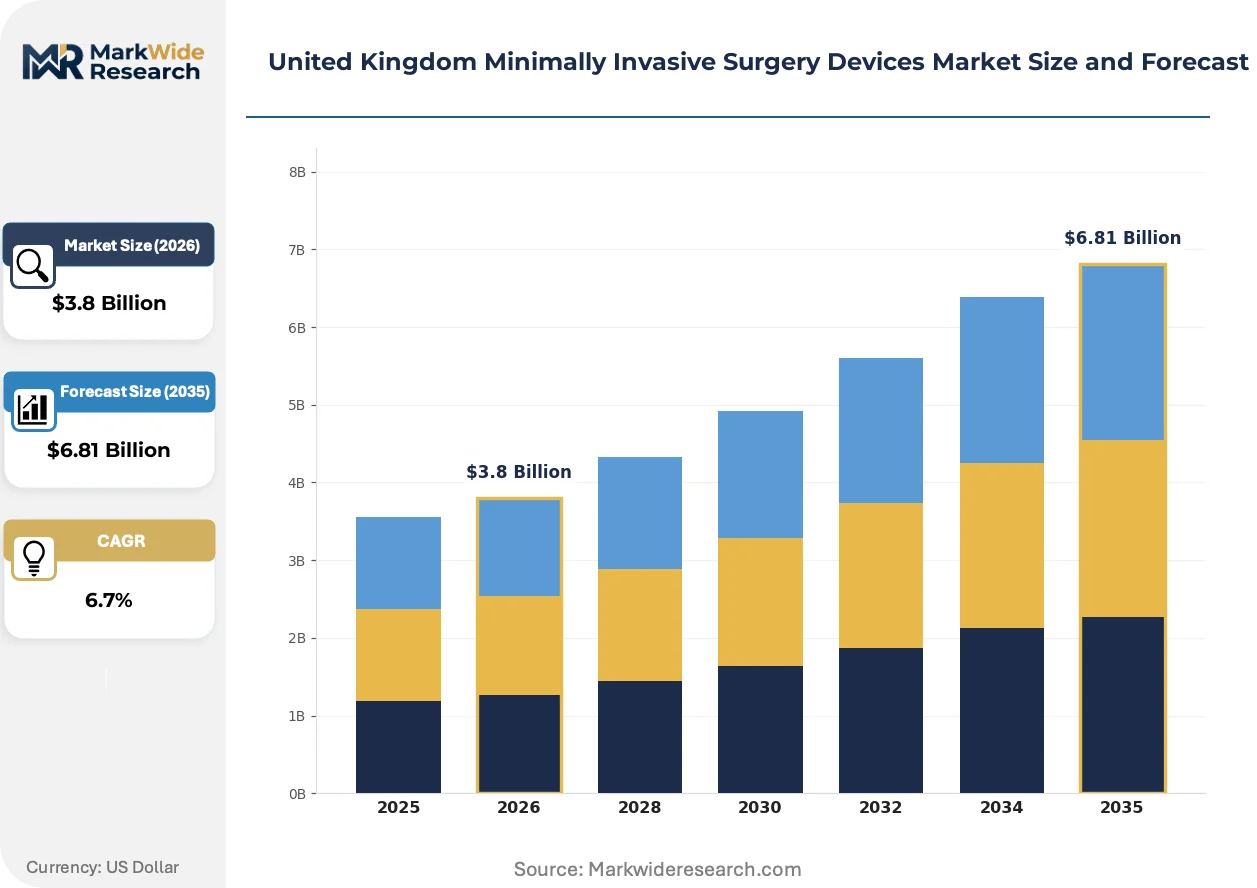
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laparoscopic Instruments, Endoscopic Devices, Robotic Surgery Systems, Suturing Devices Application: General Surgery, Gynecological Procedures, Urological Surgery, Cardiothoracic Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: 3D Imaging, Energy Devices, Surgical Navigation, Laser Technology |
| Companies Covered | Medtronic PLC, Olympus Corporation, Stryker Corporation, Intuitive Surgical Inc, Smith & Nephew, Abbott Laboratories, Zimmer Biomet, Johnson & Johnson, Koninklijke Philips NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Minimally Invasive Surgery Devices Market Evolving Landscape
Device miniaturization and intelligent energy delivery are converging to reshape surgical workflows, with manufacturers racing to embed real-time tissue feedback systems into handheld instruments.
Ultrasonic energy platforms are supplanting conventional monopolar units in gynecological and general surgery suites across NHS England. Gynecological oncologists at specialist London trusts are adopting these systems at accelerating pace, driven by reduced thermal spread and improved vessel sealing. The structural consequence is compression of monopolar instrument replacement cycles as trusts standardize around bipolar-ultrasonic hybrid platforms.
MHRA's UKCA marking requirements are tightening post-market surveillance obligations for all surgical devices. Manufacturers now face mandatory adverse event reporting and design modification cycles that extend product development timelines. Laparoscopic instrument suppliers with established UK quality management systems are responding faster than competitors reliant on EU-notified body certifications.
Centralized procurement through NHS Supply Chain frameworks is consolidating purchasing decisions at the trust level. Independent hospitals and smaller surgical centers are losing direct supplier relationships as aggregated tenders favor volume-discounted framework agreements. This shift is most visible in Greater London, where procurement teams at major teaching hospital trusts now negotiate multi-year instrument supply contracts directly with manufacturers.
United Kingdom Minimally Invasive Surgery Devices Market Segmentation
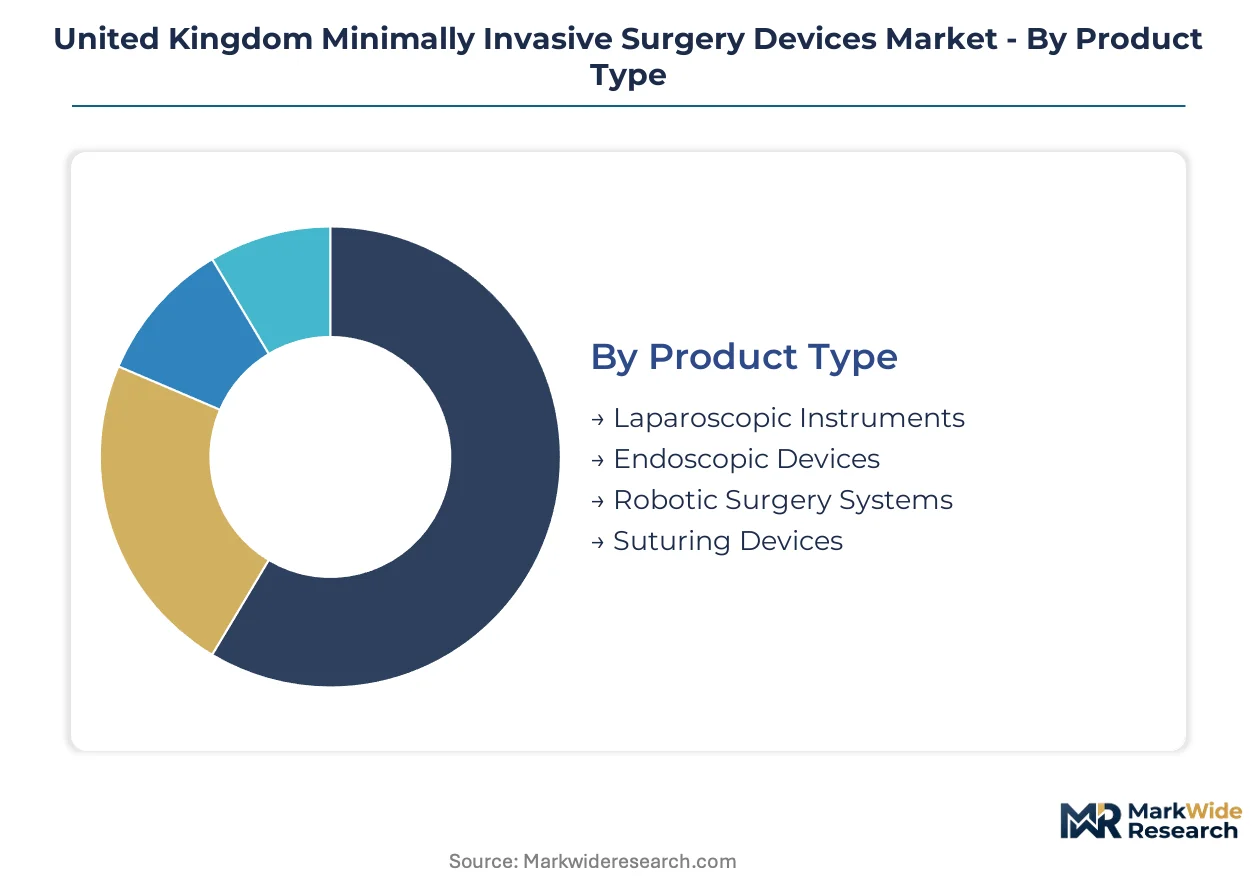
Segmentation in the United Kingdom minimally invasive surgery devices market reveals distinct margin architectures across product tiers and clinical applications. NHS procurement frameworks reward suppliers who align portfolio depth with specific hospital trust requirements.
Product Type:
Margin pools concentrate in capital-intensive platforms requiring dedicated service contracts and recurring consumable attachments.
- Laparoscopic Instruments:Surgical-grade stainless steel and polymer composite instruments manufactured to micrometer tolerances for tissue manipulation. Demand clusters in NHS England trusts expanding laparoscopic suites, driven by sterilization-wear replacement cycles and MHRA vigilance protocols.
- Robotic Surgery Systems:Capital-intensive installations integrating visualization, navigation, and powered instrumentation with proprietary maintenance pathways. Greater London teaching hospitals anchor procurement, constrained by specialist training pipeline capacity and secured capital allocation.
- Endoscopic Devices:Flexible visualization systems for diagnostic and interventional procedures across gastrointestinal and respiratory applications.
- Suturing Devices:Specialized wound closure systems spanning mechanical, absorbable, and energy-assisted modalities for laparoscopic port sites.
The dominant share belongs to laparoscopic instruments, while robotic surgery systems are closing the gap fastest.
Application:
Volume distribution tracks the geographic clustering of specialist surgical hubs across English regions.
- General Surgery:Cholecystectomy, hernia repair, and bariatric procedures utilizing standard laparoscopic instrument sets. South East specialist centers generate concentrated demand for energy devices as bipolar and ultrasonic platforms displace monopolar units.
- Gynecological Procedures:Hysterectomy, myomectomy, and oncological interventions requiring precision vessel sealing and reduced thermal spread. London trusts are adopting ultrasonic energy platforms at accelerating pace, compressing legacy instrument replacement cycles.
- Urological Surgery:Prostatectomy and nephrectomy applications with specific requirements for nerve-sparing instrumentation.
- Cardiothoracic Surgery:Minimally invasive valve repair and lung resection procedures with stringent visualization demands.
General surgery captures the largest procedure volume, though gynecological applications are expanding most quickly.
End User:
Procurement authority is consolidating toward centralized frameworks that favor suppliers with comprehensive service networks.
- Hospitals:Acute NHS trusts with dedicated laparoscopic suites and robotic-assisted surgical programs. Framework agreements aggregate purchasing across England, squeezing margins while demanding transparent UKCA marking and ISO 13485 compliance.
- Ambulatory Surgical Centers:Independent day-case facilities performing routine procedures with faster instrument turnover requirements.
- Specialty Clinics:Gynecological and urological focused practices with selective device procurement outside central frameworks.
- Research Institutions:Teaching hospitals and academic medical centers piloting next-generation platforms and training pathways.
Hospitals command the dominant procurement volume, yet ambulatory surgical centers are gaining share fastest.
Technology:
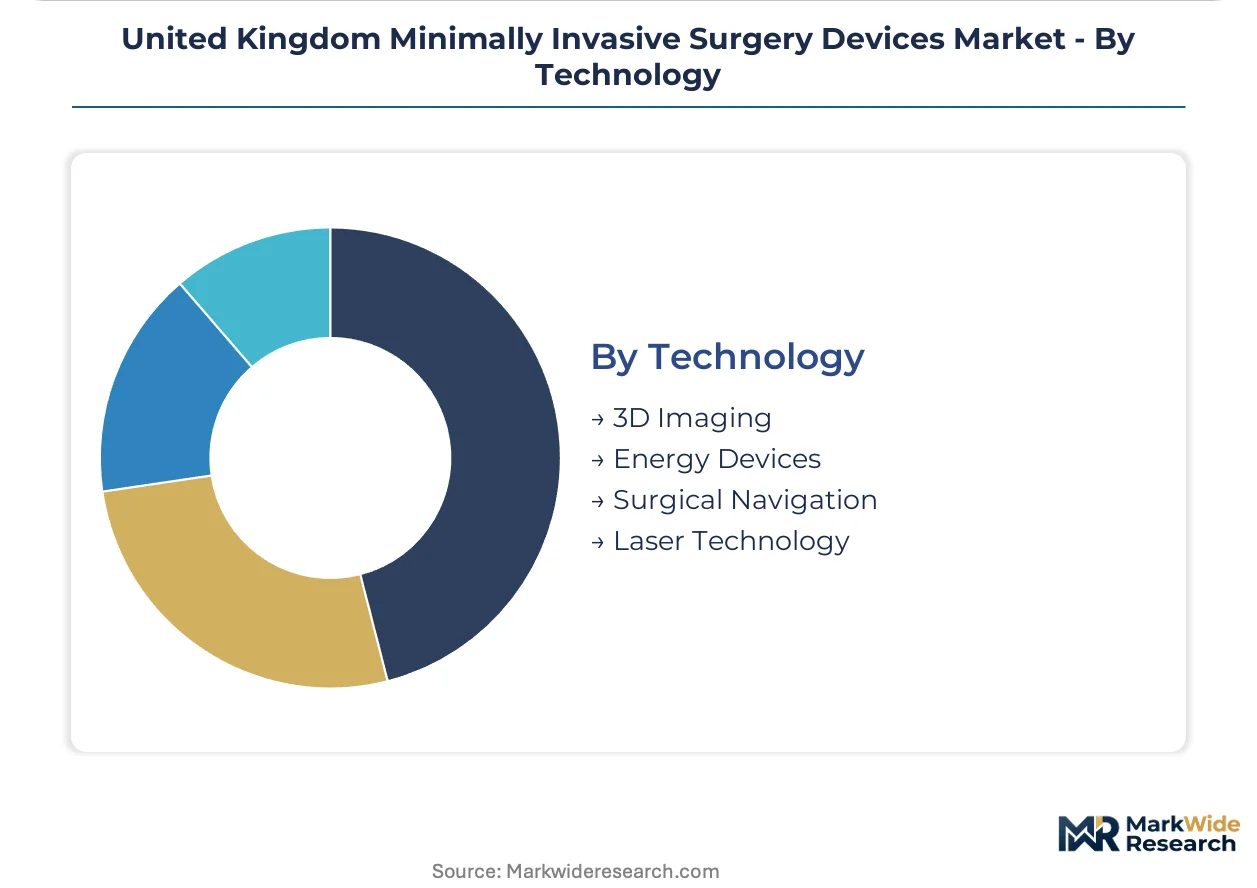
Technology tiering separates premium visualization and energy platforms from standard-performance alternatives.
- Energy Devices:Bipolar and ultrasonic platforms delivering controlled thermal energy with real-time tissue feedback. Gynecological and general surgery suites across NHS England are standardizing around hybrid bipolar-ultrasonic systems, displacing conventional monopolar inventories.
- 3D Imaging:Stereoscopic visualization systems enhancing depth perception in complex laparoscopic and robotic procedures. Teaching hospitals in Greater London anchor adoption, constrained by integration complexity with legacy IT infrastructure.
- Surgical Navigation:Image-guided platforms integrating preoperative imaging with intraoperative instrument tracking.
- Laser Technology:Precision ablation and cutting systems for specialized urological and gynecological applications.
Energy devices hold the dominant technology position, while 3D imaging is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minimally invasive surgery device procurement concentrates in England's specialist surgical corridors, where NHS trust frameworks and MHRA regulatory oversight shape distribution patterns. Scotland, Wales, and Northern Ireland operate distinct health service procurement structures with varying laparoscopic adoption rates. Sub-regional analysis reveals acute demand clustering around teaching hospital networks and robotic surgery hubs.
Greater London
London's teaching hospital trusts drive premium-tier device procurement through dedicated robotic-assisted surgical programs. MHRA vigilance protocols mandate UKCA-marked instrument inventories across Imperial College Healthcare and Guy's and St Thomas' NHS Foundation Trust. The South East cluster generates concentrated demand for bipolar and ultrasonic energy platforms as gynecological oncology centers standardize equipment specifications.
South East England
Specialist colorectal and gynecological surgical hubs in Surrey and Sussex generate localized demand spikes for advanced energy devices. NHS Supply Chain framework agreements aggregate purchasing across Oxford University Hospitals and Brighton and Sussex University Hospitals. Southampton's university hospital network anchors regional adoption of 3D visualization systems for complex laparoscopic procedures.
Midlands
University Hospitals Birmingham and Nottingham University Hospitals anchor laparoscopic suite expansion across the East and West Midlands. MHRA post-market surveillance mandates accelerate replacement cycles for aging instrument inventories in Birmingham's Queen Elizabeth Hospital. Leicester's specialist cardiothoracic center generates niche demand for precision suturing devices in minimally invasive valve repair.
North England
NHS trusts in Yorkshire and the North East show underpenetrated laparoscopic surgery adoption relative to southern regions, presenting expansion targets for instrument suppliers. Manchester's Royal Infirmary and Leeds Teaching Hospitals NHS Trust are consolidating procurement through regional framework agreements. Sheffield's teaching hospital network pilots next-generation surgical navigation platforms with integrated preoperative imaging.
Scotland
NHS Scotland operates independent procurement frameworks distinct from NHS Supply Chain England, with Health Improvement Scotland overseeing device vigilance. Edinburgh's Royal Infirmary and Glasgow's Queen Elizabeth University Hospital anchor robotic surgery adoption north of the border. Aberdeen's specialist surgical center generates concentrated demand for endoscopic devices across gastrointestinal and respiratory applications.
United Kingdom Minimally Invasive Surgery Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United Kingdom minimally invasive surgery devices market. Integrated multinationals with comprehensive laparoscopic portfolios dominate NHS framework agreements through volume-discounted supply contracts. Specialized instrument manufacturers occupy mid-tier positions with differentiated suturing and wound closure offerings. Emerging robotic platform vendors compete for capital-intensive installation contracts at teaching hospital trusts. Competitive dynamics center on securing preferred supplier status under centralized tendering and establishing UK-based servicing networks post-Brexit.
Among the integrated multinational tier, Medtronic PLC and Stryker Corporation exemplify archetypes that anchor procurement frameworks through portfolio breadth. Smith & Nephew occupies a specialized position within advanced wound closure systems. Olympus Corporation represents the visualization-centric archetype with endoscopic platform concentration. These named entities illustrate how competitive positioning stratifies across technology integration depth, geographic servicing capability, and compliance velocity with MHRA regulatory transitions.
| Leading Market Players |
|---|
| Medtronic PLC |
| Olympus Corporation |
| Stryker Corporation |
| Intuitive Surgical Inc |
| Smith & Nephew |
| Abbott Laboratories |
| Zimmer Biomet |
| Johnson & Johnson |
| Koninklijke Philips NV |
| Others |
Value Network & Pricing Analysis
Ninety-day instrument replacement cycles at NHS trusts concentrate purchasing leverage with framework-preferred suppliers, compressing margins for manufacturers without UKCA-marked inventory buffers while amplifying pricing power for holders of centralized tender awards.
Pricing Analysis
MHRA UKCA marking requirements dictate the pricing tier structure across the United Kingdom minimally invasive surgery devices landscape. Three-tier pricing separates CE-legacy instruments from transitional UKCA-certified stock and premium robotic-compatible instrument sets. Price differentiation hinges on certification velocity and sterilization-cycle durability ratings. Cost compression in standard laparoscopic tiers is intensifying because NHS Supply Chain aggregation favors volume-discounted multi-year contracts. Ambulatory surgical centers show highest price sensitivity; teaching hospital trusts with secured capital allocation demonstrate lowest.
Supply Chain Analysis
Surgical-grade stainless steel forging capacity in Germany, polymer composite molding in Switzerland, and titanium alloy machining in the United States anchor upstream supply for United Kingdom minimally invasive surgery devices. Finished instrument assembly draws from established manufacturing footprints in Ireland, the Netherlands, and domestic UK facilities post-Brexit customs friction. Single-source vulnerability concentrates in specialized energy device transducer supply. Distribution runs through NHS Supply Chain centralized warehousing with direct-to-trust logistics for robotic platform installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in United Kingdom minimally invasive surgery devices are shifting toward ecosystem lock-in as robotic system vendors bundle proprietary instrument attachments with maintenance contracts, creating interoperability barriers for standalone instrument suppliers.
For Market Incumbents: Shield framework positions by accelerating UKCA marking completion for full laparoscopic portfolios before MHRA recognition route deadlines. Deepen backward integration into surgical-grade stainless steel sourcing to offset raw material cost volatility. Prioritize sterilization-cycle durability R&D to extend replacement intervals and defend against lower-cost competitors. For New Entrants and Emerging Players: Differentiate on regional service density by establishing Yorkshire and North East technical support networks where incumbent coverage remains thin. Target gynecological energy device segments where ultrasonic platform standardization is incomplete. Pursue specialist clinic direct sales outside NHS Supply Chain aggregation. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because framework agreement concentration favors scaled suppliers with comprehensive portfolios and UK-based servicing infrastructure. Acquisition targets include mid-tier suturing specialists with ISO 13485 compliance and established hospital relationships. Monitor MHRA recognition route stability as the inflection signal for valuation recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Marking Acceleration | Early certification completion secures preferred supplier status under NHS Supply Chain tendering ahead of regulatory deadlines. |
| Hospital System Partnership | Direct relationships with Imperial College Healthcare and Guy's and St Thomas' NHS Foundation Trust anchor robotic program adoption. |
| Energy Device Platform Integration | Bipolar-ultrasonic hybrid handheld systems capture premium pricing in gynecological and general surgery applications. |
| Regional Service Network Expansion | Technical support infrastructure in underpenetrated Yorkshire and North East markets unlocks trust-level procurement access. |
| Software Companion Development | Real-time tissue feedback systems embedded in handheld instruments differentiate premium-tier energy device offerings. |
Research Methodology
A spread of perspectives from hospital procurement managers, biomedical engineers, GPO contracts administrators, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork with NHS trust supply chain directors and surgical device manufacturer account executives combined with secondary validation against MHRA vigilance databases, NHS Supply Chain framework documentation, and hospital procurement records. Bottom-up instrument replacement cycle modeling triangulated against top-down market sizing across the United Kingdom geography.
Segmentation dimensions modeled include product type tier, application specialty, end-user procurement authority, and technology platform architecture across the projection horizon. CAGRs derived from procedure volume trajectories, capital allocation patterns at teaching hospital trusts, and energy device substitution curves. Forecast inputs incorporated MHRA regulatory transition timelines and NHS capital expenditure planning cycles without specifying period endpoints.
The analysis sits within stated boundaries; outcomes outside sustained NHS funding commitments, stable MHRA-EU recognition protocols, or sterilization-wear tolerance improvements would require recalibration. Practitioners should keep alternative scenarios live as regulatory divergence and capital allocation priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Diabetes Devices Market
Medical Devices
Dysphagia Management Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Medical Devices Clinical Trials Market
Medical Devices
Self-Injections Market
Medical Devices
Phototherapy Lamps Market
Medical Devices
Powered Mattress System Market
Medical Devices
Europe Foot Orthotic Insoles Market
Medical Devices
Middle East and Africa Hip and Knee Reconstruction Devices Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
South America C-Arms Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Global Eye Massage Machine Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Blood Warmers Market