
 Global Transcatheter Embolization and Occlusion Devices Market | 2026-2036
Global Transcatheter Embolization and Occlusion Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transcatheter Embolization and Occlusion Devices Market Foresight
Germany's precision manufacturing corridor is reshaping supply security for nitinol-based embolic coils. Boston Scientific Corporation leverages captive wire-drawing capabilities to sustain margin control across European distribution channels. Cook Medical anchors its competitive position through deep specialization in custom microcatheter geometries for neurovascular access. Stryker Corporation dominates the North American hospital contracting landscape through integrated imaging-navigation bundles.
Transcatheter embolization and occlusion devices comprise detachable coils, flow-diverting plugs, calibrated microspheres, and liquid embolic agents delivered via fluoroscopy-guided catheter systems to occlude target vessels or abnormal vascular structures. These devices function through mechanical vessel blockage, flow disruption, or sclerotic tissue response, with nitinol shape-memory alloys and platinum-tungsten radiopaque markers defining core material specifications. Coils retain the largest installed base across hemorrhage control applications, while liquid embolic systems command premium positioning in arteriovenous malformation therapy where catheter navigability limits mechanical alternatives. The ambulatory surgical center end-user segment demonstrates the steepest capacity expansion as same-day embolization protocols gain protocol adoption.
The FDA's 510(k) clearance framework and the EU Medical Device Regulation's clinical evidence requirements jointly determine commercialization timelines and post-market surveillance obligations for device manufacturers. Japan's PMDA enforces stringent biocompatibility testing protocols that filter non-specialized entrants from the neurovascular device category. Stakeholders must monitor evolving CMS procedural coding decisions for embolization therapies, as reimbursement granularity directly influences hospital capital allocation to interventional radiology suites.
Market Dynamics
Nitinol wire supply concentration in Germany's precision manufacturing corridor is forcing device makers to secure captive drawing capabilities or accept margin compression across European distribution channels.
Growth Catalysts
- FDA 510(k) Pathway Efficiency:The premarket notification framework for class II devices compresses development timelines for embolic coil iterations, accelerating hospital procurement cycles in the United States.
- Same-Day Discharge Protocols:Ambulatory surgical centers are expanding interventional radiology capacity as payors mandate reduced length-of-stay for hemorrhage control procedures.
- Japan PMDA Biocompatibility Standards:Stringent neurovascular testing protocols filter non-specialized entrants, creating premium positioning for compliant device portfolios.
Market Restraints
- Platinum-Tungsten Marker Volatility:Radiopaque alloy input costs fluctuate with precious metal markets, squeezing coil manufacturing margins unpredictably.
- Single-Source Nitinol Supply:German wire-drawing concentration creates geographic vulnerability for shape-memory alloy procurement across European device assembly.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation's expanded post-market surveillance obligations extend recertification timelines and compliance expenditure.
Strategic Opportunities
- India Interventional Radiology Infrastructure:Tertiary hospital expansion in Mumbai and Delhi creates underpenetrated demand for calibrated microsphere portfolios.
- Liquid Embolic-Conformable Coil Convergence:Hybrid delivery systems combining Onyx-class polymers with detachable coil mechanics address arteriovenous malformation complexity.
- US CMS Procedural Coding Expansion:Reimbursement granularity for mechanical thrombectomy adjuncts incentivizes capital allocation to neurovascular service lines.
Industry Challenges
- Interventional Radiologist Training Pipeline:Fellowship program capacity constraints limit operator availability for complex neurovascular access procedures.
- Microcatheter-MRI Compatibility Certification:Safety testing for 3-tesla magnetic resonance environments extends product development cycles and regulatory submission costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transcatheter Embolization and Occlusion Devices Market |
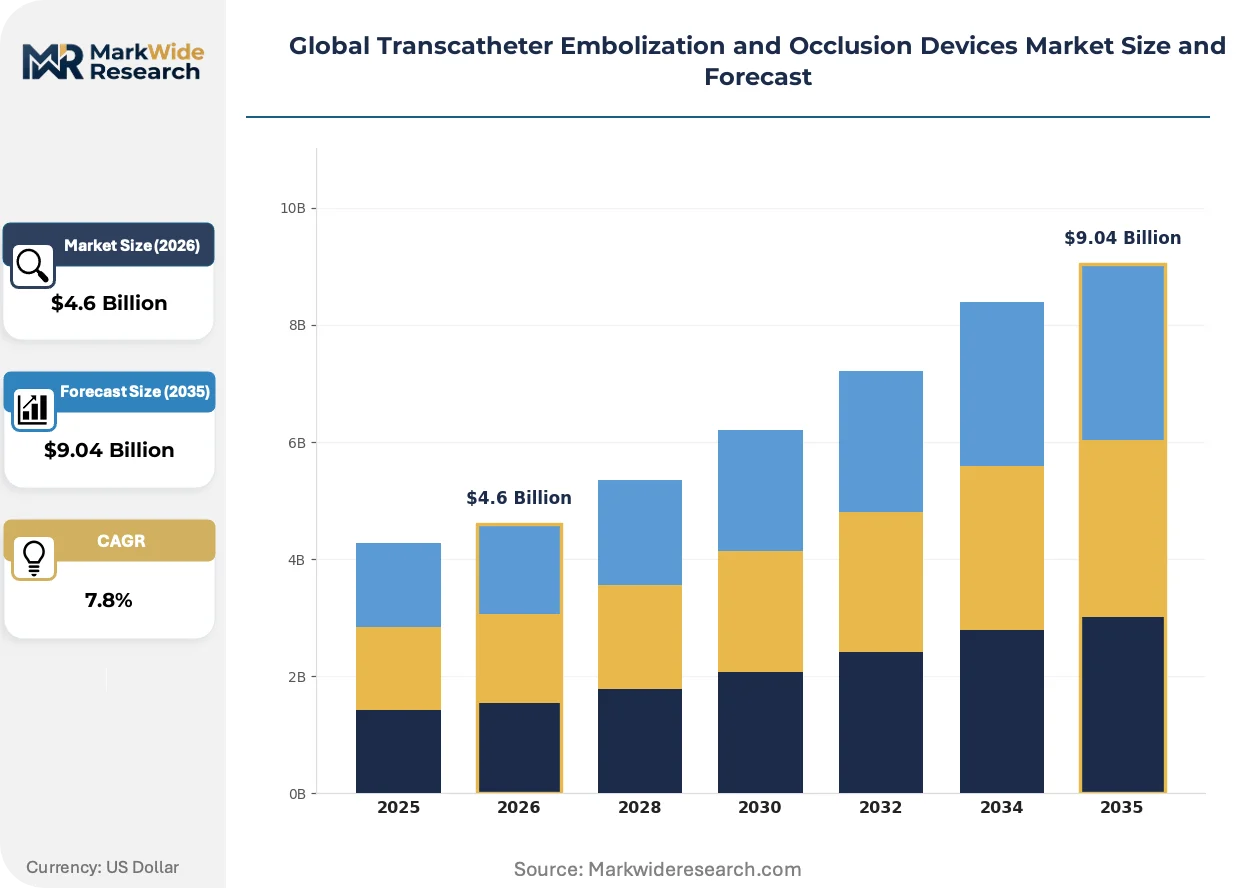
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $9.04 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
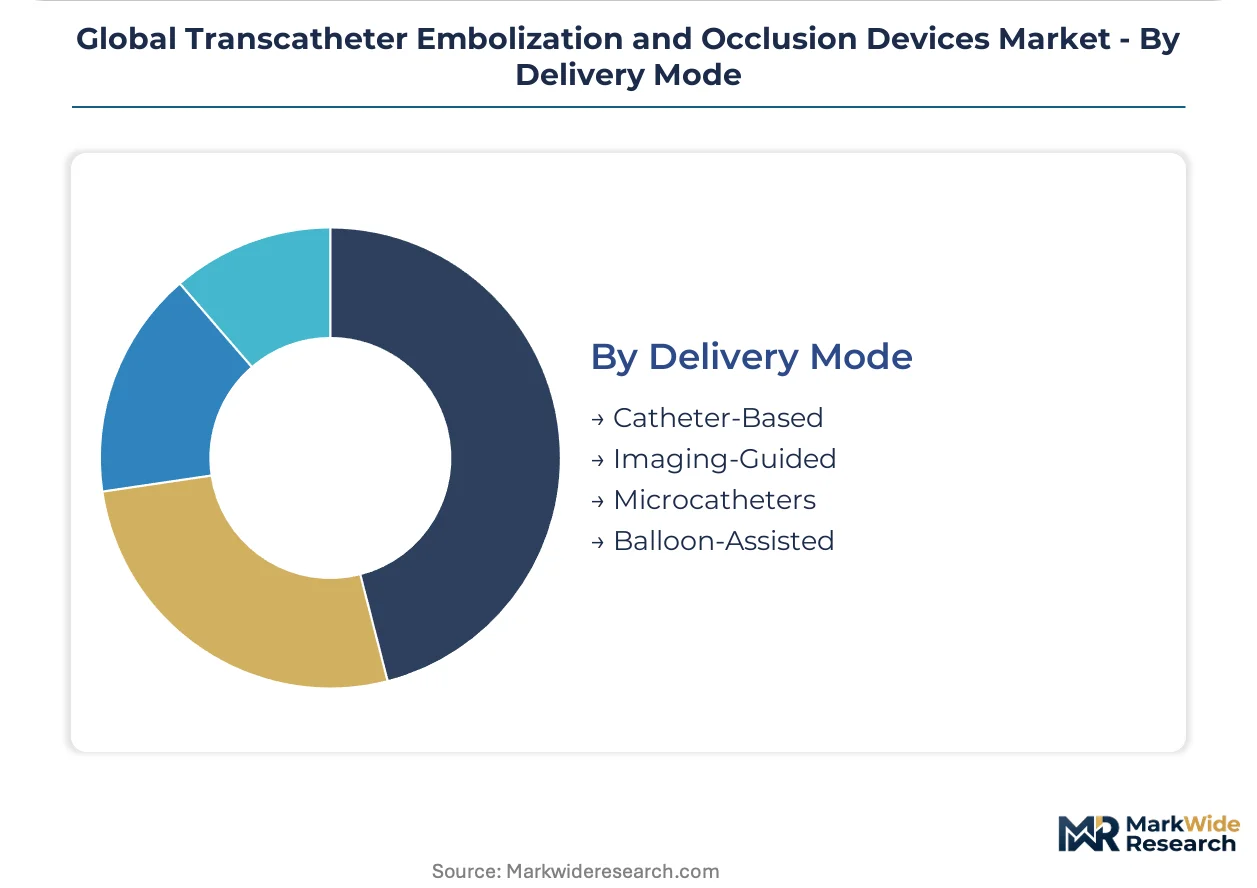
| Segmentation | Product Type: Coils, Plugs, Balloons, Particles, Liquids Therapy Area: Vascular Malformations, Tumor Embolization, Gastrointestinal Bleeds, Uterine Fibroids End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Laboratories Delivery Mode: Catheter-Based, Imaging-Guided, Microcatheters, Balloon-Assisted |
| Companies Covered | Abbott Laboratories, Cook Medical, Boston Scientific Corporation, Merit Medical Systems, Stryker Corporation, Medtronic plc, Penumbra, Inc., Johnson & Johnson Services, Inc., Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transcatheter Embolization and Occlusion Devices Market Shifts & Advancements
Computational modeling is compressing device development cycles while regulatory frameworks force evidence-generation investments that reshape competitive capital allocation.
Shape-memory alloy processing is virtualizing traditional wire-forming workflows. Finite element analysis platforms now simulate nitinol phase transformation behavior before physical prototyping, cutting iteration costs for embolic coil geometries. Tier-one manufacturers deploy these tools to accelerate neurovascular product pipelines while smaller entrants face capability gaps.
EU MDR Article 61 clinical evaluation requirements are intensifying post-market study obligations for flow-diverting devices. Manufacturers must generate real-world evidence on thromboembolic complication rates to maintain CE marking, diverting R&D resources toward surveillance infrastructure. Neurovascular plug portfolios face the steepest compliance burden as notified bodies scrutinize long-term occlusion durability data.
Hospital procurement committees are consolidating vendor relationships around integrated imaging-navigation bundles. Interventional radiology departments in the United States increasingly contract with single-source providers for catheter, coil, and fluoroscopy system packages, compressing standalone device margins. This concentration favors manufacturers with captive navigation technology portfolios over pure-play embolic suppliers.
Global Transcatheter Embolization and Occlusion Devices Market Segmentation
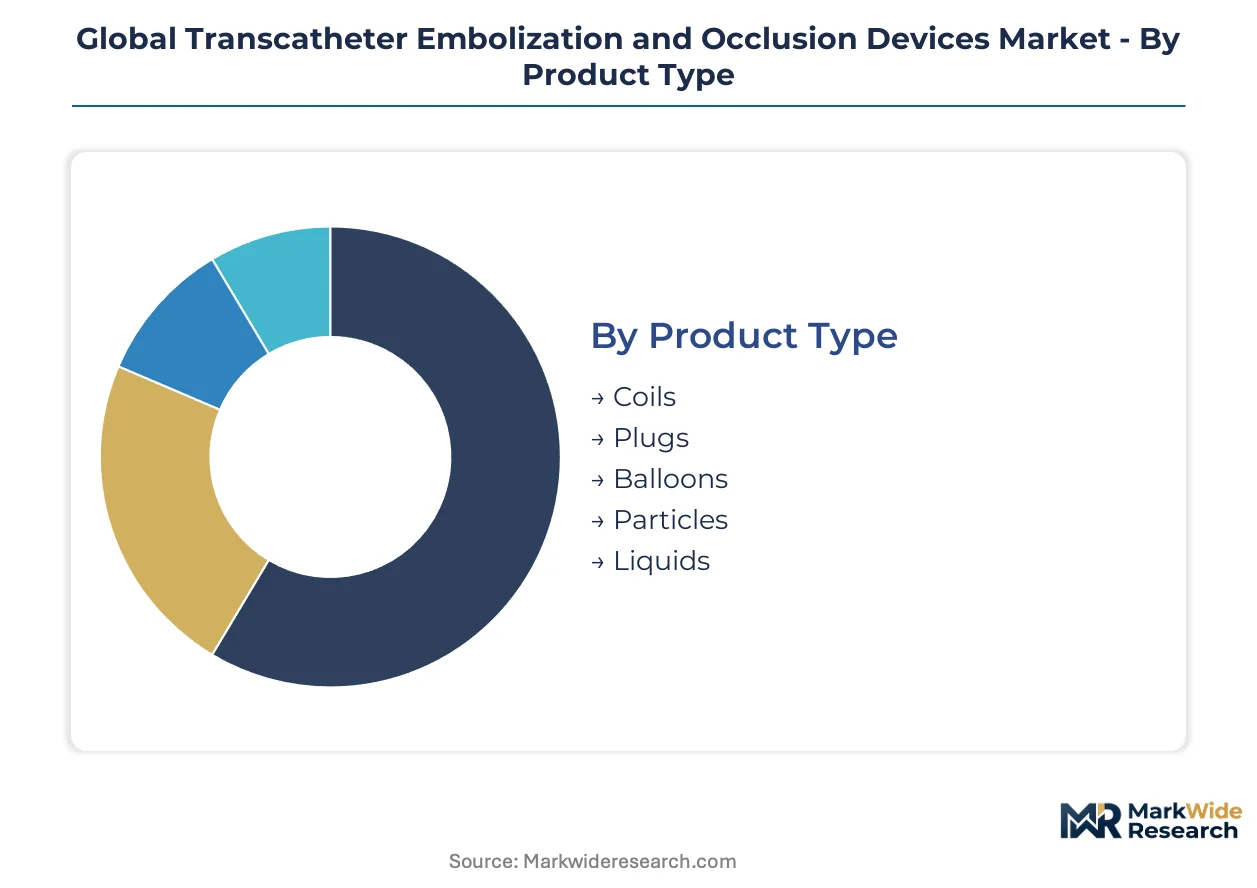
Device taxonomy in transcatheter embolization determines reimbursement coding precision and capital equipment bundling strategies. Manufacturers configure product portfolios around procedural workflow integration rather than standalone device performance.
Product Type:
After-sales service intensity varies sharply across device categories, with coil systems requiring extensive physician training support and liquid embolics demanding technical field presence for mixing protocols.
- Coils:Platinum-tungsten radiopaque markers on nitinol or stainless steel cores enable fluoroscopic visualization during deployment. Demand clusters in United States tertiary hospitals for hemorrhage control, constrained by interventional radiologist training pipeline limitations. Coil systems retain the largest installed base across neurovascular applications.
- Liquids:Ethylene vinyl alcohol copolymers and n-butyl cyanoacrylate formulations penetrate tortuous vasculature unreachable by mechanical devices. Concentrated demand in German and Japanese academic medical centers for arteriovenous malformation therapy, where catheter navigability restricts coil deployment.
- Plugs:Self-expanding nitinol frames with polymer membranes achieve rapid flow cessation in large-caliber vessels.
- Balloons:Temporary occlusion devices enable controlled flow interruption during liquid embolic injection or coil positioning.
- Particles:Calibrated microspheres deliver targeted embolization for tumor devascularization and uterine fibroid therapy.
Coils hold the largest share; momentum sits with liquids.
Therapy Area:
Cost tier stratification separates high-complexity neurovascular procedures from standardized oncologic interventions, with reimbursement differentials driving hospital service line prioritization.
- Tumor Embolization:Transarterial chemoembolization and radioembolization protocols deploy microspheres and drug-eluting beads to hepatocellular carcinoma and metastatic lesions. United States academic medical centers in Houston and New York City anchor demand, propelled by multidisciplinary tumor board adoption of interventional oncology.
- Vascular Malformations:Arteriovenous malformation and fistula therapy demands hybrid liquid embolic and coil approaches for curative intent. German precision manufacturing clusters supply critical nitinol wire for device fabrication, while Japanese PMDA biocompatibility standards filter non-specialized entrants from this high-risk category.
- Gastrointestinal Bleeds:Emergency embolization for upper and lower GI hemorrhage utilizes coils and particles for rapid hemostasis.
- Uterine Fibroids:Uterine artery embolization with calibrated microspheres offers fertility-preserving alternative to hysterectomy.
Tumor embolization captures the highest procedure volume; vascular malformations command the steepest device pricing premium.
End User:
Customer type determines procurement authority structure, with hospital committees negotiating enterprise contracts while ambulatory centers prioritize single-source vendor relationships for operational simplicity.
- Hospitals:Tertiary academic medical centers maintain comprehensive interventional radiology suites with captive biplane fluoroscopy and dedicated neurovascular operating rooms. United States hospital procurement committees increasingly consolidate around imaging-navigation bundles from Stryker and Siemens Healthineers, compressing standalone device margins.
- Ambulatory Surgical Centers:Same-day discharge protocols for uterine fibroid and select tumor embolization procedures expand capacity in freestanding settings. German outpatient clinic networks in Bavaria and North Rhine-Westphalia demonstrate fastest adoption, enabled by mature reimbursement for minimally invasive interventions.
- Specialty Clinics:Dedicated interventional radiology practices concentrate complex vascular malformation referrals.
- Diagnostic Laboratories:Imaging centers with catheterization capabilities perform limited diagnostic angiography with therapeutic conversion.
Hospitals dominate absolute volume; ambulatory surgical centers are climbing the fastest.
Delivery Mode:
Supply concentration in German microcatheter manufacturing shapes competitive access to precision delivery systems, with proprietary lumen geometries creating switching costs for physician operators.
- Microcatheters:Distal access platforms with variable stiffness profiles navigate tortuous cerebral and peripheral vasculature. Cook Medical anchors competitive position through custom tip configurations for neurovascular access, manufactured at its Indiana facilities with European distribution through German logistics hubs.
- Catheter-Based:Standard diagnostic and guiding catheters establish vascular access for embolic device introduction. Japanese PMDA enforces stringent trackability and kink resistance standards that extend product development timelines for new market entrants.
- Imaging-Guided:Real-time fluoroscopy, cone-beam CT, and rotational angiography enable precise device positioning.
- Balloon-Assisted:Temporary flow arrest during liquid embolic injection reduces nontarget embolization risk.
Microcatheters command the highest attach rates; imaging-guided delivery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance efficiency anchors United States market expansion, while German nitinol supply chains and Japanese PMDA biocompatibility protocols shape competitive access across their respective territories.
United States
CMS reimbursement granularity for interventional radiology procedures drives hospital capital allocation toward embolization service lines. FDA premarket notification pathways compress development timelines for class II device iterations. Houston and New York City academic medical centers anchor demand concentration for tumor embolization protocols.
Germany
Precision manufacturing clusters in Bavaria and North Rhine-Westphalia control nitinol wire-drawing capabilities for shape-memory alloy supply. EU MDR clinical evidence requirements extend recertification timelines for flow-diverting devices. Outpatient clinic networks demonstrate fastest ambulatory surgical center adoption for same-day fibroid embolization.
Japan
PMDA enforces stringent neurovascular biocompatibility testing that filters non-specialized device entrants from the market. METI industrial policy supports domestic precision manufacturing for microcatheter components. Tokyo and Osaka metropolitan hospital systems concentrate demand for arteriovenous malformation therapy.
India
Tertiary hospital expansion in Mumbai and Delhi creates underpenetrated demand for calibrated microsphere portfolios. CDSCO regulatory pathways for class C medical devices shape commercialization timelines for foreign manufacturers. Maharashtra and Karnataka state health infrastructure investments expand interventional radiology suite capacity.
United Kingdom
NHS England specialized commissioning frameworks determine reimbursement eligibility for complex neurovascular procedures. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards for CE-marked device recognition. London and Southeast England academic medical centers concentrate fellowship-trained interventional radiologist supply.
Global Transcatheter Embolization and Occlusion Devices Market Competitive Landscape
Capability concentration sits with specialized neurovascular manufacturers; scale advantage sits with diversified medical technology conglomerates. The vendor base organizes around three archetypes: integrated imaging-navigation bundlers, captive nitinol processors, and liquid embolic specialists. Consolidation pressure favors manufacturers with proprietary microcatheter geometries or radiopaque marker technologies. Dominant competitive moves include strategic partnerships for European distribution access and backward integration into shape-memory alloy supply.
Among diversified medical technology conglomerates, Boston Scientific Corporation and Stryker Corporation exemplify scale-driven competitive positioning. Abbott Laboratories occupies a position within the specialized cardiovascular device tier. Terumo Corporation represents Japanese precision manufacturing capabilities in microcatheter and embolic delivery systems. Cook Medical exemplifies the captive manufacturing archetype through in-house production of custom access devices.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Cook Medical |
| Boston Scientific Corporation |
| Merit Medical Systems |
| Stryker Corporation |
| Medtronic plc |
| Penumbra, Inc. |
| Johnson & Johnson Services, Inc. |
| Terumo Corporation |
| Others |
Supply & Pricing Matrix
Single-source nitinol wire dependency in Germany's precision manufacturing corridor determines both pricing tier spreads and supply chain shape, compressing margins for non-integrated device assemblers while rewarding captive drawing capabilities with pricing power across European distribution channels.
Pricing Analysis
United States tertiary hospitals pay premium multiples over Indian procurement for identical coil systems. Three-tier pricing structure across premium, standard, and economy levels separates platinum-tungsten radiopaque markers from stainless steel alternatives, with FDA 510(k) clearance tier commanding brand premiums. Cost compression in economy-tier particle embolization is intensifying because of Indian microsphere import competition. Ambulatory surgical centers exhibit highest price sensitivity; neurovascular service lines show lowest.
Supply Chain Analysis
Platinum-tungsten alloy feedstock draws from South African mining concentrates and German refining operations before wire-forming in Bavaria. Nitinol shape-memory alloy and radiopaque marker inputs feed from German and Japanese precision metalworking clusters. Single-source vulnerability concentrates in German wire-drawing for neurovascular coil cores. Distribution runs through hospital procurement committees consolidating around imaging-navigation bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational modeling platforms and EU MDR surveillance obligations together constitute a technological-regulatory inflection that rewards evidence-generation infrastructure over pure device innovation.
For Market Incumbents: Build captive clinical evidence moats through EU MDR Article 61 compliant post-market studies on thromboembolic complication rates. Backward integration into nitinol wire-drawing secures margin control against German supply concentration. Defend against liquid embolic substitute technologies by bundling coil-liquid hybrid delivery systems. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated calibrated microsphere segment for tumor embolization. Target Maharashtra and Karnataka tertiary hospital expansions with technical field presence for mixing protocol support. Go-to-market through CDSCO regulatory pathway efficiency for class C device commercialization. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors manufacturers with proprietary microcatheter geometries and radiopaque marker technologies. Long-term viability hinges on reimbursement strategy execution across CMS procedural coding expansions. Acquisition target archetype: liquid embolic specialists with Onyx-class polymer portfolios. Signal to watch: CMS granularity decisions for mechanical thrombectomy adjuncts.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Stryker's integrated imaging-navigation bundles compress standalone device margins across North American contracting. |
| FDA 510(k) Submission | Premarket notification efficiency accelerates coil iteration cycles for hemorrhage control applications. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend recertification timelines for flow-diverting plug portfolios. |
| Backward Integration | Boston Scientific's captive wire-drawing capabilities sustain margin control across European nitinol supply. |
| Reimbursement Strategy | CMS procedural coding granularity directly influences hospital capital allocation to interventional radiology suites. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with FDA 510(k) databases, EMA CE marking registries, PMDA approval records, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation produced convergent market sizing.
Calibration against historical CAGR realization patterns and procedure adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include device taxonomy, therapy area complexity tiers, end-user procurement authority structures, and delivery mode technology classes. CAGRs derived from logistic diffusion modeling of same-day discharge protocol adoption and interventional radiologist fellowship pipeline constraints.
Sensitivities concentrate around platinum-tungsten commodity volatility, EU MDR surveillance cost escalation, and CMS coding decisions for embolization therapies. Cross-checking against hospital procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market
Medical Devices
Global Gel Stent Market
Medical Devices
Artificial Respirator Market
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
Airway Management Devices Market
Medical Devices
Transcranial Doppler Ultrasounds System Market
Medical Devices
3D Printed Implants Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Clot Management Devices Market
Medical Devices
Surgical AR Systems Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Europe Manual Resuscitators Market
Medical Devices
Global Medical Device Connectors Market
Medical Devices
Ingestible Smart Pills Market
Medical Devices
Electrical Stimulation Devices (Esds) Market