
 Chest Drainage System Market | 2026-2036
Chest Drainage System Market Size, Share, and Industry Trends Forecast 2026-2036
Chest Drainage System Market Analysis
Hospital procurement channels for chest drainage systems is tilting toward bundled contracts that pair collection units with digital monitoring platforms. Medtronic leverages its end-to-end surgical portfolio to anchor long-term supply agreements with integrated delivery networks. Teleflex Incorporated competes through specialized trauma and critical care channels where clinician familiarity sustains repeat purchasing. Smiths Medical differentiates via compact, portable designs that extend its presence into emergency services and transport settings.
A chest drainage system comprises a closed apparatus—typically incorporating a drainage tube, one-way valve mechanism, and collection chamber—engineered to evacuate air, blood, or fluid from the pleural space while preventing backflow and maintaining negative intrathoracic pressure. The device relies on sterile polymer construction and precise vacuum calibration to restore lung expansion and prevent tension pneumothorax in postoperative or trauma patients. Collection units and tube systems command the largest revenue share due to replacement frequency and standardized hospital protocols, while remote monitoring-enabled delivery modes represent the fastest-expanding segment as connectivity reduces bedside intervention and readmission risk. Catheters designed for effusion management occupy a narrower but higher-margin niche where minimally invasive techniques displace traditional tube thoracostomy.
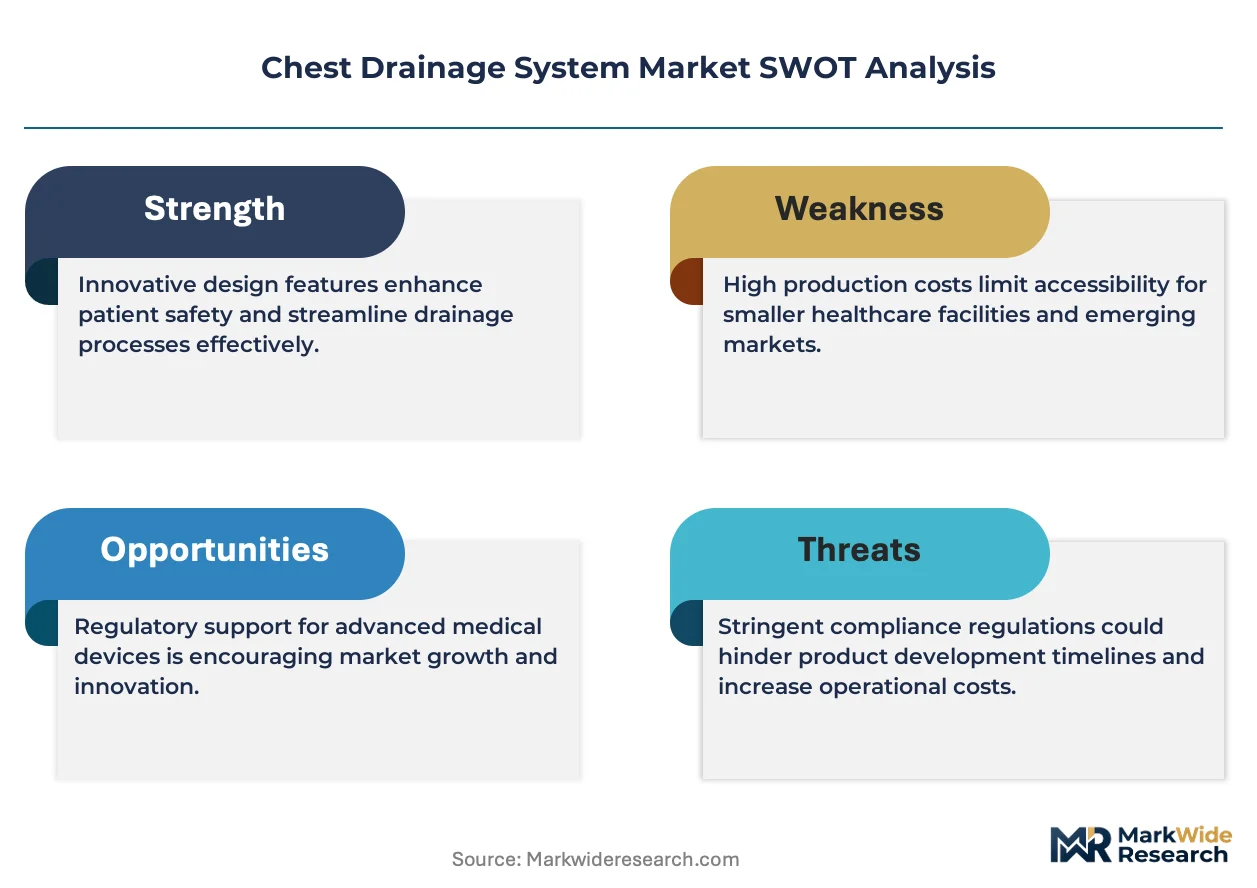
The FDA regulates chest drainage systems as Class II medical devices requiring 510(k) premarket notification, while the EU MDR mandates notified body involvement and clinical evidence for CE marking of pleural drainage products. Japan's PMDA enforces JIS-compliant sterility and biocompatibility testing that filters out smaller manufacturers lacking quality infrastructure. Stakeholders must monitor how digital health integration triggers new cybersecurity and data governance requirements across these regulatory regimes.
Market Dynamics
Hospital procurement for chest drainage systems is consolidating around integrated delivery networks that demand digital connectivity and long-term service bundling, compressing vendor margins while raising technical barriers to contract participation.
Growth Catalysts
- Rising thoracic surgery volumes:Aging populations in the United States, Germany, and Japan sustain procedural demand for pleural evacuation devices. Hospital infrastructure investments in trauma centers expand installed base requirements.
- EU MDR clinical evidence mandates:Stricter conformity assessment for Class IIa medical devices filters out marginal competitors. Surviving manufacturers capture displaced volume through certified product lines.
- Digital monitoring integration:Remote pressure sensing and automated alert systems reduce bedside nursing burden. Connected platforms justify premium positioning in critical care settings.
Market Restraints
- Polymer resin cost volatility:Medical-grade PVC and silicone feedstock prices fluctuate with petrochemical markets. Manufacturers absorb margin compression or pass through to price-sensitive hospital buyers.
- Supply concentration in Southeast Asian molding:Single-source dependencies for sterile component fabrication create disruption risk. Qualifying alternative suppliers requires 18-24 month validation cycles.
- Regulatory divergence between FDA and EU MDR:Divergent clinical evidence requirements force parallel development tracks. Smaller manufacturers lack capital to sustain dual certification pathways.
Strategic Opportunities
- Home-based pleural drainage expansion:Ambulatory care models in the United States and Japan create demand for portable, patient-operated systems. Reimbursement codes for remote monitoring support economic viability.
- Emergency medical services channel development:Pre-hospital trauma care protocols in Germany and Japan incorporate chest decompression. Compact, disposable units address field deployment constraints.
- Cybersecurity certification as competitive wedge:FDA guidance on connected device security creates first-mover advantage for pre-certified platforms. Hospital IT departments prioritize vendors with documented threat mitigation.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies face laboratory capacity constraints. Delayed test reports push product launches into subsequent fiscal periods.
- Legacy EMR integration complexity:Proprietary data formats from established monitoring systems resist interoperability. Custom interface development consumes engineering resources without direct revenue return.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chest Drainage System Market |
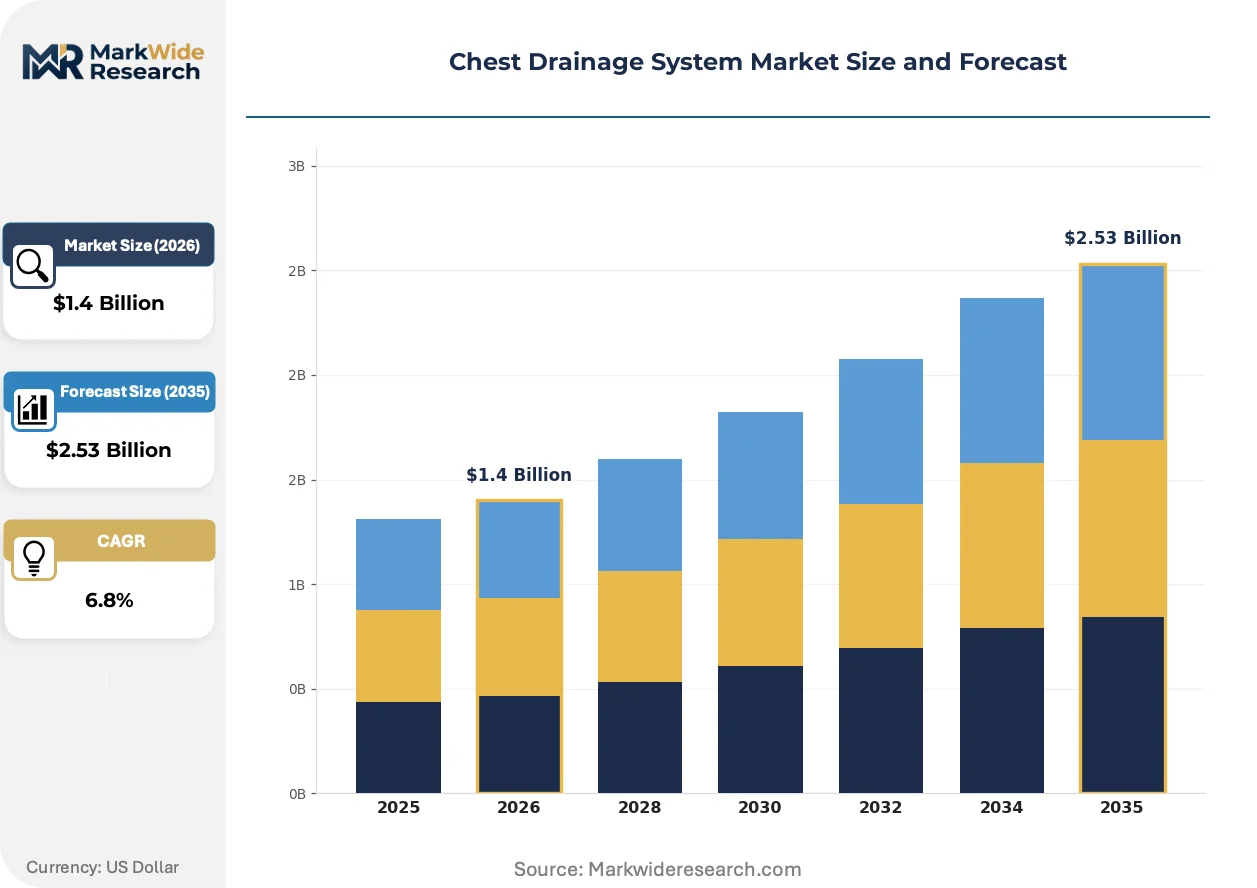
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tube Systems, One-Way Valves, Collection Units, Catheters End User: Hospitals, Clinics, Home Care, Emergency Services Delivery Mode: Manual, Automatic, Semi-Automatic, Remote Monitoring Application: Surgery, Trauma, Pneumothorax, Effusion |
| Companies Covered | Medtronic, Teleflex Incorporated, Becton Dickinson, Getinge AB, Cardinal Health, Smiths Medical, Cook Medical, Medela, ATMOS MedizinTechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chest Drainage System Market Emerging Trajectories
Active sensor integration and disposable electronics are redefining device architecture in chest drainage, shifting competitive advantage from mechanical precision to data infrastructure and software validation capabilities.
Wireless pressure transducers embedded in drainage tubing are hybridizing traditional closed-chest systems with continuous physiologic monitoring. Academic medical centers in the United States and university hospitals in Germany pilot these platforms to reduce nursing documentation burden. The technology is hybridizing hardware procurement models toward subscription-based monitoring services that bundle disposable catheters with analytics licenses.
Japan's PMDA has tightened sterility assurance requirements for polymer-based implantable devices, extending validation timelines for new material formulations. Manufacturers now submit extended biocompatibility portfolios including long-term degradation studies. High-margin effusion management catheters face the steepest compliance burden, favoring established players with captive testing laboratories.
Hospital purchasing committees now unbundle device selection from service contracts, separating capital equipment decisions from disposable replenishment agreements. Integrated delivery networks in the United States negotiate multi-year sole-source arrangements that lock in volume commitments. Germany's hospital procurement cooperatives apply similar concentration tactics, consolidating regional demand to extract price concessions.
Chest Drainage System Market Segmentation
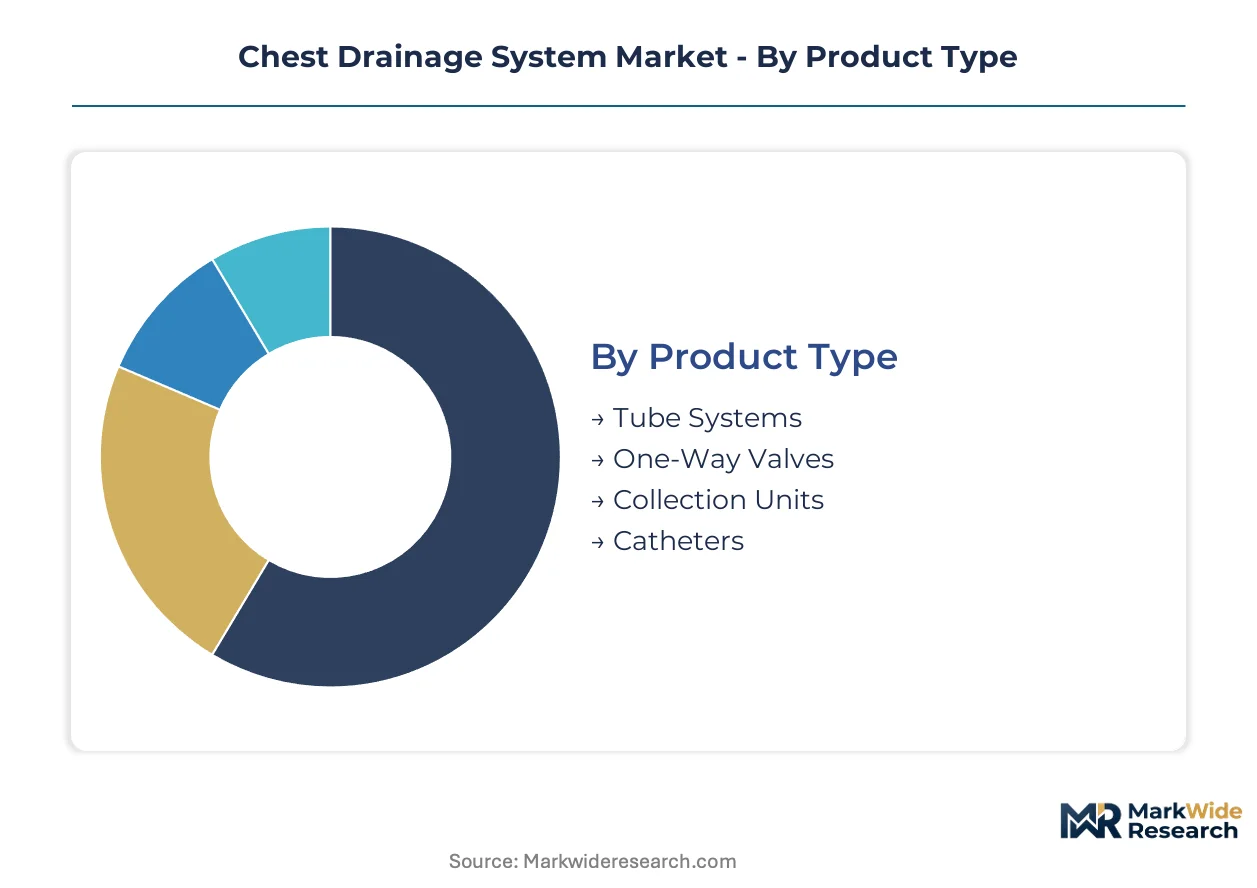
Product architecture in chest drainage spans disposable consumables with rapid replacement cycles against capital-intensive monitoring platforms with extended depreciation schedules. Understanding turnover velocity across segment categories enables vendors to align inventory models with hospital procurement rhythms and reimbursement timelines.
Product Type:
Replacement frequency varies dramatically across this category, with single-use disposables turning over in days versus durable components lasting months or years.
- Collection Units:Sterile polymer canisters engineered for 1-3 day replacement intervals dominate hospital purchasing volume. United States trauma centers and German thoracic surgery wards drive bulk procurement through standardized protocols that mandate scheduled changeouts to prevent contamination.
- Tube Systems:Silicone and PVC drainage tubing configured for specific anatomical placements require replacement every 48-72 hours under CDC infection control guidelines. Japanese university hospitals enforce particularly stringent changeout schedules that compress cycle times further.
- One-Way Valves:Mechanical flutter valves and water-seal mechanisms integrated into disposable circuits turn over with each collection unit change.
- Catheters:Percutaneous pleural catheters for effusion management deploy for extended indwelling periods measured in weeks.
Collection units anchor the volume base while remote monitoring-enabled delivery modes gain share at the steepest rate.
End User:
Procurement authority concentrates differently across settings, with integrated delivery networks wielding leverage in hospitals versus individual physician discretion in clinics.
- Hospitals:Inpatient surgical and trauma services generate the largest absolute demand through standardized protocols and high procedural throughput. United States integrated delivery networks negotiate multi-year sole-source agreements that consolidate regional volume.
- Emergency Services:Pre-hospital trauma protocols in Germany and Japan incorporate needle decompression and portable drainage. Compact disposable units address field deployment constraints where size and speed outweigh cost sensitivity.
- Clinics:Outpatient pleural procedures select lower-complexity manual systems based on physician preference.
- Home Care:Ambulatory drainage for chronic effusion patients operates under remote monitoring reimbursement codes in the United States and Japan.
Hospitals capture the dominant revenue share while emergency services represents the fastest-expanding channel.
Delivery Mode:
Technology sophistication stratifies pricing tiers, with basic mechanical systems commanding commodity margins against connected platforms sustaining premium positioning.
- Remote Monitoring:Wireless pressure transducers and automated alert systems reduce bedside nursing burden in critical care settings. United States academic medical centers pilot subscription-based models bundling disposable catheters with analytics licenses.
- Automatic:Electronic suction regulators maintain precise negative pressure without manual adjustment. German university hospitals favor these systems for postoperative thoracic surgery units where staffing ratios limit continuous bedside presence.
- Semi-Automatic:Hybrid systems combining mechanical water seals with electronic pressure display occupy mid-tier positioning.
- Manual:Traditional three-chamber water-seal systems persist in price-sensitive procurement environments.
Manual systems retain the installed base while remote monitoring climbs the fastest.
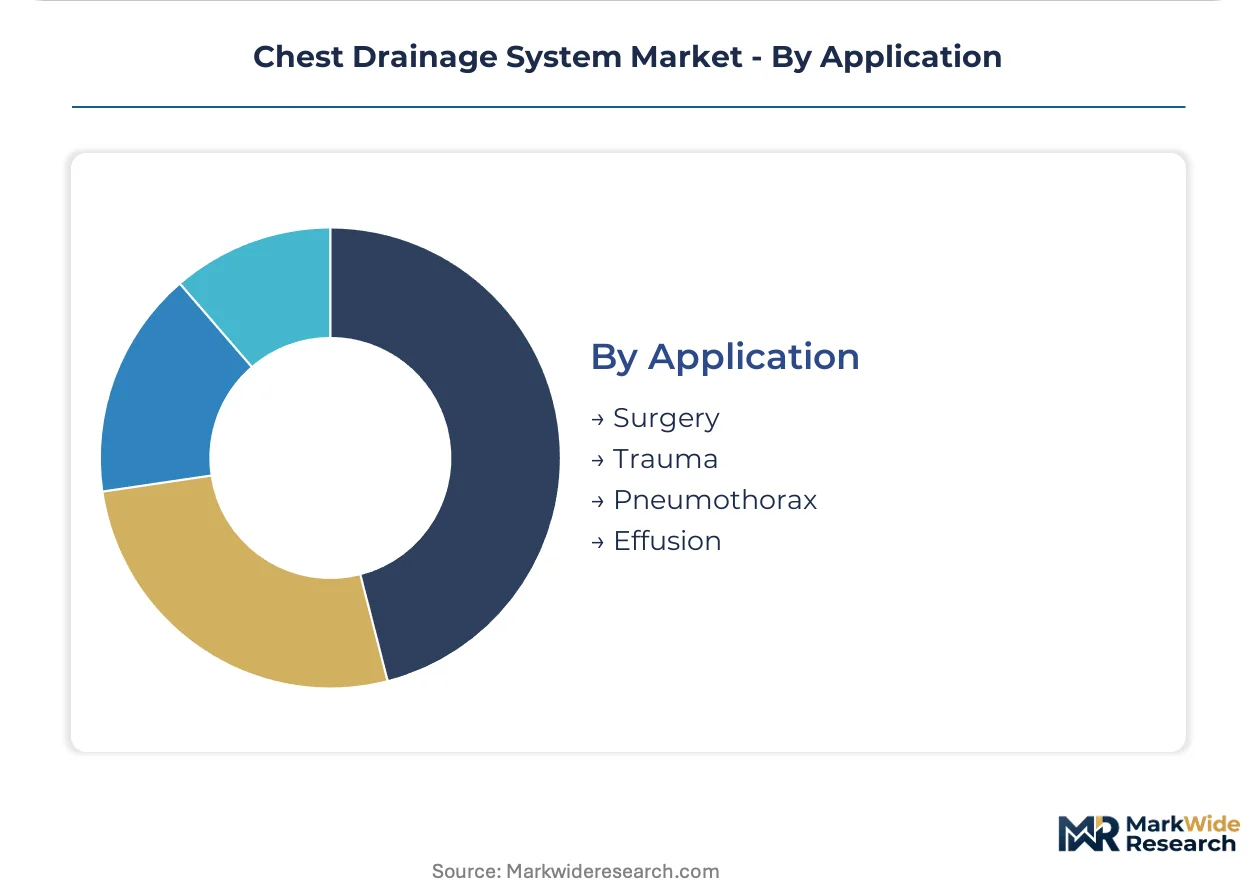
Application:
Clinical urgency and reimbursement intensity vary across indications, with trauma protocols demanding immediate availability versus elective surgery permitting scheduled procurement.
- Surgery:Elective thoracic procedures generate predictable demand through scheduled case volumes. United States hospital systems maintain par levels tied to operating room block schedules.
- Trauma:Emergency department protocols mandate immediate chest decompression capability without supply constraints. Japan's designated trauma centers stockpile compact units for field-to-hospital continuity.
- Pneumothorax:Spontaneous and iatrogenic air leak management drives replacement demand for one-way valve mechanisms.
- Effusion:Chronic fluid evacuation via indwelling catheters extends treatment duration and shifts care toward outpatient settings.
Surgery anchors the volume base while effusion management expands most quickly toward ambulatory models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Interstate Highway System and its dense network of trauma centers underwrite North American demand for rapid-deployment chest drainage systems. German rail corridors connecting the Ruhr industrial basin to university hospital clusters sustain European procurement volumes. Japan's Shinkansen network enables same-day distribution of sterile devices to designated trauma centers across the archipelago.
United States
Integrated delivery networks in Texas and California consolidate procurement for Level I trauma centers. The FDA's 510(k) premarket notification pathway shapes product development timelines for domestic manufacturers. Boston's medical device corridor anchors R&D activity for digital monitoring platforms.
Germany
Thoracic surgery volumes at university hospitals in Munich and Heidelberg drive demand for precision suction regulators. The EU MDR's clinical evidence mandates filter out marginal competitors from the CE marking process. The Baden-Württemberg medical technology cluster concentrates sterile polymer molding capacity.
Japan
Designated trauma centers in Tokyo and Osaka stockpile compact units for field-to-hospital continuity. PMDA enforces JIS-compliant sterility testing that screens out smaller manufacturers lacking quality infrastructure. The Kansai region's polymer fabrication base supplies precision-molded components.
United Kingdom
NHS procurement cooperatives in London and Manchester apply volume concentration tactics to extract price concessions. MHRA post-Brexit regulations diverge from EU MDR pathways, forcing parallel compliance tracks. The Cambridge-Oxford corridor hosts digital health integration pilots.
China
Tier-3 hospital expansion in Sichuan and Shandong provinces creates installed base requirements for basic mechanical systems. NMPA Class II medical device registration requires domestic clinical trials that extend market entry timelines. The Yangtze River Delta concentrates contract manufacturing for sterile polymer components.
Chest Drainage System Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in sterile polymer supply. The vendor base stratifies across three tiers: diversified medical technology conglomerates with end-to-end surgical portfolios, mid-cap critical care specialists with trauma channel depth, and regional fabricators serving price-sensitive procurement. Dominant competitive moves include M&A to capture digital monitoring capabilities and strategic partnerships with integrated delivery networks to lock in sole-source agreements.
Among diversified platform operators, Medtronic and Teleflex Incorporated exemplify the integrated portfolio archetype, anchoring long-term supply relationships through bundled device-service offerings. Smiths Medical occupies a position within the compact portable systems tier, representing the emergency services and transport specialization vector.
| Leading Market Players |
|---|
| Medtronic |
| Teleflex Incorporated |
| Becton Dickinson |
| Getinge AB |
| Cardinal Health |
| Smiths Medical |
| Cook Medical |
| Medela |
| ATMOS MedizinTechnik |
| Others |
Supply Flow & Price Mechanics
Southeast Asian sterile polymer molding clusters anchor component supply for chest drainage systems, concentrating margin capture upstream while hospital procurement consolidation downstream squeezes device-level profitability. Medical-grade PVC and silicone feedstock volatility transmits directly to manufacturer cost structures, forcing absorption or pass-through decisions against bundled contract pricing.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement, with integrated delivery networks extracting 15-30% price concessions against sole-source volume commitments. Pricing stratifies across premium connected platforms with remote monitoring subscriptions, standard electronic suction regulators, and economy manual water-seal systems. Cost compression in the manual tier intensifies because of commodity polymer inputs and Chinese contract manufacturer competition. Emergency services buyers show least price sensitivity due to field-deployment constraints and protocol mandates, while outpatient clinics face highest budget pressure.
Supply Chain Analysis
Medical-grade PVC and silicone feedstock draws from petrochemical complexes in China, South Korea, and Germany, with Southeast Asian molding facilities converting resin into sterile collection units and tubing. Single-source dependencies for precision valve mechanisms and transducer assemblies create 18-24 month qualification cycles for alternative suppliers. Tariff exposure on Chinese polymer components threatens margin stability as regional trade frameworks shift. Distribution runs through hospital GPO contracts and integrated delivery network procurement hubs that consolidate regional demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote monitoring subscription revenues are expanding faster than hardware sales, transforming chest drainage from capital equipment procurement into recurring service relationships with multi-year attach rates.
For Market Incumbents: Entrench digital platform dominance by acquiring wireless sensor specialists and pre-certifying cybersecurity frameworks ahead of FDA guidance finalization. Backward integration into sterile polymer compounding insulates margin from Southeast Asian supply disruption. Channel control through exclusive GPO contracts locks out mid-cap trauma specialists attempting bundled entry. For New Entrants and Emerging Players: Japan's home care reimbursement expansion offers underpenetrated white space for patient-operated portable systems with telehealth integration. Germany's emergency medical services pre-hospital protocols present a second entry vector for compact disposable units. Pursue regulatory sandbox partnerships with academic medical centers to accelerate clinical evidence generation. For Investors and Strategic Acquirers: Capital is best deployed toward connected device platforms with FDA 510(k) clearance and installed base conversion potential across the analysis window. Acquisition targets should demonstrate EMR interoperability capabilities and recurring revenue attach rates above hardware replacement cycles. Watch for EU MDR notified body backlog resolution as inflection signal for European market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence mandates filter marginal competitors from notified body queues. |
| Hospital System Partnership | Integrated delivery network sole-source agreements lock multi-year volume commitments. |
| Software Companion Development | FDA cybersecurity guidance creates first-mover advantage for pre-certified platforms. |
| Reimbursement Strategy | Remote monitoring CPT codes in United States and Japan enable subscription pricing. |
| Backward Integration | Captive polymer compounding insulates margin from Southeast Asian supply volatility. |
Methodological Framework
A spread of perspectives from thoracic surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR notified body databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up installed base modeling and top-down thoracic surgery procedure counts were triangulated to anchor forecasts.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning product architecture, delivery mode sophistication, end-user procurement authority, and application clinical urgency. CAGRs were derived from procedure volume trajectories, replacement cycle compression, and connected platform penetration curves. Specific forecast inputs included trauma center designation expansions, EU MDR transition timelines, and remote monitoring reimbursement code adoption.
Practitioners should monitor polymer resin price indices, notified body capacity constraints, and cybersecurity guidance finalization for early signals of forecast revision. Quarterly review of hospital GPO contract awards, MDR certificate issuance rates, and telehealth reimbursement policy shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South Korea Massage Equipment Market
Medical Devices
EMEA Surgical Microscopes Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
North America Single-Use Medical Device Reprocessing Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Internal Neuromodulation Devices Market
Medical Devices
Global Abutment Implants Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
Laparoscopic Surgical Robot Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Italy Minimally Invasive Surgery Devices Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Veterinary Injectable Devices Market
Medical Devices
Europe Nurse Call Systems Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Cryoballoon Ablation System Market