
 Feeding Tubes Market | 2026-2036
Feeding Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Feeding Tubes Market Intelligence
The divergence in manufacturing scale for polyurethane and silicone materials is reorganizing competitive dynamics. Large-scale manufacturers like Fresenius Kabi AG leverage extensive distribution networks to supply high-volume hospital contracts. In contrast, Boston Scientific Corporation specializes in advanced gastrostomy and jejunostomy tubes used in complex gastroenterological procedures. B. Braun Melsungen AG competes by offering a broad portfolio that includes both standard and specialized enteral feeding solutions, navigating different hospital procurement needs across Europe and North America.
A feeding tube is a medical device designed to provide enteral nutrition directly into the gastrointestinal tract. These devices are typically made from biocompatible materials such as silicone or polyurethane and vary in length and diameter based on the insertion point and patient anatomy. Their primary purpose is to support patients who are unable to consume food orally due to medical conditions. Nasogastric Tubes represent a mature, high-volume product segment for short-term feeding. Concurrently, demand for Gastrostomy Tubes is expanding within the long-term care and home healthcare end-user segments.
The regulatory environment is stringent, shaping product development and market access. In the United States, the FDA's 510(k) clearance pathway governs the approval of new feeding tube devices. Similarly, compliance with the European Union's Medical Device Regulation (MDR) is mandatory, enforcing strict requirements for clinical evidence and post-market surveillance. The critical decision for manufacturers remains whether to focus on specialized, high-margin devices for applications like pediatric feeding or compete on scale in the commoditized nasogastric tube category.
Market Dynamics
The feeding tubes market is defined by the structural tension between the high-volume, commoditized nasogastric tube segment and the high-margin, technically complex gastrostomy and jejunostomy device segment, forcing manufacturers to choose between scale-driven or specialization-driven strategies.
Growth Catalysts
- Aging Demographics:The rising prevalence of chronic and neurological conditions among the elderly population in countries like Japan and Germany directly increases the need for long-term enteral nutrition, sustaining demand for gastrostomy tubes.
- Expansion in Home Healthcare:A shift towards patient care outside of traditional hospital settings is widening the user base for feeding tubes, particularly in the home healthcare segment, which requires devices designed for non-clinical user management.
- Favorable Reimbursement Policies:Government and private payer reimbursement frameworks in North America and Europe that cover enteral nutrition therapies encourage the use of feeding tubes as a cost-effective long-term care solution.
Market Restraints
- Clinical Complication Risks:The potential for adverse events, including tube dislodgement, site infections, and aspiration pneumonia, remains a significant clinical concern that can limit adoption and increase healthcare system costs.
- Raw Material Price Volatility:Fluctuations in the price of medical-grade polyurethane and silicone, key raw materials, can compress manufacturer margins, especially in the highly competitive nasogastric tube segment.
- Stringent Regulatory Hurdles:Compliance with regulations like the European Union's MDR imposes significant costs and extends timelines for product development, clinical validation, and post-market surveillance, creating barriers to entry.
Strategic Opportunities
- Emerging Market Penetration:Increasing healthcare expenditure and infrastructure development in countries such as Brazil and India present significant opportunities for market entry and expansion, particularly for standard enteral feeding products.
- Specialized Pediatric Devices:There is a clear clinical need for a wider range of feeding tubes specifically designed for the unique anatomical and physiological requirements of neonatal and pediatric patients.
- Integration of Smart Technologies:Incorporating sensors for placement verification, clog detection, or monitoring nutritional delivery can create high-value, differentiated products and improve patient safety outcomes.
Industry Challenges
- Supply Chain Complexity:Manufacturers face the operational challenge of managing dual supply chains: one optimized for cost and volume for standard tubes and another for agility and quality for specialized devices.
- Clinical Training Requirements:The safe and effective placement of advanced devices, such as percutaneous endoscopic gastrostomy tubes, requires specialized training for clinicians, limiting their use to facilities with appropriately skilled staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feeding Tubes Market |
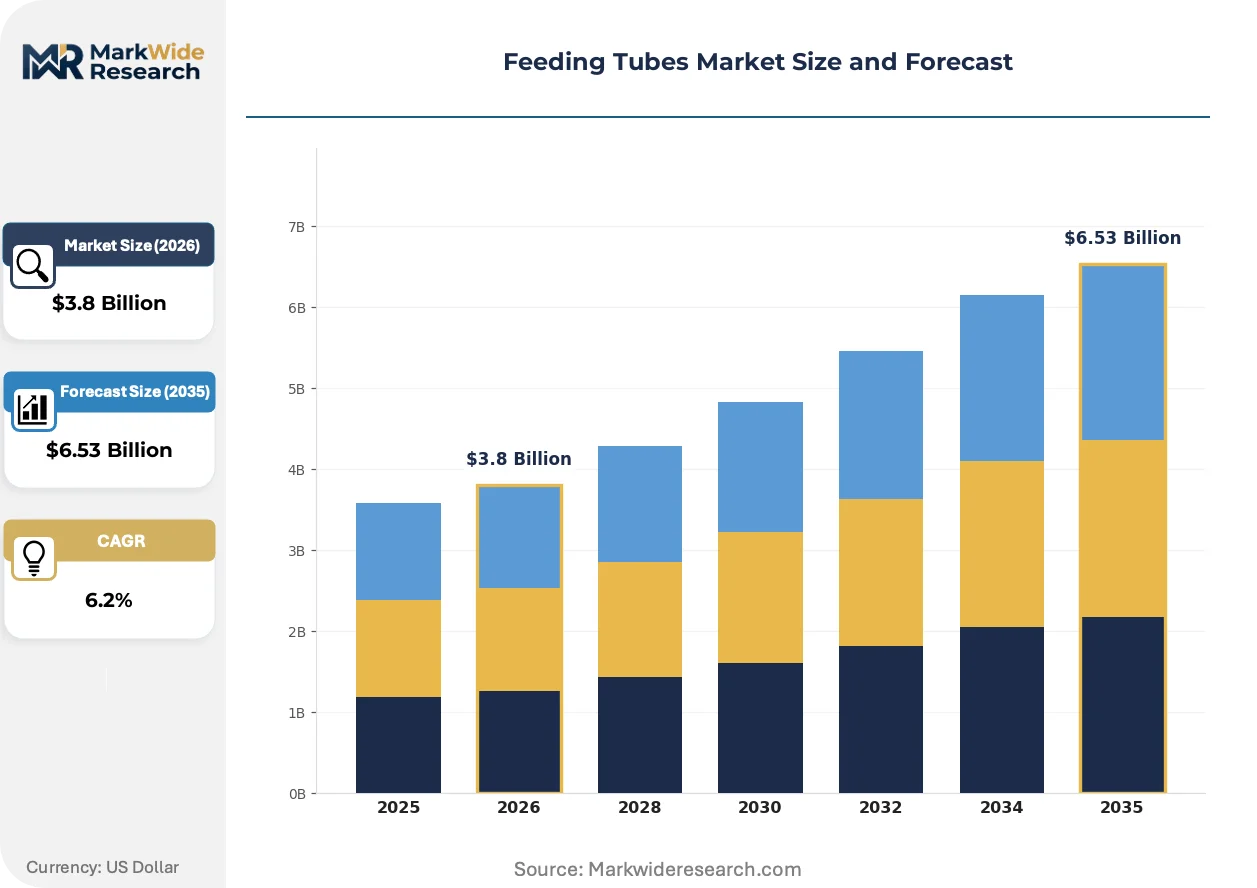
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nasogastric Tubes, Gastrostomy Tubes, Jejunostomy Tubes, Orointestinal Tubes, Duodenal Tubes Application: Neurological Disorders, Oncology Nutrition Support, Critical Care, Pediatric Feeding, Geriatric Nutrition Material: Silicone, Polyurethane, PVC, Latex, Polyethylene End User: Home Healthcare Providers, Long-term Care Facilities, Rehabilitation Centers, Specialty Clinics, Ambulatory Surgery Centers |
| Companies Covered | Fresenius Kabi AG, Cardinal Health, Boston Scientific Corporation, B. Braun Melsungen AG, Avanos Medical Inc., Abbott Laboratories, Vygon SA, Cook Medical, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feeding Tubes Market Strategic Shifts & Innovations
Product development is increasingly focused on enhancing patient safety and tailoring devices to specific clinical populations. Innovations in material science and device design are driven by stringent regulatory mandates and a clear clinical demand for reducing device-related complications.
Advanced antimicrobial and lubricious coatings are being applied to polyurethane and silicone tubes. These coatings are designed to inhibit biofilm formation and ease the insertion process, reducing patient trauma. Specialized gastroenterology and intensive care units are the primary adopters of these premium devices. This trend is bifurcating the market between standard, uncoated tubes for short-term use and premium, coated devices for long-term and high-risk patients.
The global adoption of the ISO 80369 standard for small-bore connectors is a critical regulatory-driven trend. Promoted by agencies like the FDA in the U.S. and enforced under CE marking in Europe, it mandates unique connectors like ENFit to prevent dangerous misconnections with intravenous lines. This standard impacts all enteral feeding products, forcing a system-wide transition for manufacturers and healthcare providers in major developed markets.
Hospital purchasing behavior is evolving from acquiring individual components to procuring complete, integrated enteral feeding systems. This shift favors suppliers who offer a full portfolio of compatible tubes, administration sets, and pumps, disrupting the business model for component-only specialists. This pattern is most pronounced within large health systems and Group Purchasing Organizations in the United States and Germany, which prioritize supply chain simplification and system interoperability.
Feeding Tubes Market Segmentation
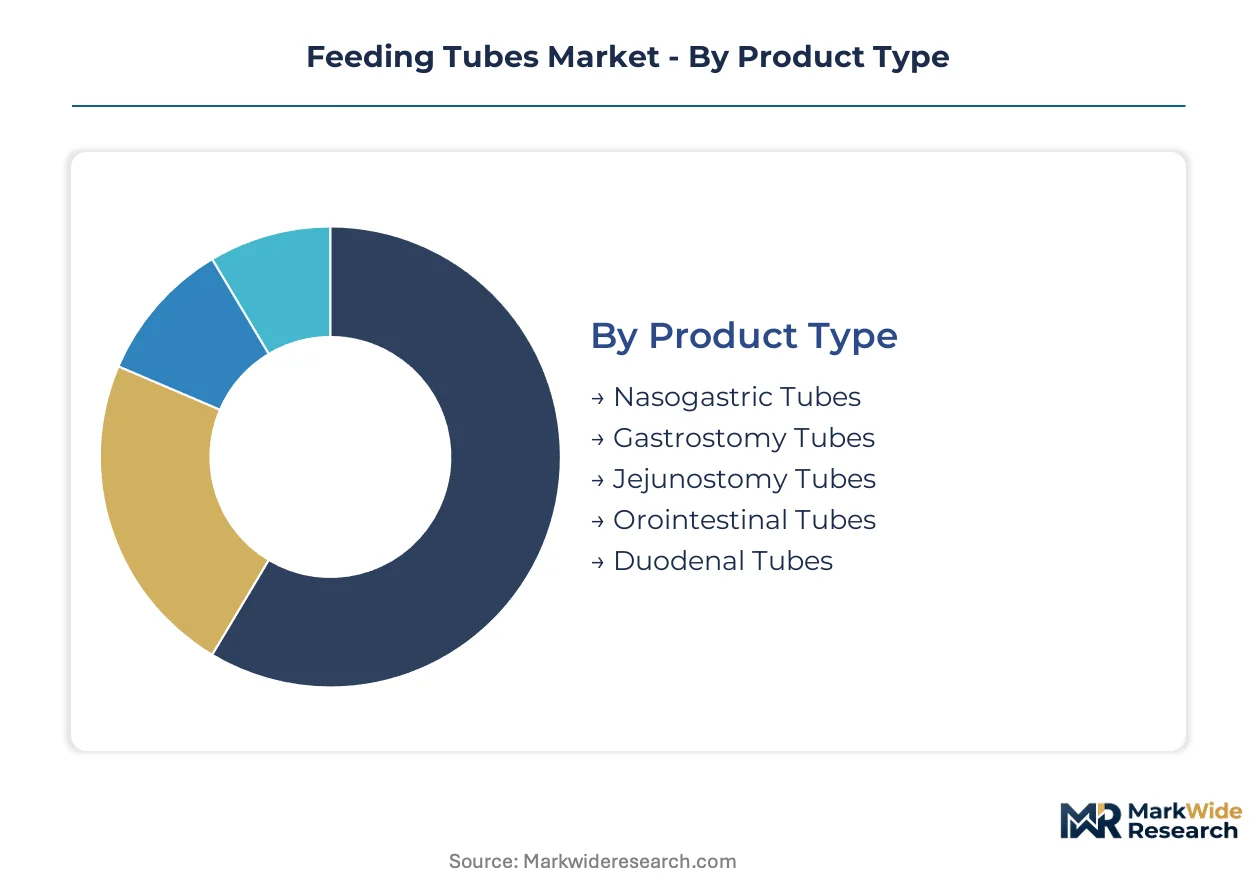
The feeding tubes market's segmentation highlights diverse product requirements and patient needs across clinical settings. Understanding these distinct categories allows manufacturers to tailor device design and distribution strategies. This granular view clarifies where specific product innovations yield the highest returns.
Product Type:
The product type segmentation dictates the primary distribution channels, ranging from high-volume hospital procurement for standard devices to specialized clinical sales for advanced solutions. Different tube designs cater to varying patient conditions and feeding durations.
- Nasogastric Tubes:These flexible tubes are inserted through the nose into the stomach. Demand concentrates in acute care settings and hospitals for short-term nutritional support across countries like Germany and Japan.
- Gastrostomy Tubes:Surgically placed directly into the stomach, these silicone devices are designed for long-term enteral nutrition. Expansion concentrates in home healthcare and long-term care, driven by an aging global population.
- Jejunostomy Tubes:Placed into the jejunum, these tubes bypass the stomach for patients with gastric motility issues.
- Orointestinal Tubes:Inserted through the mouth, these tubes are used for short-term feeding, especially in pediatric and critical care.
- Duodenal Tubes:Designed for feeding directly into the duodenum, these tubes are utilized when gastric feeding is contraindicated.
Nasogastric Tubes dominate the installed base for short-term feeding. Gastrostomy Tubes drive expansion for long-term nutritional support.
Application:
The application segments reflect specific patient cohorts and their unique clinical requirements for enteral nutrition. Each category demands distinct product features, from tube diameter to specialized insertion techniques.
- Geriatric Nutrition:This segment addresses nutritional needs of older adults, often involving long-term care for chronic conditions. Demand is sustained by rising neurological conditions among the elderly population in developed economies.
- Critical Care:Patients in intensive care units require precise, often temporary, enteral feeding, necessitating tubes with anti-clogging and easy placement. This application emphasizes patient safety in high-acuity hospital environments.
- Neurological Disorders:Patients with conditions affecting swallowing or consciousness rely on feeding tubes for essential nutrient delivery.
- Oncology Nutrition Support:Cancer patients undergoing treatment often require nutritional support via feeding tubes to maintain strength.
- Pediatric Feeding:This segment focuses on devices tailored for the unique anatomical and physiological requirements of infants and children.
Critical Care applications remain substantial within hospital settings. Pediatric Feeding demonstrates significant growth potential, driven by specialized device requirements.
Material:
Material choices directly influence product biocompatibility, flexibility, and manufacturing scale, impacting cost structures and regulatory compliance. Divergence in production capabilities reshapes competitive dynamics.
- Silicone:Known for its flexibility, biocompatibility, and long-term stability, silicone is preferred for gastrostomy tubes and other long-term indwelling devices. Large-scale manufacturers leverage advanced molding techniques.
- Polyurethane:This material offers a balance of stiffness and flexibility, suitable for both short-term nasogastric tubes and longer-term applications. Its manufacturing scale is a key differentiator for high-volume hospital contracts.
- PVC:Polyvinyl chloride tubes are generally more rigid and less expensive, primarily for short-term feeding in cost-sensitive markets.
- Latex:Less common due to allergy risks and regulatory restrictions like Europe's MDR.
- Polyethylene:Offering good chemical resistance, polyethylene tubes are employed where material durability is critical.
Polyurethane and silicone constitute the dominant materials for feeding tube construction. Innovation focuses on enhanced safety features and patient comfort.
End User:
The end-user segmentation reflects varied procurement patterns and clinical support requirements, influencing device design for user-friendliness. Each end-user type presents distinct challenges for distribution and post-market support.
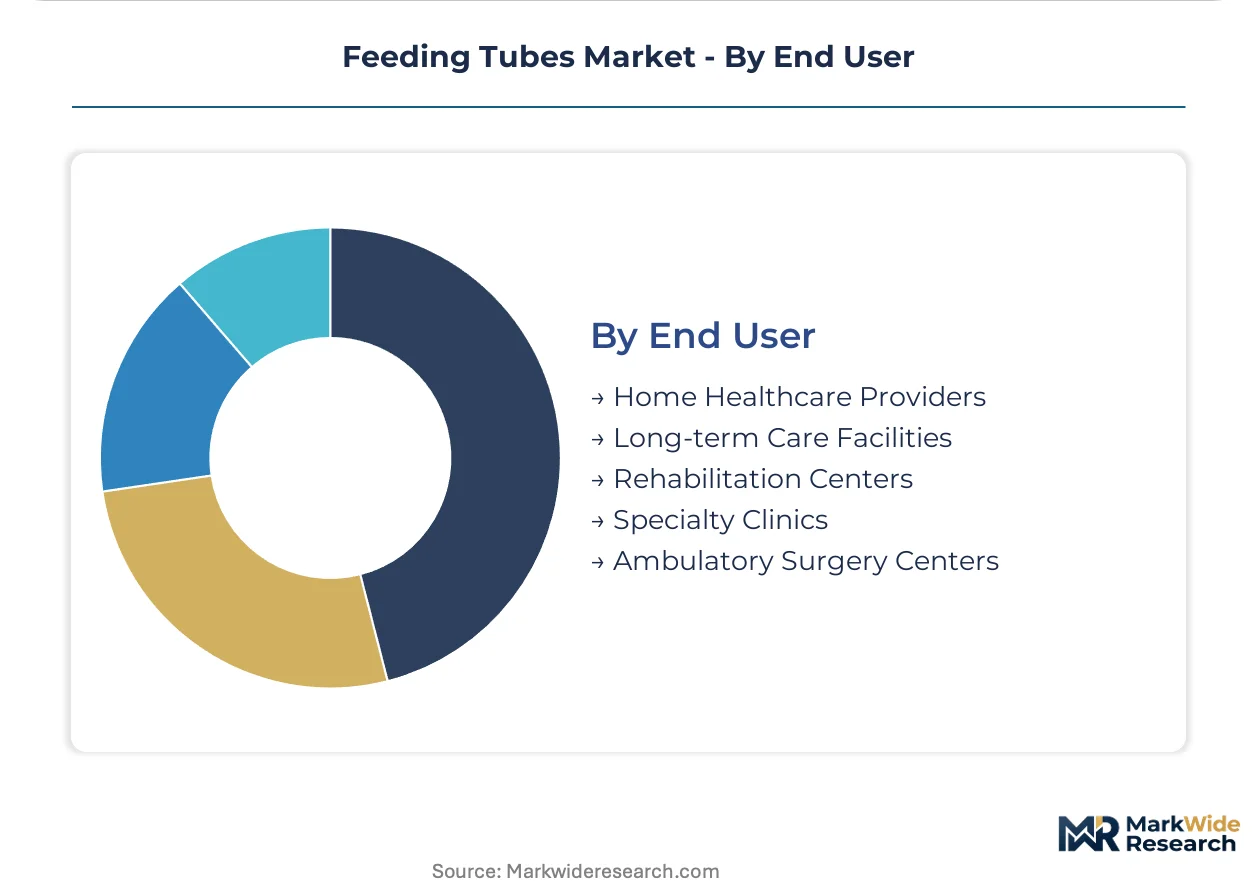
- Home Healthcare Providers:This segment serves patients receiving enteral nutrition in non-clinical settings, requiring devices optimized for ease of use by caregivers. Expansion in home healthcare is driven by a shift from traditional hospital environments.
- Long-term Care Facilities:These facilities cater to patients with chronic conditions needing continuous nutritional support over extended periods, prioritizing durability and cost-effectiveness. Gastrostomy tubes are frequently used here.
- Rehabilitation Centers:Patients recovering from severe illness or injury often require temporary feeding tube support in these centers.
- Specialty Clinics:Clinics like gastroenterology centers utilize feeding tubes for specific diagnostic or therapeutic interventions.
- Ambulatory Surgery Centers:Feeding tubes might be used here for short-term post-operative nutritional support or temporary enteral access.
Home Healthcare Providers represent a rapidly expanding segment for enteral nutrition devices. Long-term Care Facilities maintain consistent demand for durable solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional dynamics in the feeding tubes market present a pricing-power asymmetry between developed and emerging economies. Advanced healthcare infrastructures in countries like Germany support premium device pricing, while cost-effectiveness drives demand in markets such as India. This divergence influences material selection and distribution strategies across continents.
Japan
Japan's elderly population sustains demand for long-term enteral nutrition, particularly gastrostomy tubes. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures strict regulatory oversight for all medical devices. Tokyo's extensive hospital networks drive adoption of advanced feeding tube technologies.
Germany
Germany's robust healthcare system supports consistent demand for both standard and specialized feeding tubes. Compliance with the European Union's Medical Device Regulation (MDR) is paramount for market access. The medical technology cluster in Bavaria fosters innovation in device design and manufacturing.
United States
The United States market benefits from favorable reimbursement policies and expanding home healthcare services. The FDA's 510(k) clearance pathway governs the approval of new feeding tube devices. Boston's prominent biotech and medical device ecosystem drives research into smart feeding tube technologies.
Brazil
Brazil represents a significant opportunity for market entry due to increasing healthcare expenditure and infrastructure development. The Agência Nacional de Vigilância Sanitária (ANVISA) regulates medical devices, influencing product availability. São Paulo's growing medical device manufacturing sector supports local demand for standard enteral products.
India
India's expanding healthcare infrastructure and large patient population drive demand for cost-effective enteral feeding solutions. The Central Drugs Standard Control Organization (CDSCO) oversees medical device regulation and quality standards. Bengaluru's emerging medical technology sector focuses on accessible and innovative feeding tube designs.
Feeding Tubes Market Key Industry Players
Concentration sits with large, diversified medical device conglomerates that leverage extensive distribution networks. The market structure exhibits a tiered approach, encompassing high-volume generalists, specialized innovators, and broad-portfolio providers. Companies actively pursue strategies including portfolio diversification, capacity expansion, and geographic expansion to maintain competitive positioning. Strategic partnerships also facilitate technology transfer and market access in emerging regions, significantly shaping the competitive landscape.
On the scale-driven end, Fresenius Kabi AG, a German-based company, exemplifies the leveraging of extensive distribution networks for high-volume hospital contracts, particularly in the standard nasogastric tube segment. Boston Scientific Corporation, a US-based entity, occupies a position specializing in advanced gastrostomy and jejunostomy tubes, catering to complex gastroenterological procedures. B. Braun Melsungen AG, a German-based AG, represents a player with a broad portfolio, adept at navigating diverse hospital procurement needs across both established and developing markets.
| Leading Market Players |
|---|
| Fresenius Kabi AG |
| Cardinal Health |
| Boston Scientific Corporation |
| B. Braun Melsungen AG |
| Avanos Medical Inc. |
| Abbott Laboratories |
| Vygon SA |
| Cook Medical |
| Becton, Dickinson and Company |
| Others |
Cost & Logistics Intelligence
ISO 80369 compliance gates both supply qualification and price differentiation in the feeding tubes market. This standard mandates unique connectors, influencing product design and manufacturing processes for market access and premium pricing in developed economies.
Pricing Analysis
Configured-to-order solutions for complex gastroenterological procedures command a premium over standard, high-volume nasogastric tubes. Pricing stratifies across premium, standard, and economy tiers, reflecting material science innovations like antimicrobial coatings and compliance with ISO 80369 standards. Raw material price volatility, particularly for medical-grade polyurethane and silicone, compresses manufacturer margins in the commoditized segments. Home healthcare providers demonstrate higher price sensitivity for durable solutions compared to specialized hospital units adopting advanced devices.
Supply Chain Analysis
Inventory management for feeding tubes balances high-volume standard products with agility for specialized devices. Supply draws from manufacturing hubs in Germany, the United States, and emerging centers like Brazil, relying on consistent medical-grade polyurethane and silicone. Supply chain complexity, driven by dual manufacturing requirements, poses a structural risk for manufacturers. Distribution runs through extensive hospital networks and specialized clinical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The feeding tubes market requires a substitution defense against alternative nutritional support methods. Incumbents must navigate the threat of parenteral nutrition, which offers an intravenous alternative for patients unable to tolerate enteral feeding.
For Market Incumbents: Secure leadership by integrating smart technologies into advanced gastrostomy tubes, differentiating from commoditized segments. Invest in R&D for antimicrobial coatings and sensor integration to mitigate clinical complication risks and enhance patient safety. Leverage existing distribution networks to offer comprehensive enteral feeding systems, capitalizing on evolving hospital purchasing behavior. Compliance with regulations like the EU MDR requires continuous investment in clinical evidence and post-market surveillance.
For New Entrants and Emerging Players: Lead with specialized pediatric devices, addressing the clear clinical need for tailored solutions in this underserved segment. Target emerging markets like Brazil and India with cost-effective, standard enteral feeding products optimized for increasing healthcare expenditure. Differentiate through innovative material science for enhanced patient safety, focusing on specific applications like neurological disorders. Strategic partnerships can facilitate market access and technology transfer in these regions.
For Investors and Strategic Acquirers: ISO 80369 adoption reshapes the acquisition landscape, favoring companies with compliant, integrated enteral feeding systems. Long-term viability rests on an aging global population and expanding home healthcare services over the next decade. Target specialized innovators developing smart feeding tube technologies or firms with robust market access in emerging economies. Monitor the integration of sensor technology and the expansion of specialized pediatric device portfolios as key inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Smart Feeding Tubes | Differentiated products with sensors enhance patient safety and provide real-time nutritional delivery data. |
| Regulatory Approval Pathway: EU MDR Compliance | Ensures market access across Europe, critical for maintaining competitive positioning and trust. |
| Hospital System Partnership: Integrated System Sales | Secures high-volume contracts by offering complete enteral feeding solutions to large healthcare networks. |
| Geographic Expansion: Emerging Markets | Captures new demand in countries like India and Brazil with developing healthcare infrastructures. |
| Material Science Innovation: Antimicrobial Coatings | Reduces infection risks and improves patient comfort, driving adoption in high-acuity clinical settings. |
Research Approach
Desk research of clinical studies, regulatory filings, and industry reports preceded structured interviews with clinicians, hospital purchasing managers, and medical device engineers. This approach combined primary insights with secondary validation, ensuring a comprehensive market view. Bottom-up and top-down triangulation across diverse data points confirmed market sizing and growth trajectories.
Variance decomposition isolated key growth drivers and restraints influencing market projections across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, material, and end-user. Compound annual growth rates were derived from historical trends and statistical regression analysis. Key industry-specific forecast inputs included global aging population demographics and the rising prevalence of chronic conditions.
Forecasts assume regulatory continuity in EU MDR and FDA 510(k) pathways; material policy shifts would require re-modeling. Unforeseen changes in reimbursement policies or raw material supply disruptions represent key risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Patient Warming Devices Market
Medical Devices
Injectable Drug Delivery Market
Medical Devices
Treatment Pumps Market
Medical Devices
Global Dermatome Device Market
Medical Devices
Testicular Implants (Prosthesis) Market
Medical Devices
US Clear Aligners Market
Medical Devices
Heating Pads Market
Medical Devices
United Kingdom Aesthetic Devices Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Global Medical Drones Market
Medical Devices
Spain Ultrasound Devices Market
Medical Devices
Temperature Sensing Foley Catheter Market
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Global Nebulizers Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market