
 Electroceutical Devices Market | 2026-2036
Electroceutical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Electroceutical Devices Market Analysis
The shortage of trained neurostimulation programmers and bioelectronic engineers is collapsing the pace of post-implant patient optimization across major markets. Medtronic plc leverages its global service network to sustain high-touch clinical support for deep brain stimulation systems. Boston Scientific Corporation competes through differentiated vagus nerve stimulation platforms that anchor its presence in epilepsy and depression protocols. Abbott Laboratories specializes in closed-loop cardiac neuromodulation, occupying a narrow but defensible technology tier.
Electroceutical devices deliver targeted electrical impulses to modulate neural, cardiac, or muscular activity, typically operating at frequencies between 1–150 Hz with pulse widths of 60–450 microseconds depending on therapeutic target. These systems replace or augment pharmaceutical intervention for conditions refractory to conventional therapy. Neurostimulators dominate current revenue pools given established reimbursement for chronic pain and movement disorder applications, while closed-loop systems represent the fastest-expanding technology segment as algorithmic feedback enables real-time parameter adjustment. Implantable devices command premium pricing relative to transcutaneous alternatives, reflecting surgical placement requirements and longer effective lifespans.
FDA premarket approval pathways and EU MDR technical documentation requirements shape development timelines and commercial access for electroceutical manufacturers, with Japan's PMDA adding a third major regulatory gate for Asia-Pacific entry. The FDA's breakthrough devices program accelerates review for bioelectronic medicines targeting neurological conditions, compressing time-to-revenue for qualifying submissions. Stakeholders must monitor evolving payer evidence requirements for closed-loop and bioelectronic modalities, as health technology assessment bodies in Germany and Japan tighten cost-effectiveness thresholds for novel implantable therapies.
Market Dynamics
The migration from open-loop to closed-loop neuromodulation architectures is compressing development cycles and forcing hardware-software co-design investments across the electroceutical supply base.
Growth Catalysts
- FDA Breakthrough Device Program:Accelerated review timelines for bioelectronic therapies targeting treatment-resistant depression and epilepsy are compressing time-to-market for qualifying submissions.
- Closed-loop algorithmic control:Real-time parameter adjustment based on biomarker feedback is expanding addressable patient populations beyond static stimulation protocols.
- Germany's DiGA fast-track:Digital health application reimbursement pathways are creating precedent for software-enabled electroceutical companion apps.
Market Restraints
- Platinum-iridium electrode supply:Concentrated sourcing from South African refiners exposes manufacturers to price volatility and geopolitical disruption.
- EU MDR technical documentation:Expanded clinical evidence requirements for active implantable devices are extending certification timelines by 18-24 months.
- Transcutaneous stimulation alternatives:Non-invasive vagus nerve and trigeminal nerve stimulators are capturing price-sensitive chronic pain segments.
Strategic Opportunities
- Japan's aging demographic:Parkinson's disease prevalence expansion is creating unmet demand for deep brain stimulation systems in Tokyo and Osaka medical corridors.
- Gastrointestinal neuromodulation:Gastric electrical stimulation for gastroparesis represents an underdeveloped therapeutic category with limited incumbent competition.
- AI-enabled predictive maintenance:Remote battery depletion forecasting and lead impedance monitoring are creating subscription revenue streams alongside hardware sales.
Industry Challenges
- Bioelectronic engineering talent scarcity:The intersection of neural signal processing, implantable materials science, and clinical workflow design exceeds conventional biomedical training pipelines.
- Legacy EMR integration:Closed-loop systems require bidirectional data exchange with hospital information systems that lack standardized neurostimulation data schemas.
- Post-implant programming capacity:Trained clinical specialists for device optimization are concentrated in academic medical centers, constraining community hospital adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electroceutical Devices Market |
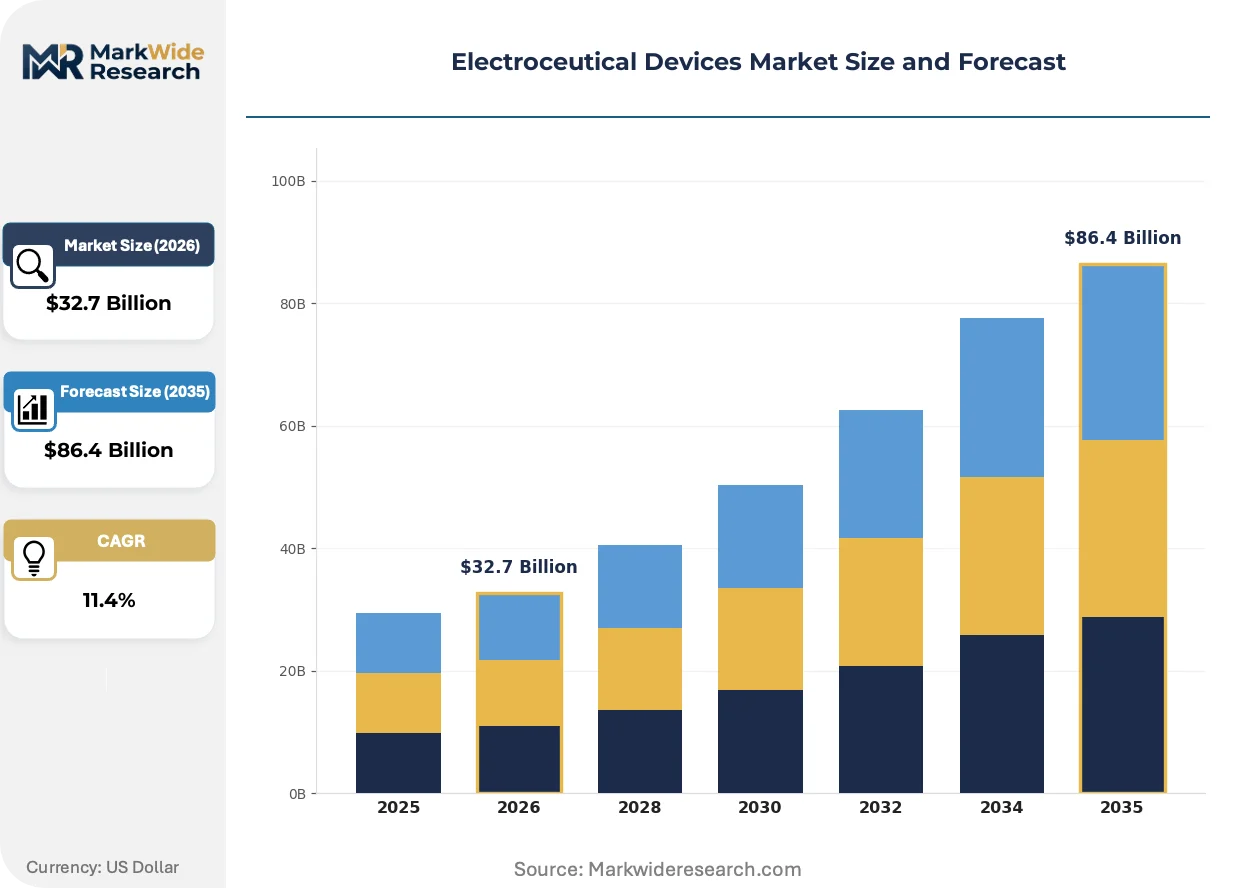
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $86.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurostimulators, Cardiac Devices, Bioelectronic Medicines, Implantable Devices Technology: Transcutaneous Electrical Nerve Stimulation, Vagus Nerve Stimulation, Deep Brain Stimulation, Closed-loop Systems End User: Hospitals, Homecare Settings, Rehabilitation Centers, Specialty Clinics Application: Chronic Pain Management, Movement Disorders, Heart Rhythm Disorders, Neurological Conditions |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Abbott Laboratories, LivaNova PLC, Cochlear Ltd., Biotronik SE & Co. KG, Nevro Corp., Sonova Holding AG, MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electroceutical Devices Market Emerging Trajectories
Algorithmic feedback control and materials science advances are converging to enable autonomous therapeutic adjustment, while regulatory frameworks race to accommodate software-defined medical devices.
Leadless cardiac neuromodulation systems are eliminating transvenous leads and their associated fracture risks. Electrophysiology departments in United States health systems are piloting these devices for heart failure patients with reduced ejection fraction. The technology is miniaturizing pulse generators to subcutaneous injectable form factors that compress procedural time and expand eligible operator pools.
Japan's PMDA has introduced conditional early approval pathways for novel implantable neuromodulators with post-market surveillance requirements. Manufacturers must submit real-world performance data within defined follow-up windows to maintain marketing authorization. Cardiac resynchronization therapy devices with adaptive algorithms face the steepest evidentiary burden under these revised standards.
Hospital procurement committees are unbundling device implantation from long-term programming and maintenance services. Academic medical centers in Germany and the United States are negotiating direct-to-manufacturer service contracts that bypass traditional distributor markups. This reconfiguration is most visible in deep brain stimulation programs where programming complexity justifies dedicated clinical engineering support.
Electroceutical Devices Market Segmentation
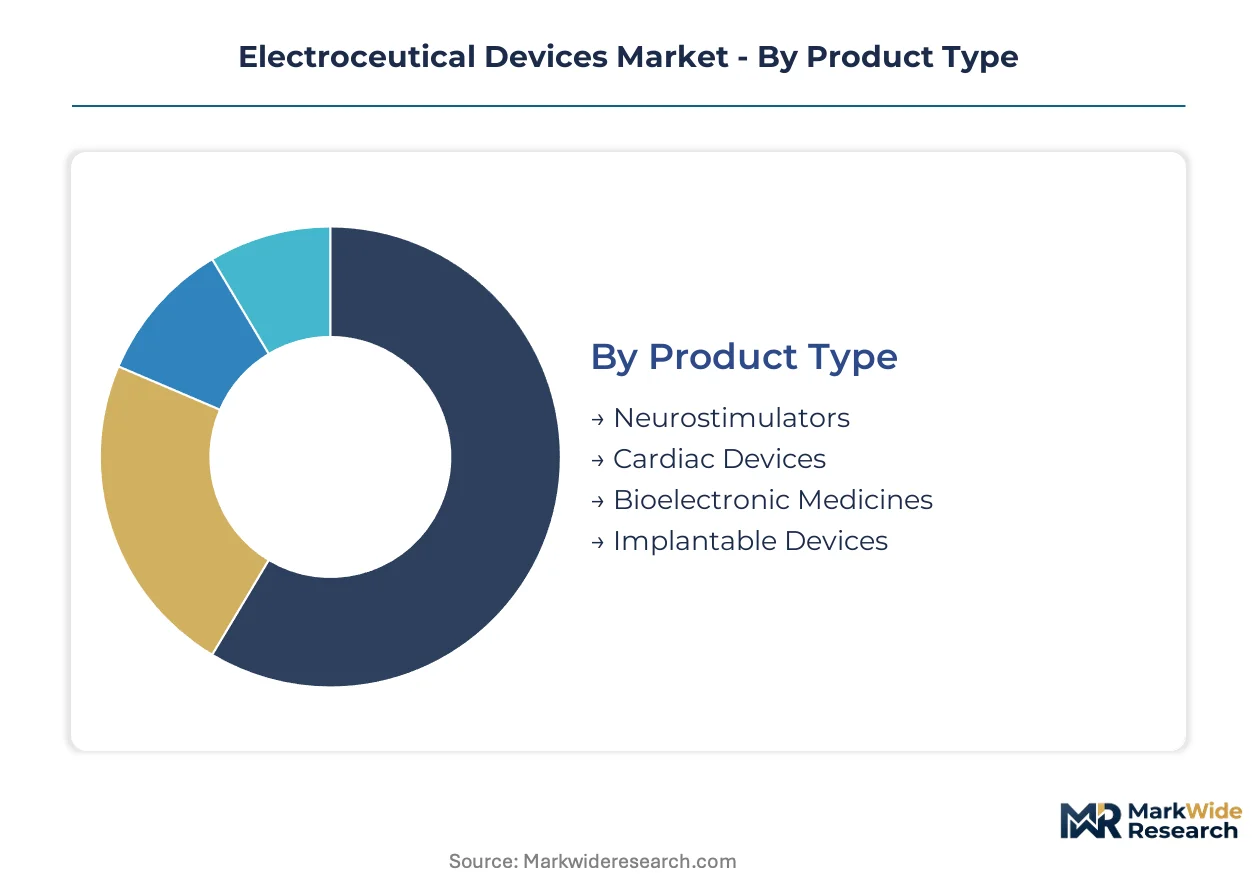
Electroceutical device manufacturers configure product portfolios around distinct reimbursement pathways, surgical complexity tiers, and patient acuity levels. Segment boundaries increasingly blur as closed-loop architectures integrate across traditional product categories and care settings.
Product Type:
Domestic manufacturing concentration varies sharply across product categories, with cardiac systems showing the tightest geographic clustering and bioelectronic medicines exhibiting the most distributed R&D footprint.
- Neurostimulators:These systems deliver targeted electrical impulses to spinal cord or peripheral nerve targets at frequencies between 2–120 Hz. Demand clusters in academic medical centers across Germany and the United States where reimbursement for chronic pain and movement disorder protocols is established. Supply chains for pulse generators and lead assemblies concentrate in Minnesota and Massachusetts manufacturing corridors.
- Cardiac Devices:Implantable cardioverter-defibrillators and cardiac resynchronization therapy systems modulate heart rhythm through transvenous or leadless delivery. Japanese hospitals in Tokyo and Osaka medical corridors drive volume for advanced heart failure applications. FDA breakthrough designations for adaptive algorithms are compressing development timelines for next-generation systems.
- Bioelectronic Medicines:Emerging therapeutic platforms target cytokine modulation and metabolic regulation through electrical signaling. Research partnerships span academic institutions in Switzerland, the United Kingdom, and California with limited commercial deployment.
- Implantable Devices:Subcutaneous pulse generators with multi-year battery lifespans command premium pricing relative to external alternatives. Surgical placement requirements limit adoption to tertiary care facilities with electrophysiology or functional neurosurgery capabilities.
Neurostimulators command the established base. The steepest expansion runs through bioelectronic medicines.
Technology:
Technology selection tracks directly to invasiveness tolerance, with transcutaneous options serving price-sensitive entry segments and implantable systems capturing refractory patient populations.
- Transcutaneous Electrical Nerve Stimulation:Non-invasive surface electrodes deliver pulsed current for chronic pain management without surgical intervention. Homecare adoption in the United States and Germany accelerates as over-the-counter devices gain pharmacy distribution.
- Vagus Nerve Stimulation:Implantable lead systems target cervical vagus nerve fibers for epilepsy and treatment-resistant depression. FDA accelerated review pathways for novel indications are expanding addressable populations beyond established neurology protocols.
- Deep Brain Stimulation:Bilateral electrode arrays modulate basal ganglia circuits for Parkinson's disease and essential tremor. Programming complexity concentrates demand in academic medical centers with dedicated functional neurosurgery programs.
- Closed-loop Systems:Real-time biomarker feedback enables autonomous parameter adjustment without clinician intervention. Algorithmic control architectures are gaining share fastest in cardiac resynchronization and responsive neurostimulation applications.
Transcutaneous electrical nerve stimulation anchors volume through accessibility. Closed-loop systems are climbing the fastest on algorithmic differentiation.
End User:
Facility type determines reimbursement tier, technical support requirements, and patient throughput economics for electroceutical deployment.
- Hospitals:Tertiary care systems handle complex implantation procedures and post-operative programming for deep brain and cardiac neuromodulation systems. Germany's university hospitals and Japan's national center hospitals concentrate specialized expertise.
- Homecare Settings:Transcutaneous devices and external trial systems enable patient-managed therapy outside clinical facilities. Remote monitoring capabilities are expanding eligible populations for home-based chronic pain management.
- Rehabilitation Centers:Post-acute facilities coordinate device programming with physical therapy protocols for movement disorder patients. Integration with functional recovery metrics distinguishes leading programs.
- Specialty Clinics:Dedicated pain management and neurology practices handle device optimization and battery replacement procedures. Concentration in urban corridors of the United States and Germany limits rural access.
Hospitals retain the procedural complexity premium. Homecare settings are expanding most quickly on remote monitoring enablement.
Application:
Application segmentation reflects the underlying disease epidemiology and the maturity of clinical evidence supporting electrical modulation efficacy.
- Chronic Pain Management:Failed back surgery syndrome and complex regional pain syndrome drive spinal cord stimulation volume. Reimbursement frameworks in the United States and Germany cover both trial and permanent implantation phases.
- Movement Disorders:Parkinson's disease and essential tremor represent the most established deep brain stimulation indications. Japan's aging demographic is expanding eligible patient pools in Tokyo and Osaka metropolitan regions.
- Heart Rhythm Disorders:Bradycardia, tachycardia, and heart failure with reduced ejection fraction command the largest installed base of active implantable devices. Leadless cardiac neuromodulation is displacing transvenous systems in selected patient populations.
- Neurological Conditions:Epilepsy, depression, and emerging inflammatory targets span vagus nerve and deep brain stimulation platforms. FDA breakthrough designations for treatment-resistant psychiatric indications are accelerating clinical trial enrollment.
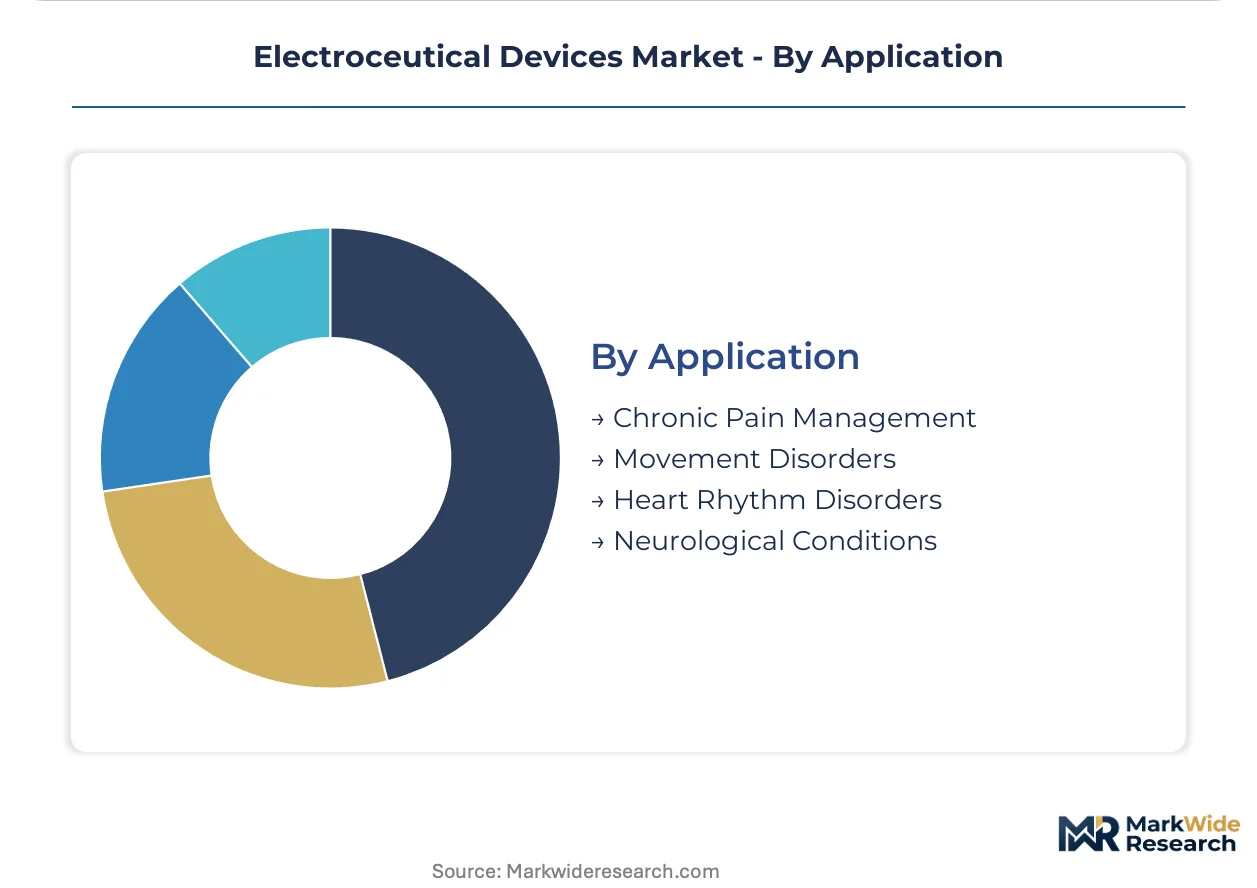
Chronic pain management holds the deepest reimbursement history. Neurological conditions are gaining share fastest on psychiatric indication expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. German hospitals prioritize closed-loop cardiac systems with algorithmic feedback, while Japanese providers concentrate deep brain stimulation capacity in aging metropolitan corridors. United States demand spreads across pain management and psychiatric indications with fragmented payer structures.
United States
FDA breakthrough device designations for treatment-resistant depression and epilepsy indications compress regulatory timelines for qualifying electroceutical submissions. The 21st Century Cures Act provisions accelerate real-world evidence collection for adaptive algorithm systems. Minneapolis and Boston manufacturing corridors concentrate pulse generator and lead assembly production for domestic supply.
Germany
University hospitals in Munich and Heidelberg anchor European demand for movement disorder neuromodulation with established functional neurosurgery programs. EU MDR technical documentation requirements extend certification timelines for active implantable devices by 18-24 months. The DiGA fast-track pathway creates precedent for software-enabled electroceutical companion applications.
Japan
PMDA conditional early approval pathways for novel implantable neuromodulators require defined post-market surveillance windows. Tokyo and Osaka medical corridors concentrate specialized expertise for Parkinson's disease prevalence expansion. METI industrial policy supports domestic manufacturing capacity for cardiac rhythm management devices.
Switzerland
Swissmedic maintains stringent technical documentation standards for active implantable medical devices with algorithmic components. Basel and Zurich research corridors host bioelectronic medicine partnerships spanning academic institutions and device manufacturers. The country's precision manufacturing base supplies specialized components for European neuromodulation assembly.
Electroceutical Devices Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in electroceutical device supply. Tier-one manufacturers command global service networks for high-touch clinical support around complex implantation and programming protocols. Specialist archetypes include algorithm-focused closed-loop developers, materials-science electrode suppliers, and regional contract manufacturers. Competitive moves concentrate on hardware-software co-design investments and unbundled service contracts that bypass traditional distributor markups.
Within the integrated multinational tier, Medtronic plc and Boston Scientific Corporation exemplify archetypes of global service network deployment and differentiated neuromodulation platform development. Abbott Laboratories occupies a position in closed-loop cardiac specialization. These three anchors represent distinct strategic vectors: comprehensive clinical support infrastructure, vagus nerve stimulation platform breadth, and adaptive algorithm cardiac systems respectively.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Abbott Laboratories |
| LivaNova PLC |
| Cochlear Ltd. |
| Biotronik SE & Co. KG |
| Nevro Corp. |
| Sonova Holding AG |
| MicroPort Scientific Corporation |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Minnesota and Massachusetts pulse generator facilities shapes both supply concentration and implantable device price floors. Scale economies in lead assembly production concentrate bargaining power with tier-one manufacturers, while transcutaneous alternatives compress entry-level pricing bands.
Pricing Analysis
Long-term service contracts dominate implantable neuromodulation, with hospitals negotiating multi-year programming and maintenance bundles separate from hardware procurement. Price differentiation rests on algorithmic sophistication and FDA breakthrough designation status, with closed-loop systems commanding premium positioning over static stimulation protocols. Cost compression in transcutaneous segments intensifies as pharmacy-distributed over-the-counter devices expand. Academic medical centers show lowest price sensitivity given reimbursement security, while community hospitals face acute budget constraints for capital-intensive implantation programs.
Supply Chain Analysis
Inventory buffers for platinum-iridium electrodes stretch to six-month coverage given concentrated South African refiner dependency. Component sourcing draws from Switzerland for precision machined parts, Germany for electronic subassemblies, and the United States for pulse generator final assembly. Single-source vulnerability in noble metal supply exposes manufacturers to geopolitical disruption and price volatility. Distribution runs through direct-to-hospital contracts that bypass traditional distributor networks for high-complexity deep brain stimulation systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electroceutical markets reward service-attach models where remote monitoring subscriptions and predictive maintenance contracts expand faster than hardware replacement cycles. AI-enabled battery depletion forecasting represents the fastest-growing recurring revenue layer.
For Market Incumbents: Shield installed base relationships through captive clinical engineering support for post-implant programming, where trained specialist scarcity creates switching costs. Deepen backward integration into electrode materials to mitigate South African supply concentration. Prioritize FDA breakthrough pathway submissions for adaptive algorithm indications to compress regulatory timelines against emerging closed-loop competitors. For New Entrants and Emerging Players: Differentiate on gastrointestinal neuromodulation white space, where gastric electrical stimulation for gastroparesis faces limited incumbent presence. Target Japan's aging metropolitan corridors for deep brain stimulation demand expansion, leveraging PMDA conditional early approval pathways. Pursue hospital procurement committee direct engagement to unbundle service contracts from established distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithm-focused developers with responsive neurostimulation platforms over commodity pulse generator manufacturers. Five-to-ten year viability hinges on software-defined medical device regulatory accommodation and health technology assessment body acceptance. Watch FDA breakthrough designation velocity as inflection indicator for bioelectronic medicine commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct contracting with German university hospitals bypasses distributor markups for deep brain stimulation. |
| Software Companion Development | DiGA fast-track eligibility in Germany creates reimbursement precedent for algorithm-enabled patient apps. |
| FDA Breakthrough Submission | Accelerated review compresses time-to-revenue for treatment-resistant depression neuromodulation platforms. |
| CE Marking Pathway | EU MDR technical documentation investments extend certification timelines but secure European market access. |
| Reimbursement Strategy | Coverage expansion for closed-loop cardiac systems in United States Medicare determines addressable patient pools. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA premarket approval databases, EU MDR technical documentation filings, and hospital procurement contract registries. Interviews with functional neurosurgeons, biomedical engineering directors, GPO contracts managers, and electrophysiology department heads inform demand-side validation. Bottom-up shipment estimates for pulse generators and leads triangulate against top-down reimbursement expenditure analysis from CMS and German sickness funds.
Segmentation dimensions modeled span product type, technology architecture, end-user facility tier, and therapeutic application across the projection horizon. CAGRs derive from logistic diffusion curves fitted to historical implantation procedure volumes and payer coverage expansion trajectories. Algorithm adoption rates and health technology assessment body cost-effectiveness thresholds feed directly into closed-loop system penetration assumptions.
The analysis sits within stated boundaries; outcomes outside sustained FDA breakthrough designation velocity or EU MDR certification timeline stability would require recalibration. Forecasts reflect documented assumptions regarding reimbursement framework evolution and trained programmer supply expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Lactate Meter Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Neurofeedback Systems Market
Medical Devices
Asia-Pacific Vagus Nerve Stimulation Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
Global Extracorporeal CO2 Removal Devices Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Global Medical Implants Market
Medical Devices
Wireless Breast Pump Market
Medical Devices
Global Bowel Management System Market
Medical Devices
Endoluminal Device Systems Market
Medical Devices
Body Contouring Devices and Procedures Market
Medical Devices
Laryngoscopes Market