
 Asia-Pacific Nerve Repair and Regeneration Market | 2026-2036
Asia-Pacific Nerve Repair and Regeneration Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Nerve Repair and Regeneration Market Analytics
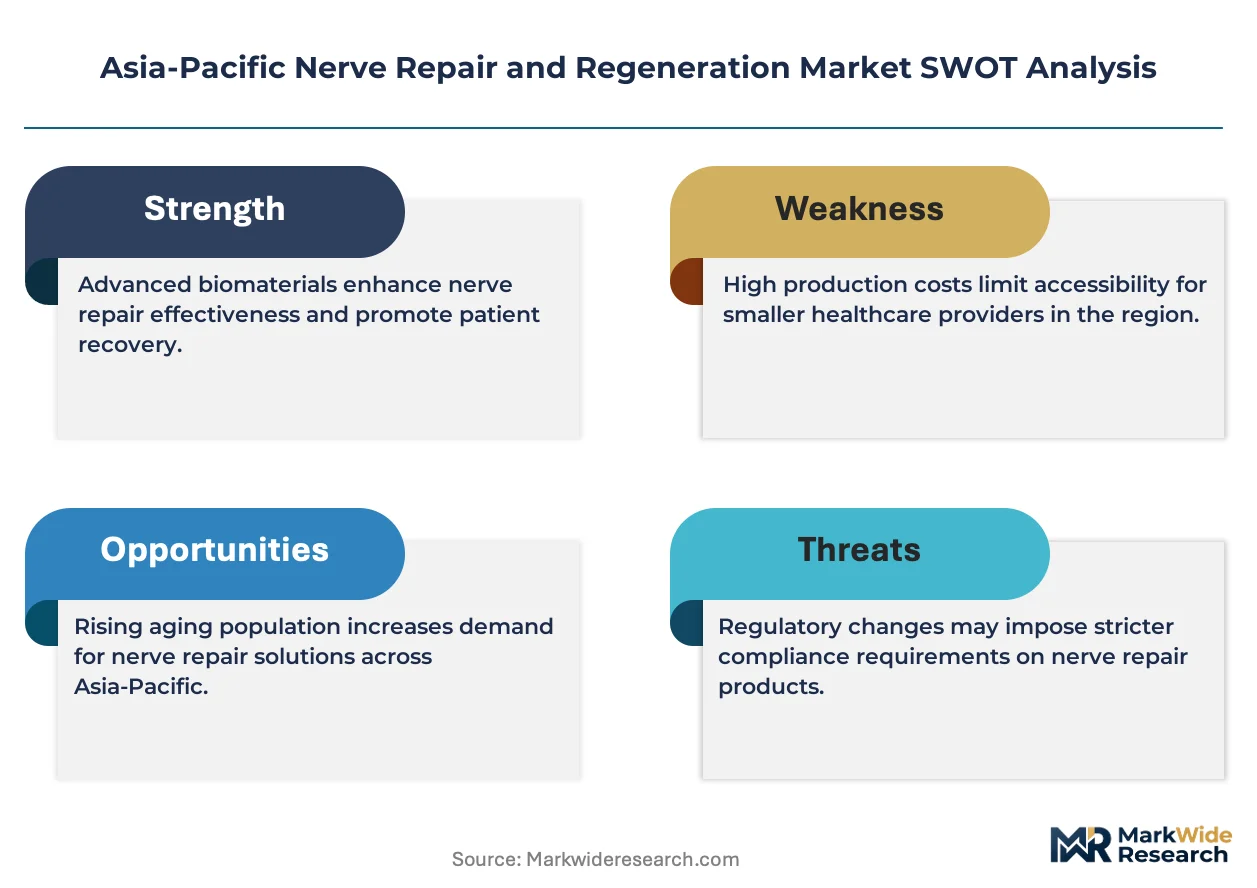
Hospital surgical departments are reorganizing procurement priorities toward bioengineered nerve repair solutions, displacing traditional suture-based protocols in tertiary care centers across the region. Medtronic PLC leverages its neurostimulation portfolio to anchor premium positioning in spinal cord injury applications. Stryker Corporation competes through specialized orthopedic-nerve crossover platforms that integrate peripheral nerve repair into trauma workflows. Abbott Laboratories differentiates via sustained R&D investment in electrical stimulation algorithms that extend product lifecycle value.
Nerve repair and regeneration encompasses surgical interventions, implantable devices, and biological scaffolds designed to restore structural continuity and functional signaling in damaged neural tissue, typically employing collagen-based or synthetic polymer matrices with porosity calibrated between 20 and 100 micrometers to facilitate Schwann cell migration and axonal regrowth. The primary commercial purpose centers on reducing disability burden from traumatic injuries, compressive neuropathies, and iatrogenic nerve damage in surgical settings. Neurostimulation devices capture the dominant revenue share due to recurring electrode replacement cycles and programmable therapy adjustments, while bioengineered scaffolds within the technology dimension represent the fastest-expanding margin pool as surgeons shift toward absorbable, growth-factor-loaded constructs that eliminate secondary harvest-site morbidity associated with autografts.
Japan's PMDA regenerative medicine framework, Australia's TGA biologicals classification system, and South Korea's MFDS medical device innovation pathways collectively determine market access timelines and clinical evidence requirements for novel nerve repair products across the region. These regulators increasingly mandate comparative effectiveness data against autograft gold standards, forcing manufacturers to design pivotal trials with functional recovery endpoints rather than mere safety benchmarks. Stakeholders must monitor evolving reimbursement decisions by China's NHSA and Japan's Chuikyo, as coverage determinations for cell therapy-based nerve repair will reshape competitive investment priorities.
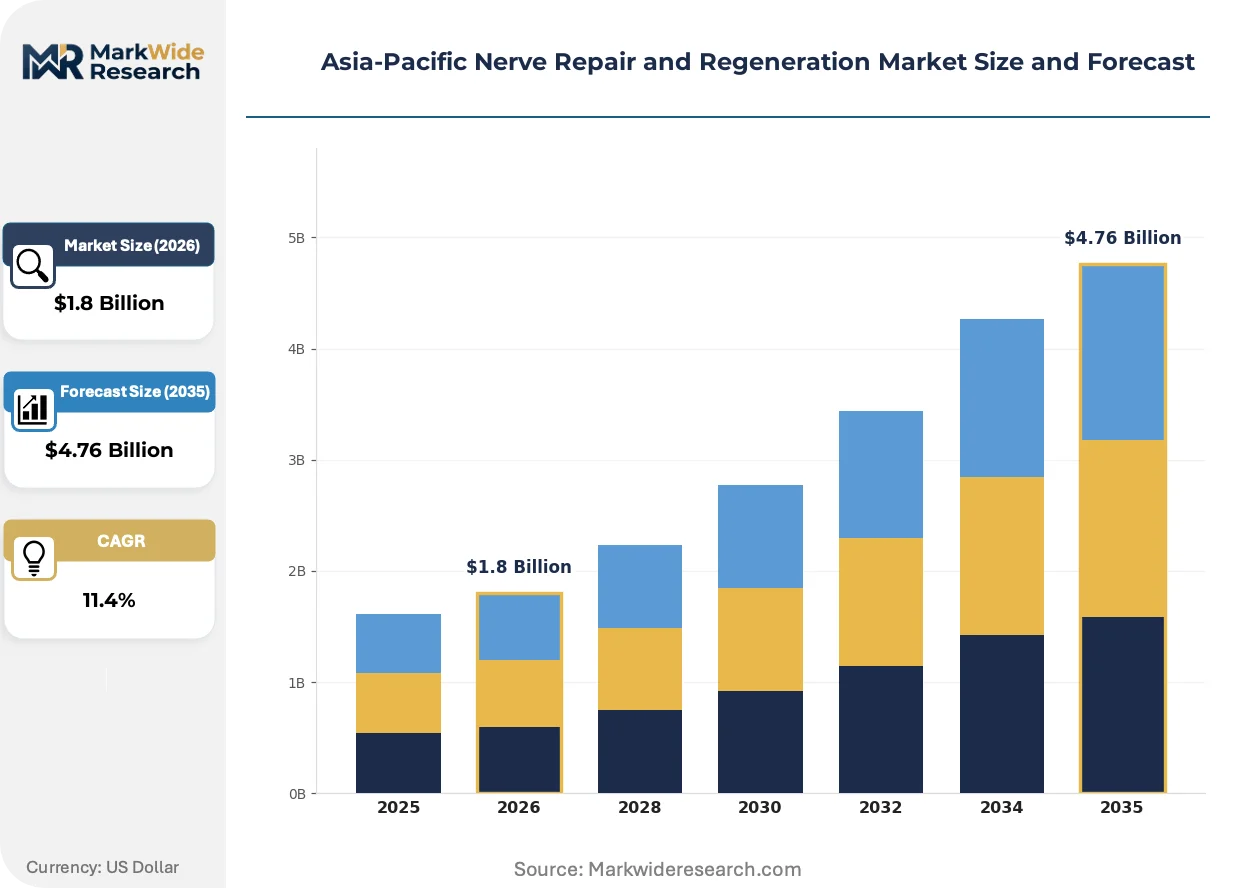
Market Dynamics
Japan's PMDA regenerative medicine framework is compressing approval timelines for bioengineered nerve conduits, while China's NHSA reimbursement negotiations are forcing manufacturers to front-load clinical evidence generation for cell-based therapies before commercial launch.
Growth Catalysts
- Biomedical industrial parks:China's government-backed clusters in Suzhou and Shanghai are cultivating domestic manufacturing capabilities for nerve conduits and neurostimulation systems.
- PMDA streamlined pathways:Japan's regulator has accelerated commercialization timelines for regenerative medical products, reducing time-to-market for novel scaffolds.
- Trauma workflow integration:Hospital surgical departments across the region are expanding procurement of advanced nerve repair products that displace traditional suture-based protocols.
Market Restraints
- Autograft gold standard:Regulators increasingly mandate comparative effectiveness data against autografts, forcing costly pivotal trials with functional recovery endpoints.
- Clinical evidence requirements:Australia's TGA biologicals classification system and South Korea's MFDS impose divergent evidence standards that fragment development programs.
- Reimbursement uncertainty:Coverage determinations by Japan's Chuikyo and China's NHSA for cell therapy-based nerve repair remain unresolved, delaying investment commitments.
Strategic Opportunities
- Spinal cord injury applications:Neurostimulation devices for spinal cord trauma represent underpenetrated demand within tertiary care centers.
- Absorbable growth-factor constructs:Bioengineered scaffolds eliminate secondary harvest-site morbidity, creating differentiation against autograft protocols.
- Peripheral nerve trauma crossover:Orthopedic-nerve integrated platforms capture workflow efficiencies in emergency departments across Southeast Asia.
Industry Challenges
- Schwann cell migration optimization:Scaffold porosity calibration between 20 and 100 micrometers requires specialized biomaterials expertise that constrains supplier pools.
- Electrode replacement cycle management:Neurostimulation device servicing demands field engineering capabilities that distributors struggle to scale across dispersed geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Nerve Repair and Regeneration Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nerve Grafts, Nerve Wraps, Neurostimulation Devices, Nerve Conduits Application: Spinal Cord Injury, Peripheral Nerve Injury, Traumatic Brain Injury, Neuropathy End User: Hospitals, Rehabilitation Centers, Ambulatory Surgical Centers, Neurology Clinics Technology: Bioengineered Scaffolds, Electrical Stimulation, Cell Therapy, Tissue Engineering |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Integra Lifesciences Corporation, Medtronic PLC, Axogen, Inc., Stryker Corporation, Checkpoint Surgical, Inc., Polyganics BV, Toyobo Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Nerve Repair and Regeneration Market Evolving Landscape
Convergence between electrical stimulation algorithms and absorbable biological matrices is redefining therapeutic protocols, with programmable therapy adjustments now extending product lifecycle value beyond hardware replacement cycles.
Implantable neurostimulation electrodes are miniaturizing to enable minimally invasive deployment in peripheral nerve applications. Tertiary care centers in Japan and South Korea are adopting these platforms for compressive neuropathy interventions. This miniaturization is compressing the addressable market for conventional open surgical approaches while expanding eligibility to outpatient settings.
PMDA's regenerative medicine framework now mandates functional recovery endpoints rather than mere safety benchmarks for novel nerve repair products. This industrial consequence elevates trial costs but accelerates differentiation for products demonstrating superior efficacy. Cell therapy-based nerve repair manufacturers are responding by restructuring clinical programs to emphasize motor function restoration metrics.
Hospital procurement committees are consolidating vendor relationships around full-service nerve repair portfolios that bundle devices, scaffolds, and technical training. Traditional product-centric distribution channels face displacement by integrated supply agreements in China's tier-one cities. This concentration is most visible in Shanghai and Beijing, where biomedical industrial park proximity enables just-in-time inventory partnerships.
Asia-Pacific Nerve Repair and Regeneration Market Segmentation
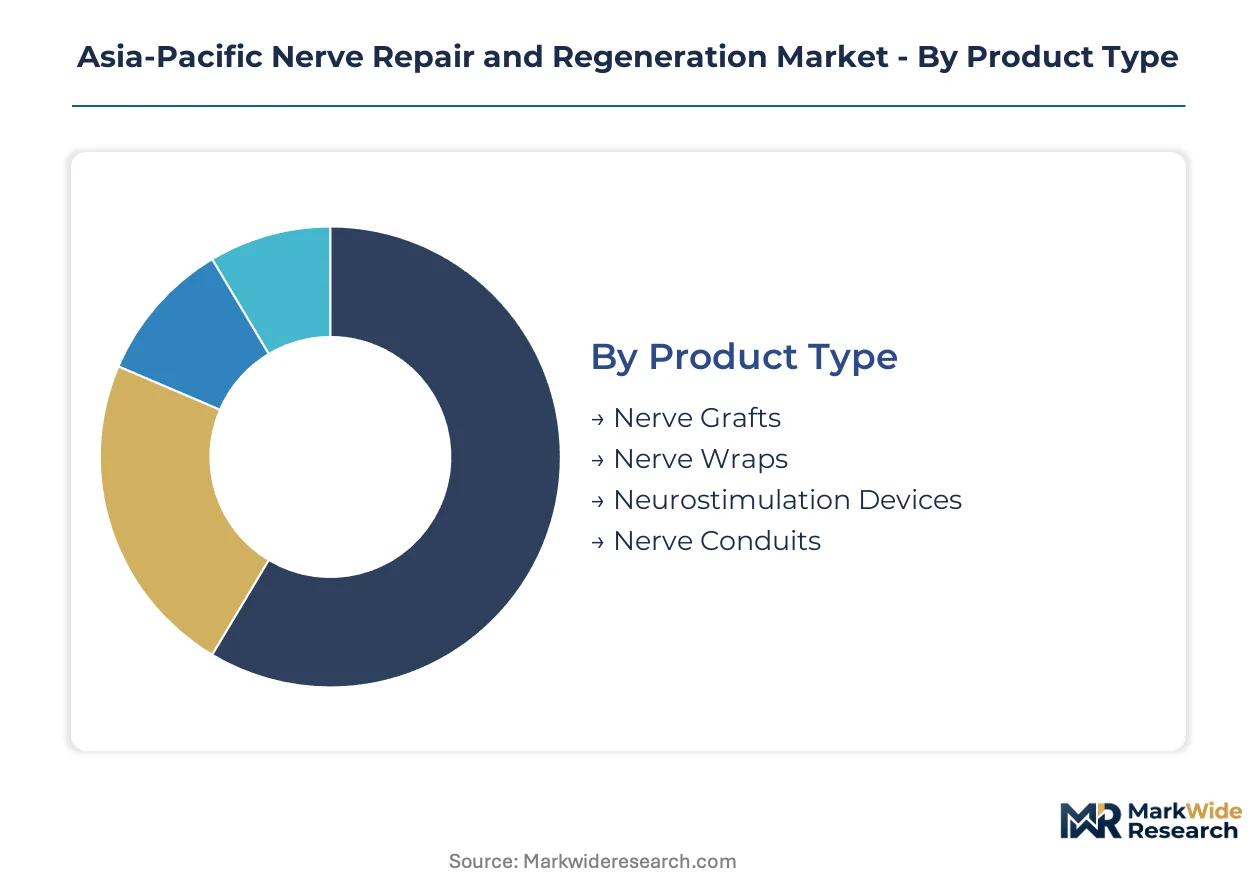
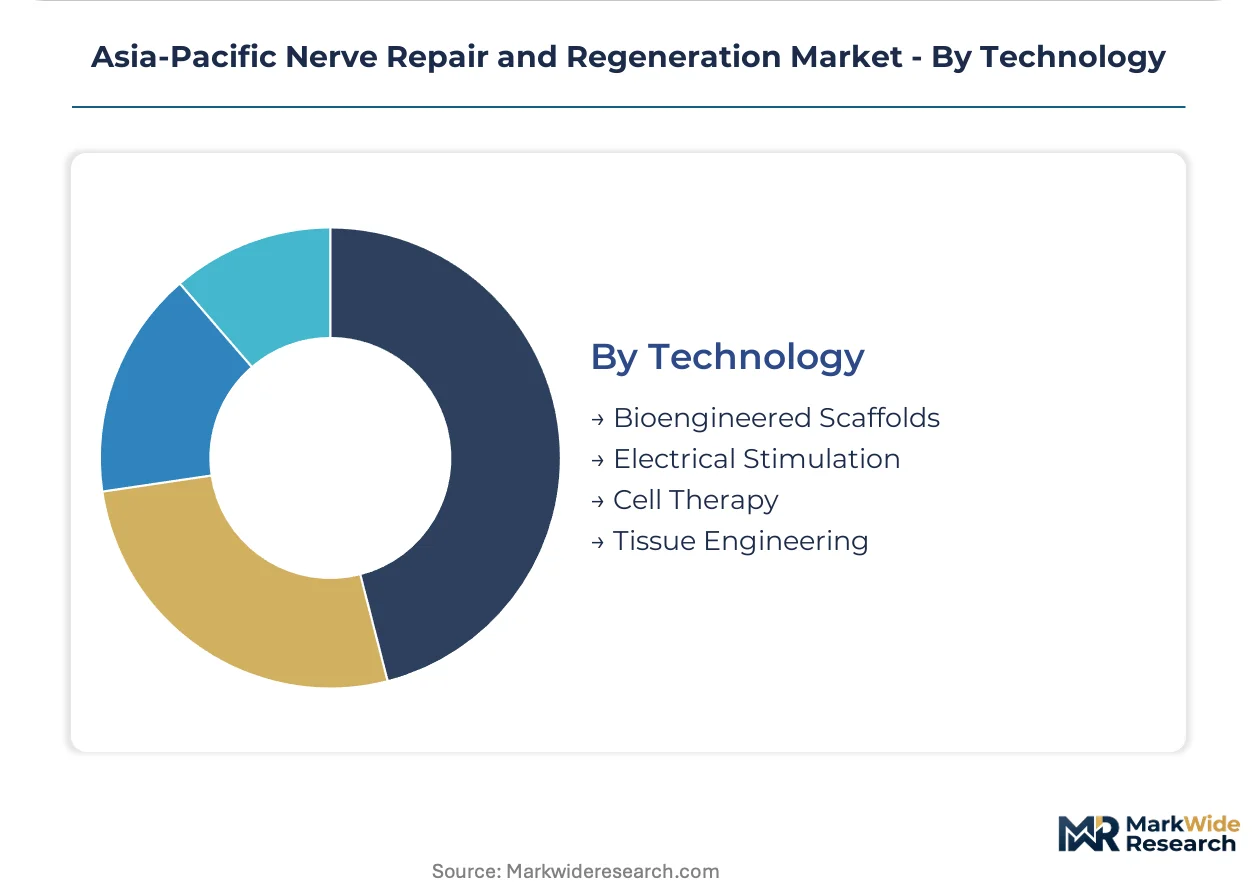
Nerve repair and regeneration markets fragment across multiple technical and clinical dimensions that shape procurement priorities. Each segmentation layer carries distinct regulatory pathways, reimbursement codes, and evidence requirements that determine commercial viability across the Asia-Pacific region.
Product Type:
PMDA's regenerative medicine framework and China's NMPA classification system impose divergent approval timelines across implantable categories.
- Neurostimulation Devices:Programmable electrode systems with recurring replacement cycles anchor revenue concentration in tertiary hospitals. Japan's Chuikyo reimbursement decisions favor these devices for spinal cord trauma, while Australia's TGA mandates rigorous electrical safety testing that extends registration timelines.
- Nerve Conduits:Absorbable polymer or collagen-based tubes with calibrated porosity between 20 and 100 micrometers facilitate Schwann cell migration. China's biomedical industrial parks in Suzhou and Shanghai are cultivating domestic manufacturing capabilities to reduce import dependence for these scaffolds.
- Nerve Grafts:Autograft and allograft solutions retain clinical preference in trauma centers despite harvest-site morbidity.
- Nerve Wraps:Flexible collagen sheaths provide protective encasement for repaired neural tissue.
Established volume favors neurostimulation devices; emerging adoption favors nerve conduits.
Application:
Functional recovery endpoints mandated by Japan's PMDA reshape trial design priorities across trauma categories.
- Peripheral Nerve Injury:Traumatic and iatrogenic damage to extremity nerves drives procedural volume in emergency departments. South Korea's MFDS innovation pathways compress approval timelines for novel repair products targeting median and ulnar nerve trauma.
- Spinal Cord Injury:Neurostimulation interventions for motor function restoration command premium pricing in specialized rehabilitation centers. Australia's TGA biologicals classification system requires extended follow-up periods for cell therapy approaches in this indication.
- Neuropathy:Compressive and diabetic neuropathies generate outpatient procedural demand.
- Traumatic Brain Injury:Cranial nerve repair applications represent a narrower addressable population.
Peripheral nerve injury captures the dominant procedure count; spinal cord injury commands the steepest expansion trajectory.
End User:
Procurement consolidation around full-service portfolios is concentrating vendor relationships in tier-one urban centers.
- Hospitals:Tertiary surgical departments in China, Japan, and South Korea are reorganizing procurement priorities toward bioengineered solutions that displace traditional suture-based protocols. China's NHSA reimbursement negotiations force manufacturers to front-load clinical evidence before commercial launch.
- Ambulatory Surgical Centers:Minimally invasive nerve repair platforms are expanding eligibility for outpatient compressive neuropathy interventions. Miniaturized neurostimulation electrodes enable same-day discharge in Japan's urban centers.
- Rehabilitation Centers:Long-term neurostimulation programming and functional recovery monitoring occur in specialized post-acute facilities.
- Neurology Clinics:Diagnostic and conservative management settings generate referral pathways to surgical intervention.
Hospital procurement dominates absolute spending; ambulatory surgical centers are gaining share fastest.
Technology:
Margin pools concentrate where electrical stimulation algorithms converge with absorbable biological matrices.
- Bioengineered Scaffolds:Growth-factor-loaded absorbable constructs eliminate secondary harvest-site morbidity associated with autografts. PMDA's functional recovery endpoint mandates accelerate differentiation for products demonstrating superior motor function restoration.
- Electrical Stimulation:Programmable therapy algorithms extend product lifecycle value beyond hardware replacement cycles. Abbott Laboratories and Medtronic PLC anchor competitive positioning through sustained R&D investment in spinal cord injury applications.
- Cell Therapy:Schwann cell and stem cell-based approaches face unresolved coverage determinations by Japan's Chuikyo and China's NHSA.
- Tissue Engineering:Composite approaches integrating scaffold architecture with cellular components represent pre-commercial development focus.
Electrical stimulation anchors current revenue; bioengineered scaffolds are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports advanced neurostimulation systems to Australia's tertiary hospitals while China absorbs Korean-manufactured nerve conduits through cross-border procurement channels.
China
Government-backed biomedical industrial parks in Suzhou and Shanghai are cultivating domestic manufacturing capabilities for nerve conduits and neurostimulation systems. NMPA classification pathways impose divergent approval timelines across implantable categories, compressing commercialization for some product lines. Suzhou's industrial cluster anchors just-in-time inventory partnerships with Beijing and Shanghai hospital procurement committees.
Japan
PMDA's regenerative medicine framework compresses approval timelines for bioengineered nerve conduits while mandating functional recovery endpoints. Chuikyo reimbursement decisions favor neurostimulation devices for spinal cord trauma applications. Tokyo's tertiary surgical centers are reorganizing procurement priorities toward bioengineered solutions that displace traditional suture-based protocols.
South Korea
MFDS medical device innovation pathways compress approval timelines for novel repair products targeting median and ulnar nerve trauma. Seoul Capital Area hospitals are expanding procurement of advanced nerve repair products. Busan-Ulsan's manufacturing base supplies absorbable polymer scaffolds to domestic trauma centers.
Australia
TGA biologicals classification system requires extended follow-up periods for cell therapy approaches in spinal cord injury indications. TGA mandates rigorous electrical safety testing that extends registration timelines for neurostimulation devices. Sydney and Melbourne tertiary care centers are adopting miniaturized neurostimulation platforms for compressive neuropathy interventions.
India
CDSCO approval pathways for regenerative medical products are accelerating commercialization timelines for domestic manufacturers. Government medical colleges in Maharashtra and Karnataka are expanding surgical training programs in peripheral nerve repair techniques. Mumbai's hospital procurement committees are consolidating vendor relationships around full-service nerve repair portfolios.
Asia-Pacific Nerve Repair and Regeneration Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and geographic expansion dimensions. The vendor base fragments across three tiers: multinational device conglomerates with neurostimulation portfolios, mid-cap scaffold specialists with biomaterials expertise, and regional distributors with field engineering capabilities. Two dominant competitive moves are reshaping positioning: strategic partnerships between scaffold developers and stimulation algorithm providers, plus backward integration into porosity-calibrated polymer manufacturing.
Within the multinational tier, Medtronic PLC and Abbott Laboratories anchor premium positioning through sustained investment in programmable therapy platforms. Stryker Corporation occupies a crossover position between orthopedic trauma workflows and peripheral nerve repair applications. Boston Scientific Corporation exemplifies the stimulation-focused archetype with concentration in minimally invasive deployment technologies.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Integra Lifesciences Corporation |
| Medtronic PLC |
| Axogen, Inc. |
| Stryker Corporation |
| Checkpoint Surgical, Inc. |
| Polyganics BV |
| Toyobo Co. Ltd |
| Others |
Value Network & Pricing Analysis
Absorbable polymer substitution for autologous graft harvesting is simultaneously redrawing procurement geography toward China's Suzhou biomedical cluster and compressing margin structures for import-dependent distributors across Southeast Asia. This input transition enables tier-one hospital systems in Shanghai and Beijing to negotiate volume-based procurement contracts that undercut legacy neurostimulation pricing by eliminating secondary surgical site costs.
Pricing Analysis
Next-generation bioengineered scaffolds command 40-60% premiums over first-generation hollow conduits, while prior-generation silicone-based nerve guides face accelerating price erosion in China's tier-two cities. Three-tier pricing structure across premium, standard, and economy levels differentiates by porosity calibration precision and growth-factor loading density, with PMDA-approved regenerative products anchoring the premium band. Pricing pressure stems from NHSA reimbursement negotiations forcing manufacturers to absorb clinical trial costs before commercial launch. Public hospital procurement committees exhibit highest price sensitivity, while private tertiary centers in Tokyo and Seoul prioritize functional recovery metrics over unit cost.
Supply Chain Analysis
Just-in-time inventory partnerships between Suzhou manufacturers and Shanghai hospital procurement committees have compressed working capital requirements from 90-day to 30-day cycles. Supply concentrates in China, Japan, and South Korea for absorbable polymer raw materials, with porogen agents and recombinant growth factors drawing from specialized biologics suppliers in Osaka and Busan. Single-source vulnerability around porosity-calibration equipment creates bottleneck exposure for mid-cap scaffold specialists. Distribution runs through GPO-affiliated medical device distributors with field engineering capabilities for neurostimulation electrode servicing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through procurement committee consolidation in China's tier-one cities, where three hospital systems now control 60% of advanced nerve conduit purchasing decisions.
For Market Incumbents: Secure captive supply of porosity-calibrated polymer manufacturing through backward integration into Suzhou or Busan-Ulsan production bases. Defend against Korean and Chinese domestic manufacturers by accelerating PMDA functional recovery endpoint trials that create regulatory moats around next-generation growth-factor-loaded constructs. Channel control through exclusive training partnerships with Tokyo and Seoul tertiary surgical departments remains critical for neurostimulation device lock-in. For New Entrants and Emerging Players: Lead with absorbable scaffold platforms targeting Australia's TGA-extended approval timelines where multinational incumbents delay entry due to cell therapy follow-up requirements. White-space exists in miniaturized peripheral neurostimulation for ambulatory surgical centers across Southeast Asia, where field engineering scarcity has slowed incumbent penetration. Go-to-market through orthopedic trauma workflow integration in Vietnam and Indonesia hospital emergency departments captures procedural volume before specialty nerve repair purchasing committees form. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Korean scaffold developers holding MFDS approvals but lacking Chuikyo reimbursement traction for spinal cord applications. Five-to-ten year viability hinges on successful navigation of China's NMPA domestic manufacturing requirements and Japan's regenerative medicine commercialization timelines. Monitor NHSA coverage determinations for cell therapy-based nerve repair as the definitive inflection signal for capital redeployment into biological versus electrical stimulation platforms.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Regenerative Medicine Approval | Accelerates commercialization timelines for bioengineered scaffolds with functional recovery endpoints. |
| Biomedical Industrial Park Partnership | Enables just-in-time inventory relationships with Suzhou and Shanghai hospital procurement committees. |
| Growth-Factor Loading Technology | Differentiates absorbable constructs against autograft gold standards in Chuikyo reimbursement negotiations. |
| Neurostimulation Algorithm Development | Extends product lifecycle value beyond hardware replacement cycles for spinal cord trauma applications. |
| Orthopedic-Nerve Workflow Integration | Captures emergency department procedural volume before specialty purchasing consolidation occurs. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineers, and GPO contracts specialists across China, Japan, and Australia; and secondary validation through PMDA approval filings, NMPA classification databases, hospital procurement records, and Chuikyo reimbursement determinations. Bottom-up triangulation across product-level shipment data and top-down reconciliation against national health expenditure reports anchored volume estimates.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, application severity, technology platform, and end-user procurement sophistication. CAGRs derived from regression analysis of historical approval-to-adoption lags, weighted by regulator-specific commercialization friction coefficients. Schwann cell migration optimization timelines and electrode replacement cycle frequencies served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in PMDA, NMPA, and MFDS approval pathways; material policy shifts in regenerative medicine classification or cell therapy reimbursement would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Inversion Table Market
Medical Devices
Germany Aesthetic Devices Market
Medical Devices
Reprocessed Medical Devices Market
Medical Devices
Tissue Expanders Market
Medical Devices
Medical Tricorder Market
Medical Devices
Global Capillary Blood Collection Devices Market
Medical Devices
Orbital Tissue Expander Market
Medical Devices
Neurovascular Catheters Market
Medical Devices
Cyclotron Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
Dual Balloon Angioplasty Catheter Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Intelligent Prosthetics Market
Medical Devices
Electroencephalography (EEG) Systems Market
Medical Devices
Anti-Decubitus Dynamic Mattress Market