
 Radial Access Catheter Market | 2026-2036
Radial Access Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Radial Access Catheter Market Analytics
Aftermarket service revenue for catheter reprocessing and sterilization validation is rewriting profit allocation across the vascular access value chain. Medtronic plc leverages its integrated hospital contracting networks to sustain premium positioning in coated introducer portfolios. Boston Scientific Corporation anchors North American distribution through direct cardiac catheterization laboratory relationships. Terumo Corporation dominates radial-specific hemostasis device ecosystems in Asia-Pacific tertiary centers.
Radial access catheters are thin-walled, kink-resistant introducer systems manufactured from Pebax or nylon multilayer extrusions with hydrophilic coatings, designed to establish arterial entry via the wrist for diagnostic and interventional procedures. Cardiology applications lead procedural volume while coated technology commands the highest unit economics due to lubricious surface treatments that reduce vascular trauma. Double-lumen configurations represent the fastest-growing product architecture as complex percutaneous coronary interventions demand simultaneous pressure monitoring and guidewire exchange capability.
FDA 510(k) clearance pathways and the EU MDR conformity assessment framework govern sterility assurance and biocompatibility testing for radial access devices entering clinical use. Japan's PMDA enforces JIS-standard material traceability that shapes supplier qualification timelines for Asian market entry. Stakeholders must monitor evolving hemostasis protocol reimbursement decisions by CMS and analogous health technology assessment bodies as transradial adoption expands beyond coronary into peripheral vascular interventions.
Market Dynamics
Transradial coronary intervention protocols are displacing femoral access across tertiary cardiac catheterization laboratories, forcing catheter manufacturers to redesign introducer systems for smaller radial artery anatomies and hemostasis management.
Growth Catalysts
- EU MDR sterility benchmarks:Tightened biocompatibility requirements for hydrophilic-coated devices are accelerating R&D investment in lubricious surface technologies across European manufacturing facilities.
- Japan's metropolitan hospital clusters:Dense concentration of tertiary interventional cardiology departments in Tokyo and Osaka generates procedural volume density that validates radial-specific device ecosystems.
- Pebax multilayer extrusion:Advanced polymer processing techniques enable thinner-walled catheter constructions that maintain kink resistance while reducing vascular trauma during complex guidewire exchanges.
Market Restraints
- Specialized polymer supply concentration:Pebax and nylon resin production concentrates among a limited supplier base in Western Europe, exposing manufacturers to input cost volatility and allocation constraints.
- FDA 510(k) pathway friction:Premarket notification requirements for novel coating chemistries extend regulatory timelines and elevate validation costs for introducer system innovators.
- Femoral access residual preference:Established interventional cardiologists in certain US hospital systems maintain procedural familiarity with transfemoral techniques, slowing radial protocol adoption curves.
Strategic Opportunities
- Peripheral vascular radial expansion:Transradial access for peripheral arterial interventions remains underdeveloped relative to coronary applications, creating white space for catheter configurations optimized to lower-extremity anatomy.
- Double-lumen architecture demand:Complex percutaneous coronary interventions requiring simultaneous pressure monitoring and guidewire exchange capability are driving premium positioning for multi-channel introducer designs.
- Aftermarket service unbundling:Catheter reprocessing and sterilization validation services represent recurring revenue streams that device manufacturers can capture through direct hospital contracting relationships.
Industry Challenges
- Interventional cardiologist training pipelines:Transradial technique proficiency requires specialized fellowship exposure and proctored case volumes that academic medical centers struggle to scale.
- EU MDR technical documentation:Conformity assessment frameworks demand extensive clinical evidence and post-market surveillance systems that mid-cap manufacturers must build without legacy infrastructure.
- Legacy catheterization laboratory retrofitting:Existing cardiac cath labs optimized for femoral access require workflow reconfiguration and radiation shielding adjustments to accommodate radial positioning protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radial Access Catheter Market |
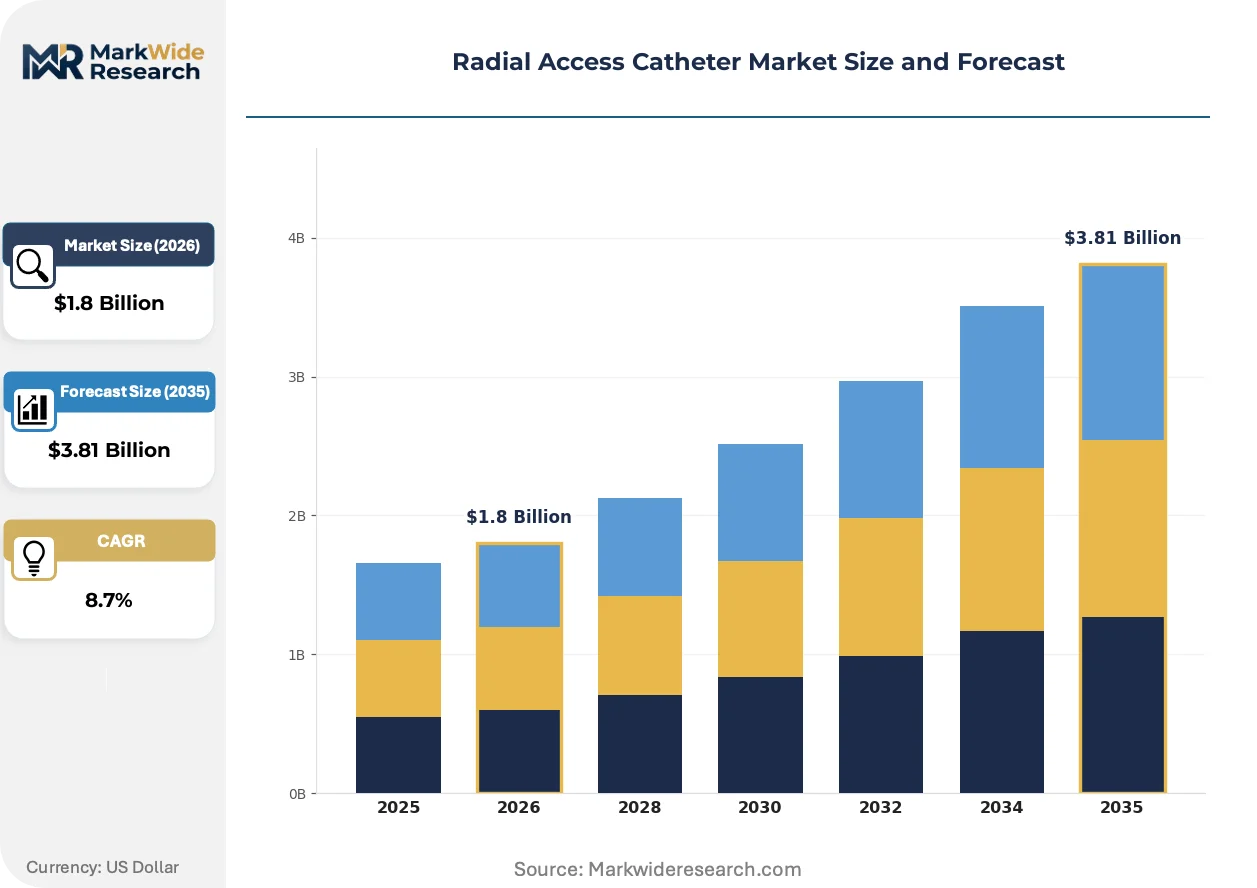
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Lumen, Double-Lumen, Sheath, Other End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Research Labs Technology: Conventional, Biodegradable, Coated, Other Application: Cardiology, Neurology, Emergency Medicine, Vascular Surgery |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Terumo Corporation, Abbott Laboratories, Becton, Dickinson and Company, Teleflex Incorporated, Edwards Lifesciences Corporation, AngioDynamics, Inc., Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radial Access Catheter Market Evolving Landscape
Digital simulation platforms are compressing product development cycles for catheter introducer systems while regulatory frameworks tighten material traceability requirements across major markets.
Computational fluid dynamics modeling paired with patient-specific arterial geometry reconstruction is virtualizing traditional benchtop testing protocols for hydrophilic coating performance. Tier-one manufacturers deploy these virtual validation environments to reduce physical prototype iterations before FDA submission. The compression of design-to-clearance timelines is concentrating competitive advantage among firms with integrated simulation capabilities.
Japan's PMDA enforcement of JIS-standard material traceability is reshaping supplier qualification timelines for Asian market entry. Manufacturers must document polymer batch provenance and coating chemistry lineage through multi-tier supply chains. Cardiology device divisions with captive resin compounding operations navigate these requirements with lower compliance friction than outsourced production models.
Hospital procurement committees are consolidating vascular access device purchasing through integrated contracting networks that bundle introducer systems with hemostasis management accessories. Cardiac catheterization laboratory directors in US health systems increasingly specify radial-first protocols in vendor selection criteria. This preference compression is visible across IDN-affiliated hospitals where standardization committees mandate transradial default positioning for eligible coronary interventions.
Radial Access Catheter Market Segmentation
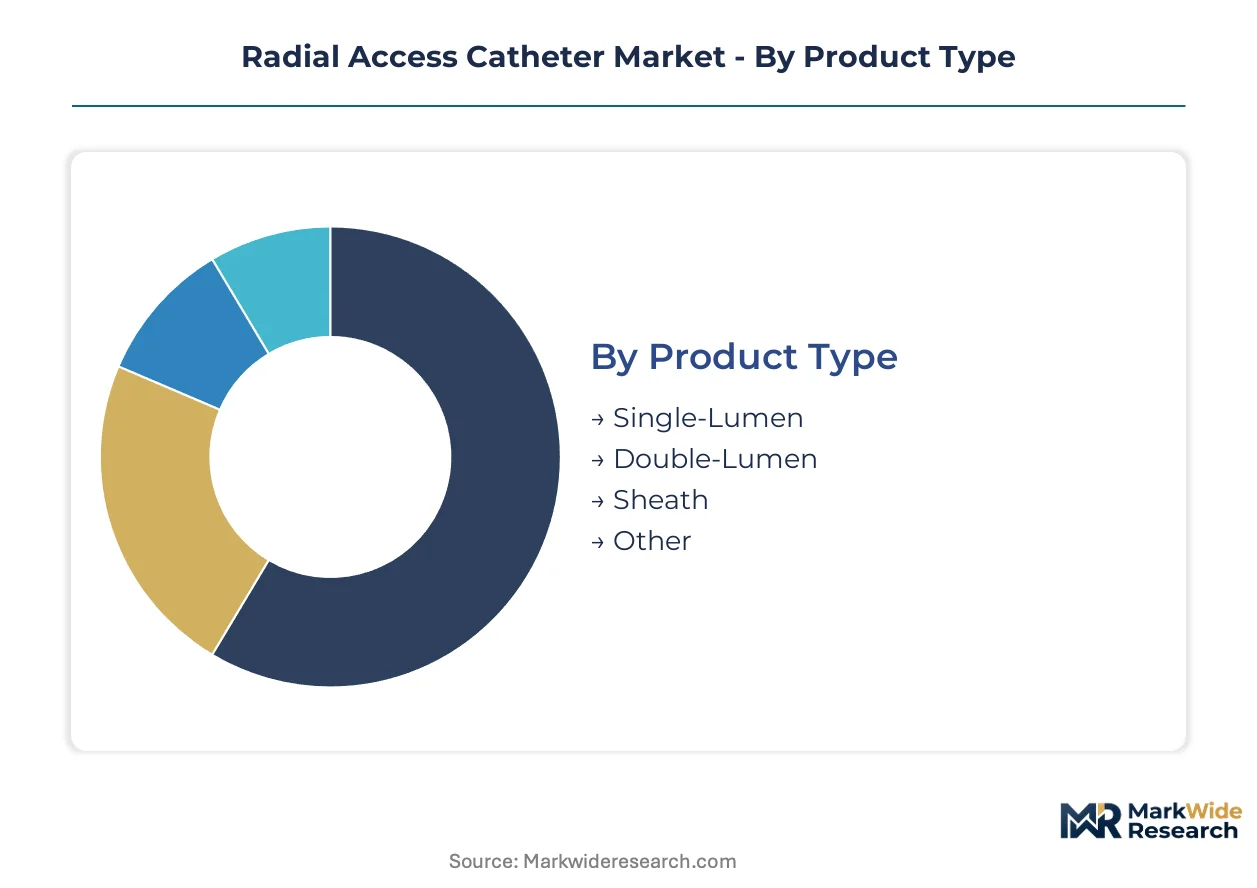
Radial access catheter segmentation reveals how procedural complexity and site-of-care economics reshape purchasing patterns across vascular access portfolios. Device configurations and surface technologies stratify sharply between high-volume coronary interventions and emerging peripheral applications.
Product Type:
Architecture complexity determines unit economics and clinical utility across transradial procedural workflows.
- Double-Lumen:Dual-channel designs enable simultaneous pressure monitoring and guidewire exchange during complex percutaneous coronary interventions. Tertiary cardiac catheterization laboratories in Japan's metropolitan hospital clusters drive procurement volume as transradial protocols expand into multi-vessel disease cases.
- Single-Lumen:Standard introducer configurations serve diagnostic coronary angiography with simpler vascular access requirements. Diagnostic centers in Germany favor these systems for throughput efficiency in high-volume screening programs.
- Sheath:Vascular access sheaths provide initial arterial entry and hemostasis management for radial protocols.
- Other:Specialized introducer variants address niche anatomical variations and pediatric applications.
Double-lumen systems command the established base in interventional cardiology. The steepest expansion runs through sheath configurations optimized for same-day discharge protocols.
End User:
Site-of-care purchasing power concentrates around procedural volume density and integrated contracting networks.
- Hospitals:Tertiary cardiac catheterization laboratories anchor radial access catheter consumption through integrated vascular access device purchasing. United States health systems with IDN-affiliated networks mandate radial-first protocols in vendor selection criteria, consolidating introducer system procurement with hemostasis management accessories.
- Diagnostic Centers:Freestanding cardiac imaging facilities prioritize cost-efficient single-lumen configurations for diagnostic angiography workflows. German outpatient cardiology clinics leverage statutory reimbursement frameworks to sustain procedural volume without overnight admission infrastructure.
- Outpatient Clinics:Ambulatory surgical centers adopt radial access for same-day intervention eligibility.
- Research Labs:Academic medical centers source specialized configurations for investigational device trials.
Hospitals retain the dominant procurement position. The steepest volume climb occurs in outpatient clinics capitalizing on ambulatory payment classification shifts.
Technology:
Surface engineering and material science differentiate clinical performance tiers and regulatory pathway complexity.
- Coated:Hydrophilic surface treatments reduce vascular trauma and friction during guidewire exchanges through lubricious polymer layers. FDA 510(k) clearance pathways and EU MDR sterility benchmarks tighten biocompatibility validation requirements for these premium-tier devices, concentrating supply among manufacturers with captive coating chemistry operations.
- Biodegradable:Absorbable polymer formulations address hemostasis management without manual compression protocols. Japan's PMDA enforces JIS-standard material traceability that extends supplier qualification timelines for these novel constructions.
- Conventional:Uncoated nylon or Pebax constructions serve cost-sensitive procurement segments.
- Other:Experimental surface modifications and antimicrobial integrations remain in preclinical evaluation.
Coated technology captures premium positioning. Biodegradable platforms are gaining share fastest as hemostasis protocol innovation accelerates.
Application:
Procedural domain dictates catheter specification requirements and operator training infrastructure.
- Cardiology:Coronary interventions dominate radial access utilization with established transradial technique proficiency and dedicated fellowship training pipelines. Transradial coronary intervention protocols displace femoral access across tertiary cardiac catheterization laboratories in the United States, Germany, and Japan, forcing introducer system redesigns for smaller radial artery anatomies.
- Vascular Surgery:Peripheral arterial interventions represent underdeveloped radial access territory relative to coronary applications. Complex percutaneous coronary interventions requiring lower-extremity access create white space for catheter configurations optimized to peripheral anatomy.
- Emergency Medicine:Stroke intervention and trauma resuscitation protocols adopt radial access for rapid vascular entry.
- Neurology:Neurointerventional procedures explore transradial alternatives to femoral approaches for cerebral angiography.
Cardiology holds the volume base. Vascular surgery presents the steepest expansion trajectory as peripheral radial protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across geographies. Japanese hospitals absorb premium-coated introducer pricing without volume contraction. German outpatient clinics demand cost-efficient single-lumen configurations. United States health systems negotiate integrated vascular access bundles that compress unit margins.
United States
IDN-affiliated hospital networks consolidate introducer procurement through standardized radial-first protocols. FDA 510(k) clearance pathways extend timelines for novel hydrophilic coating chemistries. Tertiary cardiac catheterization laboratories in Cleveland Clinic and Mayo Clinic systems anchor transradial technique training pipelines.
Japan
Metropolitan hospital clusters in Tokyo and Osaka generate procedural volume density unmatched elsewhere. PMDA enforces JIS-standard material traceability that reshapes supplier qualification timelines. Terumo Corporation's radial hemostasis protocols diffuse through Kanto region academic medical centers.
Germany
Statutory reimbursement frameworks sustain outpatient diagnostic angiography without overnight admission infrastructure. EU MDR sterility benchmarks accelerate R&D investment in lubricious surface technologies. Freestanding cardiac imaging facilities in Bavaria and North Rhine-Westphalia prioritize throughput-efficient single-lumen configurations.
China
Provincial hospital procurement committees centralize vascular access device purchasing through volume-based tender mechanisms. NMPA governs biocompatibility testing for hydrophilic-coated devices entering clinical use. Yangtze River Delta tertiary centers expand transradial coronary intervention capacity faster than northern provinces.
Switzerland
Swissmedic conformity assessment demands extensive clinical evidence for coated introducer systems seeking market authorization. Premium pricing tolerance reflects concentrated purchasing power in Zurich and Geneva private hospital networks. Cardiac catheterization laboratory directors specify radial-default positioning for eligible interventions.
Radial Access Catheter Market Competitive Landscape
Capability concentration sits with integrated coating chemistry operations; scale advantage sits with diversified cardiovascular portfolios. The market structures around three tiers: captive resin compounders with regulatory infrastructure, diversified medtech conglomerates with hospital contracting networks, and regional specialists with niche anatomical configurations. Consolidation pressure runs through integrated vascular access bundles. Technology licensing agreements compress development timelines for hydrophilic surface innovations.
Within the diversified cardiovascular tier, Medtronic plc and Boston Scientific Corporation occupy positions shaped by direct cardiac catheterization laboratory relationships. Terumo Corporation anchors the Asia-Pacific radial-specific ecosystem through metropolitan hospital cluster penetration. These three exemplify distinct competitive vectors: integrated contracting networks, North American distribution density, and regional protocol dominance respectively.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Terumo Corporation |
| Abbott Laboratories |
| Becton, Dickinson and Company |
| Teleflex Incorporated |
| Edwards Lifesciences Corporation |
| AngioDynamics, Inc. |
| Merit Medical Systems |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Western European Pebax resin suppliers determines both pricing tier spreads and supply chain shape across radial access catheter manufacturing. FDA 510(k) pathway friction for novel hydrophilic coating chemistries concentrates premium pricing power among manufacturers with captive regulatory infrastructure, while input cost volatility from polymer allocation constraints compresses margins for outsourced production models.
Pricing Analysis
Aftermarket service revenue from catheter reprocessing and sterilization validation drives lifetime value across vascular access portfolios. Three-tier pricing structure across premium, standard, and economy levels separates coated introducer systems with FDA-cleared hydrophilic surface treatments from conventional uncoated configurations. Cost compression in economy tiers intensifies because German outpatient clinics and US IDN-affiliated health systems consolidate procurement through integrated contracting networks. Diagnostic centers in high-volume screening programs exhibit the highest price sensitivity, while Japan's metropolitan tertiary hospitals absorb premium-coated introducer pricing without volume contraction.
Supply Chain Analysis
Tariff exposure between Western European polymer compounders and Asian-Pacific manufacturing facilities dominates supply chain risk assessment for radial access catheter producers. Pebax multilayer extrusion capabilities concentrate in Germany, Switzerland, and France, while coating chemistry operations draw from specialized Japanese and US suppliers. Single-source vulnerability in hydrophilic polymer feedstock creates allocation constraints during demand surges. Distribution runs through integrated hospital contracting networks that bundle introducer systems with hemostasis management accessories, compressing unit margins while securing volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Femoral access residual preference among established interventional cardiologists constitutes a substitution threat that radial-first protocol incumbents must actively neutralize through training infrastructure investment and clinical outcome documentation.
For Market Incumbents: Harden radial-specific device ecosystems by expanding proctored case volume programs at academic medical centers in the United States and Japan. Deepen backward integration into Pebax resin compounding operations to reduce exposure to Western European supplier allocation constraints. Capture aftermarket service revenue through direct hospital contracting for catheter reprocessing and sterilization validation.
For New Entrants and Emerging Players: Pursue peripheral vascular radial expansion as the most penetrable white space, given transradial access for lower-extremity interventions remains underdeveloped relative to coronary applications. Target ambulatory surgical centers capitalizing on same-day discharge protocol eligibility. Differentiate through biodegradable polymer formulations that address hemostasis management without manual compression.
For Investors and Strategic Acquirers: The market sits at a protocol substitution phase that favors manufacturers with integrated coating chemistry operations and regulatory infrastructure. Long-term viability across the analysis window hinges on EU MDR conformity assessment capabilities and PMDA JIS-standard material traceability compliance. The signal to watch is CMS reimbursement decisions for transradial peripheral vascular interventions as adoption expands beyond coronary applications.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Investment | Accelerates market access for hydrophilic-coated introducer systems across German and Swiss health systems. |
| Hospital System Partnership | Secures radial-first protocol standardization within IDN-affiliated cardiac catheterization laboratories. |
| Backward Integration into Polymer Compounding | Reduces supplier qualification friction under Japan's PMDA JIS-standard material traceability requirements. |
| Reimbursement Strategy Development | Positions peripheral vascular radial interventions for favorable CMS payment classification shifts. |
| Software Companion Development | Enables computational fluid dynamics modeling for virtual validation of coating performance before FDA submission. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with interventional cardiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation filings, CMS reimbursement decision records, and hospital procurement system contracts. Bottom-up segmentation modeling triangulated against top-down market sizing from cardiovascular device trade associations.
Forecast inputs included procedural volume trajectories across cardiology and vascular surgery applications, technology adoption curves for double-lumen versus single-lumen configurations, and regional regulatory pathway timelines. Segmentation dimensions spanned product architecture complexity, surface technology tier, end-user site-of-care economics, and geographic reimbursement framework clusters. CAGRs were derived from weighted average growth contributions across these dimensions, with specific adjustment for EU MDR transition impacts on hydrophilic-coated device commercialization.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, polymer commodity pricing, or interventional cardiology fellowship training pipeline capacity would shift the trajectory. Forecasts reflect documented assumptions about regulatory clearance timelines and reimbursement policy evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital Stethoscope Market
Medical Devices
Sphincterotomes Market
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Cast Removal Devices Market
Medical Devices
Guide Extension Catheter Market
Medical Devices
Global Dermatome Device Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Ankle Mobile Bearing System Market
Medical Devices
United Kingdom Aesthetic Devices Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
High Volume Dispensing Systems Market
Medical Devices
Smart Stairlift Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Ocular Trauma Devices Market