
 Global Patient-Controlled Analgesic Pumps Market | 2026-2036
Global Patient-Controlled Analgesic Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Patient-Controlled Analgesic Pumps Market Foresight
China is reshaping regional supply dynamics through expanded domestic manufacturing of electronic infusion systems and precision dosing modules. Becton, Dickinson and Company leverages its integrated portfolio of medication management technologies to sustain leadership across hospital procurement channels. Baxter International anchors its position through specialized elastomeric pump platforms designed for ambulatory and home-based pain protocols.
Patient-controlled analgesic pumps are electromechanical or elastomeric devices that deliver programmable doses of analgesic medication through intravenous, epidural, or subcutaneous routes, typically incorporating anti-siphon valves, dose-lockout intervals, and occlusion pressure sensors to prevent overdose or free-flow incidents. Wireless PCA systems are capturing disproportionate investment as hospitals prioritize integrated electronic health record connectivity and remote monitoring capabilities, while traditional PCA pumps maintain volume dominance in cost-sensitive procurement environments. Intravenous delivery mode occupies the largest installed base due to its established clinical protocols in postoperative settings, though epidural applications demonstrate stronger growth momentum in labor and delivery units.
FDA 510(k) premarket notification requirements and IEC 60601-1-2 electromagnetic compatibility standards govern device commercialization and interoperability testing across the United States and aligned markets. The EU Medical Device Regulation imposes stricter clinical evidence thresholds for software-enabled pumps, extending certification timelines for manufacturers seeking CE marking access. Stakeholders must monitor evolving cybersecurity guidance from national regulators as pump connectivity expands, since network-enabled dosing devices introduce novel liability and patient safety considerations that procurement committees increasingly weight in capital allocation decisions.
Market Dynamics
Wireless connectivity integration is restructuring capital allocation across hospital procurement committees, as electronic health record interoperability becomes a non-negotiable specification in tertiary care tenders.
Growth Catalysts
- Aging surgical demographics:Rising volumes of orthopedic and cardiovascular procedures among patients over 65 are expanding the addressable installed base for postoperative pain management devices in acute care settings.
- FDA 510(k) pathway efficiency:The premarket notification framework for infusion pumps enables faster commercialization timelines compared to premarket approval routes, accelerating product refresh cycles.
- Elastomeric pump miniaturization:Advances in balloon reservoir engineering are enabling single-use ambulatory systems that reduce infection risk and support early hospital discharge protocols.
Market Restraints
- Polymer supply concentration:Medical-grade silicone and thermoplastic elastomer production clusters in Southeast Asia, creating vulnerability to regional logistics disruptions.
- EU MDR clinical evidence thresholds:The Medical Device Regulation mandates extended post-market surveillance for software-enabled pumps, stretching certification timelines and freezing product portfolios.
- Reusable system depreciation:Capital-intensive electromechanical pumps face competitive pressure from disposable elastomeric alternatives that eliminate sterilization infrastructure requirements.
Strategic Opportunities
- Home-based pain management:Japan's aging population and reimbursement support for palliative care at home are creating demand for portable, patient-operated infusion systems outside institutional settings.
- 5G-enabled remote monitoring:Convergence of cellular connectivity and cloud-based dosing analytics allows anesthesiology teams to supervise epidural protocols from centralized command centers.
- India's PLI scheme for medical devices:Production-linked incentives for domestic manufacturing of precision dosing components are attracting component suppliers to establish local assembly operations.
Industry Challenges
- Cybersecurity engineering talent scarcity:Network-enabled pumps require embedded systems specialists capable of implementing IEC 62304 software lifecycle processes, a skill set concentrated in aerospace and automotive sectors.
- Legacy pump fleet interoperability:Hospitals face complex integration costs when connecting older RS-232 or proprietary protocol devices to modern HL7 FHIR health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Patient-Controlled Analgesic Pumps Market |
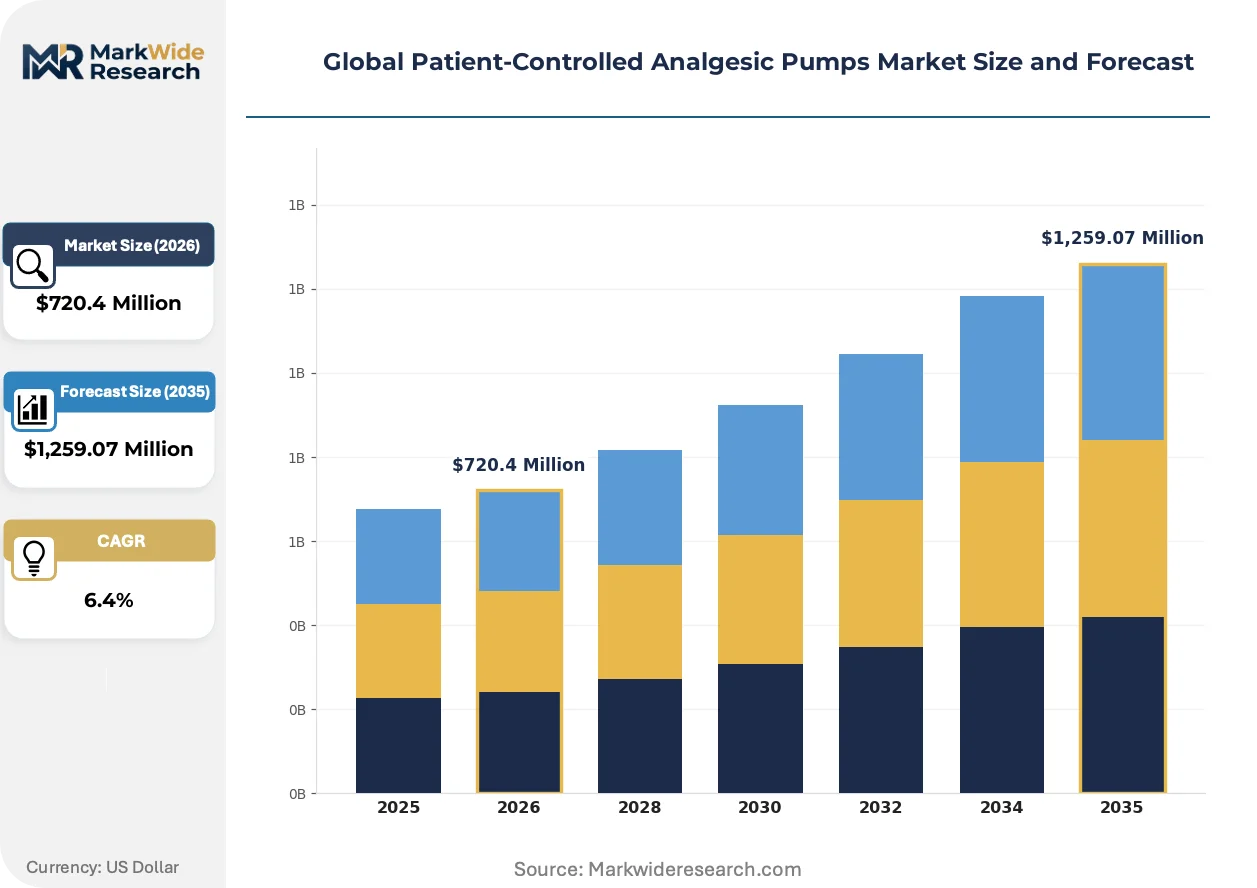
| Market Size in 2026 | $720.4 Million |
| Market Size in 2035 | $1,259.07 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional PCA Pumps, Elastomeric Pumps, Wireless PCA Systems, Ambulatory Pumps, Implantable Pumps Therapy Area: Postoperative Pain, Cancer Pain, Labor & Delivery, Chronic Pain Management, Trauma Pain End User: Hospitals, Ambulatory Surgical Centers, Home Healthcare Providers, Pain Clinics, Rehabilitation Centers Delivery Mode: Intravenous, Epidural, Subcutaneous, Intramuscular, Transdermal |
| Companies Covered | Becton, Dickinson and Company, Baxter International, B. Braun SE, ICU Medical, Inc., Fresenius SE & Co. KGaA, Arcomed AG, Micrel Medical Devices SA, Ace-medical, Changzhou Medical Bioengineering Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Patient-Controlled Analgesic Pumps Market Shifts & Advancements
Device architecture is pivoting toward disposable, connectivity-ready platforms that compress total cost of ownership while expanding remote therapeutic monitoring capabilities.
Smart elastomeric pumps with integrated flow sensors and Bluetooth Low Energy modules are migrating from niche ambulatory oncology applications into standard postoperative protocols. Academic medical centers in Germany and the United States are piloting these systems for same-day discharge orthopedic procedures. The technology is migrating from premium-tier procurement categories into mid-market hospital tenders, pressuring electromechanical incumbent pricing structures.
The EU Medical Device Regulation's software classification rules are forcing manufacturers to restructure quality management systems around cybersecurity risk management. Products with closed-loop dosing algorithms now require notified body scrutiny of machine learning training datasets. European manufacturers are responding by segregating software-enabled and mechanical-only product lines to preserve certification velocity for simpler devices.
Hospital purchasing consortia are consolidating vendor panels around integrated medication management platforms that bundle pumps with pharmacy information systems. Group purchasing organizations in the United States are awarding sole-source contracts to suppliers offering enterprise-wide interoperability guarantees. This concentration is most visible in the southeastern United States, where multi-hospital systems are retiring fragmented device fleets in favor of standardized deployments.
Global Patient-Controlled Analgesic Pumps Market Segmentation
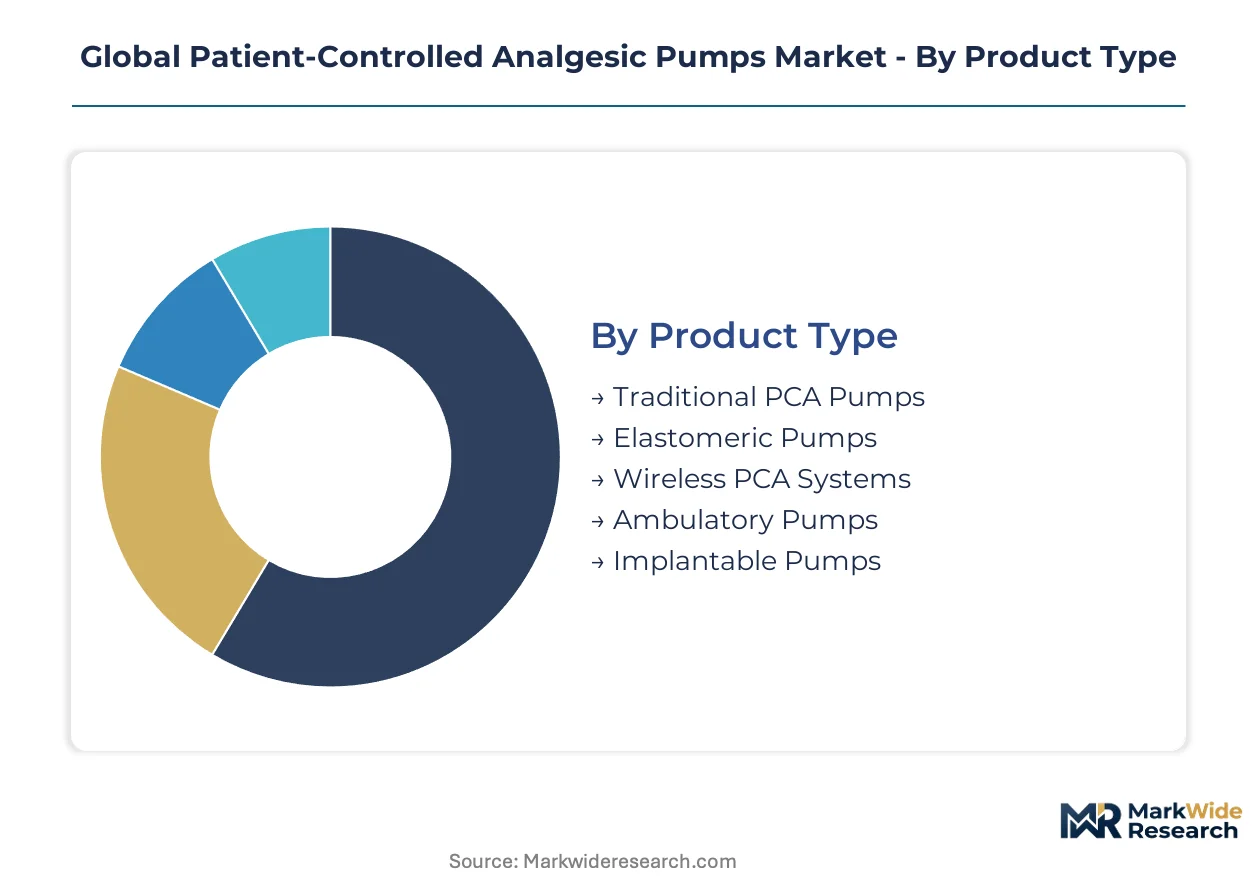
Segmentation in the patient-controlled analgesic pumps market reveals distinct procurement patterns across device architectures, clinical applications, and care settings. Understanding these divisions enables manufacturers to align R&D investment with reimbursement pathways and sterilization infrastructure requirements.
Product Type:
Mature electromechanical platforms coexist with emerging disposable and connectivity-enabled alternatives, creating tiered procurement dynamics across acute and ambulatory care.
- Traditional PCA Pumps:Electromechanical devices with programmable dose limits, anti-siphon valves, and occlusion sensors dominate hospital installed bases. Demand concentrates in United States tertiary care centers where Medicare reimbursement for acute pain management supports capital equipment procurement.
- Elastomeric Pumps:Balloon reservoir systems deliver medication through controlled elastomer contraction without electronic components. Japanese palliative care programs and German same-day discharge orthopedic protocols are expanding demand for single-use ambulatory configurations.
- Wireless PCA Systems:Bluetooth Low Energy and cellular-enabled pumps with EHR interoperability.
- Ambulatory Pumps:Portable devices designed for patient mobility outside institutional settings.
- Implantable Pumps:Surgically placed reservoirs for long-term intrathecal drug delivery.
Traditional PCA pumps retain volume leadership; wireless PCA systems hold the steepest expansion curve.
Therapy Area:
Application-driven segmentation aligns device specifications with analgesic pharmacology, procedure duration, and patient monitoring intensity.
- Postoperative Pain:The largest addressable application, encompassing orthopedic, cardiovascular, and abdominal procedures. United States surgical volume growth among patients over 65 expands demand for multimodal analgesia protocols integrating PCA with regional anesthesia.
- Cancer Pain:Requires continuous infusion capabilities and high-dose opioid compatibility. Home-based palliative care expansion in Japan and reimbursement support for outpatient oncology pain management are accelerating elastomeric pump adoption.
- Labor & Delivery:Epidural-specific devices with programmable patient-controlled bolus functionality.
- Chronic Pain Management:Long-term infusion protocols for non-malignant pain syndromes.
- Trauma Pain:Acute high-intensity analgesia for emergency and critical care settings.
Postoperative pain commands the largest installed base; labor and delivery applications are climbing the fastest.
End User:
Customer-type segmentation tracks the migration of pain management from institutional settings toward decentralized care models.
- Hospitals:Inpatient surgical units and acute pain services constitute the dominant procurement channel. Group purchasing organizations in the southeastern United States are consolidating vendor panels around enterprise-wide medication management platforms.
- Ambulatory Surgical Centers:Same-day procedure volumes are expanding demand for disposable elastomeric systems that eliminate sterilization logistics. German outpatient orthopedic networks are piloting Bluetooth-enabled pumps for remote monitoring of discharged patients.
- Home Healthcare Providers:Durable medical equipment suppliers managing long-term infusion therapy.
- Pain Clinics:Specialized interventional practices with advanced neuraxial and peripheral nerve catheter protocols.
- Rehabilitation Centers:Post-acute facilities managing pain during functional recovery programs.
Hospitals dominate capital procurement volumes; ambulatory surgical centers are gaining share fastest.
Delivery Mode:
Route-of-administration segmentation reflects pharmacokinetic requirements, infection risk profiles, and catheter placement expertise availability.
- Intravenous:Peripheral venous access enables rapid systemic analgesia with standardized nursing protocols. United States hospital formularies and pharmacy information system integration prioritize IV PCA for postoperative protocols.
- Epidural:Neuraxial delivery provides superior analgesia with reduced systemic opioid exposure. Labor and delivery units in academic medical centers are driving demand for programmable patient-controlled epidural analgesia systems.
- Subcutaneous:Alternative vascular access for patients with difficult venous anatomy.
- Intramuscular:Limited contemporary use due to unpredictable absorption and injection pain.
- Transdermal:Passive diffusion systems without active pump mechanisms.
Intravenous delivery retains procedural dominance; epidural applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor device commercialization timelines in the United States, while divergent regulatory frameworks across Germany, Japan, China, and India shape distinct procurement and certification dynamics.
United States
Medicare reimbursement policies for acute pain management drive capital equipment procurement in tertiary care centers. The FDA maintains the 510(k) premarket notification framework for infusion pumps, enabling faster product refresh cycles than premarket approval routes. Manufacturing clusters concentrate in Massachusetts and Minnesota, where precision dosing component suppliers align with hospital group purchasing organization consolidation in the Southeast.
Germany
Same-day discharge orthopedic protocols expand demand for Bluetooth-enabled elastomeric pumps with remote monitoring capabilities. The EU Medical Device Regulation imposes stricter clinical evidence thresholds for software-enabled devices, extending CE marking timelines for manufacturers. Academic medical centers in Bavaria and Baden-Württemberg pilot smart pump systems for postoperative pain protocols, pressuring electromechanical incumbent pricing.
Japan
Aging demographics and reimbursement support for palliative care at home create demand for portable patient-operated infusion systems. METI oversees medical device manufacturing standards while PMDA regulates market authorization for precision dosing technologies. Industrial activity clusters in the Kanto region around Tokyo, where domestic manufacturers develop miniaturized balloon reservoir systems for ambulatory oncology applications.
China
Expanded domestic manufacturing of electronic infusion systems and precision dosing modules reshapes regional supply dynamics. NMPA governs medical device registration under evolving cybersecurity guidance for network-enabled pumps. Production concentrates in Changzhou and the Yangtze River Delta, where component suppliers establish local assembly operations to serve hospital procurement channels.
India
Production-linked incentives for domestic manufacturing of precision dosing components attract suppliers to establish local assembly operations. CDSCO regulates medical device import and manufacturing licenses under strengthened quality management system requirements. Medical device industrial corridors in Gujarat and Karnataka host emerging pump assembly facilities targeting cost-sensitive procurement environments across South Asia.
Global Patient-Controlled Analgesic Pumps Market Competitive Landscape
Capability concentration sits with integrated medication management platforms; scale advantage sits with diversified medical technology conglomerates. The vendor base organizes around three archetypes: electromechanical system incumbents with established hospital installed bases, elastomeric pump specialists targeting ambulatory and home care migration, and connectivity-enabled challengers prioritizing EHR interoperability. Dominant competitive moves include portfolio diversification into disposable platforms and strategic partnerships with pharmacy information system vendors to secure enterprise-wide contracts.
Among diversified medical technology conglomerates, Becton, Dickinson and Company and Baxter International occupy positions representing contrasting strategic anchors—one leveraging integrated medication management technologies across hospital procurement channels, the other anchoring through specialized elastomeric platforms designed for ambulatory protocols. B. Braun SE exemplifies the European industrial archetype with manufacturing depth in precision dosing components. These three represent the tiered structure where scale, specialization, and geographic origin intersect to shape competitive positioning.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Baxter International |
| B. Braun SE |
| ICU Medical, Inc. |
| Fresenius SE & Co. KGaA |
| Arcomed AG |
| Micrel Medical Devices SA |
| Ace-medical |
| Changzhou Medical Bioengineering Co., Ltd. |
| Others |
Supply & Pricing Matrix
Polymer supply concentration in Southeast Asia creates asymmetric cost exposure that compresses margin spreads between premium electromechanical systems and disposable elastomeric alternatives while forcing procurement committees to dual-source balloon reservoir components.
Pricing Analysis
United States hospital tenders command premium positioning against German and Japanese procurement channels, with three-tier pricing structure across premium, standard, and economy levels driven by FDA 510(k) certification tier and after-sales service bundling. Cost compression in mid-market electromechanical segments intensifies because of elastomeric pump displacement in ambulatory surgical centers. Price sensitivity concentrates among ASC procurement committees optimizing for total cost of ownership, while tertiary care systems in the United States prioritize interoperability guarantees over unit economics.
Supply Chain Analysis
Medical-grade silicone and thermoplastic elastomer feedstock draws from Thailand, Malaysia, and Vietnam production clusters, with precision dosing module assembly anchored in Changzhou and the Yangtze River Delta. Balloon reservoir fabrication hinges on specialized polymer compounding capabilities concentrated among Japanese and German specialty chemical suppliers. Single-source vulnerability in medical-grade silicone creates tariff exposure risk for manufacturers lacking backward integration into polymer synthesis. Distribution runs through hospital group purchasing organizations in the southeastern United States and regional medical device distributors across Bavaria and Baden-Württemberg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a surgical volume recovery cycle, with orthopedic procedure expansion among patients over 65 providing demand floor support.
For Market Incumbents: Pre-empt elastomeric pump specialists by acquiring disposable platform capabilities or licensing Bluetooth Low Energy connectivity modules from established semiconductor vendors. Secure hospital system partnerships in the southeastern United States through enterprise-wide medication management platform bundling. Invest in IEC 62304 software lifecycle certification to defend against connectivity-enabled challengers targeting EU MDR compliance gaps. For New Entrants and Emerging Players: India's medical device industrial corridors in Gujarat and Karnataka offer underpenetrated manufacturing partnerships for cost-sensitive South Asian procurement channels. Target ambulatory surgical centers in Germany piloting same-day discharge orthopedic protocols with smart elastomeric pumps featuring integrated flow sensors. Pursue white-label arrangements with Japanese domestic manufacturers seeking miniaturized balloon reservoir engineering capabilities. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated medication management platforms over standalone pump hardware. Five-to-ten year viability rests on EHR interoperability depth and pharmacy information system integration density. Acquisition profiles should prioritize elastomeric pump specialists with FDA 510(k) clearances and established GPO contracts. Watch for CDSCO manufacturing license acceleration in India as inflection signal for regional supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Premarket notification efficiency enables faster product refresh cycles against PMA-route competitors. |
| CE Marking Pathway Restructuring | EU MDR software classification compliance preserves certification velocity for European market access. |
| Hospital System Partnership | GPO consolidation in the southeastern United States awards sole-source contracts to interoperability-guaranteed vendors. |
| Software Companion Development | Cloud-based dosing analytics integration attracts 5G-enabled remote monitoring investment from anesthesiology departments. |
| Reimbursement Strategy Alignment | Medicare acute pain management policy support drives capital equipment procurement in tertiary care centers. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and anesthesiology department heads and secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body guidance documents anchors the qualitative findings. Bottom-up installed base modeling triangulates against top-down surgical volume projections across orthopedic, cardiovascular, and labor and delivery procedure categories.
Calibration against historical adoption curves for electromechanical and elastomeric pump platforms shapes the analytical framework across the analysis window. Segmentation dimensions include product architecture, delivery mode, therapy area, and end-user setting, with regional regulatory cluster effects modeled separately. CAGRs derive from procedure volume elasticity to device penetration rates and replacement cycle dynamics for reusable versus disposable systems. Forecast inputs incorporate polymer supply lead times and cybersecurity guidance evolution from national regulators.
The forecast holds incumbent behavior within observed patterns; aggressive moves by connectivity-enabled challengers or rapid elastomeric pump miniaturization would shift outcomes. Cross-checking against surgical volume data from national health registries and GPO contract award announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
Australia Minimally Invasive Surgery Devices Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Global Sphygmomanometer Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Nurse Call Systems Market
Medical Devices
Sphincterotomes Market
Medical Devices
Supraglottic Device Market
Medical Devices
Robotic Catheterization Systems Market
Medical Devices
Water Bath Vaporizer Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Radiotherapy Devices Market
Medical Devices
South America Ultrasound Devices Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market