
 Drug Delivery Solutions Market | 2026-2036
Drug Delivery Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Delivery Solutions Market Foresight
Modular drug-device combinations is broadening buyer choice across chronic therapy categories. Pfizer Inc. leverages its manufacturing scale to supply integrated delivery systems for biologics portfolios. Novartis AG anchors its oncology franchise with patient-administered platforms that reduce infusion center burden. Becton Dickinson and Company dominates the prefillable syringe segment through backward integration into glass and polymer primary packaging.
Drug delivery solutions encompass engineered systems, devices, and formulations that transport pharmaceutical active ingredients to targeted physiological sites at controlled release rates, utilizing mechanisms ranging from passive diffusion through polymeric matrices to active pump-driven infusion with programmable dosing algorithms. These systems serve the primary commercial purpose of improving therapeutic efficacy, reducing dosing frequency, and enabling administration outside clinical settings. Injectable platforms, particularly subcutaneous formulations, occupy the largest value pool as biologics manufacturers seek alternatives to intravenous infusion. Transdermal patches represent the fastest-expanding configuration for hormone and pain therapies where steady-state plasma levels improve compliance. Oral tablets retain volume leadership in emerging markets where cost sensitivity and cold-chain limitations restrict biologic penetration.
The FDA regulates combination products under 21 CFR 3.2, requiring sponsors to demonstrate device constituent reliability alongside drug efficacy, while the EMA's MDR alignment demands enhanced clinical evidence for active implantable delivery systems. Health Canada and Japan's PMDA maintain distinct quality system requirements that fragment approval pathways for multinational sponsors. Stakeholders must monitor evolving post-market surveillance obligations as regulators tighten traceability for patient-administered devices.
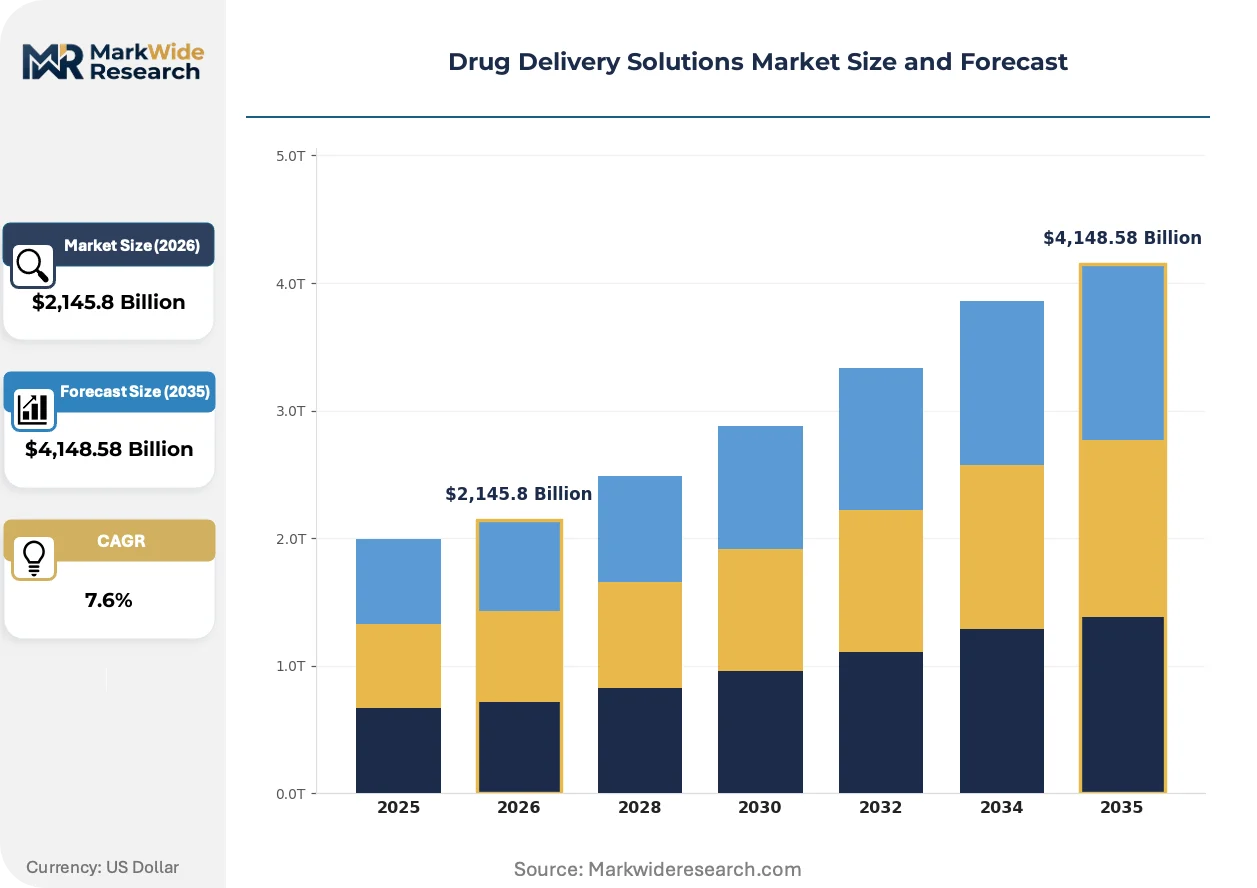
Market Dynamics
Biopharmaceutical manufacturers are consolidating supply chains around integrated device-drug platforms, forcing component suppliers to demonstrate quality system alignment under FDA 21 CFR Part 4 and EMA MDR frameworks simultaneously.
Growth Catalysts
- Chronic disease prevalence:Diabetes and autoimmune condition patient volumes in the United States, Germany, and Japan are expanding addressable demand for self-administered injectable systems.
- EMA MDR alignment:Enhanced clinical evidence requirements for active implantable delivery systems are accelerating sponsor investment in robust device constituent reliability testing.
- Subcutaneous formulation shift:Monoclonal antibody developers are engineering higher-concentration biologics compatible with patient-administered platforms, reducing infusion center dependency.
Market Restraints
- Glass primary packaging concentration:Borosilicate tubing supply is concentrated among three European and Japanese manufacturers, creating input vulnerability for prefillable syringe producers.
- FDA combination product complexity:Determining primary mode of action delays approval timelines when device and drug constituents require separate center consultations.
- Intravenous infusion substitution:Hospital-based infusion centers retain preference for established IV protocols in acute care settings, limiting rapid platform conversion.
Strategic Opportunities
- Brazil and Mexico underpenetration:Latin American chronic disease management infrastructure expansion creates demand for cost-optimized autoinjector platforms with simplified cold-chain requirements.
- Connected device convergence:Integration of Bluetooth-enabled dose tracking with electronic health record systems enables adherence monitoring reimbursement codes.
- Health Canada streamlined pathway:Updated guidance on quality system integration for combination products reduces redundant documentation for sponsors with existing FDA approvals.
Industry Challenges
- Human factors engineering talent scarcity:Specialized usability testing expertise for patient-administered devices commands premium compensation, constraining sponsor capacity.
- ISO 11608-5 certification timelines:Needle-based injection system performance testing protocols require 18-24 month validation cycles, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Delivery Solutions Market |
| Market Size in 2026 | $2,145.8 Billion |
| Market Size in 2035 | $4,148.58 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Transdermal Patches, Inhalers, Oral Tablets Delivery Mode: Intravenous, Subcutaneous, Oral, Topical Therapy Area: Oncology, Cardiovascular, Diabetes, Neurology End User: Hospitals, Clinics, Home Care, Pharmacies |
| Companies Covered | Johnson & Johnson Services, Inc., Pfizer Inc., Novartis AG, F. Hoffmann-La Roche Ltd., Becton Dickinson and Company, AstraZeneca PLC, Baxter International Inc., West Pharmaceutical Services Inc., Gerresheimer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Delivery Solutions Market Shifts & Advancements
Programmable dosing algorithms and connected health integration are compressing the gap between clinical-grade precision and home-based administration, reshaping how biologics manufacturers design commercialization pathways.
Closed-loop wearable infusion systems are unifying continuous glucose monitoring data with automated insulin delivery, eliminating manual dose calculation. Pediatric and geriatric diabetes populations in Scandinavia and the Netherlands are adopting these platforms at twice the rate of traditional pump therapy. This convergence is unifying hardware, software, and pharmaceutical constituents under single-sponsor liability frameworks that reshape partnership structures between device OEMs and drug developers.
Japan's PMDA revised its guidance on software as a medical device in combination products, requiring cybersecurity validation for wireless-enabled delivery systems. Domestic sponsors must now submit threat modeling documentation alongside traditional biocompatibility studies. Active implantable delivery systems for Parkinson's and pain management are absorbing the greatest compliance burden, with several development programs extending timelines to address post-market surveillance requirements.
Hospital procurement committees are unbundling device acquisition from pharmaceutical supply contracts, forcing delivery system manufacturers to demonstrate independent value through total cost-of-administration metrics. Integrated delivery platforms for rheumatoid arthritis and multiple sclerosis therapies face the most intense scrutiny in German and French tender processes. This pattern is most visible in European markets where health technology assessment bodies weight patient-reported outcome measures alongside clinical efficacy endpoints.
Drug Delivery Solutions Market Segmentation
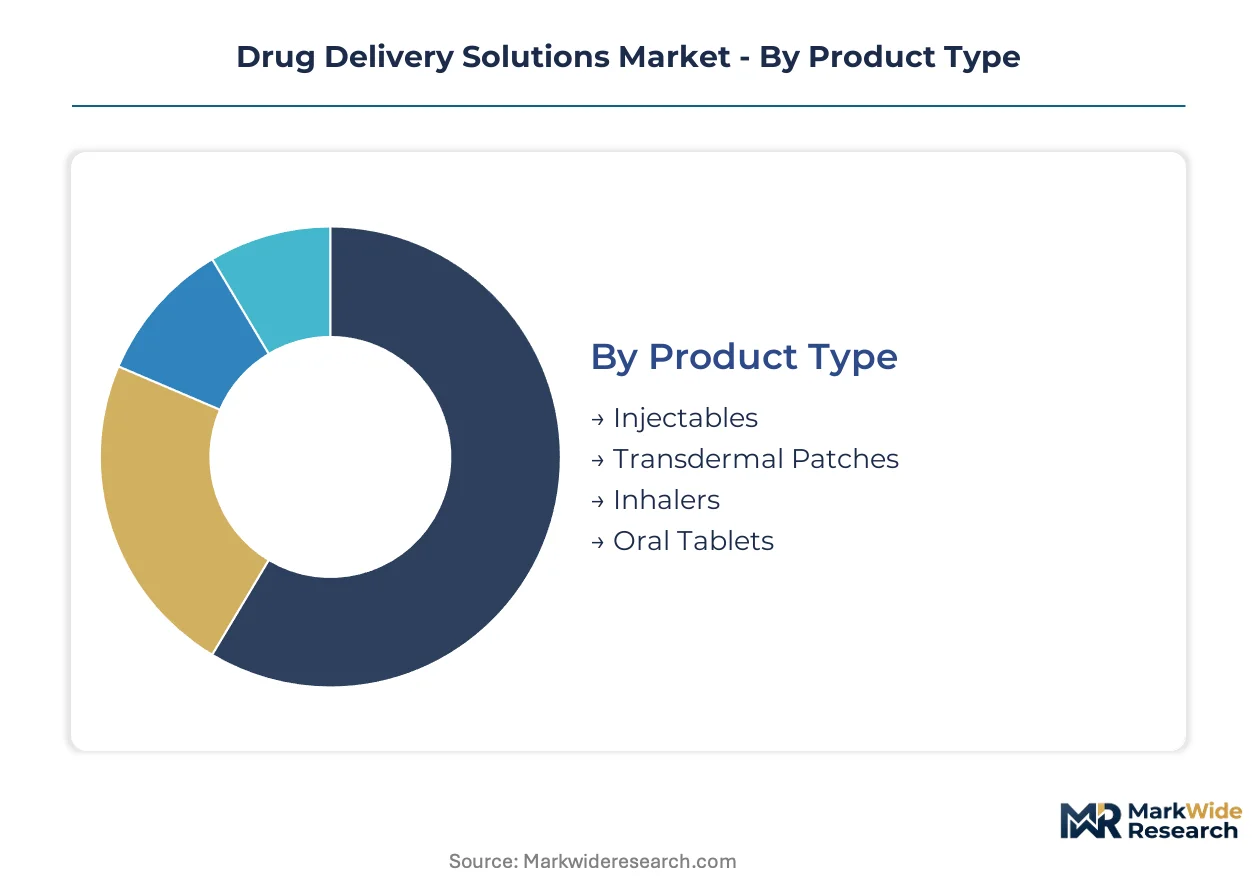
Drug delivery solutions fragment across four intersecting dimensions that determine reimbursement pathways, regulatory complexity, and manufacturing scale requirements. Each segmentation axis reveals distinct margin structures and partnership dynamics between pharmaceutical sponsors and device manufacturers.
Product Type:
Integration depth varies sharply — standalone devices command premium positioning while embedded systems sacrifice margin for volume lock-in.
- Injectables:Prefilled syringes and autoinjector platforms incorporate drug-contact materials, needle shielding, and dose accuracy mechanisms in single-use assemblies. Demand clusters in United States diabetes and autoimmune therapy markets where hospital avoidance drives self-administration preference. FDA 21 CFR Part 4 compliance costs favor sponsors with captive device manufacturing.
- Transdermal Patches:Matrix or reservoir designs diffuse active ingredients through stratum corneum via pressure-sensitive adhesive layers. German and Japanese pain management protocols increasingly specify patches for chronic opioid-sparing regimens. Steady-state plasma concentration improves adherence metrics that HTA bodies weight in reimbursement decisions.
- Inhalers:Pressurized metered-dose or dry powder devices requiring coordination between actuator mechanics and formulation particle size.
- Oral Tablets:Conventional solid dosage forms dominate emerging market volume where cold-chain limitations exclude biologic alternatives.
Volume placements concentrate in Oral Tablets; the faster expansion belongs to Injectables.
Delivery Mode:
Route selection determines site-of-care economics and patient training burden.
- Intravenous:Infusion center administration retains preference for acute oncology and immunoglobulin therapies requiring high-volume delivery. Hospital procurement committees in France and Germany unbundle device costs from pharmaceutical contracts, forcing standalone value demonstration.
- Subcutaneous:Patient-administered platforms reduce facility dependency for monoclonal antibody maintenance dosing. United States rheumatoid arthritis and multiple sclerosis populations drive fastest uptake as prior authorization frameworks favor home administration cost offsets.
- Oral:Gastrointestinal absorption limits bioavailability for large-molecule biologics, constraining application to small-molecule portfolios.
- Topical:Localized dermal or mucosal application minimizes systemic exposure for dermatology and localized pain indications.
Revenue concentration sits with Intravenous administration; Subcutaneous platforms are gaining share fastest through chronic therapy conversion.
Therapy Area:
Disease prevalence and reimbursement intensity segment addressable value pools.
- Oncology:Injectable platforms dominate immuno-oncology and antibody-drug conjugate delivery, with subcutaneous formulation shifts reducing infusion chair time. PMDA Japan tightened software validation requirements for wireless-enabled delivery systems in this category.
- Diabetes:Closed-loop wearable infusion systems unify continuous glucose monitoring with automated insulin dosing. Scandinavian and Netherlands pediatric populations adopt at twice traditional pump therapy rates.
- Cardiovascular:Transdermal nitroglycerin and oral anticoagulant delivery retain volume leadership.
- Neurology:Active implantable systems for Parkinson's disease absorb greatest regulatory compliance burden under EMA MDR alignment.
Investment intensity peaks in Oncology; Diabetes demonstrates the steepest expansion trajectory through connected device convergence.
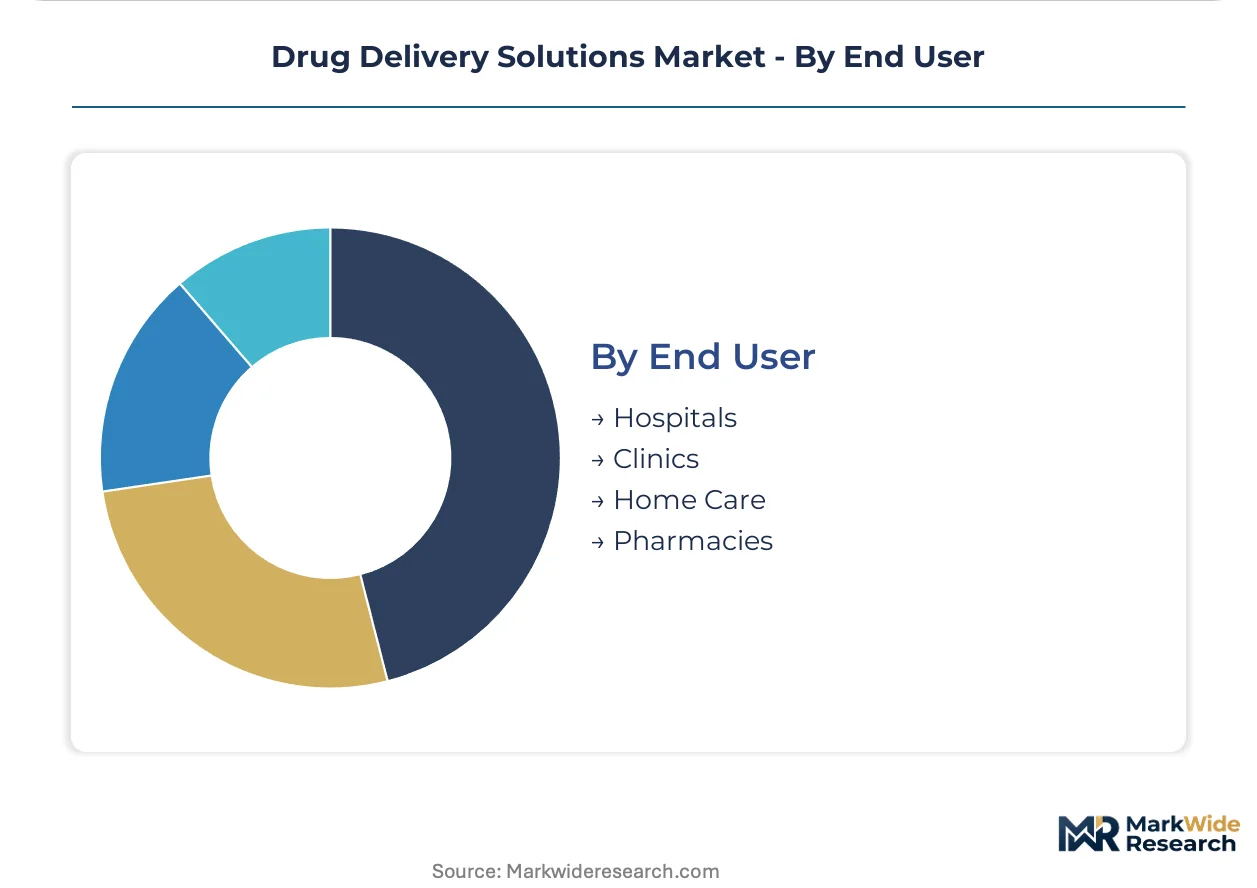
End User:
Procurement authority and reimbursement coding determine pricing power.
- Home Care:Patient-administered platforms require human factors engineering validation for diverse literacy and dexterity profiles. ISO 11608-5 certification timelines of 18-24 months compress launch windows for sponsors targeting this channel.
- Hospitals:Integrated device-drug contracts favor suppliers with quality system alignment across FDA and EMA frameworks simultaneously.
- Clinics:Outpatient infusion centers balance throughput efficiency against patient preference for reduced visit frequency.
- Pharmacies:Retail distribution enables direct patient access for self-administered oral and transdermal products.
Margin capture concentrates in Home Care; Hospital channel expansion is accelerating through value-based contracting pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German precision glass manufacturing and Japanese polymer processing, while consumption tilts toward United States chronic disease management and European hospital procurement networks.
United States
Diabetes and autoimmune patient volumes drive self-administered injectable demand across rheumatoid arthritis and multiple sclerosis therapy categories. FDA 21 CFR Part 4 compliance requirements favor sponsors with captive device manufacturing capabilities. Greater Boston and San Diego biotech clusters host development programs for closed-loop wearable infusion systems.
Germany
Hospital procurement committees unbundle device costs from pharmaceutical contracts, forcing standalone value demonstration through total cost-of-administration metrics. EMA MDR alignment demands enhanced clinical evidence for active implantable delivery systems. Baden-Württemberg precision glass manufacturers supply borosilicate tubing for prefillable syringe producers.
Japan
PMDA revised guidance on software as a medical device in combination products, requiring cybersecurity validation for wireless-enabled delivery systems. Pediatric and geriatric diabetes populations adopt closed-loop wearable infusion systems at twice traditional pump therapy rates. Tokyo-Osaka pharmaceutical corridors anchor domestic biologics manufacturing.
Brazil
Chronic disease management infrastructure expansion creates demand for cost-optimized autoinjector platforms with simplified cold-chain requirements. ANVISA maintains distinct quality system requirements that fragment approval pathways for multinational sponsors. São Paulo state hosts regional distribution hubs serving Latin American markets.
Canada
Health Canada streamlined guidance on quality system integration for combination products, reducing redundant documentation for sponsors with existing FDA approvals. Prior authorization frameworks favor home administration cost offsets for subcutaneous biologics. Ontario and Quebec provinces concentrate medical device regulatory consulting expertise.
Drug Delivery Solutions Market Competitive Landscape
The competitive structure tilts toward integrated device-drug platform consolidation. Biopharmaceutical manufacturers and component suppliers occupy distinct tiers with asymmetric bargaining power. Three archetypes dominate: captive manufacturing divisions of large-cap pharma, independent device specialists with quality system alignment, and materials suppliers with backward integration into primary packaging. Capacity expansion and strategic partnerships constitute the dominant competitive moves as sponsors seek to compress ISO 11608-5 certification timelines.
Among United States-based healthcare conglomerates, Johnson & Johnson Services, Inc. and Pfizer Inc. exemplify the integrated platform archetype through manufacturing scale advantages. Novartis AG represents the European pharmaceutical model with patient-administered oncology platforms. Becton Dickinson and Company occupies a position within the independent device specialist tier, while Gerresheimer AG anchors German materials supply with glass and polymer primary packaging capabilities.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Pfizer Inc. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| Becton Dickinson and Company |
| AstraZeneca PLC |
| Baxter International Inc. |
| West Pharmaceutical Services Inc. |
| Gerresheimer AG |
| Others |
Supply & Pricing Matrix
Borosilicate glass tubing costs flow from Baden-Württemberg and Japanese manufacturers through prefillable syringe converters, stratifying final platform pricing across premium ISO 11608-5 certified systems and economy-grade alternatives for Latin American markets.
Pricing Analysis
Margin tightening in economy-tier autoinjectors traces to ANVISA-registered Brazilian distributors sourcing cost-optimized polymer alternatives to European glass. Three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR Part 4 compliant integrated platforms from standalone devices and unbundled component supply. Cost-down pressure on standard-tier prefillable syringes accelerates because hospital procurement committees in Germany and France weight total cost-of-administration metrics above device acquisition price. Emerging market buyers exhibit highest price sensitivity; United States biopharmaceutical sponsors with captive manufacturing show lowest.
Supply Chain Analysis
Regional distribution centers in São Paulo state and Toronto-Osawa corridors manage hub-and-spoke patterns for Latin American and Canadian chronic therapy markets. Manufacturing concentrates in Germany, Japan, and the United States. Borosilicate tubing, polymer resins, and needle shielding components draw from concentrated European and Asian suppliers. Single-source vulnerability in glass primary packaging creates structural exposure. Distribution runs through pharmaceutical wholesalers and direct-to-hospital contracts for integrated device-drug platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
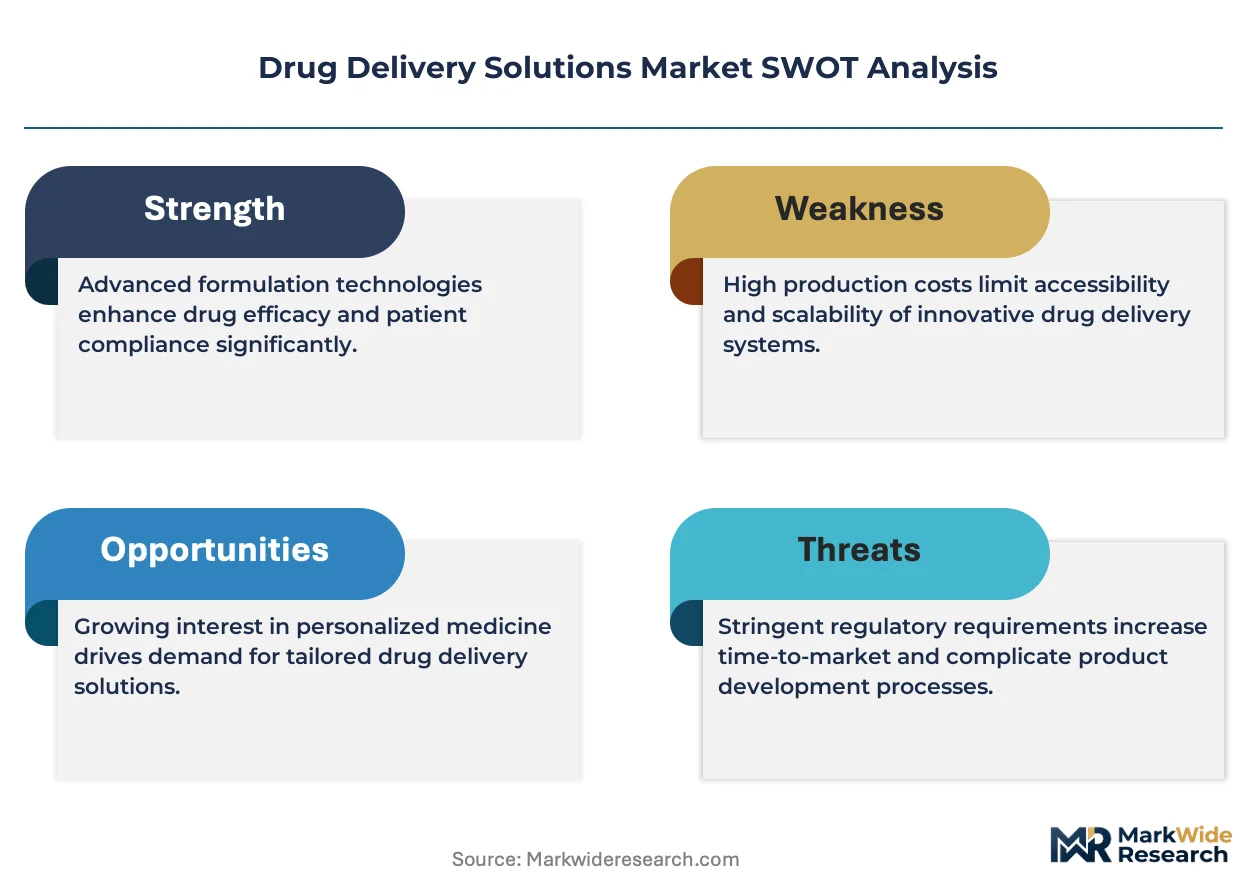
This market functions as a vertical-integration race where control over ISO 11608-5 certification timelines and borosilicate tubing supply determines competitive position.
For Market Incumbents: Anchor quality system alignment across FDA and EMA frameworks simultaneously to preempt regulatory fragmentation costs. Expand captive manufacturing into Baden-Württemberg glass supply corridors. Consolidate around human factors engineering talent pools before scarcity premiums escalate further. For New Entrants and Emerging Players: Capture Brazil and Mexico chronic disease infrastructure buildout with cold-chain-simplified autoinjector platforms. Target pharmacy-distributed self-administration segments where prior authorization frameworks favor home administration cost offsets. Lead with connected device convergence featuring Bluetooth-enabled dose tracking. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent device specialists with EMA MDR alignment and existing FDA 510(k) clearance portfolios in Germany. Long-term viability hinges on software-as-medical-device validation capabilities for wireless-enabled delivery systems. Watch PMDA cybersecurity guidance enforcement as inflection signal for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11608-5 Certification Investment | Compresses 18-24 month validation cycles for prefillable syringe launches. |
| Backward Integration into Borosilicate Tubing | Secures supply against three-manufacturer concentration in Europe and Japan. |
| Software-as-Medical-Device Validation | Addresses PMDA cybersecurity requirements for wireless-enabled delivery systems. |
| Hospital System Partnership | Demonstrates total cost-of-administration value under German unbundled procurement. |
| Reimbursement Strategy | Captures adherence monitoring codes for connected device convergence in United States. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs. Primary interviews with biopharmaceutical development executives, regulatory affairs leads, hospital procurement managers, and GPO contracts managers validated demand assumptions. FDA 21 CFR Part 4 submissions, EMA MDR technical documentation, Health Canada quality system guidance, and PMDA software validation notices supplied regulatory trajectory inputs. Bottom-up platform shipment analysis and top-down therapy area spend estimates underwent triangulation.
Segmentation granularity modeled product type, delivery mode, therapy area, and end user at country level across the analysis window. CAGRs derived from patient population growth, chronic disease prevalence trajectories, and self-administration conversion rates. Subcutaneous formulation shift assumptions and connected device adoption curves informed injectables and diabetes segment projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory harmonization delays and borosilicate supply disruptions. Forecasts reflect documented assumptions on patient preference shifts and reimbursement code evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Rapid Infuser Market
Medical Devices
Disposable Medical Devices Sensors Market
Medical Devices
Transplant Monitoring Kits Market
Medical Devices
Appendage Management Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
China Minimally Invasive Surgery Devices Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Tracheostomy Tubes Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
Autotransfusion Devices Market
Medical Devices
Digital Reading Micropipettes Market
Medical Devices
Ehealth Devices Market
Medical Devices
Germany Aesthetic Devices Market