
 North America Ablation Devices Market | 2026-2036
North America Ablation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ablation Devices Market Analytics
Radiofrequency electrode materials are expanding into advanced irrigated-tip configurations that reduce char formation and improve lesion durability. Medtronic leverages vertical integration across catheter manufacturing and energy-delivery systems to control cost structures. Boston Scientific Corporation anchors its position through R&D intensity in pulsed-field ablation platforms. Abbott differentiates via specialized cryoablation balloon technologies for atrial fibrillation treatment.
Ablation devices deliver thermal, electrical, or cryogenic energy to destroy pathological tissue through percutaneous or surgical access, typically operating at frequencies between 460 and 500 kHz for radiofrequency systems with tip temperatures monitored at 50 to 80 degrees Celsius to achieve transmural necrosis while preserving surrounding structures. Radiofrequency systems occupy the largest installed base across North American electrophysiology labs due to established reimbursement and physician training pathways. Minimally invasive technology is reshaping procedural economics as same-day discharge protocols reduce hospital bed utilization and shift case volumes toward ambulatory surgical centers.
FDA 510(k) premarket notification requirements and CMS national coverage determinations govern market access for novel ablation technologies in the United States, while Health Canada's Medical Devices Directorate sets parallel standards for Canadian commercialization. The IRA's Medicare price negotiation provisions create uncertainty for hospital capital equipment purchasing cycles. Stakeholders must monitor evolving FDA guidance on pulse-field ablation safety endpoints and state-level certificate-of-need regulations affecting ambulatory expansion.
Market Dynamics
Pulsed-field ablation is compressing physician training curves and enabling same-day discharge protocols across metropolitan hospital systems in Texas, California, and Ontario.
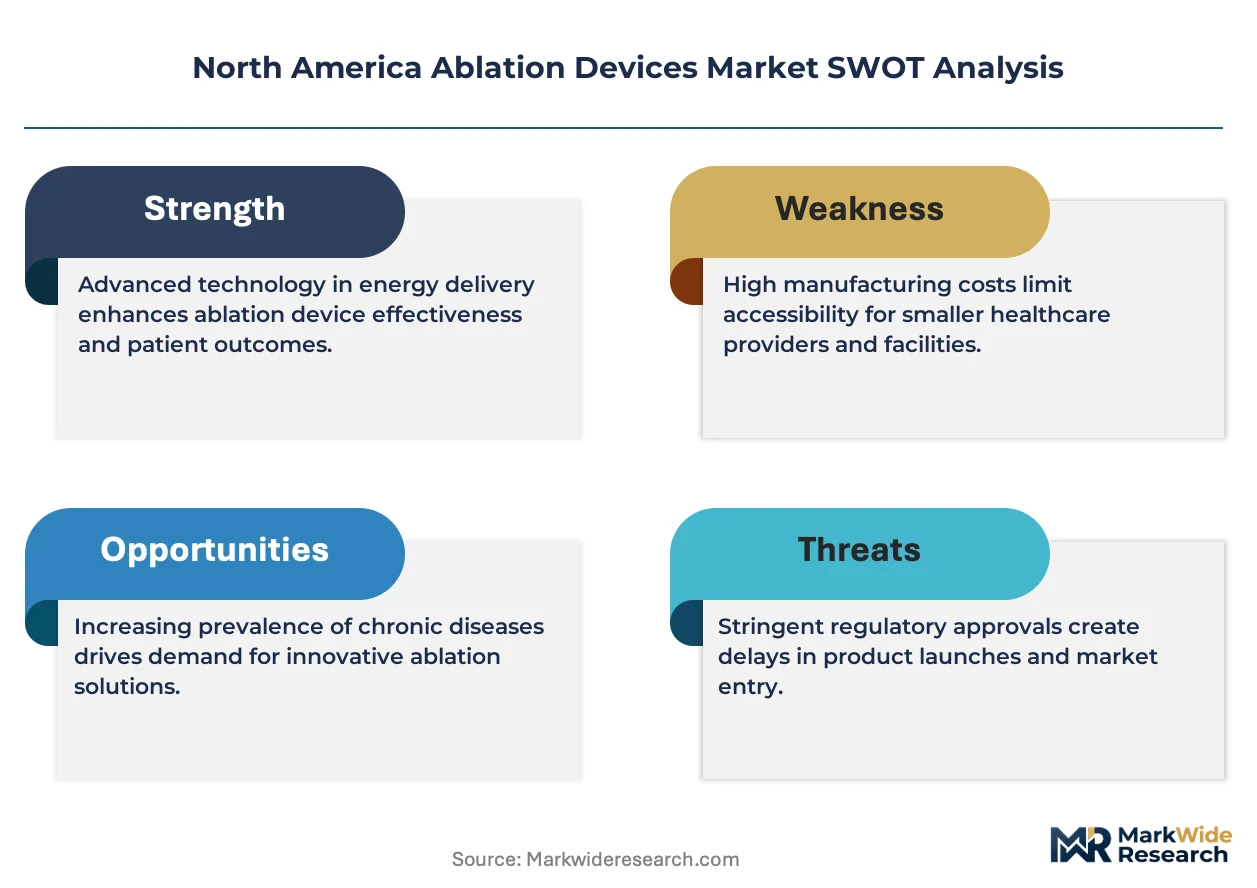
Growth Catalysts
- FDA 510(k) Pathway Acceleration:Streamlined premarket notification for minimally invasive cardiac procedures reduces time-to-commercialization for novel catheter designs. Device manufacturers leverage this to secure rapid CMS reimbursement alignment.
- Ambulatory Surgical Center Expansion:Certificate-of-need regulatory reforms in select US states enable outpatient electrophysiology labs to capture case volumes previously restricted to inpatient settings.
- Cryoablation Balloon Technology:Single-shot pulmonary vein isolation procedures reduce fluoroscopy exposure and operator fatigue, driving adoption among high-volume cardiac centers.
Market Restraints
- IRA Medicare Price Negotiation:Uncertainty surrounding capital equipment depreciation schedules delays hospital purchasing cycles for multi-catheter ablation platforms.
- Platinum-Iridium Electrode Supply Concentration:Dependence on specialized metallurgical suppliers creates input cost volatility for radiofrequency catheter manufacturers.
- Thermal Lesion Depth Variability:Anatomical constraints in obese patient populations limit transmural efficacy rates for standard radiofrequency configurations.
Strategic Opportunities
- Canadian Provincial Expansion:Health Canada's Medical Devices Directorate approval pathways enable faster Ontario and Quebec market entry for next-generation irrigated-tip systems.
- Hybrid Operating Room Integration:Convergence of robotic surgical platforms with real-time electroanatomic mapping creates premium service line differentiation for academic medical centers.
- Remote Monitoring Reimbursement Codes:New CMS billing categories for post-ablation arrhythmia surveillance incentivize integrated device-clinic partnerships.
Industry Challenges
- Electrophysiology Fellowship Pipeline:Insufficient accredited training positions constrain specialist supply needed to operate advanced mapping and ablation systems at scale.
- Legacy EMR Integration:Proprietary data formats from competing mapping platforms impede seamless workflow incorporation into existing hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ablation Devices Market |
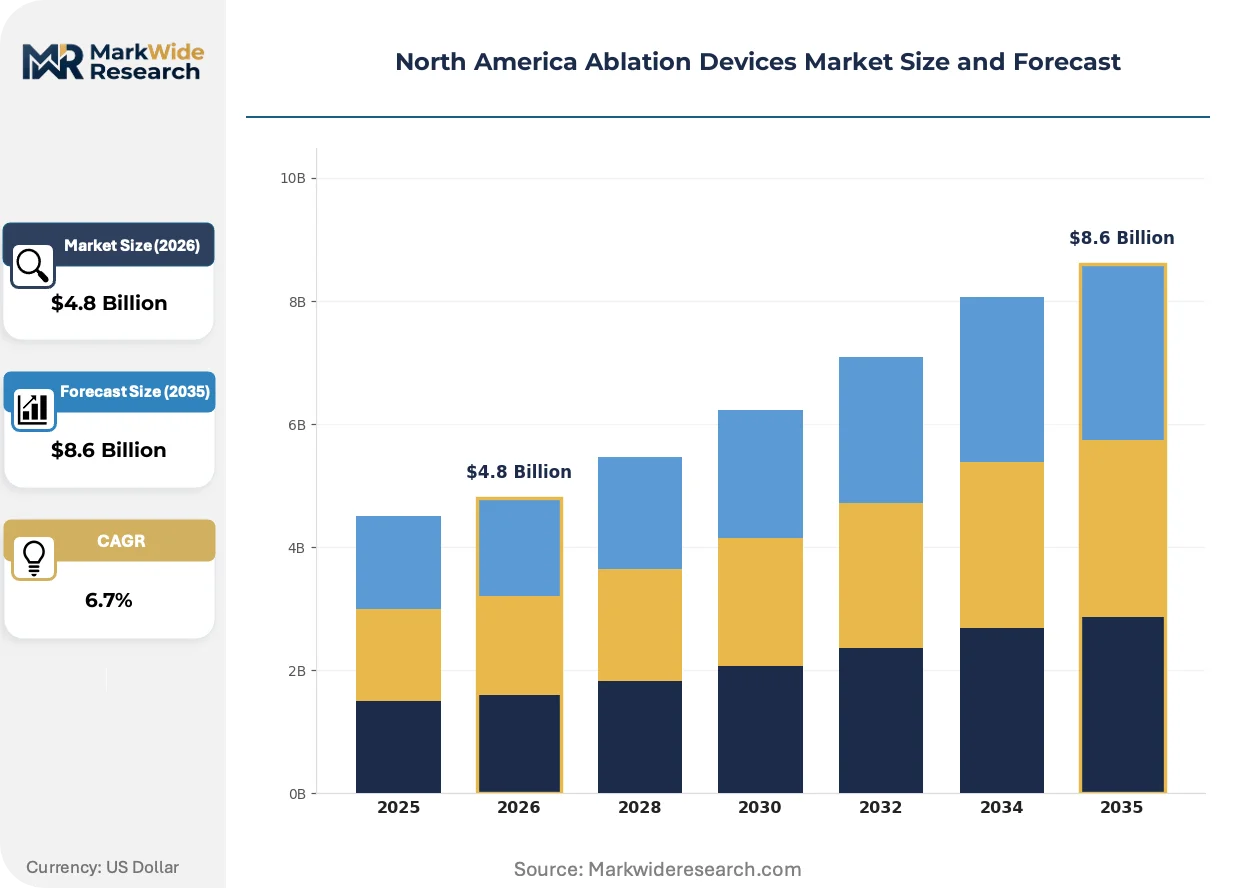
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency, Laser, Microwave, Cryoablation End User: Hospitals, Ambulatory Surgical Centers, Outpatient Clinics, Research Institutions Application: Cardiac, Oncology, Neurology, Pain Management Technology: Open Surgery, Minimally Invasive, Robotic-Assisted, Hybrid Procedures |
| Companies Covered | Medtronic, Johnson & Johnson, Boston Scientific Corporation, Abbott, AngioDynamics, Atricure, Stryker, Smith & Nephew, CONMED Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ablation Devices Market Evolving Landscape
Energy-delivery modalities are fragmenting from monopolar radiofrequency dominance toward diversified thermal and non-thermal tissue interaction mechanisms.
Irrigated-tip catheter designs with closed-loop temperature feedback is modularizing procedural standardization across electrophysiology labs. High-volume cardiac centers in Texas and California adopt these configurations to reduce steam-pop complications and enable predictable lesion sets. The technology is modularizing training protocols and compressing credentialing timelines for new operators.
FDA draft guidance on pulse-field ablation safety endpoints is reshaping clinical trial design requirements for novel non-thermal platforms. Manufacturers must now demonstrate durable pulmonary vein isolation with reduced collateral tissue injury profiles. The catheter-based cardiac ablation segment is responding with expanded preclinical testing budgets and extended follow-up study commitments.
Hospital procurement committees are consolidating vendor relationships through single-source electrophysiology lab contracts. Integrated platform purchases—combining mapping systems, energy generators, and disposable catheters—are displacing point-solution acquisitions. This concentration is most visible in Ontario's provincial health system purchasing frameworks and California's integrated delivery networks.
North America Ablation Devices Market Segmentation
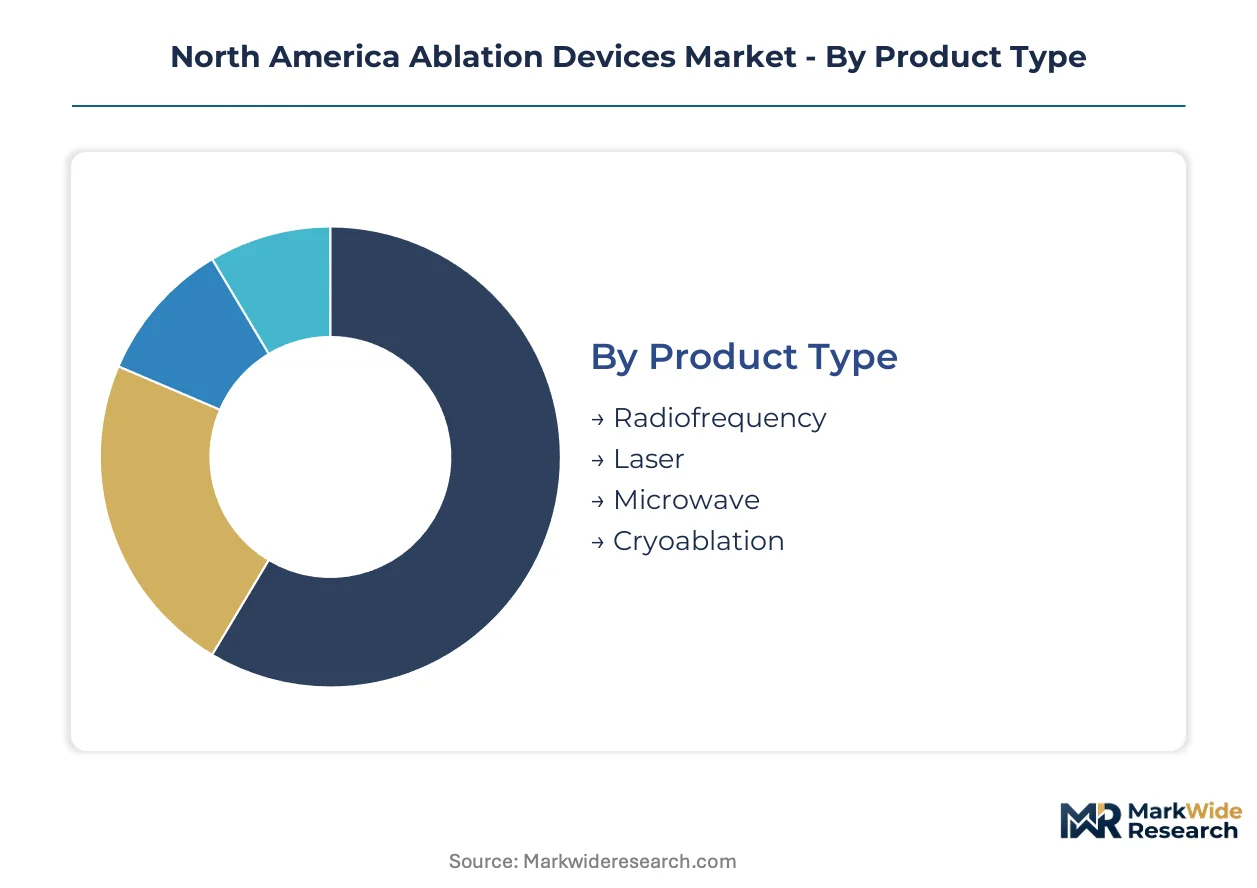
Ablation device purchasing patterns diverge sharply across care settings and procedural complexity. Capital equipment commitments, disposable catheter volumes, and reimbursement pathways all fragment along segment boundaries that determine vendor profitability and hospital procurement strategy.
Product Type:
Capital intensity concentrates in radiofrequency platforms requiring integrated generator systems and mapping console investments, while cryoablation demands specialized gas delivery infrastructure.
- Radiofrequency:Electrode-tipped catheters operating at 460-500 kHz dominate installed bases across Texas and California hospital systems. Irrigated-tip configurations reduce steam-pop complications and command premium pricing in high-volume electrophysiology labs.
- Cryoablation:Balloon-based systems using nitrous oxide or argon achieve single-shot pulmonary vein isolation. Ontario cardiac centers favor this modality for reduced fluoroscopy exposure and shorter operator training curves.
- Laser:Fiber-optic delivery systems target ophthalmologic and dermatologic applications with precise tissue penetration control.
- Microwave:Electromagnetic heating at 915 MHz or 2.45 GHz serves hepatic and renal tumor applications where larger ablation zones prove advantageous.
Most installed capacity flows through radiofrequency systems. Expansion is steepest in cryoablation as single-shot procedures gain adoption.
End User:
Reimbursement tiering separates inpatient hospital rates from ambulatory facility fees, creating distinct procurement economics across settings.
- Hospitals:Academic medical centers and metropolitan systems in Texas, California, and Ontario anchor demand for multi-modality electrophysiology suites. CMS inpatient prospective payment systems and Canadian provincial health budgets govern capital allocation cycles.
- Ambulatory Surgical Centers:Certificate-of-need reforms in select US states enable outpatient cardiac ablation with same-day discharge protocols. Medicare ASC fee schedules reimburse at lower rates but eliminate overnight stay costs.
- Outpatient Clinics:Pain management and dermatologic applications concentrate in independent practice settings with lower equipment thresholds.
- Research Institutions:Preclinical testing and clinical trial infrastructure support next-generation pulsed-field ablation development under FDA investigational device exemption pathways.
Procedure volume concentrates in hospital-based labs. Volume migration toward ambulatory surgical centers is accelerating fastest where regulatory permits.
Application:
Clinical evidence depth and reimbursement coverage breadth vary dramatically across therapeutic areas, determining addressable market size per segment.
- Cardiac:Atrial fibrillation ablation commands the largest addressable population with established CPT codes and coverage determinations. Pulsed-field platforms are compressing procedure times and enabling same-day discharge across metropolitan Texas and California systems.
- Oncology:Tumor ablation for liver, lung, and kidney malignancies serves patients ineligible for surgical resection. Interventional radiology departments in Ontario cancer centers drive adoption of microwave and cryoablation systems.
- Neurology:Movement disorder and epilepsy applications remain concentrated in specialized academic centers with deep brain stimulation crossover.
- Pain Management:Radiofrequency denervation for spinal and joint applications serves chronic pain populations in outpatient settings with lower capital barriers.
Revenue concentration sits with cardiac applications. Oncology is gaining share fastest as interventional radiology expands tumor ablation programs.
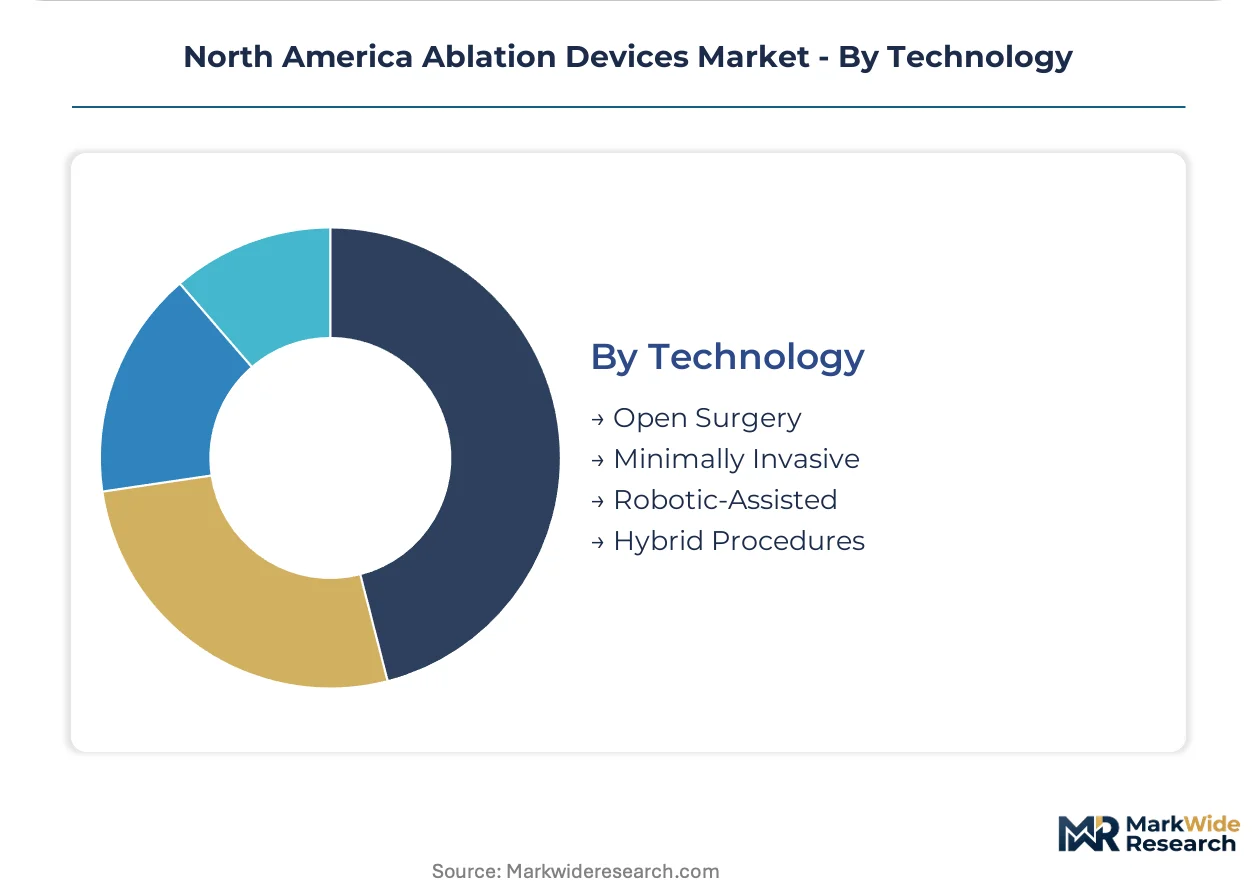
Technology:
Procedural economics and training infrastructure requirements stratify adoption curves across access modalities.
- Minimally Invasive:Percutaneous catheter access dominates cardiac and vascular applications with reduced recovery times driving hospital throughput metrics. Texas and California health systems prioritize these configurations for ambulatory transition.
- Robotic-Assisted:Magnetic navigation and robotic catheter control enable remote operator positioning with reduced fluoroscopy exposure. Academic medical centers deploy these platforms for complex arrhythmia substrates and training value.
- Open Surgery:Surgical ablation during concomitant cardiac procedures serves structural heart disease patients requiring mechanical valve replacement or coronary bypass.
- Hybrid Procedures:Combined surgical and catheter-based approaches in hybrid operating rooms address persistent atrial fibrillation with epicardial and endocardial lesion sets.
Minimally invasive platforms carry the largest installed base. Robotic-assisted configurations are climbing the fastest as electrophysiology labs upgrade mapping integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan hospital systems across Texas anchor North American demand for catheter-based cardiac ablation, with Ontario and California forming secondary concentration zones for minimally invasive electrophysiology programs.
United States
Texas and California health systems drive installed base expansion for multi-modality electrophysiology suites. FDA 510(k) premarket notification pathways accelerate commercialization timelines for novel catheter designs. Dallas-Fort Worth and Houston cardiac centers adopt pulsed-field platforms to enable same-day discharge protocols.
Canada
Ontario's provincial health purchasing frameworks consolidate vendor relationships for integrated mapping and energy-delivery systems. Health Canada's Medical Devices Directorate sets parallel approval standards to FDA pathways for cross-border commercialization. Toronto and Ottawa hospital networks favor cryoablation balloon technologies for reduced fluoroscopy exposure.
Mexico
Mexico City metropolitan hospitals expand interventional cardiology programs through public-private partnerships with US device distributors. COFEPRIS regulatory alignment with FDA standards facilitates faster market entry for established North American manufacturers. Guadalajara medical centers develop regional referral networks for complex arrhythmia cases.
North America Ablation Devices Market Competitive Landscape
Global majors compete with regional champions across technology platforms and hospital procurement relationships. The vendor base stratifies into three tiers: diversified medical technology conglomerates with full electrophysiology portfolios, mid-scale cardiovascular specialists with focused ablation offerings, and niche interventional radiology equipment suppliers. Strategic archetypes include irrigated-tip catheter innovators, cryoablation platform developers, and pulsed-field energy pioneers. Competitive dynamics center on single-source electrophysiology lab contracts and integrated platform bundling.
Among diversified medical technology conglomerates, Medtronic, Boston Scientific Corporation, and Abbott exemplify full-portfolio positioning. Medtronic leverages in-house production of catheter manufacturing and energy-delivery systems. Boston Scientific Corporation anchors its presence through R&D intensity in emerging modalities. Abbott occupies a differentiated position via specialized cryoablation technologies. These three entities represent the premium-tier competitive vector where integrated platform purchases displace point-solution acquisitions.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Abbott |
| AngioDynamics |
| Atricure |
| Stryker |
| Smith & Nephew |
| CONMED Corporation |
| Others |
Value Network & Pricing Analysis
Electrophysiology fellowship concentration in Texas and California creates labor-cost differentials that widen pricing-tier spreads between academic medical centers and community hospital systems. These regional workforce premiums feed into procurement committee evaluations of integrated platform bundles versus point-solution acquisitions.
Pricing Analysis
Platinum-iridium electrode cost pass-through from specialized metallurgical suppliers anchors premium pricing for irrigated-tip radiofrequency catheters. Three-tier pricing structure across premium irrigated-tip, standard solid-tip, and economy reusable configurations separates vendor tiers by lesion durability data and closed-loop temperature feedback capabilities. Pricing pressure stems from IRA Medicare price negotiation uncertainty delaying hospital capital equipment depreciation schedules. Ambulatory surgical centers exhibit highest price sensitivity due to lower reimbursement rates under Medicare ASC fee schedules, while academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
FDA 510(k) clearance and Health Canada Medical Devices Directorate certification create dual-qualification gating for catheter manufacturers seeking North American market entry. Component sourcing draws from precision machining clusters in Germany, nitinol wire suppliers in the United States, and platinum-group metal refiners in South Africa. Single-source vulnerability concentrates in specialized electrode metallurgy for radiofrequency applications. Distribution runs through hospital procurement committees consolidating vendor relationships through single-source electrophysiology lab contracts, with GPO contracts managers negotiating integrated platform purchases across Texas, California, and Ontario health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Ablation Devices Market functions as a stable compounder anchored by irreversible procedure volume migration toward minimally invasive cardiac interventions. Reimbursement code stability and expanding ambulatory capacity create predictable revenue visibility across the analysis window.
For Market Incumbents: Cement platform stickiness through captive supply of mapping system software upgrades and disposable catheter lock-in provisions. Deepen backward integration into electrode metallurgy to buffer platinum-iridium cost volatility threatening margin structures. Prioritize Ontario and Quebec provincial health framework penetration ahead of competitive entrants leveraging Health Canada approval pathway acceleration. For New Entrants and Emerging Players: Enter via pulsed-field ablation safety endpoint trials addressing FDA draft guidance requirements as the most penetrable regulatory white space. Target ambulatory surgical center certificate-of-need reform states for outpatient electrophysiology lab partnerships with lower incumbent switching costs. Pursue remote monitoring reimbursement code integration as a differentiated service-layer attach. For Investors and Strategic Acquirers: Diversified medical technology conglomerates represent the most active acquirer category in this space, seeking electrophysiology portfolio gaps to fill. Long-term viability frames around procedure volume compounding and same-day discharge protocol expansion. Acquisition target archetypes include mid-scale cardiovascular specialists with focused cryoablation or pulsed-field platforms. Watch FDA final guidance on pulse-field ablation safety endpoints as the inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notification reduces time-to-commercialization for novel catheter designs in Texas and California systems. |
| Hospital System Partnership | Single-source electrophysiology lab contracts with Ontario provincial health frameworks displace point-solution vendor relationships. |
| Reimbursement Strategy Development | CMS national coverage determination alignment enables rapid physician adoption and procurement committee approval. |
| Software Companion Development | Real-time electroanatomic mapping integration addresses legacy EMR interoperability challenges in hospital information systems. |
| CE Marking Pathway Parallel | Health Canada Medical Devices Directorate approval enables faster Ontario and Quebec market entry for next-generation platforms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, Health Canada device approvals, CMS national coverage determinations, and hospital procurement databases. Bottom-up catheter volume modeling and top-down health system capital expenditure triangulation anchored market size estimates.
Comparable-period anchoring linked historical radiofrequency installed base data to projected cryoablation and pulsed-field adoption curves across the modeling period. Segmentation dimensions spanned energy modality, access technology, end-user setting, and therapeutic application, with CAGRs derived from procedure volume growth rates and reimbursement trajectory analysis. Forecast inputs incorporated electrophysiology fellowship pipeline constraints and certificate-of-need regulatory reform timelines.
Inputs from FDA premarket notification databases and CMS reimbursement schedules were available through the study window; gaps in real-time hospital capital equipment purchasing cycle data introduce uncertainty bands around near-term generator system deployment forecasts. Forecasts reflect documented assumptions regarding pulsed-field safety endpoint clearance timelines and ambulatory surgical center regulatory expansion. A model refresh is warranted upon material change in IRA Medicare price negotiation implementation or FDA final guidance on non-thermal ablation safety thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Fluorescence-Guided Surgery Systems Market
Medical Devices
Cholesterol Management Devices Market
Medical Devices
Lactate Meter Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Germany Anesthesia Devices Market
Medical Devices
Global Vaginal Speculum Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
Dysphagia Management Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Supraglottic Device Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Graft Delivery Devices Market
Medical Devices
Peripheral Vascular Guide Wire Market