
 Foot and Ankle Allograft Market | 2026-2036
Foot and Ankle Allograft Market Size, Share, and Industry Trends Forecast 2026-2036
Foot and Ankle Allograft Market Analysis
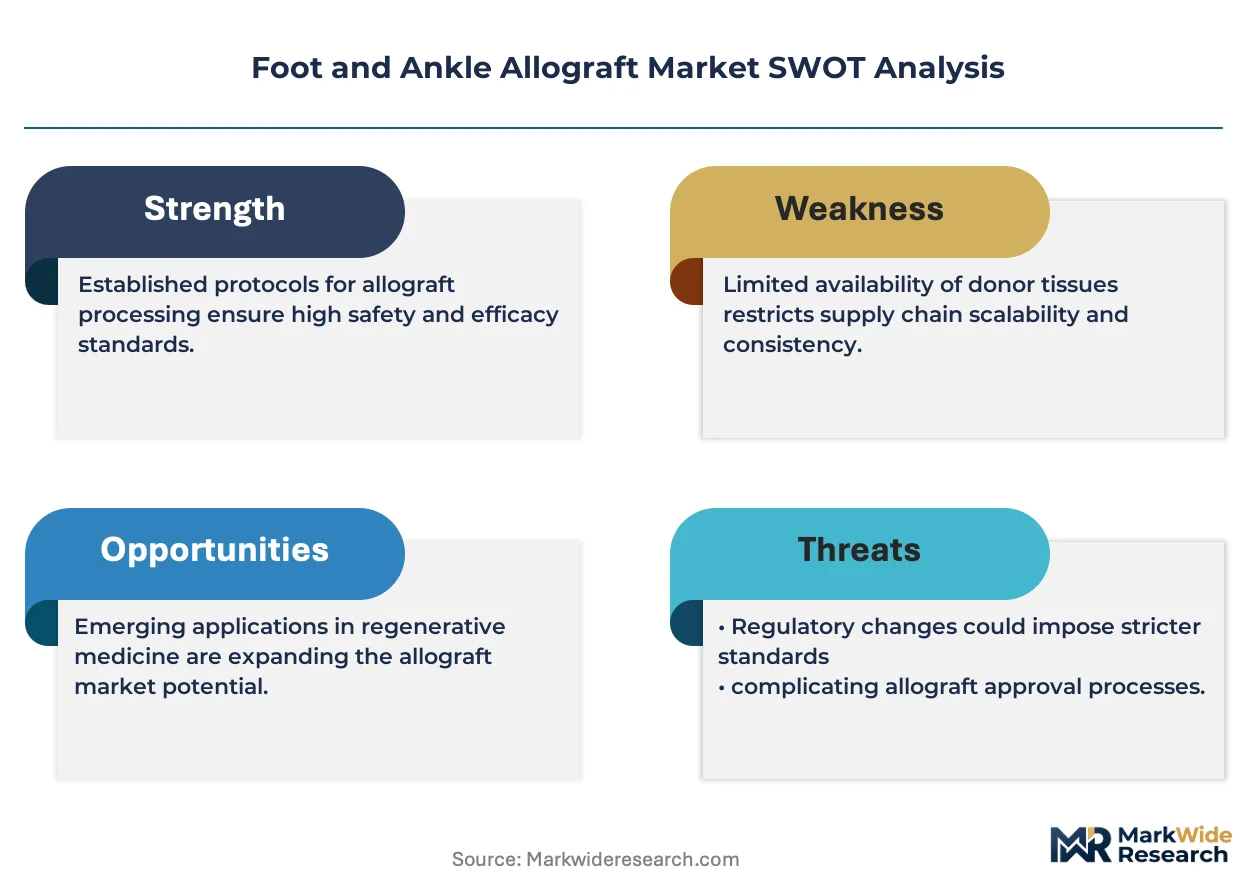
The EU Medical Device Regulation is repositioning procurement criteria for human-derived implants across European hospitals. AlloSource leverages its vertically integrated tissue recovery network to sustain supply continuity amid these compliance shifts. Zimmer Biomet anchors its portfolio through proprietary processing protocols that differentiate allograft offerings from synthetic alternatives.
Foot and ankle allografts comprise sterilized human donor tissue—predominantly cortical or cancellous bone, tendons, and cartilage—processed through aseptic techniques and preserved via cryopreservation or freeze-drying to restore structural integrity following trauma or degenerative joint disease. Demineralized bone matrix leads product type revenue due to its osteoinductive properties and established reimbursement pathways, while cartilage allografts represent the fastest-growing segment as surgeons shift toward biologic resurfacing over metallic fusion. Hospitals dominate end user volume, though sports medicine facilities command premium pricing for specialized tendon and ligament reconstruction procedures.
FDA oversight through 21 CFR Part 1271 and the American Association of Tissue Banks standards govern donor screening, processing validation, and distribution chain integrity for allograft products in the United States. The EU MDR and EMA guidance on human-derived substances impose additional clinical evidence requirements that constrain market access for non-European suppliers. Stakeholders must monitor evolving equivalence determinations between regional regulatory frameworks to optimize portfolio allocation and manufacturing site qualification strategies.
Market Dynamics
The Foot and Ankle Allograft Market pivots on the FDA's evolving tissue guidance framework, which is compressing processing validation timelines while expanding indications for biologic resurfacing over metallic fusion. This regulatory recalibration simultaneously elevates compliance costs and creates tiered market access tiers based on clinical evidence depth.
Growth Catalysts
- Biologic resurfacing protocols:Surgeons at orthopedic clinics and sports medicine facilities are substituting cartilage allografts for ankle arthrodesis, driven by patient demand for joint-preserving motion.
- 21 CFR Part 1271 harmonization:The FDA's streamlined donor screening equivalency determinations are reducing batch release delays for aseptically processed tendon grafts.
- United States demand concentration:Tissue bank networks in Colorado and Florida are capturing economies of scale in cryopreservation logistics that lower per-unit procurement costs for hospital systems.
Market Restraints
- Cortical bone input volatility:Donor tissue availability fluctuates with regional mortality demographics and consent rate variability, creating supply discontinuities for weight-bearing structural grafts.
- EU MDR clinical evidence requirements:The European Medical Device Regulation's tightened equivalence pathways are extending market access timelines for non-European suppliers by 18-36 months.
- Synthetic bone substitute substitution:Polymer-ceramic composites from industrial chemical suppliers are capturing price-sensitive volume in revision arthroplasty cases where osteoinductivity is secondary.
Strategic Opportunities
- Underpenetrated ambulatory surgery centers:Freestanding orthopedic facilities in Texas and Arizona are building captive tissue processing partnerships to bypass hospital procurement markups.
- Demineralized bone matrix-cartilage combination products:Converging osteoinductive scaffolds with chondrocyte viability preservation is opening ankle osteochondral lesion indications previously reserved for autograft.
- Direct-to-facility distribution channels:Tissue banks are deploying cold-chain logistics platforms that bypass traditional distributor tiers, capturing margin and improving graft viability windows.
Industry Challenges
- Histocompatibility testing skill scarcity:Processing facilities face recruitment constraints for technicians trained in flow cytometry-based donor-recipient matching protocols.
- Cleanroom capex intensity:Aseptic processing suites requiring ISO 5-7 classification demand capital deployment that squeezes mid-tier tissue bank expansion capacity.
- American Association of Tissue Banks certification timelines:New facility accreditation averages 14-18 months, delaying operational revenue for emerging market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foot and Ankle Allograft Market |
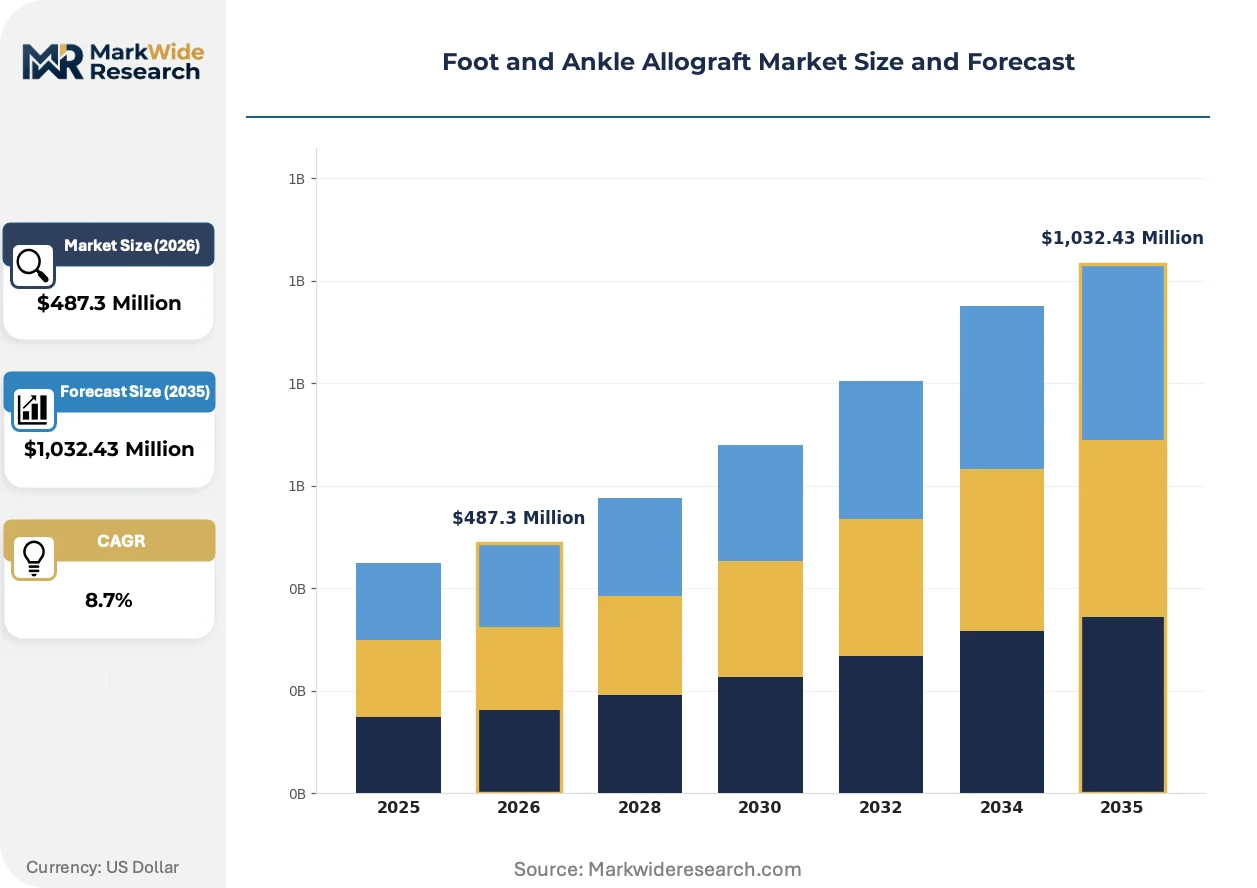
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Demineralized Bone Matrix, Tendon Grafts, Whole Bone Allografts, Cartilage Allografts End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Sports Medicine Facilities Application: Ligament Reconstruction, Cartilage Repair, Fracture Fixation, Osteochondral Defects Delivery Mode: Surgical Procedures, Minimally Invasive Techniques, Open Surgery, Arthroscopy |
| Companies Covered | AlloSource, Arthrex, Zimmer Biomet, RTI Surgical Holdings, JRF Ortho, Integra LifeSciences, MTF Biologics, LifeNet Health, Bone Bank Allografts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foot and Ankle Allograft Market Emerging Trajectories
Processing technology and procurement logic are restructuring competitive advantage in human-derived implants, with preservation methods and distribution models commanding equal strategic weight as graft biology itself.
Lyophilization with terminal sterilization is overtaking traditional cryopreservation as the dominant preservation modality for structural bone allografts. Hospital procurement committees are prioritizing room-temperature storage logistics that eliminate liquid nitrogen dependency. This compression of cold-chain infrastructure is enabling ambulatory facilities to stock inventory previously reserved for tertiary medical centers.
The EU Medical Device Regulation's tightened equivalence determinations are forcing non-European suppliers to construct parallel clinical evidence packages for European market access. Tissue banks with existing CE-marked portfolios are defending position through proprietary processing protocols that differentiate from synthetic alternatives. Smaller suppliers are retreating from European orthopedic clinics to concentrate on United States hospital system contracts.
Sports medicine facilities are unbundling graft procurement from surgical service contracts, creating standalone tissue bank relationships that bypass hospital materiel management. This disintermediation concentrates purchasing authority with fellowship-trained foot and ankle surgeons rather than centralized procurement officers. The shift is most visible in Florida and California, where private equity-backed orthopedic platforms are consolidating specialty practice networks.
Foot and Ankle Allograft Market Segmentation
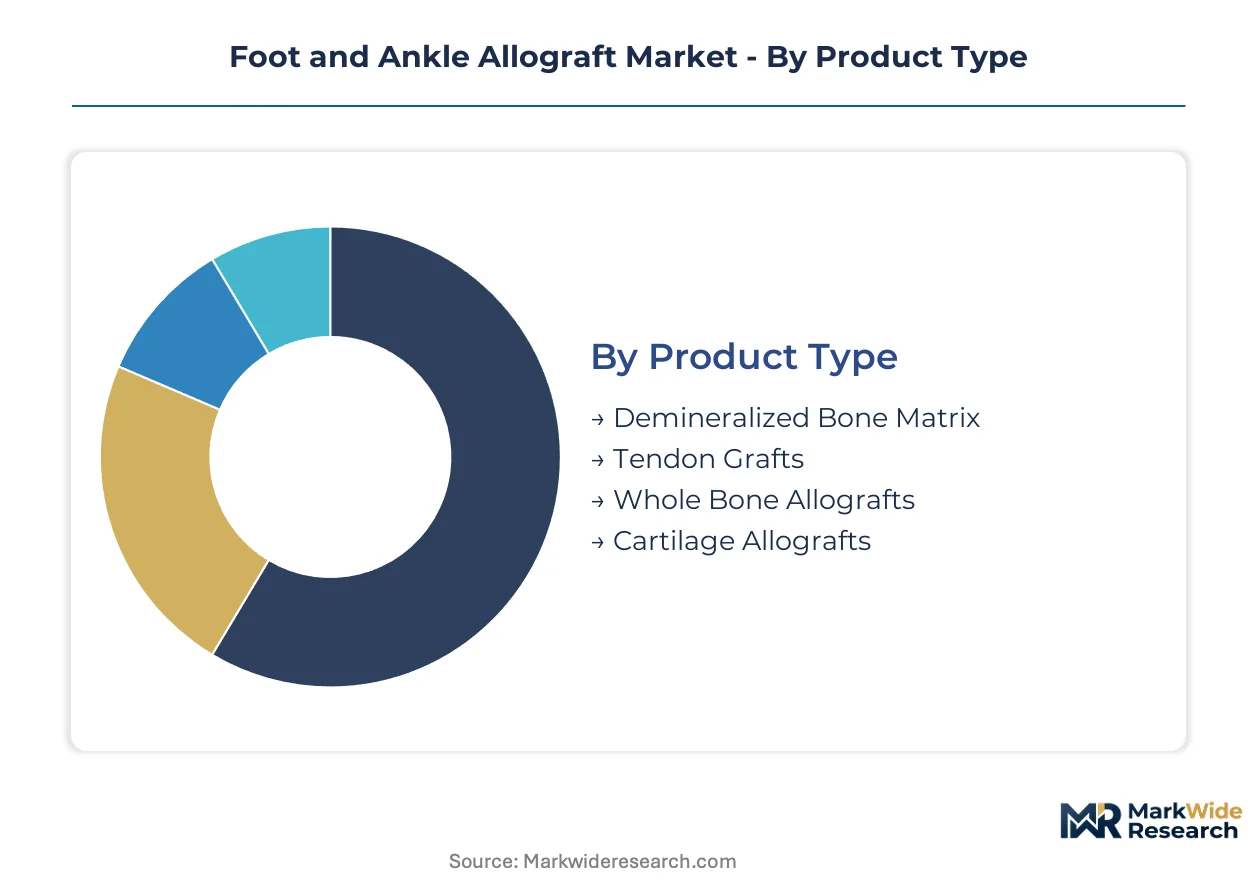
Segmentation in the foot and ankle allograft market reveals how procurement authority, clinical setting, and surgical technique reshape demand patterns. Processing capabilities and cold-chain logistics concentrate differently across each dimension, creating distinct competitive arenas for tissue banks.
Product Type:
Supply concentration in cryopreservation infrastructure favors processors with captive donor networks and aseptic suite capacity.
- Demineralized Bone Matrix:Acid-extracted collagen scaffold retaining bone morphogenetic proteins for osteoinduction. Hospital systems in Colorado and Florida prioritize this category for revision arthrodesis cases due to established reimbursement codes and room-temperature storage compatibility.
- Cartilage Allografts:Viable chondrocyte-bearing grafts preserved via controlled-rate freezing for biologic resurfacing. Sports medicine facilities in California and Texas are substituting these for ankle arthrodesis as patient demand for joint motion preservation intensifies.
- Tendon Grafts:Sterilized Achilles or peroneal tendon segments for ligament reconstruction protocols.
- Whole Bone Allografts:Structural cortical or cancellous segments for weight-bearing defect reconstruction.
Demineralized bone matrix absorbs the bulk of installed capacity; cartilage allografts are expanding most quickly.
End User:
Cost tier stratification separates premium-priced specialty settings from high-volume hospital procurement.
- Hospitals:Tertiary medical centers with centralized materiel management and committee-based purchasing. United States hospital systems leverage tissue bank networks in Colorado and Florida to capture economies of scale in cryopreservation logistics.
- Sports Medicine Facilities:Fellowship-trained surgeon-directed procurement with unbundled graft sourcing. Private equity-backed orthopedic platforms in Florida and California are consolidating these networks and bypassing traditional distributor tiers.
- Orthopedic Clinics:Freestanding facilities building captive tissue processing partnerships.
- Rehabilitation Centers:Post-acute settings with limited direct procurement authority.
Hospitals dominate absolute volume; sports medicine facilities command the steepest price premiums.
Application:
Volume concentration in trauma cases contrasts with margin concentration in elective biologic procedures.
- Fracture Fixation:Structural allograft supplementation for comminuted tibial pilon and calcaneal fractures. United States trauma centers prioritize cortical bone segments for weight-bearing reconstruction where autograft harvest risks donor site morbidity.
- Osteochondral Defects:Focal cartilage and subchondral bone lesions addressed through biologic resurfacing. Surgeons at orthopedic clinics are shifting toward allograft mosaicplasty as an alternative to metallic fusion for talus lesions.
- Ligament Reconstruction:Lateral ankle instability and peroneal tendon repair applications.
- Cartilage Repair:Generalized chondral defect management across ankle joint surfaces.
Fracture fixation absorbs the bulk of installed capacity; osteochondral defect applications are climbing the fastest.
Delivery Mode:
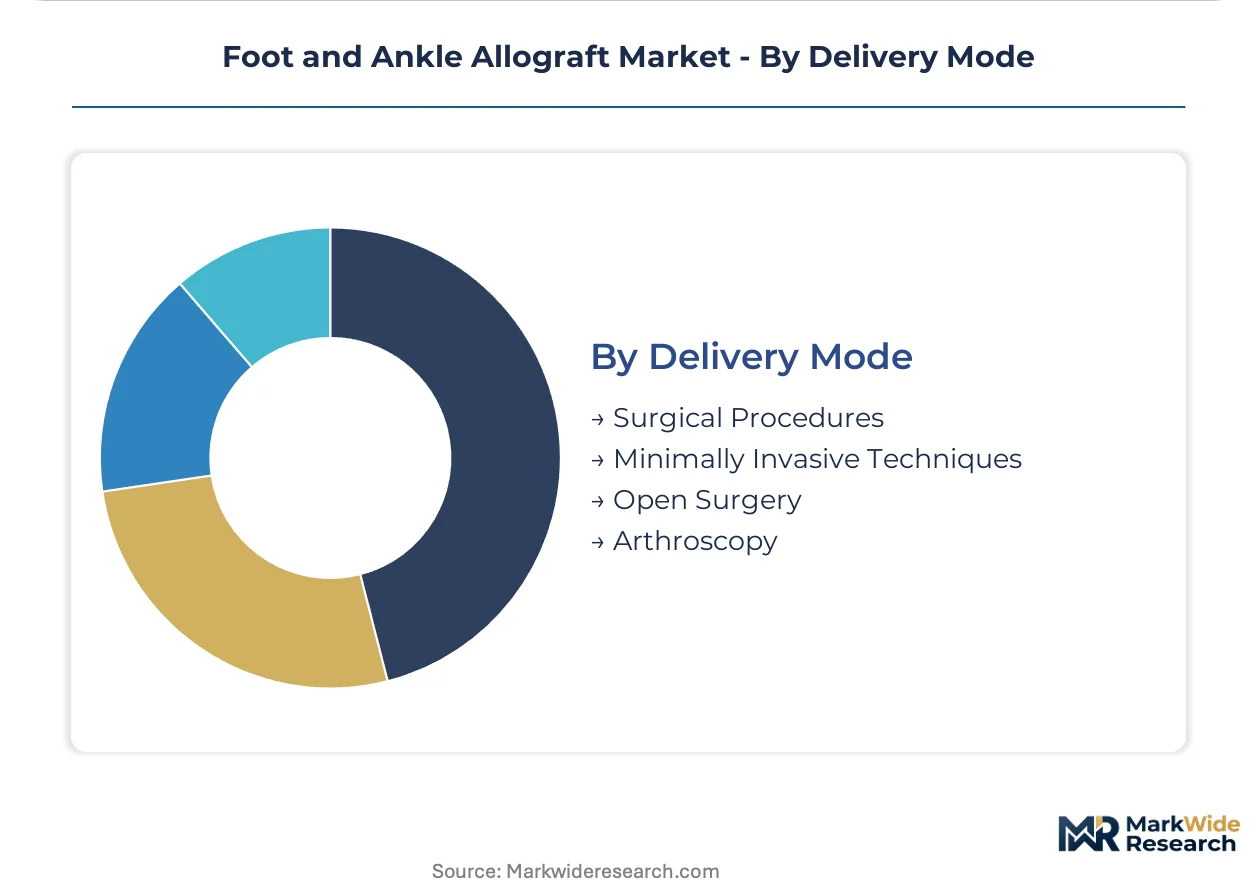
Margin structure diverges sharply between capital-intensive arthroscopy and conventional open approaches.
- Arthroscopy:Minimally invasive ankle joint access requiring specialized instrumentation and allograft sizing precision. Sports medicine facilities in Texas and Arizona are driving adoption as fellowship-trained surgeons demand grafts compatible with small-joint arthroscopic portals.
- Minimally Invasive Techniques:Percutaneous or limited-incision approaches reducing soft tissue disruption. Ambulatory surgery centers are prioritizing these protocols to support same-day discharge and lower facility fee exposure.
- Open Surgery:Traditional extensile approaches for complex reconstruction or revision cases.
- Surgical Procedures:General category encompassing all operative delivery contexts.
Open surgery retains the bulk of installed capacity; arthroscopy is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Centennial, Colorado anchors North American allograft processing capacity through AlloSource's vertically integrated tissue recovery network. This concentration shapes procurement patterns for hospital systems across the United States.
United States
FDA oversight through 21 CFR Part 1271 compresses processing validation timelines while expanding biologic resurfacing indications. The American Association of Tissue Banks certification requirements average 14-18 months for new facilities. Tissue bank networks in Colorado and Florida capture economies of scale in cryopreservation logistics.
Germany
The EU Medical Device Regulation's tightened equivalence pathways extend market access timelines for non-European suppliers by 18-36 months. EMA guidance on human-derived substances imposes additional clinical evidence requirements. Hospital procurement committees in Bavaria and North Rhine-Westphalia prioritize CE-marked portfolios with proprietary processing protocols.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance tracks for tissue banks serving NHS trusts versus private orthopedic platforms. The Medicines and Healthcare products Regulatory Agency maintains alignment with EU MDR standards. London and Manchester surgical hubs concentrate demand for specialized tendon and ligament reconstruction procedures.
Switzerland
Swissmedic's stringent donor screening standards exceed baseline EU requirements, creating a premium-tier market segment. The country's bilateral agreements with the EU facilitate cross-border tissue distribution. Basel and Zurich medical centers drive adoption of cartilage allografts for joint-preserving ankle procedures.
Canada
Health Canada's tissue regulations emphasize traceability through the entire donor-to-recipient chain. Provincial health authorities in Ontario and British Columbia negotiate centralized procurement contracts with approved tissue banks. Toronto and Vancouver trauma centers prioritize structural cortical bone segments for weight-bearing reconstruction cases.
Foot and Ankle Allograft Market Vendor Landscape
Premium-margin players sit above commodity-margin players across preservation technology and distribution channel dimensions. The vendor base stratifies into three tiers: vertically integrated tissue banks with captive donor networks, specialized biologics processors with proprietary aseptic protocols, and regional distributors dependent on third-party supply. Dominant competitive moves include direct-to-facility distribution channel construction and ambulatory surgery center partnership formation.
Within the integrated tissue bank tier, AlloSource and MTF Biologics exemplify archetypes with captive recovery networks spanning multiple states. Arthrex occupies a position among specialized processors emphasizing sports medicine facility relationships. Zimmer Biomet anchors the diversified orthopedic conglomerate segment, leveraging existing surgical instrumentation sales channels to bundle allograft procurement.
| Leading Market Players |
|---|
| AlloSource |
| Arthrex |
| Zimmer Biomet |
| RTI Surgical Holdings |
| JRF Ortho |
| Integra LifeSciences |
| MTF Biologics |
| LifeNet Health |
| Bone Bank Allografts |
| Others |
Supply Flow & Price Mechanics
Cryopreservation logistics costs cascade through three distinct pricing tiers as tissue banks in Colorado and Florida capture economies of scale that hospital systems leverage for volume discounts while ambulatory surgery centers absorb premium markups for small-batch viability preservation.
Pricing Analysis
Value-based pricing anchored to surgical outcome metrics governs cartilage allograft transactions at sports medicine facilities. Pricing stratifies across premium, standard, and economy tiers based on American Association of Tissue Banks certification grade and chondrocyte viability preservation protocol. Cost compression in the standard tier is intensifying because synthetic bone substitutes from industrial chemical suppliers are capturing price-sensitive revision arthroplasty volume. Hospital procurement committees exhibit the highest price sensitivity due to centralized materiel management and committee-based purchasing authority, while fellowship-trained foot and ankle surgeons at private equity-backed orthopedic platforms demonstrate the least sensitivity when unbundling graft procurement from surgical service contracts.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital systems mandate tissue bank qualification across both Colorado and Florida recovery networks to mitigate batch release disruption risk. Geographic supply concentration centers on the United States, with Switzerland and Germany serving as secondary hubs for CE-marked portfolios. Raw material dependencies rest on donor tissue availability, aseptic processing suite capacity, and liquid nitrogen cold-chain infrastructure. Single-source vulnerability concentrates in cryopreservation logistics where regional mortality demographics and consent rate variability create supply discontinuities. Distribution runs through direct-to-facility channels that bypass traditional distributor tiers, with tissue banks deploying proprietary cold-chain platforms to improve graft viability windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive donor recovery networks has become the defining competitive race as tissue banks seek upstream control over supply continuity amid FDA processing validation timeline compression.
For Market Incumbents: Acquire regional tissue recovery organizations to secure donor consent pipeline density in demographically favorable states. Defend market position by accelerating proprietary processing protocol differentiation that creates clinical evidence depth for EU MDR equivalence determinations. Channel control through direct-to-facility distribution platform expansion protects margin from distributor tier compression. For New Entrants and Emerging Players: The price-point gap between premium cartilage allografts and economy-tier demineralized bone matrix offers entry traction for specialized biologics processors. Ambulatory surgery centers in Texas and Arizona represent the most penetrable segment where captive tissue processing partnerships bypass hospital procurement markups. A go-to-market angle emphasizing room-temperature storage compatibility for lyophilized structural grafts addresses logistics cost sensitivity in freestanding orthopedic facilities. For Investors and Strategic Acquirers: FDA 21 CFR Part 1271 harmonization announcements expanding biologic resurfacing indications are the leading indicator that cartilage allograft demand acceleration is materializing. Over the projection horizon, vertically integrated tissue banks with captive recovery networks and existing CE-marked portfolios present the most defensible acquisition archetype. The signal to monitor is American Association of Tissue Banks certification timeline compression for new facilities, which would indicate regulatory capacity expansion enabling market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Tissue Recovery Network Expansion | Backward integration into donor consent pipelines secures supply continuity against regional mortality volatility. |
| Proprietary Aseptic Processing Protocol Development | FDA-validated differentiation creates tiered market access based on clinical evidence depth. |
| Direct-to-Facility Distribution Platform Deployment | Cold-chain logistics bypassing distributor tiers captures margin and improves graft viability windows. |
| EU MDR Clinical Evidence Package Construction | Parallel equivalence determinations defend European orthopedic clinic access against tightened pathways. |
| Demineralized Bone Matrix-Cartilage Combination Product R&D | Converging osteoinductive scaffolds with chondrocyte viability preservation opens ankle osteochondral lesion indications. |
Methodological Framework
FDA 510(k) filings, American Association of Tissue Banks accreditation records, and hospital procurement database extracts formed the secondary backbone for supply-side capacity assessment. Primary interviews with tissue bank operations directors, orthopedic surgeons at sports medicine facilities, hospital GPO contracts managers, and biomedical engineers validated processing technology adoption patterns. Bottom-up triangulation across donor recovery volume data and top-down reconciliation against surgical procedure incidence estimates anchored market sizing.
Historical trendline analysis of demineralized bone matrix and cartilage allograft shipment volumes established baseline growth trajectories across the analysis window. The forecast framework segmented by product type, end user archetype, application, and delivery mode, with CAGRs derived from surgical procedure volume elasticity to biologic resurfacing protocol adoption. Chondrocyte viability preservation technology diffusion curves and cryopreservation logistics cost trajectories served as industry-specific forecast inputs.
Inputs from tissue bank financial disclosures and hospital system procurement records were available through the study window; gaps in real-time donor consent rate data introduce uncertainty bands around supply-side capacity projections. Deviation in FDA tissue guidance framework evolution or EU MDR equivalence determination timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Oral Appliance Market
Medical Devices
Temporary Pacing Leads Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market
Medical Devices
Autotransfusion Devices Market
Medical Devices
Home Dialysis Systems Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Infant Radiant Warmer Market
Medical Devices
Peripheral Nerve Stimulators Market
Medical Devices
Sharps Destruction Device Market
Medical Devices
Infusion Management Market
Medical Devices
Hand and Wrist Devices Market
Medical Devices
Anterior Cervical Fixation Devices Market
Medical Devices
United Kingdom Neonatal and Prenatal Devices Market