
 Soft Tissue Market | 2026-2036
Soft Tissue Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Tissue Market Outlook
A shortage of trained orthopedic surgeons is redrawing competitive dynamics across the soft tissue repair landscape. Stryker Corporation leverages its integrated sports medicine portfolio to dominate arthroscopic delivery platforms. Smith & Nephew Plc anchors its position through advanced wound healing matrices that target chronic diabetic ulcers. Zimmer Biomet specializes in rotator cuff repair systems that extend its reach into ambulatory surgery settings.
Soft tissue comprises collagen, elastin, and fibrin matrices that provide structural support to organs, muscles, and connective systems, with engineered variants manufactured through decellularization, electrospinning, or recombinant protein synthesis to restore mechanical function after injury or degeneration. Collagen-based products occupy the largest revenue pool given their established reimbursement and broad surgical applicability, while hyaluronic acid injectables are registering the fastest clinical uptake in cosmetic and orthopedic outpatient settings. Sports medicine applications are concentrating margin pools as athletes and active aging populations drive preference for minimally invasive repair options.
The FDA regulates soft tissue biologics through its Center for Biologics Evaluation and Research, requiring stringent premarket approval pathways that filter out undercapitalized entrants, while the EU MDR imposes enhanced clinical evidence requirements on implantable matrices that reshape European market access timelines. ISO 13485 quality management standards govern manufacturing consistency across multinational supply chains. Stakeholders must monitor evolving regenerative medicine advanced therapy designations and their impact on competitive positioning.
Market Dynamics
The FDA's updated biologics guidance is compressing product qualification timelines while simultaneously elevating evidence requirements, creating a bifurcation where well-capitalized firms capture accelerated pathways and smaller developers face exclusionary capital barriers.
Growth Catalysts
- Collagen scaffold innovation:Electrospinning and decellularization techniques are expanding surgical applicability across tendon, ligament, and dermal repair procedures.
- ASC infrastructure buildout:United States ambulatory surgical centers are installing dedicated soft tissue repair suites, concentrating procedure volume outside hospital settings.
- EU MDR clarity:Enhanced clinical evidence requirements for implantable matrices are filtering out marginal competitors and rewarding firms with robust trial infrastructure.
Market Restraints
- Bovine collagen supply concentration:Raw material sourcing clusters in specific geographic processing regions, exposing manufacturers to zoonotic disease transmission risks and trade disruption.
- Recombinant protein synthesis costs:Mammalian cell culture production requires specialized bioreactor infrastructure that limits batch scalability and elevates unit economics.
- FDA premarket approval friction:Stringent Center for Biologics Evaluation and Research pathways demand multi-year clinical programs that consume capital reserves before revenue generation.
Strategic Opportunities
- Chronic diabetic ulcer application:Advanced wound healing matrices address an underserved patient population with recurring treatment cycles and favorable reimbursement profiles.
- Active aging demographic expansion:Sports medicine applications among non-athletic populations aged 55-75 are creating new volume pools for rotator cuff and meniscal repair products.
- ISO 13485 certification leverage:Quality management standardization enables supplier qualification across multinational orthopedic OEM procurement networks.
Industry Challenges
- Orthopedic surgeon training deficit:Fellowship programs produce insufficient arthroscopic specialists to match ambulatory surgical center expansion timelines, constraining procedure throughput.
- Decellularization protocol standardization:Variability in residual DNA clearance and extracellular matrix preservation across manufacturing sites creates batch consistency risks and regulatory scrutiny.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Tissue Market |
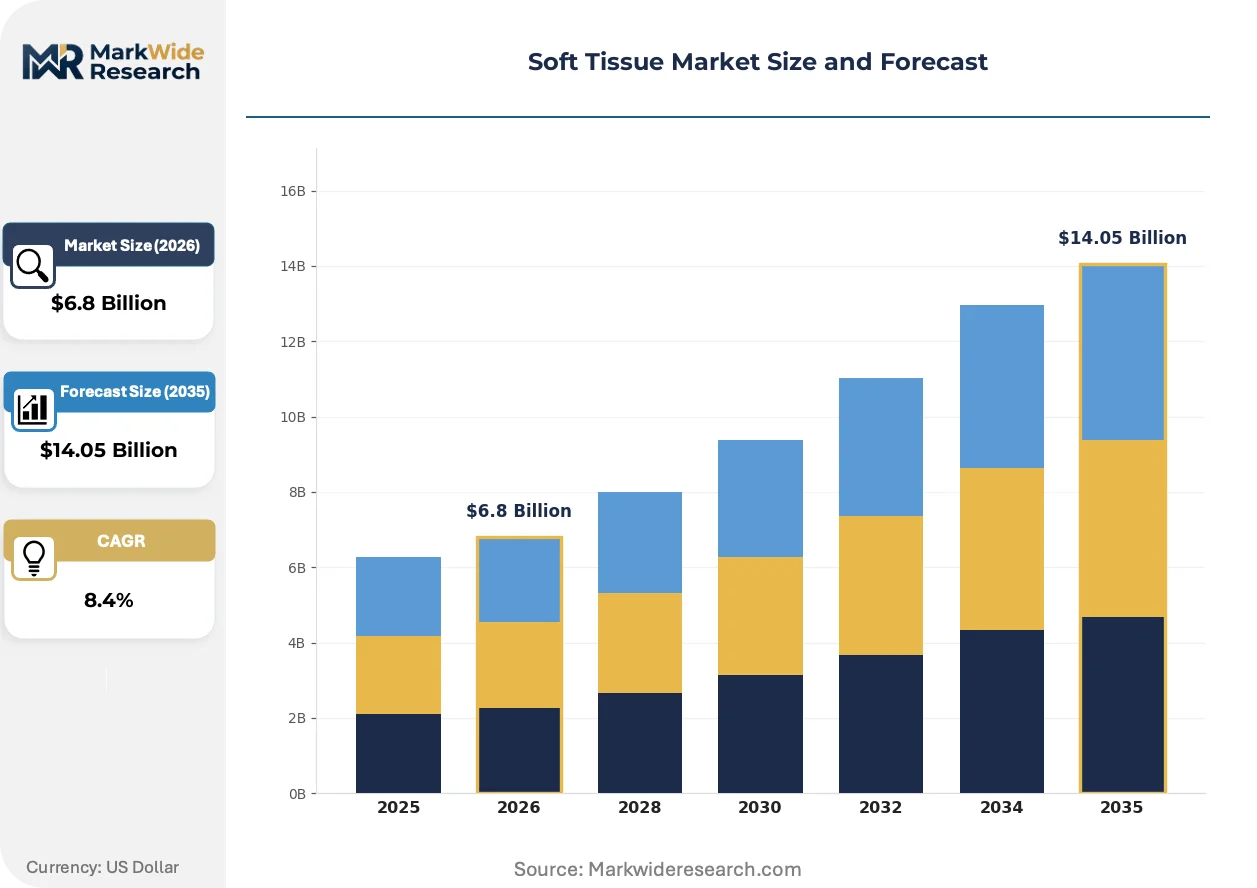
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen, Hyaluronic Acid, Elastin, Fibrin Application: Wound Healing, Cosmetic Surgery, Orthopedics, Sports Medicine End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Delivery Mode: Topical, Injectable, Surgical, Implantable |
| Companies Covered | Stryker Corporation, Smith & Nephew Plc, Becton, Dickinson and Company, Arthrex, Inc., Medtronic Plc, Johnson & Johnson, Zimmer Biomet, Integra LifeSciences, Baxter International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Tissue Market Strategic Shifts
Biologic manufacturing is pivoting from extraction-based to engineered production systems, while regulatory frameworks and procurement patterns undergo simultaneous recalibration that favors integrated solution providers over component suppliers.
Recombinant human collagen produced through tobacco plant expression systems is decomposing the traditional bovine and porcine sourcing model. Biotech firms with agricultural bioreactor partnerships are securing supply agreements with major orthopedic distributors. The structural consequence is decomposing legacy tannery-dependent supply chains and compressing raw material cost volatility for qualified manufacturers.
EU MDR Article 117 requirements for implantable devices are extending clinical evidence timelines for soft tissue matrices entering European markets. Notified bodies are demanding extended follow-up data that exceeds prior CE marking standards. Manufacturers are responding by sequencing market launches to prioritize United States FDA clearance before European submission, reshaping regional revenue timing.
Hospital procurement departments are consolidating vendor panels and demanding bundled pricing across suture, anchor, and matrix product categories. Independent distributors are losing shelf space to manufacturer-direct sales forces with dedicated orthopedic specialist teams. This concentration is most visible in United States metropolitan markets where health system consolidation has created super-regional purchasing coalitions with substantial volume leverage.
Soft Tissue Market Segmentation
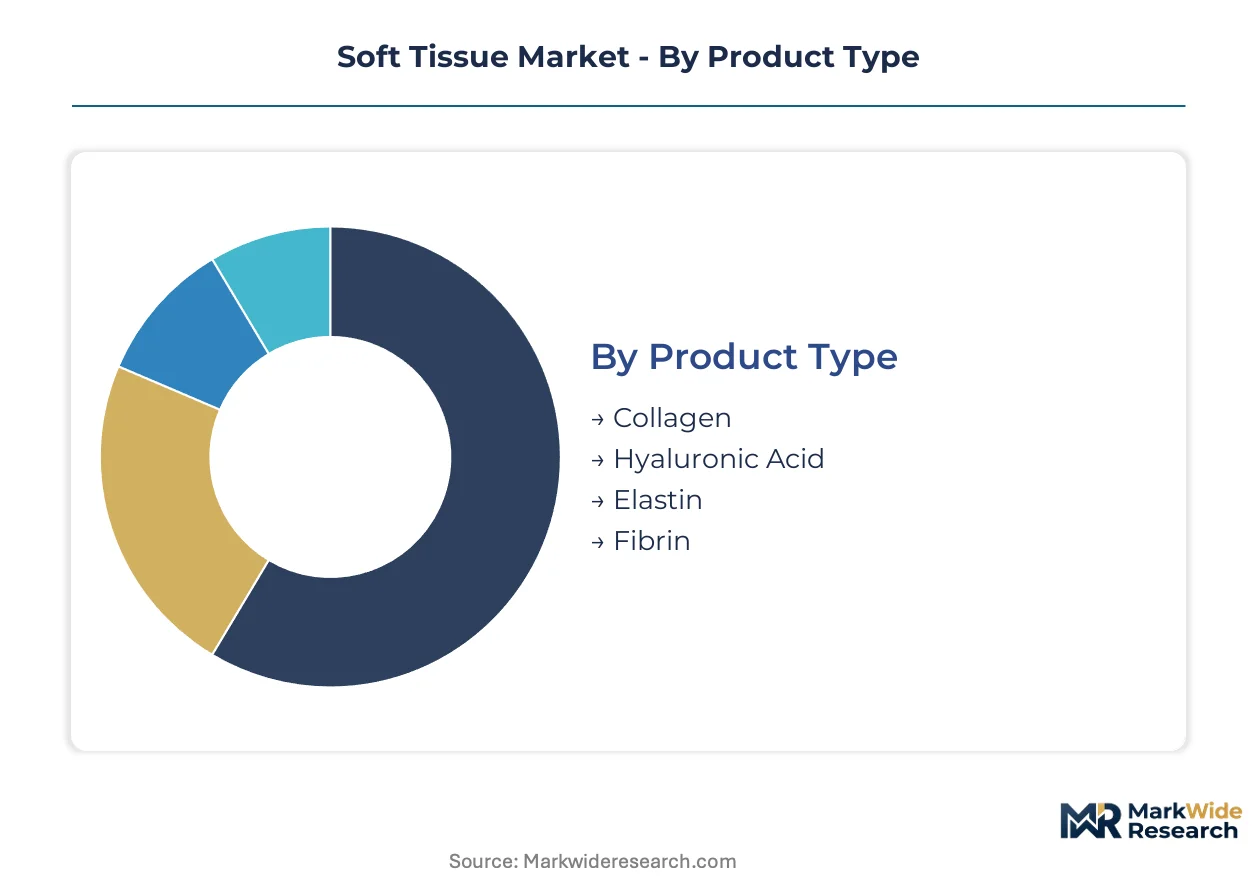
Soft tissue product differentiation determines reimbursement pathways, regulatory classification, and procurement channel access. Segmentation reveals how collagen-based matrices command hospital formulary placement while hyaluronic acid injectables penetrate outpatient cosmetic channels.
Product Type:
Domestic manufacturing concentrates collagen extraction in United States and European processing facilities, while recombinant protein production through plant-based systems is expanding in Israel and Singapore export hubs.
- Collagen:Extracted from bovine, porcine, or recombinant sources, collagen scaffolds provide structural matrices for tendon repair and dermal regeneration. United States orthopedic surgeons drive demand through ambulatory surgical center rotator cuff procedures, with FDA premarket approval pathways filtering supplier qualification.
- Hyaluronic Acid:Linear polysaccharide chains manufactured through bacterial fermentation or avian extraction, formulated as viscosupplements for joint lubrication or dermal fillers. Cosmetic dermatology clinics in South Korea and Brazil represent high-volume export destinations, propelled by outpatient procedure expansion and direct-to-consumer marketing channels.
- Elastin:Cross-linked protein matrices supporting elastic recoil in vascular and dermal applications.
- Fibrin:Hemostatic sealants derived from plasma fractionation, deployed in surgical adhesion prevention.
Collagen commands the established base. The steepest expansion runs through hyaluronic acid.
Application:
Procedure reimbursement tiers separate hospital-based surgical repair from clinic-administered cosmetic injections, with sports medicine bridging both settings through ambulatory migration.
- Wound Healing:Advanced matrices targeting chronic diabetic ulcers leverage recurring treatment cycles and favorable Medicare reimbursement. United States wound care centers concentrate demand, constrained by bovine collagen supply chain geographic clustering.
- Cosmetic Surgery:Injectable fillers and biostimulatory agents address facial volume loss and skin laxity. Brazil and Mexico clinics drive Latin American volume, fueled by medical tourism infrastructure and price-sensitive consumer segments.
- Orthopedics:Meniscal repair and cartilage regeneration applications.
- Sports Medicine:Arthroscopic delivery platforms for ligament reconstruction.
Wound healing anchors revenue stability. Cosmetic surgery delivers the most rapid volume acceleration.
End User:
Capital intensity and regulatory oversight stratify procurement authority, with hospital value analysis committees imposing vendor consolidation that excludes smaller manufacturers.
- Hospitals:Integrated health systems with centralized purchasing negotiate bundled contracts across suture, anchor, and matrix categories. United States metropolitan super-regional coalitions extract volume discounts, reshaping distributor relationships toward manufacturer-direct models.
- Clinics:Independent dermatology and orthopedic practices with direct procurement autonomy.
- Home Care:Self-administered wound dressing applications.
- Rehabilitation Centers:Post-acute recovery facilities with limited biologic formulary access.
Hospitals dominate procurement leverage. Clinics represent the most dynamic expansion channel.
Delivery Mode:
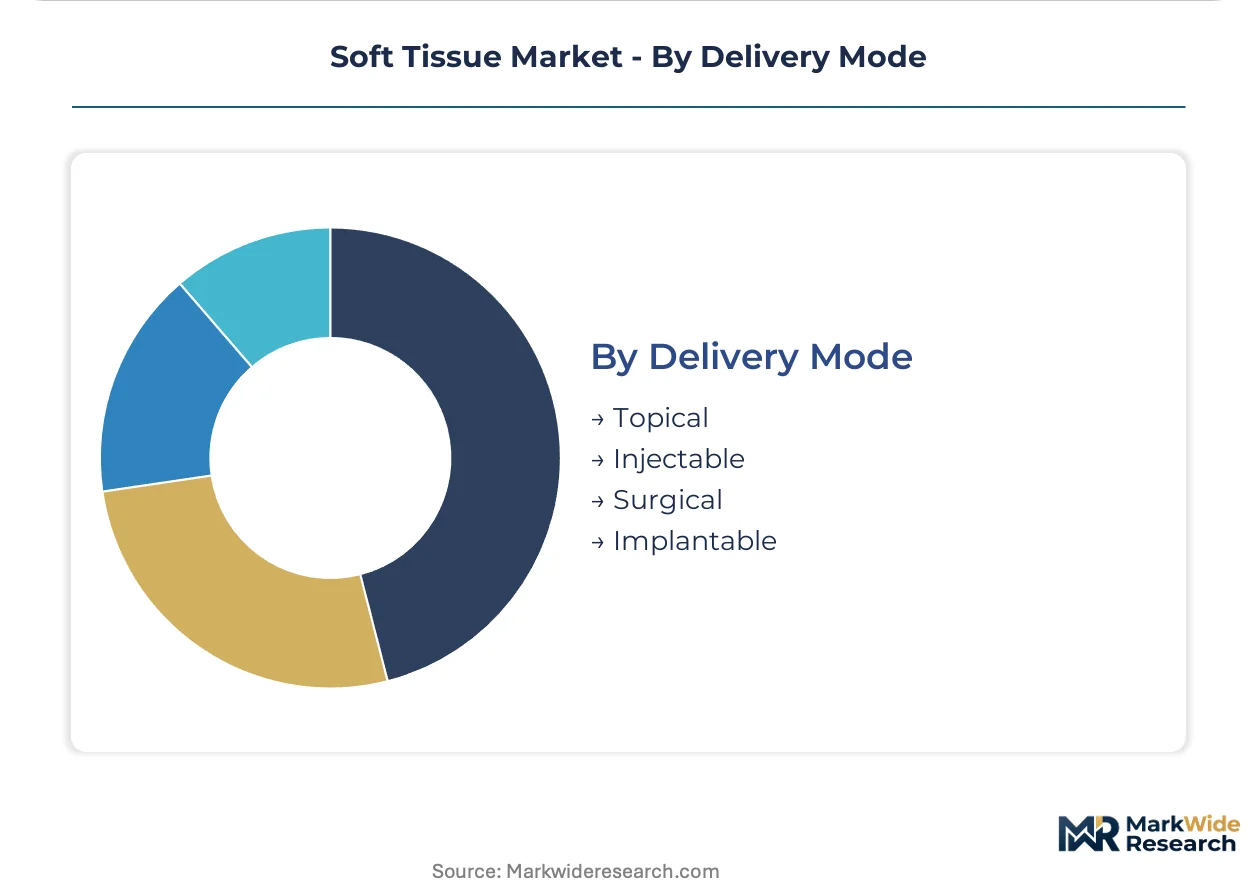
Regulatory classification complexity increases with tissue invasiveness, from cosmetic topical approvals to multi-year implantable PMA pathways.
- Topical:Surface-applied matrices and hydrogels for partial-thickness wound coverage.
- Injectable:Minimally invasive intra-articular and intradermal administration.
- Surgical:Open procedure deployment requiring operative suite infrastructure.
- Implantable:Permanent or resorbable matrices subject to FDA Center for Devices and Radiological Health or Center for Biologics Evaluation and Research oversight, with EU MDR Article 117 clinical evidence requirements extending European market access timelines.
Injectable formats capture outpatient volume migration. Implantable systems retain the highest revenue per procedure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States surgeons favor arthroscopic delivery systems for rotator cuff repair, while European clinicians prioritize chronic wound matrices, and Asian markets concentrate hyaluronic acid injectables in cosmetic dermatology channels.
United States
Ambulatory surgical centers in Texas and Florida are installing dedicated soft tissue repair suites, shifting procedure volume from hospital settings. FDA Center for Biologics Evaluation and Research pathways filter supplier qualification through stringent premarket approval requirements. Greater Boston anchors recombinant protein research, with biotech firms partnering agricultural bioreactor operators to decompose legacy tannery-dependent supply chains.
Germany
Hospital procurement coalitions in North Rhine-Westphalia negotiate bundled contracts across suture, anchor, and matrix categories, reshaping distributor relationships toward manufacturer-direct models. EU MDR Article 117 requirements extend clinical evidence timelines for implantable matrices entering European markets. Baden-Württemberg hosts specialized notified bodies demanding extended follow-up data that exceeds prior CE marking standards.
China
Domestic manufacturers in Jiangsu and Zhejiang provinces scale electrospinning capacity for collagen scaffold production targeting tendon and ligament repair. NMPA biologics oversight imposes multi-year clinical program requirements that consume capital reserves before revenue generation. Yangtze River Delta medical device clusters concentrate decellularization processing facilities serving both domestic consumption and export markets.
Japan
PMDA regulatory frameworks govern soft tissue biologics through premarket approval pathways comparable to FDA stringency, filtering undercapitalized entrants from commercialization. METI industrial policy supports regenerative medicine advanced therapy designations that accelerate qualified product timelines. Kansai region wound care centers demonstrate preference for advanced matrices targeting diabetic ulcer populations with recurring treatment cycles.
Brazil
Cosmetic dermatology clinics in São Paulo and Rio de Janeiro drive Latin American volume for hyaluronic acid injectables, fueled by medical tourism infrastructure and price-sensitive consumer segments. ANVISA pharmaceutical regulation imposes clinical evidence requirements that extend market access timelines relative to United States benchmarks. Southeast metropolitan markets concentrate ambulatory procedure expansion among active aging demographics aged 55-75 seeking minimally invasive repair options.
Soft Tissue Market Competitive Environment
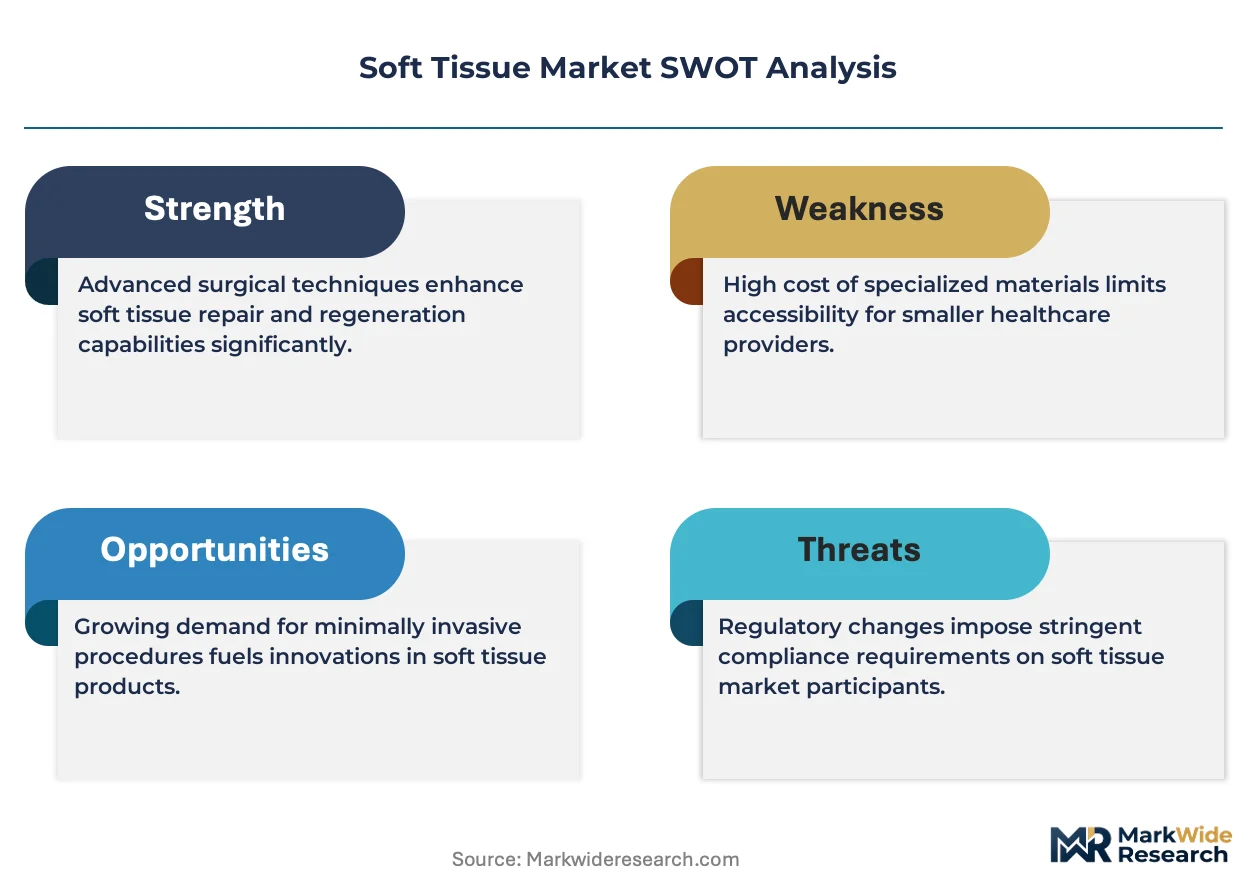
A small set of integrated leaders sits above a broader specialist tier, with orthopedic conglomerates controlling arthroscopic delivery platforms while wound care specialists anchor chronic application segments. The structure rewards firms with dedicated sales forces and ISO 13485 certification that enables supplier qualification across multinational OEM procurement networks. Three archetypes dominate: integrated orthopedic conglomerates with sports medicine portfolios, advanced wound healing specialists targeting diabetic populations, and biologic material innovators with recombinant production capabilities. Competitive moves concentrate on M&A for technology access and strategic partnerships with agricultural bioreactor operators to secure alternative collagen sourcing.
Within the integrated orthopedic tier, Stryker Corporation and Zimmer Biomet exemplify scale-driven positioning through comprehensive sports medicine and rotator cuff repair system offerings. Smith & Nephew Plc occupies a distinct archetype as a wound healing specialist with established formulary placement in chronic diabetic ulcer channels. These three firms represent contrasting pathways to market position: one through arthroscopic platform dominance, another through ambulatory surgery migration, and the third through recurring treatment cycle capture in underserved patient populations.
| Leading Market Players |
|---|
| Stryker Corporation |
| Smith & Nephew Plc |
| Becton, Dickinson and Company |
| Arthrex, Inc. |
| Medtronic Plc |
| Johnson & Johnson |
| Zimmer Biomet |
| Integra LifeSciences |
| Baxter International, Inc. |
| Others |
Value Chain & Pricing Dynamics
Electrospinning capacity utilization above 80 percent in United States and German processing facilities creates scale advantages that compress unit costs for qualified collagen scaffold manufacturers while establishing price floors that exclude smaller batch operators from hospital formulary consideration.
Pricing Analysis
Long-term offtake agreements between orthopedic OEMs and recombinant protein producers anchor pricing stability for high-volume purchasers, while spot-market bovine collagen transactions expose smaller manufacturers to commodity volatility. Pricing stratifies across premium, standard, and economy tiers based on FDA premarket approval status and ISO 13485 certification level. Cost compression in standard-grade matrices is intensifying because hospital procurement coalitions extract volume discounts through bundled suture-anchor-matrix contracts. Ambulatory surgical centers demonstrate the highest price sensitivity due to thin procedure margins, whereas integrated health systems with centralized value analysis committees prioritize supply security over unit cost.
Supply Chain Analysis
Bovine collagen extraction clusters in United States Midwestern processing facilities and Northern Italian tannery regions, creating geographic chokepoints that concentrate raw material sourcing for implantable matrices. Decellularization protocols draw from bovine Achilles tendon, porcine small intestine submucosa, and recombinant tobacco plant expression systems as primary inputs. Single-source vulnerability runs through legacy tannery-dependent suppliers exposed to zoonotic disease transmission risks. Distribution runs through manufacturer-direct sales forces with dedicated orthopedic specialist teams, displacing independent distributors in metropolitan United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arthroscopic delivery platform consolidation is shifting competitive economics toward ecosystem control, as integrated sports medicine portfolios capture procedure volume through interoperability with ambulatory surgical center scheduling systems and electronic health record integration.
For Market Incumbents: Compound platform stickiness by embedding collagen scaffold ordering within proprietary arthroscopic instrument workflows, locking out standalone matrix competitors. Secure backward integration into recombinant protein production through agricultural bioreactor partnerships to neutralize bovine supply concentration risks. Prioritize ISO 13485 certification maintenance to retain supplier qualification across multinational OEM procurement networks facing vendor consolidation pressures.
For New Entrants and Emerging Players: FDA regenerative medicine advanced therapy designation fast-tracks offer accelerated pathways for engineered collagen variants with differentiated mechanical properties. Target chronic diabetic ulcer applications in United States wound care centers, where incumbent formulary placement remains incomplete and Medicare reimbursement cycles favor innovative matrix technologies. Pursue white-label manufacturing partnerships with established distributors lacking captive biologic production capabilities.
For Investors and Strategic Acquirers: Agricultural bioreactor operators with tobacco plant expression capabilities represent the most attractive acquisition archetype, given their role in decomposing legacy tannery-dependent supply chains and compressing raw material cost volatility. Monitor EU MDR notified body backlog resolution as the critical inflection signal for European market access timeline normalization and revenue recognition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Protein Production Partnership | Agricultural bioreactor collaborations in Israel and Singapore secure alternative collagen sourcing outside tannery-dependent supply chains. |
| EU MDR Clinical Evidence Buildout | Extended follow-up data investment enables implantable matrix market access ahead of competitors facing notified body delays. |
| ASC Dedicated Suite Installation | Texas and Florida ambulatory surgical center partnerships concentrate rotator cuff procedure volume outside hospital settings. |
| Chronic Diabetic Ulcer Formulary Placement | Medicare reimbursement optimization in United States wound care centers captures recurring treatment cycle revenue pools. |
| ISO 13485 Certification Expansion | Quality management standardization qualifies suppliers across multinational orthopedic OEM procurement networks undergoing vendor consolidation. |
Study Parameters
A standing panel of orthopedic surgeons, ambulatory surgical center administrators, hospital purchasing committee chairs, and GPO contracts managers provided ongoing calibration against market developments throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body guidance documents. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures to ensure segmentation consistency.
Consistency checks validated volume and value outputs against external benchmarks including regulatory submission timelines and health system capital expenditure disclosures across the analysis window. Segmentation modeling incorporated product type, application, end user, and delivery mode dimensions alongside geographic regulatory cluster differentiation. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, with inputs including ambulatory surgical center infrastructure buildout rates and fellowship program graduation counts.
Decision-makers should treat outputs as directional under assumptions of stable FDA biologics guidance and continued EU MDR implementation trajectory; material deviation in either regulatory pathway would warrant model refresh. Practitioners should keep alternative scenarios live as orthopedic surgeon training pipeline constraints and recombinant protein synthesis cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
North America Neurostimulation Devices Market
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
Critical Care Devices Market
Medical Devices
Global Glucometer Market
Medical Devices
Physiotherapy Laser Wrist Watch Market
Medical Devices
United States Small Bone and Joint Devices Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
Zygomatic and Pterygoid Implants Market
Medical Devices
Percutaneous Nephrostomy Catheters Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Global Photobiostimulation Market
Medical Devices
Prefilled Syringe Small Molecule Market