
 France Respiratory Devices Market | 2026-2036
France Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
France Respiratory Devices Market Foresight
Multi-source procurement for critical ventilator components is hardening across French hospital networks as supply security takes precedence over unit cost minimization. Philips Healthcare sustains broad manufacturing scale across European production hubs, while ResMed Inc. specializes in cloud-connected sleep apnea platforms that dominate home care channels. Drägerwerk AG & Co. KGaA anchors its position through intensive R&D spending on anesthesia and ventilation convergence technologies.
Respiratory devices encompass electromechanical systems engineered to assist, monitor, or replace spontaneous breathing, typically operating at flow rates between 0.5 and 60 liters per minute and pressure ranges from 2 to 40 cm H₂O depending on therapeutic indication. These systems serve acute life support, chronic disease management, and diagnostic monitoring across institutional and ambulatory settings. Ventilators command the largest installed base within French intensive care units, while CPAP machines represent the fastest-expanding product category as obstructive sleep apnea diagnoses multiply through simplified home screening protocols. Sleep apnea treatment applications now attract disproportionate capital allocation from distributors building direct-to-patient subscription models.
ANSM enforces CE marking under the EU Medical Device Regulation alongside France-specific vigilance reporting timelines that compress adverse event disclosure windows relative to neighboring jurisdictions. The country's national health technology assessment body, HAS, conditions reimbursement expansion on demonstrated clinical outcomes, steering manufacturers toward evidence-generation investments rather than pure feature differentiation. Stakeholders must weigh the trade-off between scaling home care automation and preserving direct clinical oversight as reimbursement frameworks evolve toward episode-based payment structures.
Market Dynamics
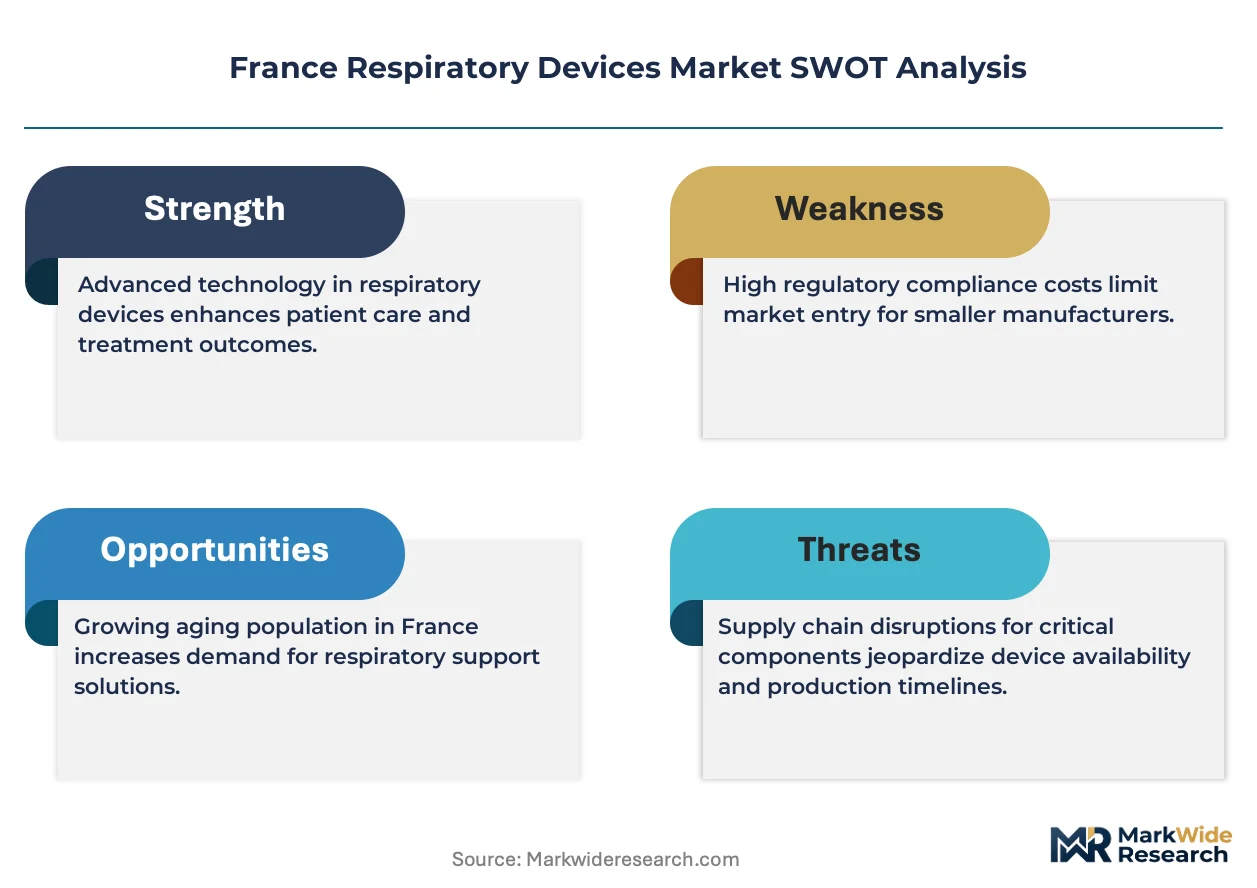
ANSM's post-market surveillance tightening for Class IIb and III devices is compressing clinical evidence generation timelines while forcing manufacturers to restructure quality management systems around real-world performance data capture.
Growth Catalysts
- Hospital-at-home program expansion:Ile-de-France regional health agencies are reimbursing portable oxygen concentrators for COPD patients, creating institutional pull for ambulatory respiratory support equipment.
- EU MDR CE marking pathways:Manufacturers completing MDR technical documentation early are securing notified body priority review, accelerating market access relative to lagging competitors.
- Cloud-connected monitoring platforms:Sleep apnea management is migrating to remote patient monitoring architectures that enable therapy adherence tracking and automated pressure adjustments.
Market Restraints
- Critical component supply concentration:Turbine motors and precision flow sensors rely on a narrow German and Swiss supplier base, exposing French device assemblers to single-source vulnerability.
- Clinical evidence generation costs:ANSM's expanded vigilance reporting requirements demand post-market clinical follow-up studies that add 15-25% to total product lifecycle compliance expenditure.
- Skilled biomedical technician scarcity:Ventilator maintenance and calibration expertise concentrates in Paris and Lyon metropolitan clusters, constraining service network expansion into secondary cities.
Strategic Opportunities
- Occitanie and Provence-Alpes-Côte d'Azur underpenetration:Rural respiratory care infrastructure outside the Paris basin offers first-mover advantage for portable device distributors building direct-to-patient logistics networks.
- AI-enabled diagnostic convergence:Machine learning algorithms analyzing nocturnal oximetry patterns are enabling simplified home sleep apnea screening, expanding addressable patient populations beyond traditional polysomnography channels.
- Episode-based reimbursement pilots:HAS experimentation with bundled payment for chronic respiratory disease management is incentivizing device manufacturers to integrate remote monitoring into therapy protocols.
Industry Challenges
- MDR technical documentation backlog:Notified body capacity constraints are extending CE marking timelines for innovative ventilation modes, delaying product launches by 12-18 months relative to pre-2021 MDR transition periods.
- Legacy hospital IT integration complexity:Cloud-connected respiratory devices must interface with heterogeneous electronic health record systems across AP-HP, CHU, and private clinic networks, fragmenting deployment architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Respiratory Devices Market |
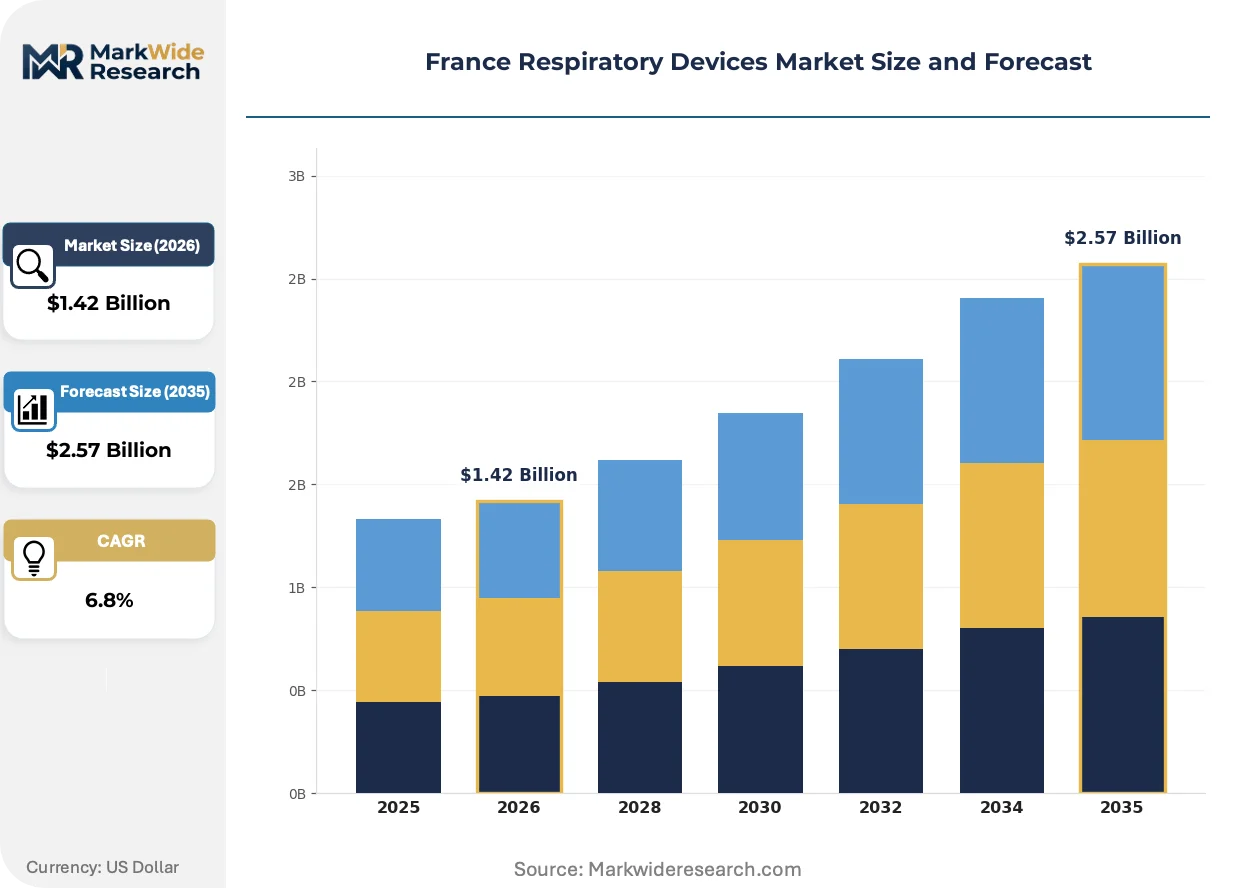
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, Oxygen Concentrators, Nebulizers, CPAP Machines, Pulse Oximeters Application: Chronic Obstructive Pulmonary Disease, Asthma Management, Sleep Apnea Treatment, Pulmonary Rehabilitation, Acute Respiratory Distress End User: Hospitals, Home Care Facilities, Respiratory Clinics, Diagnostic Centers, Emergency Medical Services Distribution Channel: Direct Sales, Medical Distributors, Online Retailers, Pharmacies, Specialty Stores |
| Companies Covered | Fisher & Paykel Healthcare Corporation Limited, GE Healthcare, Philips Healthcare, Becton, Dickinson and Company, Drive DeVilbiss Healthcare, ResMed Inc., Drägerwerk AG & Co. KGaA, Teleflex Incorporated, Medtronic plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Respiratory Devices Market Shifts & Advancements
Respiratory device architecture is converging around continuous data telemetry, algorithmic therapy personalization, and distributed manufacturing footprints that reduce single-point supply dependencies.
Micro-electromechanical flow sensors are integrating with ultrasonic oxygen analyzers to enable closed-loop FiO2 control in portable ventilators. Home care equipment suppliers in the Paris metropolitan corridor are adopting these sensor fusion platforms to meet ANSM accuracy requirements for long-term oxygen therapy reimbursement. The technology is integrating real-time respiratory mechanics monitoring into devices previously limited to preset flow delivery, compressing the functional gap between hospital and home ventilator categories.
ANSM's alignment with EU MDR Article 83 post-market surveillance requirements is mandating systematic literature review and PMCF study protocols for all Class IIb respiratory devices. Manufacturers are restructuring quality management systems to capture real-world performance data through cloud-connected device registries. Intensive care ventilator segments face the steepest compliance burden, with vigilance reporting timelines compressed to 10 days for serious incidents versus 30-day norms in neighboring jurisdictions.
Direct-to-patient subscription models are displacing traditional durable medical equipment distribution for sleep apnea therapy. Distributors are unbundling device provision from mask resupply, creating recurring revenue streams through automated compliance monitoring and remote pressure titration. This behavioral shift concentrates most visibly in Ile-de-France, where urban density and digital health literacy enable same-day delivery logistics for consumable replenishment.
France Respiratory Devices Market Segmentation
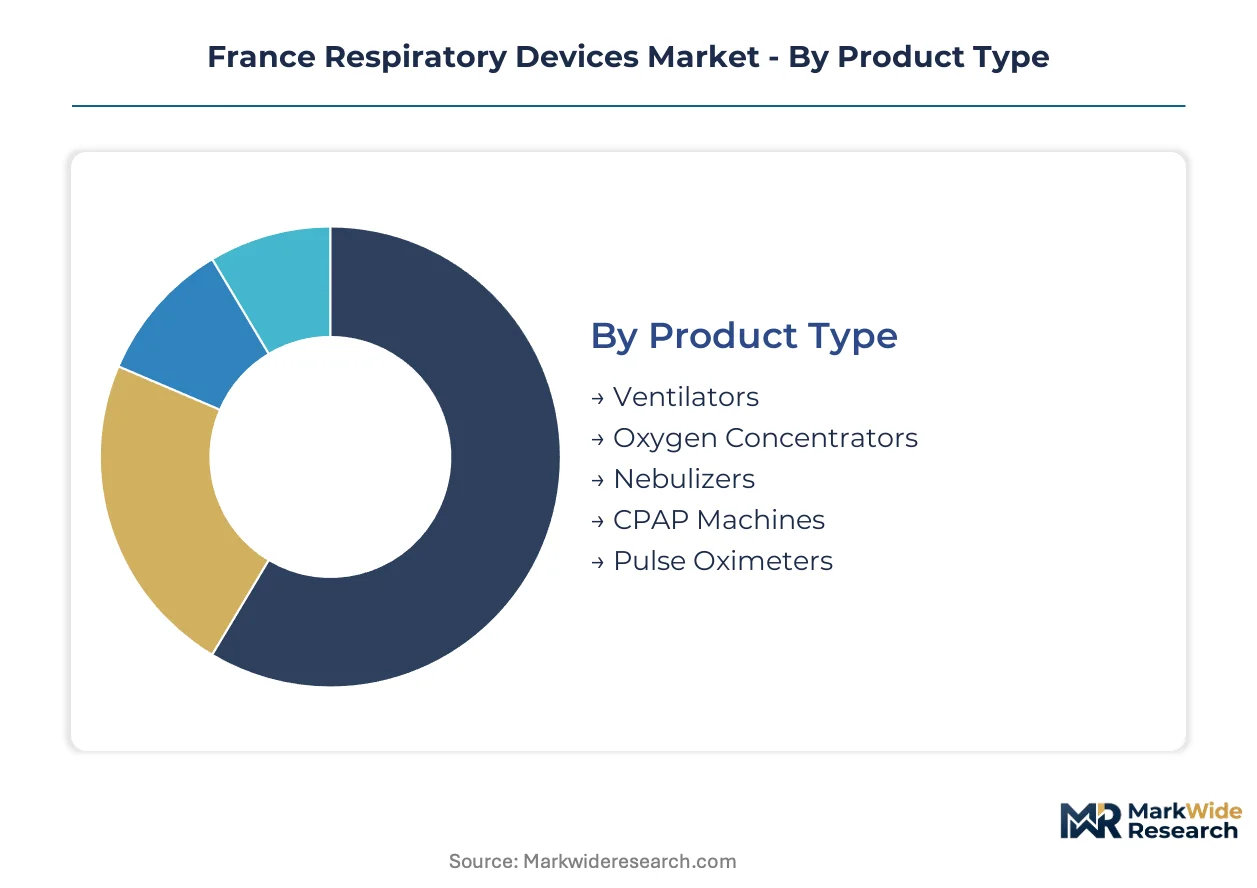
Device specification and therapeutic indication determine procurement pathways across French healthcare networks. ANSM classification tiers and HAS reimbursement codes segment addressable markets by clinical risk and care setting.
Product Type:
Flow generation architecture and pressure modulation capabilities differentiate therapeutic utility across acute and ambulatory environments.
- Ventilators:Electromechanical systems delivering controlled tidal volumes between 50-2000 mL with PEEP capabilities from 0-25 cm H₂O. Demand concentrates in AP-HP intensive care units and regional CHU networks, where invasive ventilation capacity expansion responds to pandemic preparedness mandates.
- CPAP Machines:Continuous positive airway pressure devices generating 4-20 cm H₂O through turbine-driven flow circuits with integrated humidification. Home care facilities in Ile-de-France deploy these most intensively as sleep apnea diagnoses multiply through simplified screening protocols.
- Oxygen Concentrators:Pressure swing adsorption units extracting 90-96% FiO₂ from ambient air at flow rates of 0.5-10 L/min. Portable variants are gaining share fastest in Occitanie rural health networks.
- Nebulizers:Jet and mesh aerosol generators producing 1-5 micron particle distributions for bronchodilator delivery. Respiratory clinics in Lyon and Marseille metropolitan clusters standardize on vibrating mesh platforms for medication efficiency.
- Pulse Oximeters:Photoplethysmography sensors measuring SpO₂ and pulse rate through tissue perfusion analysis. Diagnostic centers deploy multi-parameter variants with waveform display for pre-operative assessment protocols.
Mature deployment sits with ventilators. Newer deployment is concentrated in CPAP machines.
Application:
Pathophysiology severity and disease chronicity determine device selection criteria and reimbursement authorization pathways.
- Sleep Apnea Treatment:Obstructive and central sleep disordered breathing requiring positive pressure intervention or adaptive servo-ventilation. Ile-de-France home care programs drive volume through direct-to-patient logistics networks and remote adherence monitoring.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation requiring long-term oxygen therapy and non-invasive ventilation during exacerbations. HAS reimbursement for portable concentrators in Occitanie and Provence-Alpes-Côte d'Azur is expanding addressable populations beyond hospital discharge.
- Asthma Management:Reversible airway obstruction treated through metered-dose inhaler coordination aids and peak flow monitoring. Pediatric respiratory clinics in Paris prioritize nebulizer compatibility with bronchodilator formulations.
- Acute Respiratory Distress:Rapid-onset hypoxemic respiratory failure demanding invasive mechanical ventilation with lung-protective strategies. SAMU-SMUR emergency medical services specify transport ventilators with 6-hour battery autonomy.
- Pulmonary Rehabilitation:Structured exercise and breathing retraining programs utilizing supplemental oxygen and ventilatory muscle training devices. Regional health agencies in Grand Est pilot bundled payment models for post-exacerbation recovery.
Established therapeutic protocols govern COPD management. Emerging protocols are reshaping sleep apnea care delivery.
End User:
Care setting infrastructure and clinical oversight intensity determine device specification requirements and service contract structures.
- Hospitals:Acute care institutions with 24-hour biomedical engineering coverage and centralized gas supply infrastructure. AP-HP and CHU networks specify ventilator fleets with centralized telemetry and automated alarm escalation.
- Home Care Facilities:Ambulatory service providers managing long-term oxygen and non-invasive ventilation through visiting nurse networks. Ile-de-France agencies are expanding fastest as hospital-at-home programs gain reimbursement traction.
- Respiratory Clinics:Specialized outpatient facilities conducting pulmonary function testing and sleep disorder diagnostics. Lyon and Marseille clusters concentrate expertise for complex titration protocols.
- Diagnostic Centers:Independent imaging and laboratory facilities incorporating overnight oximetry and spirometry into pre-operative assessment. Private operators in Paris metropolitan corridor invest in AI-enabled sleep study interpretation.
- Emergency Medical Services:Pre-hospital care providers requiring ruggedized portable ventilators and oxygen delivery systems. SAMU-SMUR specifications prioritize battery duration and helicopter transport compatibility.
Hospital procurement dominates capital equipment acquisition. Home care facilities are expanding most quickly as reimbursement shifts toward ambulatory models.
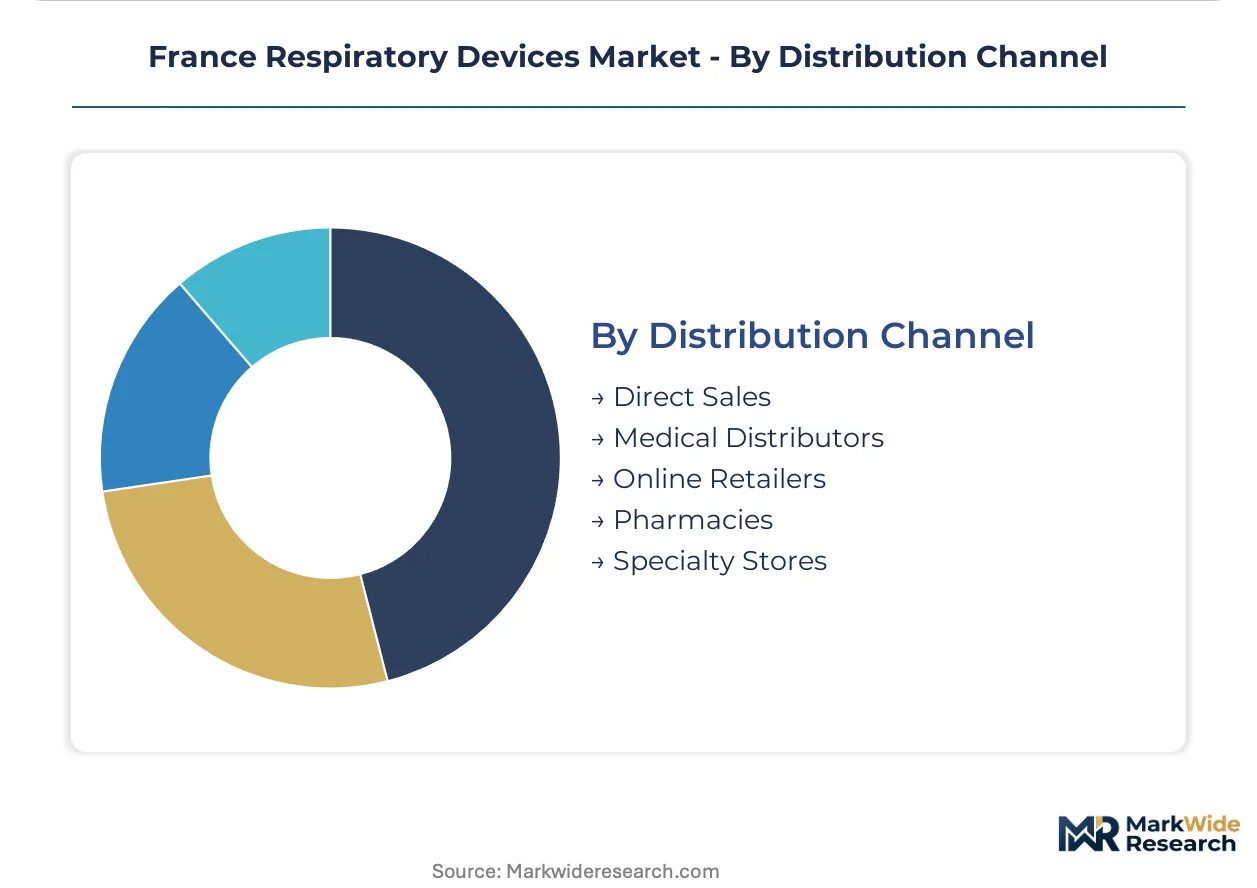
Distribution Channel:
Customer relationship intensity and technical service requirements determine channel economics and manufacturer margin structures.
- Medical Distributors:Specialized intermediaries with biomedical technician networks and consignment inventory arrangements. Regional distributors in Provence-Alpes-Côte d'Azur maintain ventilator fleets for emergency deployment contracts.
- Direct Sales:Manufacturer-employed account executives managing hospital group purchasing organization negotiations. Philips Healthcare and ResMed deploy direct teams for AP-HP and large CHU networks.
- Online Retailers:E-commerce platforms enabling patient-initiated procurement of CPAP masks and consumables. Ile-de-France urban density supports same-day delivery logistics for subscription replenishment.
- Pharmacies:Community dispensaries authorized for limited respiratory device distribution under pharmacist supervision. Rural networks in Brittany and Normandy leverage pharmacy points for pulse oximeter accessibility.
- Specialty Stores:Durable medical equipment suppliers with fitting services for masks and interfaces. Sleep-focused retailers in Paris offer pressure titration and compliance coaching.
Direct sales relationships anchor hospital procurement. Online retailers are capturing share fastest in home care consumables.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision sensor manufacturing clusters in Bavaria and Baden-Württemberg anchor component supply for French device assemblers, while turbine motor fabrication concentrates in Swiss industrial zones bordering the Rhine. This cross-border production geography shapes procurement risk profiles across metropolitan France.
Île-de-France
Hospital-at-home program expansion drives portable oxygen concentrator demand through AP-HP network procurement. ANSM vigilance reporting timelines compress adverse event disclosure to 10 days for Class III devices. Paris metropolitan corridor concentrates sleep apnea diagnostic centers deploying AI-enabled home screening platforms.
Auvergne-Rhône-Alpes
Lyon biomedical engineering clusters sustain ventilator maintenance expertise scarce elsewhere in secondary cities. HAS reimbursement pilots for bundled COPD management incentivize remote monitoring integration. Saint-Étienne manufacturing subcontractors specialize in precision flow sensor calibration for portable ventilator producers.
Provence-Alpes-Côte d'Azur
Rural respiratory care infrastructure underpenetration offers first-mover advantage for direct-to-patient logistics networks. Regional health agencies expand portable concentrator reimbursement for post-exacerbation discharge. Marseille respiratory clinics concentrate complex titration protocol expertise serving Mediterranean basin referrals.
Occitanie
Rural health network gaps in portable device distribution attract distributor investment in automated replenishment logistics. HAS authorization for long-term oxygen therapy reimbursement outside hospital settings expands addressable patient populations. Toulouse aerospace supplier networks pivot toward medical device component precision manufacturing.
Hauts-de-France
Aging industrial demographics concentrate COPD prevalence rates above national averages, driving home oxygen therapy demand. Regional hospital networks participate in SAMU-SMUR emergency ventilator fleet standardization programs. Lille metropolitan biomedical service providers extend maintenance coverage into Belgian border health networks.
France Respiratory Devices Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and cloud-connected platform architectures. Market structure consolidates around three tiers: diversified health technology conglomerates with full portfolio coverage, sleep therapy specialists with direct-to-patient subscription infrastructure, and regional distributors with emergency deployment service contracts. Dominant competitive moves include M&A for notified body technical documentation assets and strategic partnerships for AI-enabled diagnostic algorithm licensing.
Within the diversified technology tier, Philips Healthcare and GE Healthcare occupy positions spanning hospital capital equipment through home care automation. ResMed Inc. exemplifies the sleep therapy specialist archetype with cloud-connected platform concentration. Drägerwerk AG & Co. KGaA anchors the anesthesia-ventilation convergence segment through intensive R&D positioning. Fisher & Paykel Healthcare Corporation Limited represents humidification and respiratory interface specialization, while Medtronic plc sits within the broader medical device conglomerate structure with critical care portfolio breadth.
| Leading Market Players |
|---|
| Fisher & Paykel Healthcare Corporation Limited |
| GE Healthcare |
| Philips Healthcare |
| Becton, Dickinson and Company |
| Drive DeVilbiss Healthcare |
| ResMed Inc. |
| Drägerwerk AG & Co. KGaA |
| Teleflex Incorporated |
| Medtronic plc |
| Others |
Supply & Pricing Matrix
Cloud-connected platform architectures are compressing service delivery costs while concentrating procurement leverage among distributors with direct-to-patient logistics capabilities. This technology shift simultaneously reduces per-unit hardware margins and elevates recurring revenue streams through subscription-based monitoring services, reshaping how manufacturers and buyers negotiate total cost of ownership across Ile-de-France and secondary city networks.
Pricing Analysis
Extended warranty and preventive maintenance bundling separates premium ventilator contracts from unbundled CPAP transactions in home care channels. Three-tier pricing structure across premium, standard, and economy levels reflects ANSM classification tiers and HAS reimbursement codes rather than raw manufacturing cost. Cost compression in portable oxygen concentrators is intensifying because Occitanie regional health agencies are expanding competitive tender frameworks. Hospital procurement committees at AP-HP and CHU networks exhibit lowest price sensitivity due to pandemic preparedness mandates, while rural home care facilities in Brittany and Normandy face strict budget ceilings.
Supply Chain Analysis
Dual-sourcing qualification requirements for turbine motors and precision flow sensors are hardening across French hospital networks as supply security takes precedence over unit cost minimization. Component fabrication draws from German and Swiss industrial zones bordering the Rhine, with pressure swing adsorption membrane production anchored in Belgian chemical processing clusters. Single-source vulnerability concentrates in micro-electromechanical sensor calibration equipment, exposing assemblers to extended lead time volatility. Distribution runs through specialized medical distributors with biomedical technician networks and consignment inventory arrangements serving AP-HP and regional CHU networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithmic therapy personalization is displacing preset-flow device architectures, creating transition risk for manufacturers with legacy product portfolios. Cloud-connected monitoring platforms now define competitive minimums rather than premium differentiation.
For Market Incumbents: Lock in notified body relationships and MDR technical documentation assets before capacity constraints extend CE marking timelines further. Prioritize backward integration into precision sensor calibration capabilities to reduce German and Swiss supplier dependency. Defend against sleep apnea therapy commoditization by embedding AI-enabled diagnostic algorithms that create switching costs for direct-to-patient subscription platforms.
For New Entrants and Emerging Players: Direct-to-patient e-commerce routes offer lowest barrier to entry for CPAP mask and consumable replenishment in Ile-de-France urban corridors. Target Occitanie and Provence-Alpes-Côte d'Azur rural respiratory care infrastructure gaps where distributor service networks remain underdeveloped. Partner with regional health agencies piloting episode-based reimbursement for chronic respiratory disease management to secure preferential device placement.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified health technology conglomerates seeking cloud-connected platform assets and notified body technical documentation libraries. Long-term viability hinges on regulatory compliance infrastructure rather than pure R&D differentiation. Watch ANSM vigilance reporting timeline compression as inflection indicator for compliance cost escalation and market consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR CE Marking Pathway | Early completion secures notified body priority review and accelerates market access relative to lagging competitors. |
| Hospital System Partnership | AP-HP network procurement contracts anchor ventilator fleet standardization and create multi-year revenue visibility. |
| Software Companion Development | Cloud-connected adherence tracking enables automated pressure titration and locks in recurring subscription revenue streams. |
| Reimbursement Strategy | HAS bundled payment pilot alignment positions manufacturers for episode-based chronic respiratory disease management contracts. |
| Backward Integration | In-house precision flow sensor calibration reduces single-source vulnerability to German and Swiss supplier concentration. |
Research Methodology
Independent corroboration across hospital procurement database analysis, GPO contract review, and ANSM vigilance registry examination underwrites the qualitative findings. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and home care facility administrators combined with secondary validation from HAS reimbursement authorization records, EU MDR notified body disclosure filings, and regional health agency tender documentation. Bottom-up device shipment modeling and top-down healthcare expenditure allocation triangulate market sizing across the analysis window.
Comparable-period anchoring to pre-pandemic ventilator deployment baselines and post-MDR transition CE marking velocity establishes the forecast framework. Segmentation dimensions modeled include product type, therapeutic application, end-user care setting, and distribution channel complexity, with regional reimbursement policy variation as an additional cross-cutting dimension. CAGRs derive from installed base replacement cycles, hospital-at-home program expansion trajectories, and sleep apnea diagnosis rate trends. Forecast inputs incorporate ANSM vigilance reporting burden estimates and HAS technology assessment timeline assumptions.
The model holds under stable EU MDR implementation timelines and continued HAS reimbursement expansion for ambulatory respiratory care; deviation in notified body capacity constraints or regional health agency budget austerity would shift the outlook materially. Forecasts reflect assumptions about cloud-connected platform adoption velocity and direct-to-patient logistics network maturation. Deviation in AI-enabled home sleep apnea screening penetration or turbine motor supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Non- Resorbable Cranial Fixation System Market
Medical Devices
Fluorescence-Guided Surgery Systems Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Brazil Aesthetic Equipment Market
Medical Devices
Uterine Fibroid Embolization Devices Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Body Contouring Devices and Procedures Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Global Artificial Organ Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
3D Printed Medical Implants Market