
 At-Home Laser Hair Removal Devices Market | 2026-2036
At-Home Laser Hair Removal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
At-Home Laser Hair Removal Devices Market Insights
A capital-intensity divergence between players is rotating competitive advantage toward firms with in-house semiconductor sourcing and clinical validation infrastructure. Ulike leverages its Shenzhen manufacturing base to control diode laser supply chains and compress unit economics. Philips Lumea sustains premium positioning through dermatological co-development programs and proprietary SenseIQ skin-tone adaptation. Tria Beauty anchors its North American presence with FDA-cleared 810 nm diode platforms that command higher average selling prices in specialty retail.
At-home laser hair removal devices are handheld or corded appliances that emit coherent or filtered broadband light at wavelengths between 600 nm and 1200 nm to thermally disable hair follicles through selective photothermolysis, with built-in skin-contact sensors and cooling mechanisms to prevent epidermal injury. The primary commercial purpose is to offer consumers a repeatable, lower-cost alternative to professional clinic sessions for semi-permanent hair reduction across body areas. IPL devices dominate unit shipments due to lower bill-of-materials costs and broader skin-tone compatibility, while diode laser systems capture disproportionate margin pools among safety-conscious buyers seeking clinical-grade outcomes. The online distribution channel is expanding fastest as direct-to-consumer brands bypass traditional retail markups, though retail stores still occupy critical touchpoints for first-time purchasers requiring physical demonstration.
FDA 510(k) clearance and MDR compliance in Europe are raising barriers to entry by mandating controlled clinical studies for optical fluence claims and thermal injury thresholds. The EU AI Act and GDPR intersect with connected-device variants that collect skin-tone data, forcing manufacturers to navigate dual compliance frameworks for hardware safety and algorithmic transparency. Stakeholders must monitor evolving state-level laser device classifications in the United States and emerging GB standard harmonization in China to anticipate where regulatory arbitrage opportunities will open or close.
Market Dynamics
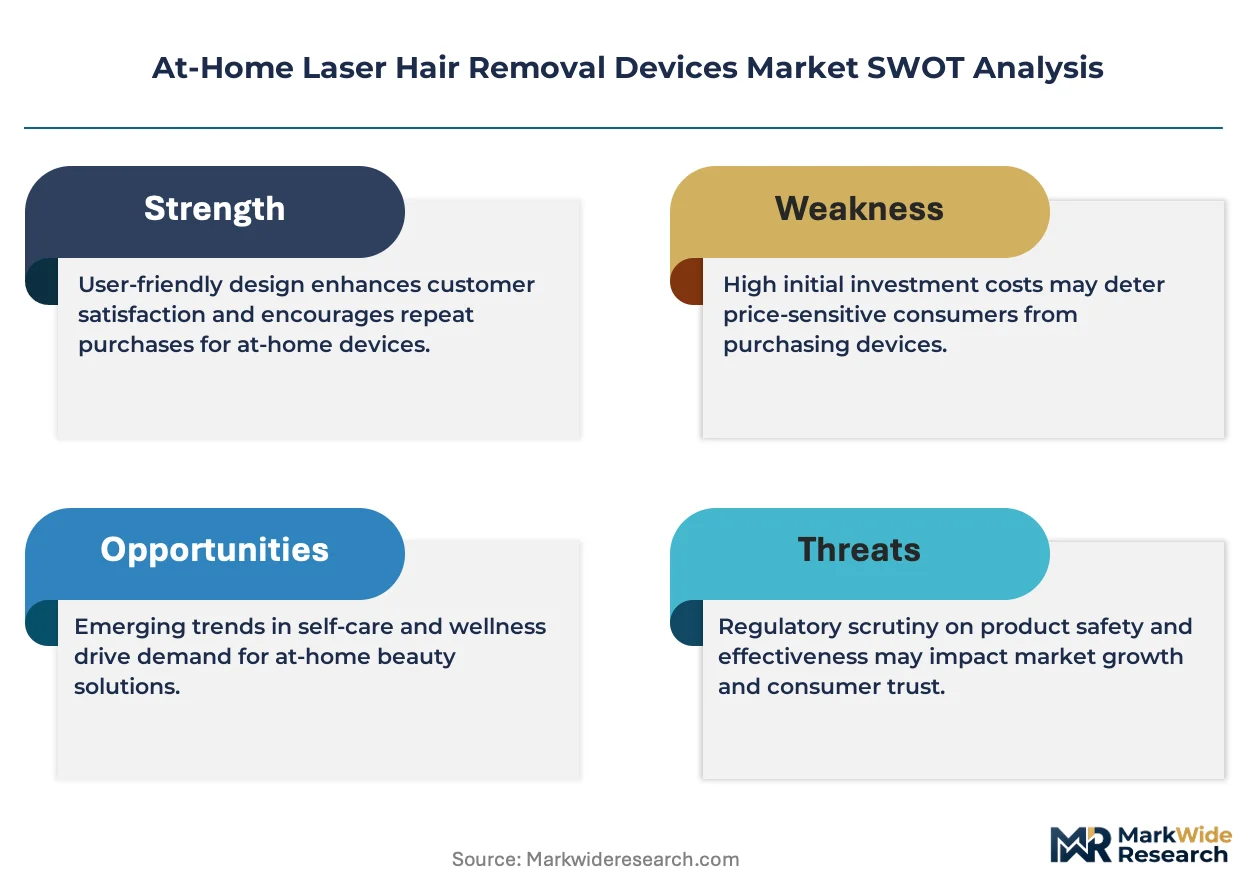
IPL device commoditization is compressing margins across the entry-level tier while diode laser platforms consolidate premium positioning through clinical-grade safety certifications and proprietary cooling architectures.
Growth Catalysts
- FDA 510(k) clearance acceleration:Streamlined premarket notification pathways for optical fluence devices are reducing time-to-market for compliant manufacturers in the United States.
- Beauty-conscious millennials and Gen Z consumers:These cohorts normalize at-home aesthetic routines through social media validation and dermatologist endorsement channels.
- E-commerce penetration:Direct-to-consumer distribution models bypass traditional retail markups and enable subscription-based consumable revenue streams.
Market Restraints
- GaAs diode supply concentration:Gallium arsenide semiconductor sourcing clusters in East Asian foundries, creating single-source vulnerability for diode laser manufacturers.
- MDR clinical study requirements:European Medical Device Regulation mandates controlled thermal injury threshold studies, extending compliance timelines and capital requirements.
- Professional clinic substitution:Medical spa chains offer bundled pricing and physician supervision that undermines consumer willingness to pay for handheld alternatives.
Strategic Opportunities
- Connected-device AI integration:Skin-tone sensing algorithms paired with mobile apps enable personalized treatment protocols and recurring software revenue.
- GB standard harmonization in China:Emerging national safety benchmarks for optical output create first-mover advantage for compliant foreign entrants.
- Men's grooming vertical expansion:Underpenetrated male demographic for body hair management represents white-space positioning beyond traditional female marketing.
Industry Challenges
- Biomedical optics talent scarcity:Shortage of engineers with combined laser physics and dermatological safety expertise constrains R&D velocity.
- EU AI Act algorithmic transparency:Connected devices collecting skin-tone data face dual compliance burden for hardware safety and explainable AI documentation.
- State-level laser classification fragmentation:Inconsistent medical device versus consumer appliance categorization across United States jurisdictions complicates national distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | At-Home Laser Hair Removal Devices Market |
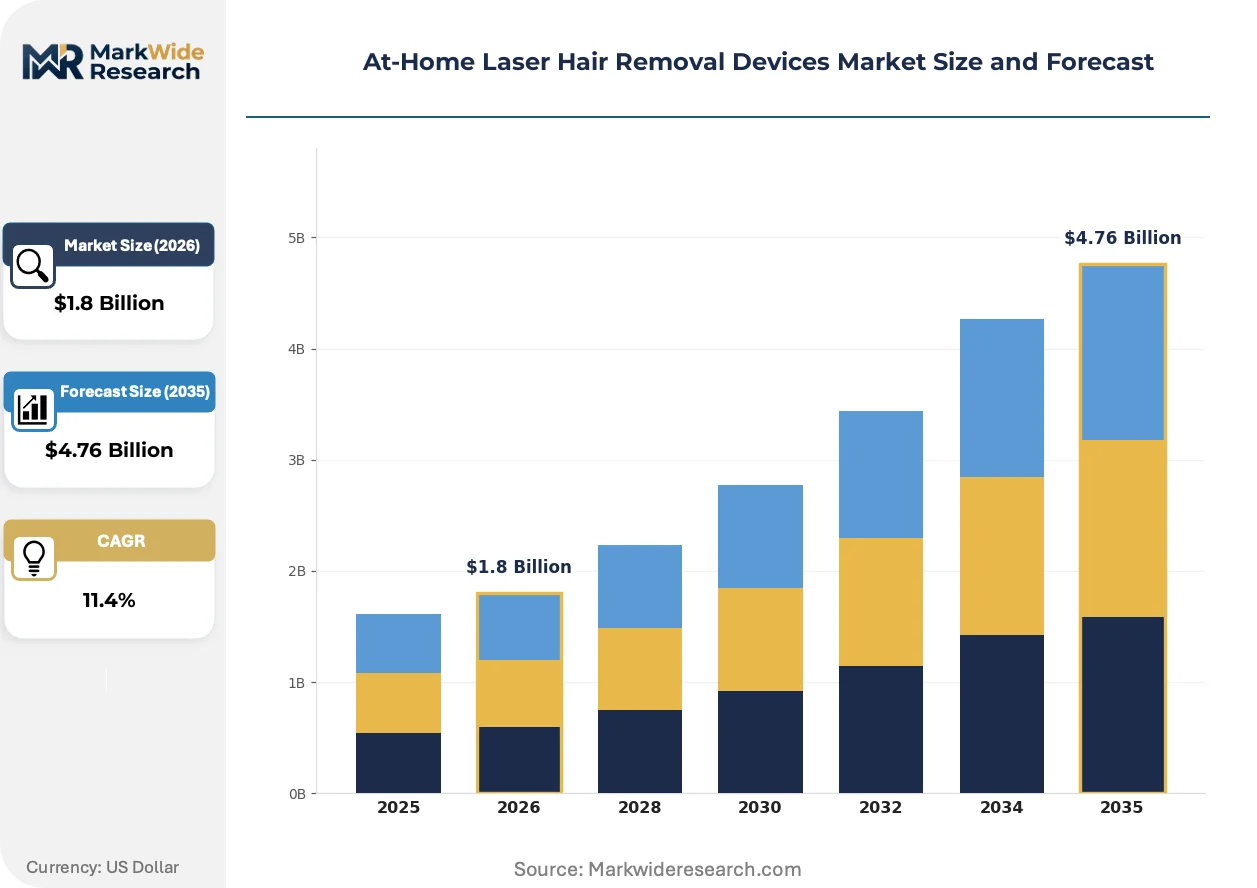
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Laser, IPL, Ruby Laser, Alexandrite Laser End User: Women, Men, Professional Use, Clinics Technology: Pulsed Light, Continuous Wave, Fractional Laser, Q-Switched Laser Distribution Channel: Online, Retail Stores, Direct Sales, Distributors |
| Companies Covered | Braun, Ulike, RoseSkinCo, Nood, SmoothSkin, Tria Beauty, Philips Lumea, CurrentBody Skin, Silkn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
At-Home Laser Hair Removal Devices Market Trends and Innovations
Semiconductor miniaturization and intelligent skin-sensing algorithms are redefining device architecture, while regulatory convergence around optical safety benchmarks reshapes competitive entry barriers across major economies.
Multi-wavelength diode arrays with integrated melanin detection sensors are displacing fixed-spectrum IPL platforms in premium consumer segments. Safety-conscious buyers in Germany and the United States prioritize clinical-grade outcomes over unit economics. This displacement is compressing addressable margin pools for manufacturers lacking proprietary wavelength-tuning capabilities.
EU AI Act intersection with MDR compliance is forcing algorithmic transparency documentation for connected devices processing biometric skin data. Manufacturers must now maintain dual audit trails for hardware thermal safety and machine-learning decision logic. European market entrants with pre-existing GDPR infrastructure capture compliance cost advantages over hardware-only competitors.
Subscription-based consumable models are disrupting traditional one-time device purchases through recurring filter cartridge and cooling gel revenue. Direct-to-consumer brands with captive mobile app ecosystems lock in replacement cycles that retail-dependent competitors cannot replicate. This behavioral shift concentrates lifetime value capture among vertically integrated platforms in the United States and China.
At-Home Laser Hair Removal Devices Market Segmentation
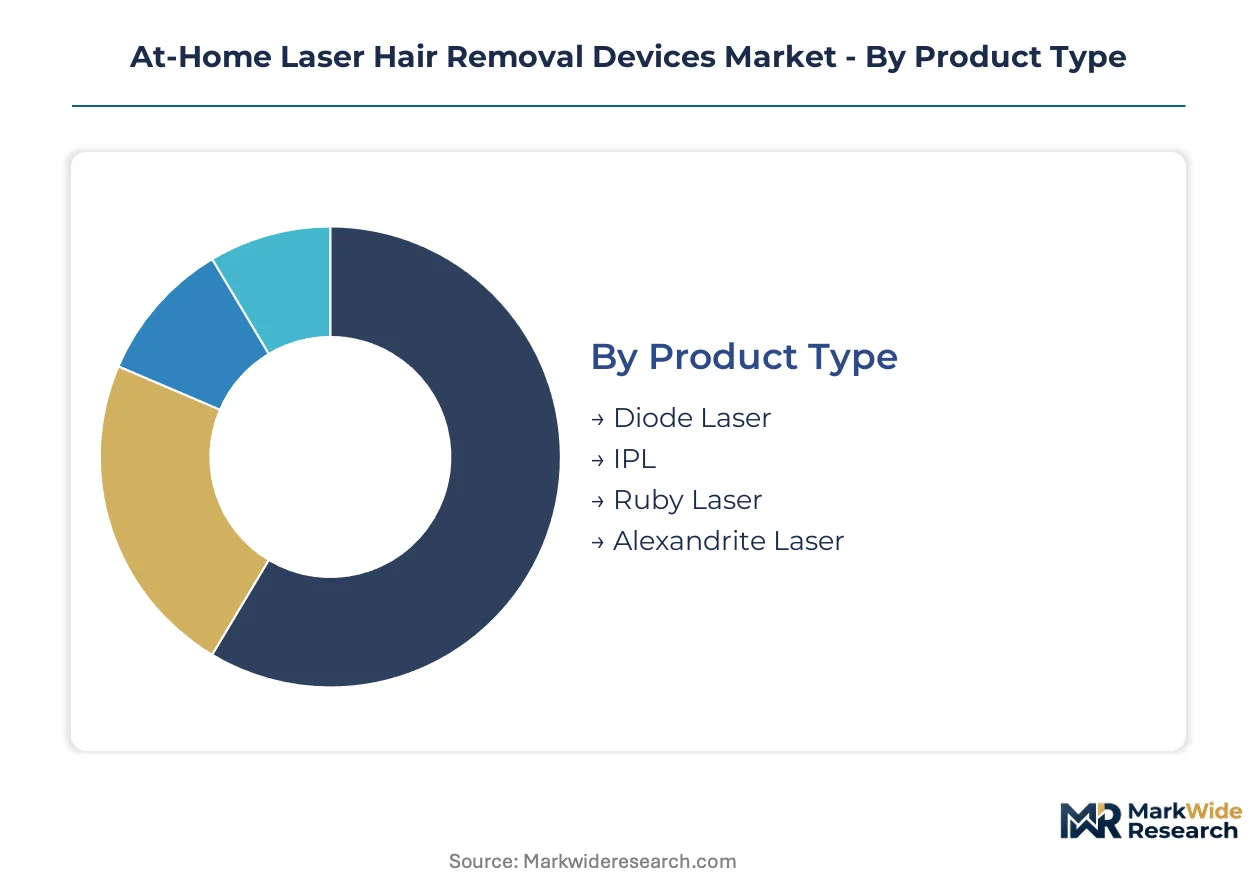
At-home laser hair removal devices fragment across four critical dimensions that determine pricing power, regulatory pathway, and channel strategy. Product type and technology choices lock manufacturers into specific semiconductor supply chains and clinical validation requirements. Distribution channel selection increasingly separates direct-to-consumer disruptors from legacy retail-dependent incumbents.
Product Type:
Domestic demand concentrates in IPL and diode laser platforms across the United States, Germany, and China, while ruby and alexandrite systems remain export-dependent specialty segments serving clinical-adjacent consumers.
- Diode Laser:These devices deploy gallium arsenide semiconductor arrays emitting coherent light at 810 nm, with integrated thermoelectric cooling modules preventing epidermal injury. Demand clusters among safety-conscious buyers in Germany and the United States seeking clinical-grade outcomes, though GaAs supply concentration in East Asian foundries creates procurement vulnerability.
- IPL:Intense pulsed light platforms utilize xenon flashlamps with cut-off filters delivering broadband wavelengths between 600-1200 nm, achieving lower bill-of-materials costs through commodity optical components. China and the United States drive volume shipments as beauty-conscious millennials normalize at-home aesthetic routines through social media validation.
- Ruby Laser:Chromium-doped aluminum oxide crystal systems emitting at 694 nm target specific melanin absorption peaks for lighter skin tones.
- Alexandrite Laser:Titanium-sapphire based platforms at 755 nm wavelength occupy premium positioning for consumers with Fitzpatrick skin types I-III.
IPL holds the largest share; momentum sits with diode laser systems gaining share fastest among safety-certified premium buyers.
End User:
Cost tier stratification separates mass-market personal use from professional-grade equipment requiring FDA 510(k) or MDR compliance documentation and clinical training support infrastructure.
- Women:Traditional core demographic driving replacement cycles for body hair management across legs, underarms, and bikini areas, with subscription-based filter cartridge models capturing recurring revenue through captive mobile app ecosystems in the United States.
- Men:Underpenetrated white-space segment expanding into chest, back, and facial hair grooming as male aesthetic routines normalize through influencer marketing and dermatologist endorsement channels in Germany and China.
- Professional Use:Licensed aesthetician-operated devices requiring higher optical fluence outputs and comprehensive liability insurance coverage.
- Clinics:Medical spa chains seeking bundled pricing advantages through physician-supervised treatment protocols.
Women's personal use dominates volume; men's grooming represents the steepest expansion trajectory as marketing pivots beyond traditional female targeting.
Technology:
Application requirements dictate pulse structure selection, with hair follicle thermal damage thresholds varying significantly across anatomic sites and skin phototypes.
- Pulsed Light:High-peak-power, short-duration energy delivery enables selective photothermolysis of melanin-rich follicles while sparing surrounding tissue, with integrated skin-contact sensors mandating FDA clearance for optical fluence claims in the United States.
- Continuous Wave:Sustained emission platforms historically confined to professional settings due to elevated thermal injury risk, now emerging in consumer variants with real-time epidermal temperature feedback.
- Fractional Laser:Microbeam array technology creating microscopic treatment zones for faster healing and reduced downtime.
- Q-Switched Laser:Nanosecond pulse duration systems primarily deployed for pigmented lesion treatment with limited hair reduction applications.
Pulsed light commands installed base leadership; continuous wave platforms are climbing the fastest as cooling architectures improve.
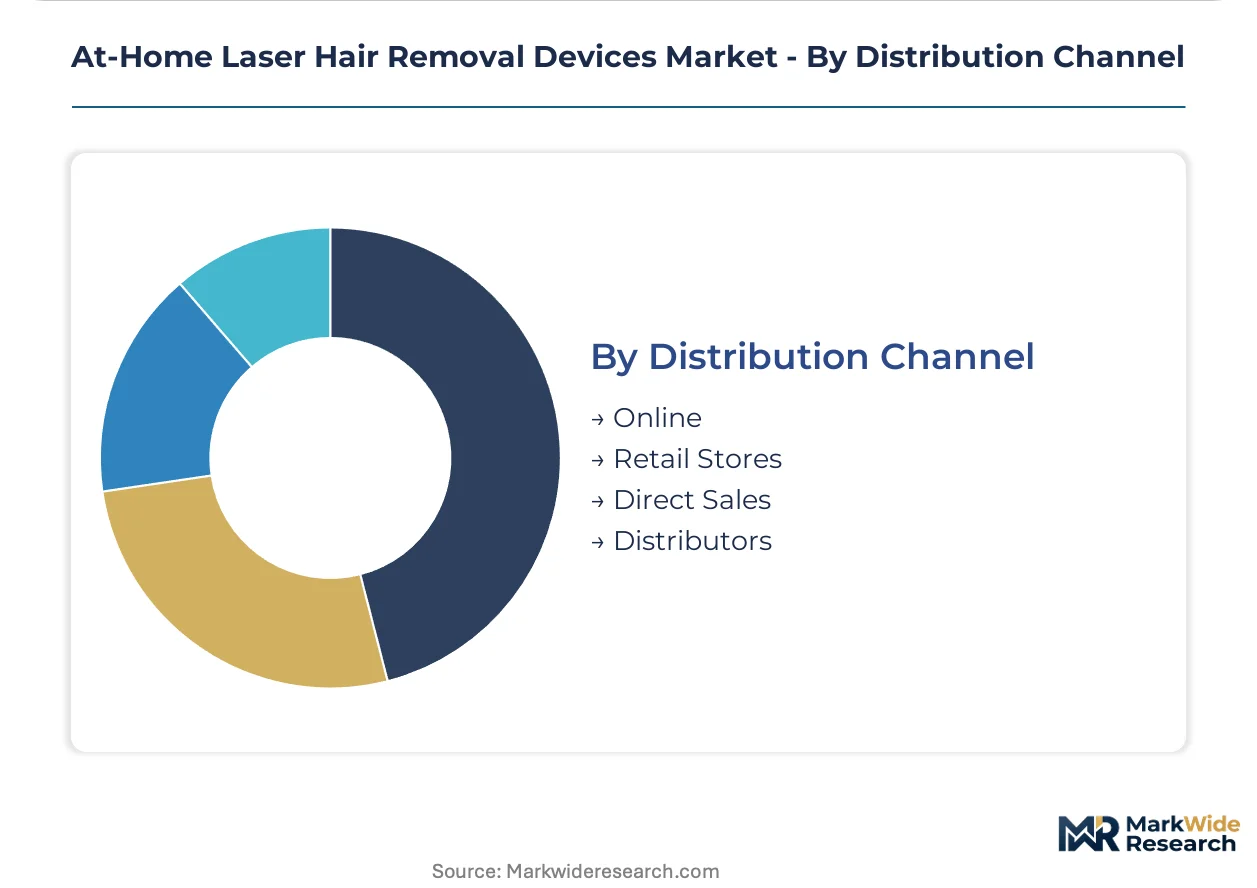
Distribution Channel:
Volume concentration tilts toward e-commerce as direct-to-consumer brands bypass traditional retail markups, though physical demonstration remains critical for first-time purchaser conversion.
- Online:Direct-to-consumer platforms and marketplace aggregators enable subscription-based consumable revenue streams and personalized treatment protocol delivery through connected-device mobile apps, with China and the United States leading penetration rates.
- Retail Stores:Specialty beauty retailers and pharmacy chains provide tactile demonstration and immediate fulfillment for skeptical first-time buyers requiring physical product interaction before purchase commitment.
- Direct Sales:Manufacturer-owned channels capturing full margin stack through proprietary e-commerce infrastructure and telehealth consultation integration.
- Distributors:Third-party logistics networks serving fragmented geographic markets with localized regulatory compliance support and after-sales service capacity.
Online channels hold the largest share; retail stores retain defensive positioning for demographic expansion beyond early adopter cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany and the United States where clinical-grade certification commands consumer willingness to pay, while volume manufacturing advantages cluster in China's Pearl River Delta corridor.
United States
Beauty-conscious millennials and Gen Z consumers normalize at-home aesthetic routines through dermatologist endorsement channels and social media validation. FDA 510(k) clearance pathways for optical fluence devices raise compliance barriers while streamlining time-to-market for qualified manufacturers. California's Silicon Valley and Greater Boston host connected-device startups integrating AI skin-sensing algorithms with mobile app ecosystems.
China
Domestic demand concentrates in IPL platforms as lower bill-of-materials costs enable mass-market penetration across tier-one and tier-two cities. Emerging GB standard harmonization for optical output safety creates first-mover positioning for compliant foreign entrants alongside domestic manufacturers. Shenzhen anchors diode laser semiconductor sourcing with captive gallium arsenide foundry capacity serving regional OEM assembly networks.
Germany
Safety-conscious buyers prioritize clinical-grade outcomes over unit economics, consolidating premium positioning for diode laser platforms with proprietary cooling architectures. MDR clinical study requirements for thermal injury threshold documentation extend compliance timelines while filtering out undercapitalized competitors. Bavaria's precision optics cluster around Munich supplies thermoelectric cooling modules and melanin detection sensors to device integrators.
Japan
Meticulous skin-tone adaptation standards drive demand for multi-wavelength platforms with real-time epidermal feedback systems. PMDA regulatory frameworks for home-use optical devices mandate extensive biocompatibility testing that favors established manufacturers with clinical validation infrastructure. Kanto region's Tokyo-Osaka industrial corridor concentrates distribution partnerships linking domestic OEMs to specialty beauty retail channels.
United Kingdom
E-commerce penetration rates for direct-to-consumer brands bypass traditional retail markups while enabling subscription-based consumable revenue streams. GDPR infrastructure requirements for connected devices collecting biometric skin data create compliance cost advantages for manufacturers with pre-existing data governance frameworks. London's fintech and health-tech crossover ecosystem supports telehealth consultation integration with proprietary device platforms.
At-Home Laser Hair Removal Devices Market Competitive Landscape
Concentration sits with vertically integrated manufacturers controlling in-house semiconductor sourcing and clinical validation infrastructure. The vendor base stratifies across three tiers: premium players with dermatological co-development programs, mid-market specialists leveraging Shenzhen manufacturing economies, and entry-level IPL assemblers competing on unit economics. Strategic moves center on M&A activity targeting AI skin-sensing algorithm developers and capacity expansion into gallium arsenide diode foundry partnerships.
Among Asia-Pacific-based manufacturers, Ulike exemplifies the vertically integrated archetype with Shenzhen manufacturing control over diode laser supply chains. Tria Beauty anchors the North American premium tier through FDA-cleared positioning in specialty retail channels. Philips Lumea occupies the dermatological co-development vector with proprietary skin-tone adaptation technologies. Braun represents the diversified consumer appliance conglomerate leveraging cross-category brand equity into optical beauty devices.
| Leading Market Players |
|---|
| Braun |
| Ulike |
| RoseSkinCo |
| Nood |
| SmoothSkin |
| Tria Beauty |
| Philips Lumea |
| CurrentBody Skin |
| Silkn |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for gallium arsenide diode wafers lock in supply access and price visibility for premium manufacturers while exposing entry-level IPL assemblers to spot-market xenon flashlamp volatility. This contract-structure divergence separates FDA-cleared diode platforms with captive semiconductor sourcing from commoditized IPL competitors exposed to filter cartridge cost swings.
Pricing Analysis
The customization-premium spread separates configured-to-order diode laser systems from standard IPL platforms. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) certification level and proprietary cooling architecture differentiation. Cost compression in the IPL tier intensifies because xenon flashlamp commoditization erodes brand premiums. Entry-level buyers in China exhibit highest price sensitivity; German safety-conscious consumers demonstrate lowest sensitivity to unit economics.
Supply Chain Analysis
Inventory lead-times for thermoelectric cooling modules stretch procurement horizons for European device integrators sourcing from Bavaria's precision optics cluster. GaAs semiconductor fabrication concentrates in China, Taiwan, and South Korea, while xenon flashlamp assembly feeds from Chinese component ecosystems. The supply chain rests on single-source vulnerability for high-purity gallium arsenide substrates. Distribution runs through direct-to-consumer platforms bypassing traditional retail markups in the United States and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
At-home laser hair removal sits in early-cycle expansion as male grooming penetration normalizes body hair management routines beyond traditional female demographics. Dermatologist endorsement channels and social media validation accelerate adoption velocity across millennial and Gen Z cohorts.
For Market Incumbents: Shield premium positioning through backward integration into GaAs diode foundry partnerships that secure supply against East Asian concentration risk. Invest in FDA 510(k) pathway acceleration for multi-wavelength platforms to outpace MDR clinical study timelines that filter undercapitalized rivals. Channel control through captive mobile app ecosystems locks in subscription filter revenue that retail-dependent competitors cannot replicate.
For New Entrants and Emerging Players: FDA 510(k) fast-track consulting partnerships compress premarket notification timelines for optical fluence claims. White-space concentration sits with men's grooming verticals in Germany and China where influencer marketing normalizes male aesthetic routines. Target connected-device AI integration with skin-tone sensing algorithms that enable personalized treatment protocols and recurring software revenue streams.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturers with in-house semiconductor sourcing and clinical validation infrastructure. Long-term viability centers on five-to-ten year windows where regulatory convergence around MDR and FDA optical safety benchmarks consolidates vendor tiers. Watch GB standard harmonization progress in China as the inflection signal for compliant foreign entrant positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Skin-Sensing Algorithm Acquisition | Captures personalized treatment protocol revenue through mobile app ecosystems in the United States. |
| GaAs Diode Foundry Partnership | Secures supply chain resilience against East Asian semiconductor concentration for premium diode platforms. |
| FDA 510(k) Fast-Track Investment | Accelerates premarket clearance timelines for optical fluence claims ahead of MDR clinical study requirements. |
| Men's Grooming Brand Extension | Unlocks underpenetrated male demographic for body hair management through influencer marketing channels. |
| Subscription Consumable Model Launch | Locks in recurring filter cartridge revenue through captive direct-to-consumer platforms bypassing retail markups. |
Research Methodology
A spread of perspectives from biomedical optics engineers, dermatological safety consultants, FDA regulatory affairs specialists, and e-commerce platform operators converged on the working assumptions. Primary interviews with device manufacturers and channel partners combined with secondary validation from FDA 510(k) filings, MDR clinical study databases, and customs trade records for optical component flows. Bottom-up unit economics modeling and top-down market sizing triangulated volume and value outputs.
Segmentation dimensions modeled include product type, technology pulse structure, end-user demographic, and distribution channel across the projection horizon. CAGRs derived from historical shipment trajectories and penetration rate assumptions for connected-device variants. Industry-specific forecast inputs incorporate GaAs diode supply elasticity and dermatologist endorsement channel conversion rates.
Decision-makers should treat outputs as directional under stable regulatory clearance timelines and intact semiconductor supply assumptions; material deviation would warrant model refresh. Specific risk factors include MDR clinical study timeline extensions, state-level laser device classification fragmentation, and EU AI Act algorithmic transparency documentation burdens. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Single Use Contact Lenses Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
Hair Removal Devices Market
Medical Devices
Global High-Flow Nasal Cannula Market
Medical Devices
Baby Thermometer Market
Medical Devices
Foot and Ankle Allograft Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
High Flow Ventilators Market
Medical Devices
Needle-Free Vaccine Injectors Market
Medical Devices
Global Transradial Access Market
Medical Devices
Global Medical Device Security Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
India Respiratory Devices Market
Medical Devices
Pocket Ventilation Systems Market
Medical Devices
3D and 4D Ultrasound Devices Market
Medical Devices
Bowel Irrigation System Market