
 Global Blood Banking Devices Market | 2026-2036
Global Blood Banking Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Banking Devices Market Foresight
The EU Medical Device Regulation is repositioning compliance costs for blood storage equipment and automated collection platforms entering European markets. Haemonetics Corporation leverages integrated apheresis technology to anchor its position in automated blood collection. Fresenius Kabi AG competes through specialized blood component separation systems. Grifols, S.A. dominates plasma-derived therapy logistics, extending its influence into adjacent blood banking infrastructure.
Blood banking devices encompass instruments engineered for collection, processing, testing, storage, and labeling of blood and derived components, operating within temperature parameters typically ranging from 1°C to 6°C for whole blood preservation and -40°C to -150°C for plasma cryopreservation. These systems serve the critical function of maintaining haemovigilance chain integrity from donor arm to patient transfusion. Automated blood collection systems command the largest revenue pool due to capital intensity and replacement cycles, while molecular diagnostics within the technology dimension captures the fastest expansion trajectory as nucleic acid testing protocols displace serological methods. Blood storage equipment generates stable aftermarket revenue through calibration contracts and cold-chain monitoring upgrades.
The FDA enforces 21 CFR Part 606 cGMP standards for blood and blood components, while the EMA's MDR framework mandates clinical evidence for Class IIa and above devices. WHO guidelines on blood screening and ISO 15189 accreditation requirements shape quality management expectations across national health systems. Stakeholders must monitor evolving pathogen inactivation mandates and harmonized traceability standards as determinants of product roadmap prioritization and market access sequencing.
Market Dynamics
Automated blood collection systems are consolidating collection, processing, and data logging into single-platform architectures, compressing capital deployment timelines for hospital blood banks and independent collection centers.
Growth Catalysts
- FDA Pathogen Reduction Guidance:Updated validation requirements for pathogen inactivation technologies are accelerating device replacement cycles among US-based blood centers.
- Aging Demographics in Germany and Japan:Sustained transfusion volume from elderly populations is driving procurement of high-throughput automated collection platforms.
- Nucleic Acid Testing Protocols:Molecular diagnostics methods are displacing serological screening, expanding installed bases of NAT-compatible processing equipment.
Market Restraints
- Platinum-Group Metal Input Costs:Temperature control components in cryopreservation units face volatile palladium and rhodium pricing, squeezing margin structures for storage equipment manufacturers.
- EU MDR Compliance Burden:Clinical evidence requirements for Class IIa and above blood banking devices are extending market access timelines and inflating regulatory spend for European entrants.
- Refrigerant Substitution Pressures:F-Gas Regulation phase-down schedules are forcing redesign of cold-chain systems before next-generation cooling technologies achieve cost parity.
Strategic Opportunities
- India's Blood Center Modernization:CDSCO streamlined approval pathways and expanding health infrastructure budgets are opening procurement windows for automated component separation systems.
- WHO Traceability Mandates:Harmonized barcoding and electronic record standards across national health systems are creating upgrade demand for labeling and inventory management modules.
- AI-Enabled Haemovigilance:Convergence of machine learning algorithms with cold-chain monitoring sensors is enabling predictive failure detection and reducing wastage rates in plasma logistics.
Industry Challenges
- ISO 15189 Accreditation Timelines:Quality management system certification for molecular diagnostics labs is creating bottlenecks in testing capacity expansion.
- Legacy LIS Integration Complexity:Hospital information system interoperability requirements are prolonging implementation cycles for automated collection platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Banking Devices Market |
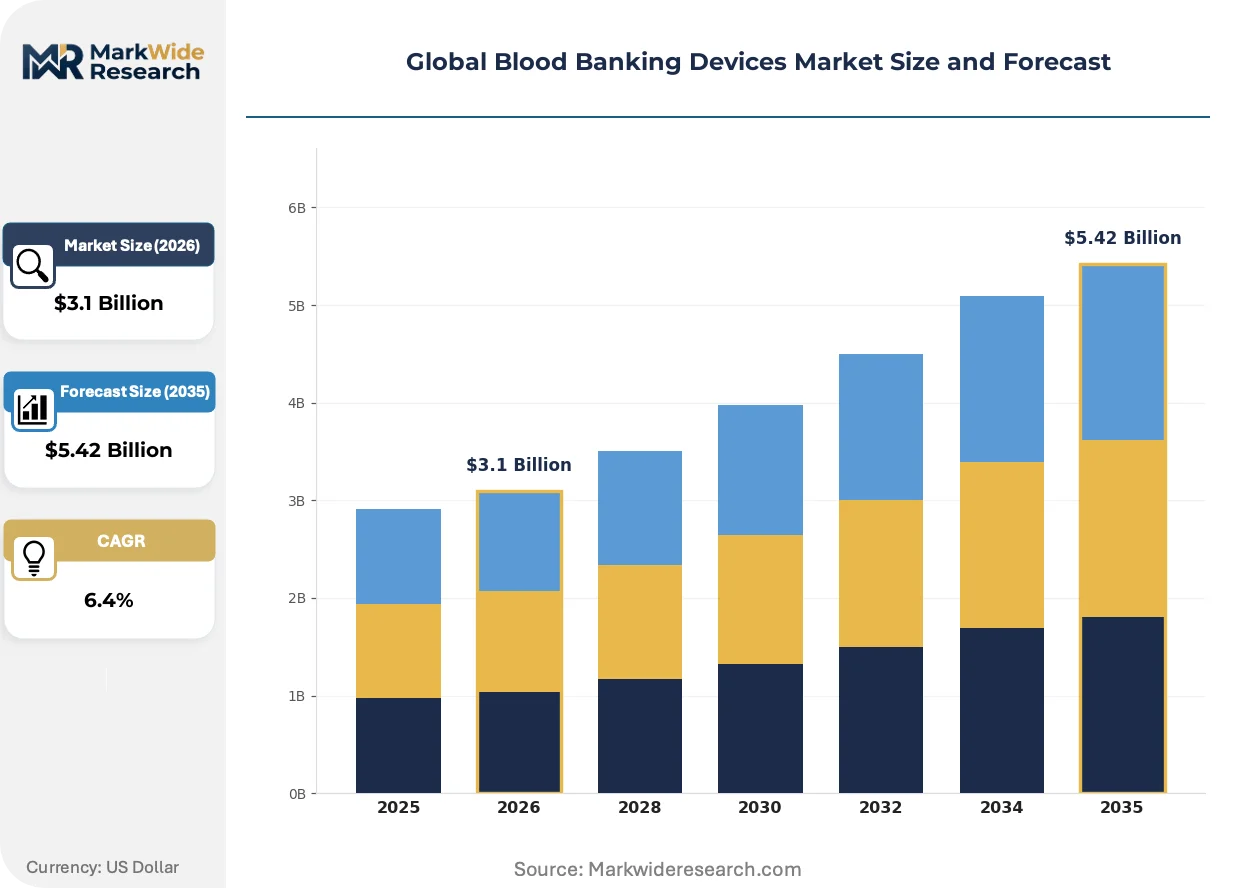
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Blood Collection Systems, Blood Component Separators, Blood Analyzers, Blood Storage Equipment, Blood Labeling Devices Technology: Immunohematology, Molecular Diagnostics, Chemiluminescence, Flow Cytometry, Microarray End User: Blood Banks, Diagnostic Laboratories, Research Institutes, Healthcare Facilities Application: Blood Screening, Blood Testing, Blood Component Preparation, Quality Control |
| Companies Covered | Haemonetics Corporation, Terumo Corporation, Fresenius Kabi AG, Grifols, S.A., Macopharma, Becton, Dickinson and Company, Thermo Fisher Scientific, Inc., Beckman Coulter, Inc., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Banking Devices Market Shifts & Advancements
Digital integration and closed-system automation are compressing manual handling steps across the haemovigilance chain, while regulatory frameworks in major markets are tightening evidence requirements for device safety claims.
Integrated apheresis platforms is unifying donor screening, component collection, and automated labeling into continuous workflows. Hospital blood banks in the United States are deploying these systems to reduce staff touchpoints and minimize collection-to-inventory time. This consolidation is compressing the traditional multi-vendor procurement model into single-source capital agreements with integrated service contracts.
EMA's MDR framework is mandating post-market clinical follow-up for Class IIa blood storage equipment and automated collection platforms. Manufacturers must now generate real-world performance data to maintain CE marking, inflating regulatory affairs headcount and extending product lifecycle management costs. European notified bodies are prioritizing submissions from devices with existing FDA 510(k) clearances, creating a sequential market access pattern.
Leasing structures are displacing outright purchase for high-capital automated collection systems in Japan and Germany. Independent blood centers are favoring equipment-as-a-service arrangements that bundle maintenance, calibration, and software updates into per-procedure fees. This shift is most visible among mid-tier collection networks seeking to preserve liquidity for plasma fractionation capacity expansion.
Global Blood Banking Devices Market Segmentation
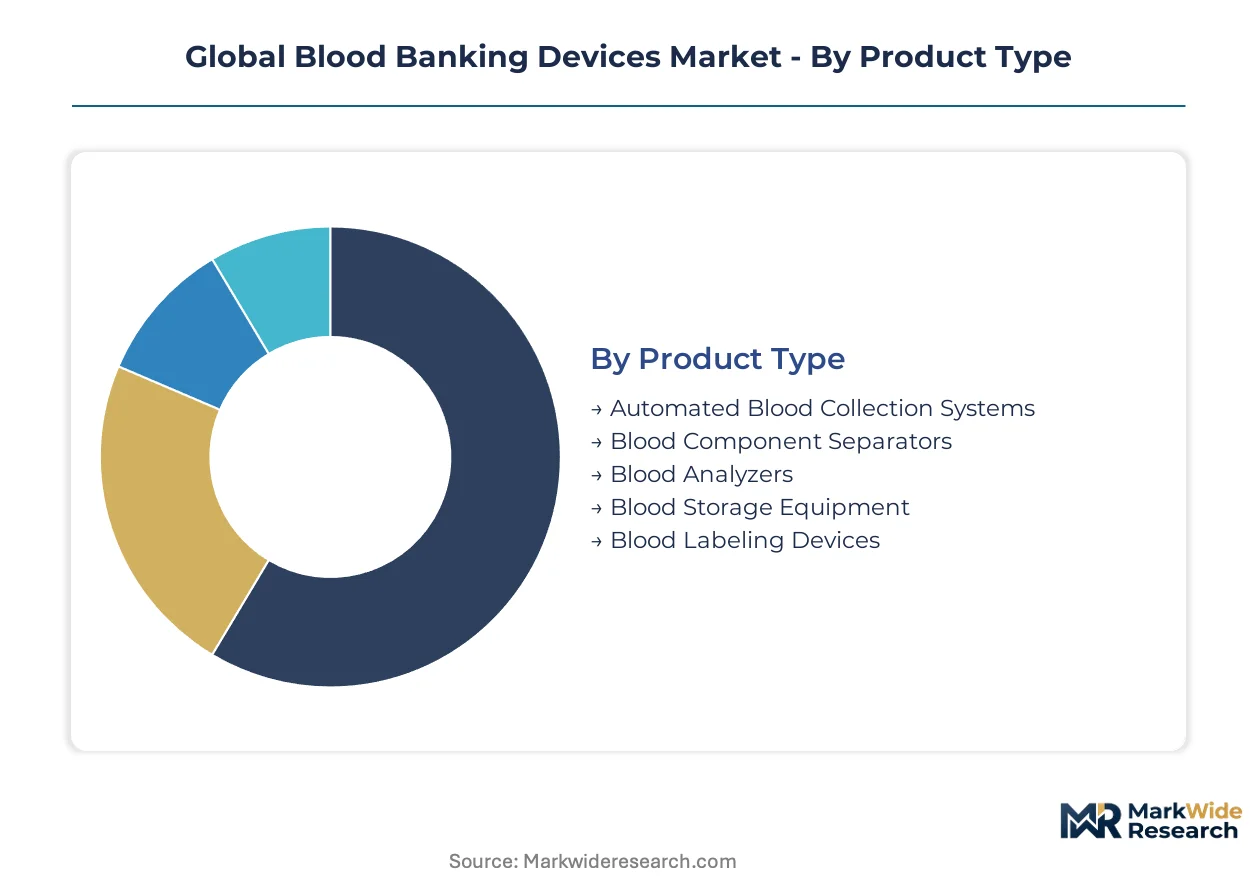
Device segmentation in blood banking traces capital deployment patterns across collection, processing, and storage workflows. Procurement cycles differ sharply between automated platforms with seven-year replacement horizons and consumable-heavy testing modalities with shorter refresh intervals.
Product Type:
Upgrade cycles concentrate where capital intensity intersects with regulatory-driven obsolescence, particularly for platforms facing new FDA pathogen reduction validation requirements.
- Automated Blood Collection Systems:Integrated apheresis platforms consolidate donor screening, component collection, and data logging into single-source architectures. Hospital blood banks in the United States and Germany are compressing multi-vendor procurement into unified capital agreements with bundled service contracts.
- Blood Component Separators:Centrifugation-based systems extract plasma, platelets, and red cell concentrates from whole blood units. Procurement in Japan centers on high-throughput platforms serving aging populations with sustained transfusion volume.
- Blood Analyzers:Automated hematology and coagulation testing units process donor screening samples.
- Blood Storage Equipment:Refrigeration and cryopreservation units maintain temperature integrity from 1°C to 6°C for whole blood and -40°C to -150°C for plasma.
- Blood Labeling Devices:Barcode and RFID-enabled systems enforce traceability compliance across the haemovigilance chain.
Automated Blood Collection Systems sits at the top of the volume ranking, with Blood Storage Equipment climbing the fastest on cold-chain monitoring upgrade demand.
Technology:
Cost tier stratification separates capital-intensive instrument platforms from reagent-heavy testing methodologies, with reimbursement rates determining adoption velocity in hospital laboratories.
- Molecular Diagnostics:Nucleic acid testing protocols detect viral genomes at earlier infection stages than serological methods. NAT-compatible processing equipment is displacing legacy systems in blood centers across the United States, Germany, and Japan.
- Immunohematology:Automated blood grouping and antibody screening platforms process donor and patient samples through gel card or solid-phase methodologies. European blood banks are prioritizing MDR-compliant upgrades for Class IIa devices.
- Chemiluminescence:High-sensitivity immunoassay detection for infectious disease markers.
- Flow Cytometry:Cell population analysis for specialized component characterization.
- Microarray:High-throughput genotyping for extended blood group matching.
Immunohematology commands the largest installed base, while Molecular Diagnostics gains share fastest on regulatory displacement of serological screening.
End User:
Customer type determines procurement modality, with independent blood centers favoring lease structures and hospital networks prioritizing integrated platform consolidation.
- Blood Banks:Independent collection centers and hospital-based blood banks deploy automated collection platforms, component separators, and storage equipment. Japanese and German operators are shifting toward equipment-as-a-service arrangements that bundle maintenance into per-procedure fees.
- Diagnostic Laboratories:Hospital and reference labs operate molecular diagnostics and immunohematology testing lines. ISO 15189 accreditation timelines are creating bottlenecks in capacity expansion for NAT processing.
- Research Institutes:Academic and commercial research facilities utilize flow cytometry and microarray platforms.
- Healthcare Facilities:Transfusion services and surgical suites consume processed blood components.
Blood Banks dominate procurement volume, with Diagnostic Laboratories expanding most quickly on nucleic acid testing protocol adoption.
Application:
Application segmentation follows the haemovigilance chain from donor arm to patient transfusion, with quality mandates driving instrumentation density at each stage.
- Blood Screening:Infectious disease and blood group testing of donor units. FDA pathogen reduction guidance is accelerating replacement cycles for screening platforms in US-based centers.
- Blood Testing:Pre-transfusion compatibility testing and patient sample analysis. Hospital laboratories in Japan are automating cross-matching workflows to reduce manual handling errors.
- Blood Component Preparation:Centrifugation, filtration, and separation of whole blood into therapeutic components.
- Quality Control:In-process and post-release testing for component potency and safety.
Blood Screening leads application spending, with Blood Testing climbing fastest on pre-transfusion automation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled hematology technicians and biomedical engineers cluster in mature healthcare systems where transfusion medicine infrastructure commands sustained capital investment. Workforce density in blood banking specialization varies sharply between established markets and emerging procurement frontiers.
United States
Hospital blood banks in Texas and California are consolidating multi-vendor procurement into single-source automated collection agreements. FDA 21 CFR Part 606 cGMP enforcement is accelerating device replacement cycles among independent collection centers. The Boston-Cambridge corridor anchors molecular diagnostics R&D for nucleic acid testing protocols.
Germany
Aging demographics in Bavaria and North Rhine-Westphalia sustain transfusion volume for high-throughput component separation platforms. EU MDR clinical evidence requirements are extending market access timelines for Class IIa storage equipment. The Frankfurt-Rhine-Main cluster concentrates cold-chain engineering expertise for cryopreservation systems.
Japan
Metropolitan Tokyo blood centers are shifting toward equipment-as-a-service leasing structures for apheresis platforms. METI reimbursement frameworks favor automated processing to reduce manual handling errors. The Osaka-Kobe industrial zone manufactures precision temperature control components for plasma logistics.
India
CDSCO streamlined approval pathways are opening procurement windows for component separation systems in Maharashtra and Gujarat. National health infrastructure budgets are expanding blood center modernization in tier-2 cities. The Bangalore-Hyderabad corridor is incubating domestic cold-chain monitoring technology startups.
Switzerland
Swissmedic quality mandates are shaping traceability standards for labeling devices serving cross-border plasma logistics. Basel's pharmaceutical cluster drives demand for GMP-compliant storage equipment in fractionation facilities. Geneva-based WHO headquarters influences harmonized barcoding protocols adopted by national health systems.
Global Blood Banking Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the blood banking device landscape. The vendor base stratifies into three tiers: integrated platform providers commanding premium pricing, component specialists defending niche positions, and regional fabricators serving price-sensitive procurement. Strategic archetypes include apheresis technology anchors, cold-chain engineering houses, and diagnostics platform integrators. Dominant competitive moves encompass M&A for technology tuck-ins and geographic expansion through distributor partnerships.
Within the integrated platform tier, Haemonetics Corporation and Terumo Corporation exemplify capital-intensive equipment providers with global service networks. Fresenius Kabi AG occupies a position among diversified healthcare conglomerates with blood component separation capabilities. These three entities represent contrasting archetypes: the pure-play apheresis specialist, the Japanese precision manufacturer, and the German diversified medical technology group.
| Leading Market Players |
|---|
| Haemonetics Corporation |
| Terumo Corporation |
| Fresenius Kabi AG |
| Grifols, S.A. |
| Macopharma |
| Becton, Dickinson and Company |
| Thermo Fisher Scientific, Inc. |
| Beckman Coulter, Inc. |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation phase-down schedules gate qualified supply for cryopreservation equipment manufacturers and anchor premium-tier pricing access for compliant cold-chain systems. Buyers seeking MDR-validated storage platforms face extended lead times and elevated procurement costs as refrigerant redesign cycles compress available vendor pools.
Pricing Analysis
Bundled service contracts now command forty percent of automated collection system transactions, with per-procedure fee structures displacing capital purchase in Japan and Germany. Pricing stratifies across FDA-cleared, CE-marked, and non-certified equipment tiers, with pathogen reduction validation status serving as the primary price differentiation driver. Cost compression in standard-tier storage equipment is intensifying because palladium and rhodium price volatility squeezes temperature control component margins. Independent blood centers exhibit highest price sensitivity, while hospital networks in the United States prioritize integration value over unit cost.
Supply Chain Analysis
ISO 15189 and FDA 21 CFR Part 606 qualification requirements gate component supply for molecular diagnostics labs and automated processing platforms. Temperature control subsystems concentrate manufacturing in Japan and Germany, while precision centrifugation components source primarily from Switzerland and the United States. Supply chain risk centers on single-source vulnerability for platinum-group metal inputs in cryopreservation units. Distribution runs through specialized medical device distributors with cold-chain logistics capabilities, bypassing generalist healthcare procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as nucleic acid testing protocols displace serological methods and elevate specifications for NAT-compatible processing equipment.
For Market Incumbents: Hedge against margin erosion in standard-tier storage equipment by securing captive supply agreements for palladium-based temperature control components. Accelerate MDR clinical evidence generation for Class IIa devices to preempt European notified body bottlenecks. Prioritize backward integration into refrigerant technology to insulate from F-Gas Regulation redesign cycles. For New Entrants and Emerging Players: CDSCO streamlined approval pathways in India open a window for component separation system penetration in Maharashtra and Gujarat blood center modernization programs. Target diagnostic laboratory segments facing ISO 15189 accreditation bottlenecks with modular molecular diagnostics platforms requiring minimal quality system infrastructure. Pursue equipment-as-a-service go-to-market structures to bypass capital purchase barriers among mid-tier collection networks. For Investors and Strategic Acquirers: Roll-up economics work for cold-chain monitoring technology specialists because fragmented domestic startup ecosystems in India and Southeast Asia lack scale to serve multinational plasma logistics operators. Five-to-ten year viability hinges on consolidation of AI-enabled haemovigilance capabilities. Monitor FDA pathogen reduction guidance implementation velocity as inflection indicator for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR clinical evidence requirements extend timelines for Class IIa blood storage equipment entrants. |
| Hospital System Partnership | Integrated platform consolidation in Texas and California compresses multi-vendor procurement into single-source agreements. |
| Software Companion Development | AI-enabled haemovigilance modules reduce plasma wastage through predictive cold-chain failure detection. |
| Reimbursement Strategy | METI frameworks in Japan favor automated processing to minimize manual handling error liability. |
| Backward Integration | In-house production of temperature control components insulates manufacturers from platinum-group metal price volatility. |
Research Methodology
Bottom-up blood bank procurement modeling reconciled against top-down automated collection system shipment tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and blood center operations directors combine with secondary validation from FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and WHO haemovigilance guidelines. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of replacement cycles and regulatory-driven obsolescence patterns informs the projection framework. Segmentation dimensions span product type, technology modality, end-user category, and application stage across the haemovigilance chain. CAGRs derive from fitted growth curves applied to installed base expansion and upgrade velocity. Forecast inputs incorporate nucleic acid testing protocol adoption rates and pathogen reduction technology validation timelines.
Revisions become necessary when FDA guidance on pathogen inactivation technologies shifts, EU MDR enforcement intensity changes, or platinum-group metal price volatility exceeds historical bands. A model refresh is warranted upon material change in WHO traceability mandate harmonization progress across national health systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Catheter Stabilization Devices Market
Medical Devices
Gracey Curette Market
Medical Devices
3D Printing in Healthcare Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Neurovascular Devices Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
Lactate Meter Market
Medical Devices
Urine Collection Devices Market
Medical Devices
Global Gynecology Devices Market
Medical Devices
Jet Nebulizers Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
Sharps Destruction Device Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market