
 Global Female Stress Urinary Incontinence Treatment Devices Market | 2026-2036
Global Female Stress Urinary Incontinence Treatment Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Female Stress Urinary Incontinence Treatment Devices Market Intelligence
CE marking under the EU Medical Device Regulation is reorganizing competitive access across European markets. Boston Scientific Corporation leverages its integrated urology portfolio to sustain catheter and sling placement in major hospital systems. Coloplast A/S anchors Nordic and German markets through direct specialist channel control. Johnson & Johnson Services Inc. differentiates via Ethicon's long-standing surgeon training infrastructure across North American academic medical centers.
Female stress urinary incontinence treatment devices encompass implantable and non-implantable systems designed to restore urethral closure pressure, including mid-urethral polypropylene slings, injectable bulking agents, and neuromuscular electrical stimulators operating at 35-50 Hz pulse frequencies for pelvic floor rehabilitation. The primary commercial purpose is to reduce involuntary urine leakage during exertion while minimizing mesh erosion and repeat intervention rates. Slings still command the largest revenue pool among product types, though electrical stimulation devices are gaining fastest in physiotherapy center settings where non-surgical preference is strengthening. Minimally invasive surgical approaches concentrate margin capture in ambulatory surgical centers, while direct sales channels to urology clinics yield superior pricing power compared with distributor-mediated hospital procurement.
FDA 510(k) clearance pathways and the EU MDR's enhanced clinical evidence requirements are extending development timelines and raising capital barriers for new entrants. Japan's PMDA and South Korea's MFDS maintain distinct biocompatibility testing standards that fragment Asia-Pacific registration strategies. Stakeholders must monitor reimbursement recalibrations for outpatient sling procedures and the evolving clinical evidence base around synthetic mesh safety.
Market Dynamics
EU MDR compliance timelines are compressing competitive access for implantable pelvic floor devices while ambulatory surgical centers capture margin from traditional hospital settings. Synthetic mesh safety scrutiny continues to reshape clinical practice patterns across developed markets.
Growth Catalysts
- Aging demographics in Japan:The country's super-aged population drives procedure volume expansion for minimally invasive sling placements. PMDA's structured reimbursement pathways accelerate physician adoption.
- MDR transition extensions:Extended CE marking timelines allow incumbent manufacturers to consolidate market presence before new entrants achieve compliance. This regulatory window favors established device portfolios.
- Neuromuscular stimulation protocols:Pelvic floor rehabilitation at 35-50 Hz pulse frequencies gains traction in physiotherapy centers. Non-surgical preference strengthens device demand outside traditional urology channels.
Market Restraints
- Polypropylene biocompatibility testing:Fragmented standards across Japan's PMDA and South Korea's MFDS extend registration timelines. Duplicative testing raises capital barriers for Asia-Pacific market entry.
- Mesh erosion liability exposure:Synthetic sling safety litigation concentrates manufacturer risk in the United States. Product liability costs compress margins for implantable device categories.
- Single-source raw material dependence:Medical-grade polypropylene supply concentrates among specialized polymer producers in Germany. Input cost volatility threatens consistent device pricing.
Strategic Opportunities
- Underpenetrated outpatient channels in Germany:Direct specialist channel control yields superior pricing power compared to distributor-mediated hospital procurement. Nordic market proximity enables cross-border service expansion.
- Injectable bulking agent convergence:Cross-linked collagen and carbon bead technologies merge with ultrasound-guided placement systems. This convergence opens ambulatory procedure volumes previously reserved for surgical intervention.
- IRA outpatient reimbursement recalibration:United States Medicare payment adjustments for office-based sling procedures create financial incentives for site-of-service migration. Academic medical centers respond with dedicated urology clinic expansion.
Industry Challenges
- Pelvic floor reconstructive surgery specialization:Fellowship-trained urogynecologist scarcity limits procedure capacity expansion in community hospital settings. Training infrastructure gaps constrain volume growth outside major metropolitan clusters.
- EU MDR technical documentation compilation:Enhanced clinical evidence requirements for implantable devices demand retrospective registry data aggregation. Small manufacturers face insurmountable compliance resource requirements.
- Legacy electronic health record integration:Neuromuscular stimulation device data streams require custom API development for seamless clinic workflow incorporation. Interoperability friction slows physiotherapy center technology adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Female Stress Urinary Incontinence Treatment Devices Market |
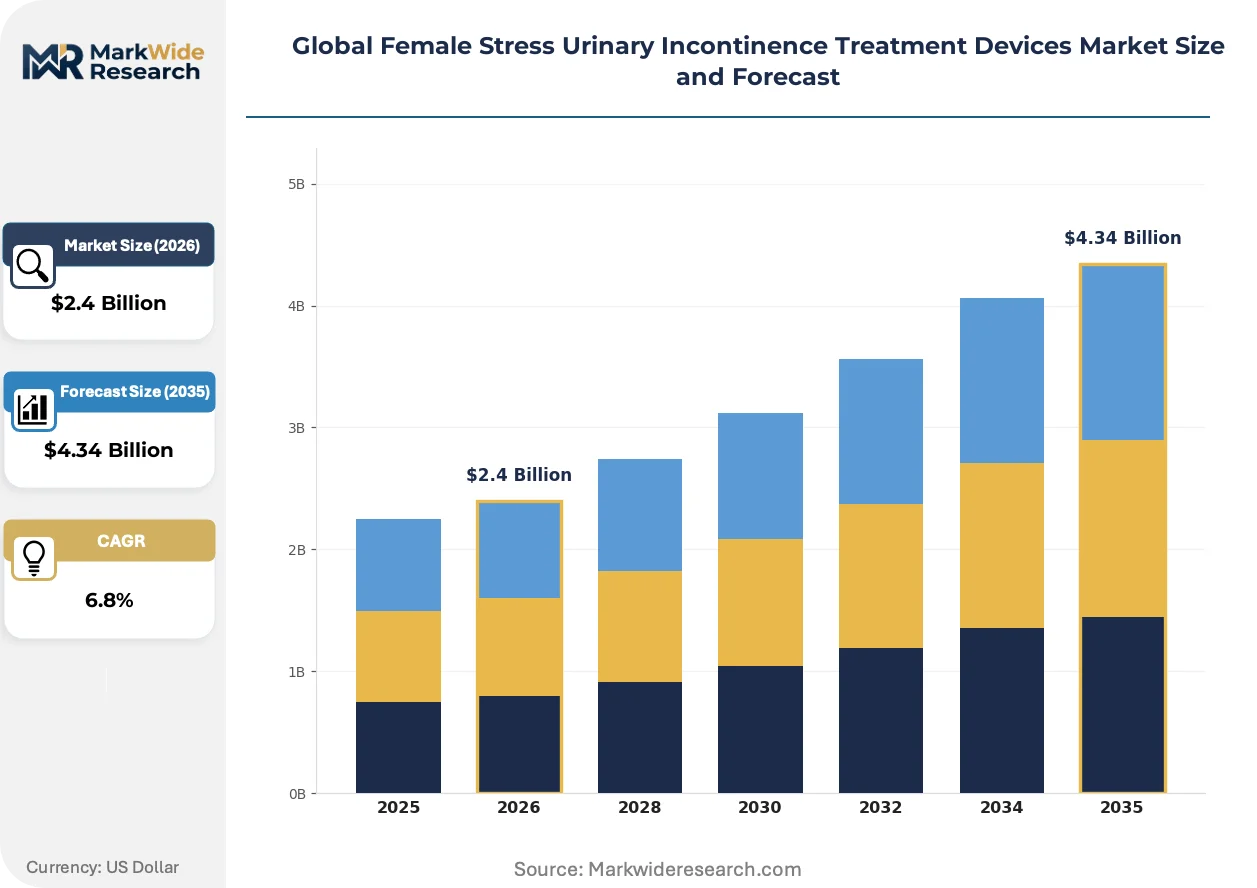
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slings, Bulking Agents, Electrical Stimulation Devices, Urethral Inserts, Pelvic Floor Exercisers Therapy Approach: Surgical, Minimally Invasive, Non-Surgical, Pharmacological, Behavioral Therapy End User: Urology Clinics, Physiotherapy Centers, Specialized Treatment Centers, Ambulatory Surgical Centers Distribution Channel: Hospitals, Online Retailers, Medical Distributors, Pharmacies, Direct Sales |
| Companies Covered | Boston Scientific Corporation, Johnson & Johnson Services Inc., Coloplast A/S, BD (Becton, Dickinson and Company), CooperSurgical Inc., Teleflex Incorporated, Karl Storz, B. Braun SE, American Medical Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Female Stress Urinary Incontinence Treatment Devices Market Strategic Shifts & Innovations
Device miniaturization and bioabsorbable material science are compressing the boundary between permanent implant and temporary therapeutic intervention. Regulatory evidence standards simultaneously elevate while reimbursement pathways fragment across payor categories.
Bioabsorbable urethral bulking agents incorporating cross-linked hyaluronic acid matrices are supplanting permanent synthetic slings in selected patient populations. Ambulatory surgical centers in the United States adopt these alternatives at accelerating pace for low-grade stress incontinence cases. This substitution is compressing average revenue per procedure while expanding addressable patient volumes beyond surgical candidates.
EU MDR Article 61 clinical evaluation requirements are extending post-market surveillance obligations for mid-urethral sling manufacturers. The regulation forces retrospective registry participation and periodic safety reporting that smaller competitors cannot sustain. Implantable pelvic floor device categories face the most severe compliance burden, with notified body capacity constraints extending certification timelines.
Patient-directed purchasing through direct-to-clinic channels is disrupting traditional hospital procurement hierarchies for electrical stimulation devices. Physiotherapy centers in Germany and Japan now source neuromuscular stimulators outside group purchasing organization frameworks. This channel fragmentation enables manufacturers to capture margin previously allocated to distributor networks and hospital administrative overhead.
Global Female Stress Urinary Incontinence Treatment Devices Market Segmentation
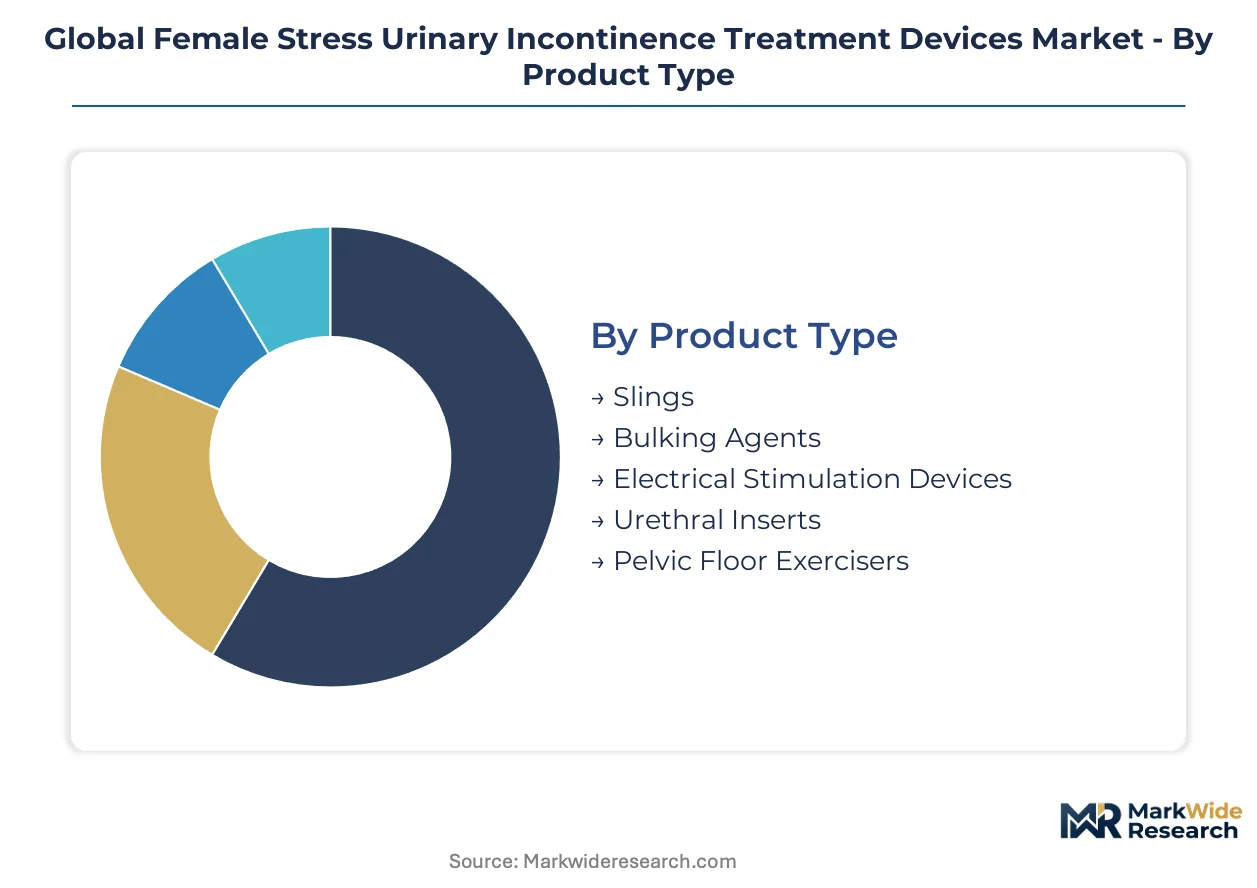
Device categorization in female stress urinary incontinence treatment reveals how substitution pressures reshape revenue allocation across surgical and non-surgical alternatives. Manufacturers must track segment-specific regulatory burdens and channel economics to defend margin positions.
Product Type:
Polypropylene mesh alternatives and neuromuscular technologies face intensifying substitution pressure from bioabsorbable bulking agents and pelvic floor exercisers.
- Slings:Mid-urethral polypropylene mesh systems restore urethral closure pressure through suburethral support. Demand concentrates in ambulatory surgical centers across the United States and Germany, though mesh erosion liability exposure compresses manufacturer margins.
- Electrical Stimulation Devices:Neuromuscular stimulators operating at 35-50 Hz pulse frequencies drive pelvic floor rehabilitation. Physiotherapy centers in Japan and Germany source these outside group purchasing organization frameworks, capturing margin previously allocated to distributor networks.
- Bulking Agents:Cross-linked collagen and carbon bead formulations merge with ultrasound-guided placement.
- Urethral Inserts:Disposable mechanical devices provide temporary coaptation for activity-specific use.
- Pelvic Floor Exercisers:Biofeedback-enabled resistance trainers support home-based rehabilitation protocols.
Slings retain volume leadership; electrical stimulation devices hold the steepest expansion curve.
Therapy Approach:
Cost tier stratification separates premium surgical intervention from economy non-surgical alternatives, with reimbursement calibration determining site-of-service migration.
- Surgical:Retropubic and transobturator sling placements require operating room infrastructure and fellowship-trained urogynecologist capacity.
- Minimally Invasive:Single-incision mini-slings and injectable bulking procedures reduce recovery time and facility fees.
- Non-Surgical:Pelvic floor muscle training combined with electrical stimulation protocols gains traction where patient preference favors avoidance of implantable devices.
- Pharmacological:Alpha-adrenergic agonists and topical estrogen adjuncts address mild stress incontinence symptoms.
- Behavioral Therapy:Timed voiding and fluid management protocols serve as first-line intervention.
Minimally invasive approaches capture margin fastest; surgical intervention maintains the highest average revenue per procedure.
End User:
Volume concentration in outpatient settings is accelerating as reimbursement incentives favor site-of-service migration away from inpatient facilities.
- Urology Clinics:Dedicated incontinence service lines in academic medical centers concentrate high-complexity sling placements. United States Medicare payment adjustments for office-based procedures drive dedicated clinic expansion.
- Physiotherapy Centers:German and Japanese centers now source neuromuscular stimulators through direct-to-clinic channels, bypassing hospital procurement hierarchies.
- Specialized Treatment Centers:Urogynecology-focused facilities combine surgical and conservative management pathways.
- Ambulatory Surgical Centers:Freestanding facilities capture increasing share of low-grade stress incontinence procedures.
Urology clinics retain procedural volume leadership; physiotherapy centers are climbing the fastest as non-surgical preference strengthens.
Distribution Channel:
Customer type fragmentation separates institutional procurement from patient-directed purchasing, with channel economics determining manufacturer margin capture.
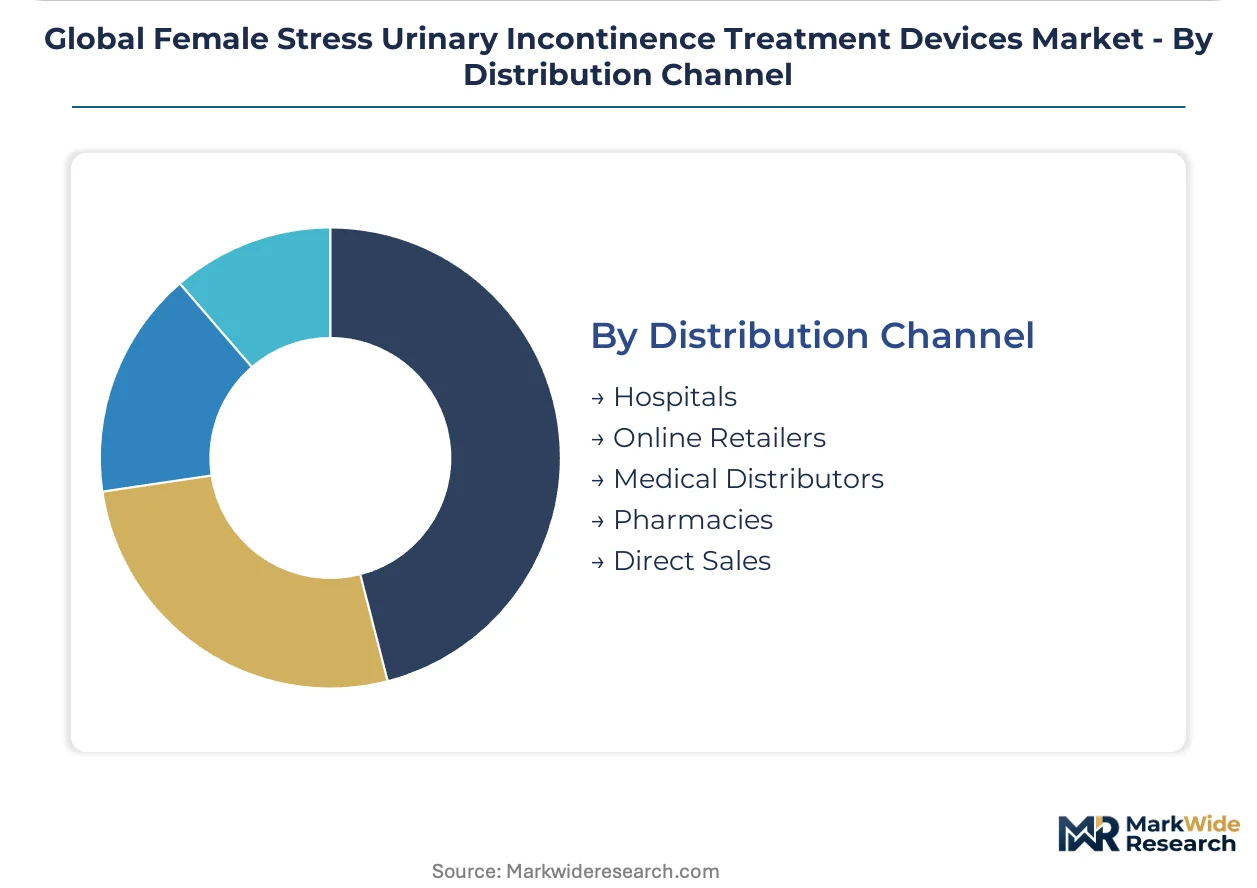
- Hospitals:Group purchasing organization frameworks dominate implantable device procurement, compressing pricing power for mid-urethral sling manufacturers.
- Direct Sales:Manufacturer-controlled specialist channels yield superior pricing power compared to distributor-mediated hospital procurement in Nordic and German markets.
- Medical Distributors:Regional networks service community hospital settings where urogynecologist scarcity limits procedure capacity.
- Online Retailers:Patient-directed purchasing of pelvic floor exercisers and electrical stimulation devices expands beyond prescription channels.
- Pharmacies:Retail distribution supports urethral inserts and bulking agent access for self-managed care.
Hospital channels retain volume concentration; direct sales are expanding most quickly as manufacturers bypass distributor overhead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement adjustments for office-based sling procedures are accelerating site-of-service migration in the United States. Japan's PMDA structured pathways compress physician adoption timelines for neuromuscular stimulation protocols. Germany's direct specialist channel control yields superior pricing power compared to distributor-mediated procurement.
United States
Ambulatory surgical centers capture increasing procedure volumes as IRA outpatient reimbursement recalibration creates financial incentives for migration away from inpatient facilities. FDA 510(k) clearance pathways maintain predictable regulatory timelines for established device categories. Academic medical centers in Boston and New York Metro expand dedicated urology clinic infrastructure to capture office-based sling revenue.
Germany
Underpenetrated outpatient channels in Bavaria and North Rhine-Westphalia concentrate direct sales opportunities outside hospital procurement hierarchies. EU MDR transition extensions allow incumbent manufacturers to consolidate market presence before new entrants achieve compliance. Medical-grade polypropylene supply clusters around specialized polymer producers in the Rhine-Ruhr industrial corridor.
Japan
Super-aged demographics in Kanto and Kansai regions drive procedure volume expansion for minimally invasive sling placements. METI coordinates PMDA reimbursement pathway acceleration for pelvic floor rehabilitation devices. Tokyo and Osaka physiotherapy centers source neuromuscular stimulators through direct-to-clinic channels, bypassing traditional hospital procurement.
United Kingdom
NHS England payment reforms favor day-case surgical pathways for stress incontinence intervention. MHRA post-Brexit regulatory autonomy enables streamlined conformity assessment for established device categories. London and Manchester urogynecology centers concentrate fellowship-trained surgical capacity for complex reconstructive procedures.
South Korea
MFDS biocompatibility testing standards fragment Asia-Pacific registration strategies for polypropylene mesh systems. Seoul Capital Area ambulatory facilities adopt ultrasound-guided bulking agent placement at accelerating pace. Busan-Ulsan medical device manufacturing clusters supply regional demand for electrical stimulation components.
Global Female Stress Urinary Incontinence Treatment Devices Market Key Industry Players
Player mix skews toward integrated medical technology conglomerates with dedicated urology portfolios. Market structure concentrates around three to four entities controlling implantable device categories, while electrical stimulation segments fragment across specialized physiotherapy equipment manufacturers. Strategic archetypes separate portfolio-integrated multinationals from single-product specialists and regional channel controllers. Dominant competitive moves include direct specialist channel establishment and retrospective clinical registry assembly for EU MDR compliance.
Among integrated multinationals, Boston Scientific Corporation and Johnson & Johnson Services Inc. exemplify the portfolio-anchored archetype with cross-category urology presence. Coloplast A/S occupies a distinct position as a Nordic channel controller with direct specialist market access. These three entities represent divergent strategic postures: integrated portfolio breadth, surgeon training infrastructure depth, and regional channel dominance respectively.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Johnson & Johnson Services Inc. |
| Coloplast A/S |
| BD (Becton, Dickinson and Company) |
| CooperSurgical Inc. |
| Teleflex Incorporated |
| Karl Storz |
| B. Braun SE |
| American Medical Solutions |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation agreements with German polymer producers lock in medical-grade polypropylene supply visibility for mid-urethral sling manufacturers while insulating against raw material cost volatility. These contractual structures anchor pricing predictability for implantable device categories across the United States and European markets.
Pricing Analysis
Certification level (FDA 510(k) versus EU MDR CE marking) creates the primary spread between premium implantable slings and economy-tier electrical stimulation devices. Per-unit transactional pricing dominates surgical categories, while subscription-based leasing models gain traction for neuromuscular stimulators in physiotherapy settings. Pricing pressure stems from mesh erosion liability exposure compressing margins on polypropylene mesh systems. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement ceilings, whereas academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for Asian-sourced electrical stimulation components destined for German physiotherapy centers. Medical-grade polypropylene production clusters in Germany and the United States, with specialized polymer converters feeding device assembly operations. Single-source dependence on Rhine-Ruhr industrial corridor suppliers creates tariff exposure vulnerability under transatlantic trade policy shifts. Distribution runs through direct specialist channels for implantable devices, while neuromuscular stimulators bypass traditional hospital procurement hierarchies via direct-to-clinic fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioabsorbable bulking agent convergence with ultrasound-guided placement systems constitutes a technological inflection disrupting traditional sling economics. EU MDR compliance timeline extensions simultaneously compress competitive access for implantable categories.
For Market Incumbents: Compound defensive moats by accelerating retrospective clinical registry assembly for EU MDR Article 61 compliance before notified body capacity constraints tighten further. Secure backward integration into medical-grade polypropylene resin production to neutralize input cost volatility from German supplier concentration. Channel control investments in Nordic and German direct specialist networks defend pricing power against distributor-mediated procurement erosion.
For New Entrants and Emerging Players: Differentiate on neuromuscular stimulation protocol customization for physiotherapy center workflows, where legacy electronic health record integration friction slows incumbent adoption. Target underpenetrated outpatient channels in Bavaria and North Rhine-Westphalia where direct sales bypass hospital group purchasing organization compression. Deploy software companion development as primary go-to-market angle, capturing margin through data-enabled service bundling rather than device commodity competition.
For Investors and Strategic Acquirers: Single-product electrical stimulation specialists with proprietary 35-50 Hz pulse frequency protocols represent the most defensible acquisition archetype against portfolio-integrated multinational competition. Long-term viability hinges on reimbursement pathway durability for outpatient pelvic floor rehabilitation across Medicare and European statutory health insurance systems. Monitor PMDA reimbursement acceleration signals from METI as inflection indicator for Asia-Pacific market expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 61 clinical evaluation requirements extend certification timelines for implantable slings. |
| Hospital System Partnership | Academic medical center urology clinic expansion captures IRA outpatient reimbursement recalibration incentives. |
| Software Companion Development | Custom API integration for electronic health record interoperability accelerates physiotherapy center adoption. |
| Reimbursement Strategy | Medicare payment adjustments for office-based sling procedures drive site-of-service migration. |
| Backward Integration | In-house medical-grade polypropylene production neutralizes Rhine-Ruhr supplier concentration risk. |
Research Approach
Desk research of FDA 510(k) clearance databases, EU MDR notified body guidance documents, and PMDA reimbursement bulletins preceded structured interviews with urogynecologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. Secondary validation drew from CMS Medicare claims data, hospital procurement databases, and medical device trade flow records. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions across the analysis window.
Variance decomposition across product type, therapy approach, end user, and distribution channel dimensions informed the analytical framework throughout the projection horizon. CAGRs were derived from segmented procedure volume trajectories and average revenue per procedure assumptions. Forecast inputs incorporated aging demographic projections, reimbursement pathway stability assessments, and regulatory compliance timeline trajectories specific to implantable pelvic floor device categories.
Material uncertainties — synthetic mesh safety litigation outcomes, EU MDR notified body capacity constraints, and polypropylene biocompatibility testing standard harmonization — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory timeline adherence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wearable Cardioverter Defibrillators Market
Medical Devices
Anterior Cervical Fixation Devices Market
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Abdominal Closure Systems Market
Medical Devices
Peripheral Vascular Guide Wire Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Medical Device Trays Market
Medical Devices
Netherlands Artificial Organs and Bionic Implants Market
Medical Devices
US Clear Aligners Market
Medical Devices
Global Wedge Pressure Catheter Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
Argentina Ultrasound Devices Market
Medical Devices
Minimally Invasive Spine Technologies Market