
 Brazil Aesthetic Devices Market | 2026-2036
Brazil Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Aesthetic Devices Market Outlook
Aftermarket service revenue is fragmenting across Brazil's aesthetic devices landscape as clinics seek localized maintenance partnerships over manufacturer-dependent contracts. AbbVie (Allergan Aesthetics) leverages its established dermal filler portfolio to anchor premium positioning in metropolitan São Paulo. Galderma competes through specialized training networks that lock in dermatologist loyalty for its injectable platforms. Candela Corporation controls the laser refurbishment channel, extending equipment lifecycles for mid-tier cosmetic surgery centers in Brazil's interior states.
Aesthetic devices encompass electromechanical and energy-based systems engineered to deliver precise thermal, optical, or mechanical effects at tissue depths ranging from 0.5 mm to 15 mm, primarily for cosmetic enhancement and dermatological treatment. Laser devices dominate Brazil's product type hierarchy due to their versatility across hair removal and skin rejuvenation protocols, while radiofrequency platforms capture expanding margin pools in body contouring applications. Non-invasive technology leads the Brazilian market by procedure volume, though minimally invasive injectables sustain higher per-treatment revenue yields.
ANVISA governs device registration and post-market surveillance, while the Brazilian Ministry of Health establishes safety benchmarks that shape clinical adoption thresholds. ANVISA's accelerated review track for Class III non-invasive devices has compressed market entry timelines, stimulating import flows from Israeli and Korean manufacturers. Stakeholders must monitor pending updates to Brazil's medical device tax structure and ANVISA's alignment with international harmonization protocols to anticipate margin compression or competitive displacement.
Market Dynamics
ANVISA's accelerated review track for Class III non-invasive devices has compressed market entry timelines, triggering a supply influx from Israeli and Korean manufacturers that is reshaping competitive positioning in Brazil's southeastern corridor.
Growth Catalysts
- ANVISA Registration Streamlining:The regulator's fast-track pathway for non-invasive technologies has halved approval durations for radiofrequency and laser platforms. Dermatology clinics in São Paulo now refresh device fleets at compressed cycles.
- Medical Tourism Infrastructure:Rio de Janeiro's cosmetic surgery centers attract Latin American patients seeking cost-competitive aesthetic procedures. Disposable income convergence with regional visitors sustains premium device utilization rates.
- Radiofrequency Platform Versatility:Energy-based systems now address body contouring protocols previously requiring surgical intervention. Mid-tier clinics leverage single-device flexibility to expand service menus without capital multiplication.
Market Restraints
- Import Duty Structure:Brazil's medical device tax framework imposes cumulative levies on Korean and Israeli manufactured systems. Cost stacking compresses margin pools for distributors serving interior states.
- Maintenance Skill Concentration:Trained biomedical engineers cluster in São Paulo and Rio de Janeiro. Clinics in Minas Gerais and Paraná face extended equipment downtime due to technician scarcity.
- Reimbursement Absence:Brazil's private health plans exclude elective aesthetic procedures from coverage. Out-of-pocket payment requirements limit addressable demand to upper-middle income segments.
Strategic Opportunities
- Northeast Corridor Expansion:Salvador and Recife cosmetic surgery centers operate aging laser fleets. Equipment refresh cycles in these coastal cities lag São Paulo by four to six years.
- Combination Therapy Protocols:Sequential radiofrequency and injectable treatments deliver superior outcomes for skin laxity cases. Protocol bundling raises per-patient revenue yields above standalone procedure economics.
- Refurbishment Channel Control:Candela Corporation's laser refurbishment network extends equipment lifecycles. Third-party service partnerships in Brazil's interior states capture aftermarket revenue streams.
Industry Challenges
- Biomedical Technician Training Gap:Brazilian technical institutes produce insufficient graduates specializing in energy-based device repair. Clinic operators compete for scarce field service talent.
- ANVISA Post-Market Surveillance Compliance:Adverse event reporting requirements for Class III devices demand dedicated regulatory affairs staffing. Smaller clinic chains lack internal compliance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Aesthetic Devices Market |
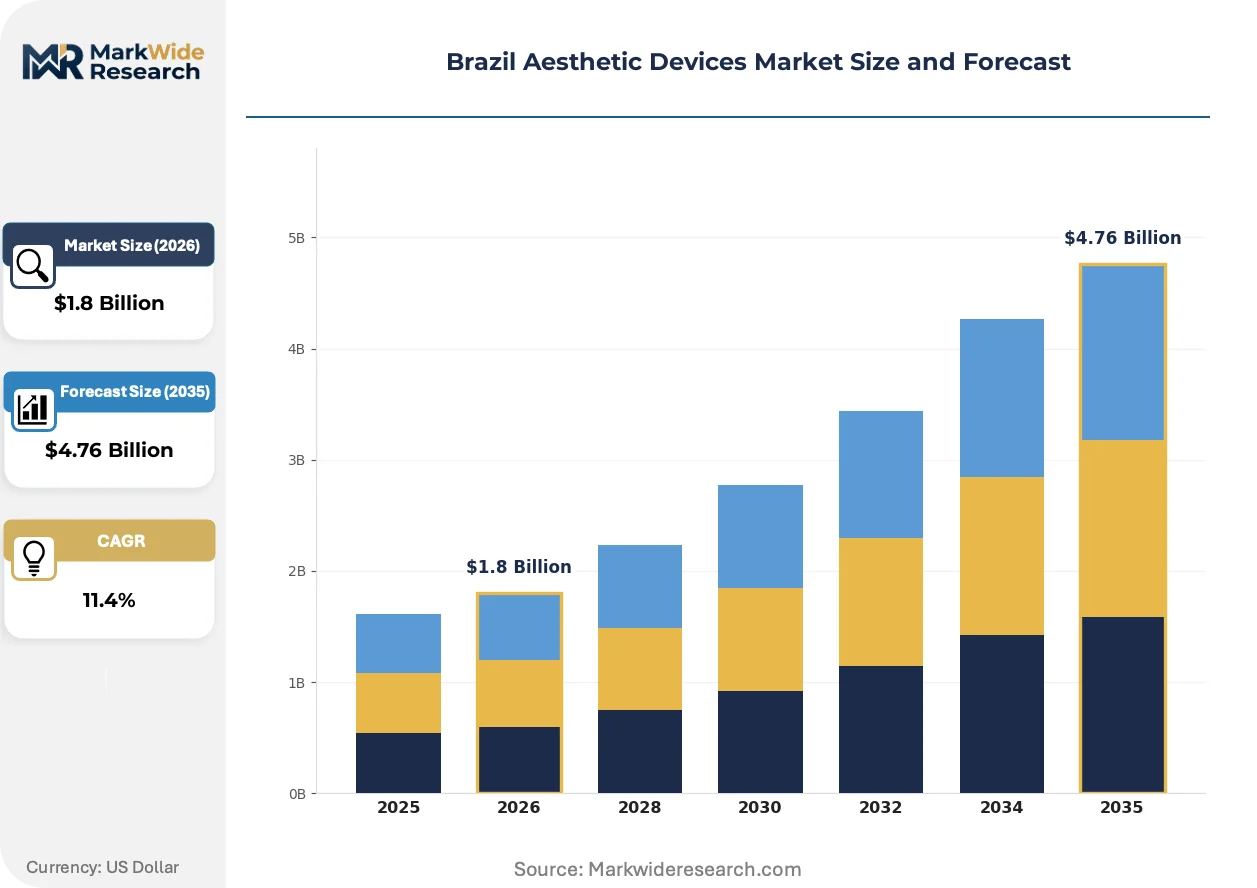
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Injectables, Radiofrequency Devices, Ultrasound Devices End User: Dermatology Clinics, Cosmetic Surgery Centers, Spa and Wellness Centers, Home Users Application: Body Contouring, Skin Rejuvenation, Hair Removal, Wrinkle Reduction Technology: Non-invasive, Minimally Invasive, High-intensity Focused Ultrasound, LED Therapy |
| Companies Covered | AbbVie (Allergan Aesthetics), Galderma, Cutera, Candela Corporation, Lumenis, Merz Pharma, Bausch Health Companies, Sisram Medical (Alma Lasers), El.En. S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Aesthetic Devices Market Strategic Shifts
Technology convergence and regulatory adaptation are compressing product lifecycles while fragmenting procurement authority across Brazil's aesthetic devices landscape.
Fractional laser platforms are migrating from ablative CO2 systems to non-ablative erbium-doped fiber configurations. Dermatology clinics in São Paulo's Jardins district adopt these systems to minimize patient downtime and expand daily treatment throughput. The technology shift is compressing residual values for legacy ablative equipment in secondary markets.
ANVISA's alignment with international harmonization protocols is accelerating mutual recognition agreements with MFDS and PMDA. Korean manufacturers now submit existing technical documentation rather than generating Brazil-specific dossiers. This regulatory convergence most benefits mid-tier radiofrequency importers seeking rapid market penetration.
After-sales service unbundling is fragmenting long-term revenue streams for device manufacturers. Brazilian clinic operators now source maintenance from independent biomedical firms rather than manufacturer-captive service contracts. The behavioral shift is most visible in Rio de Janeiro's cosmetic surgery corridor, where localized partnerships reduce annual service expenditures.
Brazil Aesthetic Devices Market Segmentation
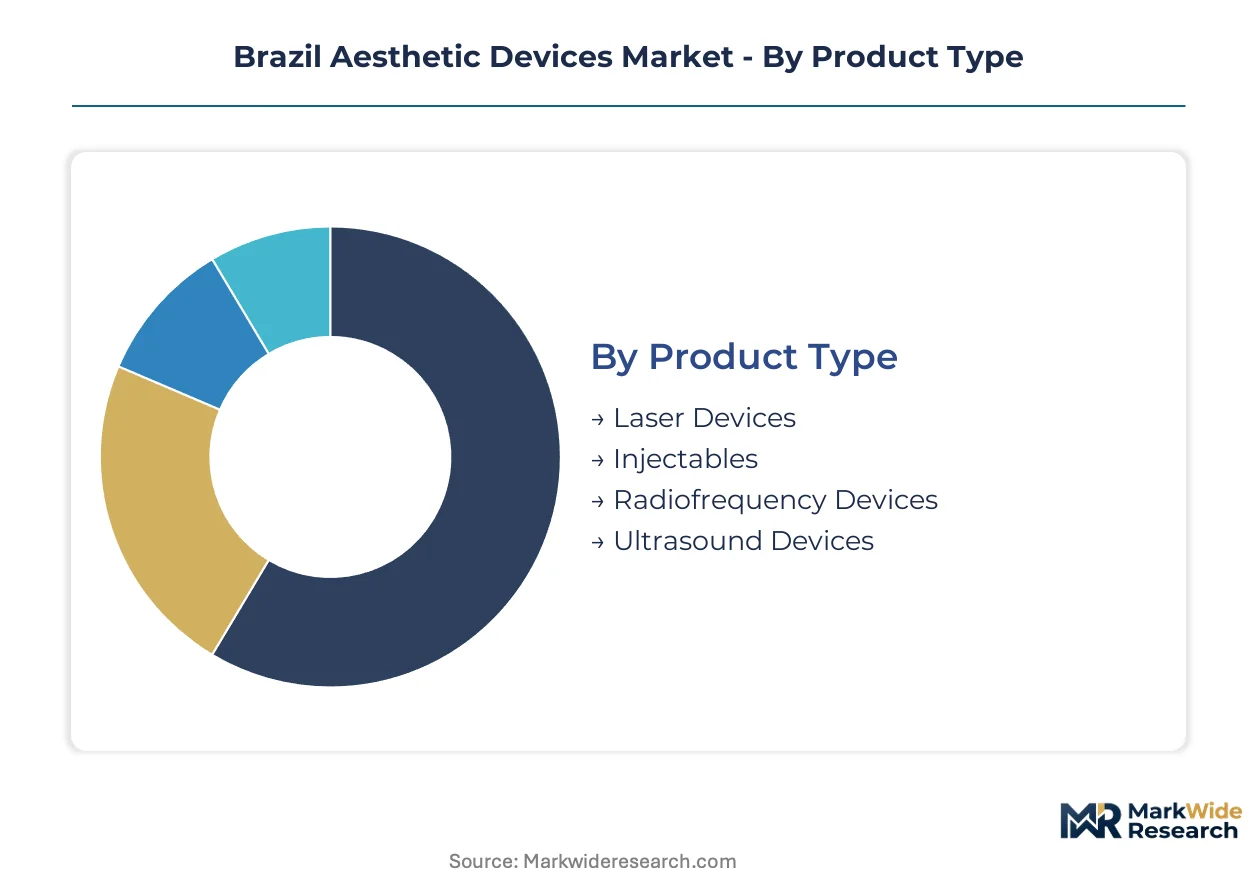
Segmentation reveals how after-sales service intensity varies dramatically across Brazil's aesthetic devices landscape. Laser platforms demand specialized biomedical engineering support concentrated in São Paulo, while radiofrequency systems tolerate broader service networks. Understanding these service-cost differentials shapes procurement strategies for clinics operating outside southeastern Brazil's technical talent corridor.
Product Type:
After-sales service intensity clusters heavily around laser and radiofrequency platforms, where thermal calibration and optical alignment demand recurring technical intervention.
- Injectables:Biologic formulations require cold-chain logistics rather than device maintenance. São Paulo dermatology clinics source hyaluronic acid and botulinum toxin products through AbbVie and Galderma distribution networks with minimal technical service overhead.
- Laser Devices:Energy-based systems utilizing CO2, erbium, and diode wavelengths generate the highest service revenue attachment rates. Optical component degradation and cooling system failures drive 15-20% lifetime cost premiums for maintenance contracts in Rio de Janeiro's high-utilization cosmetic surgery centers.
- Radiofrequency Devices:Monopolar and bipolar configurations deliver thermal energy to subcutaneous tissue layers for skin tightening protocols. Mid-tier clinics in Minas Gerais favor these systems for their mechanical simplicity and lower service dependency compared to laser alternatives.
- Ultrasound Devices:High-intensity focused ultrasound platforms penetrate at depths up to 15 mm for non-surgical fat reduction. ANVISA's recent classification clarifications have streamlined registration for Korean-manufactured systems entering the Brazilian market.
By volume, laser devices lead. By growth pace, radiofrequency platforms are gaining share fastest.
End User:
Procurement authority fragments across customer types with divergent capital deployment horizons and technical staffing capabilities.
- Dermatology Clinics:Physician-led facilities in São Paulo's Jardins district maintain dedicated biomedical technicians and refresh device fleets every 3-4 years. These clinics generate premium pricing power through specialist positioning and combination therapy protocols.
- Cosmetic Surgery Centers:Rio de Janeiro's coastal facilities attract medical tourism flows from Argentina and Colombia. High patient throughput justifies multi-platform investments and captive maintenance staffing.
- Spa and Wellness Centers:Non-medical operators face ANVISA restrictions on Class III device operation. Most concentrate on LED therapy and superficial radiofrequency systems with lower regulatory barriers.
- Home Users:Consumer-grade LED masks and microcurrent devices bypass clinic infrastructure entirely. E-commerce penetration in Brazil's southeast enables direct-to-patient distribution without intermediary service requirements.
Dermatology clinics command the highest per-device revenue yields. Home users are expanding most quickly.
Application:
Margin structures diverge sharply between procedures requiring consumable attachment and those operating on pure device economics.
- Hair Removal:Diode laser platforms dominate this high-frequency, low-margin category. São Paulo clinics compete aggressively on package pricing, compressing equipment payback periods to 18-24 months.
- Skin Rejuvenation:Fractional laser and radiofrequency combinations address photodamage and texture concerns. Brazilian patients demonstrate strong willingness to pay premium pricing for visible downtime reduction.
- Body Contouring:Cryolipolysis and high-intensity focused ultrasound systems target adipose tissue reduction without surgical intervention. Rio de Janeiro centers bundle these with lymphatic drainage protocols to differentiate service offerings.
- Wrinkle Reduction:Neurotoxin injections and dermal fillers sustain the highest per-treatment margins across Brazil's aesthetic market. Injectable demand concentrates in patients aged 35-55 with disposable income above R$15,000 monthly.
Hair removal generates the highest procedure volumes. Body contouring holds the steepest expansion trajectory.
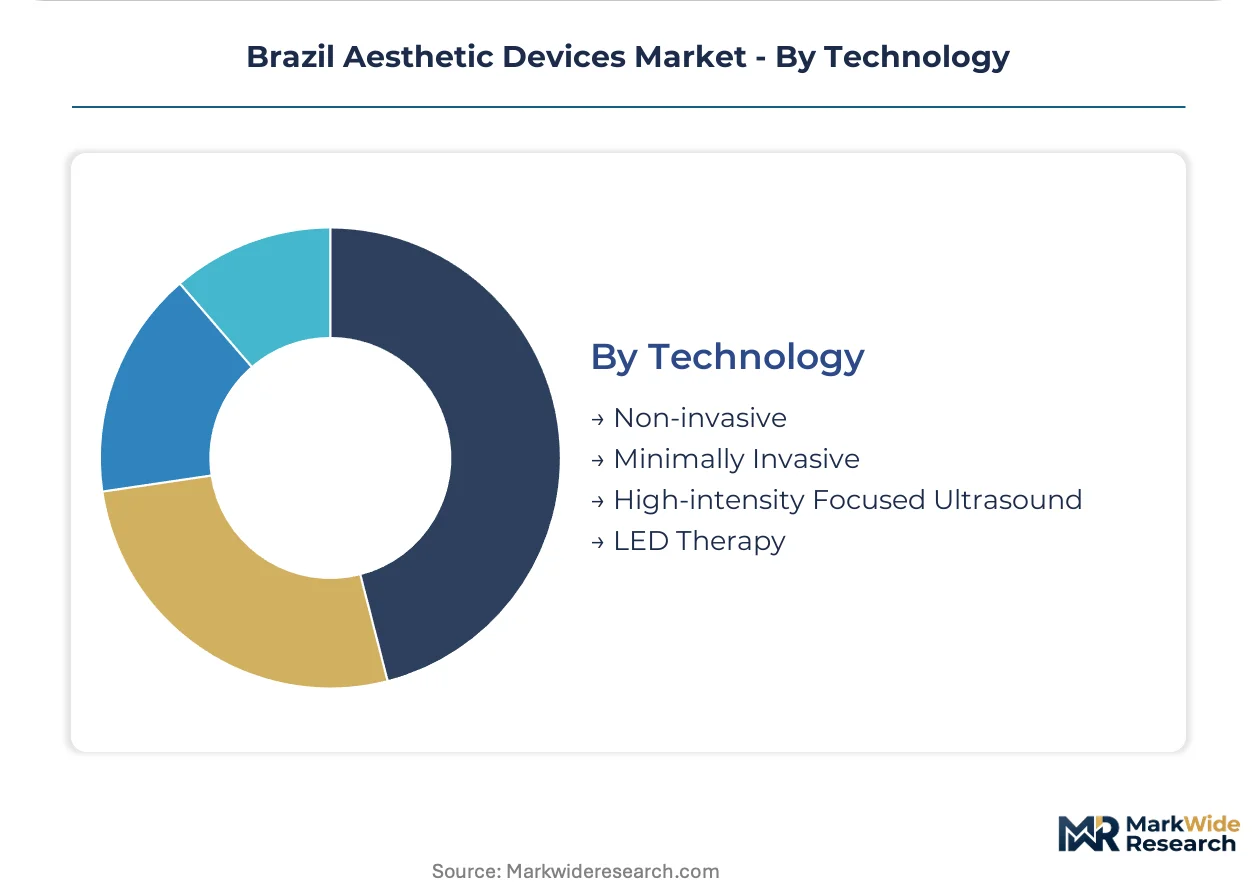
Technology:
Regulatory classification intensity shapes competitive entry patterns and post-market compliance burdens.
- Non-invasive:ANVISA's accelerated review track has compressed approval timelines for laser and radiofrequency platforms. Israeli and Korean manufacturers exploit this pathway to penetrate Brazil's southeastern corridor ahead of European competitors.
- Minimally Invasive:Injectable delivery systems and microneedling platforms occupy this category. Physician supervision requirements limit addressable market to licensed clinical settings.
- High-intensity Focused Ultrasound:Deep tissue thermal delivery at 1-2 MHz frequencies enables fat reduction and skin lifting without surface damage. Brazilian adoption lags Korean and US markets by approximately 3-4 years.
- LED Therapy:Low-level light emission at specific wavelengths addresses acne and inflammation with minimal regulatory burden. Home-use penetration is highest for this technology category.
Non-invasive technology dominates procedure counts. High-intensity focused ultrasound is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's aesthetic devices consumption concentrates in its southeastern corridor, where São Paulo and Rio de Janeiro deploy premium laser and radiofrequency platforms at substantially higher utilization rates than clinics in the northeast or interior states.
São Paulo
Dermatology clinics in the Jardins district drive demand for fractional laser and combination therapy protocols. ANVISA's accelerated review track for Class III non-invasive devices enables faster fleet refresh cycles. Physician-led facilities maintain dedicated biomedical technicians and source hyaluronic acid products through established distribution networks.
Rio de Janeiro
Cosmetic surgery centers along the coastal corridor attract medical tourism flows from Argentina and Colombia. High patient throughput justifies multi-platform investments in body contouring and skin rejuvenation systems. Localized maintenance partnerships reduce annual service expenditures compared to manufacturer-captive contracts.
Minas Gerais
Mid-tier clinics in Belo Horizonte favor radiofrequency devices for their mechanical simplicity and lower service dependency. Trained biomedical engineer scarcity extends equipment downtime compared to southeastern metros. Equipment refresh cycles lag São Paulo by four to six years.
Bahia
Salvador cosmetic surgery centers operate aging laser fleets with limited access to refurbishment channels. Candela Corporation's service network has minimal presence in this coastal market. Disposable income constraints limit addressable demand to upper-middle income segments.
Paraná
Curitiba clinics compete for scarce field service talent with São Paulo-based operators. ANVISA post-market surveillance compliance demands strain smaller clinic chains lacking dedicated regulatory affairs staffing. Korean-manufactured ultrasound systems penetrate through distributor partnerships.
Brazil Aesthetic Devices Market Competitive Environment
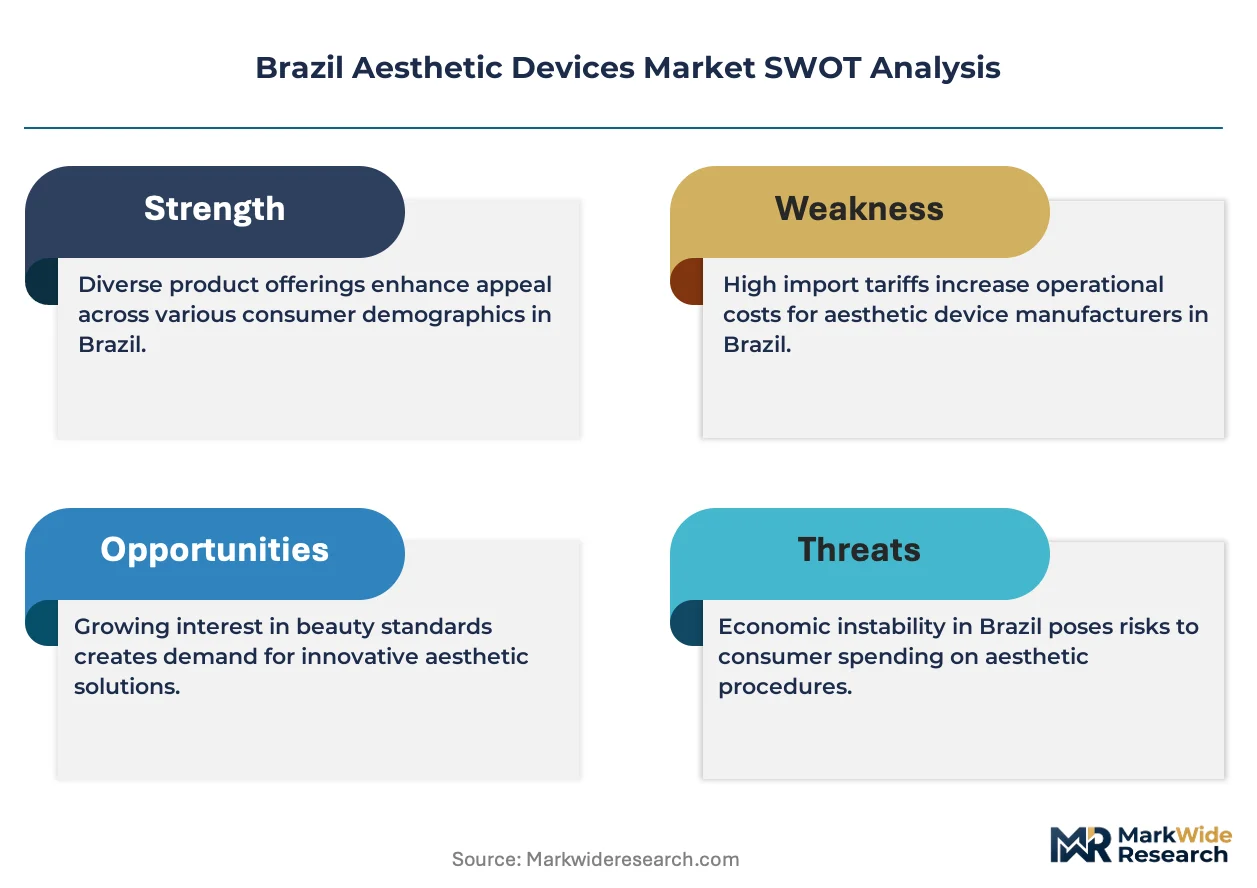
Capability concentration sits with established pharmaceutical-aesthetic conglomerates; scale advantage sits with specialized energy-based device manufacturers. The market structures around three tiers: injectable-focused biologics leaders, laser and radiofrequency platform specialists, and emerging Korean and Israeli entrants exploiting regulatory harmonization. Strategic moves cluster on localized service partnerships and combination therapy protocol development.
Within the pharmaceutical-aesthetic tier, AbbVie (Allergan Aesthetics) and Galderma occupy positions anchored by dermal filler and neurotoxin portfolios. Candela Corporation exemplifies the specialized device archetype through its laser refurbishment network. Among energy-based platform providers, Lumenis and Cutera represent Israeli and US-origin manufacturers respectively, while Sisram Medical (Alma Lasers) sits within the Chinese-backed specialty tier.
| Leading Market Players |
|---|
| AbbVie (Allergan Aesthetics) |
| Galderma |
| Cutera |
| Candela Corporation |
| Lumenis |
| Merz Pharma |
| Bausch Health Companies |
| Sisram Medical (Alma Lasers) |
| El.En. S.p.A. |
| Others |
Value Chain & Pricing Dynamics
The Port of Santos corridor shapes cost dynamics across Brazil's aesthetic devices landscape, with containerized freight rates from Israeli and Korean manufacturing hubs feeding into distributor margin structures and downstream price differentiation between São Paulo metropolitan clinics and interior state operators.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement for high-volume dermatology chains, while spot purchasing persists for mid-tier clinics in Minas Gerais and Paraná. Price differentiation rests on ANVISA registration tier and after-sales service bundling, with premium-positioned laser platforms commanding substantial markups over unbundled alternatives. Cost compression in the radiofrequency segment is intensifying as Korean manufacturers exploit regulatory harmonization to bypass traditional distributor layers. Hospital purchasing committees and GPO-affiliated cosmetic surgery centers exhibit the highest price sensitivity, whereas physician-led Jardins district clinics prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Export-control regimes on high-power laser diodes and RF generator components constrain flows from US and Israeli sources, forcing Brazilian distributors to diversify sourcing. Manufacturing concentrates in South Korea, Israel, and China, with optical subsystems and cooling modules drawing from specialized component suppliers in Germany and Japan. Single-source vulnerability sits with precision optical coatings for fractional laser platforms, where qualified vendor lists remain narrow. Distribution runs through authorized distributor networks with ANVISA import licensing, rather than direct manufacturer-to-clinic relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as São Paulo dermatology clinic chains consolidate procurement through group purchasing organizations, fragmenting vendor pricing power and compressing margin pools for distributors serving smaller interior state operators.
For Market Incumbents: Pre-empt service unbundling by capturing independent biomedical engineering firms in Rio de Janeiro and Belo Horizonte before competitors lock in localized maintenance partnerships. Anchor positioning through ANVISA regulatory affairs staffing investments that smaller clinic chains cannot replicate internally, while expanding refurbishment channel control to extend equipment lifecycles and defend against Korean price-led entrants.
For New Entrants and Emerging Players: Salvador and Recife's aging laser fleets represent immediate addressable whitespace, with equipment refresh cycles lagging southeastern benchmarks by four to six years. Target mid-tier cosmetic surgery centers in these coastal cities through distributor partnerships offering bundled technical training, leveraging ANVISA's accelerated review track to compress market entry timelines against established European competitors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized radiofrequency platform developers with proprietary electrode configurations and service network density in Brazil's southeastern corridor. Long-term viability hinges on combination therapy protocol development that locks in physician loyalty through superior clinical outcomes. Watch Korean manufacturer market share trajectories as the inflection signal for pricing pressure intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Fast-Track Registration | Accelerated approval timelines compress competitive entry barriers for non-invasive laser and radiofrequency platforms. |
| Localized Service Partnership | Independent biomedical engineering alliances in interior states reduce clinic downtime and capture aftermarket revenue streams. |
| Combination Therapy Protocol Development | Sequential radiofrequency and injectable treatment bundling raises per-patient yields above standalone procedure economics. |
| Refurbishment Channel Expansion | Equipment lifecycle extension through certified pre-owned programs defends margin pools against price-led Korean entrants. |
| Medical Tourism Infrastructure Investment | Rio de Janeiro coastal corridor positioning attracts Latin American patients and sustains premium device utilization rates. |
Study Parameters
A spread of perspectives from dermatology clinic operators, biomedical engineering service providers, ANVISA regulatory consultants, distributor procurement managers, and cosmetic surgery center administrators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through ANVISA registration databases, Brazilian Ministry of Health safety benchmark publications, and customs import records for medical device classifications. Bottom-up clinic fleet inventories and top-down manufacturer shipment estimates were triangulated to establish baseline market sizing.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeled across product type, end user archetype, application protocol, and technology classification intensity. CAGRs were derived from fitted adoption curves calibrated to observed replacement cycles and fleet expansion patterns. Key inputs included ANVISA review timeline compression effects, regional technician density differentials, and medical tourism patient flow trajectories from Argentina and Colombia.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Korean manufacturers or accelerated regulatory harmonization beyond MFDS alignment would shift outcomes. Material shifts in Brazil's medical device tax structure or ANVISA post-market surveillance enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Mechanical Ventilator Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Contact Lenses Market
Medical Devices
Global Robotic Endoscopy Devices Market
Medical Devices
At-Home Laser Hair Removal Devices Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
Australia General Surgical Devices Market
Medical Devices
Global Photobiostimulation Market
Medical Devices
Critical Care Devices Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Europe Ambulatory Infusion Pumps Market
Medical Devices
Anorectal Manometry Systems Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Craniomaxillofacial Devices Market