
 Minimally Invasive Laser Therapy Devices Market | 2026-2036
Minimally Invasive Laser Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Minimally Invasive Laser Therapy Devices Market Foresight
Software-defined wavelength modulation is hardening as a recurring revenue layer that reshapes procurement economics for minimally invasive laser platforms. Boston Scientific Corporation leverages integrated service contracts to lock in multi-year hospital commitments across its interventional laser portfolio. Medtronic sustains R&D intensity in fiber-optic delivery systems that extend its cardiovascular laser applications. Alma Lasers dominates aesthetic laser segments through channel control in Asia-Pacific dermatology clinics.
Minimally invasive laser therapy devices employ coherent light sources—typically Nd:YAG, diode, or CO2 variants—delivered through flexible fiber optics or articulated arms at wavelengths between 532 nm and 10,600 nm to ablate, coagulate, or photocoagulate tissue with thermal precision below 1 mm collateral damage zones. Diode lasers lead in unit volume across outpatient settings due to compact footprint and reduced cooling infrastructure, while fiber lasers capture margin pools in ophthalmology where sub-micron beam stability governs retinal procedure outcomes. Dermatology applications in hair removal and vascular lesion treatment remain mature revenue basins, whereas robotic delivery modes in urology represent the fastest-expanding configuration as prostate and kidney stone procedures shift toward computer-navigated ablation.
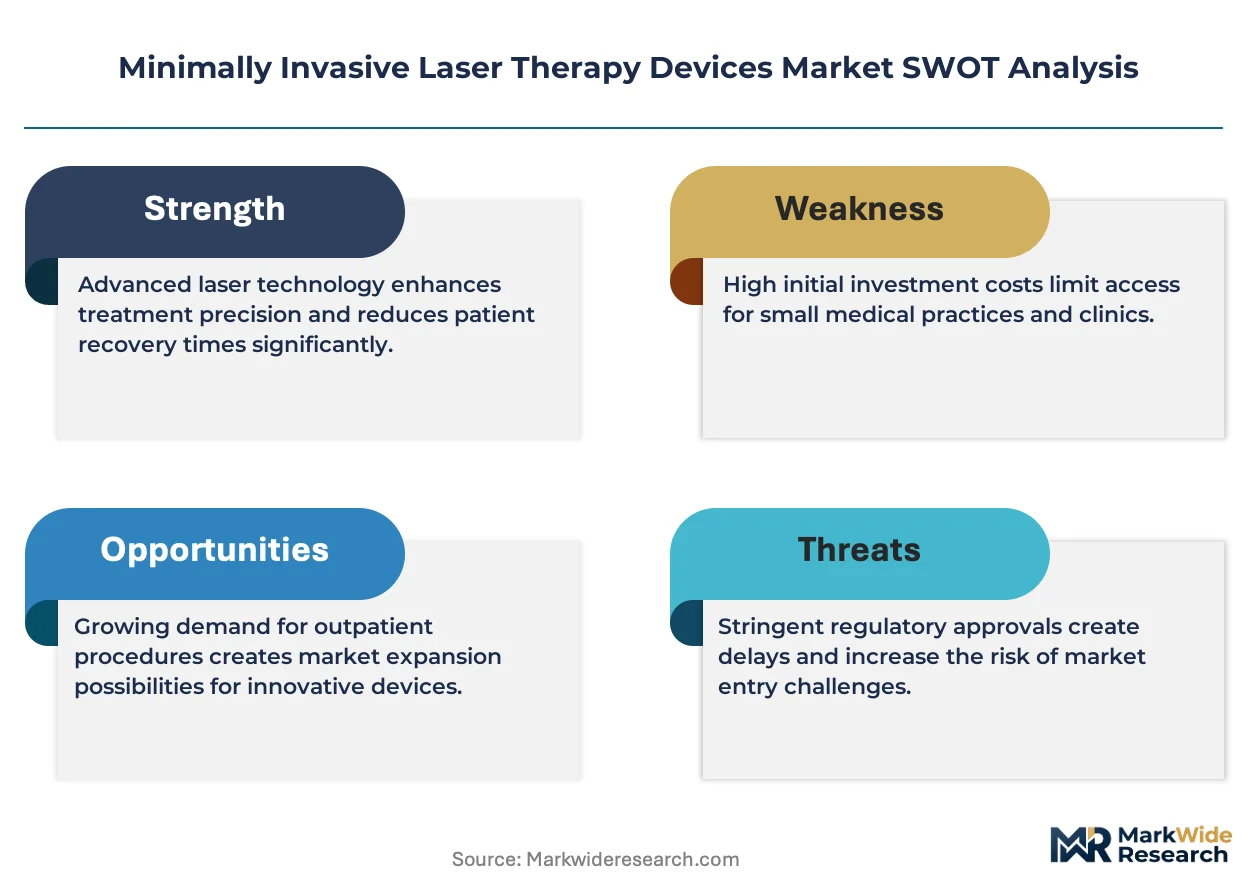
FDA 510(k) premarket notification and the EU Medical Device Regulation (MDR) impose escalating clinical evidence requirements on laser system manufacturers, directly shaping product development timelines and market access costs for new entrants. ISO 13485 quality management certification and IEC 60601-1-2 electromagnetic compatibility standards further constrain supply-side participation to firms with established regulatory infrastructure. Stakeholders must monitor evolving reimbursement codes for office-based laser procedures as payor policies increasingly determine whether ambulatory deployment outpaces hospital-based installation.
Market Dynamics
Software-defined wavelength modulation is hardening procurement economics for minimally invasive laser platforms, locking hospitals into multi-year service contracts that displace capital equipment purchases.
Growth Catalysts
- Ambulatory Surgical Center Expansion:Outpatient laser procedures are displacing traditional operating room visits across Germany and the United States, with university hospitals in Heidelberg anchoring clinical adoption of robotic-assisted delivery systems.
- FDA 510(k) Pathway Efficiency:Streamlined premarket notification for diode and fiber laser variants accelerates commercialization timelines for manufacturers with established quality management systems.
- Robotic Delivery Integration:Computer-navigated ablation systems in urology are capturing procedure volume from conventional laparoscopic techniques, particularly in prostate and kidney stone applications.
Market Restraints
- MDR Technical Documentation Burden:EU Medical Device Regulation imposes escalating clinical evidence requirements that extend product development timelines and inflate market access costs for new entrants.
- Fiber-Optic Supply Concentration:Specialized silica fiber production concentrates among Japanese and German suppliers, creating input vulnerability for cardiovascular laser manufacturers.
- Cooling Infrastructure Requirements:CO2 and Nd:YAG systems demand substantial capital investment in thermal management, constraining deployment in resource-limited outpatient settings.
Strategic Opportunities
- Asia-Pacific Dermatology Channel Control:Underpenetrated aesthetic laser segments in South Korea and Singapore offer expansion potential through clinic network partnerships.
- Integrated Service Contract Models:Software-defined wavelength platforms enable recurring revenue streams that reshape hospital procurement from capital expenditure to operational budgeting.
- Reimbursement Code Evolution:Payor policy shifts toward office-based laser procedures in the United States create tailwinds for ambulatory deployment over hospital-based installation.
Industry Challenges
- Electromagnetic Compliance Certification:IEC 60601-1-2 testing requirements for laser systems impose extended validation cycles that delay product launches.
- Interventional Cardiology Talent Pipeline:Fiber-optic delivery expertise remains concentrated among aging specialist cohorts, constraining training capacity for next-generation operators.
- Legacy Hospital IT Integration:Robotic laser delivery systems require costly interface development with existing electronic health record and surgical navigation infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minimally Invasive Laser Therapy Devices Market |
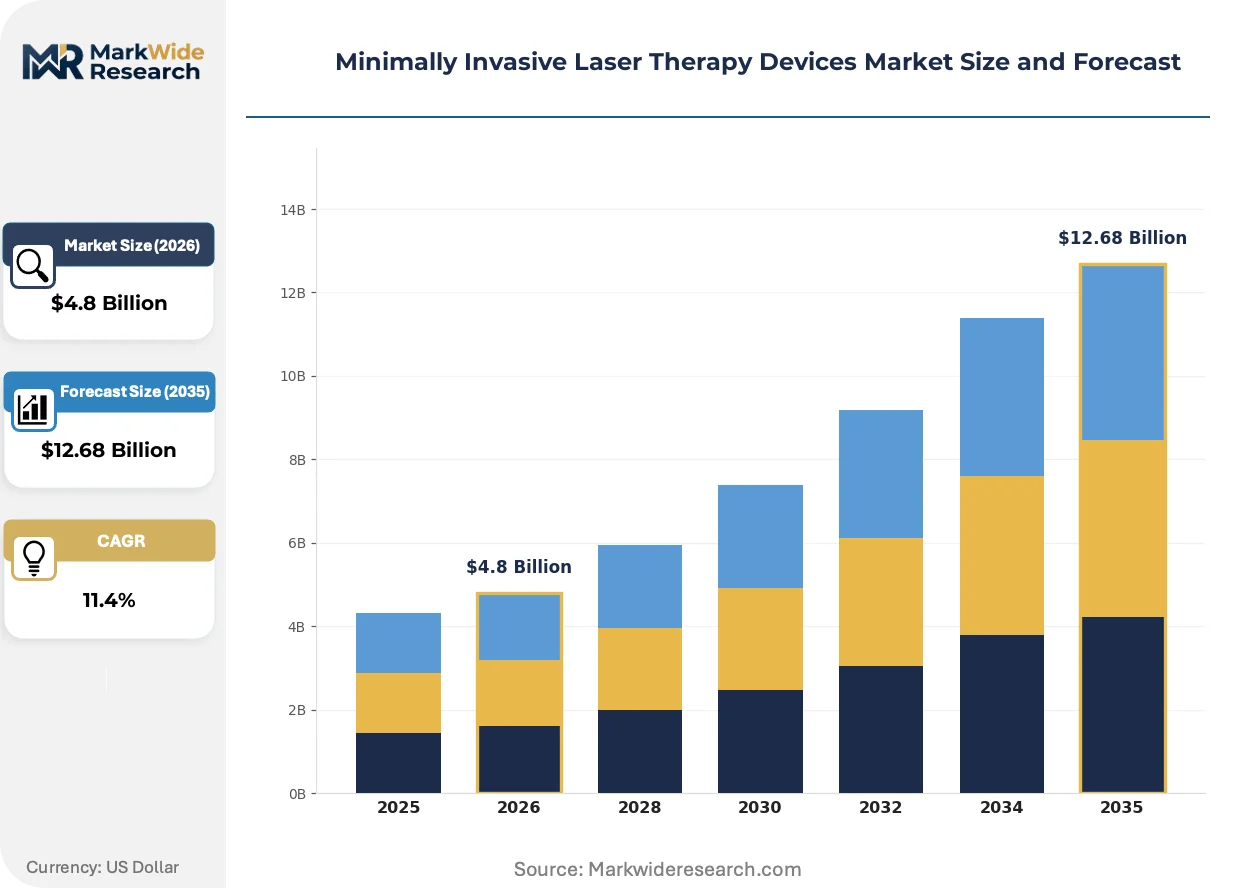
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Power Lasers, Fiber Lasers, Diode Lasers, CO2 Lasers Therapy Area: Dermatology, Ophthalmology, Orthopedics, Urology End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions Delivery Mode: Contact, Non-Contact, Hybrid, Robotic |
| Companies Covered | Boston Scientific Corporation, Medtronic, TE Connectivity, Cynosure, Biolitec AG, IRIDEX Corporation, Alma Lasers, Lumenis Be Ltd., AngioDynamics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minimally Invasive Laser Therapy Devices Market Shifts & Advancements
Wavelength-tunable diode architectures are compressing the traditional segmentation between aesthetic and surgical laser applications, forcing manufacturers to reconceptualize platform design around service-based revenue models.
Multi-wavelength diode engines are unifying previously separate hair removal, vascular lesion, and pigmentation treatment modalities into single-platform configurations. Dermatology clinics in Seoul and Singapore are adopting these systems at accelerated replacement cycles. This unification is compressing equipment footprint requirements and enabling subscription-based pricing that displaces outright purchase models.
EU MDR Article 10 technical documentation mandates now require post-market clinical follow-up data for all Class IIb laser systems, including those with predicate device histories. Manufacturers must maintain systematic literature review protocols and periodic safety update reports. Ophthalmology fiber laser suppliers face the steepest compliance burden due to retinal procedure risk classifications.
After-sales service unbundling is fragmenting traditional equipment vendor relationships as hospital procurement teams separately negotiate maintenance, software updates, and consumable supply agreements. Ambulatory surgical centers in Germany and the United States are driving this disintermediation, favoring third-party service providers over manufacturer-captive contracts. This pattern is most visible in cardiovascular laser applications where fiber-optic replacement cycles create predictable aftermarket revenue pools.
Minimally Invasive Laser Therapy Devices Market Segmentation
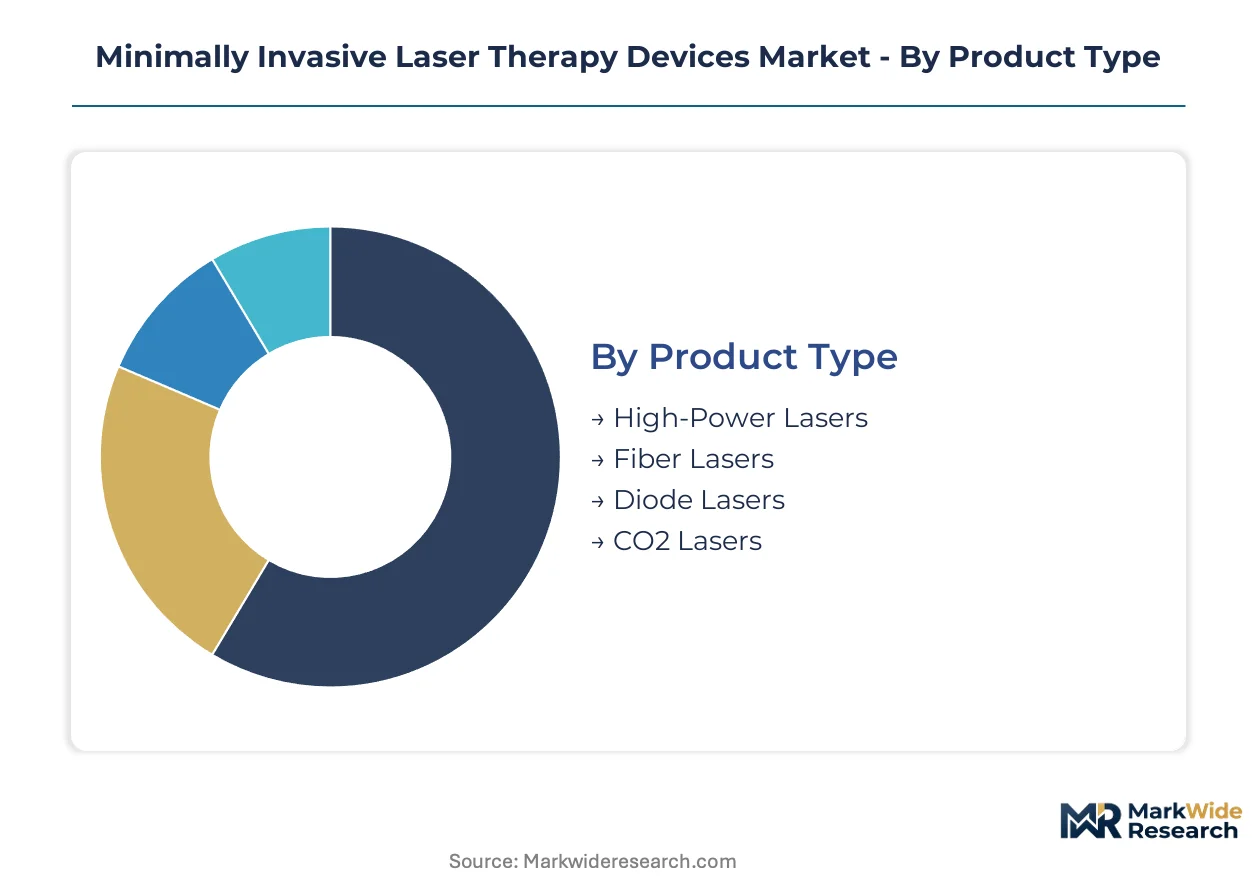
Segmentation in minimally invasive laser therapy devices reveals how procurement decisions split between high-volume outpatient configurations and precision surgical platforms. Understanding these divisions exposes where manufacturers can capture recurring revenue versus one-time capital sales.
Product Type:
Standardization dominates diode and CO2 platforms, while fiber and high-power systems demand extensive customization for surgical subspecialties.
- Diode Lasers:Compact solid-state designs operating at 800-1000 nm wavelengths with minimal cooling infrastructure. Demand concentrates in German and US dermatology clinics where outpatient hair removal and vascular procedures displace hospital-based treatment. Reduced footprint and plug-and-play deployment accelerate ambulatory adoption.
- Fiber Lasers:Doped silica gain media delivering sub-micron beam stability through flexible waveguides. Heidelberg university hospitals anchor clinical uptake for retinal photocoagulation where thermal precision below 0.5 mm governs outcomes. FDA 510(k) predicate pathways streamline commercialization for established manufacturers.
- High-Power Lasers:Nd:YAG and erbium variants exceeding 50W output for deep tissue ablation with articulated arm delivery.
- CO2 Lasers:10,600 nm gas discharge systems requiring substantial thermal management infrastructure for dermatological resurfacing.
Most installed capacity flows through Diode Lasers. Expansion is steepest in Fiber Lasers.
Therapy Area:
Maturity gradients separate established aesthetic applications from emerging robotic surgical configurations across clinical specialties.
- Dermatology:Mature revenue basin encompassing hair removal, vascular lesion treatment, and skin resurfacing modalities. Seoul and Singapore clinic networks drive replacement cycles for multi-wavelength platforms. Subscription pricing models displace outright equipment purchases.
- Urology:Computer-navigated ablation systems for prostate and kidney stone procedures capture volume from conventional laparoscopy. German ambulatory surgical centers lead robotic delivery adoption. Reimbursement code evolution toward office-based procedures accelerates deployment.
- Ophthalmology:Retinal photocoagulation and capsulotomy applications demanding sub-micron beam stability.
- Orthopedics:Cartilage reshaping and soft tissue release procedures with emerging robotic guidance integration.
Dermatology retains the largest installed base. Urology climbs the fastest as robotic integration reshapes procedural economics.
End User:
Capital intensity and service contract structures diverge sharply between integrated hospital networks and fragmented outpatient operators.
- Ambulatory Surgical Centers:Outpatient laser procedures displace traditional operating room visits across Germany and the United States. Procurement teams separately negotiate maintenance, software updates, and consumable agreements. Third-party service providers win preference over manufacturer-captive contracts.
- Hospitals:University medical centers in Heidelberg and Berlin anchor robotic-assisted laser delivery adoption. Multi-year integrated service contracts lock in commitments across interventional portfolios. Legacy IT integration costs constrain rapid system replacement.
- Clinics:Dermatology and ophthalmology practices with compressed equipment footprint requirements.
- Research Institutions:Preclinical and clinical trial settings for wavelength-tunable platform validation.
Hospitals maintain the deepest installed base. Ambulatory Surgical Centers gain share fastest as payor policies shift reimbursement toward outpatient settings.
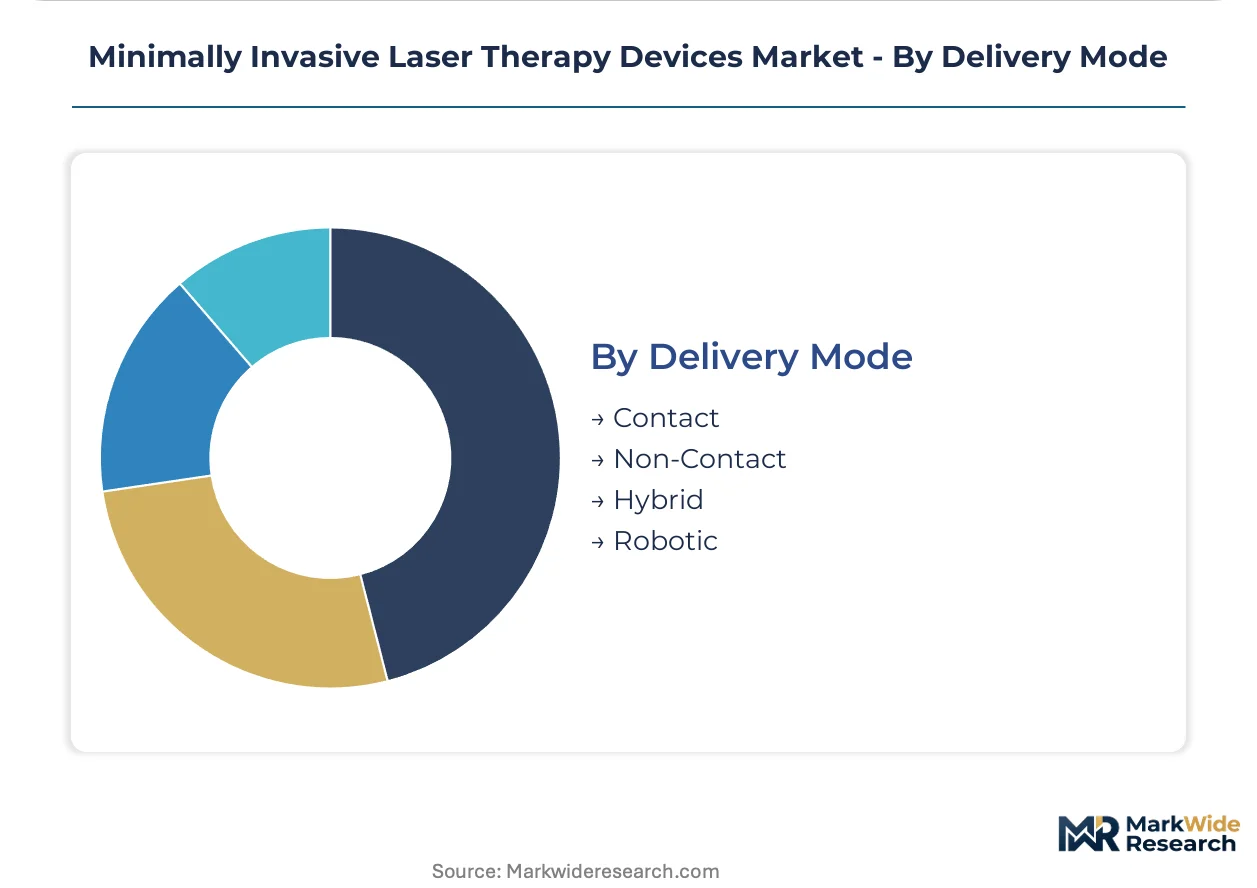
Delivery Mode:
Precision requirements and capital investment thresholds stratify adoption between manual techniques and computer-navigated configurations.
- Robotic:Computer-navigated ablation with real-time tissue tracking and automated beam positioning. Urology applications in prostate procedures concentrate demand in German university hospitals. FDA clearance pathways for 510(k) systems accelerate commercialization timelines.
- Contact:Direct fiber-optic or handpiece tissue interface for controlled thermal delivery.
- Non-Contact:Articulated arm or free-beam configurations for surface ablation without mechanical tissue interaction.
- Hybrid:Switchable contact and non-contact modalities for multi-procedure flexibility.
Contact systems retain the broadest installed footprint. Robotic configurations expand most quickly as surgical navigation infrastructure penetrates outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are arbitraging compliance costs by shifting final assembly toward jurisdictions with streamlined 510(k) pathways while maintaining R&D clusters in high-regulation markets. This geographic split separates revenue capture from regulatory burden.
United States
FDA 510(k) premarket notification pathways accelerate commercialization for diode and fiber laser variants, concentrating new product launches in California and Massachusetts medical technology corridors. Ambulatory surgical centers in Texas and Florida drive outpatient procedure volume displacement from hospital operating rooms. Reimbursement code evolution toward office-based laser procedures creates procurement tailwinds for third-party service providers.
Germany
EU MDR Article 10 technical documentation mandates extend development timelines for Class IIb laser systems, favoring established manufacturers with systematic post-market clinical follow-up protocols. Heidelberg and Berlin university hospitals anchor robotic-assisted laser delivery adoption for urology applications. Baden-Württemberg precision engineering clusters supply fiber-optic delivery components to cardiovascular laser manufacturers.
China
NMPA medical device registration requirements are tightening clinical evidence standards for imported laser systems, creating compliance barriers for foreign entrants. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou dominate domestic diode laser production for dermatology applications. Local procurement preferences in tier-one hospitals favor indigenous wavelength-tunable platforms.
Japan
METI industrial standards for medical laser safety impose extended electromagnetic compatibility validation cycles that delay product launches. Tokyo and Osaka metropolitan areas concentrate demand for ophthalmology fiber lasers where sub-micron beam stability governs retinal procedure outcomes. PMDA quality management certification requirements constrain supply-side participation to firms with established regulatory infrastructure.
South Korea
MFDS medical device approval pathways prioritize locally conducted clinical trials, extending market access timelines for foreign manufacturers. Seoul clinic networks drive accelerated replacement cycles for multi-wavelength diode platforms in aesthetic applications. Subscription-based pricing models displace outright equipment purchases across Gangnam district dermatology practices.
Minimally Invasive Laser Therapy Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated device vendors capturing margin pools in surgical applications while OEM suppliers dominate aesthetic laser commoditization. The vendor base concentrates around three strategic archetypes: diversified medtech conglomerates with interventional portfolios, pure-play laser specialists with channel control in dermatology, and component suppliers with fiber-optic delivery expertise. M&A activity targets wavelength-tunable platform capabilities, while strategic partnerships lock in multi-year service contracts that displace capital equipment purchases.
Within the diversified medtech tier, Boston Scientific Corporation and Medtronic exemplify integrated service contract models that reshape hospital procurement economics. Alma Lasers occupies a position representing channel control specialists with Asia-Pacific dermatology clinic penetration. These three anchors illustrate how competitive positioning stratifies between recurring revenue platforms and capital sales dependence.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| TE Connectivity |
| Cynosure |
| Biolitec AG |
| IRIDEX Corporation |
| Alma Lasers |
| Lumenis Be Ltd. |
| AngioDynamics, Inc. |
| Others |
Supply & Pricing Matrix
Wavelength-tunable diode architectures compressing aesthetic and surgical laser applications simultaneously reshape cost economics and supply concentration by forcing manufacturers toward service-based revenue models that decouple hardware margins from recurring software tiers.
Pricing Analysis
Distributor margins on diode laser systems range from 15-25 percent for standard configurations versus 8-12 percent for robotic delivery platforms where manufacturers sell direct-to-hospital under multi-year service contracts. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) predicate status and ISO 13485 certification grade. Cost compression in economy-tier diode systems is intensifying because Chinese manufacturers are flooding Asian dermatology channels with unbundled hardware. Ambulatory surgical centers exhibit highest price sensitivity due to capital budget constraints, while German university hospitals prioritize beam stability specifications over unit cost.
Supply Chain Analysis
Freight costs for specialized silica fiber-optic components from Japanese and German suppliers add 3-5 percent to landed costs for cardiovascular laser manufacturers assembling in the United States. Fiber-optic gain media production concentrates in Japan, Germany, and the United States, while diode laser chip fabrication draws from Chinese and South Korean foundries. Single-source vulnerability in high-purity silica preform supply creates exposure for retinal photocoagulation system builders. Distribution runs through manufacturer-direct sales teams for robotic platforms and regional distributors for aesthetic diode systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in minimally invasive laser therapy devices rests on software-defined wavelength platforms that convert capital sales into recurring service revenue, offsetting hardware commoditization in aesthetic segments.
For Market Incumbents: Extend integrated service contract coverage to lock in ambulatory surgical center relationships before third-party service providers capture aftermarket revenue pools. Deepen backward integration into fiber-optic delivery component production to reduce exposure to Japanese and German supplier concentration. Invest in MDR Article 10 technical documentation capabilities to extend compliance moats against emerging competitors lacking systematic post-market clinical follow-up protocols.
For New Entrants and Emerging Players: Enter via underpenetrated Asia-Pacific dermatology channels in South Korea and Singapore where subscription pricing models are displacing outright equipment purchases. Target multi-wavelength diode platforms for aesthetic clinic networks seeking compressed equipment footprints. Pursue white-label manufacturing partnerships with Yangtze River Delta production hubs to bypass NMPA registration barriers for imported systems.
For Investors and Strategic Acquirers: Valuations sit cheapest among component suppliers with fiber-optic delivery expertise rather than integrated device vendors facing hardware margin compression. Five-to-ten year viability favors firms with wavelength-tunable platform architectures and established regulatory infrastructure. Monitor FDA 510(k) clearance velocity for robotic urology systems as inflection indicator for procedural volume shifts toward computer-navigated ablation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Streamlined premarket notification accelerates commercialization timelines for diode laser variants in Texas and Florida ambulatory networks. |
| MDR Technical Documentation Investment | Systematic post-market clinical follow-up protocols extend compliance moats against emerging competitors lacking EU regulatory infrastructure. |
| Software-Defined Wavelength Development | Service-based revenue conversion offsets hardware commoditization in Seoul and Singapore aesthetic clinic channels. |
| Fiber-Optic Delivery Backward Integration | In-house silica fiber production reduces single-source vulnerability to Japanese and German component suppliers. |
| Hospital System Partnership Expansion | Multi-year integrated service contracts lock in Heidelberg and Berlin university hospital commitments across interventional portfolios. |
Research Methodology
Bottom-up ambulatory surgical center and hospital procurement modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and dermatology clinic operators were combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement code repositories, and hospital procurement system records. Triangulation across these sources ensures segmentation integrity across product type, therapy area, end user, and delivery mode dimensions.
Historical trendline analysis of diode and fiber laser unit shipments informed projection frameworks across the analysis window. Segmentation dimensions modeled include laser source architecture, clinical specialty application, facility type capital intensity, and robotic versus manual delivery configuration. CAGRs were derived from slope analysis of normalized adoption curves weighted by reimbursement code evolution and regulatory pathway efficiency. Forecast inputs incorporated MDR compliance cost trajectories and ambulatory surgical center construction permits.
Inputs from FDA premarket notification databases and EU MDR Article 10 technical documentation repositories were available through the study window; gaps in real-time ambulatory surgical center procurement transaction data introduce uncertainty bands around near-term volume estimates. Forecasts reflect assumptions regarding reimbursement policy continuity and fiber-optic supply chain stability. A model refresh is warranted upon material change in CMS office-based procedure reimbursement codes or NMPA registration requirements for imported laser systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Elbow Fixators Market
Medical Devices
Pulmonary Function Testing System Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
US Pulse Oximeters Market
Medical Devices
Canada Varicose Vein Treatment Devices Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
Knee Braces Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
Cranial Closure and Fixation Devices Market
Medical Devices
Catheter Coatings Market