
 Tissue Processing Systems Market | 2026-2036
Tissue Processing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Processing Systems Market Outlook
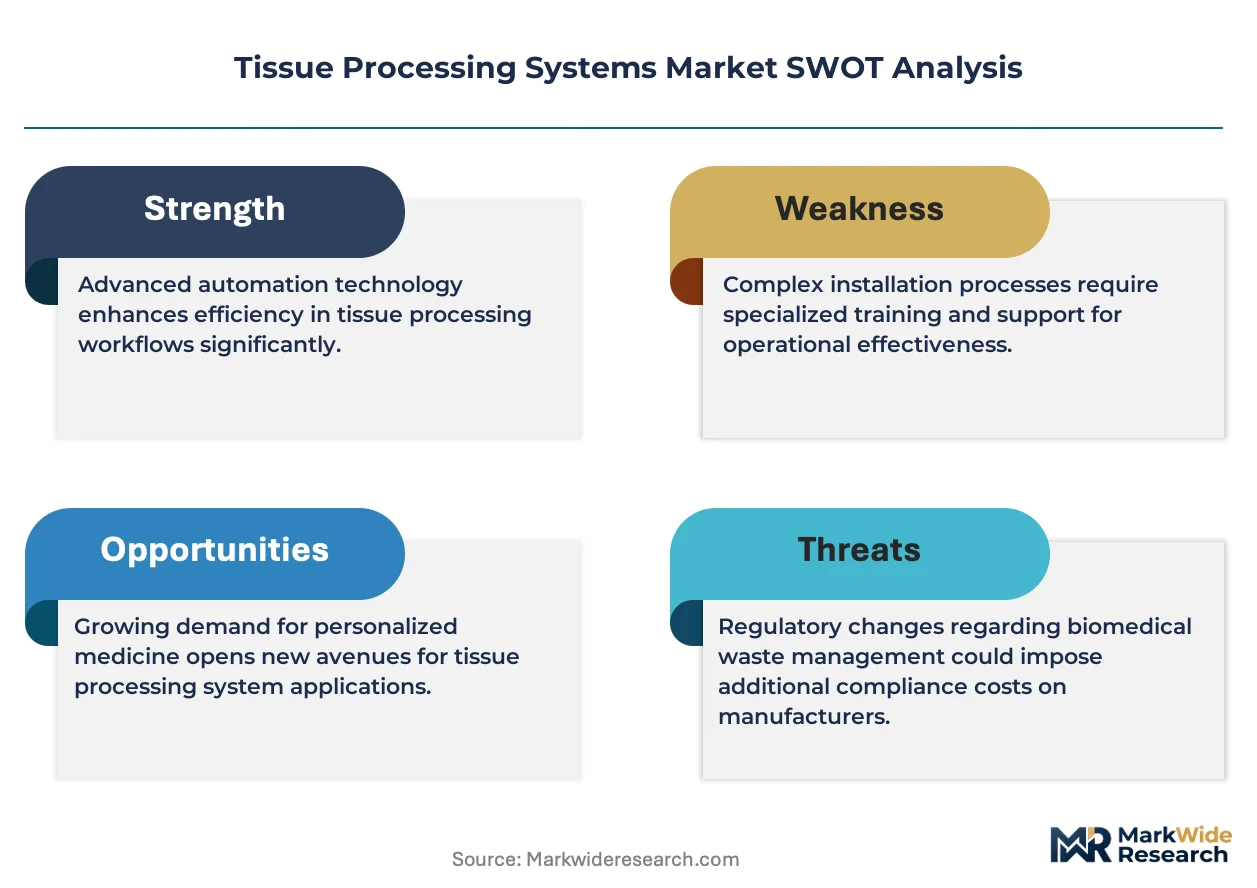
Paraffin wax formulations are decoupling from petroleum-derived feedstocks as bio-based alternatives gain cost parity in tissue processing workflows. Thermo Fisher Scientific leverages its life sciences distribution network to sustain instrument placement rates across hospital pathology departments. Leica Biosystems anchors its competitive position through embedded workflow software that integrates microtomy with digital pathology platforms. Sakura Finetek differentiates via vacuum impregnation technology leadership in high-throughput clinical laboratories.
Tissue processing systems comprise automated, manual, and hybrid instruments that prepare biological specimens for histological examination through dehydration, clearing, and paraffin infiltration cycles operating at precise temperature gradients between 45°C and 65°C. These systems enable pathologists to generate thin-section slides for disease diagnosis and cancer staging in clinical and research settings. Automated processors command the primary margin pool as laboratories prioritize walkaway efficiency and standardized turnaround times. Diagnostic laboratories represent the fastest-growing end-user channel as outsourced histopathology services expand regionally. Chemical fixation technology retains entrenched clinical adoption despite cryostat advances in intraoperative consultation settings.
The FDA enforces quality system regulation and premarket notification requirements that govern tissue processor safety validation and manufacturing documentation. ISO 15189 accreditation standards for medical laboratories drive demand for processors with automated reagent tracking and audit trail capabilities. The Clinical Laboratory Improvement Amendments framework shapes staffing and equipment competency requirements in hospital-based pathology units. Stakeholders must monitor evolving digital pathology interoperability standards as whole-slide imaging integration reshapes instrument specification criteria.
Market Dynamics
The diagnostic laboratory sector is consolidating procurement authority into centralized supply chains that favor automated tissue processors with integrated reagent tracking and digital pathology compatibility.
Growth Catalysts
- CLIA Laboratory Accreditation:The Clinical Laboratory Improvement Amendments mandate competency documentation for histopathology equipment, driving replacement cycles toward processors with automated audit trails and remote monitoring capabilities.
- Digital Pathology Convergence:Whole-slide imaging platforms require standardized specimen preparation workflows, compelling laboratories to upgrade from manual to automated processing systems for image quality consistency.
- Histopathology Outsourcing:Commercial diagnostic laboratories in the United States are expanding regional reference networks, creating concentrated demand for high-throughput vacuum impregnation systems.
Market Restraints
- Petroleum-Derived Paraffin Volatility:Conventional paraffin wax formulations face feedstock price instability, compressing margins for processors dependent on traditional infiltration media.
- Capital Equipment Concentration:Academic medical centers in the United States control a disproportionate share of new system placements, creating demand vulnerability to federal research funding fluctuations.
- Cryostat Substitution:Frozen section technology advances in intraoperative consultation settings limit penetration of rapid microwave processing systems in surgical pathology.
Strategic Opportunities
- Bio-Based Paraffin Formulations:Plant-derived infiltration media achieving cost parity with petroleum alternatives open positioning for sustainable workflow marketing in environmentally accredited laboratories.
- Research Histology Services:Contract research organizations handling toxicology and preclinical studies represent an underpenetrated channel requiring specialized large-volume processing protocols.
- ISO 15189 Compliance Mandates:Medical laboratory accreditation expansion across European healthcare systems creates specification requirements for processors with automated reagent traceability and quality control documentation.
Industry Challenges
- Histotechnologist Workforce Constraints:The American Society for Clinical Pathology reports sustained vacancy rates in histology technician positions, limiting operational capacity for complex manual processing workflows.
- Legacy System Integration:Hospital pathology departments with embedded Leica Biosystems or Sakura Finetek installations face switching costs when migrating to integrated digital pathology platforms requiring new processing protocols.
- FDA Quality System Documentation:Premarket notification requirements for modified tissue processors impose validation timelines that delay product iteration cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Processing Systems Market |
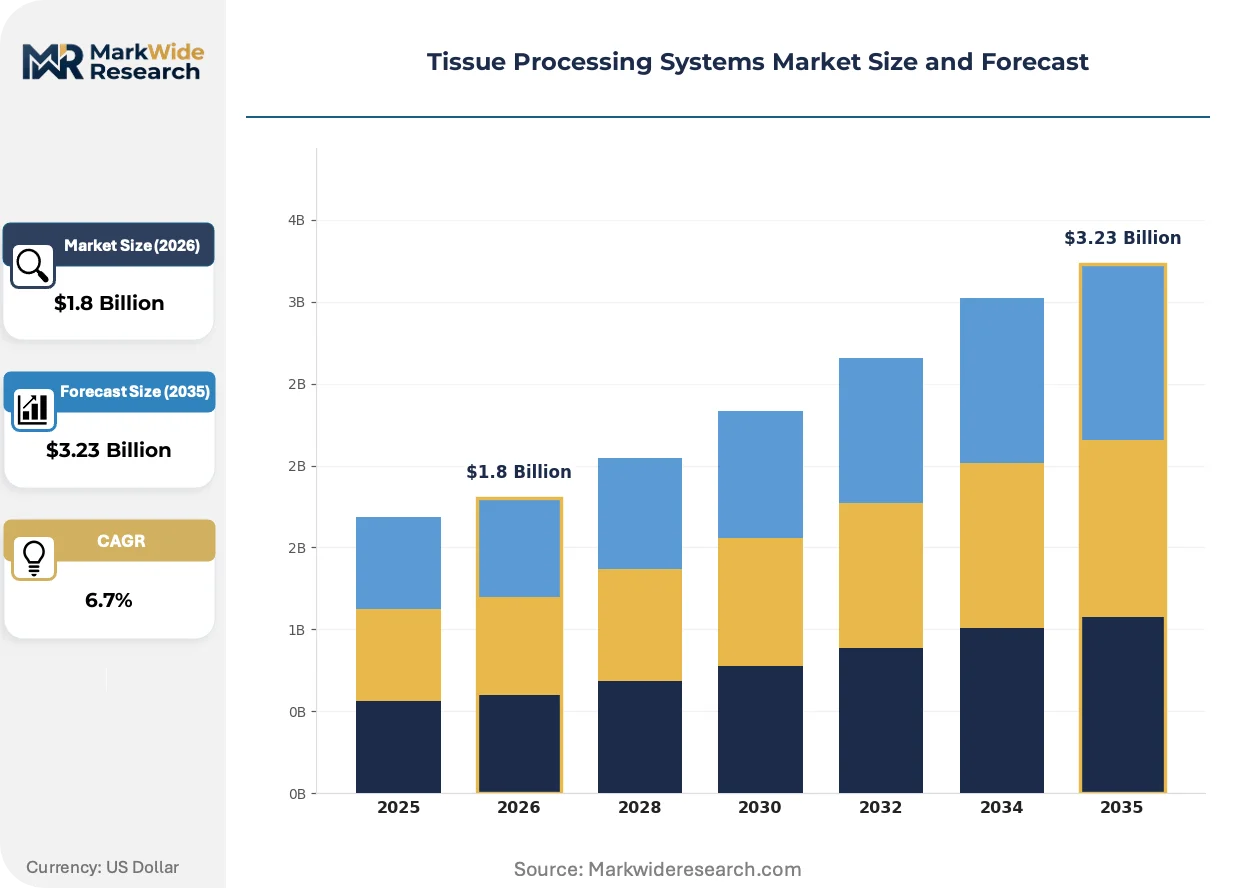
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Processors, Manual Processors, Hybrid Processors, Tissue Embedding Stations End User: Hospitals, Diagnostic Laboratories, Research Institutes, Forensic Laboratories Technology: Microtomy, Cryostats, Vacuum Impregnation, Chemical Fixation Application: Pathology, Histology, Cancer Research, Biomedical Research |
| Companies Covered | Milestone Medical, Histo-Line Laboratories, Thermo Fisher Scientific, Roche Diagnostics, Agilent Technologies, Leica Biosystems, Epredia, SLEE medical, Sakura Finetek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Processing Systems Market Strategic Shifts
Automation architectures are fragmenting into component-based configurations that permit laboratories to upgrade specific processing stages without full system replacement. This modularity is compressing capital commitment thresholds and reshaping vendor service revenue models.
Microwave-assisted tissue processing is modularizing around interchangeable chamber designs that accommodate varying specimen batch sizes. Mid-sized hospital laboratories in the United States are adopting these configurations to bridge between low-volume manual workflows and high-throughput vacuum systems. The technology is modularizing capital deployment by allowing pathology departments to scale processing capacity through add-on units rather than forklift upgrades.
REACH chemical registration requirements in Europe are restricting traditional clearing agent formulations, compelling processor manufacturers to validate xylene-free and low-toxicity reagent protocols. The regulation is accelerating substitution timelines for conventional dehydration chemistry. Histopathology service providers in Germany and France are prioritizing processors with validated green chemistry compatibility to preempt operational disruption.
Consolidated purchasing organizations are unbundling service contracts from equipment procurement, shifting pathology departments toward third-party maintenance providers and consumables sourcing flexibility. This disintermediation pressures original equipment manufacturers to defend placement through software lock-in rather than captive service agreements. The pattern is most visible in United States health system networks where supply chain rationalization has centralized capital approval authority.
Tissue Processing Systems Market Segmentation
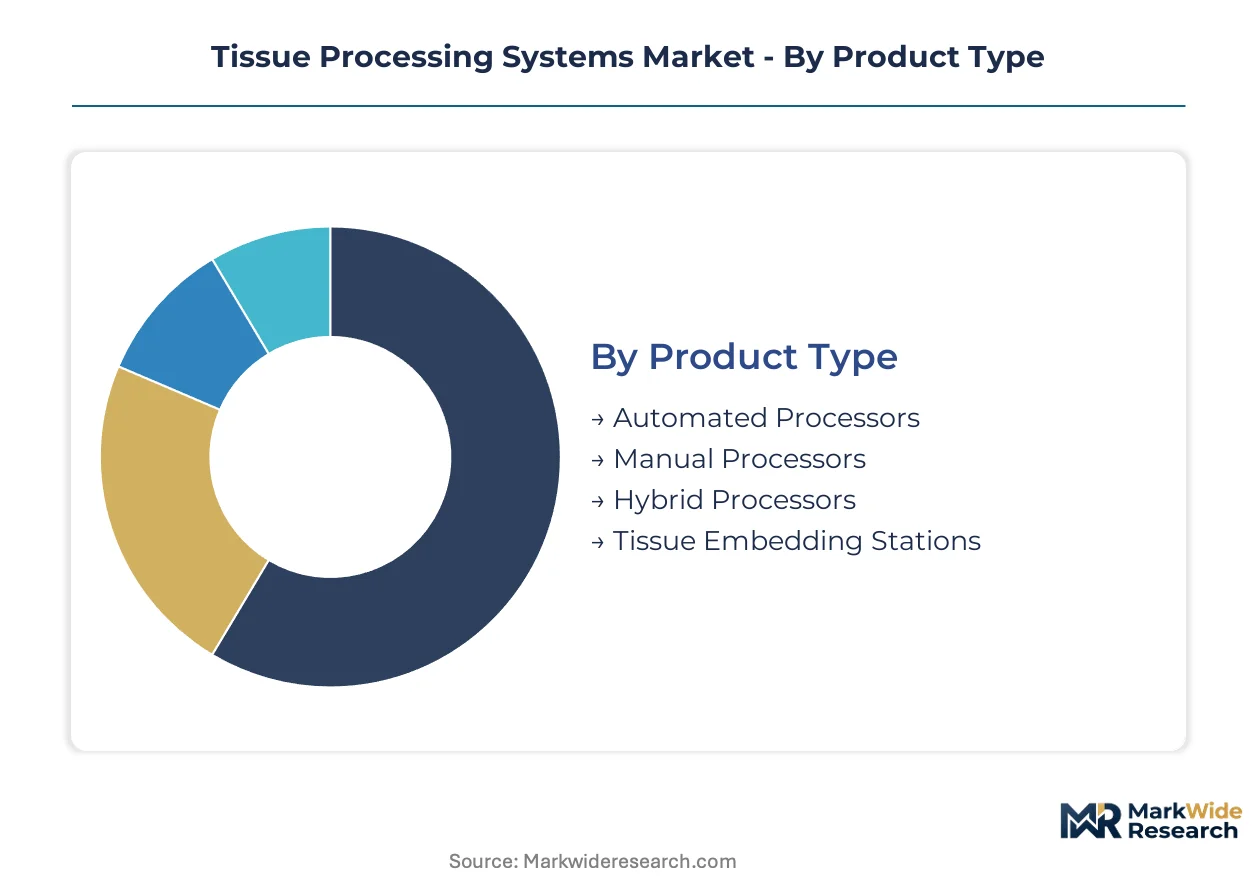
Tissue processing systems fragment across multiple dimensions that determine capital deployment patterns and vendor positioning strategies. Product architecture, end-user workflow intensity, and technology modality each create distinct specification requirements and margin profiles across the installed base.
Product Type:
Automated processors capture the premium tier through walkaway efficiency and audit trail capabilities, while manual systems retain volume presence in resource-constrained settings.
- Automated Processors:These systems execute dehydration, clearing, and paraffin infiltration cycles with minimal operator intervention. Academic medical centers in the United States drive procurement of these units as histopathology workloads intensify and CLIA documentation requirements tighten.
- Manual Processors:Benchtop units requiring technician oversight for reagent changes and timing control. Smaller hospital pathology departments in rural United States markets continue specifying these systems where capital budgets constrain automation adoption.
- Hybrid Processors:Configurations permitting automated batch processing with manual intervention options for specialized specimens.
- Tissue Embedding Stations:Dedicated instruments for paraffin block formation preceding microtomy sectioning.
Mature deployment sits with manual processors in legacy installations. Newer deployment is concentrated in automated processors as laboratories prioritize standardization and throughput.
End User:
Customer type determines specification intensity, with high-throughput reference laboratories demanding integrated reagent tracking and smaller facilities prioritizing capital efficiency.
- Hospitals:In-house pathology departments serving surgical and oncology services. These units in the United States specify processors with digital pathology platform compatibility as whole-slide imaging adoption accelerates.
- Diagnostic Laboratories:Commercial reference providers handling outsourced histopathology. Regional networks in the United States are expanding fastest, creating concentrated demand for vacuum impregnation systems with batch flexibility.
- Research Institutes:Academic and government laboratories conducting mechanistic studies.
- Forensic Laboratories:Medical examiner offices and criminalistics units processing post-mortem specimens.
Installed base concentration rests with hospitals. Steepest expansion trajectory belongs to diagnostic laboratories as outsourcing patterns deepen.
Technology:
Processing modality selection reflects the tension between section quality requirements and turnaround time pressures across clinical settings.
- Microtomy:Rotary and sliding microtomes for thin-section generation from paraffin blocks. Hospital pathology departments in the United States anchor demand for these systems as the foundational technology for diagnostic slide preparation.
- Vacuum Impregnation:Pressure-assisted paraffin infiltration accelerating processing cycles. High-throughput clinical laboratories specify these systems where rapid turnaround for cancer staging drives workflow design.
- Cryostats:Frozen section instruments for intraoperative consultation.
- Chemical Fixation:Formalin-based preservation protocols preceding paraffin processing.
Conventional deployment centers on chemical fixation. Accelerating deployment is visible in vacuum impregnation as commercial laboratories scale regional capacity.
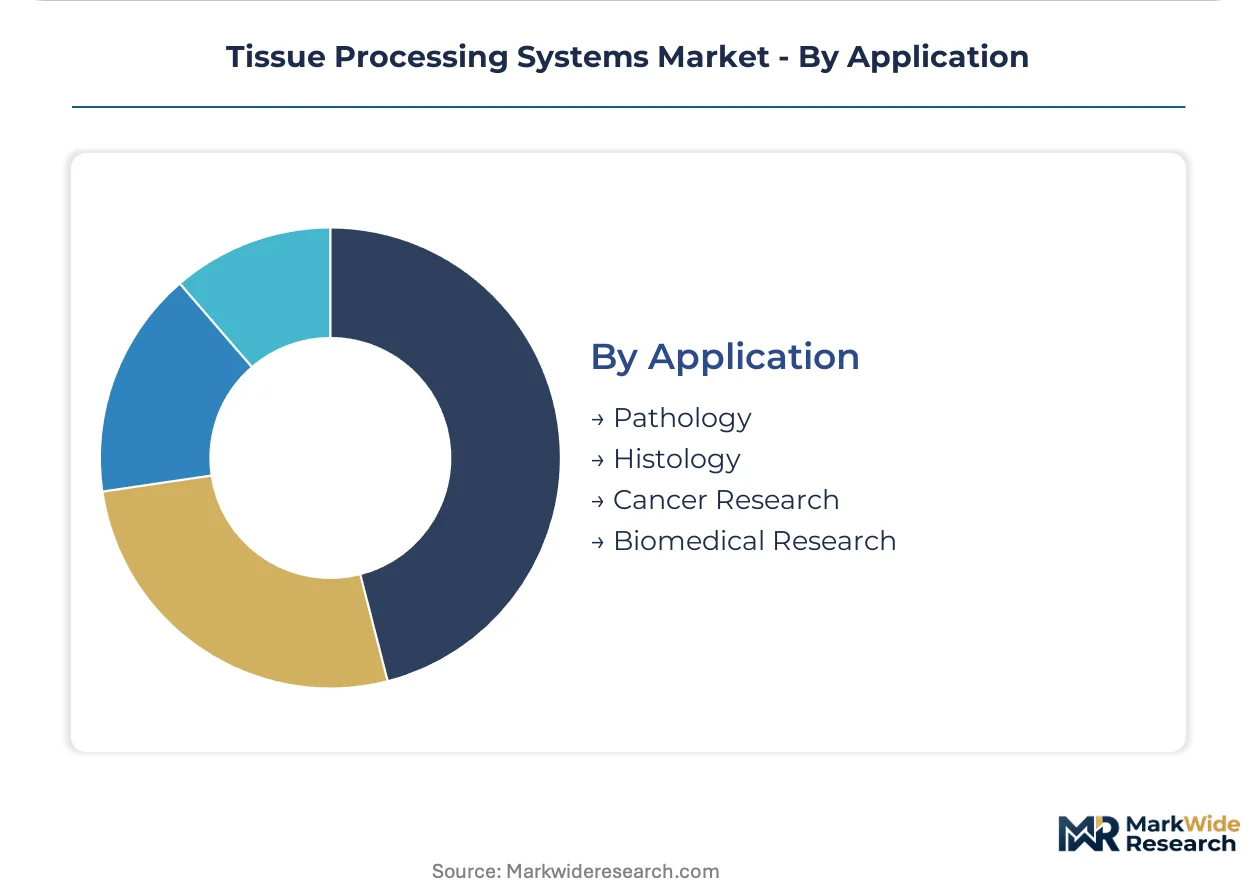
Application:
Use case specificity shapes instrument configuration, with diagnostic applications demanding regulatory-compliant documentation and research settings tolerating protocol flexibility.
- Pathology:Clinical diagnostic workflows for disease identification and cancer staging. Hospital-based anatomic pathology services in the United States represent the core demand channel, with FDA quality system regulation governing equipment validation protocols.
- Histology:General tissue preparation for morphological examination. Contract research organizations handling toxicology studies are expanding specifications for large-volume processing capabilities.
- Cancer Research:Tumor biology and therapeutic response studies.
- Biomedical Research:Fundamental mechanistic investigations across disease models.
Established deployment dominates pathology services. Emerging deployment concentrates in cancer research as translational programs expand specimen banking requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic laboratories in the United States control the dominant share of new tissue processing system placements, with academic medical centers and commercial reference networks driving procurement cycles. Capital deployment concentrates where histopathology outsourcing has consolidated into regional hub-and-spoke models.
United States
Federal research funding flows through the National Institutes of Health sustain instrument replacement cycles at university-affiliated medical centers. The FDA's quality system regulation governs premarket notification pathways for automated processors, extending validation timelines for equipment modifications. The Boston-Cambridge corridor anchors demand for high-throughput systems serving consolidated pathology service networks.
Germany
REACH chemical registration requirements are accelerating the phase-out of xylene-based clearing agents in histopathology workflows. The German Institute for Medical Documentation and Information enforces quality standards for diagnostic laboratory accreditation. The Rhine-Ruhr metropolitan region concentrates processor installations at university hospital networks transitioning to digital pathology platforms.
China
Hospital pathology departments in tier-one cities are expanding automated processing capacity to handle rising cancer screening volumes. The National Medical Products Administration classifies tissue processors as Class II medical devices, requiring domestic registration for imported equipment. The Yangtze River Delta clusters manufacturing and clinical demand, with Shanghai-based medical centers piloting microwave-assisted processing protocols.
Japan
Aging demographics are intensifying histopathology workloads at regional cancer centers, driving specifications for walkaway automation. The Pharmaceuticals and Medical Devices Agency enforces Good Manufacturing Practice standards for tissue processing equipment validation. The Kansai region around Osaka maintains dense concentrations of university hospitals with embedded Leica Biosystems and Sakura Finetek installations.
United Kingdom
NHS pathology consolidation programs are centralizing specimen processing into regional laboratory hubs, favoring vacuum impregnation systems with batch flexibility. The Medicines and Healthcare products Regulatory Agency aligns device registration with EU MDR transitional provisions post-Brexit. London and the Southeast concentrate procurement authority within consolidated NHS trusts managing multi-site histopathology networks.
Tissue Processing Systems Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated life sciences conglomerates commanding premium placements in academic medical centers while regional fabricators serve price-sensitive hospital laboratories. The vendor base organizes into three tiers: multinational diagnostics platforms with embedded software ecosystems, mid-scale equipment specialists with workflow-integrated offerings, and regional assemblers competing on capital efficiency. Consolidation pressure is intensifying as procurement authority centralizes into health system supply chains and diagnostic laboratory networks.
Within the multinational diagnostics tier, Thermo Fisher Scientific and Leica Biosystems occupy positions shaped by distribution depth and digital pathology integration capabilities. Sakura Finetek anchors the vacuum impregnation specialization vector. Milestone Medical, Histo-Line Laboratories, and SLEE medical represent the European mid-scale fabrication cluster. Roche Diagnostics and Agilent Technologies sit within the broader life sciences instrumentation conglomerate archetype. Epredia carries the legacy histopathology equipment lineage following corporate restructuring from prior ownership structures.
| Leading Market Players |
|---|
| Milestone Medical |
| Histo-Line Laboratories |
| Thermo Fisher Scientific |
| Roche Diagnostics |
| Agilent Technologies |
| Leica Biosystems |
| Epredia |
| SLEE medical |
| Sakura Finetek |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up diagnostic laboratory networks in the United States anchor procurement authority, compressing capital equipment pricing through centralized supply chains while extending service contract margins for compliant original equipment manufacturers. This ownership concentration reshapes both vendor pricing discipline and distribution channel economics across the tissue processing value chain.
Pricing Analysis
High-throughput vacuum impregnation systems capture premium margins through FDA-validated audit trail capabilities, while manual processors compete on capital efficiency in resource-constrained settings. Price differentiation centers on ISO 15189 compliance tier and digital pathology platform integration depth. Cost compression in standard automated tiers is intensifying as consolidated purchasing organizations unbundle service agreements from equipment procurement. Academic medical centers exhibit lowest price sensitivity due to NIH funding insulation, whereas rural hospital pathology departments prioritize capital efficiency over feature depth.
Supply Chain Analysis
Paraffin wax feedstock supply rests on petroleum-derived producers in the United States, Germany, and China, with bio-based alternatives emerging from European specialty chemical manufacturers. Precision temperature control components, vacuum chamber assemblies, and automated reagent tracking modules constitute critical hardware dependencies. Single-source vulnerability concentrates in embedded workflow software licenses from established diagnostics platforms. Distribution runs through life sciences conglomerate direct sales forces in academic medical centers and third-party laboratory supply distributors in commercial reference networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tissue processing systems market functions as a cost-of-compliance arena where FDA quality system regulation and ISO 15189 accreditation standards erect formidable barrier-to-entry moats. Equipment manufacturers bearing validated documentation capabilities command sustainable placement advantages against undifferentiated competitors.
For Market Incumbents: Anticipate cryostat substitution advances in intraoperative settings by accelerating microwave-assisted processing protocol validation for rapid turnaround applications. Defend installed base stickiness through backward integration into consumables supply, particularly bio-based paraffin formulations achieving cost parity. Channel control via embedded digital pathology software lock-in represents the priority defensive lever against disintermediation from third-party maintenance providers. For New Entrants and Emerging Players: Modular microwave-assisted tissue processing architectures offer a technology-first wedge into mid-sized hospital laboratories bridging manual workflows and high-throughput vacuum systems. Contract research organizations handling toxicology and preclinical studies present the most penetrable white-space channel, requiring specialized large-volume processing protocols absent from incumbent portfolios. A software-companion go-to-market angle emphasizing remote monitoring and automated reagent traceability bypasses entrenched equipment replacement cycles. For Investors and Strategic Acquirers: Consolidated purchasing organization contract awards in United States health system networks are the leading indicator that procurement authority concentration is accelerating vendor consolidation timelines. The five-to-ten year viability window favors acquisition targets with FDA premarket notification clearances and validated digital pathology interoperability. Watch for REACH chemical registration enforcement in Europe as the signal triggering accelerated xylene-free reagent protocol substitution and associated processor replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Notification Pathway | Validates automated audit trail capabilities for CLIA-mandated laboratory compliance documentation. |
| ISO 15189 Accreditation Alignment | Opens procurement access to European hospital networks enforcing medical laboratory quality standards. |
| Digital Pathology Platform Integration | Secures software lock-in preventing customer migration to competing processing workflows. |
| Bio-Based Paraffin Supply Agreement | Preempts REACH-driven operational disruption in European histopathology service markets. |
| Contract Research Organization Partnership | Captures underpenetrated toxicology and preclinical research histology services channel. |
Study Parameters
Independent corroboration across pathology department heads, diagnostic laboratory operations directors, and biomedical equipment procurement managers underwrites the qualitative findings in this study. Secondary validation draws from FDA 510(k) premarket notification databases, ISO 15189 accreditation registries, and hospital capital expenditure disclosures. Bottom-up instrument placement tracking triangulates against top-down market sizing derived from life sciences conglomerate segment reporting.
Rate-of-change decomposition across product architecture, end-user workflow intensity, and technology modality segments informs the analytical framework over the projection horizon. CAGRs were derived from modeled replacement cycles, outsourcing penetration trajectories, and regulatory compliance mandate timelines. Forecast inputs incorporate CLIA laboratory accreditation expansion patterns and digital pathology platform adoption curves specific to anatomic pathology services.
Several conditions sit outside the modeled scope, including geopolitical trade restriction impacts on precision component sourcing and unforeseen cryotechnology advances displacing chemical fixation protocols. Forecasts reflect assumptions regarding sustained NIH funding flows and stable petroleum-derived paraffin feedstock availability. A small set of named triggers warrants ongoing watch: REACH enforcement acceleration in Europe, consolidated purchasing organization contract award patterns in United States health systems, and histotechnologist workforce vacancy rate trajectories reported by the American Society for Clinical Pathology.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Vacuum System Market
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
Sanitary Napkin Equipment Market
Medical Equipment
Global Steam Autoclaves Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
Medical Cart Battery Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Global Platelet Incubator Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
Global Mortuary Equipment Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
US Biomedical Refrigerators and Freezers Market