
 Global Semiconductor Lasers Market | 2026-2036
Global Semiconductor Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Lasers Market Intelligence
A shift from single-source to multi-source optical component procurement is recalibrating supply chain risk models across telecom infrastructure programs. Coherent Corp. leverages vertical integration across gallium arsenide wafer fabrication and packaged module assembly. IPG Photonics Corporation anchors high-power fiber laser production for industrial cutting and welding equipment. Nichia Corporation specializes in blue-violet diode architectures that dominate optical data storage and lithography illumination.
Semiconductor lasers are solid-state devices that generate coherent light through stimulated emission in p-n junction structures, typically operating at wavelengths from ultraviolet to infrared with output powers ranging from milliwatts to multi-kilowatt in fiber-coupled configurations. These devices serve as precision energy sources for material processing, optical communications, medical therapeutics, and sensing applications. Diode lasers capture the largest volume share in consumer electronics and automotive lidar modules, while quantum cascade lasers are gaining fastest in gas sensing and spectroscopy instrumentation. Vertical cavity surface emitting lasers command premium positioning in datacenter transceivers due to parallel array scalability and lower threshold currents than edge-emitting alternatives.
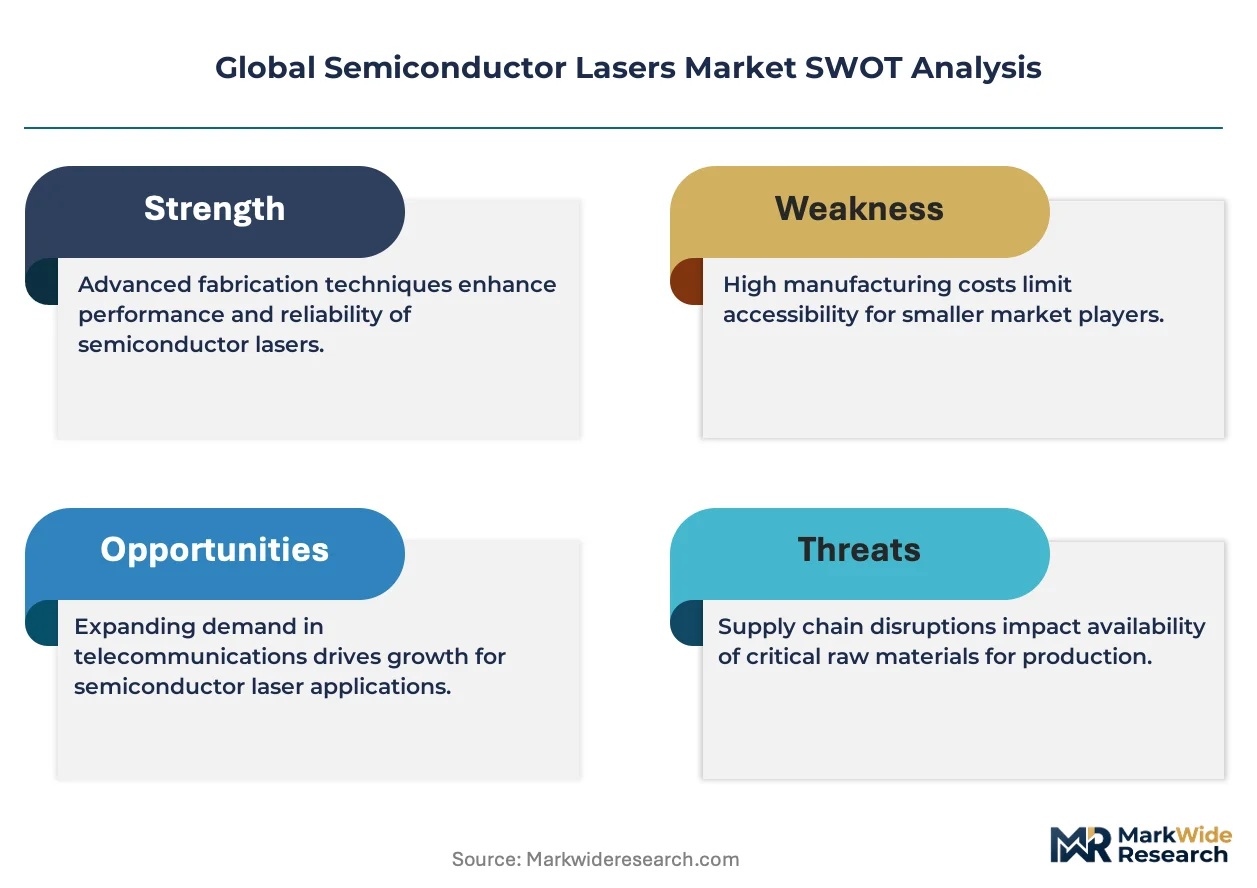
FDA device classification rules govern laser surgical equipment marketed in the United States, while the EU MDR and CE marking requirements impose clinical performance documentation burdens on medical laser manufacturers seeking European market access. China's SAMR enforces GB standards on laser product safety classifications that affect import eligibility for industrial systems. Japan's METI administers JIS standards that shape domestic procurement specifications for precision manufacturing equipment. Stakeholders must track divergence between regional safety classification thresholds and emerging restrictions on gallium and indium raw material sourcing.
Market Dynamics
Datacenter interconnect builds by hyperscale cloud operators are expanding fiber laser deployments, tightening supply chains around gallium arsenide wafer fabrication and packaged module assembly capacity.
Growth Catalysts
- Dual Carbon Policy Framework:China's MIIT energy efficiency mandates under dual carbon goals are accelerating replacement cycles for legacy industrial laser systems. GB standards on product certification create compliance-driven refresh demand.
- Optical Communications Infrastructure:Vertical cavity surface emitting laser arrays are scaling into 800G datacenter transceivers. Parallel emitters reduce power consumption per bit versus edge-emitting alternatives.
- Precision Manufacturing Clusters:East Asian manufacturing concentration spanning Japan, South Korea, and Taiwan generates dense supplier ecosystems. Proximity between diode fabricators and module integrators compresses logistics lead times.
Market Restraints
- Raw Material Concentration:Gallium and indium refining capacity concentrates in Chinese state-controlled enterprises. Export permit volatility creates input cost uncertainty for non-Chinese laser manufacturers.
- Technical Thermal Limitations:High-power fiber lasers face brightness degradation from thermal lensing in kilowatt-class continuous wave operation. Active cooling architectures add system complexity and failure modes.
- Regulatory Divergence:FDA device classification rules for surgical equipment diverge from EU MDR clinical documentation requirements. Dual-track compliance burdens extend product launch timelines.
Strategic Opportunities
- Quantum Sensing Applications:Quantum cascade lasers for gas spectroscopy remain underpenetrated in emissions monitoring. Methane detection mandates in EU F-Gas Regulation create regulatory tailwind.
- Automotive Lidar Integration:Solid-state scanning architectures are displacing mechanical beam steering. 1550nm fiber amplifiers enable eye-safe operation at extended range for highway autonomy.
- Medical Therapeutics Expansion:Blue-violet diode architectures for photodynamic therapy face limited installed base in oncology. PMDA accelerated approval pathways in Japan reduce clinical trial duration for new indications.
Industry Challenges
- Compound Semiconductor Talent Scarcity:MOCVD reactor operation and III-V epitaxy design expertise concentrates in legacy telecom optoelectronics hubs. Foundry engineering pipelines fail to match capacity expansion timelines.
- Multi-Source Qualification Burden:Telecom infrastructure programs now mandate second-source optical component approval. Dual qualification cycles extend procurement lead times without volume guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Lasers Market |
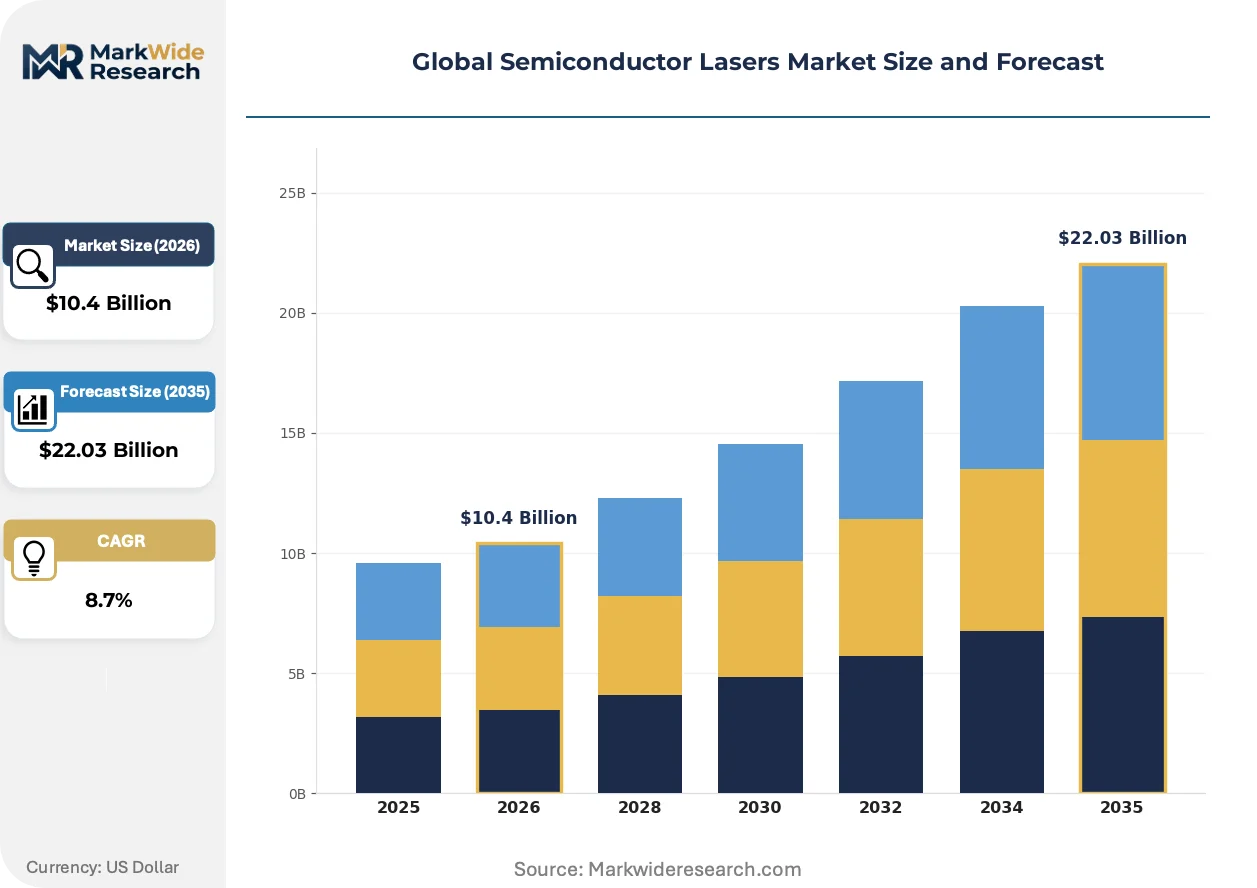
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $22.03 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Wave Lasers, Pulsed Lasers, Quantum Cascade Lasers, Diode Lasers Application: Telecommunication, Industrial Processing, Medical Devices, Consumer Electronics Technology: Edge Emitting Lasers, Vertical Cavity Surface Emitting Lasers, Fiber Lasers, Hybrid Lasers End User: Aerospace, Automotive, Healthcare, Retail |
| Companies Covered | Coherent Corp., IPG Photonics Corporation, Lumentum Holdings Inc., TRUMPF, Nichia Corporation, Hamamatsu Photonics K.K., Jenoptik AG, ROHM Semiconductor, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Lasers Market Strategic Shifts & Innovations
Silicon photonics packaging techniques are migrating into compound semiconductor laser fabrication, compressing form factors and enabling co-packaged optics architectures for next-generation switching silicon.
Hybrid silicon III-V integration is integrating indium phosphide gain sections with silicon nitride passive circuits. Cloud switch vendors at 51.2T aggregate bandwidth are adopting co-packaged optics to reduce electrical trace losses. This convergence is integrating photonics and electronics at the package level, displacing traditional pluggable transceiver form factors.
EU F-Gas Regulation phase-down schedules are tightening availability of sulfur hexafluoride for high-voltage switchgear, indirectly pressuring industrial laser gas delivery system designs. Manufacturers are redesigning excimer laser gas handling to reduce fluorinated greenhouse gas inventories. Medical excimer laser systems for ophthalmology face extended recertification timelines under MDR clinical performance documentation rules.
Buyer consolidation among hyperscale cloud operators is compressing supplier negotiation cycles and unbundling after-sales service contracts from hardware procurement. Direct sourcing teams at major datacenter operators now manage optical component qualification in-house, displacing traditional distributor technical support roles. This pattern is most visible in North American and East Asian cloud buildouts where procurement functions centralize at headquarters level.
Global Semiconductor Lasers Market Segmentation
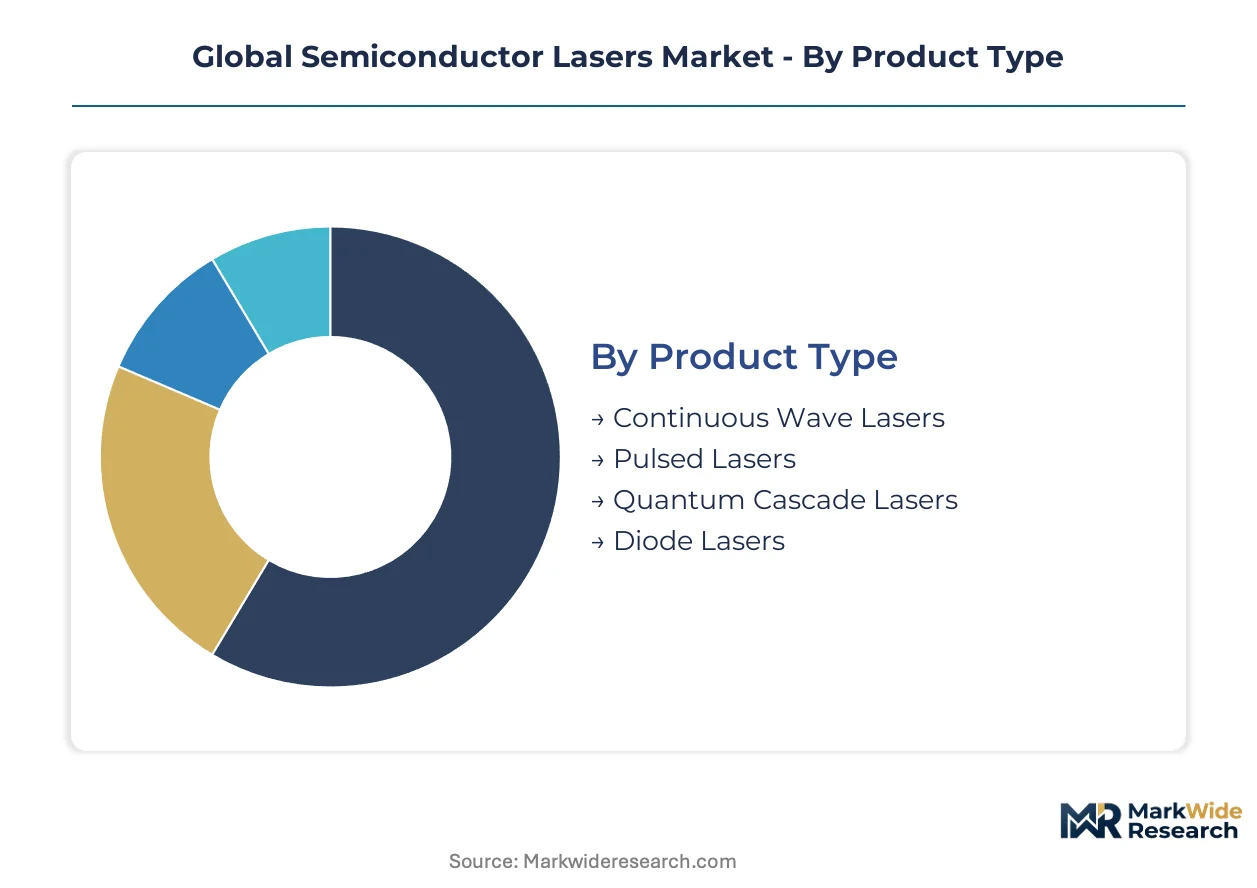
Semiconductor laser buyers segment procurement by operational requirements, wavelength precision, and integration complexity. Product specifications diverge sharply between datacenter transceiver arrays and industrial cutting systems, reshaping supplier qualification protocols.
Product Type:
Buyers differentiate primarily by output stability needs and thermal management architecture.
- Continuous Wave Lasers:These devices deliver stable, uninterrupted optical output essential for precision material processing and scientific instrumentation. Demand concentrates in German automotive manufacturing clusters where welding seam quality standards under KBA certification protocols mandate consistent energy delivery.
- Diode Lasers:Compact p-n junction devices operating across ultraviolet to infrared wavelengths dominate consumer electronics and automotive lidar modules. East Asian manufacturing clusters in Japan, South Korea, and Taiwan absorb the highest volumes for smartphone proximity sensors and vehicle safety systems.
- Pulsed Lasers:Nanosecond to femtosecond pulse architectures enable cold ablation in medical dermatology and micromachining.
- Quantum Cascade Lasers:Intersubband transition devices emit in mid-infrared for gas spectroscopy and environmental monitoring.
Diode lasers lead volumes today; quantum cascade lasers are gaining share fastest.
Application:
End-use concentration determines pricing power and qualification cycle length.
- Telecommunication:Datacenter interconnect builds at 800G aggregate bandwidth consume vertical cavity surface emitting laser arrays. Hyperscale operators in Ashburn, Virginia and Singapore compress supplier margins through direct procurement consolidation.
- Industrial Processing:High-power fiber laser systems execute cutting, welding, and additive manufacturing operations. Japanese precision equipment manufacturers under METI JIS standards specify beam quality metrics that exclude lower-tier suppliers.
- Medical Devices:Surgical and therapeutic equipment faces FDA device classification and EU MDR dual-track compliance burdens.
- Consumer Electronics:Smartphone facial recognition and proximity sensing drive high-volume, low-margin diode procurement.
Industrial processing commands the highest unit values; telecommunication is expanding most quickly.
Technology:
Integration density and packaging cost separate buyer tiers.
- Vertical Cavity Surface Emitting Lasers:Perpendicular emission geometry enables wafer-scale testing and parallel array packaging. Cloud switch vendors at 51.2T bandwidth adopt co-packaged optics to reduce electrical trace losses.
- Fiber Lasers:Doped silica gain media deliver kilowatt-class output for heavy industrial cutting. China's MIIT energy efficiency mandates under dual carbon goals accelerate replacement of legacy CO2 systems in domestic manufacturing.
- Edge Emitting Lasers:Traditional longitudinal cavity designs persist in long-haul telecommunications for superior beam quality.
- Hybrid Lasers:Silicon photonics integration with III-V gain sections compresses form factors for next-generation switching silicon.
Edge emitting lasers retain installed base dominance; vertical cavity surface emitting lasers show steepest expansion trajectory.
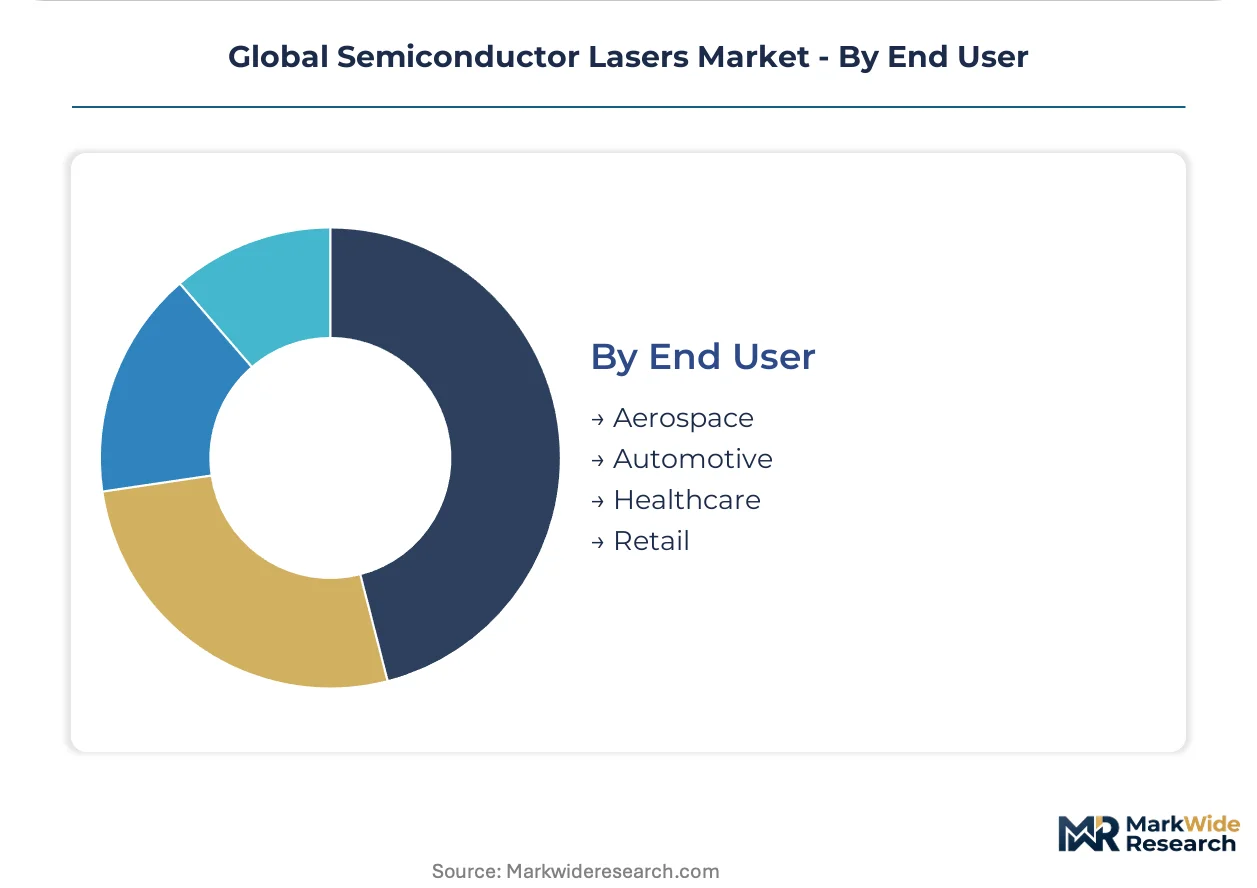
End User:
Procurement sophistication and regulatory exposure define customer segmentation.
- Automotive:Solid-state lidar integration at 1550nm wavelengths enables eye-safe highway autonomy. German KBA type approval and US NHTSA safety standards impose divergent testing protocols.
- Healthcare:Laser surgical equipment requires FDA 510(k) clearance or EU MDR clinical performance documentation. Japan's PMDA accelerated approval pathways reduce trial duration for photodynamic therapy indications.
- Aerospace:Satellite optical communications and sensing applications demand radiation-hardened packaging.
- Retail:Barcode scanning and point-of-sale authentication drive commoditized diode consumption.
Healthcare generates premium pricing; automotive is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters spanning Japan, South Korea, and Taiwan concentrate the highest semiconductor laser fabrication density worldwide. These three markets absorb disproportionate volumes for datacenter transceivers, automotive lidar modules, and precision industrial equipment. Regulatory divergence across the US, Europe, and China is fragmenting compliance pathways for multinational suppliers.
United States
Hyperscale cloud operators in Ashburn, Virginia and the Pacific Northwest are driving 800G datacenter transceiver deployment. FDA device classification rules govern surgical laser equipment marketed domestically. The Southeast manufacturing corridor is attracting fiber laser assembly operations seeking proximity to automotive OEMs.
China
MIIT dual carbon goals and GB standards on energy efficiency are accelerating replacement cycles for legacy industrial laser systems. SAMR enforces laser product safety classifications that affect import eligibility. Yangtze River Delta fabrication hubs concentrate gallium arsenide wafer capacity under state-controlled enterprise structures.
Germany
Automotive manufacturing clusters under KBA certification protocols demand consistent welding seam quality from continuous wave laser systems. REACH and RoHS compliance burdens shape material sourcing for EU-bound equipment. Bavarian precision equipment manufacturers specify beam quality metrics that exclude lower-tier suppliers.
Japan
METI administers JIS standards that shape domestic procurement specifications for precision manufacturing equipment. PMDA accelerated approval pathways reduce clinical trial duration for photodynamic therapy indications. Kanto and Kansai industrial corridors maintain dense supplier ecosystems between diode fabricators and module integrators.
South Korea
MFDS regulates medical laser device registration while memory semiconductor manufacturers drive demand for lithography illumination systems. Seoul Capital Area fabs specialize in vertical cavity surface emitting laser arrays for consumer electronics proximity sensing. Busan-Ulsan heavy industry clusters import high-power fiber lasers for shipbuilding automation.
Global Semiconductor Lasers Market Key Industry Players
Global majors compete with regional champions across wavelength specialization and vertical integration depth. The vendor base clusters around three tiers: diversified photonics conglomerates with captive wafer fabrication, pure-play fiber laser specialists, and niche diode architects serving single end-use verticals. Strategic archetypes include backward-integrated compound semiconductor foundries, application-specific module assemblers, and IP-heavy design houses licensing epitaxy recipes. Dominant competitive moves encompass multi-source qualification partnerships with hyperscale datacenter operators and in-house production of gallium arsenide substrates to bypass raw material export constraints.
Among the diversified photonics conglomerates, Coherent Corp. exemplifies the backward-integrated archetype through its spanning of gallium arsenide wafer fabrication and packaged module assembly. IPG Photonics Corporation anchors the high-power industrial segment as a pure-play fiber laser specialist. Nichia Corporation occupies a position within the niche diode tier, its name signaling specialization in blue-violet architectures for optical data storage and lithography illumination. These three entities represent distinct competitive vectors: captive supply chain control, application-specific power scaling, and wavelength-specific IP accumulation.
| Leading Market Players |
|---|
| Coherent Corp. |
| IPG Photonics Corporation |
| Lumentum Holdings Inc. |
| TRUMPF |
| Nichia Corporation |
| Hamamatsu Photonics K.K. |
| Jenoptik AG |
| ROHM Semiconductor |
| Mitsubishi Electric Corporation |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between FDA-cleared surgical systems and uncertified industrial modules generates parallel pricing ladders that track supply chain complexity. Premium-tier medical equipment commands substantial markups reflecting dual-track compliance investments, while commodity diode arrays for consumer electronics compete on wafer-scale manufacturing efficiency in East Asian foundries.
Pricing Analysis
Input-cost pass-through from gallium arsenide wafer fabrication dominates pricing dynamics across all tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared medical systems from industrial fiber lasers and commodity diode arrays. Cost compression in consumer electronics diodes intensifies as smartphone proximity sensor volumes plateau. Datacenter operators exhibit lowest price sensitivity due to transceiver qualification lock-in, while automotive lidar procurement teams negotiate aggressively on volume commitments.
Supply Chain Analysis
Single-source vulnerability sits with Chinese state-controlled enterprises controlling gallium and indium refining capacity. Manufacturing gravity centers on Taiwan, South Korea, and Japan for compound semiconductor fabrication. MOCVD reactor components and III-V epitaxy wafers draw from concentrated supplier bases. Export permit volatility from Beijing creates persistent supply chain risk. Distribution runs through direct procurement teams at hyperscale cloud operators, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as datacenter bandwidth expansion sustains replacement cycles across telecom infrastructure. Optical interconnect demand from cloud operators provides predictable revenue visibility.
For Market Incumbents: Anticipate margin compression from multi-source qualification mandates by hyperscale buyers. Defend positioning through backward integration into gallium arsenide substrate production, bypassing Chinese export constraints. Invest in FDA 510(k) pathway expertise to capture medical premium tiers as EU MDR documentation burdens extend competitor timelines. For New Entrants and Emerging Players: Direct-to-cloud procurement channels offer entry routes around entrenched distributor relationships. Target quantum cascade laser architectures for methane detection under EU F-Gas Regulation mandates. Pursue PMDA accelerated approval pathways in Japan for photodynamic therapy indications where installed base remains limited. For Investors and Strategic Acquirers: Consolidation pressure builds where MOCVD reactor operation expertise concentrates in legacy telecom optoelectronics hubs. Five-to-ten-year viability favors compound semiconductor foundries with captive epitaxy capabilities. Watch hyperscale capex disclosure patterns as inflection indicators for 800G transceiver demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | In-house gallium arsenide wafer fabrication insulates against Chinese export permit volatility. |
| Dual Certification Investment | Simultaneous FDA 510(k) and EU MDR pathways accelerate premium medical market access. |
| Co-Packaged Optics Partnership | Integration with cloud switch vendors at 51.2T bandwidth captures next-generation transceiver demand. |
| Quantum Sensing Application Development | Methane detection mandates under EU F-Gas Regulation create regulatory tailwind for mid-infrared lasers. |
| Geographic Manufacturing Footprint Expansion | Southeast US assembly operations reduce logistics lead times to automotive OEM clusters. |
Research Approach
Multiple input streams — primary interviews with MOCVD reactor operators, datacenter procurement directors, and medical device regulatory specialists; secondary validation through SEC filings, hyperscaler capex disclosures, and FDA 510(k) databases; customs records on gallium arsenide wafer trade flows — were reconciled through bottom-up and top-down triangulation.
Historical shipment data cross-referenced against expert panel inputs established baseline demand curves across the projection horizon. Segmentation dimensions modeled include product architecture, wavelength precision tier, end-use regulatory cluster, and geographic manufacturing hub. CAGRs were derived from installed base replacement cycles and technology substitution elasticities. Forecast inputs incorporated MIIT dual carbon policy implementation timelines and EU F-Gas Regulation phase-down schedules.
The model assumes a particular technology adoption path; alternative pathways for silicon photonics integration would alter the outlook. Forecasts reflect assumptions on hyperscale cloud buildout continuity and raw material export policy stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Optical Imaging Market
Optics
Optical Fiber Raw Material Market
Optics
Anti Glare Film Market
Optics
Electro Optics Market
Optics
Advanced Optics Market
Optics
Asia-Pacific Anti-Blue Ray Myopia Lenses Market
Optics
Fiber Optic Development Tools Market
Optics
Acrylic Lenses Market
Optics
Glass Scintillator Market
Optics
Fiber Optic Amplifier Market
Optics
Optical Fiber Market
Optics
Fiber-Optic Couplers Market
Optics
Fiber Optic Receiver Market
Optics
Collimating Lens Market
Optics
Fiber Optic Cable Market
Optics
Sports Optics Market