
 Advanced Optics Market | 2026-2036
Advanced Optics Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Optics Market Analysis
Software-defined adaptive optics is broadening what suppliers monetize beyond hardware alone. Coherent Corp. leverages its vertically integrated crystal growth and fabrication capabilities to control specialty laser supply chains. Samsung Electronics anchors consumer imaging demand through dense CMOS sensor integration across mobile and automotive platforms. Texas Instruments specializes in digital light processing chipsets that underpin structured-light and lithography systems.
Advanced optics encompasses precision-engineered components and systems that manipulate electromagnetic radiation across ultraviolet through infrared wavelengths, typically requiring surface figure tolerances below one-tenth of a wavelength and sub-nanometer coating uniformity achieved through ion-beam sputtering or atomic layer deposition. These specifications serve critical functions in laser-based manufacturing, biomedical diagnostics, and high-bandwidth communications infrastructure. Photonics and optical coatings technologies currently capture the deepest margin pools due to proprietary thin-film stacks and fiber-coupled architectures, while quantum dots remain an emerging dimension with concentrated R&D investment. Medical imaging and defense applications lead volume absorption, though telecommunications infrastructure refresh cycles are accelerating fastest as coherent pluggable optics displace discrete transponder designs.
FDA device classification rules govern optical diagnostic equipment market entry in the United States, while the EU AI Act and MDR impose escalating conformity requirements on imaging systems with embedded decision-support algorithms. ECHA REACH restrictions on heavy-metal coatings and persistent organic compounds directly reformulate supplier material strategies across the value chain. Stakeholders must weigh regulatory compliance timelines against technology migration paths when allocating capital between evolutionary coating improvements and disruptive quantum photonics platforms.
Market Dynamics
Defense procurement cycles and coherent pluggable optics deployment are the dominant forces compressing supplier lead times and reshaping capacity allocation across precision manufacturing clusters.
Growth Catalysts
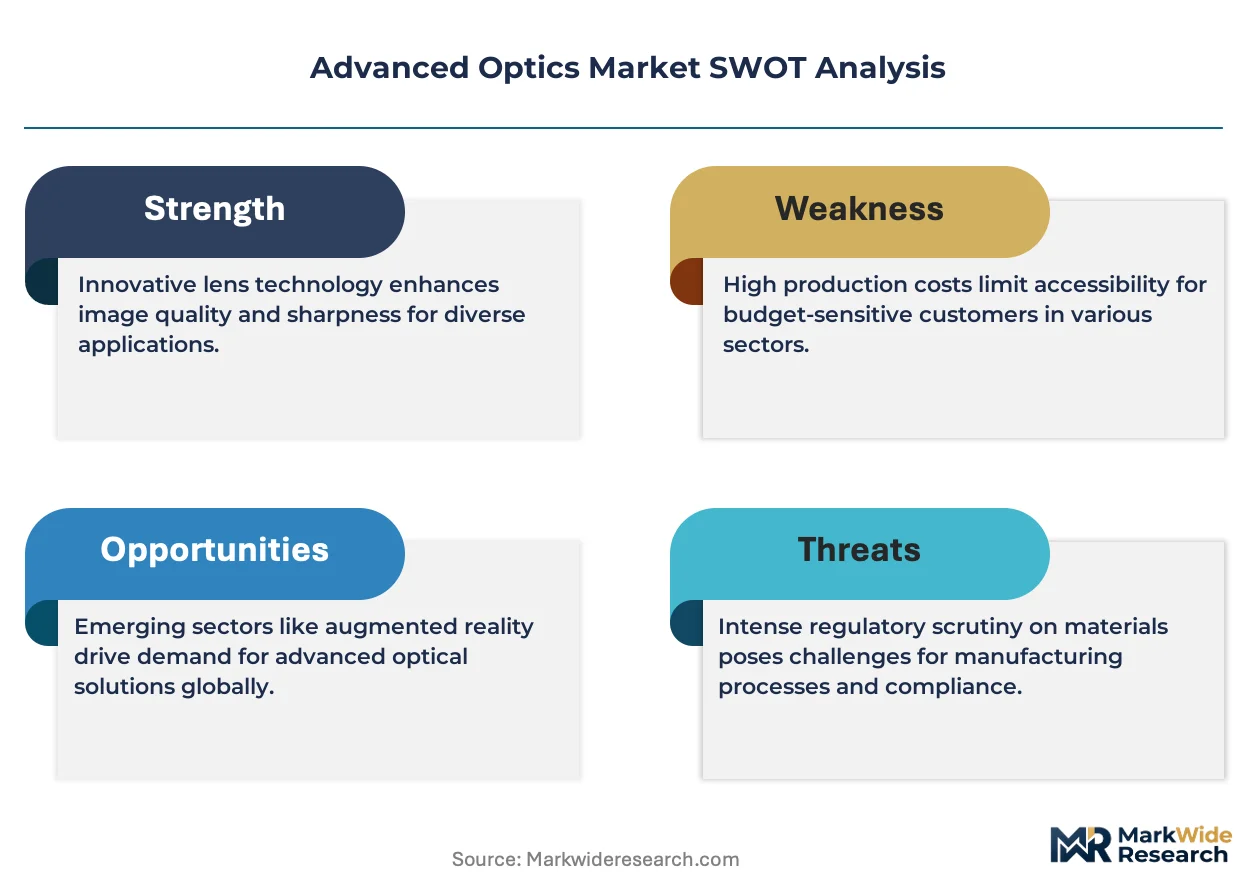
- EU AI Act and MDR:Imaging systems with embedded algorithms face escalating conformity requirements, pulling demand toward certified optical subsystems that meet clinical-grade reliability standards.
- Coherent pluggable optics:Telecommunications infrastructure refresh cycles are accelerating as pluggable designs displace discrete transponder architectures, concentrating procurement among hyperscale data center operators.
- Germany's precision corridor:Manufacturing gravity around Jena and Oberkochen anchors supply chain resilience for ion-beam sputtered coatings and specialty crystal growth.
Market Restraints
- ECHA REACH restrictions:Heavy-metal coating reformulations and persistent organic compound phase-outs are forcing material strategy resets across thin-film stack suppliers.
- Specialty laser crystal supply:Vertically integrated producers control captive feedstock for nonlinear optical crystals, creating bottleneck risk for independent component fabricators.
- Sub-nanometer uniformity thresholds:Atomic layer deposition equipment scarcity limits coating capacity expansion for ultraviolet-grade optics.
Strategic Opportunities
- Quantum photonics R&D:Quantum dot integration and entangled photon sources represent underdeveloped revenue streams with concentrated government funding in national photonics programs.
- Automotive LiDAR qualification:Structured-light and solid-state scanning modules are penetrating advanced driver-assistance systems, opening volume contracts outside traditional defense and medical verticals.
- Software-defined adaptive optics:Algorithm-controlled wavefront correction is shifting supplier monetization from hardware-only sales toward recurring service and calibration revenue.
Industry Challenges
- Ion-beam sputtering technician scarcity:Coating chamber operation and thin-film metrology expertise pools are shallow relative to capacity expansion targets.
- FDA 510(k) pathway compression:Optical diagnostic equipment submissions face reviewer backlog, extending time-to-revenue for biomedical imaging innovators.
- Legacy lithography integration:Deep-ultraviolet stepper retrofits require custom optical path re-engineering that fragments engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Optics Market |
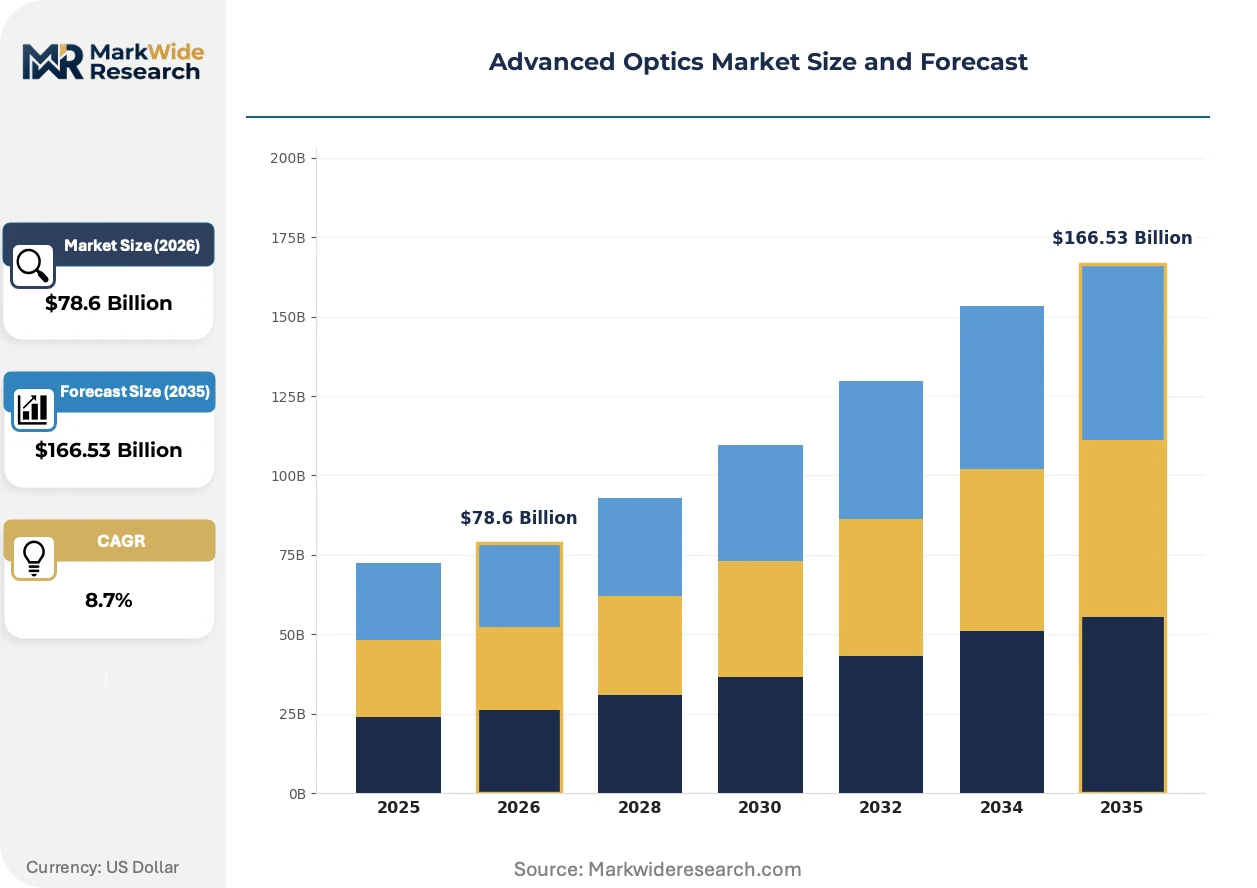
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $166.53 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lasers, Lenses, Mirrors, Sensors Technology: Photonics, Nanotechnology, Quantum Dots, Optical Coatings Application: Aerospace, Defense, Telecommunications, Medical Imaging End User: Manufacturing, Research Institutes, Healthcare, Consumer Electronics |
| Companies Covered | OmniVision Technologies Inc., Samsung Electronics Co., Ltd., Broadcom Inc., IPG Photonics Corp., Texas Instruments Incorporated, Coherent Corp., Intel Corporation, Fabrinet, Lumentum Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Optics Market Emerging Trajectories
Computational control layers and regulatory material constraints are simultaneously elevating software content and reformulating physical substrate specifications across the value chain.
Metasurface optics is rewriting the trade-off between optical performance and form factor. Automotive LiDAR and augmented-reality headset developers are adopting flat, subwavelength-structured lenses at prototype scale. The technology is compressing traditional refractive element counts by an order of magnitude in miniature imaging systems.
REACH and RoHS compliance timelines are hardening material specifications for optical coatings. Suppliers must document substance declarations through full supply chain tiers to maintain CE marking eligibility. German and French coating houses are accelerating fluoropolymer and chalcogenide glass substitution programs to meet 2027 restriction deadlines.
Hyperscale buyers are consolidating vendor panels for coherent transceiver modules. Direct procurement relationships with optical engine suppliers are displacing traditional distributor channels in North American and European data center builds. This concentration is most visible among cloud infrastructure operators specifying 800G and 1.6T pluggable form factors.
Advanced Optics Market Segmentation
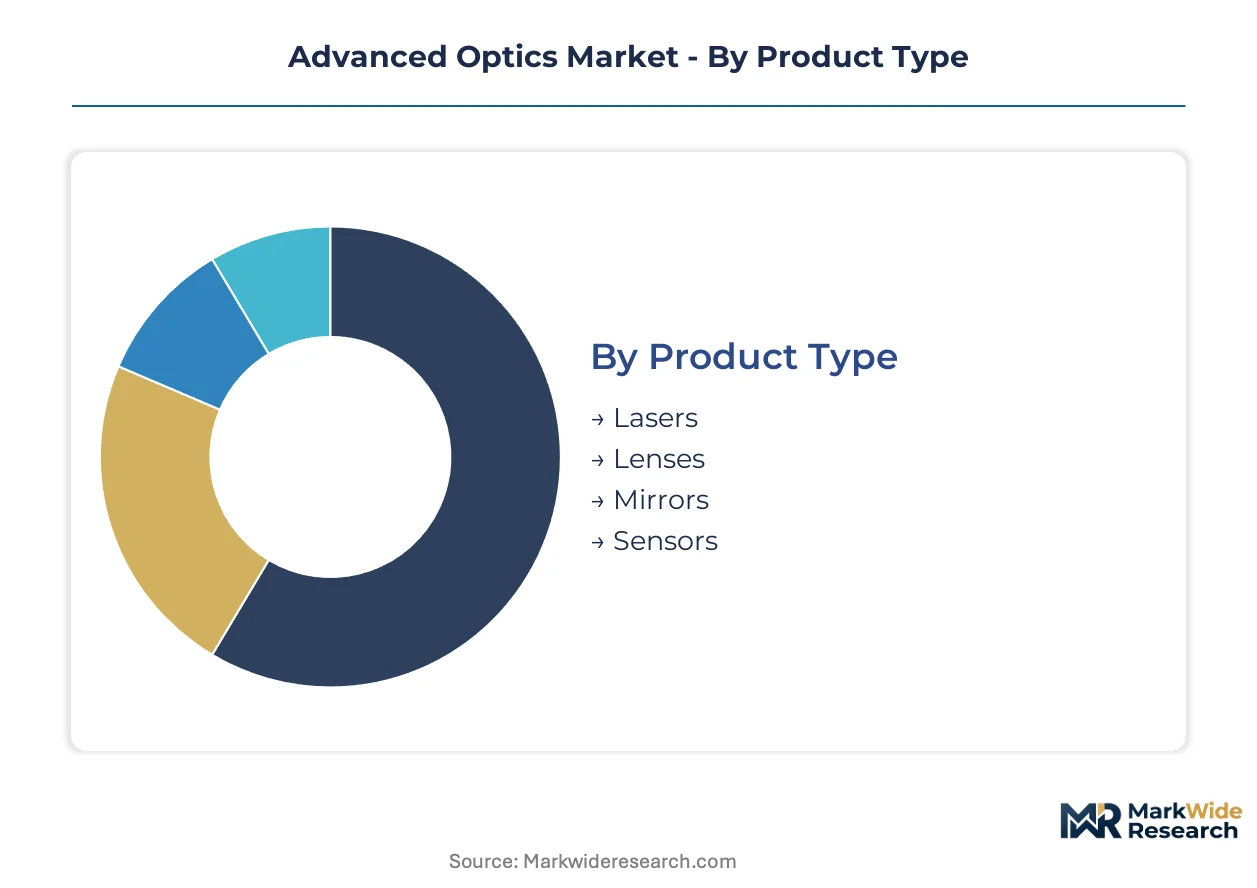
Segmentation in advanced optics reveals how technical specifications fragment procurement patterns across defense, medical, and telecommunications verticals. Each dimension—product architecture, underlying physics, use case, and buyer sophistication—creates distinct margin profiles and certification requirements that reshape supplier strategy.
Product Type:
Standardized commodity optics compete against application-specific engineered subsystems, with customization intensity rising sharply from passive components to active sources.
- Lasers:Solid-state and fiber-coupled architectures dominate precision manufacturing and directed-energy applications. Defense contractors in the United States and Germany are consolidating procurement around eye-safe wavelengths and ruggedized packaging for field-deployable targeting systems.
- Lenses:Aspheric and freeform surfaces reduce element counts in miniature imaging systems. Automotive LiDAR developers in Japan and South Korea are driving demand for thermal-stable substrates that maintain figure tolerance across operating temperature swings.
- Mirrors:Dielectric-coated and metallic substrates serve beam steering and cavity stabilization functions. Ion-beam sputtered high-reflectivity stacks command premium pricing in ultraviolet lithography and gravitational-wave detection installations.
- Sensors:CMOS and InGaAs focal plane arrays convert optical signals to electrical output. Samsung Electronics and Sony anchor volume demand through mobile camera and automotive imaging module integration.
Most installed capacity flows through Lenses. Expansion is steepest in Lasers.
Technology:
Proprietary process control separates thin-film coating specialists from commodity component fabricators, with government-funded quantum initiatives creating new capability requirements.
- Photonics:Fiber-coupled and integrated waveguide architectures enable high-bandwidth signal processing. Coherent pluggable optics deployment by hyperscale data center operators is concentrating procurement among suppliers with vertical crystal growth and packaging capabilities.
- Optical Coatings:Ion-beam sputtering and atomic layer deposition achieve sub-nanometer uniformity for ultraviolet-grade performance. ECHA REACH restrictions on heavy-metal precursors are forcing German and French coating houses to accelerate fluoropolymer substitution programs.
- Nanotechnology:Metasurface and subwavelength-structured elements compress form factors in augmented-reality headsets. Prototype-scale adoption by automotive LiDAR developers is validating manufacturing scalability.
- Quantum Dots:Colloidal semiconductor nanocrystals tunable across visible and infrared emission bands. National photonics programs in the United States, China, and the European Union are concentrating R&D funding before commercial volume materializes.
Revenue concentrates in Photonics. Patent filing velocity is highest in Quantum Dots.
Application:
Certification intensity and procurement cycle length vary dramatically between mission-critical defense systems and high-volume consumer electronics integration.
- Defense:Precision targeting, surveillance, and directed-energy systems require hardened environmental specifications. United States and European contractors are scaling procurement of adaptive optics and laser rangefinder subsystems under multi-year platform contracts.
- Medical Imaging:Optical coherence tomography and fluorescence-guided surgery systems demand FDA 510(k) or EU MDR clearance. Embedded algorithmic decision-support triggers escalating conformity requirements under the EU AI Act.
- Telecommunications:Coherent transceiver modules for 800G and 1.6T data center interconnects displace discrete transponder architectures. Direct procurement relationships with optical engine suppliers are consolidating vendor panels among North American and European hyperscale operators.
- Aerospace:Satellite optical communication terminals and earth observation payloads require radiation-hardened components. German precision manufacturing clusters around Jena supply ion-beam sputtered coatings for space-qualified mirror substrates.
Procurement value concentrates in Defense. Volume expansion is fastest in Telecommunications.
End User:
Buyer sophistication and technical specification authority determine whether suppliers sell standardized catalog products or engineer-to-order subsystems.
- Manufacturing:Laser-based cutting, welding, and additive fabrication systems require beam delivery optics with predictable thermal lensing behavior. German machine tool builders specify fused silica substrates with low thermal expansion coefficients.
- Healthcare:Hospital systems and diagnostic device OEMs purchase FDA-cleared optical subassemblies. Reviewer backlog in the 510(k) pathway is extending time-to-revenue for biomedical imaging innovators.
- Research Institutes:National laboratories and university consortia commission custom optical systems for fundamental physics and materials science. Government funding cycles create lumpy demand with extended qualification timelines.
- Consumer Electronics:Smartphone and automotive Tier 1 suppliers drive massive unit volumes with tight cost constraints. Dense CMOS sensor integration across mobile and automotive platforms anchors demand for wafer-scale optical packaging.
Volume flows through Consumer Electronics. Specification complexity is highest in Research Institutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing corridor commands ion-beam sputtering expertise, while the United States channels defense procurement through multi-year platform contracts. Japan and South Korea anchor consumer imaging volume through dense CMOS integration, with China accelerating domestic crystal growth capacity.
United States
Defense contractors scale procurement of precision targeting and surveillance systems under multi-year platform awards. FDA device classification rules govern optical diagnostic equipment market entry, extending time-to-revenue for biomedical imaging innovators. Greater Boston and Silicon Valley concentrate adaptive optics R&D tied to national photonics programs.
Germany
Machine tool builders specify fused silica substrates with low thermal expansion coefficients for laser-based manufacturing systems. ECHA REACH restrictions on heavy-metal coatings and persistent organic compounds force material strategy resets across thin-film stack suppliers. Jena and Oberkochen anchor supply chain resilience for ion-beam sputtered coatings and specialty crystal growth.
China
Domestic producers accelerate capacity for nonlinear optical crystals and fiber-coupled architectures. NMPA and MIIT standards govern medical imaging and telecommunications equipment certification. Yangtze River Delta manufacturing clusters scale atomic layer deposition capacity for ultraviolet-grade optics.
Japan
Automotive LiDAR developers drive demand for thermal-stable substrates maintaining figure tolerance across operating temperature swings. METI funding supports metasurface optics prototyping for augmented-reality applications. Kansai and Chubu regions concentrate precision glass molding and aspheric lens fabrication.
South Korea
Consumer electronics manufacturers anchor massive unit volumes for wafer-scale optical packaging. MFDS clearance requirements shape biomedical imaging subsystem procurement patterns. Seoul Capital Area facilities specialize in dense CMOS sensor integration across mobile and automotive platforms.
Advanced Optics Market Vendor Landscape
Top-tier vendors anchor photonics and coating technology, while mid-scale fabricators compete on specialized substrate geometries and regional certification speed. The vendor base stratifies across vertically integrated crystal growers, thin-film deposition specialists, and CMOS-integrated packaging houses. Strategic archetypes include captive supply chain controllers, algorithm-augmented subsystem providers, and hyperscale-direct optical engine suppliers. Competitive moves concentrate on backward integration into specialty materials and direct procurement relationships displacing traditional distributor channels.
Among Asia-Pacific-based electronics conglomerates, Samsung Electronics Co., Ltd. exemplifies volume-driven CMOS integration, while OmniVision Technologies Inc. occupies a position within imaging sensor specialization. Texas Instruments Incorporated represents the digital light processing archetype underpinning structured-light and lithography systems. These three companies illustrate how geographic concentration and technology anchoring shape competitive positioning without overlapping core competencies.
| Leading Market Players |
|---|
| OmniVision Technologies Inc. |
| Samsung Electronics Co., Ltd. |
| Broadcom Inc. |
| IPG Photonics Corp. |
| Texas Instruments Incorporated |
| Coherent Corp. |
| Intel Corporation |
| Fabrinet |
| Lumentum Holdings |
| Others |
Supply Flow & Price Mechanics
ECHA REACH phase-out deadlines for heavy-metal coatings and persistent organic compounds gate qualified supply access and premium-tier pricing eligibility for optical subsystem vendors. German and French coating houses that complete fluoropolymer substitution programs by 2027 command price premiums from defense and medical imaging buyers requiring CE-marked, substance-declared components.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for ultraviolet-grade atomic layer deposition coatings. Three-tier pricing structure across premium, standard, and economy levels separates ion-beam sputtered high-reflectivity stacks from magnetron-sputtered alternatives and uncoated substrates. Cost compression in standard-tier lenses intensifies because automotive LiDAR developers in Japan and South Korea negotiate volume contracts with thermal-stable substrate specifications. Consumer electronics buyers exhibit highest price sensitivity, while research institutes commissioning custom gravitational-wave detection optics show lowest.
Supply Chain Analysis
Nonlinear optical crystal supply rests on vertically integrated producers in the United States, Germany, and China controlling captive feedstock for specialty laser architectures. German precision manufacturing clusters around Jena and Oberkochen anchor ion-beam sputtering expertise, while South Korean facilities specialize in dense CMOS sensor integration. Single-source vulnerability concentrates in specialty laser crystal growth, where independent component fabricators lack backward integration into rare-earth doped YAG and vanadate feedstock. Distribution runs through direct procurement relationships with hyperscale data center operators displacing traditional distributor channels for coherent pluggable optics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Advanced Optics Market represents a late-cycle quality story as telecommunications infrastructure refresh cycles and defense procurement compress supplier lead times toward premium-specification subsystems. Buyers now prioritize certified optical engines over commodity components, rewarding vendors with vertical crystal growth and packaging capabilities.
For Market Incumbents: Acquire atomic layer deposition equipment fleets to secure ultraviolet-grade coating capacity before 2027 REACH restriction deadlines. Consolidate around Jena and Oberkochen manufacturing corridors to anchor supply chain resilience for ion-beam sputtered coatings. Counter emerging metasurface optics entrants by accelerating fluoropolymer substitution programs that maintain CE marking eligibility under ECHA substance declarations. For New Entrants and Emerging Players: Enter via automotive LiDAR qualification pathways for structured-light and solid-state scanning modules penetrating advanced driver-assistance systems. Target South Korean and Japanese automotive Tier 1 suppliers seeking thermal-stable substrates with figure tolerance across operating temperature swings. Pursue software-defined adaptive optics service contracts that shift monetization from hardware-only sales toward recurring calibration revenue. For Investors and Strategic Acquirers: Roll-up economics work for thin-film coating specialists because ECHA REACH compliance timelines fragment mid-scale German and French houses unable to fund fluoropolymer substitution programs alone. Five-to-ten-year viability favors vendors with vertical integration into specialty crystal growth and direct hyperscale relationships for coherent transceiver modules. Monitor NMPA and MIIT certification acceleration in China as inflection indicator for domestic capacity displacement of imported ultraviolet-grade optics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Crystal Growth | Captive YAG and vanadate feedstock secures laser supply chains against single-source bottlenecks. |
| Fluoropolymer Substitution Program Acceleration | CE marking eligibility under ECHA REACH 2027 deadlines preserves European defense and medical access. |
| Direct Hyperscale Procurement Relationship | Cloud infrastructure operators specifying 800G and 1.6T pluggable form factors consolidate vendor panels. |
| Software-Defined Adaptive Optics Platform Launch | Algorithm-controlled wavefront correction shifts supplier monetization toward recurring service revenue. |
| Automotive LiDAR Module Qualification | Structured-light and solid-state scanning penetration into advanced driver-assistance systems opens volume contracts. |
Methodological Framework
Direct dialogue with coating chamber operators, thin-film metrology technicians, defense procurement officers, biomedical imaging OEM regulatory affairs leads, and hyperscale data center optical engine specifiers grounded qualitative findings. Secondary validation drew from FDA 510(k) submission databases, ECHA REACH substance restriction notifications, SEC filings of publicly traded photonics vendors, and German machine tool builder procurement specifications. Bottom-up segment sizing and top-down macro constraint triangulation cross-checked volume and value estimates.
Segmentation outputs across product architecture, underlying physics, use case intensity, and buyer sophistication dimensioned the analytical framework over the projection horizon. CAGRs derived from installed base turnover rates, replacement cycle compression, and technology substitution curves modeled coherent pluggable optics displacement of discrete transponder designs and metasurface optics prototype scaling. Forecast inputs incorporated ECHA compliance timeline adherence probabilities and NMPA certification velocity for Chinese domestic capacity.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time coating chamber utilization rates and defense contract award timing introduce uncertainty bands around near-term capacity expansion trajectories. Forecasts reflect documented assumptions regarding REACH substitution program completion rates and hyperscale data center build schedules. A small set of triggers—ECHA restriction deadline extensions, FDA 510(k) pathway backlog resolution, and Chinese atomic layer deposition equipment import acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Photonics Sensor Market
Optics
Picosecond Lasers Market
Optics
Europe Laser Interferometer Market
Optics
Fiber Optic Amplifier Market
Optics
MEMS Mirrors Market
Optics
Global Super Hi Vision Market
Optics
Optical Wavelength Service Market
Optics
Optical Measuring Systems Market
Optics
Fiber-Optic Couplers Market
Optics
Asia-Pacific Anti-Blue Ray Myopia Lenses Market
Optics
Fiber Optical Receivers Market
Optics
Optical Profilometer Market
Optics
Optical Telephoto Lens Market
Optics
Smart Glass Market
Optics
Beam Expanders Market
Optics
Optical Fiber Market