
 Fiber Optic Amplifier Market | 2026-2036
Fiber Optic Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optic Amplifier Market Analytics
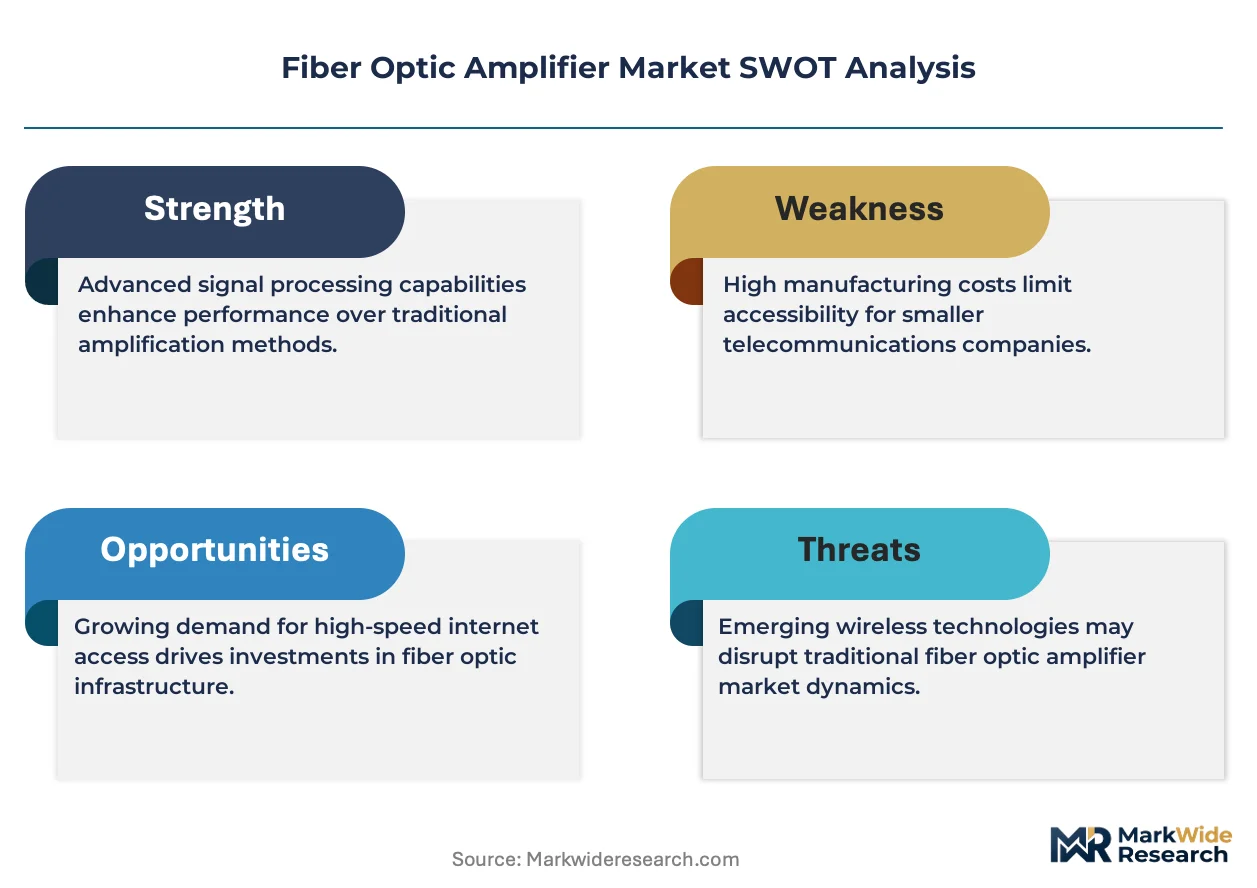
The fiber optic amplifier market is pivoting on a widening split between premium EDFA modules for submarine and long-haul routes and commodity optical boosters for metro access. Lumentum Holdings Inc. leverages its vertical integration in pump laser diodes to command premium tier positioning. Coherent Corporation anchors its competitiveness through coherent optical engine bundling with amplifier subsystems.
A fiber optic amplifier is an active photonic device that boosts optical signal power without optical-to-electrical conversion, typically employing erbium-doped fiber pumped at 980 nm or 1480 nm to achieve noise figures below 5 dB and output powers exceeding 20 dBm. Doped fiber amplifiers dominate current revenue owing to proven reliability in submarine cable systems, while semiconductor optical amplifiers are gaining traction in data center interconnects where compact form factors and CMOS compatibility offset higher noise penalties. Raman amplifiers occupy a specialized niche in ultra-long-haul links where distributed amplification extends unrepeatered reach.
FCC Part 15 emissions rules and FDA laser safety classifications shape product certification requirements for U.S. deployments, while EU REACH restrictions on rare-earth element processing influence supply chain configuration for European vendors. China's MIIT sets domestic network equipment standards that favor local amplifier suppliers for national backbone projects. Stakeholders must weigh regulatory divergence against the cost of maintaining multiple product qualification streams.
Market Dynamics
Data center operators in China, Germany, and the United States are driving procurement toward high-output EDFA modules while submarine cable consortia demand ultra-low-noise variants, creating a bifurcation in amplifier specifications that reshapes vendor R&D allocation and factory loading.
Growth Catalysts
- EU Energy Efficiency Directives:Tighter standby power limits for telecom equipment are accelerating replacement cycles in European backbone networks, favoring next-generation pump laser architectures.
- Hyperscale Data Center Buildouts:Domestic cloud providers in China are constructing massive fiber backbones between Beijing, Shanghai, and Shenzhen, concentrating demand for high-channel-count amplifier arrays.
- Raman Amplification:Distributed amplification schemes are extending unrepeatered submarine reach across trans-Pacific routes, reducing the need for costly mid-ocean regenerators.
Market Restraints
- Rare-Earth Supply Concentration:Erbium and ytterbium refining capacity clusters in Chinese processing facilities, exposing amplifier manufacturers to export quota volatility and price swings.
- Semiconductor Optical Amplifier Noise Floors:SOAs exhibit 3-5 dB higher noise figures than EDFAs, limiting their deployment in long-haul links despite CMOS compatibility advantages.
- EU REACH Compliance Costs:Restrictions on rare-earth element processing and chemical handling are forcing European vendors to maintain dual qualification streams for domestic and export markets.
Strategic Opportunities
- India National Broadband Mission:The government's rural fiberization targets under BharatNet Phase III are opening procurement windows for cost-optimized amplifier modules in tier-2 and tier-3 cities.
- Coherent Optical Engine Convergence:Integration of DSP-enabled transceivers with amplifier subsystems is creating bundled solution opportunities for submarine cable system integrators.
- Silicon Photonics Interconnects:CMOS-compatible amplifier designs are penetrating intra-data center links, displacing traditional pluggable optics in hyperscale facilities.
Industry Challenges
- Specialized Fiber Splicing Expertise:Erbium-doped fiber handling requires precision fusion splicing capabilities that exceed standard telecom technician training, constraining field deployment velocity.
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA laser safety, FCC Part 15 emissions, and MIIT network equipment approvals extend product launch cycles by 8-14 months for global amplifier platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Amplifier Market |
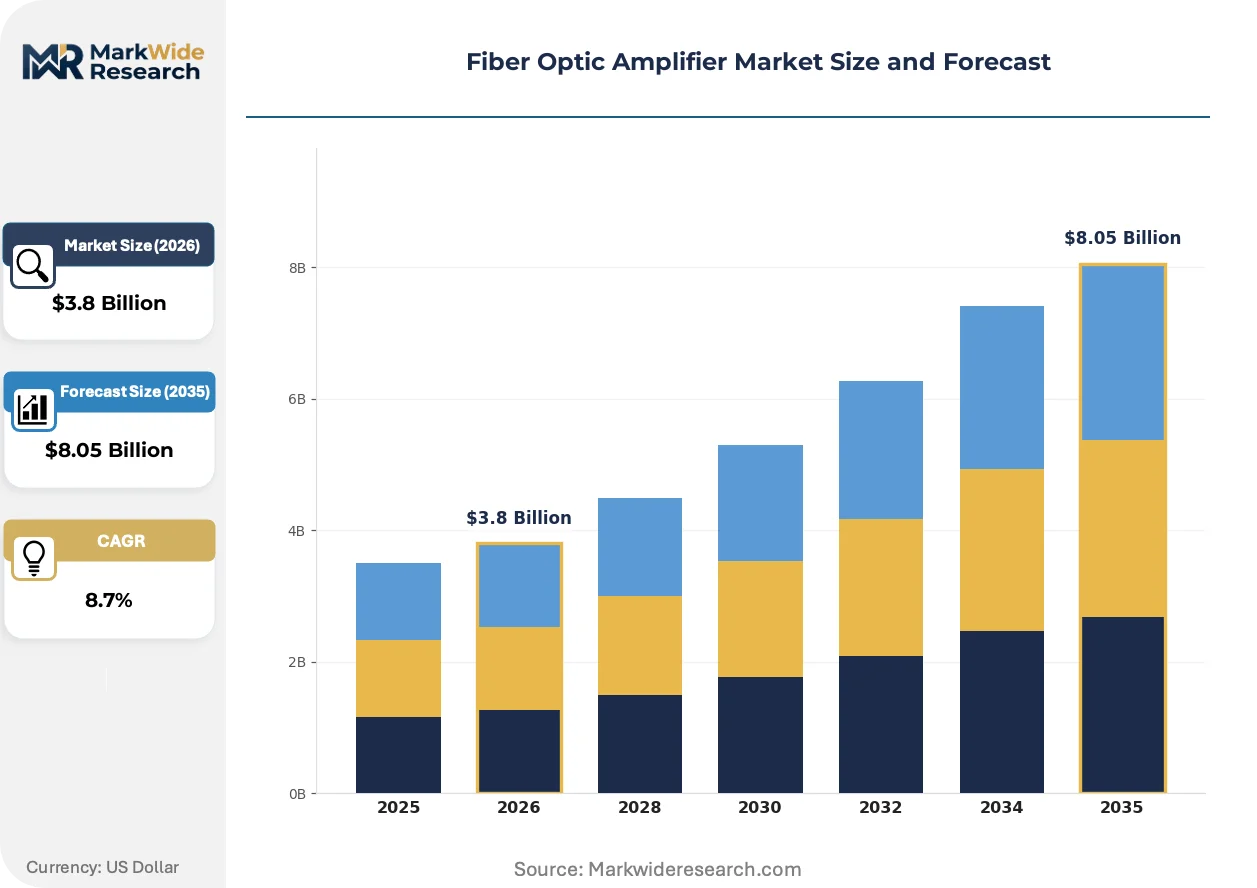
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Doped Fiber Amplifiers, Semiconductor Optical Amplifiers, Raman Amplifiers, Fiber Parametric Amplifiers End User: Telecommunication, Data Centers, Research Institutions, Defense Application: Long-Haul Communication, Metro Networks, CATV, Optical Networking Technology: EDFA, SOA, RFA, Optical Booster |
| Companies Covered | Lumentum Holdings Inc., Coherent Corporation, Broadcom Inc., II-VI Incorporated, Ciena Corporation, Huawei Technologies Co., Ltd., Sumitomo Electric Industries, Ltd., IPG Photonics Corporation, Fujitsu Optical Components, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Amplifier Market Evolving Landscape
Amplifier architectures are fragmenting along application-specific performance vectors, with submarine, data center, and metro access segments diverging on noise, power, and form factor priorities. This specialization is compressing the viable design space for general-purpose platforms.
Hybrid Raman-EDFA amplification is overtaking pure EDFA designs in ultra-long-haul submarine cables. The combined scheme distributes gain across the transmission fiber itself, reducing effective noise figure below 4 dB. Trans-Pacific cable consortia including those landing in Japan, California, and Singapore have standardized on hybrid configurations for 12,000 km+ unrepeatered spans. This architecture is overtaking discrete amplifier hut deployments, eliminating roughly 30% of mid-ocean power and maintenance infrastructure.
EU F-Gas Regulation phase-down schedules are pressuring manufacturers to eliminate sulfur hexafluoride from high-voltage pump laser power supplies. German and French amplifier vendors are redesigning driver electronics around solid-state alternatives, adding 6-9 months to product development cycles. Submarine amplifier pressure housings and terrestrial high-power outdoor cabinets face the most acute redesign deadlines under the 2030 reduction targets.
Chinese state-owned carriers are consolidating amplifier procurement under centralized MIIT framework agreements, compressing vendor margins and standardizing specifications across provincial network builds. Previously fragmented provincial tenders allowed customization for local terrain and traffic patterns. The centralized model favors domestic suppliers with scale manufacturing in Wuhan and Shenzhen, forcing foreign amplifier vendors to compete on price within narrower performance bands or exit backbone tier-1 procurement entirely.
Fiber Optic Amplifier Market Segmentation
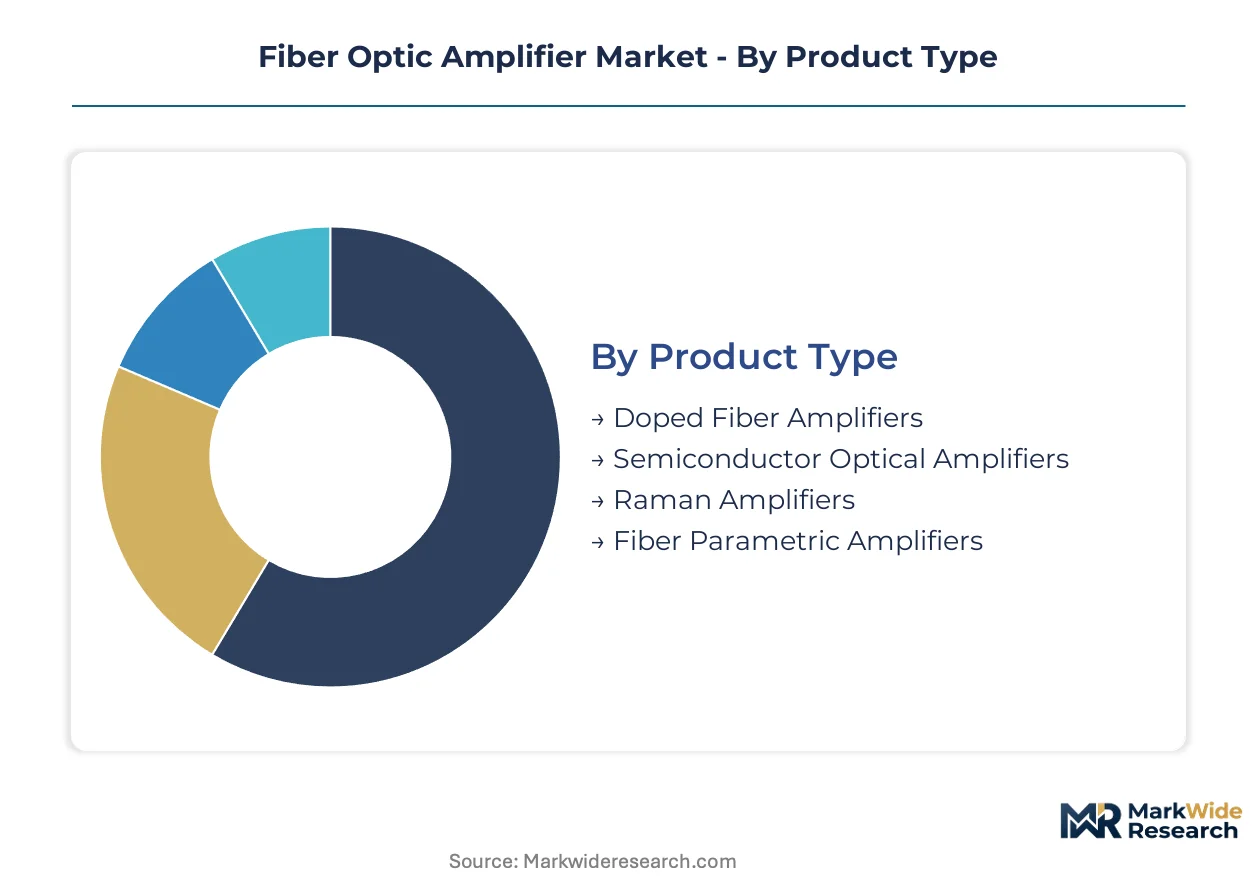
Amplifier procurement splits sharply between legacy network refresh cycles and greenfield hyperscale deployments. Equipment buyers weight noise figure, channel density, and energy draw differently across submarine, metro, and data center contexts. Segmentation clarity enables vendors to align factory loading with divergent qualification timelines and margin profiles.
Product Type:
Upgrade cycles vary dramatically by amplifier physics, with doped fiber systems facing 10-15 year replacement horizons in submarine cables while semiconductor designs turn over every 3-5 years in cloud facilities.
- Doped Fiber Amplifiers:Erbium-doped fiber pumped at 980 nm or 1480 nm achieves noise figures below 5 dB and output powers exceeding 20 dBm. Submarine cable consortia across trans-Pacific routes standardize on these modules for 12,000 km+ unrepeatered spans, though rare-earth supply concentration in Chinese processing facilities exposes manufacturers to quota volatility.
- Semiconductor Optical Amplifiers:III-V compound semiconductor chips deliver CMOS-compatible amplification in compact form factors. Hyperscale data centers in China deploy these for intra-facility links despite 3-5 dB noise penalties that disqualify them from long-haul use.
- Raman Amplifiers:Distributed gain schemes pump transmission fiber directly, extending reach without discrete amplifier huts.
- Fiber Parametric Amplifiers:Nonlinear optical effects in specialty fibers enable phase-sensitive amplification for research applications.
Volume placements concentrate in doped fiber amplifiers; the faster expansion belongs to semiconductor optical amplifiers.
End User:
Customer procurement authority shapes specification rigidity, with state-owned carriers enforcing centralized frameworks while private cloud operators negotiate custom performance bands.
- Telecommunication:National backbone operators in China consolidate procurement under MIIT framework agreements, compressing margins and standardizing specifications across provincial builds. German and French carriers face EU Energy Efficiency Directive deadlines that accelerate replacement cycles.
- Data Centers:Domestic cloud providers in Beijing, Shanghai, and Shenzhen construct massive fiber backbones, concentrating demand for high-channel-count amplifier arrays with tight latency constraints.
- Research Institutions:Universities and national laboratories drive low-volume, high-specification orders for experimental amplification schemes.
- Defense:Military communications networks require ruggedized modules with enhanced electromagnetic interference shielding.
Telecommunication captures the dominant share of unit shipments; data centers are climbing the fastest.
Application:
Distance requirements and signal regeneration economics determine amplifier architecture selection, with unrepeatered spans favoring distributed gain and metro rings prioritizing cost-optimized discrete modules.
- Long-Haul Communication:Trans-Pacific and trans-Atlantic submarine cables deploy hybrid Raman-EDFA configurations to eliminate roughly 30% of mid-ocean power infrastructure. FCC Part 15 emissions rules and FDA laser safety classifications extend product launch cycles by 8-14 months for these platforms.
- Metro Networks:Urban fiber rings in tier-2 and tier-3 Indian cities under BharatNet Phase III open procurement windows for cost-optimized modules with relaxed noise specifications.
- CATV:Cable television distribution networks require high-output amplifiers to overcome splitter losses in last-mile coaxial plants.
- Optical Networking:Enterprise and carrier Ethernet overlays demand flexible amplification with software-defined gain control.
Long-haul communication absorbs the premium-priced volume; metro networks are gaining share fastest.
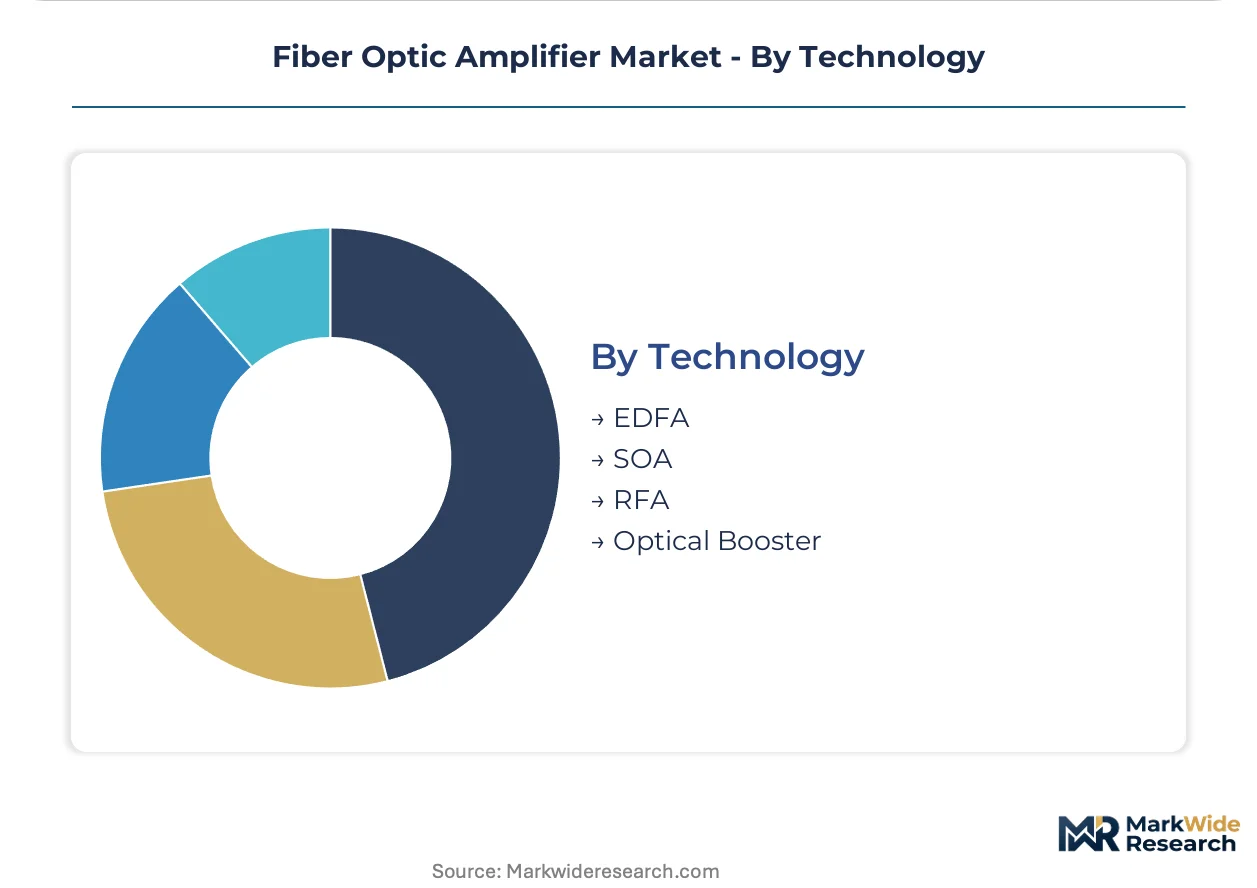
Technology:
Technology selection locks vendors into specific supply chain configurations, with EDFA production requiring captive rare-earth fiber drawing while SOA manufacturing leverages standard semiconductor foundries.
- EDFA:Erbium-doped fiber amplifier technology dominates submarine and terrestrial backbone revenue through proven reliability in undersea cable systems. EU REACH restrictions on rare-earth element processing force European vendors to maintain dual qualification streams.
- SOA:Semiconductor optical amplifier designs penetrate intra-data center links where CMOS compatibility offsets higher noise floors.
- RFA:Raman fiber amplifier technology occupies ultra-long-haul niches requiring distributed amplification.
- Optical Booster:High-power post-amplifier modules compensate for mux/demux losses in dense wavelength division systems.
EDFA maintains the installed base dominance; SOA shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wuhan and Shenzhen anchor amplifier manufacturing concentration, with Chinese state-owned carriers consolidating procurement under MIIT framework agreements that compress vendor margins across provincial network builds.
China
Domestic cloud providers in Beijing, Shanghai, and Shenzhen construct massive fiber backbones between tier-1 cities, driving procurement toward high-channel-count amplifier arrays. MIIT sets domestic network equipment standards that favor local suppliers for national backbone projects. Wuhan and Shenzhen industrial clusters concentrate EDFA module manufacturing for both domestic deployment and export markets.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth metro areas expand high-capacity optical link deployments. FCC Part 15 emissions rules and FDA laser safety classifications shape product certification requirements for amplifier deployments. Submarine cable landing stations in California and New Jersey drive demand for ultra-low-noise EDFA variants on trans-Pacific routes.
Germany
Deutsche Telekom and other national carriers face EU Energy Efficiency Directive deadlines that accelerate replacement cycles in backbone networks. EU F-Gas Regulation phase-down schedules pressure manufacturers to eliminate sulfur hexafluoride from high-voltage pump laser power supplies. Berlin and Munich host amplifier system integrators redesigning driver electronics around solid-state alternatives.
Japan
Trans-Pacific cable consortia landing in Chiba and Kanagawa prefectures standardize on hybrid Raman-EDFA configurations for 12,000 km+ unrepeatered spans. METI oversees industrial standards for optical communications equipment. Yokohama and Osaka industrial corridors concentrate precision fusion splicing expertise for erbium-doped fiber handling.
India
BharatNet Phase III rural fiberization targets under the National Broadband Mission open procurement windows for cost-optimized amplifier modules in tier-2 and tier-3 cities. TRAI regulates telecom equipment standards while BIS certification applies to network infrastructure. Chennai and Pune emerging as assembly locations for import-dependent amplifier subsystems.
Fiber Optic Amplifier Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and application specialization, with submarine cable qualification creating the steepest margin differentiation. The vendor base stratifies into three tiers: integrated pump laser manufacturers, amplifier subsystem specialists, and contract assembly houses. Strategic archetypes include vertically integrated photonics conglomerates, pure-play optical component vendors, and state-affiliated national champions. Dominant competitive moves center on coherent optical engine bundling and rare-earth fiber supply chain locking.
Within the integrated photonics tier, Lumentum Holdings Inc. and Coherent Corporation exemplify divergent approaches to amplifier market positioning. Lumentum leverages in-house pump laser diode production to command premium-tier placement. Coherent anchors its competitiveness through subsystem bundling with coherent optical engines. Huawei Technologies Co., Ltd. occupies a distinct position as a state-affiliated national champion with captive demand from Chinese backbone operators.
| Leading Market Players |
|---|
| Lumentum Holdings Inc. |
| Coherent Corporation |
| Broadcom Inc. |
| II-VI Incorporated |
| Ciena Corporation |
| Huawei Technologies Co., Ltd. |
| Sumitomo Electric Industries, Ltd. |
| IPG Photonics Corporation |
| Fujitsu Optical Components |
| Others |
Value Network & Pricing Analysis
State-affiliated national champions with captive rare-earth fiber drawing operations anchor supply-side discipline, compressing export-market pricing while private-label assemblers in India and Vietnam absorb margin pressure through volume scaling.
Pricing Analysis
Uptime-guarantee contracts serve as the dominant value-based pricing anchor, with submarine cable consortia paying premiums for mean-time-between-failure commitments exceeding 25 years. Three-tier pricing structure across premium, standard, and economy levels separates MIIT-qualified backbone tiers from metro-access and rural-fiber deployments. Cost compression in the economy tier is intensifying because Chinese state-owned carriers consolidate procurement under centralized framework agreements. Hyperscale data center operators exhibit the lowest price sensitivity, while BharatNet Phase III rural contractors face acute budget constraints.
Supply Chain Analysis
Refurbished pump laser modules and remanufactured erbium-doped fiber coils flow back into secondary markets through certified pre-owned channels, extending component lifecycles. Manufacturing gravity centers on China, Japan, and Germany, with Wuhan and Shenzhen clusters dominating EDFA module assembly. Production draws from erbium and ytterbium refining concentrated in Chinese processing facilities, 980 nm pump laser diodes from Japanese foundries, and specialty fusion splicing equipment from German precision-tooling houses. Single-source vulnerability in rare-earth element supply exposes amplifier vendors to export quota volatility. Distribution runs through submarine cable system integrators, national carrier procurement frameworks, and hyperscale direct-fulfillment contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with pump laser diode production and rare-earth fiber drawing emerging as the decisive upstream levers separating premium-tier vendors from margin-compressed assemblers.
For Market Incumbents: Deepen captive rare-earth fiber drawing capabilities to insulate against Chinese export quota volatility. Lock submarine cable qualification status through extended mean-time-between-failure warranties. Semiconductor optical amplifier noise floors below 3 dB represent the substitute threat demanding R&D preemption. For New Entrants and Emerging Players: Begin with cost-optimized amplifier modules for BharatNet Phase III rural fiberization in tier-2 and tier-3 Indian cities. Target metro-access deployments where noise specifications remain relaxed. Partner with Chennai and Pune assembly houses to bypass import-dependent subsystem barriers. For Investors and Strategic Acquirers: MIIT framework agreement award announcements are the leading indicator that vendor consolidation has reached inflection. Long-term viability hinges on backward integration into pump laser production or rare-earth fiber drawing. Acquisition targets should display captive supply agreements with Chinese erbium refiners or Japanese 980 nm laser foundries. Watch for F-Gas Regulation solid-state power supply redesign completions as margin-recovery signals.| Strategic Initiative | Industry Significance |
|---|---|
| Pump Laser Diode Backward Integration | Lumentum's in-house production commands premium-tier positioning against subsystem assemblers. |
| Submarine Cable Qualification Investment | Hybrid Raman-EDFA configurations eliminate 30% of mid-ocean infrastructure for trans-Pacific consortia. |
| Silicon Photonics CMOS Compatibility | SOA designs displace pluggable optics in hyperscale intra-data center links despite noise penalties. |
| EU F-Gas Regulation Compliance Redesign | German and French vendors face 6-9 month development delays replacing sulfur hexafluoride power supplies. |
| Coherent Optical Engine Bundling | Coherent Corporation anchors competitiveness through DSP-enabled transceiver-amplifier subsystem integration. |
Research Methodology
Independent corroboration across amplifier subsystem engineering directors, submarine cable procurement leads, hyperscale data center network architects, and rare-earth materials sourcing managers underwrites the qualitative findings. Primary interviews with MIIT framework agreement negotiators, EU Energy Efficiency Directive compliance officers, and BharatNet Phase III implementation contractors combined with secondary validation from FCC Part 15 equipment authorization databases, FDA laser product registration filings, and customs trade data for erbium-doped fiber imports. Bottom-up unit economics and top-down infrastructure capex trajectories triangulate market sizing.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include amplifier physics type, end-user procurement authority, application distance requirements, and pump laser architecture generation. CAGRs derive from equipment replacement cycle analysis and hyperscale facility buildout pipelines. Forecast inputs incorporate submarine cable landing station commitments, MIIT provincial backbone tender schedules, and EU F-Gas Regulation phase-down compliance deadlines.
Underlying measurement precision varies by segment; submarine cable and data center deployments carry tighter precision than research institution and defense applications. Forecasts reflect documented assumptions regarding rare-earth supply quota stability, pump laser diode yield improvements, and hyperscale capex continuity. Practitioners should monitor MIIT framework agreement award volumes, EU solid-state power supply redesign completions, and trans-Pacific cable consortium procurement announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Laser Transmitter Market
Optics
Lasers Market
Optics
Optical Receivers Market
Optics
Optical Profilometer Market
Optics
Polymeric Optical Fiber Market
Optics
Global Fiber Optic Sensors Market
Optics
Smartphone Lenses Market
Optics
Picosecond Lasers Market
Optics
Plastic Lens Market
Optics
Fixed Focal Length Lenses Market
Optics
Stroboscope Market
Optics
Fiber Optic Receiver Market
Optics
Optical Telephoto Lens Market
Optics
Global Enhanced Vision System Market
Optics
Optical Fiber Raw Material Market
Optics
Global Super Hi Vision Market