
 Compound Semiconductor Market | 2026-2036
Compound Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Compound Semiconductor Market Intelligence
Software-defined functionality in power and RF systems is expanding the addressable market for high-performance components. Infineon Technologies leverages its extensive scale in automotive and industrial power electronics. Wolfspeed Inc. specializes in the production of Silicon Carbide and Gallium Nitride materials, controlling a key part of the upstream supply chain. Skyworks Solutions Inc. dominates the complex front-end modules for mobile devices, a significant high-volume application.
Compound semiconductors are materials formed from two or more elements, such as Gallium Nitride (GaN) or Indium Phosphide (InP). Their superior properties, including wider bandgaps, enable devices to operate at higher frequencies and power densities than silicon. Among product types, Gallium Nitride and Silicon Carbide are seeing rapid adoption. This shift is most evident in the power electronics and RF components application segments, supporting electric vehicles and 5G base stations.
Material standards are shaped by frameworks like the EU's RoHS directive, which restricts hazardous elements in electronics. Concurrently, energy efficiency mandates from the US EPA and China's dual carbon goals create specific demand for SiC and GaN-based power converters. Future market leadership will depend on securing access to critical raw materials and mastering complex epitaxy and MOCVD manufacturing processes.
Market Dynamics
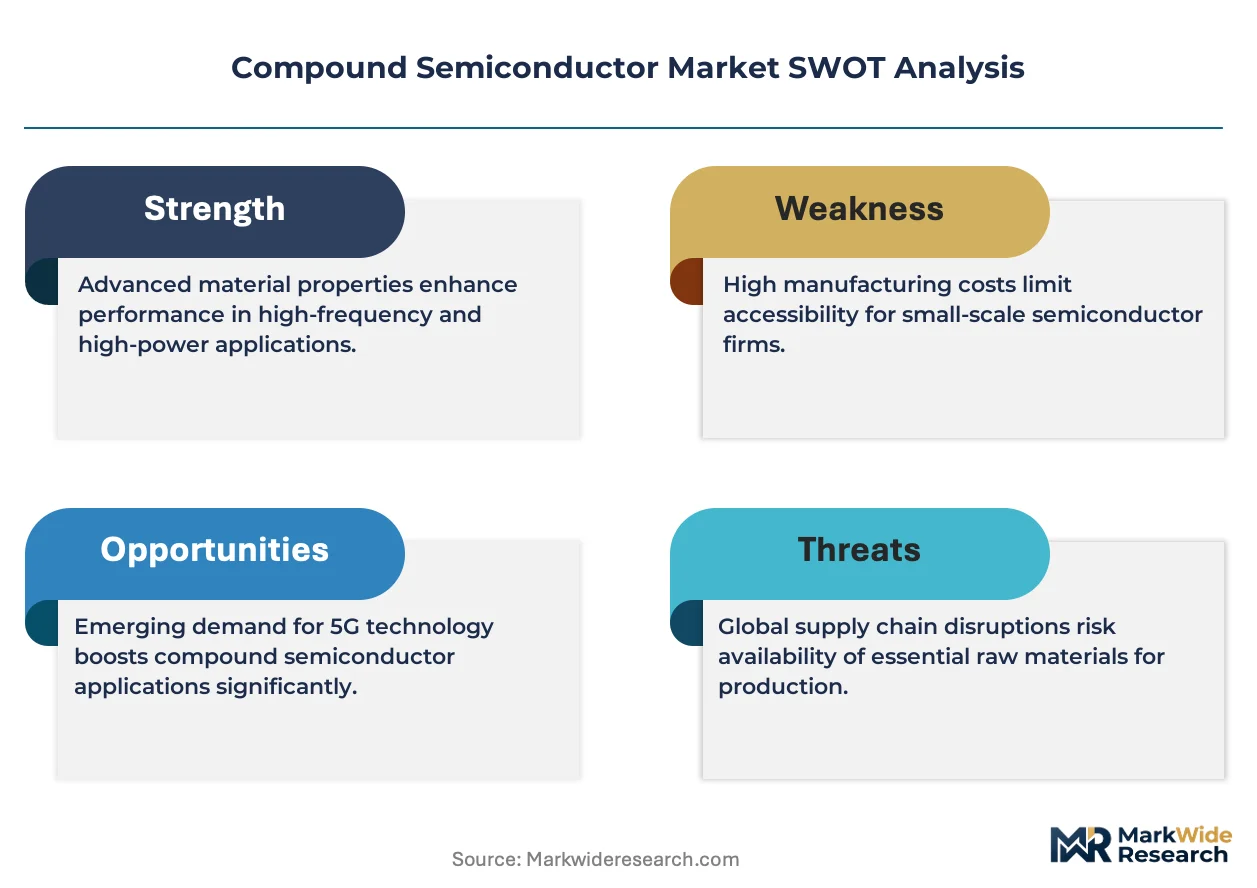
The central dynamic shaping the compound semiconductor market is the performance gap between legacy silicon and the requirements of next-generation power and RF systems. This gap forces a shift toward materials like SiC and GaN, despite their higher manufacturing complexity and cost.
Growth Catalysts
- Wide-Bandgap Materials:The superior properties of materials like Gallium Nitride and Silicon Carbide enable higher efficiency and power density in applications such as electric vehicle inverters and 5G base station power supplies.
- Energy Efficiency Mandates:Regulatory frameworks including the EU Green Deal and China's dual carbon goals create specific demand for SiC and GaN power devices to meet stringent energy consumption targets.
- Telecommunication Infrastructure:The global deployment of 5G and the development of 6G networks require high-frequency RF components that can only be produced using compound semiconductors like Gallium Arsenide and Indium Phosphide.
Market Restraints
- Manufacturing Complexity:Processes like metal-organic chemical vapor deposition (MOCVD) and epitaxy for compound semiconductors are significantly more complex and costly than silicon CMOS manufacturing, limiting production scale and yield.
- Substrate Availability:The supply of high-quality, large-diameter SiC and GaN substrates is a primary bottleneck, constraining device manufacturing capacity and contributing to higher component costs.
- Geopolitical Concentration:Advanced fabrication and packaging capacity is heavily concentrated in a few locations, such as Taiwan's Hsinchu Science Park, creating significant supply chain vulnerability to regional disruptions.
Strategic Opportunities
- Software-Defined Systems:The expansion of software-defined functionality in radio and power systems creates an opportunity for programmable compound semiconductor components that can adapt to multiple standards and operating conditions.
- Heterogeneous Integration:Combining compound semiconductor devices with silicon logic on a single package or chip allows designers to leverage the performance of GaN or SiC with the low cost and integration density of silicon.
- Underpenetrated Power Applications:Significant opportunity exists in displacing silicon in industrial motor drives, solar inverters, and uninterruptible power supplies where the efficiency gains from SiC and GaN justify the initial cost premium.
Industry Challenges
- Specialized Talent Shortage:A critical lack of engineers and technicians with expertise in compound semiconductor physics, epitaxy, and device fabrication hinders research and development and slows production ramp-ups.
- High Capital Investment:Building or expanding a compound semiconductor fabrication facility requires immense capital expenditure, creating a high barrier to entry for new players and constraining capacity growth for incumbents.
- Standardization Gaps:A lack of universally accepted standards for testing, reliability, and packaging of new SiC and GaN devices can slow adoption as end-users face integration and qualification hurdles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compound Semiconductor Market |
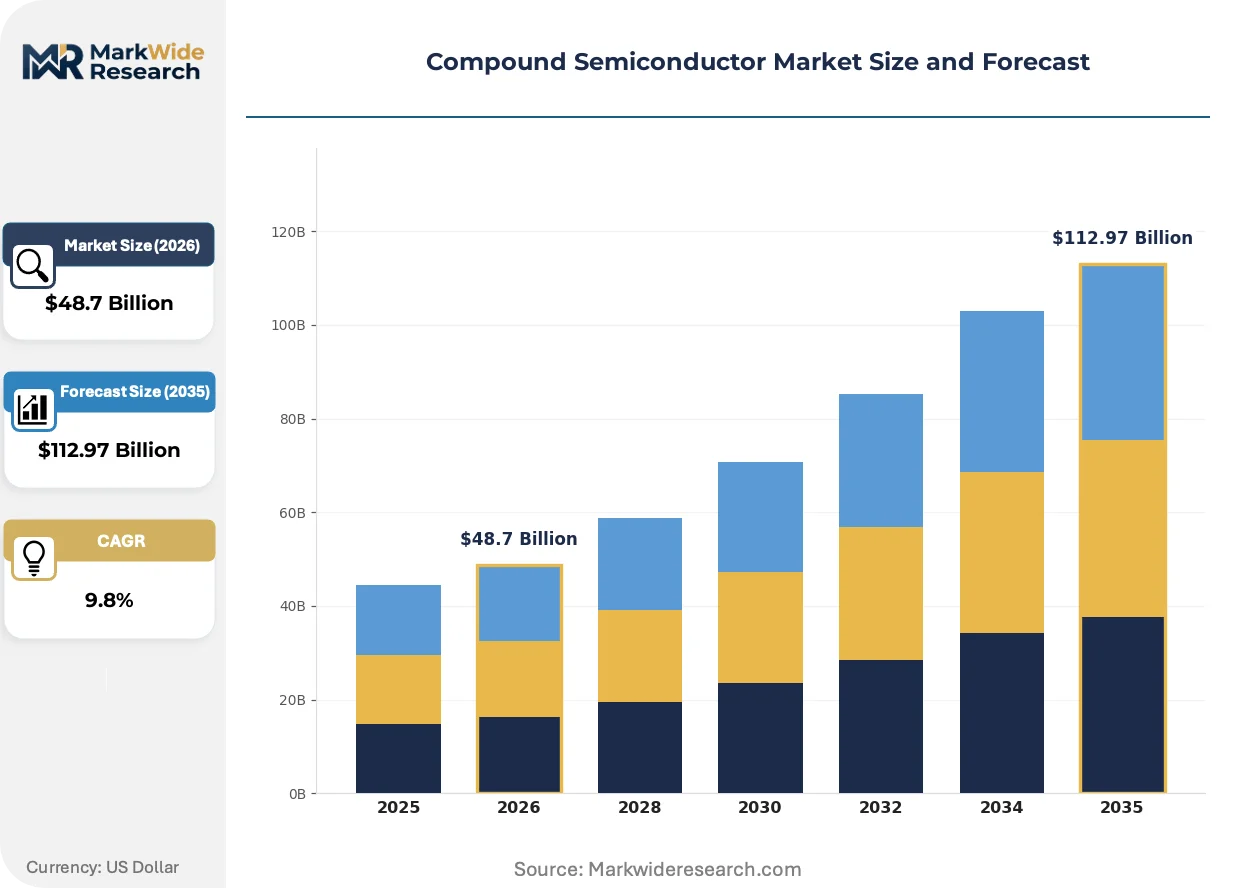
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $112.97 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gallium Nitride, Indium Phosphide, Gallium Arsenide, Silicon Carbide, Aluminum Gallium Arsenide Application: Optoelectronics, Power Electronics, RF Components, Photovoltaics, Sensor Technology Technology: MOCVD, HVPE, MBE, CVD, Epitaxy End User: Telecommunication Firms, Defense Contractors, Consumer Electronics Manufacturers, Semiconductor Foundries |
| Companies Covered | Analog Devices Inc., STMicroelectronics, Skyworks Solutions Inc., Onsemi, Infineon Technologies, Wolfspeed Inc., ams-OSRAM AG, TSMC, Qorvo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compound Semiconductor Market Strategic Shifts & Innovations
The market is defined by a push for higher performance in demanding applications, which in turn drives material and process innovation. This evolution is happening alongside a regulatory environment that increasingly values the energy efficiency that these advanced materials enable.
Gallium Nitride (GaN) technology provides superior electron mobility for high-frequency switching and power conversion. This material is seeing rapid adoption in consumer electronics for compact fast chargers and in telecommunications for efficient 5G radio frequency amplifiers. GaN-on-Silicon technology is integrating the performance benefits of GaN with the established, cost-effective scale of silicon manufacturing, accelerating its broader market acceptance.
The EU's RoHS directive, which restricts hazardous elements in electronics, continues to influence material science and component design across the industry. This regulation, combined with energy efficiency standards from the US EPA, creates a strong incentive for adopting SiC and GaN devices. Power electronics manufacturers are most affected, redesigning converters and inverters to achieve compliance and market their products on efficiency metrics.
A notable behavioral shift is occurring as system designers increasingly prioritize total cost of ownership and performance-per-watt over initial component price. This change in procurement logic favors the use of more expensive but highly efficient SiC and GaN components over traditional silicon in critical infrastructure. The trend is most pronounced in data center power supplies and electric vehicle powertrains, particularly in Europe and North America.
Compound Semiconductor Market Segmentation
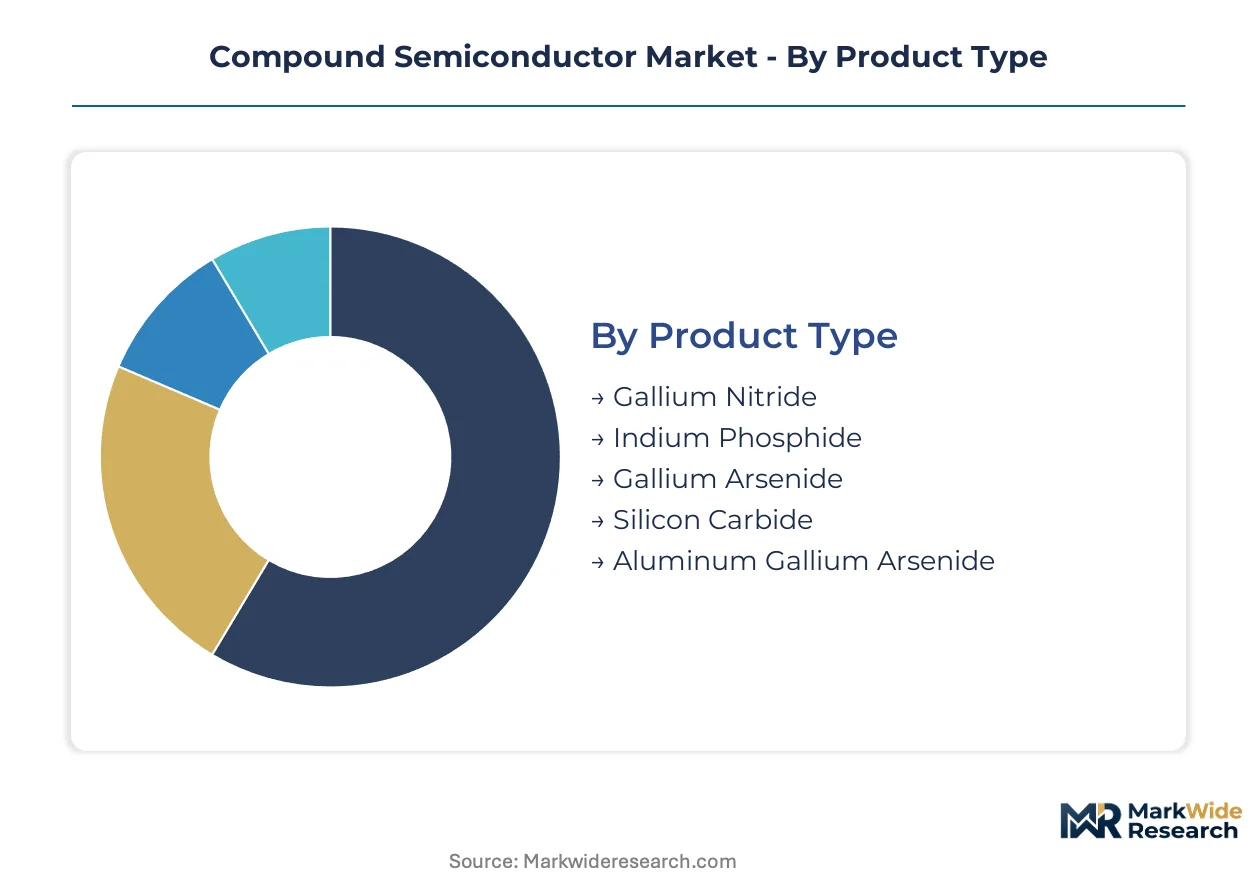
The Compound Semiconductor Market's segmentation reveals the diverse material science and application-specific demands driving its expansion. Understanding these distinct categories provides clarity on where technological innovation and investment are concentrating. This detailed breakdown highlights the specialized requirements across various industry verticals.
Product Type:
Product type selection is influenced by the customization-versus-standardization spectrum, where specialized materials serve niche, high-performance needs.
- Gallium Nitride:This wide-bandgap material offers superior electron mobility for high-frequency switching and power conversion. Demand is concentrating in consumer electronics for compact fast chargers and in telecommunications for efficient 5G radio frequency amplifiers, driven by energy efficiency mandates from the US EPA.
- Silicon Carbide:Known for its exceptional thermal conductivity and high breakdown voltage, Silicon Carbide enables efficient power devices for extreme environments. Demand is strongly concentrating in electric vehicle inverters and industrial motor drives, propelled by the EU Green Deal's emphasis on energy efficiency.
- Indium Phosphide:Indium Phosphide offers excellent properties for high-speed optoelectronic devices, especially in fiber optic communication.
- Gallium Arsenide:Gallium Arsenide is a foundational material for high-frequency RF components and specialized laser diodes.
- Aluminum Gallium Arsenide:Aluminum Gallium Arsenide is critical for light-emitting diodes and high-power laser applications.
Most installed capacity flows through Gallium Arsenide. Expansion is steepest in Gallium Nitride.
Application:
Volume requirements vary across application segments, with some areas demanding mass production and others prioritizing bespoke, high-performance solutions.
- Power Electronics:This segment involves devices that manage and convert electrical power efficiently, including inverters, converters, and power supplies. Demand is concentrating in electric vehicles and industrial motor drives, driven by stringent energy efficiency regulations like China's dual carbon goals.
- RF Components:Radio Frequency components enable wireless communication, including amplifiers, switches, and filters for high-frequency signals. Demand is concentrating in 5G and future 6G telecommunication infrastructure, requiring high-performance materials like Gallium Arsenide and Indium Phosphide.
- Optoelectronics:Optoelectronics integrates light and electronics, encompassing LEDs, laser diodes, and photodetectors for sensing and display.
- Photovoltaics:Photovoltaics converts light into electricity for solar cells and energy harvesting, prioritizing efficiency.
- Sensor Technology:Sensor technology uses compound semiconductors for advanced environmental, automotive, and industrial sensing applications.
The largest portion of market volume resides in Power Electronics. The RF Components segment is climbing the fastest.
Technology:
Supply concentration for manufacturing technologies dictates access to advanced processes, often localized in established semiconductor hubs.
- MOCVD:Metal-Organic Chemical Vapor Deposition is a crucial epitaxial growth technique for depositing thin layers of compound semiconductors. This technology is vital for producing high-quality Gallium Nitride and Gallium Arsenide devices, with significant capacity concentrated in regions like Taiwan's Hsinchu Science Park.
- Epitaxy:Epitaxy involves growing crystalline layers on a substrate, forming the active regions of compound semiconductor devices. It is a fundamental process for achieving the precise material structures required for high-performance components, essential for both Silicon Carbide and Gallium Nitride production.
- HVPE:Hydride Vapor Phase Epitaxy is a high-growth-rate technique used for thick GaN layers in power devices.
- MBE:Molecular Beam Epitaxy provides atomic-layer precision for complex heterostructures in high-end device fabrication.
- CVD:Chemical Vapor Deposition is a broad process category for depositing various thin films, including dielectric and conductive layers.
The most significant supply chain control resides with MOCVD. Epitaxy is gaining share fastest.
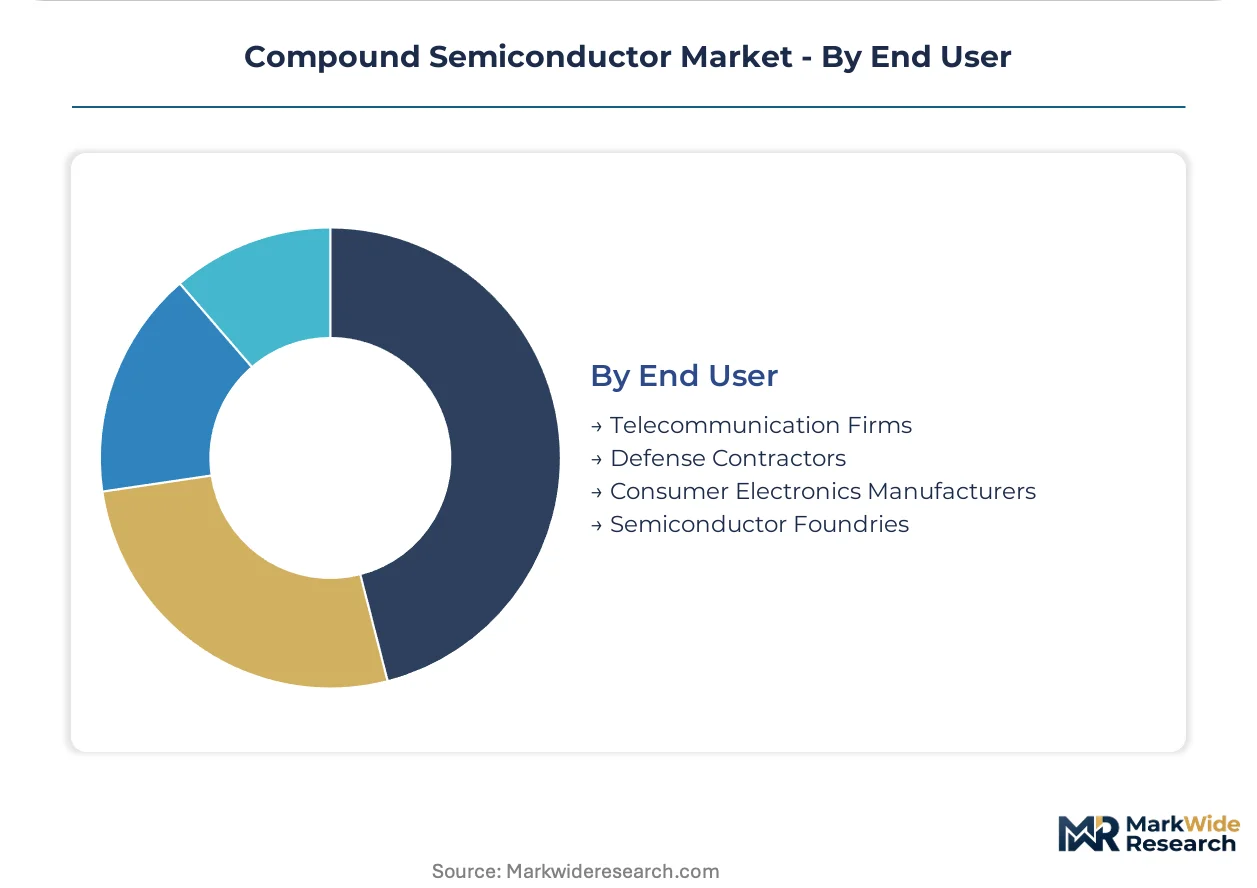
End User:
Customer type influences product specifications and procurement patterns, ranging from large-scale industrial buyers to highly specialized defense sector clients.
- Telecommunication Firms:These firms deploy compound semiconductors in base stations, satellites, and networking equipment for 5G and 6G infrastructure. Their demand is driven by the need for high-frequency, high-power RF components to enable faster data transmission.
- Consumer Electronics Manufacturers:This segment integrates compound semiconductors into devices like smartphones, laptops, and wearables for fast chargers and advanced display technologies. Efficiency and miniaturization are primary drivers, particularly for GaN-based power solutions.
- Defense Contractors:Defense contractors utilize compound semiconductors for radar systems, electronic warfare, and secure communication, prioritizing robust performance and reliability.
- Semiconductor Foundries:Foundries serve as manufacturing partners, producing compound semiconductor wafers and devices for fabless companies and integrated device manufacturers.
The largest customer base is comprised of Consumer Electronics Manufacturers. The Telecommunication Firms segment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States prioritizes advanced compound semiconductor research for defense applications, while China emphasizes domestic production to meet its vast industrial demand. This global market for compound semiconductors is shaped by varied regional demands and regulatory environments. Advanced manufacturing capabilities and strategic investments differentiate key geographical areas.
United States
Demand for 5G telecommunication infrastructure and electric vehicle power electronics drives growth. The US EPA's energy efficiency mandates influence device design and adoption. Silicon Valley and Arizona are seeing investment in new fabrication facilities and research hubs.
Germany
Automotive and industrial power electronics applications require advanced SiC and GaN materials. The EU Green Deal promotes energy-efficient power converters and systems. Dresden's "Silicon Saxony" cluster focuses on advanced manufacturing and R&D for wide-bandgap technologies.
China
Extensive 5G network deployment and electric vehicle production fuel significant demand. China's dual carbon goals accelerate the shift to SiC and GaN devices for energy efficiency. Shanghai and Shenzhen are developing integrated circuit industrial parks to support domestic production.
Japan
High-speed communication and automotive electronics require advanced compound semiconductor materials. METI initiatives support next-generation semiconductor development and capacity expansion. Kumamoto Prefecture is attracting new fab investments for advanced logic and power devices.
Taiwan
The region is critical for advanced manufacturing and foundry services for compound semiconductors. The government supports the semiconductor industry through strategic investments and talent development. Hsinchu Science Park remains a global hub for compound semiconductor production and innovation.
Compound Semiconductor Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting the market's hybrid structure. The industry exhibits a tiered landscape, with material suppliers, device manufacturers, and integrated device manufacturers forming distinct strategic archetypes. Capacity expansion and strategic partnerships remain dominant competitive moves across these players.
Leading integrated device manufacturers like Infineon Technologies leverage extensive scale in automotive and industrial power electronics. Wolfspeed Inc. exemplifies a specialist controlling critical upstream supply chains for Silicon Carbide and Gallium Nitride materials. Skyworks Solutions Inc. anchors the high-volume mobile device segment with complex front-end modules.
| Leading Market Players |
|---|
| Analog Devices Inc. |
| STMicroelectronics |
| Skyworks Solutions Inc. |
| Onsemi |
| Infineon Technologies |
| Wolfspeed Inc. |
| ams-OSRAM AG |
| TSMC |
| Qorvo Inc. |
| Others |
Cost & Logistics Intelligence
Specialized talent concentrations in established semiconductor hubs like Hsinchu Science Park influence manufacturing costs, creating differentials that shape pricing across various compound semiconductor product tiers.
Pricing Analysis
Capacity additions in Taiwan's Hsinchu Science Park are reshaping price floors for high-volume compound semiconductor components. The dominant pricing model remains contract-based long-term offtake, particularly for large automotive and telecommunication clients. Price differentiation stems from quality grade, driven by epitaxy process precision, and volume scale for major device manufacturers. Pricing pressure stems from substrate availability bottlenecks, pushing costs upward for SiC and GaN materials. Consumer electronics manufacturers exhibit the highest price sensitivity, while defense contractors prioritize performance over cost.
Supply Chain Analysis
Silicon Carbide substrate supply rests on a few specialized producers, introducing critical dependencies for device manufacturers. Geographic supply concentration is evident in Taiwan for advanced fabrication, Japan for specialized materials, and Germany for power electronics R&D. Raw material dependencies include high-purity SiC powder and gallium sources. Single-source vulnerability for large-diameter substrates represents a structural supply chain risk. Distribution for high-performance components runs through direct sales channels to integrated device manufacturers and large original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, driven by the fundamental performance advantages of compound semiconductors over silicon in next-generation power and RF systems.
For Market Incumbents: Deploy strategic raw material agreements to secure access to critical SiC and GaN substrates, mitigating supply chain bottlenecks. Invest heavily in advanced epitaxy and MOCVD process optimization to improve yields and reduce manufacturing complexity, addressing margin pressure from new entrants. Expand fabrication capacity in diversified geographies to reduce geopolitical concentration risk, enhancing operational resilience.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for highly efficient SiC and GaN power devices in industrial motor drives and solar inverters. Target underpenetrated power applications where total cost of ownership, not just initial component price, drives procurement decisions. A go-to-market angle focusing on GaN-on-Silicon solutions offers a path to leverage established silicon manufacturing infrastructure for broader market acceptance.
For Investors and Strategic Acquirers: Vertically integrated device manufacturers are the most active acquirers in this space, seeking to control upstream material supply. The long-term viability of compound semiconductors is assured by their intrinsic properties for electrification and high-frequency communication. Acquisition target archetypes include specialists in advanced epitaxy equipment, substrate manufacturing, or innovative packaging technologies. Commercialization of larger diameter SiC and GaN wafers is a signal to watch for accelerated market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Enables higher production volumes of SiC and GaN devices for electric vehicle and 5G base station demand. |
| Raw Material Offtake Agreements | Secures consistent supply of critical SiC and GaN substrates for leading device manufacturers. |
| Heterogeneous Integration R&D | Combines compound semiconductor performance with silicon logic, improving system efficiency and reducing cost. |
| Talent Development Programs | Addresses the specialized talent shortage in compound semiconductor physics and advanced manufacturing processes. |
| Standardization Initiatives | Accelerates market adoption by establishing common testing and reliability frameworks for new GaN and SiC devices. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, providing a robust foundation for market analysis. Primary interviews engaged device engineers, foundry executives, material scientists, and telecom infrastructure planners across key regions. Secondary validation drew from company annual reports, industry association data, government technology roadmaps, and relevant academic research, all triangulated with bottom-up market sizing from component volumes and top-down validation from end-user spending.
The forecast framework anchored the projection horizon to historical reference periods, ensuring continuity and relevance. Segmentation dimensions modeled included product type, application, technology, end-user, and regional demand patterns. Compound annual growth rates were derived based on historical growth trends, projected technological advancements, and the impact of regulatory mandates. Key forecast inputs included 5G/6G rollout schedules, electric vehicle adoption rates, and global energy efficiency mandates.
Revisions become necessary when significant shifts in geopolitical stability or fundamental technological breakthroughs materialize. Forecasts reflect assumptions regarding technological maturation and the evolution of international trade policies. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Chiplets Market
Semiconductors
Wide Bandgap Semiconductors Market
Semiconductors
Gaas Wafer Market
Semiconductors
Smartphone Battery Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Digital Semiconductors Market
Semiconductors
Semiconductor Intellectual Property Market
Semiconductors
Europe Semiconductor Market
Semiconductors
Organic Polymer Electronics Market
Semiconductors
ASEAN Semiconductor Market
Semiconductors
North America Semiconductor Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
China Semiconductor Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
Semiconductor Market