
 Optical Fiber Raw Material Market | 2026-2036
Optical Fiber Raw Material Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Fiber Raw Material Market Analysis
A capital-intensity divergence between integrated preform manufacturers and coating-material suppliers is redrawing competitive boundaries across the value chain. Corning Incorporated leverages captive germanium tetrachloride sourcing and vertical furnace operations to sustain margin control at the preform stage. Sumitomo Electric Industries anchors its position through proprietary vapor-phase axial deposition technology that dominates high-purity silica production for submarine-grade fiber.
Optical fiber raw materials encompass the chemical precursors, glasses, polymers, and dopants used to manufacture waveguide structures capable of transmitting light signals with attenuation below 0.2 dB per kilometer at 1550 nanometers. Preform fabrication consumes ultra-pure silicon tetrachloride and germanium tetrachloride in modified chemical vapor deposition reactors, establishing the refractive index profile that defines signal propagation performance. Silica preforms command the dominant value share given their role in telecommunications backbone networks, while specialty glass formulations for medical device applications capture premium pricing due to stringent biocompatibility requirements. Polymer materials in plastic optical fiber segments compete on cost for short-reach automotive and lighting solutions where bandwidth demands remain modest.
FDA standards govern medical-grade fiber biocompatibility in the United States, while ECHA REACH restrictions on halogenated compounds constrain coating chemistry formulations across Europe. China's MIIT enforces national GB standards for fiber optic performance that foreign suppliers must satisfy for network infrastructure tenders. Stakeholders must monitor evolving PFAS regulations in multiple jurisdictions, as perfluorinated coatings face prospective phase-outs that would force material substitutions across the coating process segment.
Market Dynamics
AI-driven data center buildouts are compressing procurement cycles for ultra-low-loss fiber precursors, forcing preform manufacturers to synchronize capacity expansion with hyperscaler deployment timelines rather than traditional telecom capex cycles.
Growth Catalysts
- Hyperscale data center densification:Cloud operators in Northern Virginia, Frankfurt, and Singapore are deploying multi-fiber push-on cables that consume triple the preform volume per rack unit compared to legacy single-mode infrastructure.
- ECHA REACH purity mandates:Tightening halogen thresholds in coating chemistries are accelerating substitution toward UV-curable acrylates with certified low-chlorine content, expanding addressable premium material markets.
- Submarine cable renewal cycles:Transoceanic systems reaching end-of-design-life are driving replacement demand for titanium-doped silica preforms capable of withstanding 8,000-meter pressure environments.
Market Restraints
- Germanium tetrachloride supply concentration:Four Chinese refiners control 70% of global semiconductor-grade feedstock, exposing preform costs to export quota volatility and geopolitical friction.
- Modified chemical vapor deposition reactor capex:Single MCVD train installations require $15-25 million upfront investment with 36-month commissioning timelines, freezing out mid-tier entrants.
- Plastic optical fiber substitution ceiling:Perfluorinated polymer fibers from Asahi Glass and Chromis Fiberoptics capture automotive lighting and industrial sensing below 100-meter distances, capping silica expansion in short-reach segments.
Strategic Opportunities
- India's BharatNet rural broadband mandate:Government tenders for 600,000 village connections specify G.652.D fiber with domestic content requirements, opening localized preform sourcing partnerships.
- Medical device convergence:Minimally invasive surgical robotics from Intuitive Surgical and Stryker are integrating coherent imaging bundles requiring biocompatible polyimide coatings with FDA 510(k) fast-track pathways.
- China MIIT dual carbon enforcement:Provincial energy intensity quotas are shuttering coal-fired silica smelters, creating acquisition targets for hydrogen-reduction furnace technology holders.
Industry Challenges
- Plasma-enhanced chemical vapor deposition talent scarcity:Less than 200 engineers globally possess operational expertise in PECVD preform scaling, forcing poaching wars between Corning, Sumitomo Electric, and Yangtze Optical Fibre.
- ISO/IEC 60793-1-20 certification bottlenecks:Three testing houses in Germany, Japan, and the US maintain monopoly on multimode bandwidth characterization, creating 14-month backlog for new product qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Fiber Raw Material Market |
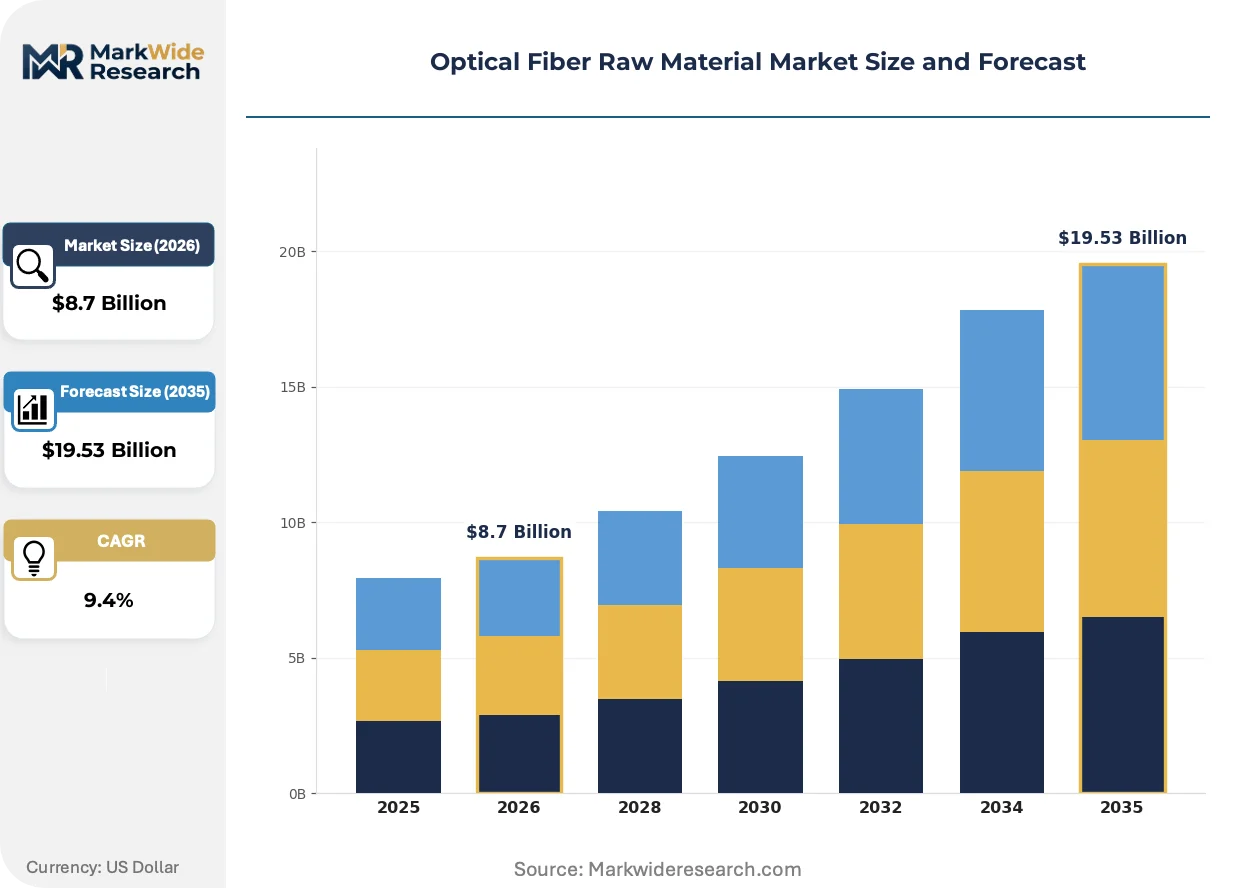
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Silica, Plastic, Specialty Glass, Polymer Production Process: Preform Fabrication, Drawing, Coating, Extruding End User: Telecommunications, Data Centers, IT Infrastructure, Automotive Application: Telecom Networks, Data Transmission, Medical Devices, Lighting Solutions |
| Companies Covered | Sterlite Technologies Limited, CommScope Holding Company, Inc., Corning Incorporated, Sumitomo Electric Industries, Ltd., Hengtong Group, Prysmian Group, Nexans S.A., Fujikura Ltd., Yangtze Optical Fibre and Cable Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Fiber Raw Material Market Emerging Trajectories
Process intensification and regulatory chemistry constraints are converging to redefine competitive advantage away from scale economies toward precision deposition control and circular material flows.
Vapor-phase axial deposition is supplanting outside vapor deposition for submarine-grade preform manufacturing due to its superior radial uniformity and reduced germanium consumption. Cable consortiums deploying trans-Pacific routes are specifying VAD-sourced core rods exclusively. This technology compression is marginalizing OVD-licensed suppliers without in-house VAD retrofit capability.
ECHA F-Gas Regulation phase-down schedules are forcing coating formulators to abandon hydrofluorocarbon blowing agents in cable jacketing compounds. European compounders are accelerating qualification of hydrofluoroolefin and hydrocarbon alternatives with comparable dielectric properties. Medical fiber suppliers face the steepest reformulation burden given biocompatibility revalidation requirements under EU MDR.
Hyperscalers are consolidating optical fiber procurement under direct master service agreements with preform manufacturers, disintermediating traditional cable OEM distributors. Microsoft, Amazon Web Services, and Google Cloud are negotiating five-year take-or-pay contracts with volume commitments exceeding national carrier scale. This channel compression is most advanced in Northern Virginia's Data Center Alley, where three buyers account for 40% of regional fiber consumption.
Optical Fiber Raw Material Market Segmentation
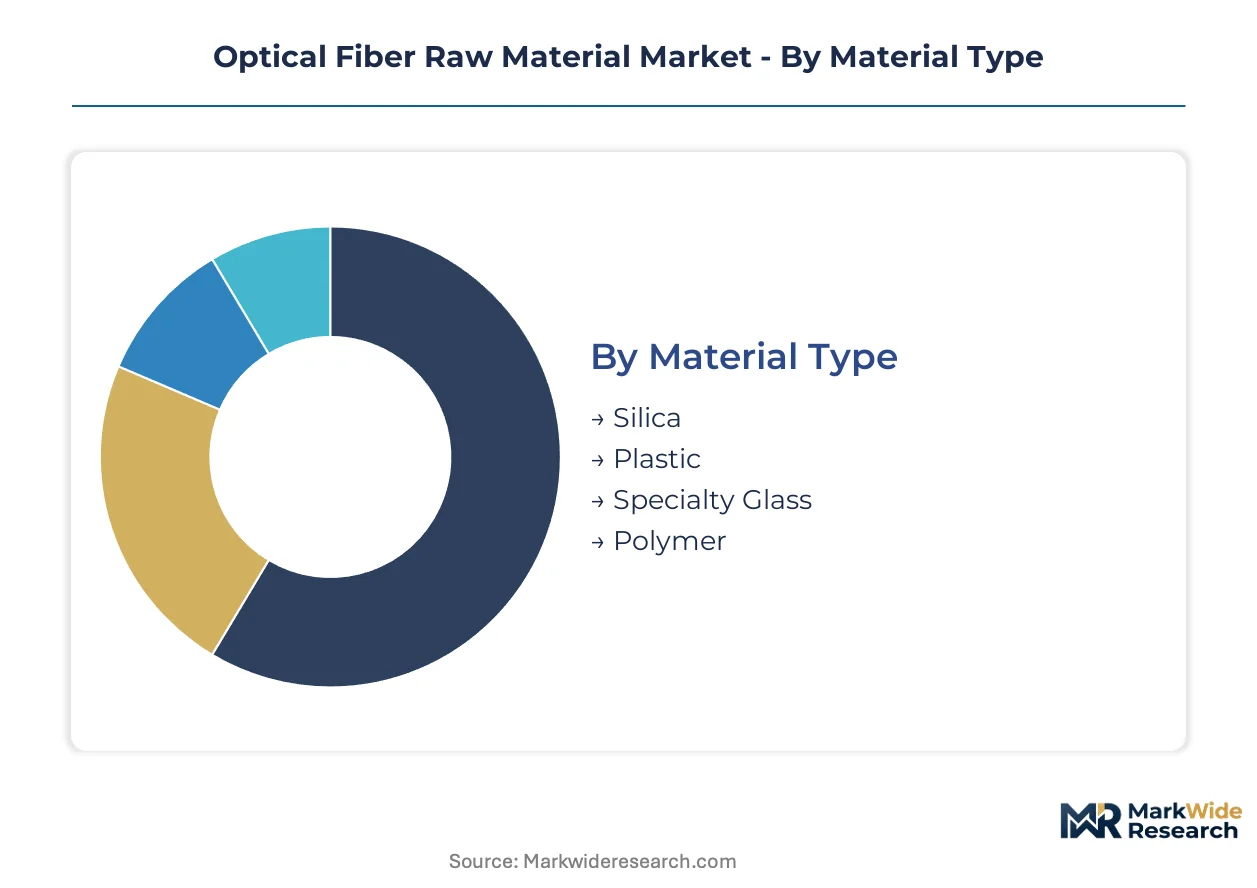
Optical fiber raw material segmentation reveals divergent supply chain architectures across material chemistries and production stages. Each category maps distinct procurement patterns, regulatory exposure, and margin structures that shape supplier positioning.
Material Type:
Silica and specialty glass segments anchor domestic production in China and the United States, while plastic and polymer categories rely heavily on export-oriented supply chains from Japan and Germany.
- Silica:Ultra-pure silicon dioxide derived from vapor-phase axial deposition and modified chemical vapor deposition processes forms the waveguide core and cladding structures. Demand concentrates in submarine cable manufacturing, where titanium-doped formulations withstand 8,000-meter pressure environments in trans-Pacific routes.
- Plastic:Perfluorinated polymers from Asahi Glass and Chromis Fiberoptics serve automotive lighting and industrial sensing below 100-meter distances. Export-led supply chains from Japanese compounders face ECHA F-Gas Regulation phase-down pressures forcing hydrofluoroolefin substitution.
- Specialty Glass:Fluorine-doped and rare-earth formulations enable high-power laser delivery and radiation-hardened sensing. German and US suppliers dominate medical device certification pathways under FDA 510(k) and EU MDR frameworks.
- Polymer:UV-curable acrylates and polyimides form buffer coatings and jacketing layers. REACH-compliant low-chlorine formulations command premium positioning in European telecommunications infrastructure.
Silica holds the largest share; momentum sits with specialty glass as medical device convergence accelerates.
Production Process:
Preform fabrication and drawing operations absorb the majority of capital intensity, while coating and extruding stages concentrate cost optimization pressures from compound suppliers.
- Preform Fabrication:Modified chemical vapor deposition and vapor-phase axial deposition reactors establish refractive index profiles through precise germanium tetrachloride doping. Single MCVD train installations require $15-25 million upfront investment with 36-month commissioning timelines, freezing out mid-tier entrants.
- Drawing:Fiber pulling from preform rods at 1,000-2,000 meters per minute converts glass structures to operational waveguides. Tower height and tension control differentiate quality tiers for submarine versus terrestrial applications.
- Coating:Dual-layer UV-curable acrylate application protects drawn fiber from microbending and moisture ingress. ECHA REACH halogen thresholds are accelerating substitution toward certified low-chlorine content formulations.
- Extruding:Cable jacketing through polyethylene or flame-retardant compounds completes mechanical and environmental protection. Hydrocarbon and hydrofluoroolefin blowing agents are displacing hydrofluorocarbons under F-Gas Regulation enforcement.
Preform fabrication commands the highest value capture; coating is expanding most quickly as regulatory chemistry constraints deepen.
End User:
Telecommunications and data center procurement now exceeds traditional carrier scale, while automotive and IT infrastructure segments present divergent certification and volume requirements.
- Telecommunications:National backbone and access network deployments specify G.652.D and G.654.E fiber grades. India's BharatNet rural broadband mandate for 600,000 village connections is opening localized preform sourcing partnerships with domestic content requirements.
- Data Centers:Hyperscale operators in Northern Virginia, Frankfurt, and Singapore are deploying multi-fiber push-on cables consuming triple the preform volume per rack unit compared to legacy infrastructure. Microsoft, Amazon Web Services, and Google Cloud are negotiating five-year take-or-pay contracts directly with preform manufacturers.
- IT Infrastructure:Enterprise and colocation facilities demand standardized single-mode and multimode specifications. ISO/IEC 60793-1-20 certification bottlenecks at three testing houses in Germany, Japan, and the US create 14-month qualification backlogs for new product entries.
- Automotive:In-vehicle optical networks for advanced driver-assistance systems and infotainment backbone specify plastic optical fiber for cost-sensitive short-reach applications. Perfluorinated polymer fibers face substitution ceilings from silica in higher-bandwidth domains.
Telecommunications retains volume leadership; data centers are gaining share fastest through hyperscaler procurement consolidation.
Application:
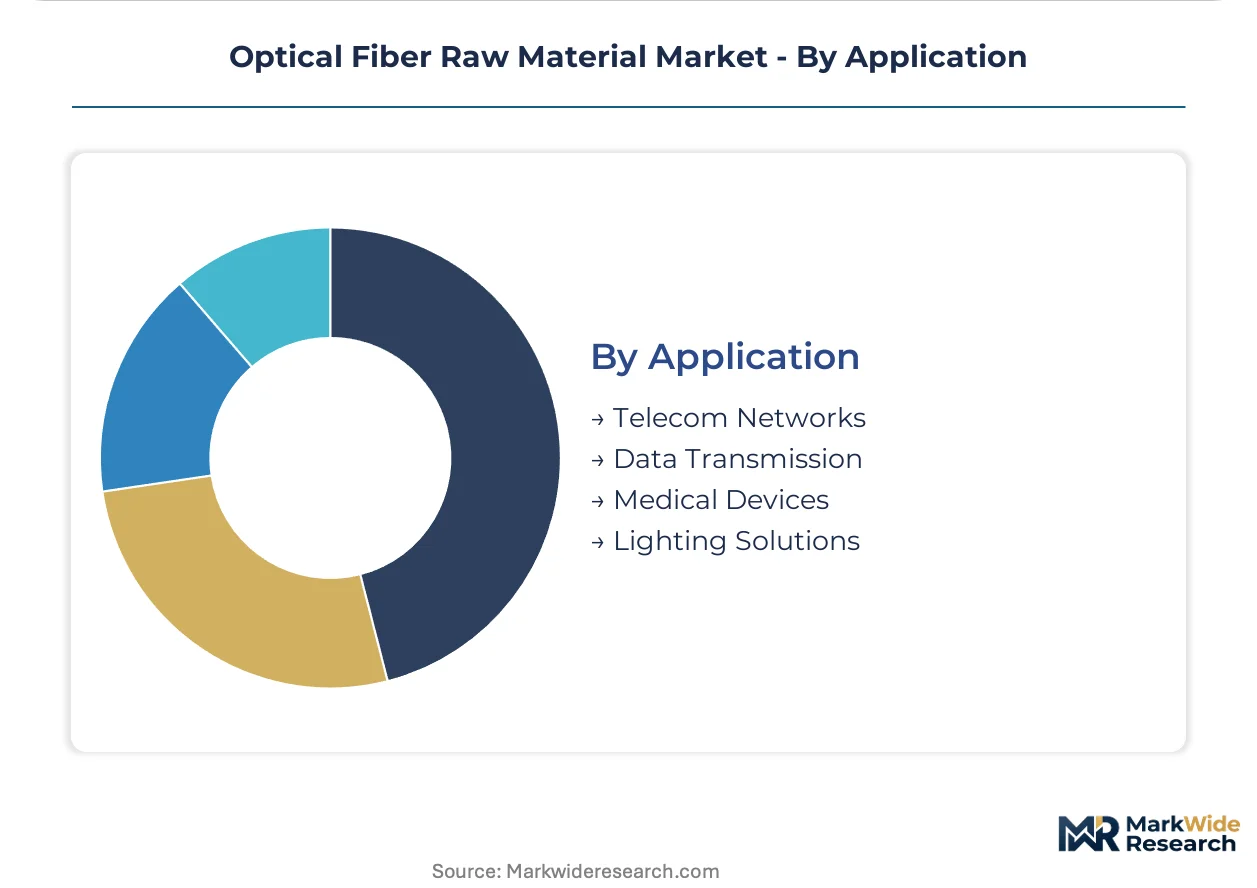
Telecom networks and data transmission applications dominate volume consumption, while medical devices and lighting solutions capture premium pricing through specialized certification and performance requirements.
- Telecom Networks:Submarine and terrestrial long-haul systems demand ultra-low-loss single-mode fiber with attenuation below 0.2 dB per kilometer at 1550 nanometers. Transoceanic cable renewal cycles are driving replacement demand for pressure-resistant preform formulations.
- Data Transmission:Inter-data center and intra-facility connectivity requires high-fiber-count cables with standardized connector interfaces. MPO-16 and MPO-32 configurations are displacing legacy duplex fiber in cloud computing density buildouts.
- Medical Devices:Minimally invasive surgical robotics from Intuitive Surgical and Stryker integrate coherent imaging bundles requiring biocompatible polyimide coatings. FDA 510(k) and EU MDR fast-track pathways differentiate qualified suppliers.
- Lighting Solutions:Plastic optical fiber serves decorative and functional illumination in automotive, architectural, and industrial settings. Bandwidth limitations below 100 meters constrain silica substitution in this cost-driven segment.
Telecom networks hold the largest share; medical devices show the steepest expansion trajectory as surgical robotics adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward Chinese refiners controlling germanium tetrachloride feedstock, while European compounders absorb reformulation costs under REACH halogen mandates. This asymmetry reshapes procurement geography for preform manufacturers.
China
MIIT dual carbon enforcement shutters coal-fired silica smelters in Hebei and Shandong provinces. Yangtze Optical Fibre and Hengtong Group anchor domestic supply chains serving hyperscaler data center buildouts in Beijing and Shanghai. Provincial energy intensity quotas create acquisition targets for hydrogen-reduction furnace technology holders.
United States
FDA 510(k) pathways govern medical-grade fiber biocompatibility for surgical robotics integration. Northern Virginia's Data Center Alley concentrates 40% of regional fiber consumption through direct Microsoft, Amazon Web Services, and Google Cloud procurement. EPA oversight of perfluorinated compounds pressures coating chemistry substitutions.
Germany
ECHA REACH restrictions on halogenated compounds constrain coating formulations for telecommunications infrastructure. Three testing houses maintain monopoly on multimode bandwidth characterization, creating qualification bottlenecks for new product entries. Rhine-Ruhr industrial corridor hosts compounders accelerating hydrofluoroolefin alternatives under F-Gas Regulation phase-down schedules.
India
BharatNet rural broadband mandate specifies 600,000 village connections with domestic content requirements for G.652.D fiber. TRAI spectrum allocation supports fiber-to-the-home expansion in Maharashtra and Karnataka. Localized preform sourcing partnerships open for foreign suppliers meeting BIS certification thresholds.
Japan
METI industrial standards govern vapor-phase axial deposition technology for submarine-grade preform manufacturing. Kanto region maintains concentration of specialty glass formulators serving medical device convergence. JIS certification requirements differentiate suppliers for coherent imaging bundles in minimally invasive surgical systems.
Optical Fiber Raw Material Market Vendor Landscape
Concentration sits with integrated preform manufacturers controlling captive germanium tetrachloride sourcing and vertical furnace operations. Three structural tiers have emerged: multinational conglomerates with full value chain coverage, regional specialists dominating single geographies, and technology licensors without in-house deposition capability. Competitive moves center on strategic partnerships with hyperscaler data center operators and capacity expansion synchronized to submarine cable renewal cycles.
Within the integrated multinational tier, Corning Incorporated and Sumitomo Electric Industries exemplify archetypes combining proprietary deposition technology with captive chemical feedstock control. Yangtze Optical Fibre and Cable Co., Ltd. occupies a position representing state-anchored domestic supply chain consolidation. Hengtong Group sits within the regional specialist category leveraging proximity to Chinese hyperscaler demand clusters.
| Leading Market Players |
|---|
| Sterlite Technologies Limited |
| CommScope Holding Company, Inc. |
| Corning Incorporated |
| Sumitomo Electric Industries, Ltd. |
| Hengtong Group |
| Prysmian Group |
| Nexans S.A. |
| Fujikura Ltd. |
| Yangtze Optical Fibre and Cable Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
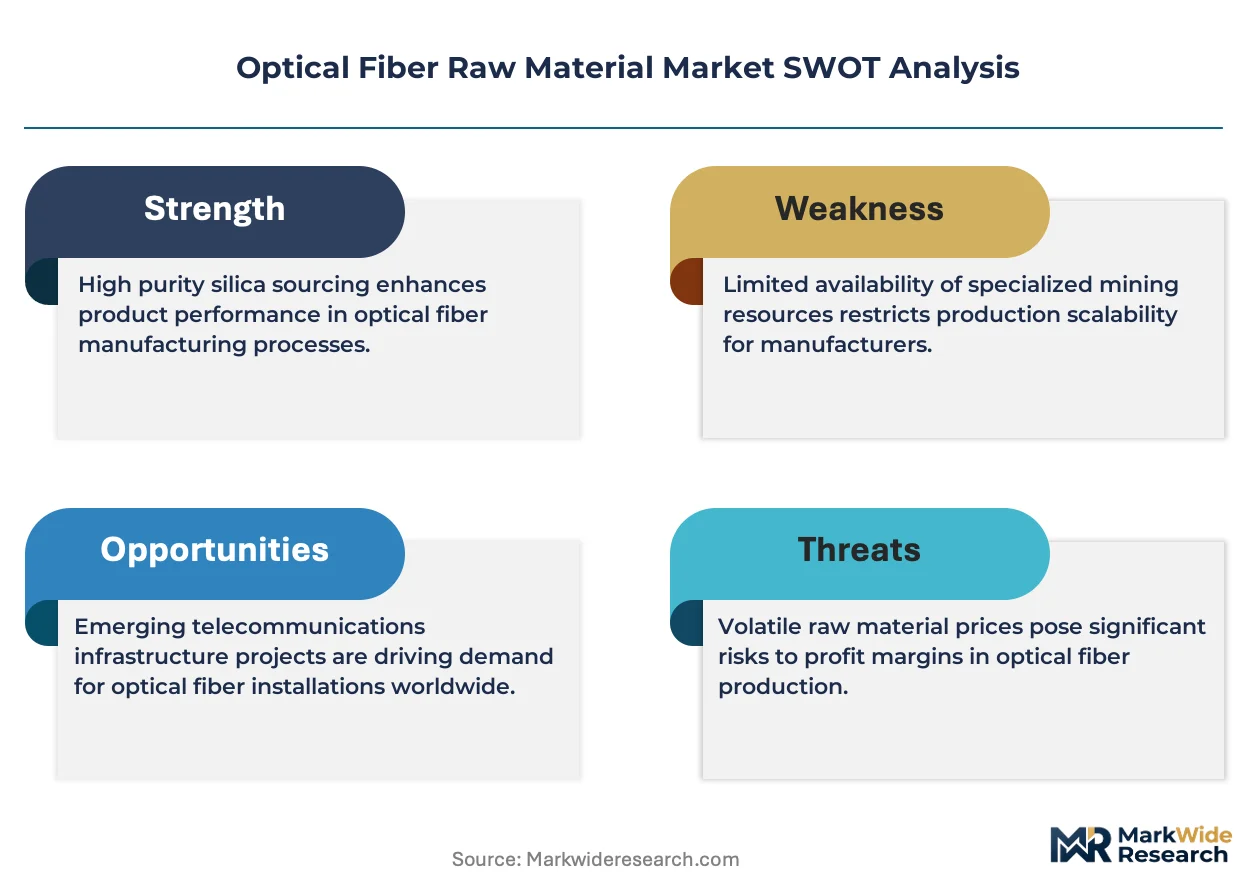
UV-curable acrylate substitution for halogenated coatings under ECHA REACH mandates is redrawing procurement geography toward Rhine-Ruhr compounders while compressing margin structures for Asian coating suppliers locked into legacy chemistries. This input transition simultaneously elevates European formulators to premium positioning and forces price realignment across preform-cable value chains tethered to REACH-compliant material sourcing.
Pricing Analysis
The customization-premium spread separates submarine-grade titanium-doped silica preforms from standard G.652.D terrestrial fiber, with pressure-resistant formulations commanding substantial uplifts over access-network grades. Price differentiation hinges on certification tier—ISO/IEC 60793-1-20 bandwidth characterization for multimode versus uncertified short-reach plastic fiber—and volume scale, where hyperscaler take-or-pay contracts compress unit economics below carrier procurement levels. Cost compression in standard-grade silica preforms is intensifying because Chinese hydrogen-reduction furnace technology holders are absorbing shuttered coal-fired capacity at distressed asset valuations. Data center operators exhibit lowest price sensitivity given latency-driven performance requirements, while BharatNet rural broadband tenders in India enforce aggressive domestic content cost floors.
Supply Chain Analysis
Germanium tetrachloride refining concentration in Chinese state-controlled refiners creates a single-source vulnerability for preform manufacturers lacking captive tetrachloride sourcing or long-term offtake hedges. Geographic supply concentration centers on China for semiconductor-grade feedstock, the United States for medical-device-certified specialty glass, and Japan for vapor-phase axial deposition reactor components. Raw material dependencies encompass silicon tetrachloride for MCVD core deposition, titanium tetrachloride for submarine-grade dopant formulations, and perfluorinated polymers facing ECHA F-Gas Regulation phase-down restrictions. Distribution runs through direct master service agreements with hyperscaler data center operators, disintermediating traditional cable OEM distributor networks in Northern Virginia, Frankfurt, and Singapore clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscaler procurement consolidation is fragmenting legacy carrier-centric supply structures, creating specialized niches for medical-grade biocompatible coating specialists and submarine-grade preform technology licensors outside integrated multinational hierarchies.
For Market Incumbents: Fortify captive germanium tetrachloride sourcing through backward integration into Chinese refinery partnerships or long-term quota-lock arrangements, while accelerating VAD reactor capacity expansion synchronized to trans-Pacific cable renewal cycles. Threats from plasma-enhanced chemical vapor deposition talent scarcity—less than 200 qualified engineers globally—require preemptive employment bonds and knowledge-capture protocols to prevent poaching by Yangtze Optical Fibre and Sumitomo Electric. For New Entrants and Emerging Players: Lead with hydrogen-reduction furnace technology acquisition targets in Hebei and Shandong provinces, where MIIT dual carbon enforcement has shuttered coal-fired silica smelters at distressed valuations. The most penetrable white space sits with India BharatNet localized preform sourcing partnerships, leveraging BIS certification pathways and domestic content requirements to bypass incumbent supply agreements. A go-to-market angle anchored to G.652.D fiber qualification for 600,000 village connections offers volume scale without hyperscaler procurement consolidation pressures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed coating compounders in the Rhine-Ruhr corridor holding REACH-compliant low-chlorine acrylate formulations and hydrofluoroolefin substitution patents under ECHA F-Gas enforcement. Long-term viability across the analysis window hinges on positioning upstream of hyperscaler direct procurement consolidation, where five-year take-or-pay contracts with Microsoft, Amazon Web Services, and Google Cloud provide revenue visibility exceeding national carrier cycles. The signal to watch is submarine cable consortium specification shifts toward exclusive VAD-sourced core rods, which would strand OVD-licensed suppliers without retrofit capability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Germanium Tetrachloride | Captive feedstock sourcing insulates Corning and Sumitomo Electric from Chinese export quota volatility. |
| VAD Reactor Capacity Expansion | Submarine cable consortiums are specifying VAD-sourced core rods exclusively for trans-Pacific routes. |
| REACH-Compliant Coating Reformulation | Rhine-Ruhr compounders with hydrofluoroolefin alternatives capture premium positioning under ECHA enforcement. |
| Hyperscaler Direct Procurement Agreement | Microsoft, Amazon Web Services, and Google Cloud contracts disintermediate traditional cable OEM distributors. |
| Hydrogen-Reduction Furnace Technology Acquisition | MIIT dual carbon shutdowns in Hebei and Shandong create distressed asset opportunities for technology holders. |
Methodological Framework
Initial hypotheses were tested against primary input from preform fabrication plant managers, hyperscaler data center procurement officers, coating compounder technical R&D directors, and submarine cable consortium engineering leads, then refined through secondary validation against SEC 10-K filings, MIIT GB standard documentation, ECHA REACH restriction updates, and hyperscaler capex disclosure transcripts. Bottom-up fiber demand modeling triangulated against top-down preform capacity assessments across China, the United States, Japan, and Germany.
Variance decomposition across the projection horizon isolates volume drivers—hyperscale data center densification, submarine cable renewal cycles, BharatNet rural broadband deployment—from price dynamics shaped by germanium tetrachloride supply concentration and REACH-compliant coating reformulation costs. Segmentation dimensions encompass material type, production process, end user, and application, with CAGRs derived from fiber-kilometer demand elasticity to data center rack-unit expansion and medical device surgical robotics adoption curves. Industry-specific forecast inputs include MCVD train commissioning timelines and ISO/IEC 60793-1-20 certification backlog durations at German, Japanese, and US testing houses.
The analysis sits within stated boundaries; outcomes outside sustained hyperscaler capex commitment, ECHA F-Gas Regulation enforcement continuity, or MIIT dual carbon quota stringency would require recalibration. Forecasts reflect documented assumptions regarding germanium tetrachloride supply availability, REACH halogen threshold implementation schedules, and submarine cable consortium technology specifications. Practitioners should keep alternative scenarios live as geopolitical friction around critical mineral export controls and PFAS coating phase-out timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Excimer Laser Market
Optics
Middle East and Africa Tunable Laser Market
Optics
Smartphone Lenses Market
Optics
Fiber Optic Connectivity Market
Optics
Solid State Lasers Market
Optics
Germanium Lens Market
Optics
Laser Transmitter Market
Optics
AR and VR Lens Market
Optics
Photonics Sensor Market
Optics
Fiber-Optic Couplers Market
Optics
Camera Module Lens Market
Optics
Smart Glass Market
Optics
India Laser Market
Optics
Fiber Optic Development Tools Market
Optics
Beam Expanders Market
Optics
Europe Smart Glass Market