
 Anti Glare Film Market | 2026-2036
Anti Glare Film Market Size, Share, and Industry Trends Forecast 2026-2036
Anti Glare Film Market Intelligence
Expertise in optical coating chemistry and polymer science is bifurcating the competitive landscape. 3M Company leverages its extensive R&D in adhesives and optical sciences to maintain a premium position in specialized applications. Mitsubishi Chemical Corporation specializes in high-performance polyester and polycarbonate substrates, supplying key display manufacturers. Nitto Denko Corporation dominates the supply of films for high-end consumer electronics, including smartphones and tablets, through its advanced coating technologies.
Anti glare film is a specialized polymer sheet, typically made from polyester or polycarbonate, designed to reduce specular reflection on electronic displays and other surfaces. Its effectiveness is achieved through microscopic surface texturing or diffusion coatings that scatter ambient light, measured by parameters like gloss and haze value. Within applications, consumer electronics remains the largest segment, but automotive displays represent the fastest-growing area. Polyester-based films lead product types due to their favorable cost-performance balance, while advanced nano coating technologies command higher margins.
Product quality and safety are governed by a matrix of international and national standards, including ISO specifications for optical properties. Material composition is subject to chemical regulations like the EU's REACH framework, while films used in US medical devices must meet specific FDA requirements. Environmental directives such as RoHS also impact material selection for manufacturers globally. Navigating the trade-offs between optical performance, durability, and compliance with evolving substance restrictions will define future product development strategies.
Market Dynamics
The central force shaping the anti glare film market is the technical and commercial divergence between high-volume, cost-sensitive applications in consumer electronics and high-performance, specialized films for automotive and medical displays, creating distinct paths for innovation and competition.
Growth Catalysts
- Automotive Cockpit Evolution:The automotive industry's shift towards digital cockpits with larger, integrated touchscreens and head-up displays necessitates advanced anti glare films to ensure driver safety and readability under varied lighting conditions.
- Display Manufacturing Concentration:The geographic consolidation of display panel production in South Korea, Taiwan, and China creates a concentrated demand hub, simplifying supply chains for film producers targeting the largest electronics manufacturers.
- PET Substrate Innovation:Advances in polyester (PET) film coating and texturing technology enable the production of thinner, more durable, and optically superior films, meeting the stringent design requirements of modern smartphones, tablets, and laptops.
Market Restraints
- Petrochemical Price Volatility:The cost of core raw materials like polyester and polycarbonate substrates is directly linked to volatile petrochemical feedstock prices, creating margin pressure and pricing instability for film manufacturers.
- Performance Trade-offs:A fundamental technical constraint is the trade-off between haze, which provides the anti-glare effect, and display clarity. Achieving high haze values without sacrificing image resolution or brightness remains a significant challenge.
- Chemical Regulation Compliance:Adherence to stringent chemical regulations, such as the EU's REACH framework, restricts the use of certain additives and coating materials, increasing R&D costs and lengthening product development timelines.
Strategic Opportunities
- Medical Device Displays:There is a significant opportunity in films for medical monitors and diagnostic equipment, where high optical performance and durability are critical and subject to specific regulatory clearances like those from the US FDA.
- Multi-Functional Film Development:Integrating anti-glare properties with other functionalities, such as anti-microbial, anti-fingerprint, or privacy features, creates value-added products that can command premium pricing in multiple end-use markets.
- Emerging Production Hubs:As electronics manufacturing diversifies into Southeast Asia and India, establishing local finishing or converting operations presents an opportunity to capture new demand and mitigate geopolitical supply chain risks.
Industry Challenges
- Complex Compliance Navigation:Manufacturers face the operational challenge of aligning products with a fragmented landscape of international standards, including ISO specifications for optical properties and RoHS directives on hazardous substances.
- Capital-Intensive Production:Achieving the microscopic surface textures required for effective anti-glare performance necessitates significant capital investment in precision coating lines and cleanroom environments, creating a high barrier to entry.
- Intellectual Property Protection:Safeguarding proprietary nano-coating formulations and surface texturing processes is a persistent challenge, particularly in jurisdictions with inconsistent enforcement of intellectual property rights.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti Glare Film Market |
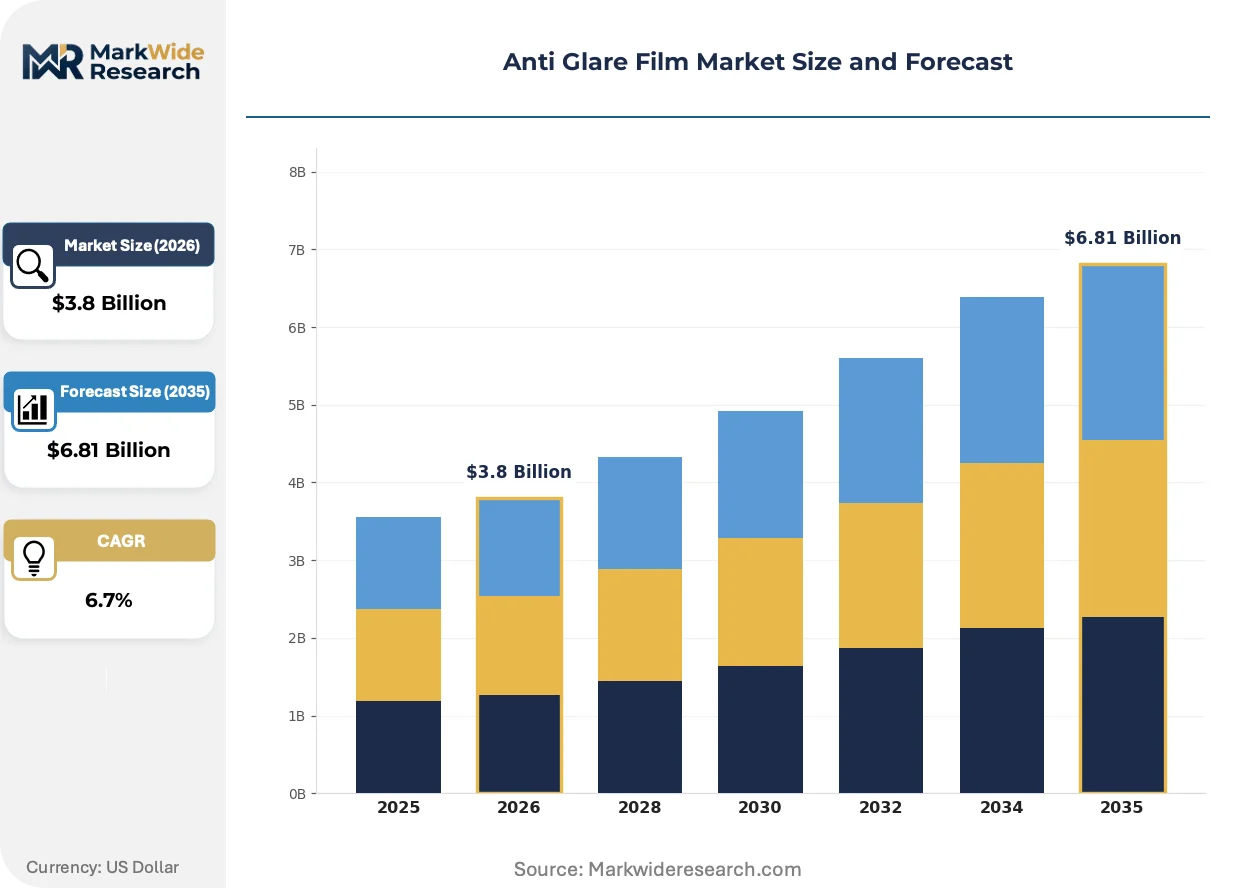
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Vinyl, Polycarbonate, Acrylic Application: Consumer Electronics, Automotive, Commercial, Healthcare Technology: Optical Coating, PET Coating, LCD Technologies, Nano Coating End User: Retail, Manufacturing, Education, Hospitality |
| Companies Covered | 3M Company, Honeywell International Inc., EssilorLuxottica, Mitsubishi Chemical Corporation, Nitto Denko Corporation, Carl Zeiss AG, PPG Industries Inc., Covestro AG, Toppan Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti Glare Film Market Strategic Shifts & Innovations
Material science advancements are enabling a new generation of multi-functional films that move beyond simple glare reduction. This evolution is driven by end-market demands for integrated performance, durability, and enhanced user experience in increasingly complex electronic displays.
Hybrid optical films combine anti-glare surface texturing with anti-reflection and privacy-filtering layers. Automotive and premium consumer electronics segments are the primary adopters of these sophisticated, multi-layer constructions. This technology is decomposing the traditional market for single-function films into a more complex, application-specific hierarchy where value is tied to integrated performance.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a notable regulatory development impacting the industry. This mandate requires large companies and their suppliers to provide detailed disclosures on environmental and social impacts across their value chains. Film manufacturers supplying European OEMs now face increased pressure to document material sourcing and chemical usage, accelerating investment in lifecycle assessment capabilities.
A significant behavioral shift is occurring as major display panel fabricators move from transactional component purchasing to collaborative co-development. Instead of selecting off-the-shelf films, these customers now partner with film specialists early in the design phase to create custom-engineered optical solutions. This trend is most visible in South Korea and Taiwan, where it provides a critical competitive edge in display performance.
Anti Glare Film Market Segmentation
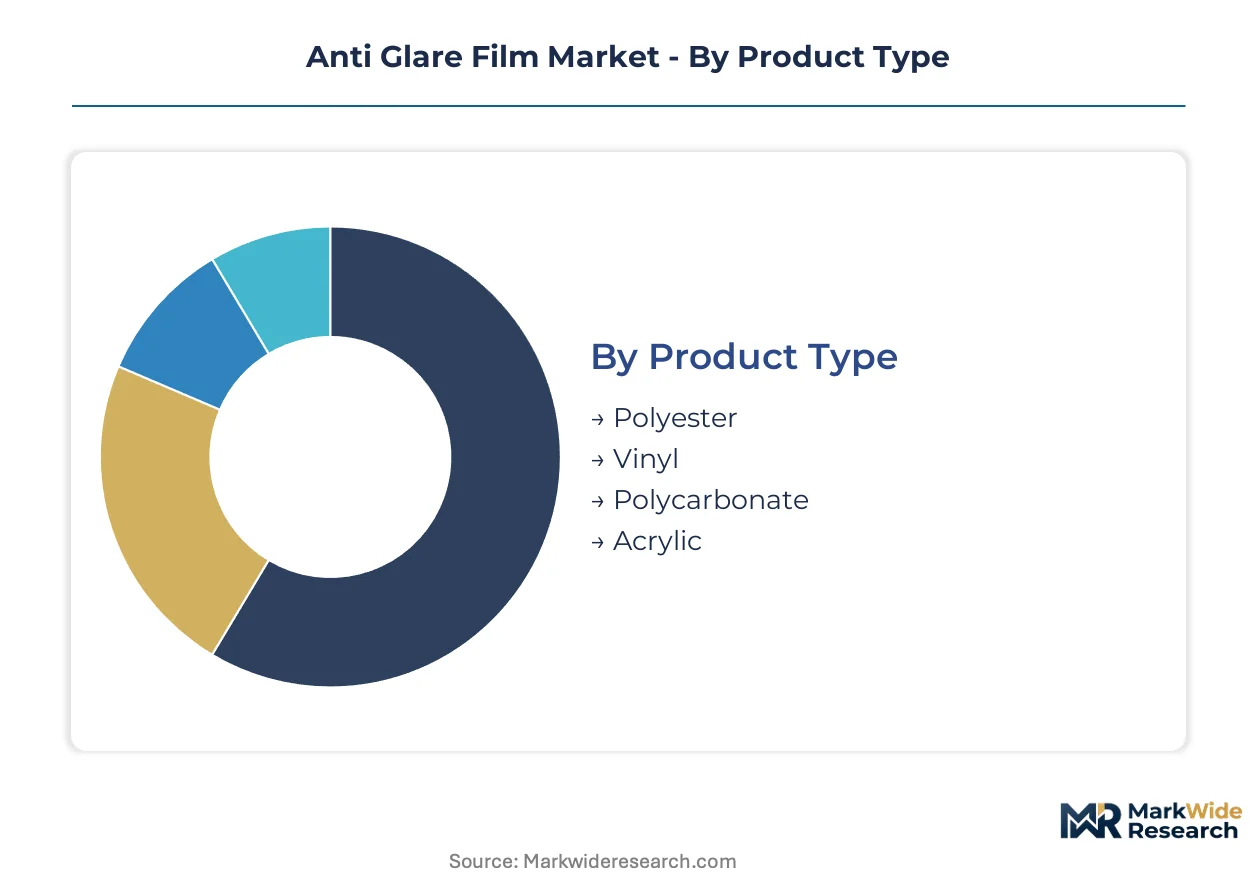
The anti glare film market segments reflect the diverse technical requirements and regulatory frameworks across various end-use applications. Understanding these distinct segments is critical for manufacturers to align product development with specific performance mandates and compliance standards. Each category presents unique material science challenges and market dynamics.
Product Type:
Regulatory differentiation significantly influences material selection and formulation within anti glare film product types. Compliance with chemical substance restrictions, such as the EU's REACH framework, dictates which polymers and additives are permissible for specific markets. This regulatory landscape drives innovation towards safer, more sustainable material compositions.
- Polyester:These films, primarily PET-based, offer a favorable cost-performance balance and dominate the market due to their mechanical strength and optical clarity. Demand concentrates in consumer electronics manufacturing hubs across South Korea and Taiwan, where high-volume display panel production occurs.
- Polycarbonate:Polycarbonate films provide superior impact resistance and thermal stability, making them suitable for demanding environments like automotive dashboards and industrial displays. The automotive sector, particularly in Germany and Japan, drives demand for these high-performance substrates.
- Vinyl:Vinyl anti glare films typically serve less stringent applications where flexibility and ease of application are prioritized over advanced optical properties. These are often used in signage and protective overlays.
- Acrylic:Acrylic films offer high transparency and scratch resistance, finding applications in point-of-sale displays and certain medical devices. Their rigidity makes them suitable for flat panel protection.
Established volume favors Polyester films; emerging adoption favors Polycarbonate in specialized, high-durability applications.
Application:
Cost tiering dictates the performance specifications and material choices across different anti glare film applications. High-volume consumer electronics demand cost-effective solutions, while specialized medical or automotive displays require premium-priced, high-performance films. This differentiation impacts R&D investment and manufacturing processes.
- Consumer Electronics:This segment represents the largest application area, encompassing smartphones, tablets, and laptops, where anti glare films enhance readability and user experience. The concentration of display panel production in China and South Korea generates significant volume demand.
- Automotive:Anti glare films in automotive cockpits and head-up displays ensure driver safety and clear visibility under varying light conditions. This application represents the fastest-growing trajectory due to the shift towards larger, integrated digital screens in vehicles across Europe and North America.
- Commercial:Commercial applications include digital signage, point-of-information kiosks, and industrial control panels where display readability in public or industrial settings is essential. Durability and consistent performance are key requirements.
- Healthcare:Films for medical monitors and diagnostic equipment require high optical clarity and often integrate anti-microbial properties for sterile environments. US FDA and European EMA regulations influence material selection for these critical devices.
The largest volume resides in Consumer Electronics; Automotive applications are climbing the fastest.
Technology:
Application-specific requirements drive the development and adoption of anti glare film technologies. For instance, high-end consumer electronics demand advanced nano coating for superior optical performance, while basic displays might utilize simpler optical coating methods. This tailors technological innovation to market needs.
- Nano Coating:Advanced nano coating technologies create microscopic surface textures that effectively scatter ambient light, offering superior anti-glare performance with minimal impact on display clarity. These command higher margins in premium consumer electronics and specialized automotive displays.
- PET Coating:Polyester (PET) coating technology involves applying anti-glare layers onto PET film substrates, enabling thinner, more durable films for modern portable devices. Innovation in this area supports the stringent design requirements of smartphones and tablets.
- Optical Coating:Traditional optical coating techniques apply a thin layer of material to the film surface to reduce reflection, often balancing cost with acceptable anti-glare properties. This technology finds broad use in general display applications.
- LCD Technologies:Anti glare films specifically designed for Liquid Crystal Display (LCD) panels optimize light transmission and color reproduction while mitigating glare. These are integral to the performance of various display types.
Value creation is highest in Nano Coating; PET Coating continues to refine its performance capabilities.
End User:
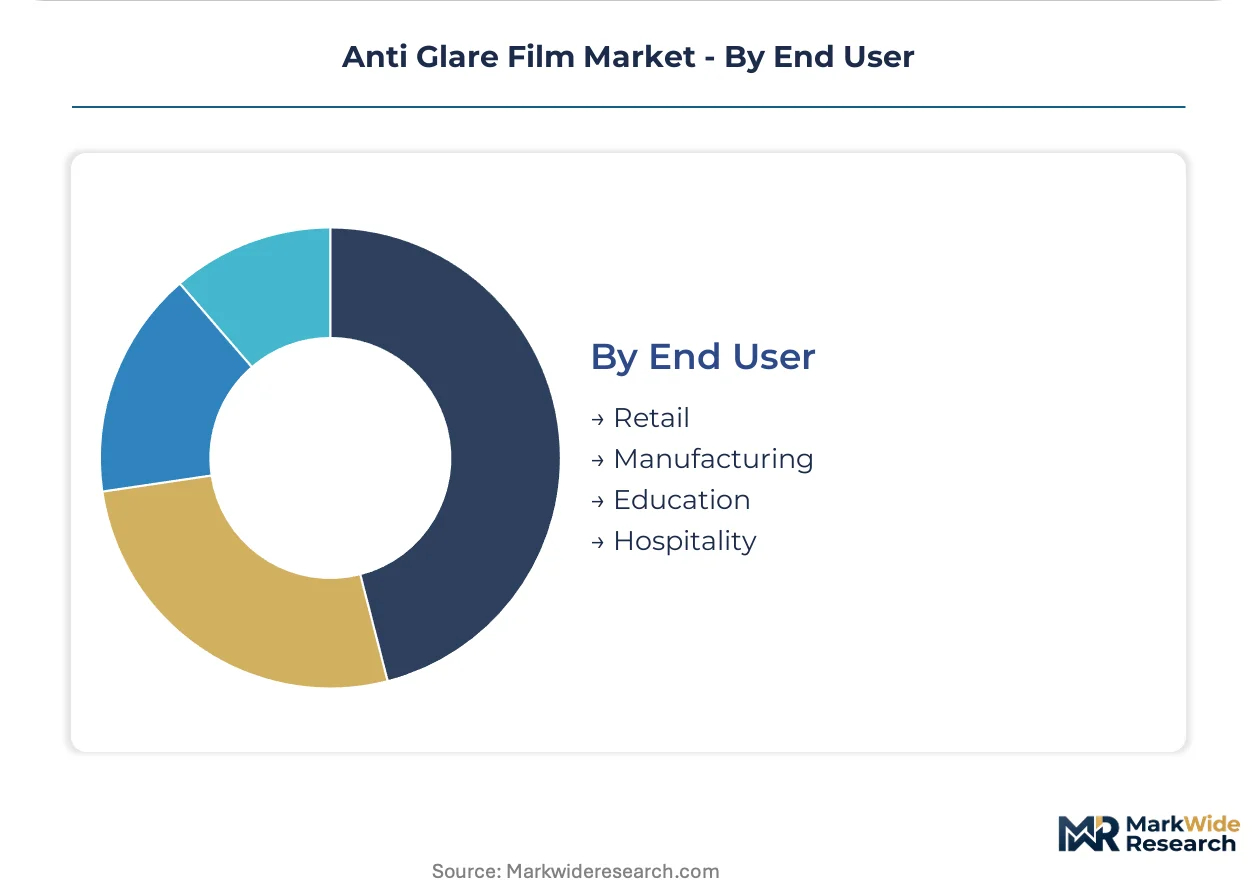
Volume requirements significantly differentiate anti glare film demand across end-user segments. Large-scale manufacturing operations require bulk supply for integrated display components, whereas retail and hospitality sectors might demand smaller batches for specific display installations. This impacts procurement and supply chain strategies.
- Manufacturing:This end-user segment includes display panel fabricators and electronics manufacturers that integrate anti glare films directly into their products. The concentration of manufacturing in China, South Korea, and Taiwan drives substantial demand for raw film materials.
- Retail:Anti glare films are deployed in retail environments for point-of-sale systems, digital price tags, and promotional displays to enhance visibility for customers. Durability and aesthetic integration are important considerations for these applications.
- Education:Educational institutions utilize anti glare films on interactive whiteboards, classroom tablets, and computer monitors to reduce eye strain for students and educators. Cost-effectiveness and long-term durability are key purchasing factors.
- Hospitality:The hospitality sector employs anti glare films on in-room televisions, digital directories, and conference room displays to improve guest experience and readability. Ease of cleaning and anti-fingerprint properties are often valued.
The largest demand trajectory stems from Manufacturing; Retail applications show consistent, steady adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The anti glare film market exhibits varied consumption patterns across key geographies, driven by distinct end-use market concentrations. While display manufacturing hubs prioritize cost-effective, high-volume films, regions with advanced automotive industries demand specialized, high-performance solutions. This differential shapes regional investment in material science and production capabilities.
South Korea
South Korea's robust display panel industry drives substantial demand for anti glare films, particularly for high-end consumer electronics. The country's MFDS regulations influence material selection for medical display applications, ensuring device safety and performance. Seoul and Gyeonggi Province house numerous display fabricators and R&D centers, fostering innovation in advanced film technologies.
China
China's extensive electronics manufacturing ecosystem creates immense volume demand for anti glare films across diverse applications. GB standards and MIIT policies guide product quality and industrial development within the domestic market. The Yangtze River Delta and Pearl River Delta regions are critical hubs for display assembly and film integration, attracting significant investment.
Germany
Germany's premium automotive sector requires advanced anti glare films for digital cockpits and head-up displays, prioritizing optical clarity and durability. Compliance with EU's REACH framework and KBA automotive standards is essential for market entry. Bavarian and Baden-Württemberg regions, with their strong automotive OEM presence, are key demand centers for specialized film solutions.
United States
The United States market sees demand from both its advanced medical device industry and growing automotive display integration. FDA requirements mandate specific material compositions and performance criteria for films used in medical monitors. Silicon Valley and the Detroit metropolitan area represent significant innovation and application hubs for anti glare film technologies.
Taiwan
Taiwan's position as a global leader in display panel production and semiconductor manufacturing generates consistent demand for anti glare films. Local industry standards often align with global ISO specifications for optical properties and material performance. Hsinchu Science Park and Southern Taiwan Science Park are major clusters for display component manufacturing and film integration.
Anti Glare Film Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the anti glare film market. This tiered landscape reflects varying capabilities from fundamental material science to advanced coating application. Strategic archetypes include diversified chemical giants, specialized optical film manufacturers, and niche solution providers. Dominant competitive moves involve continuous R&D investment in nano coating technologies and strategic partnerships with display panel fabricators.
Among the established players, 3M Company exemplifies a diversified technology conglomerate leveraging extensive R&D in optical sciences for specialized applications. Mitsubishi Chemical Corporation, a major chemical producer, occupies a strong position in high-performance polyester and polycarbonate substrates. Nitto Denko Corporation represents a specialist in advanced coating technologies, anchoring the supply of films for high-end consumer electronics.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| EssilorLuxottica |
| Mitsubishi Chemical Corporation |
| Nitto Denko Corporation |
| Carl Zeiss AG |
| PPG Industries Inc. |
| Covestro AG |
| Toppan Inc. |
| Others |
Cost & Logistics Intelligence
Scale economies in advanced coating lines shape both supply concentration and price floors for high-performance anti-glare films. This dynamic forces cost-sensitive applications to leverage high-volume production centers.
Pricing Analysis
Long-term offtake agreements dominate pricing for high-volume anti-glare film contracts with major display manufacturers. Price differentiation stems from optical performance specifications and customization levels for specialized applications. Pricing pressure stems from volatile petrochemical feedstock costs, particularly for PET and polycarbonate substrates. Consumer electronics segments exhibit the highest price sensitivity, while automotive and medical displays accept premium pricing.
Supply Chain Analysis
The concentration of display panel production in South Korea, Taiwan, and China creates a geographic chokepoint for anti-glare film supply. Supply relies heavily on polyester (PET) and polycarbonate substrates, alongside specialized nano-coating chemicals. A structural risk involves the intellectual property protection of advanced coating formulations, especially across diverse jurisdictions. Distribution runs primarily through direct sales channels to large-scale electronics and display manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
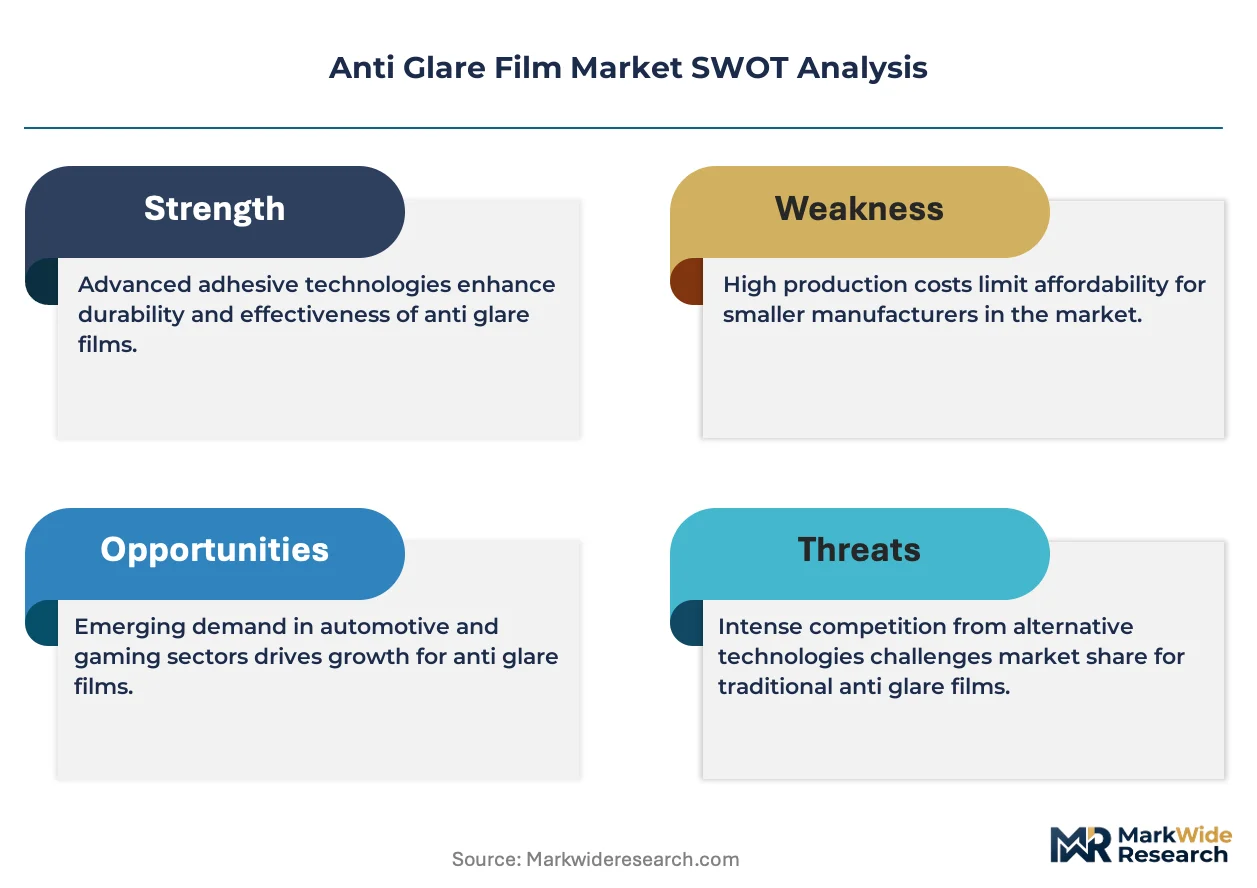
This market demands a substitution defense as integrated display technologies, like in-glass anti-glare solutions, threaten traditional film applications. Incumbents must navigate this evolving competitive landscape.
For Market Incumbents: Shield core market share by investing heavily in multi-functional film R&D, integrating anti-glare properties with anti-microbial or privacy features. Deepen vertical integration into specialized coating chemical production to mitigate raw material price volatility. Strengthen strategic partnerships with display panel fabricators in South Korea and Taiwan to co-develop next-generation optical solutions.
For New Entrants and Emerging Players: Medical device certification fast-tracks, such as US FDA pre-market approvals, offer a strategic entry point for specialized anti-glare films. Target the healthcare segment, focusing on high-performance films for diagnostic equipment where durability and optical clarity command premium pricing. A go-to-market angle involves collaborating with medical device OEMs on regulatory-compliant material development.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized optical film manufacturers providing custom-engineered solutions to automotive and medical display fabricators. Identify acquisition targets with proprietary nano-coating technologies or strong intellectual property portfolios in advanced polymer science. The signal to watch is the adoption rate of integrated multi-functional films in premium automotive cockpits.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Hybrid Film R&D | Develops multi-functional solutions for premium automotive and consumer electronics displays. |
| Secure Raw Material Supply | Mitigates petrochemical price volatility impacting polyester and polycarbonate film costs. |
| Expand Regional Finishing | Supports localized demand in emerging electronics manufacturing hubs like Southeast Asia. |
| Pursue Medical Device Certifications | Unlocks high-margin opportunities in regulated healthcare display applications. |
| Partner with Display Fabricators | Accelerates co-development of custom optical solutions for next-generation displays. |
Research Approach
The analysis maps anti-glare film sub-sectors, each validated through extensive primary interviews with optical engineers, procurement managers, R&D directors, and regulatory compliance officers. Secondary validation drew from ISO specifications, EU REACH filings, display industry reports, and patent databases. This approach enabled bottom-up market sizing and top-down triangulation of volume and value.
Consistency checks against external benchmarks ensured the robustness of the forecast framework across the projection horizon. Segmentation dimensions modeled included product type, application, technology, end user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends, projected demand drivers, and expert consensus. Display panel production forecasts and automotive digital cockpit adoption rates served as key industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside significant raw material price swings or rapid display technology shifts would require recalibration. Forecasts reflect assumptions concerning market dynamics and technological trajectories. Practitioners should keep alternative scenarios live as new chemical regulations and geopolitical supply chain risks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Acrylic Lenses Market
Optics
Digital Holographic Microscopy Market
Optics
Fiber Optic Connectivity Market
Optics
Fiber Optic Cable Market
Optics
Sports Optics Market
Optics
North America Optical Imaging Market
Optics
Optical Sensing Market
Optics
Residential 1080P Laser Television Projector Market
Optics
Lasers Market
Optics
Fiber Optic Amplifier Market
Optics
Fiber Optics Market
Optics
Laser Transmitter Market
Optics
AR and VR Lens Market
Optics
Photonic Crystals Market
Optics
Latin America Optical Imaging Market
Optics
Electro Optics Market