
 Electro Optics Market | 2026-2036
Electro Optics Market Size, Share, and Industry Trends Forecast 2026-2036
Electro Optics Market Foresight
Software-defined beam steering and algorithmic image processing is rebalancing contract structures toward recurring software licenses and performance-based maintenance agreements. L3Harris Technologies leverages its classified program access to sustain long-term service revenue streams. Leonardo S.p.A. anchors European sovereign capability through national procurement frameworks. Hamamatsu Photonics K.K. dominates photomultiplier and solid-state sensor supply for scientific instrumentation.
Electro optics encompasses devices and systems that generate, modulate, detect, or manipulate electromagnetic radiation across the ultraviolet through infrared spectrum, typically operating at wavelengths from 10 nanometers to 1 millimeter with response times measured in picoseconds for advanced photodetectors. These systems serve military targeting, medical imaging, telecommunications backhaul, and industrial automation by converting optical signals into electrical intelligence or projecting controlled energy beams. Imaging systems command the largest revenue pool due to defense modernization cycles, while fiber optics segments accelerate fastest as data center interconnects and 5G fronthaul deployments multiply. Quantum dot technology occupies premium positioning for quantum sensing and advanced displays where spectral precision determines performance.
The U.S. Department of Defense drives demand through ITAR-controlled export restrictions and MIL-STD-810 environmental qualification requirements that filter foreign competition. EMA and CE marking frameworks in Europe shape medical electro optics certification pathways, while Japan's METI coordinates domestic photonics R&D consortia under national technology roadmaps. Stakeholders must monitor how quantum technology export controls and semiconductor equipment restrictions reshape supplier eligibility and component sourcing strategies.
Market Dynamics
Defense procurement cycles and quantum sensing commercialization are compressing product lifecycles while elevating software content in electro optics contracts. ITAR-controlled supply chains and MIL-STD-810 qualification requirements now filter vendor eligibility before technical merit enters consideration.
Growth Catalysts
- Defense modernization mandates:United States military branches are accelerating night vision and targeting system replacements under classified program budgets. Allied NATO members mirror this procurement intensity.
- CE marking pathway expansion:European medical device regulations under MDR are streamlining electro optics certification for diagnostic imaging, reducing time-to-market for photonic sensor manufacturers.
- Quantum dot spectral precision:Advanced nanomaterials are enabling quantum sensing applications that demand picosecond response times and single-photon detection thresholds.
Market Restraints
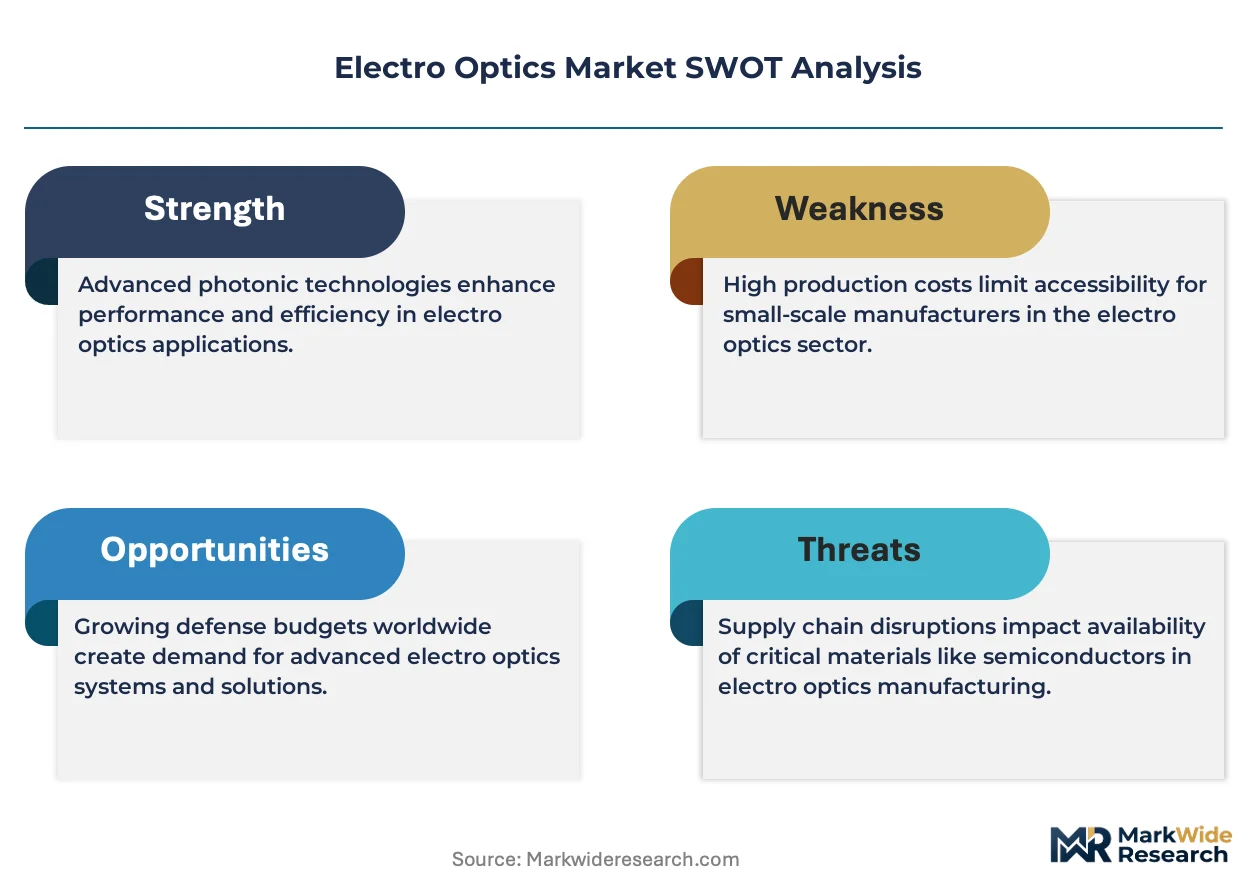
- Gallium arsenide supply concentration:Substrate materials for high-performance photodetectors depend on limited foundry capacity concentrated in East Asian manufacturing clusters.
- ITAR export friction:United States International Traffic in Arms Regulations block technology transfer to non-allied nations, segmenting addressable demand pools.
- Solid-state lidar displacement:Mechanical beam-steering architectures face substitution pressure from MEMS-based and optical phased array alternatives in automotive sensing.
Strategic Opportunities
- German precision manufacturing ecosystem:Stuttgart and Munich industrial clusters host medical OEMs seeking qualified electro optics suppliers for surgical navigation systems.
- Japan METI photonics roadmap:National R&D consortia under Ministry of Economy, Trade and Industry coordination fund domestic quantum technology development.
- Telecommunications backhaul expansion:Fiber optics segments accelerate as data center interconnects and 5G fronthaul deployments multiply transmission infrastructure demand.
Industry Challenges
- Specialized photonics engineering scarcity:Quantum optics and integrated photonics design talent pools remain shallow relative to defense and telecommunications hiring demand.
- MIL-STD-810 qualification timelines:Environmental testing protocols for military-grade imaging systems extend product development cycles by 18-24 months.
- Legacy analog system integration:Digital electro optics architectures face friction retrofitting into fielded platforms with proprietary interface standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electro Optics Market |
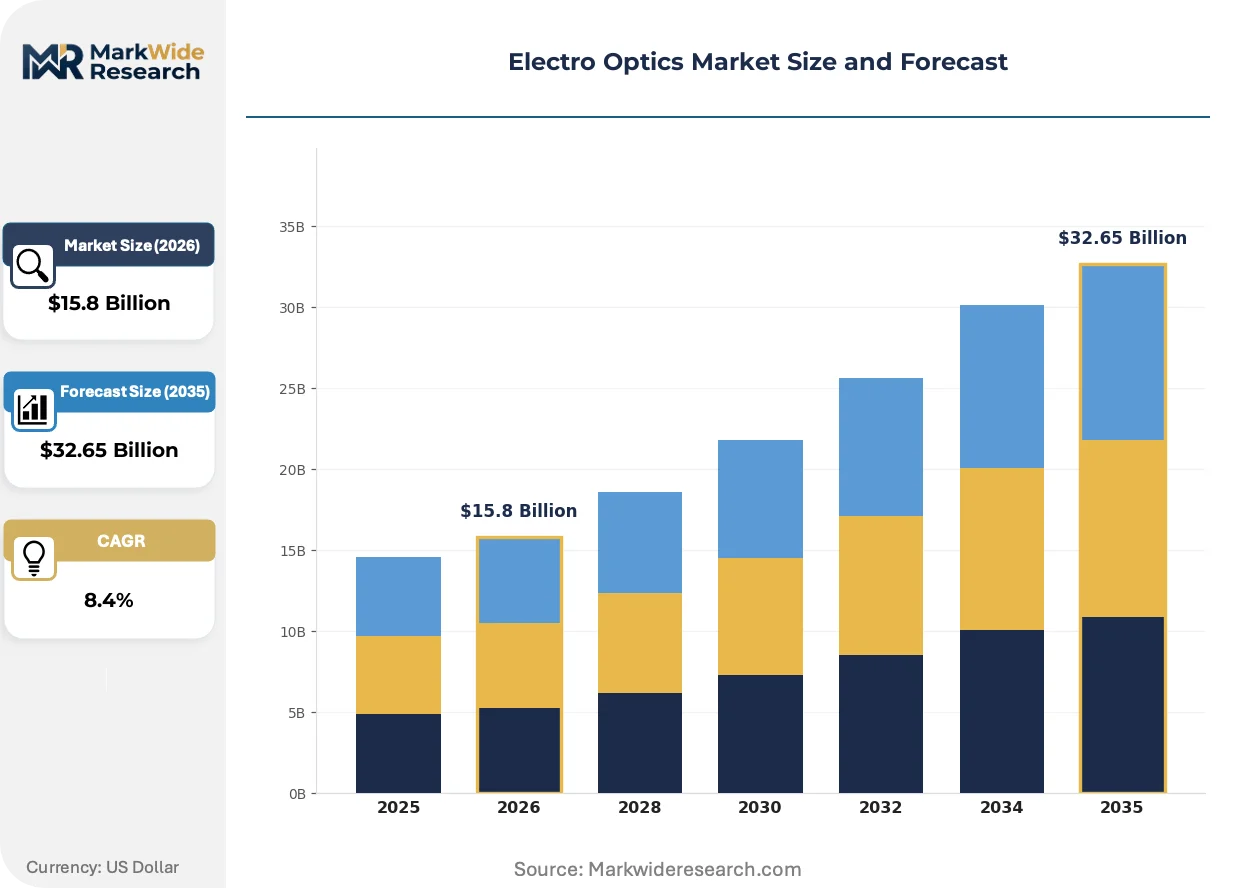
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $32.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lasers, Sensors, Imaging Systems, Fiber Optics Technology: Quantum Dots, Photonic Crystals, Waveguides, Organic Photonics End User: Defense, Aerospace, Telecommunications, Medical Application: Surveillance, Communication, Automation, Display |
| Companies Covered | L3Harris Technologies Inc., Leonardo S.p.A., Excelitas Technologies Corp., Hamamatsu Photonics K.K., Teledyne FLIR, Northrop Grumman Corporation, Lockheed Martin Corporation, Raytheon Technologies Corporation, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electro Optics Market Shifts & Advancements
Algorithmic image processing and software-defined beam steering are rebalancing contract economics toward recurring revenue models. Photonic integration and quantum sensing advances are compressing component form factors while expanding functional boundaries.
Photonic integrated circuits are converging with silicon CMOS fabrication processes to enable mass-manufacturable optical transceivers. Data center operators and telecommunications carriers are adopting co-packaged optics at accelerating deployment schedules. This convergence is collapsing cost structures for 800G and 1.6T interconnects while displacing discrete component assemblies.
EU AI Act algorithmic transparency requirements are extending to medical imaging systems incorporating machine-learning-based diagnostic assistance. Electro optics OEMs serving European healthcare markets must document training data provenance and decision boundary logic. High-resolution pathology scanners and ophthalmic diagnostic platforms face the steepest compliance adaptation curves.
Performance-based maintenance agreements are displacing traditional hardware purchase-plus-warranty structures in defense electro optics procurement. United States military program offices now prioritize availability metrics and software update cadence over unit acquisition cost. L3Harris Technologies and Leonardo S.p.A. have restructured service organizations to capture this contract model evolution.
Electro Optics Market Segmentation
Segmentation in electro optics reveals how certification burdens and procurement channels fragment addressable demand. Military-grade segments navigate ITAR and MIL-STD-810 gates, while medical applications face divergent FDA and CE marking pathways.
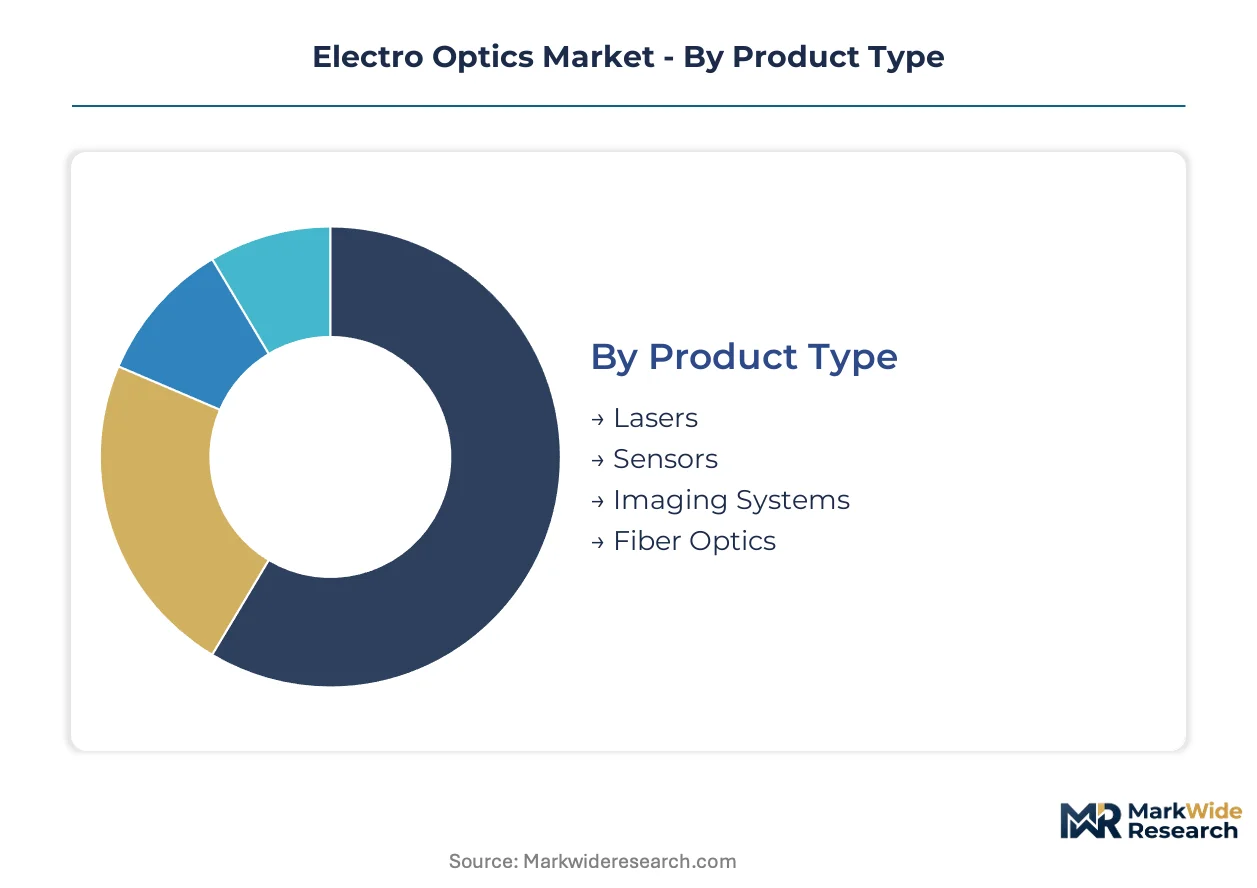
Product Type:
ITAR-controlled defense segments demand MIL-STD-810 environmental qualification, while medical imaging products require FDA 510(k) or CE marking under MDR frameworks.
- Imaging Systems:These systems integrate infrared focal plane arrays, image intensifier tubes, and cooled detector assemblies for night vision and targeting applications. United States defense procurement concentrates demand through classified program budgets, with allied NATO members mirroring this intensity under shared technical standards.
- Fiber Optics:Optical fiber assemblies, connectors, and transceivers enable data center interconnects and telecommunications backhaul. Deployment schedules for 5G fronthaul and hyperscale data centers in Germany and Japan are multiplying transmission infrastructure demand.
- Lasers:Solid-state and fiber laser sources span industrial cutting, medical surgery, and directed-energy applications.
- Sensors:Photodetectors, photomultipliers, and solid-state sensing elements serve scientific instrumentation and automation.
Leading the category by volume: Imaging Systems. Growing fastest: Fiber Optics.
Technology:
Cost tiers separate laboratory-grade quantum systems from mass-manufacturable photonic integrated circuits.
- Quantum Dots:Nanocrystal semiconductor structures enable single-photon detection and spectral precision for quantum sensing. Defense agencies in the United States fund development through national security research budgets.
- Photonic Integrated Circuits:Silicon photonics and indium phosphide platforms converge with CMOS fabrication to produce mass-manufacturable optical transceivers. Co-packaged optics adoption by telecommunications carriers in Japan is collapsing cost structures for 800G interconnects.
- Photonic Crystals:Periodic dielectric structures manipulate light propagation for advanced filtering and sensing.
- Waveguides:Channel structures confine and direct electromagnetic waves in planar and fiber geometries.
- Organic Photonics:Polymer-based emitters and detectors offer flexible form factors for display and wearable applications.
Commanding premium pricing: Quantum Dots. Expanding most quickly: Photonic Integrated Circuits.
End User:
Customer type determines contract structure, with defense favoring performance-based maintenance and medical requiring diagnostic validation.
- Defense:Military procurement spans night vision goggles, laser designators, and electro-optical targeting systems. United States program offices prioritize availability metrics and software update cadence over unit acquisition cost.
- Medical:Diagnostic imaging, surgical navigation, and ophthalmic equipment demand FDA or CE marking compliance. European OEMs in Stuttgart and Munich industrial clusters source qualified suppliers for surgical navigation systems.
- Aerospace:Aircraft sensor suites and satellite payloads require radiation-hardened components and extended qualification timelines.
- Telecommunications:Carriers deploy optical transceivers for backbone and access network expansion.
Dominating contract value: Defense. Steepest compliance curve: Medical.
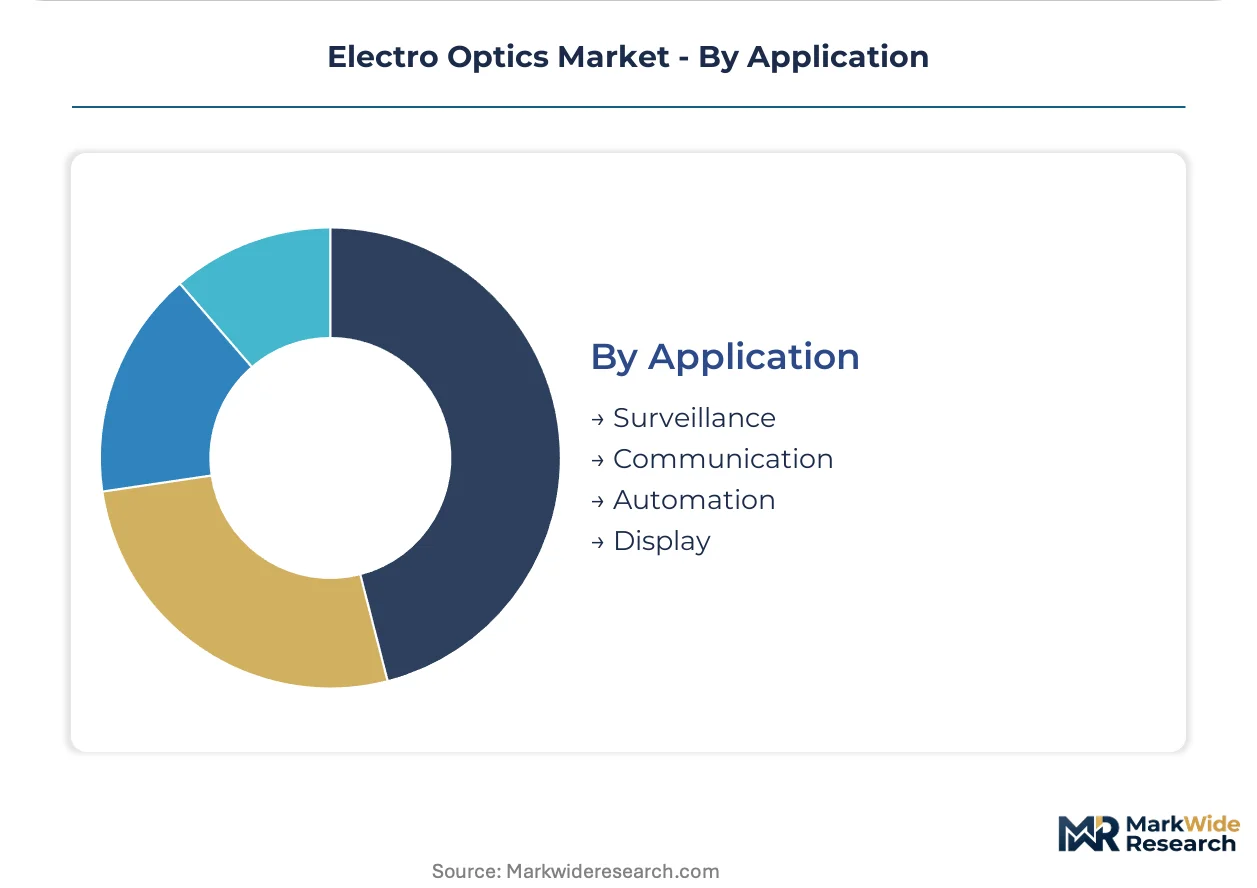
Application:
Maturity gradients separate established surveillance markets from emerging automation deployments.
- Surveillance:Border monitoring, perimeter security, and reconnaissance systems integrate multispectral imaging. United States Customs and Border Protection procurement drives demand for long-range thermal systems.
- Communication:Free-space optical links and fiber-based networks transmit data across defense and commercial infrastructure. Japanese telecommunications carriers accelerate co-packaged optics deployment schedules.
- Automation:Machine vision and LiDAR guide industrial robotics and autonomous vehicle perception.
- Display:Head-mounted and heads-up display systems project information for military and aviation operators.
Highest installed base: Surveillance. Gaining share fastest: Automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in East Asian foundries, while defense procurement concentrates in North American and European capitals. Consumption patterns split between ITAR-controlled military programs and commercial telecommunications deployments.
United States
Department of Defense procurement drives night vision and targeting system demand through classified program budgets. ITAR export restrictions filter vendor eligibility before technical evaluation begins. Arizona and Florida host concentrated defense contractor facilities supporting electro-optical subsystem assembly.
Germany
Stuttgart and Munich industrial clusters source qualified suppliers for surgical navigation and diagnostic imaging equipment. CE marking under MDR frameworks streamlines certification pathways for photonic sensor manufacturers. Bavarian precision manufacturing ecosystems anchor European sovereign capability in medical electro optics.
Japan
METI coordinates national photonics R&D consortia funding quantum technology development and domestic supply chain security. Co-packaged optics deployment by telecommunications carriers accelerates transmission infrastructure expansion. Hamamatsu anchors photomultiplier and solid-state sensor production for scientific instrumentation.
United Kingdom
Defense procurement mirrors NATO technical standards for electro-optical targeting and surveillance systems. National security research budgets fund quantum sensing development through academic-industry partnerships. Southwest England hosts specialized photonics engineering talent pools supporting defense contractor demand.
South Korea
Telecommunications carriers deploy optical transceivers for 5G fronthaul and data center interconnect expansion. Domestic semiconductor equipment restrictions reshape component sourcing strategies for photonic integrated circuits. Seoul Capital Area concentrates display and optical component manufacturing capacity.
Electro Optics Market Competitive Landscape
Top-tier vendors anchor defense procurement channels, while mid-tier specialists serve medical and industrial segments. The vendor base stratifies across ITAR-cleared integrators, CE-marked medical device suppliers, and telecommunications component manufacturers. Three archetypes dominate: classified program access holders, precision manufacturing ecosystem anchors, and photonic integrated circuit scale producers. Competitive moves concentrate on strategic partnerships for quantum technology development and capacity expansion for fiber optics transmission infrastructure.
Within the defense-tier segment, L3Harris Technologies Inc. and Northrop Grumman Corporation represent ITAR-cleared integrators with sustained program access. Leonardo S.p.A. exemplifies European sovereign capability through national procurement frameworks. Hamamatsu Photonics K.K. anchors scientific instrumentation supply from Japanese manufacturing bases.
| Leading Market Players |
|---|
| L3Harris Technologies Inc. |
| Leonardo S.p.A. |
| Excelitas Technologies Corp. |
| Hamamatsu Photonics K.K. |
| Teledyne FLIR |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| Thales Group |
| Others |
Supply & Pricing Matrix
Gallium arsenide substrate costs cascade through defense imaging system pricing tiers, with ITAR-controlled foundry premiums amplifying downstream margin compression for non-cleared suppliers competing on medical and industrial contracts.
Pricing Analysis
Price erosion across photonic integrated circuit tiers traces to CMOS fabrication convergence collapsing discrete component assembly premiums. Three-tier pricing structure across ITAR-cleared defense, CE-marked medical, and unqualified industrial levels separates buyers by certification burden rather than unit performance alone. Cost-down pressure on fiber optics transceivers accelerates because telecommunications carriers negotiate volume offtakes tied to 800G deployment schedules. Defense program offices exhibit lowest price sensitivity due to availability-based contracting, while industrial automation buyers drive hardest unit-cost negotiations.
Supply Chain Analysis
Regional distribution centers in Arizona and Florida consolidate defense contractor subassemblies before final integration, while Stuttgart and Munich hubs serve European medical OEM clusters. Manufacturing gravity centers on Taiwan and South Korea for photonic integrated circuit foundry capacity, Japan for photomultiplier and solid-state sensor production, and the United States for ITAR-cleared imaging system assembly. Raw material flows draw from gallium arsenide substrate suppliers, indium phosphide wafer producers, and rare-earth dopant processors. Single-source vulnerability concentrates in East Asian foundry capacity for high-performance photodetectors. Distribution runs through authorized defense procurement channels, medical device distributor networks, and telecommunications carrier direct agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electro optics competition has become a vertical-integration race, with captive control over gallium arsenide substrate supply and classified program access serving as the decisive upstream and downstream levers separating tier-one integrators from component suppliers.
For Market Incumbents: To counter MEMS-based solid-state lidar displacement threatening mechanical beam-steering architectures, L3Harris Technologies and Leonardo S.p.A. should deepen captive supply of indium phosphide wafer processing and expand performance-based maintenance agreement penetration to lock in recurring revenue against hardware commoditization. For New Entrants and Emerging Players: Capture white-space in German surgical navigation subsystem supply by qualifying under MDR streamlined pathways, and exploit Japan METI photonics consortium funding gaps for quantum dot sensing development. The most penetrable entry point sits in medical electro optics certification consulting, bridging Stuttgart OEM procurement requirements with Asian component sourcing. For Investors and Strategic Acquirers: ITAR clearance acquisition premiums stabilizing near defense budget authorization cycles is the leading indicator that sovereign capability consolidation will accelerate across European and Indo-Pacific markets. Five-to-ten year viability favors vertically integrated platforms with both foundry access and program office relationships over pure-play component suppliers. The signal to monitor is classified program budget reallocation toward software-defined architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Foundry Partnership | Co-packaged optics adoption by Japanese telecommunications carriers collapses 800G transceiver cost structures. |
| ITAR Clearance Acquisition | United States defense procurement channels filter vendor eligibility before technical evaluation begins. |
| MDR Certification Pathway Investment | European medical device regulations streamline Stuttgart and Munich OEM supplier qualification timelines. |
| Quantum Sensing R&D Consortium | METI-coordinated national photonics roadmaps fund domestic quantum dot development in Japan. |
| Performance-Based Maintenance Restructuring | United States military program offices prioritize availability metrics over unit acquisition cost. |
Research Methodology
Independent corroboration across defense procurement officers, medical device regulatory leads, telecommunications carrier network planners, and photonic integrated circuit foundry engineers underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with secondary validation through ITAR-controlled program budget disclosures, FDA 510(k) submission databases, METI photonics roadmap publications, and CE marking MDR transition filings. Bottom-up segment sizing triangulated against top-down defense expenditure tracking and telecommunications infrastructure deployment schedules.
Rate-of-change decomposition across product type, technology tier, end-user vertical, and application maturity underpins the forecast framework. Segmentation dimensions modeled include imaging system versus fiber optics versus laser source categories, ITAR-cleared versus commercial qualification tiers, defense versus medical versus telecommunications end-user contracts, and surveillance versus automation application growth gradients. CAGRs derive from procurement cycle timing, certification pathway duration, and technology substitution elasticity. Industry-specific inputs incorporate MIL-STD-810 qualification timeline data and co-packaged optics deployment acceleration curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to quantum technology export control expansion, semiconductor equipment restriction escalation, and gallium arsenide supply concentration disruption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Photostimulation Lasers Market
Optics
Interchangeable Lens Market
Optics
Smartphone Camera Lenses Market
Optics
Collimating Lens Market
Optics
Photonics Sensor Market
Optics
Optical Gratings Market
Optics
US Photonics Market
Optics
AR and VR Lens Market
Optics
Photonic Crystals Market
Optics
Anti Glare Film Market
Optics
Middle East and Africa Tunable Laser Market
Optics
Residential 1080P Laser Television Projector Market
Optics
Asia-Pacific Anti-Blue Ray Myopia Lenses Market
Optics
Optical Telescope Market
Optics
Beam Combining Optics Market
Optics
Polymeric Optical Fiber Market