
 Collimating Lens Market | 2026-2036
Collimating Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Collimating Lens Market Analysis
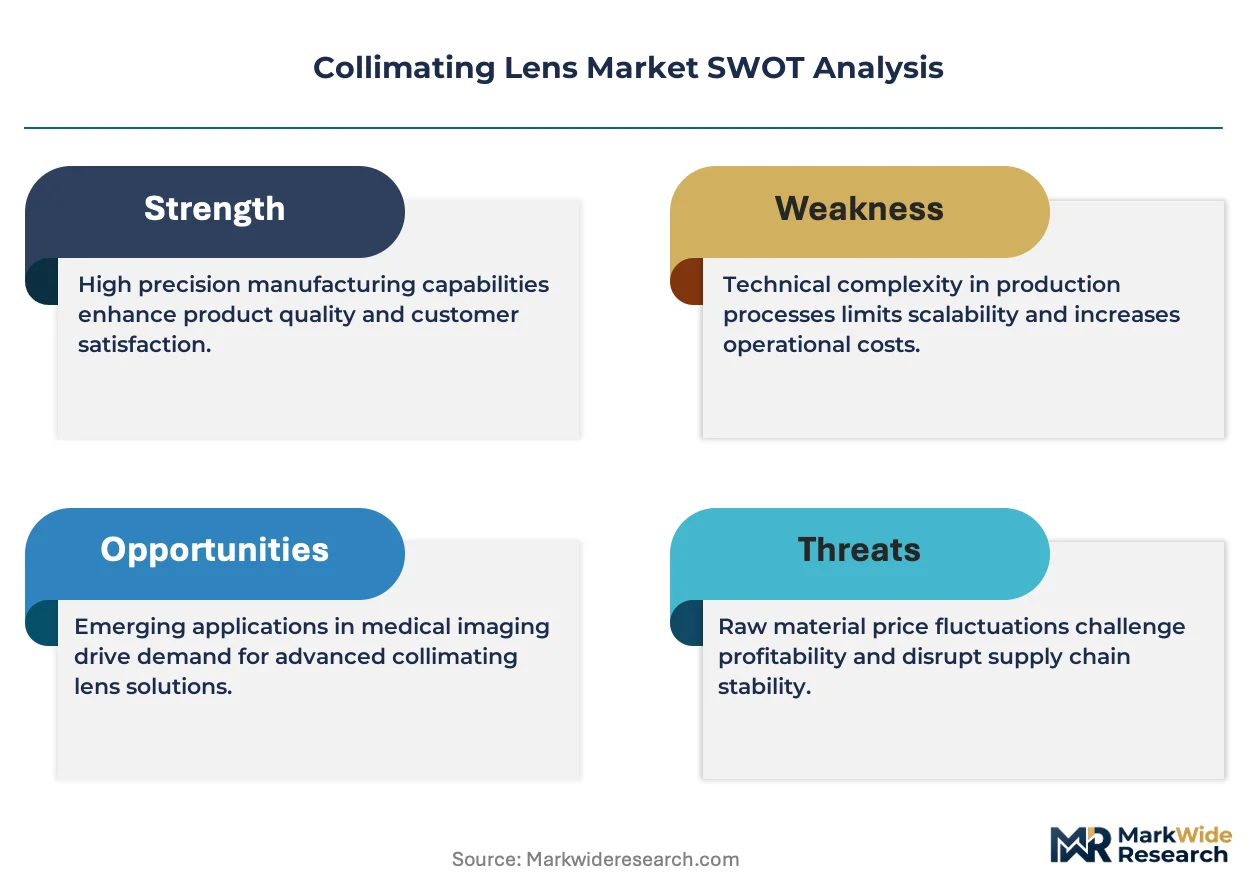
The capital-intensity divergence between integrated manufacturers and modular assemblers is collapsing as aspheric lens fabrication demands in-house diamond-turning capabilities. Thorlabs leverages its vertically integrated production network across North America and Europe to control substrate quality from raw glass to coated optic. INGENERIC GmbH specializes in high-NA collimators for diode laser bars, anchoring its position in industrial materials processing systems.
A collimating lens transforms divergent light from a point source into a parallel beam through precisely curved surfaces, typically manufactured via CNC grinding, polishing, or single-point diamond turning to achieve surface figure accuracies below λ/4. Its primary purpose centers on beam conditioning in laser systems, spectrometers, and projection engines where wavefront quality determines system performance. Glass substrates dominate precision applications for thermal stability and transmission bandwidth, while plastic injection-molded optics compete in cost-sensitive consumer electronics where volume scale offsets lower durability. Achromatic doublet designs command premium positioning in biomedical imaging and defense targeting systems where chromatic aberration corrupts measurement fidelity.
FDA device regulations in the United States govern collimating optics embedded in surgical laser systems and diagnostic instruments, while REACH and RoHS frameworks in Europe restrict heavy metal content in optical coatings and substrate dopants. China's GB standards and NMPA medical device rules shape market access for imported precision optics. Stakeholders must monitor tightening fluorophosphate glass supply chains and qualification timelines for replacement eco-glass formulations.
Market Dynamics
Aspheric fabrication requirements are forcing capital convergence across the collimating lens value chain, eroding the traditional separation between substrate suppliers and finished optic manufacturers.
Growth Catalysts
- Semiconductor lithography:EUV source conditioning demands sub-nanometer wavefront precision, pulling high-NA collimator volumes into foundry capital equipment budgets.
- REACH compliance deadlines:ECHA restrictions on lead oxide and arsenic in optical glass are accelerating qualification of fluorophosphate substitutes for precision applications.
- Industrial laser densification:Materials processing systems in Germany's Jena-Oberkochen corridor now specify collimator modules with integrated beam-shaping functionality.
Market Restraints
- Raw material concentration:Schott AG and Ohara Corporation control premium optical glass melt capacity, creating single-source risk for low-dispersion substrates.
- Substitution pressure:Diffractive optical elements from NIL Technology compete in beam-shaping applications where chromatic performance is secondary.
- Capital intensity:Single-point diamond turning platforms require seven-figure capex commitments, freezing out modular assemblers from aspheric production.
Strategic Opportunities
- Underpenetrated defense imaging:Targeting pods and rangefinder systems in India present unmet demand for athermalized achromatic designs.
- Regulatory tailwind:EU AI Act classification of medical imaging AI as high-risk systems mandates traceable optic performance, favoring qualified European suppliers.
- Technology convergence:Freeform surfaces combined with metasurface coatings enable single-element replacements for multi-lens assemblies in space-constrained LiDAR.
Industry Challenges
- Skill scarcity:Diamond-turning technicians with λ/20 surface figure expertise command premium wages, constraining production scaling.
- Certification timelines:FDA 510(k) pathways for surgical laser collimators extend 18-24 months, freezing design iterations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collimating Lens Market |
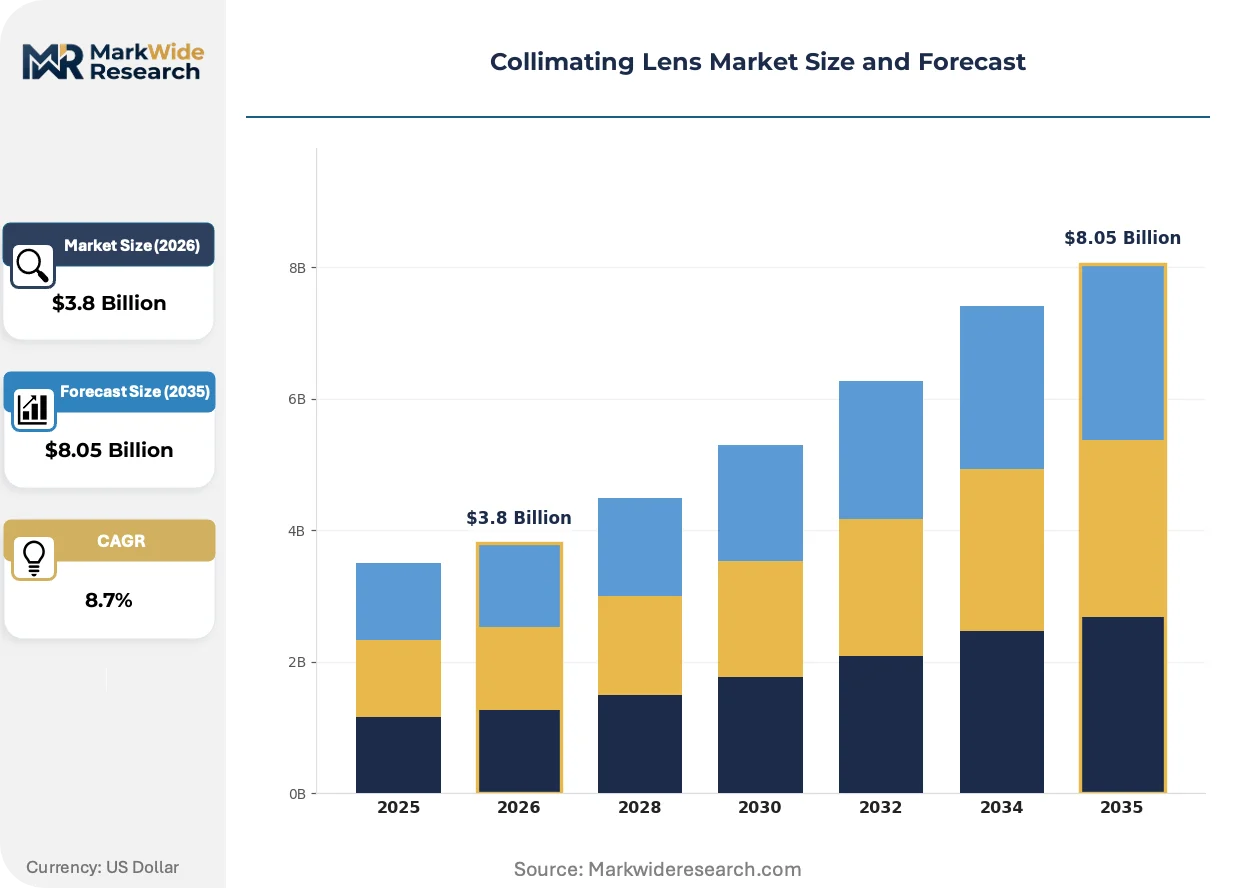
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aspheric Lens, Achromatic Lens, Plano-Convex Lens, Cylindrical Lens Application: Laser Systems, Optical Instruments, Projectors, Telecommunications Material: Glass, Plastic, Sapphire, Quartz End User: Healthcare, Defense, Manufacturing, Consumer Electronics |
| Companies Covered | Ocean Optics, TRIOPTICS GmbH, LightPath Technologies, Avantes BV, Auer Lighting GmbH, Thorlabs, INGENERIC GmbH, Edmund Optics, IPG Photonics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collimating Lens Market Emerging Trajectories
Metasurface-augmented optics are compressing the traditional multi-element stack into thinner assemblies, forcing incumbents to defend position through precision metrology rather than volume scale.
Freeform surface fabrication is fragmenting the historical spherical-aspheric binary in collimator design. Medical imaging OEMs in the United States are specifying toroidal and biconic geometries for off-axis illumination paths. This capability spread is compressing the addressable market for conventional rotationally symmetric lenses.
REACH substance restrictions are tightening supply qualification burdens across European precision optics. ECHA's 2023 candidate list expansion for reprotoxic substances now captures several common optical coating precursors. German substrate manufacturers are accelerating in-house recycling streams to maintain coating chemistry access.
Specification consolidation among tier-one laser system builders is compressing vendor counts in collimator procurement. Buyers in materials processing now demand bonded assemblies with certified wavefront error rather than discrete lens sourcing. This pattern concentrates procurement power with integrators holding captive metrology capability.
Collimating Lens Market Segmentation
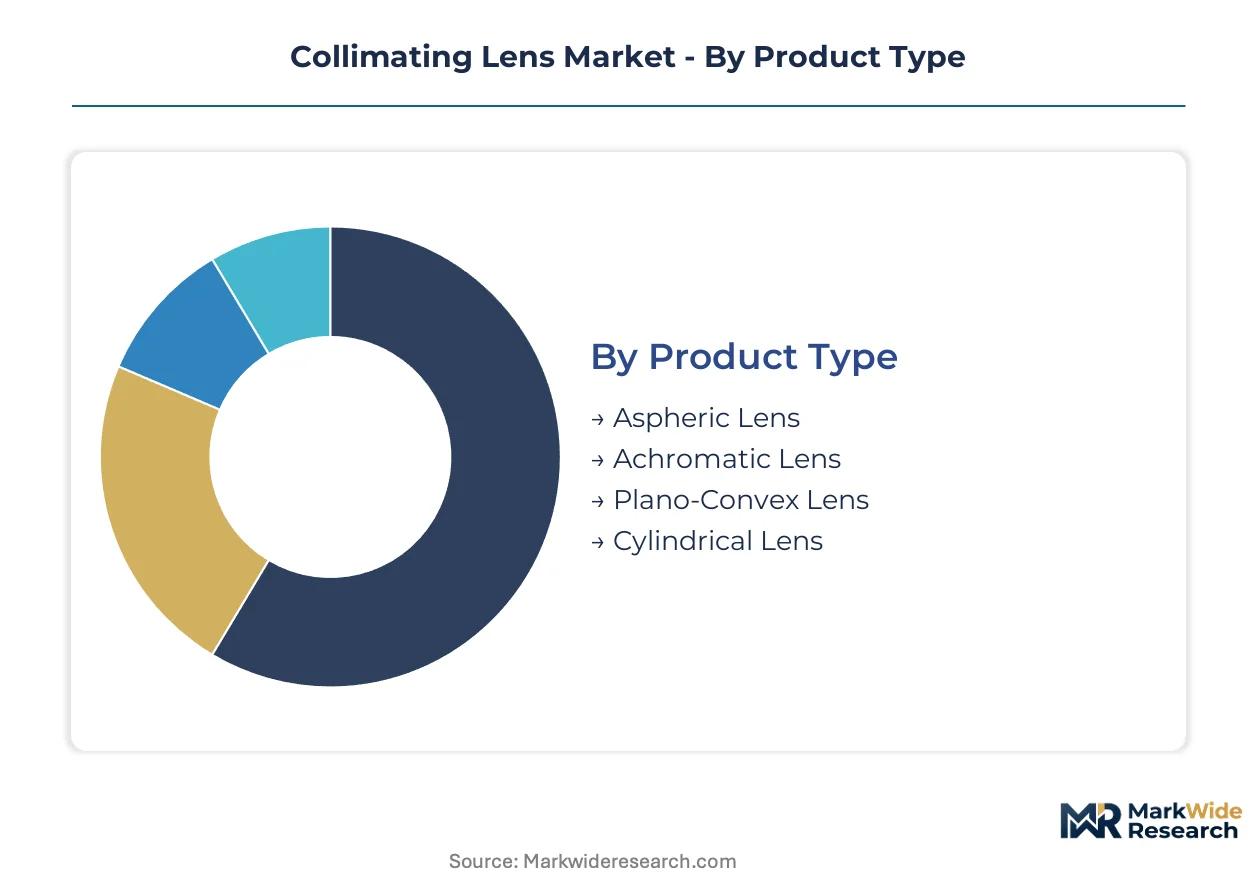
Collimating lens procurement patterns diverge sharply across technical specifications, with surface figure tolerances and thermal stability requirements dicting supplier qualification tiers. Understanding segment-level margin distribution enables vendors to prioritize R&D investments and capacity allocation.
Product Type:
Margin pools concentrate in aspheric and achromatic designs where diamond-turning capabilities and multi-element bonding expertise create defensible positioning.
- Achromatic Lens:Doublet and triplet configurations fuse crown and flint glass elements to nullify chromatic aberration across visible and near-infrared bands. Demand concentrates in biomedical imaging systems from German OEMs and defense targeting pods where measurement fidelity justifies unit premiums. FDA device regulations and EMA quality standards extend qualification timelines, entrenching incumbent suppliers.
- Aspheric Lens:Single-point diamond turning produces rotationally non-symmetric surfaces that correct spherical aberration without multi-element stacking. Semiconductor lithography OEMs in Japan and the Netherlands specify sub-nanometer wavefront precision for EUV source conditioning, pulling high-NA collimator volumes into foundry capital equipment budgets.
- Plano-Convex Lens:Spherical singlets dominate cost-sensitive industrial laser applications where λ/4 surface figure suffices.
- Cylindrical Lens:Anamorphic correction for diode laser bars and line-scan imaging systems in materials processing.
Achromatic lens lines hold installed capacity from defense and medical device long-term supply agreements. Aspheric designs are rotating up the share rankings as semiconductor capital intensity accelerates.
Application:
Application-level procurement volume tracks capital equipment cycles in precision manufacturing and defense modernization programs.
- Laser Systems:Beam conditioning for materials processing, medical surgery, and semiconductor fabrication demands thermal stability and wavefront purity. Germany's Jena-Oberkochen precision optics cluster anchors industrial laser specification development, with integrated beam-shaping functionality now standard in fiber laser delivery systems.
- Telecommunications:Dense wavelength division multiplexing and free-space optical links require collimation for fiber-to-chip coupling. China's NMPA and GB standards shape market access for imported precision optics in domestic 5G infrastructure builds.
- Optical Instruments:Spectrometers and interferometers prioritize achromatic performance for broadband source analysis.
- Projectors:Cost-engineered plastic optics compete on volume scale in consumer and commercial display segments.
Laser systems applications hold installed capacity from multi-year semiconductor foundry equipment contracts. Telecommunications is climbing the fastest as datacenter interconnect bandwidth requirements intensify.
Material:
Material selection trades thermal and transmission performance against REACH compliance burdens and supply concentration risk.
- Glass:Borosilicate and fluorophosphate formulations deliver thermal stability and broad transmission bandwidth for precision applications. ECHA restrictions on lead oxide and arsenic dopants are accelerating qualification of substitute eco-glass formulations, with Schott AG and Ohara Corporation controlling premium melt capacity.
- Sapphire:Exceptional hardness and chemical resistance suit harsh-environment defense and aerospace applications.
- Plastic:Injection-molded optics from cyclic olefin polymers compete in cost-sensitive consumer electronics where volume scale offsets lower durability and thermal limits.
- Quartz:UV-grade fused silica dominates deep-ultraviolet lithography and laser ablation systems.
Glass substrates hold installed capacity from biomedical and defense qualification pipelines. Sapphire is gaining share fastest as targeting pod and rangefinder specifications tighten environmental tolerance requirements.
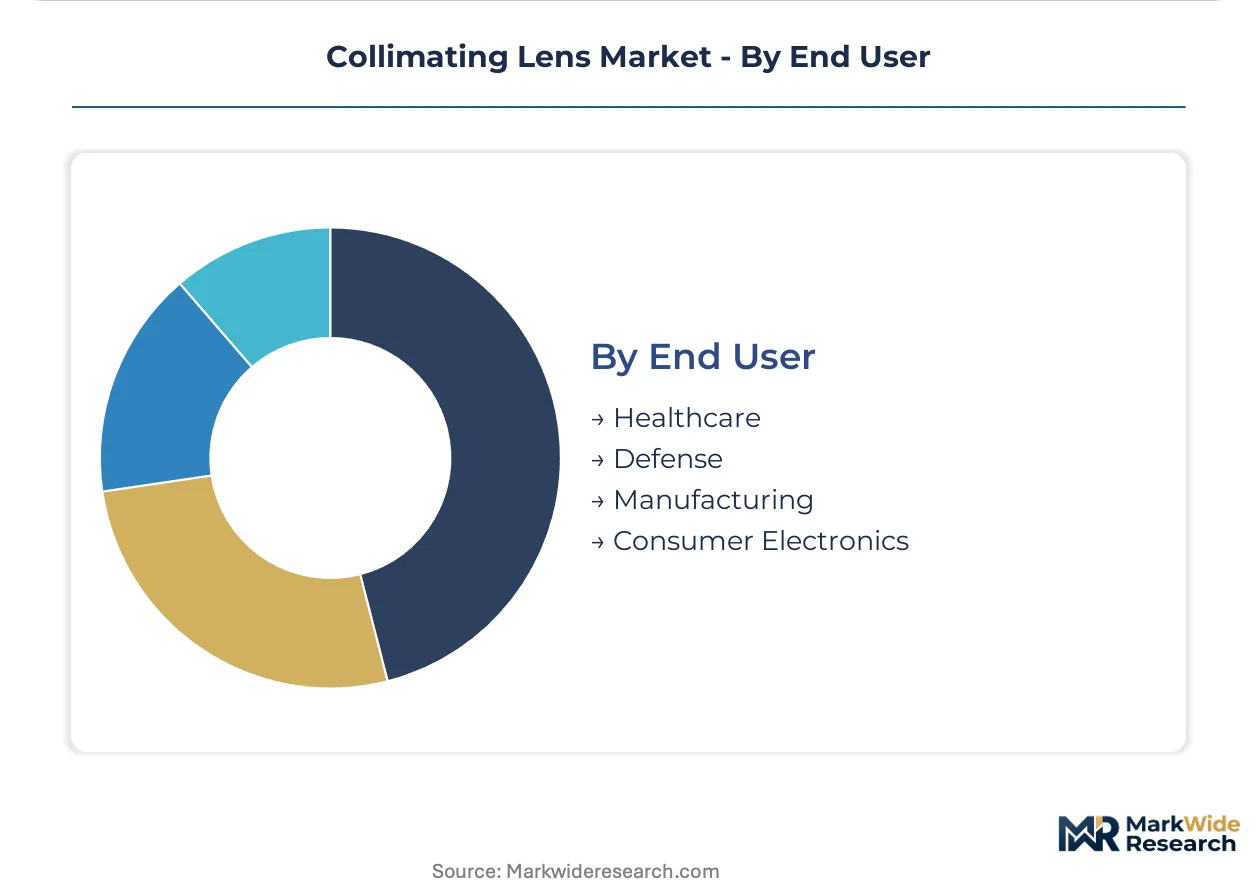
End User:
End-user procurement authority concentrates with system integrators holding captive metrology and bonding capabilities.
- Defense:Targeting pods, rangefinders, and fire-control systems demand athermalized achromatic designs for field reliability. India's defense modernization programs present unmet demand as domestic precision optics capacity remains underdeveloped.
- Healthcare:Surgical laser systems and diagnostic instruments fall under FDA 510(k) and EMA MDR pathways, with 18-24 month certification timelines freezing design iterations and favoring qualified European suppliers.
- Manufacturing:Industrial materials processing systems specify collimator modules with integrated beam-shaping functionality.
- Consumer Electronics:Price-engineered specifications prioritize plastic optics and automated assembly compatibility.
Defense end users hold installed capacity from multi-year platform contracts. Healthcare is expanding most quickly as EU AI Act classification of medical imaging AI mandates traceable optic performance documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing power for precision aspheric collimators, while Chinese fabricators compete on volume scale for plano-convex industrial laser applications. This asymmetry shapes procurement patterns across semiconductor, defense, and medical device supply chains.
United States
FDA 510(k) pathways for surgical laser collimators extend 18-24 months, freezing design iterations for domestic healthcare OEMs. The EPA monitors fluorophosphate glass waste streams from optical substrate fabrication. Greater Boston anchors biomedical imaging specification development, with achromatic doublet demand concentrated in diagnostic instrument clusters.
Germany
ECHA REACH restrictions on lead oxide and arsenic dopants accelerate qualification of eco-glass substitutes across Jena-Oberkochen precision optics corridors. The EU AI Act classification of medical imaging AI as high-risk systems mandates traceable optic performance documentation. Baden-Württemberg hosts integrated beam-shaping module production for industrial fiber laser delivery systems.
China
NMPA medical device rules and GB standards shape market access for imported precision optics in domestic 5G infrastructure and surgical laser builds. MIIT industrial policy prioritizes captive optical glass melt capacity for semiconductor lithography supply security. Yangtze River Delta clusters concentrate plastic injection-molded collimator production for consumer electronics volume scales.
Japan
METI technology roadmaps prioritize sub-nanometer wavefront precision for EUV source conditioning in foundry capital equipment. PMDA quality standards extend qualification timelines for surgical laser optics. Chubu-Nagoya regions anchor diamond-turning technician training pipelines for λ/20 surface figure expertise.
India
Defense modernization programs generate unmet demand for athermalized achromatic collimators in targeting pods and rangefinder systems. CDSCO medical device regulations tighten import documentation for surgical laser optics. Maharashtra and Karnataka precision optics clusters remain underdeveloped against specification requirements from domestic aerospace integrators.
Collimating Lens Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the collimating lens value chain. Vertically integrated substrate-to-coating manufacturers command premium positioning in semiconductor and biomedical segments, while modular assemblers compete on volume scale for industrial laser applications. Three archetypes dominate: captive-glass-melt specialists, diamond-turning precision fabricators, and injection-molding volume producers. Competitive moves center on backward integration into raw glass supply and geographic expansion through qualified bonding facility networks.
Among German fabricators, TRIOPTICS GmbH and INGENERIC GmbH exemplify the precision-specialist archetype anchored in the Jena-Oberkochen corridor. Thorlabs represents the vertically integrated North American model with captive substrate control across multiple continents. These three occupy positions that reflect the structural divergence between EU regulatory-compliance premiums and scale-driven cost engineering.
| Leading Market Players |
|---|
| Ocean Optics |
| TRIOPTICS GmbH |
| LightPath Technologies |
| Avantes BV |
| Auer Lighting GmbH |
| Thorlabs |
| INGENERIC GmbH |
| Edmund Optics |
| IPG Photonics Corporation |
| Others |
Supply Flow & Price Mechanics
Single-point diamond turning capacity utilization above 80% across Germany and Japan simultaneously concentrates supply-side pricing power and establishes hard price floors for aspheric collimators. Buyers seeking sub-nanometer wavefront precision face captive supply relationships with fabricators holding in-house metrology, while plano-convex standard optics compete on volume scale from Chinese injection-molding clusters.
Pricing Analysis
Configured-to-order pricing for aspheric and achromatic designs commands 3-4x premiums over standard plano-convex catalog items. Three-tier pricing structure across premium, standard, and economy levels segments by surface figure tolerance and certification grade, with FDA 510(k) qualified medical optics capturing the top tier. Cost compression in consumer electronics plastic optics is intensifying because Yangtze River Delta fabricators are scaling automated assembly. Industrial laser OEMs exhibit the lowest price sensitivity, while consumer projector assemblers drive the hardest volume negotiations.
Supply Chain Analysis
Strategic stockpiling of fluorophosphate glass substrates dominates inventory strategy as ECHA REACH restrictions tighten supply qualification timelines. Premium optical glass melt capacity concentrates in Germany, Japan, and China, with Schott AG and Ohara Corporation controlling low-dispersion formulations. Raw material dependencies rest on borosilicate and fluorophosphate glass, diamond-turning equipment spindles, and ion-beam coating precursors. Single-source vulnerability in eco-glass substitutes presents structural risk as lead oxide alternatives face extended qualification. Distribution runs through direct OEM supply agreements for precision tiers and distributor networks for standard industrial grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metasurface-augmented optics and freeform surface fabrication are compressing multi-element assemblies into single components, creating a high-growth disruption as traditional spherical-aspheric design paradigms lose addressable market share.
For Market Incumbents: Secure captive diamond-turning technician pipelines through apprenticeship partnerships with Chubu-Nagoya technical institutes, addressing the skill scarcity constraining λ/20 surface figure production scaling. Deepen backward integration into fluorophosphate glass recycling streams to maintain coating chemistry access under ECHA reprotoxic substance restrictions. Defend positioning against NIL Technology diffractive optical elements by embedding wavefront metrology certification into bonded assembly offerings. For New Entrants and Emerging Players: Lead with athermalized achromatic designs targeting India's underdeveloped defense precision optics capacity, where CDSCO import documentation gaps create procurement friction for established European suppliers. White-space exists in integrated beam-shaping modules for fiber laser delivery systems, where Baden-Württemberg incumbents face capacity constraints. Go-to-market through qualification partnerships with German Jena-Oberkochen cluster fabricators seeking overflow capacity absorption. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated substrate-to-coating specialists with captive glass melt capability, as REACH compliance burdens accelerate consolidation. Long-term viability over the next decade hinges on qualification pipeline depth for eco-glass formulations and metasurface coating integration. Target acquisition archetypes include German precision fabricators holding EMA MDR certification and Japanese diamond-turning houses with EUV lithography relationships. Watch for inflection when semiconductor foundry capital equipment budgets for EUV source conditioning cross sustained allocation thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Glass Melt Capacity | Captive fluorophosphate supply secures REACH-compliant substrate access against Schott-Ohara concentration. |
| Freeform Surface Fabrication Capability Investment | Toroidal and biconic geometries capture medical imaging OEM specifications from rotationally symmetric incumbents. |
| Metasurface Coating Technology Licensing | Single-element LiDAR replacements compress assembly thickness for space-constrained automotive integration. |
| Diamond-Turning Technician Apprenticeship Programs | λ/20 surface figure expertise pipelines constrain production scaling across Jena-Oberkochen corridors. |
| EMA MDR Certification Pathway Acceleration | Traceable optic performance documentation captures EU AI Act high-risk system procurement mandates. |
Methodological Framework
A standing panel of diamond-turning technicians, biomedical imaging OEM procurement directors, semiconductor lithography equipment planners, and defense rangefinder system integrators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from SEC filings of precision optics manufacturers, ECHA substance restriction updates, FDA 510(k) clearance databases, and METI technology roadmap publications. Bottom-up build-ups of collimator unit demand across laser systems, telecommunications, and medical device applications were triangulated against top-down capital equipment spending forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, application, material composition, and end-user procurement authority, with additional granularity on surface figure tolerance tiers specific to precision optics. CAGRs were derived from fitted growth curves calibrated to semiconductor foundry equipment cycles and defense modernization program timelines. Industry-specific forecast inputs incorporated EUV lithography source conditioning specifications and industrial laser densification patterns in Germany's precision optics corridor.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor capital intensity and stable REACH regulatory frameworks would require recalibration. Forecasts reflect documented assumptions regarding fluorophosphate glass substitute qualification timelines and diamond-turning capacity expansion trajectories. Specific risk factors that could revise projections include accelerated metasurface technology displacement of refractive optics and abrupt ECHA substance list expansions capturing additional coating precursors. Revision becomes warranted when EUV lithography adoption rates or defense procurement allocation thresholds cross modeled sensitivity bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Excimer Lasers for DUV Lithography Market
Optics
Polymeric Optical Fiber Market
Optics
Advanced Optics Market
Optics
North America Optical Imaging Market
Optics
Sports Optics Market
Optics
Excimer Laser Market
Optics
Smart Photochromic Lenses Market
Optics
Optical Liquid Level Sensor Market
Optics
Fiber-Optic Filters Market
Optics
Interchangeable Lens Market
Optics
EUV Pellicle Market
Optics
APAC Smart Glass Market
Optics
Fiber Optic Connectivity Market
Optics
Optical Fiber Raw Material Market
Optics
US Photonics Market
Optics
Tunable Laser Market