
 Asia-Pacific Anti-Blue Ray Myopia Lenses Market | 2026-2036
Asia-Pacific Anti-Blue Ray Myopia Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Anti-Blue Ray Myopia Lenses Market Insights
The Asia-Pacific anti-blue ray myopia lenses market is restructuring around a widening gap between premium ophthalmic-grade coatings and commodity-tinted alternatives. Essilor leverages its proprietary blue-violet light filtering technology to command premium positioning across Chinese optical chains. HOYA Corporation anchors its regional footprint through deep partnerships with Japanese eye clinics and independent optometrists. Mingyue Glasses Co., Ltd. competes aggressively on polycarbonate volume, supplying mid-tier optical stores throughout Southeast Asia.
Anti-blue ray myopia lenses combine dioptric correction with selective wavelength filtration, typically blocking 380-450nm high-energy visible light through multi-layer dielectric coatings or substrate-doped polymers while maintaining luminous transmittance above 90%. These lenses serve the dual purpose of refractive error correction and retinal photoreceptor protection for prolonged digital device users. Progressive lenses capture the largest margin pool as aging digital workers require seamless near-to-intermediate vision zones with integrated blue-light defense. Polycarbonate dominates volume production due to inherent UV and impact resistance, though Trivex gains share among pediatric prescriptions where lightness and safety standards matter most. Online retail channels expand fastest in South Korea and Australia, though eye clinics retain diagnostic credibility and higher attachment rates for premium coatings.
Japan's PMDA and China's NMPA both classify advanced ophthalmic lenses as medical devices, requiring clinical substantiation of myopia progression claims and biocompatibility testing for direct ocular contact materials. Australia's TGA and South Korea's MFDS enforce parallel standards for blue-light blocking efficacy assertions, creating a fragmented compliance landscape for pan-Asia-Pacific manufacturers. The EU MDR's influence persists as a benchmark for quality documentation even absent direct jurisdiction. Stakeholders must monitor evolving pediatric myopia management guidelines from national ophthalmology societies, as clinical endorsement protocols increasingly determine reimbursement eligibility and parental purchase decisions across the region.
Market Dynamics
China's MIIT display emission standards have triggered a regulatory cascade across Asia-Pacific, forcing lens manufacturers to recalibrate coating formulations while simultaneously educating consumers about retinal protection thresholds.
Growth Catalysts
- Screen-time epidemiology:School-aged children in Japan, South Korea, and China now average six-plus hours of daily device exposure, creating irreversible demand for pediatric myopia management solutions.
- MIIT GB standards:China's tightened blue-light emission caps for electronic displays have normalized protective eyewear as essential rather than discretionary across tier-one cities.
- Polycarbonate substrate advances:Improved impact resistance and UV blocking in injection-molded lenses have displaced crown glass in volume ophthalmic applications throughout Southeast Asia.
Market Restraints
- Monomer cost volatility:Thiourethane and Trivex raw material prices fluctuate with petrochemical feedstock indices, compressing margin stability for premium lens fabricators.
- Coating equipment concentration:Vacuum deposition chambers and magnetron sputtering systems concentrate among Japanese and German equipment suppliers, creating capex bottlenecks for regional entrants.
- Clinical substantiation requirements:Japan's PMDA and China's NMPA both mandate longitudinal myopia progression studies, extending product launch timelines by eighteen to thirty-six months.
Strategic Opportunities
- Vietnam and Indonesia expansion:Optical retail penetration remains below fifteen percent in secondary Vietnamese and Indonesian cities, offering first-mover positioning for mid-tier polycarbonate suppliers.
- Tele-optometry integration:Remote refraction platforms paired with direct-to-consumer lens fulfillment are converging in South Korea and Australia, bypassing traditional clinic gatekeepers.
- Pediatric reimbursement frameworks:Japan's Ministry of Health, Labour and Welfare is evaluating myopia control lens inclusion in national health insurance, which would eliminate price sensitivity for guardian purchasers.
Industry Challenges
- Optometrist training deficits:Qualified practitioners capable of fitting progressive addition lenses with integrated blue filtration remain scarce in India's tier-two and tier-three cities.
- Multi-jurisdiction dossier complexity:Manufacturers must compile separate clinical packages for Australia's TGA, South Korea's MFDS, and China's NMPA, fragmenting regulatory affairs resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Anti-Blue Ray Myopia Lenses Market |
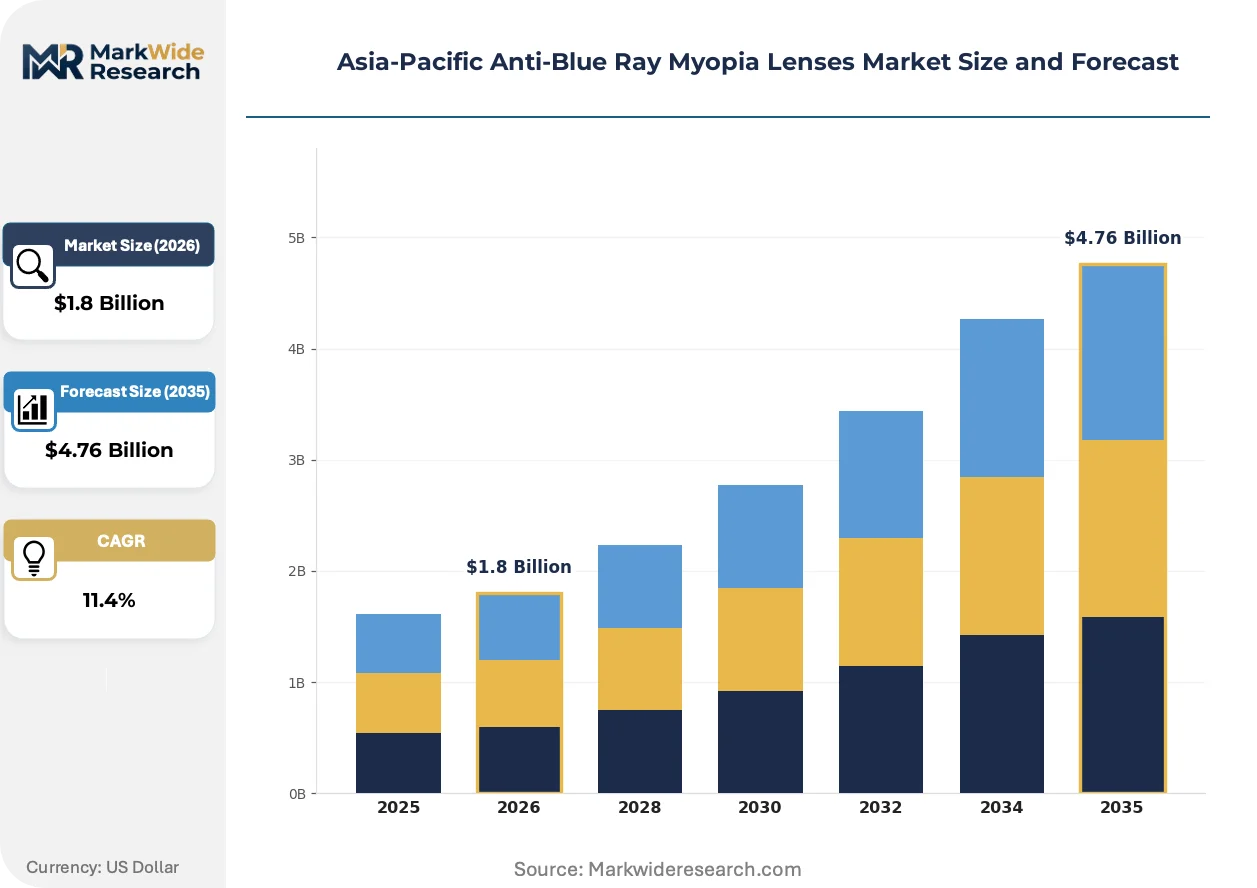
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Vision, Bifocal, Progressive, Wraparound End User: Children, Adults, Seniors, Athletes Material: Polycarbonate, Trivex, Glass, CR-39 Distribution Channel: Optical Stores, Online Retail, Supermarkets, Eye Clinics |
| Companies Covered | Essilor, HOYA Corporation, ZEISS, Seiko, Nikon, Shamir Optical Industry Ltd, Chemiglas Corp., Mingyue Glasses Co., Ltd., Shanghai Conant Optics Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Anti-Blue Ray Myopia Lenses Market Trends and Innovations
Multi-layer dielectric coatings are advancing beyond simple wavelength blocking toward selective photoreceptor protection, while distribution channels fragment between diagnostic credibility and convenience optimization.
Photochromic-anti-blue hybrid substrates are converging with indoor-outdoor lifestyle patterns among aging digital workers in Japan and South Korea. These dual-function materials darken under UV exposure while maintaining static blue-violet filtration indoors. Progressive lens wearers in metropolitan prefectures adopt these formulations fastest, compressing the traditional segmentation between task-specific and all-day eyewear categories.
China's NMPA issued draft guidance in early 2024 requiring randomized controlled trial data for any myopia progression claims on ophthalmic lens labeling. This regulatory tightening eliminates marketing language around "myopia control" for products lacking clinical substantiation. Premium coating providers with existing pediatric trial data gain immediate positioning advantage, while commodity suppliers face reformulation or relabeling costs.
Guardian purchasing behavior across China's tier-one cities now prioritizes clinic-certified lenses over internet-direct alternatives despite price premiums of forty to sixty percent. This preference shift reflects anxiety over childhood myopia progression rather than cost optimization. Japanese and South Korean parents exhibit parallel patterns, though Australia's remote regional populations maintain stronger online channel attachment due to optometrist accessibility constraints.
Asia-Pacific Anti-Blue Ray Myopia Lenses Market Segmentation
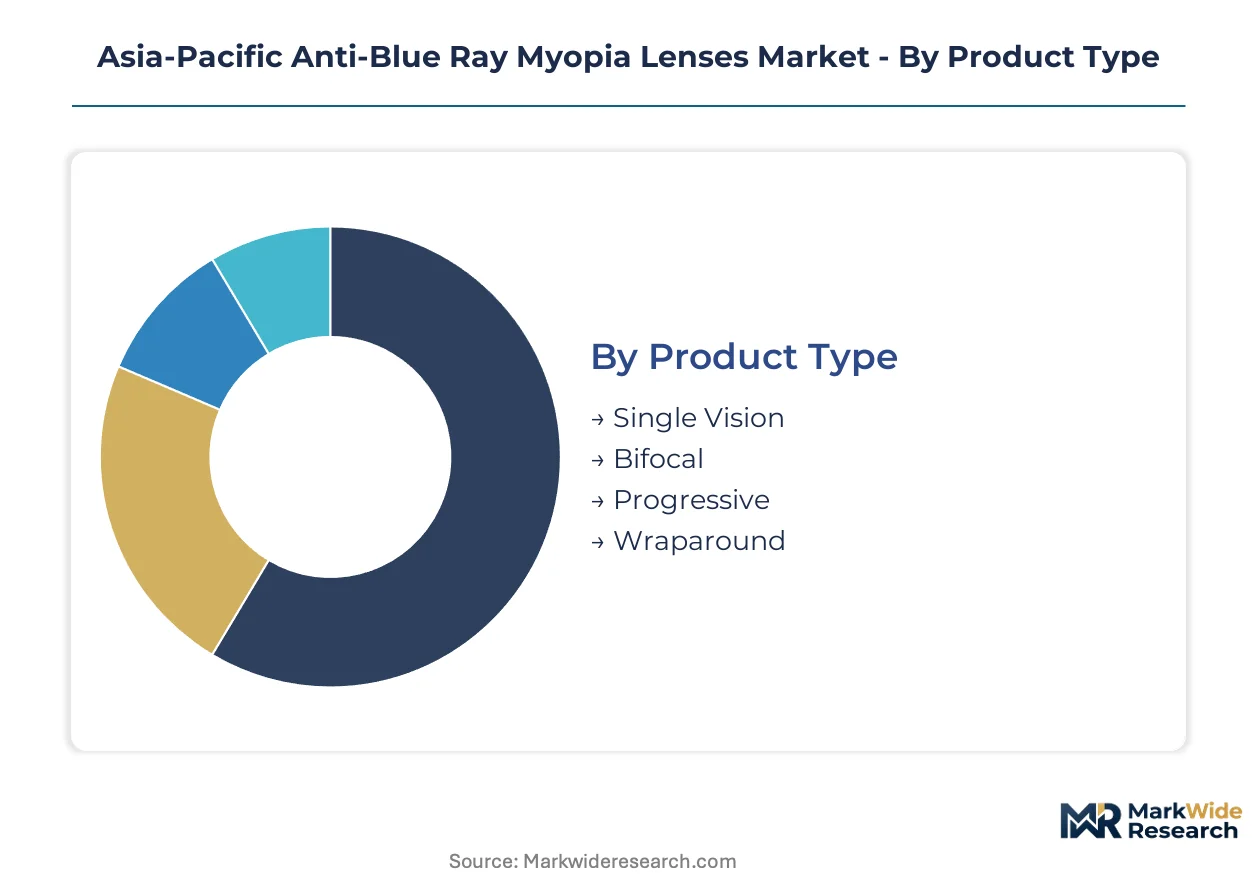
Anti-blue ray myopia lenses segment across four critical dimensions that determine coating complexity, price positioning, and channel strategy. Product architecture dictates whether blue filtration integrates into single-vision correction or multi-focal progressive designs. Material selection balances optical clarity against impact resistance for pediatric versus adult prescriptions.
Product Type:
Integration depth varies sharply: single-vision and bifocal lenses function as standalone refractive corrections, while progressive and wraparound designs embed blue filtration within complex optical geometries requiring precision surfacing.
- Single Vision:Uniform dioptric power across the entire lens surface simplifies blue-coating application through standard vacuum deposition. Demand concentrates in China's tier-one cities where parents prioritize entry-level protection for school-aged children facing MIIT-regulated display emissions.
- Progressive:Graduated power zones from distance to near vision require coating uniformity across complex aspheric curves. Aging digital workers in Japan's metropolitan prefectures drive adoption as presbyopia coincides with prolonged screen exposure.
- Bifocal:Distinct distance and reading segments with visible dividing lines suit cost-sensitive seniors in Southeast Asian secondary cities. Blue filtration applies uniformly despite optical discontinuity.
- Wraparound:Curved base geometries for athletic applications demand flexible coating adhesion and peripheral light management. Australian outdoor workers and recreational athletes generate niche demand.
Single vision leads volumes today; progressive lenses are gaining share fastest among aging Asia-Pacific digital workforces.
End User:
Cost tier stratification separates guardian-funded pediatric prescriptions from self-purchased adult corrections and reimbursement-eligible senior categories.
- Children:Myopia progression management drives the steepest prescription growth. China's NMPA clinical substantiation requirements now govern marketing claims, favoring suppliers with longitudinal trial data.
- Adults:Workplace digital eye strain creates replacement-cycle demand across South Korean and Australian white-collar cohorts. Tele-optometry platforms accelerate direct-to-consumer fulfillment.
- Seniors:Presbyopia-plus-blue-light concerns concentrate in Japan's aging demographic. National health insurance evaluation for myopia control lenses would eliminate price sensitivity.
- Athletes:Impact-resistant polycarbonate wraparounds with integrated filtration serve cricket players in India and cyclists in Australia. Volume remains constrained by specialized fitting requirements.
Children's prescriptions dominate absolute growth; adult segments maintain the largest installed base.
Material:
Supply concentration for thiourethane monomers and Trivex polymers concentrates among Japanese and German chemical suppliers, fragmenting regional manufacturing autonomy.
- Polycarbonate:Injection-molded lenses with inherent UV and impact resistance capture volume production. Southeast Asian optical retail chains source aggressively from Chinese mid-tier fabricators.
- Trivex:Lightweight, shatter-resistant substrates meet pediatric safety standards. Premium positioning in Japanese eye clinics reflects material cost premiums over polycarbonate.
- Glass:Crown glass persists in high-aberration prescriptions requiring precise surfacing. Declining share throughout the region as polycarbonate optical quality improves.
- CR-39:Allyl diglycol carbonate offers superior optical clarity at lower impact resistance. Niche adoption in fashion-forward Australian and South Korean adult segments.
Polycarbonate commands volume leadership; Trivex climbs fastest among safety-conscious pediatric prescribers.
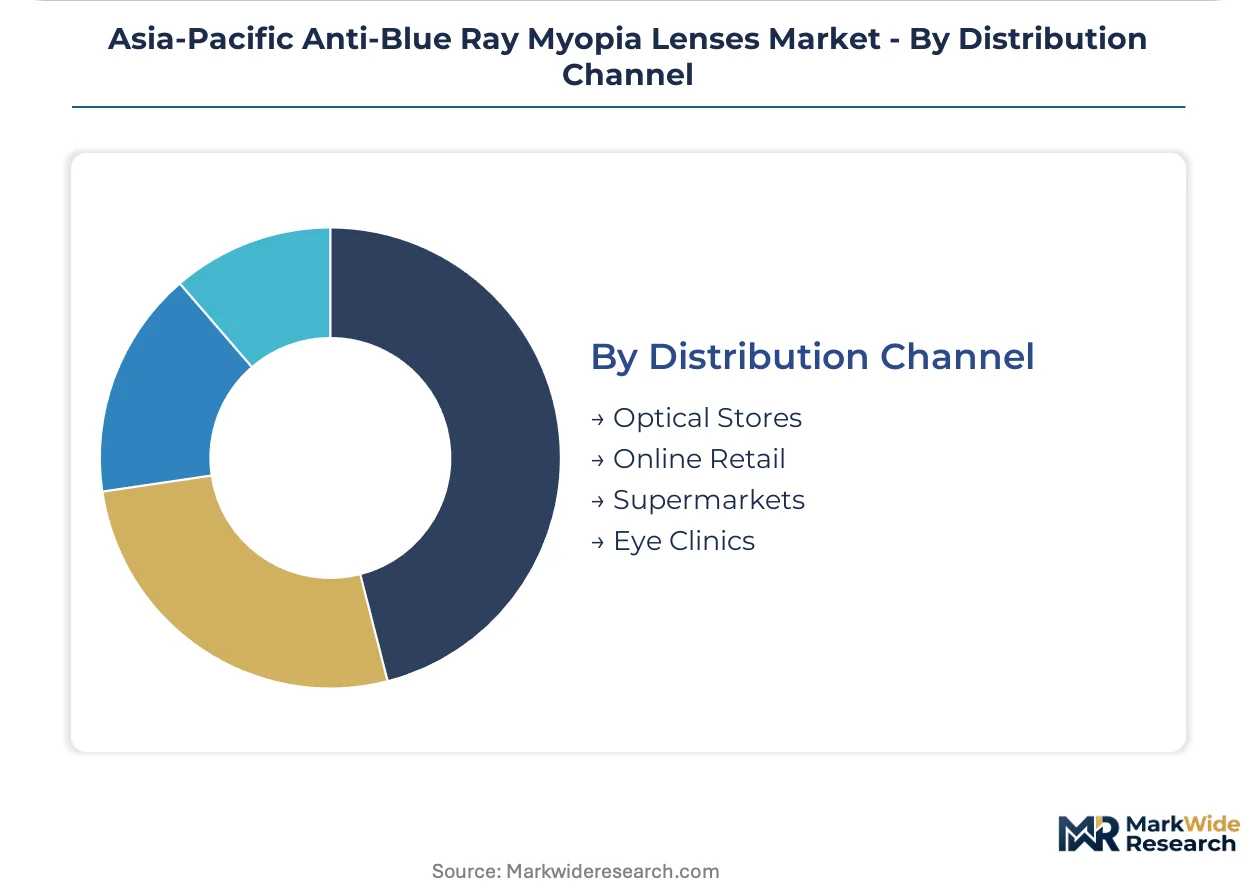
Distribution Channel:
Customer type fragmentation separates diagnostic-credible clinical channels from convenience-optimized retail and direct-to-consumer platforms.
- Optical Stores:Independent and chain retailers throughout Vietnam and Indonesia offer first-mover positioning as penetration remains below fifteen percent in secondary cities. Mid-tier polycarbonate suppliers compete on volume.
- Eye Clinics:Diagnostic credibility drives premium coating attachment rates. Guardian purchasing behavior across China's tier-one cities now prioritizes clinic-certified lenses despite forty to sixty percent price premiums.
- Online Retail:South Korean and Australian consumers lead remote refraction adoption. Australia's regional populations maintain stronger channel attachment due to optometrist accessibility constraints.
- Supermarkets:Mass-market reading glasses with basic tinting serve price-sensitive seniors. Blue filtration claims often lack clinical substantiation under TGA and MFDS enforcement.
Eye clinics capture premium value; online retail expands most quickly in digitally mature markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optometrist density and manufacturing infrastructure concentrate demand across five Asia-Pacific markets, with regulatory frameworks diverging sharply between medical-device jurisdictions and consumer-goods regimes.
China
School-aged screen-time averaging six-plus hours daily drives pediatric prescription volumes in Beijing, Shanghai, and Shenzhen. MIIT tightened GB standards for blue-light emission from electronic displays in 2023, normalizing protective eyewear as essential in tier-one cities. Yangtze River Delta optical clusters supply polycarbonate substrates to mid-tier retail chains throughout Southeast Asia.
Japan
Aging digital workers with presbyopia-plus-blue-light concerns dominate progressive lens demand in Tokyo, Osaka, and Nagoya metropolitan prefectures. PMDA classifies advanced ophthalmic lenses as medical devices, mandating longitudinal myopia progression studies that extend product launches by eighteen to thirty-six months. Kanto region eye clinics anchor premium coating attachment rates through diagnostic credibility.
South Korea
White-collar workplace digital eye strain creates replacement-cycle demand across Seoul Capital Area white-collar cohorts. MFDS enforces parallel standards for blue-light blocking efficacy assertions alongside clinical substantiation requirements. Tele-optometry platforms paired with direct-to-consumer lens fulfillment converge fastest here, bypassing traditional clinic gatekeepers.
Australia
Remote regional populations maintain stronger online retail channel attachment due to optometrist accessibility constraints in Queensland and Western Australia. TGA enforces standards for blue-light blocking efficacy claims, creating compliance overlap with EU MDR documentation benchmarks. Outdoor workers and recreational athletes generate niche wraparound lens demand.
Vietnam
Optical retail penetration remains below fifteen percent in secondary cities like Da Nang and Can Tho, offering first-mover positioning for mid-tier polycarbonate suppliers. The country's national pharmaceutical regulator applies less stringent medical-device classification than PMDA or NMPA, compressing market entry timelines. Ho Chi Minh City retail chains source aggressively from Chinese fabricators.
Asia-Pacific Anti-Blue Ray Myopia Lenses Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across coating formulation and substrate fabrication. The market structures around three tiers: multinational ophthalmic giants with proprietary dielectric technologies, regional mid-volume fabricators serving price-sensitive retail chains, and specialized pediatric safety suppliers. Strategic moves concentrate on clinical trial investments for regulatory substantiation and tele-optometry platform partnerships for channel bypass.
Among Japanese and European multinationals, HOYA Corporation and ZEISS exemplify the premium ophthalmic archetype through deep clinic partnerships and proprietary coating portfolios. Essilor occupies a parallel position with blue-violet light filtering technology commanding premium positioning across Chinese optical chains. Mingyue Glasses Co., Ltd. represents the mid-tier volume fabricator archetype, supplying polycarbonate lenses throughout Southeast Asian retail networks. Shanghai Conant Optics Co., Ltd. sits within the same tier, competing on injection-molded substrate scale for China's domestic market.
| Leading Market Players |
|---|
| Essilor |
| HOYA Corporation |
| ZEISS |
| Seiko |
| Nikon |
| Shamir Optical Industry Ltd |
| Chemiglas Corp. |
| Mingyue Glasses Co., Ltd. |
| Shanghai Conant Optics Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Captive coating formulation capabilities in Japanese and German equipment suppliers anchor both supply security and premium pricing power for multinational ophthalmic giants serving Asia-Pacific markets. This upstream control over vacuum deposition chambers and magnetron sputtering systems enables tiered margin extraction across single-vision, progressive, and pediatric safety lens categories.
Pricing Analysis
Bundled clinic-certified lens-and-coating services command forty to sixty percent premiums over unbundled internet-direct alternatives in China's tier-one cities. Three-tier pricing structure across premium ophthalmic-grade coatings, mid-tier polycarbonate substrates, and economy-tinted alternatives reflects certification grade and diagnostic credibility differentiation. Pricing pressure stems from thiourethane monomer cost volatility tied to petrochemical feedstock indices. Guardian purchasers exhibit lowest price sensitivity for pediatric prescriptions, while mass-market seniors in Southeast Asian secondary cities prioritize economy tiers.
Supply Chain Analysis
Direct-to-eye-clinic channels handle premium progressive and pediatric safety demand, while optical retail chains and tele-optometry platforms serve volume single-vision segments. Raw material concentration in Japan and Germany for thiourethane monomers and Trivex polymers creates single-source vulnerability for regional mid-tier fabricators. Polycarbonate substrate fabrication clusters in China's Yangtze River Delta feed Southeast Asian retail networks. Distribution runs through diagnostic-credible eye clinics in Japan's Kanto region, independent optical stores throughout Vietnam and Indonesia, and direct-to-consumer platforms in South Korea and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific anti-blue ray myopia lenses market functions as a stable compounder where regulatory tightening around clinical substantiation continuously elevates barriers and consolidates share among trial-capable incumbents.
For Market Incumbents: Anchor defensive positioning through longitudinal pediatric myopia progression studies that satisfy China's NMPA and Japan's PMDA requirements, creating eighteen-to-thirty-six-month launch delays for emerging competitors. Deepen clinic partnership networks in metropolitan prefectures to maintain diagnostic-credible channel control against tele-optometry disintermediation. Prioritize backward integration into coating equipment capabilities to reduce capex bottlenecks from Japanese and German suppliers.
For New Entrants and Emerging Players: Capture white-space opportunity in Vietnam and Indonesia's secondary cities where optical retail penetration remains below fifteen percent, enabling first-mover positioning without direct incumbent confrontation. Target mid-tier polycarbonate volume supply to price-sensitive Southeast Asian retail chains lacking access to premium coating portfolios. Pursue tele-optometry platform partnerships in South Korea and Australia to bypass traditional clinic gatekeepers.
For Investors and Strategic Acquirers: Consolidation pressure builds where clinical trial infrastructure and multi-jurisdiction regulatory dossier capabilities concentrate among a narrowing set of multinational ophthalmic giants. The market supports long-term compounder framing given irreversible screen-time epidemiology and tightening pediatric myopia management standards. Target acquisition profiles should emphasize regional mid-tier fabricators with established Southeast Asian retail relationships and latent coating upgrade potential. Monitor Japan's Ministry of Health, Labour and Welfare reimbursement evaluations as a signal for eliminating price sensitivity in guardian-funded pediatric segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Investment | Longitudinal myopia progression studies satisfy NMPA and PMDA substantiation mandates for pediatric claims. |
| Tele-Optometry Partnership | Remote refraction platforms in South Korea and Australia bypass traditional clinic distribution gatekeepers. |
| Backward Integration | In-house coating equipment production reduces dependency on Japanese and German vacuum deposition suppliers. |
| Geographic Expansion | First-mover positioning in Vietnam and Indonesia's underpenetrated secondary cities captures volume growth. |
| Regulatory Dossier Harmonization | Unified clinical packages for TGA, MFDS, and NMPA reduce fragmented compliance resource allocation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ophthalmic lens manufacturing executives, regulatory affairs specialists at NMPA and PMDA, eye clinic optometrists, and optical retail procurement managers with secondary validation through MIIT GB standard filings, PMDA medical device registration databases, and Asia-Pacific customs trade records. Bottom-up prescription volume modeling and top-down market sizing triangulated across these sources.
Comparable-period anchoring linked projection assumptions to historical reference data across the analysis window, with segmentation modeling across product architecture, material substrate, end-user cohort, and distribution channel dimensions. CAGRs derived from fitted growth curves incorporating screen-time epidemiology trajectories, regulatory timeline impacts, and channel penetration saturation curves. Forecast inputs included polycarbonate substrate cost indices and tele-optometry adoption velocity metrics.
Underlying measurement precision varies by segment; premium ophthalmic-grade coatings and clinic-certified distribution channels carry tighter precision than commodity-tinted alternatives and mass-market retail. Forecasts reflect documented assumptions about regulatory substantiation timelines and reimbursement policy evolution. Periodic stress-testing of base assumptions is recommended given pediatric myopia management guideline revisions and raw material cost volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Plastic Lens Market
Optics
Excimer Laser Market
Optics
Fiber Optic Receiver Market
Optics
Global High Purity Quartz Glass Market
Optics
Electro Optics Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Fixed Focal Length Lenses Market
Optics
Beam Expanders Market
Optics
Optical Gratings Market
Optics
Global Nanophotonics Market
Optics
India Laser Market
Optics
Fiber-Optic Filters Market
Optics
Quartz Glass Market
Optics
Liquid Crystal on Silicon Market
Optics
Optical Liquid Level Sensor Market
Optics
Optical Lens for Mobile Phone Market