
 Spectroscopy Equipment and Supplies Market | 2026-2036
Spectroscopy Equipment and Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Spectroscopy Equipment and Supplies Market Analytics
German optical engineering clusters and Japanese precision manufacturers is consolidating around high-end mass spectrometry supply chains. Thermo Fisher Scientific leverages vertical integration across ion source manufacturing and consumables distribution to sustain pricing power in pharmaceutical accounts. Bruker anchors its position through R&D intensity in nuclear magnetic resonance and X-ray diffraction adjacent technologies. Shimadzu Corporation dominates Asian distribution channels for chromatography-mass spectrometry hybrid systems.
Spectroscopy equipment and supplies encompass instruments that measure electromagnetic radiation absorption, emission, or scattering to identify molecular composition, typically operating across ultraviolet through infrared wavelengths with resolution thresholds reaching picometer precision. These systems serve pharmaceutical quality control, environmental contaminant detection, and materials characterization by converting optical signals into quantitative chemical data. Mass spectrometers command the deepest margin pools due to recurring consumables demand and service contract attachment rates. Fourier Transform infrared systems retain mature installed bases in academic settings while dispersive UV-Vis instruments face price compression from Asian competitors. Hybrid technology platforms represent the fastest structural expansion as laboratories consolidate multiple analytical modalities into single workflow stations.
FDA 21 CFR Part 11 electronic records requirements and EMA GMP Annex 15 qualification standards shape instrument validation protocols and software compliance costs for vendors serving regulated industries. REACH chemical registration mandates in Europe and EPA Method compliance in the United States drive replacement cycles for environmental monitoring deployments. Stakeholders must monitor evolving data integrity enforcement patterns and regional certification reciprocity agreements to anticipate capital equipment procurement timing across multinational laboratory networks.
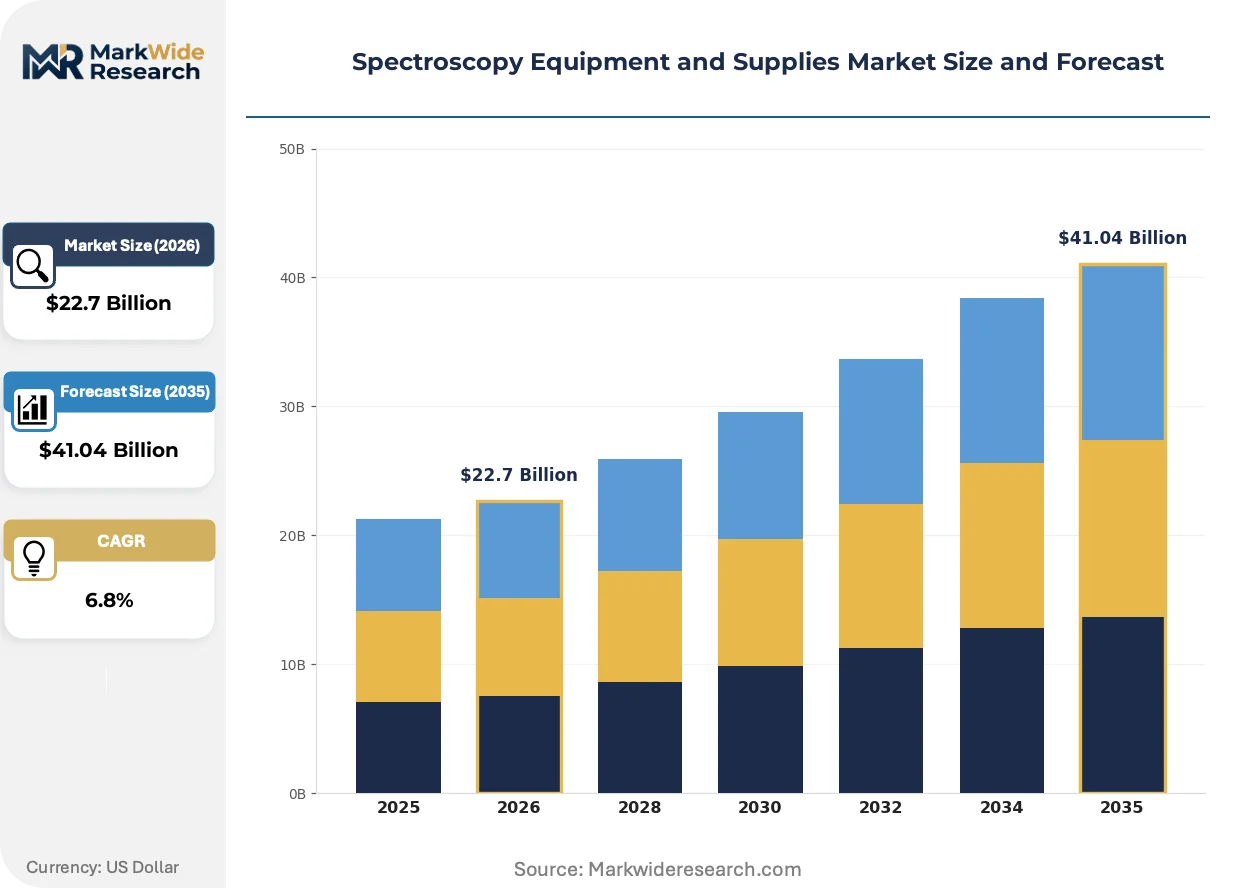
Market Dynamics
Hybrid mass spectrometry platforms are compressing capital expenditure cycles as pharmaceutical laboratories consolidate multiple analytical modalities into single workflow stations, forcing incumbents to defend service contract attach rates through software lock-in strategies.
Growth Catalysts
- FDA 21 CFR Part 11 mandates:Electronic records requirements in pharmaceutical manufacturing are accelerating instrument replacement cycles as quality control labs upgrade validation protocols.
- Biologics manufacturing expansion:Protein characterization demands are pulling high-resolution mass spectrometry into contract development and manufacturing organization facilities.
- China's NMPA GMP enforcement:Domestic pharmaceutical producers are expanding analytical instrument fleets to meet purity documentation standards for export markets.
Market Restraints
- Helium supply volatility:Gas chromatography-mass spectrometry systems face input cost pressure from concentrated noble gas sourcing in Qatar and Algeria.
- Academic budget stagnation:Fourier Transform infrared installed bases in university settings extend replacement timelines beyond typical depreciation schedules.
- Portable Raman substitution:Handheld molecular identification devices are capturing routine field screening applications previously served by benchtop systems.
Strategic Opportunities
- India CDMO buildout:Contract research organizations in Hyderabad and Bangalore are underpenetrated for high-end nuclear magnetic resonance capacity.
- EPA Method modernization:Environmental monitoring agencies are mandating triple quadrupole mass spectrometry for emerging contaminant detection protocols.
- Cloud-native instrument control:Remote diagnostics and predictive maintenance platforms are opening subscription revenue streams independent of hardware sales.
Industry Challenges
- Spectroscopist talent scarcity:Specialized PhD-level expertise in ion optics and signal processing is concentrating in German and Swiss industrial clusters.
- Legacy data migration:Decades of proprietary file formats in chromatography data systems create integration friction with modern laboratory information management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spectroscopy Equipment and Supplies Market |
| Market Size in 2026 | $22.7 Billion |
| Market Size in 2035 | $41.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mass Spectrometers, UV-Vis Spectrophotometers, NIR Spectrometers, FTIR Spectrometers Application: Pharmaceutical Analysis, Environmental Monitoring, Food Testing, Biochemical Research End User: Research Laboratories, Academic Institutions, Pharmaceutical Companies, Government Agencies Technology: Dispersive, Fourier Transform, Hybrid, Non-Destructive |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Bruker, PerkinElmer, Shimadzu Corporation, Waters, JEOL Ltd., Rigaku Corporation, Hitachi High-Tech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spectroscopy Equipment and Supplies Market Evolving Landscape
Artificial intelligence is embedding into spectral interpretation workflows, compressing analysis timelines while raising the bar for vendor software differentiation. Three developments are restructuring competitive positioning.
Orbitrap-based high-resolution mass spectrometry is unifying qualitative identification and quantitative measurement in single acquisition runs. Pharmaceutical quality control laboratories in the United States and Germany are adopting these platforms to eliminate sequential method transfers between discovery and manufacturing stages. This convergence is compressing the addressable market for standalone time-of-flight systems by collapsing two instrument categories into one capital purchase.
REACH chemical registration mandates in Europe are mandating analytical data packages for substance volumes above one ton annually. Industrial chemical producers are deploying inductively coupled plasma mass spectrometry for elemental impurity profiling to satisfy ECHA documentation requirements. Contract testing laboratories in Germany and the Netherlands are expanding capacity fastest to capture this compliance-driven demand.
Service unbundling is fragmenting traditional instrument procurement patterns. Academic and mid-sized pharmaceutical buyers are separating hardware acquisition from validation, training, and maintenance contracts, sourcing these elements through third-party specialists. This disintermediation is most visible in United States university systems where centralized procurement offices now negotiate multi-vendor service frameworks independent of original equipment manufacturer relationships.
Spectroscopy Equipment and Supplies Market Segmentation
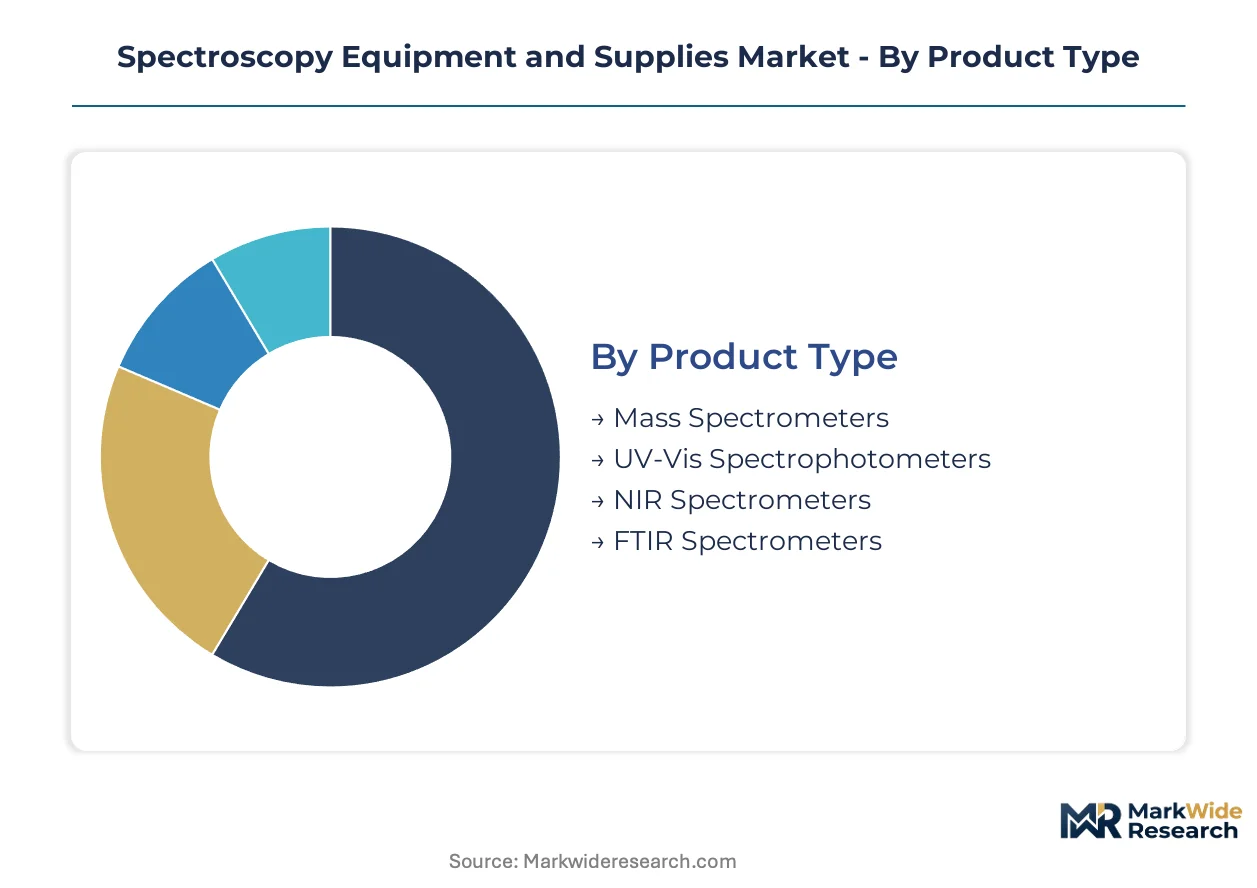
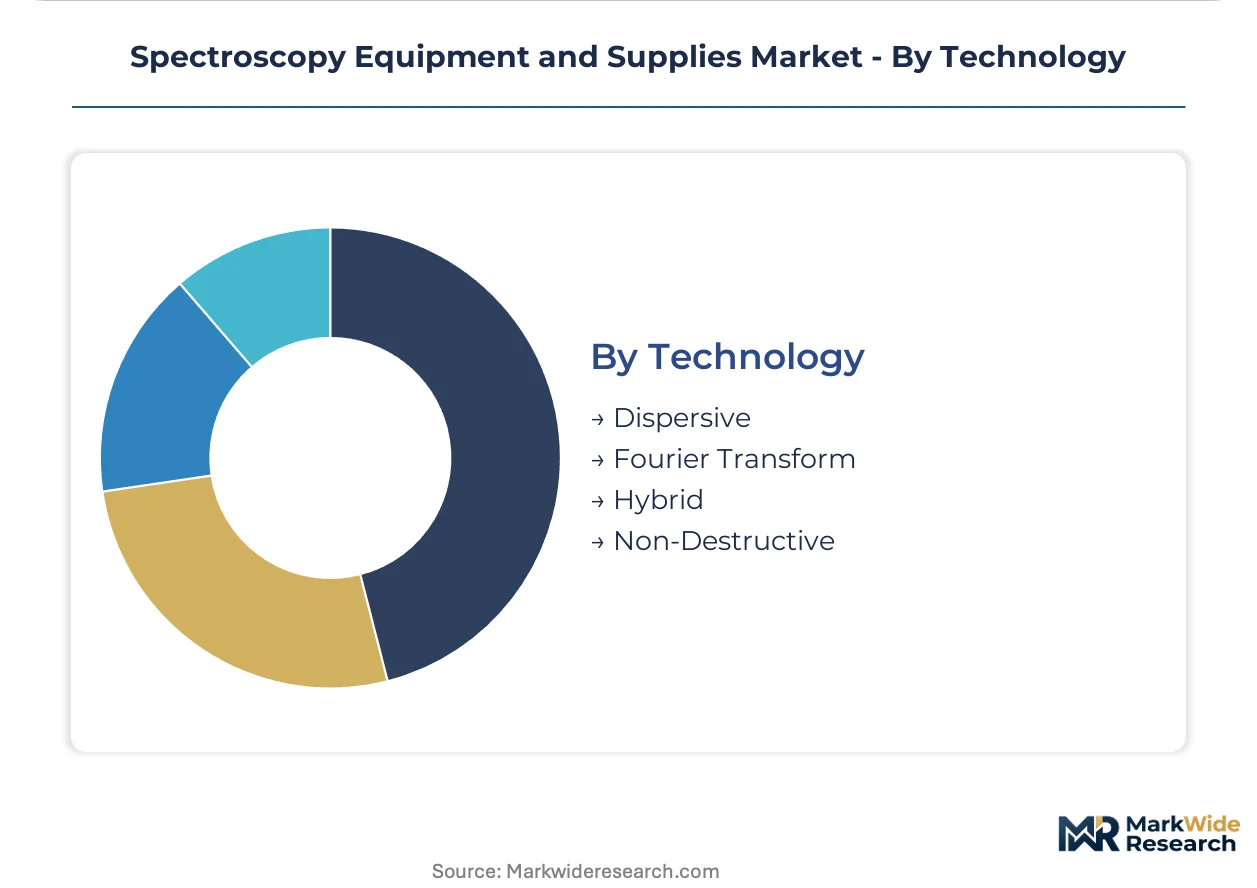
Spectroscopy equipment segmentation reveals distinct capital intensity patterns across technology platforms. Pharmaceutical procurement cycles and regulatory compliance requirements reshape demand concentration within each category.
Product Type:
Capital intensity varies sharply across instrument categories, with ion optics manufacturing and vacuum system engineering demanding the deepest upfront investment.
- Mass Spectrometers:These systems integrate ion sources, mass analyzers, and detectors operating under high vacuum conditions. Pharmaceutical quality control laboratories in the United States and Germany are absorbing capacity to meet FDA 21 CFR Part 11 and EMA GMP Annex 15 validation requirements. Recurring consumables demand and service contract attachment rates sustain vendor margin pools.
- UV-Vis Spectrophotometers:Instruments measuring ultraviolet and visible light absorption through dispersive or diode-array architectures. Academic institutions across India and China extend replacement timelines amid budget stagnation, compressing pricing power for established suppliers.
- NIR Spectrometers:Near-infrared systems enable rapid, non-destructive composition analysis for agricultural and pharmaceutical applications.
- FTIR Spectrometers:Fourier Transform infrared platforms retain mature installed bases in university settings with extended depreciation schedules.
Mass spectrometers absorb the bulk of installed capacity; NIR spectrometers are expanding most quickly.
Application:
Regulatory enforcement intensity determines segment profitability, with compliance-driven replacement cycles shortening in heavily regulated domains.
- Pharmaceutical Analysis:Purity verification, impurity profiling, and stability testing for small-molecule and biologic drug products. United States contract development and manufacturing organizations are pulling high-resolution mass spectrometry into quality control workflows to satisfy FDA documentation standards.
- Environmental Monitoring:Detection of contaminants in air, water, and soil matrices. EPA Method modernization mandates in the United States are forcing triple quadrupole mass spectrometry adoption for emerging pollutant protocols.
- Food Testing:Authenticity verification, adulterant detection, and nutritional labeling compliance.
- Biochemical Research:Protein characterization, metabolomics, and structural biology investigations.
Pharmaceutical analysis commands the largest revenue share; environmental monitoring is climbing the fastest.
End User:
Procurement sophistication separates segments, with centralized purchasing offices reshaping vendor relationships in institutional accounts.
- Research Laboratories:Commercial and government facilities conducting applied and fundamental investigations. Germany's optical engineering clusters and Swiss precision manufacturers concentrate specialized PhD-level spectroscopist talent, constraining capacity expansion.
- Academic Institutions:Universities and colleges with extended equipment depreciation schedules. United States university systems are unbundling hardware acquisition from validation and maintenance contracts, sourcing services through third-party specialists.
- Pharmaceutical Companies:Drug manufacturers operating under FDA, EMA, and NMPA GMP enforcement.
- Government Agencies:Environmental protection, food safety, and forensic laboratories.
Pharmaceutical companies deploy the highest-value instrument fleets; research laboratories are gaining share fastest.
Technology:
Platform architecture determines workflow consolidation potential, with hybrid systems commanding premium positioning.
- Hybrid:Integrated platforms combining multiple analytical modalities into single workflow stations. Pharmaceutical laboratories in the United States and Germany are adopting hybrid mass spectrometry to eliminate sequential method transfers between discovery and manufacturing stages.
- Fourier Transform:Interferometer-based signal processing enabling high-resolution spectral acquisition. Mature installed bases in academic settings face extended replacement cycles.
- Dispersive:Wavelength-separation through prisms or gratings, dominant in UV-Vis configurations.
- Non-Destructive:Raman and NIR techniques preserving sample integrity for field and at-line deployment.
Fourier Transform technology retains the largest installed base; hybrid platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium sourcing from Qatar and Algeria feeds gas chromatography-mass spectrometry operations across pharmaceutical manufacturing clusters. Instrument procurement concentrates where FDA, EMA, and NMPA enforcement tightens purity documentation standards.
United States
Contract development and manufacturing organizations in Massachusetts and North Carolina are absorbing high-resolution mass spectrometry capacity. EPA Method modernization mandates triple quadrupole adoption for emerging contaminant detection. Boston's biopharma corridor concentrates protein characterization demand from biologics manufacturers.
Germany
Industrial chemical producers in Ludwigshafen and Leverkusen deploy inductively coupled plasma mass spectrometry for REACH compliance. ECHA documentation requirements for substance volumes above one ton annually drive replacement cycles. Contract testing laboratories in Munich and Hamburg expand fastest to capture compliance-driven demand.
China
Domestic pharmaceutical producers in Jiangsu and Zhejiang provinces expand analytical instrument fleets. NMPA GMP enforcement tightens purity documentation standards for export markets. Shanghai's Pudong district hosts the fastest-growing concentration of chromatography-mass spectrometry hybrid system deployments.
Japan
Precision manufacturers in Kyoto and Osaka prefectures consolidate around high-end mass spectrometry supply chains. METI industrial standards shape instrument validation protocols for regulated industries. Tokyo-Yokohama corridor concentrates specialized PhD-level spectroscopist talent in optical engineering clusters.
India
Contract research organizations in Hyderabad and Bangalore are underpenetrated for high-end nuclear magnetic resonance capacity. CDSCO quality enforcement accelerates instrument replacement cycles in formulation facilities. Gujarat's pharmaceutical manufacturing belt attracts capital equipment procurement from export-oriented generics producers.
Spectroscopy Equipment and Supplies Market Competitive Landscape
Global majors compete with regional champions across ion source manufacturing and consumables distribution networks. Market structure consolidates around vertically integrated conglomerates and specialized component suppliers. Three archetypes dominate: full-stack instrument builders, consumables-focused specialists, and software-anchored platform vendors. Competitive moves concentrate on service contract bundling and predictive maintenance platform development.
Among US-based conglomerates, Thermo Fisher Scientific and Agilent Technologies exemplify full-stack instrument builders with captive consumables revenue streams. Bruker anchors the European precision engineering tier through R&D intensity in adjacent analytical technologies. Shimadzu Corporation represents Asian distribution channel dominance for hybrid chromatography-mass spectrometry systems.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Bruker |
| PerkinElmer |
| Shimadzu Corporation |
| Waters |
| JEOL Ltd. |
| Rigaku Corporation |
| Hitachi High-Tech Corporation |
| Others |
Value Network & Pricing Analysis
Performance-tier bifurcation between FDA-validated pharmaceutical-grade systems and commodity academic instruments manifests in both pricing architecture and supply chain configurations. Premium vendors capture margin through captive consumables and service lock-in, while Asian manufacturers compress UV-Vis pricing through diode-array standardization.
Pricing Analysis
Warranty and validation-bundling separates pharmaceutical procurement from academic unbundling trends. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification requirements, ion optics precision grades, and software compliance depth. Cost compression in dispersive UV-Vis runs through Chinese diode-array competition. Contract development and manufacturing organizations show lowest price sensitivity; Indian universities exhibit highest.
Supply Chain Analysis
Dual-sourcing mandates from FDA-inspected pharmaceutical buyers require qualified secondary suppliers for vacuum pumps and ion source filaments. Component manufacturing concentrates in Germany, Japan, and Massachusetts. High-purity helium draws from Qatar and Algeria; rare-earth magnets for NMR rest on Chinese processing. Single-source vulnerability sits with noble gas logistics. Distribution runs through authorized service organizations with captive spare parts inventories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA 21 CFR Part 11 validation requirements erect barrier-to-entry moats for instrument vendors serving regulated pharmaceutical accounts.
For Market Incumbents: Anticipate portable Raman substitution in field screening applications by embedding predictive maintenance platforms into service contracts. Deepen backward integration into ion source manufacturing to defend consumables attach rates against third-party specialists. Software lock-in through chromatography data system integration represents the critical defensive lever.
For New Entrants and Emerging Players: Mid-tier Indian contract research organizations in Hyderabad and Bangalore present the most penetrable buyer archetype, given underpenetrated high-end nuclear magnetic resonance capacity. Cloud-native instrument control platforms offer a subscription-based go-to-market angle independent of hardware capital cycles.
For Investors and Strategic Acquirers: Re-rating potential sits with consumables-focused specialists given recurring revenue visibility and service contract attachment rates. Long-term viability favors vendors with software-anchored platform architectures over pure hardware builders. Watch EPA Method modernization timelines as inflection indicators for environmental monitoring equipment demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Service Contract Unbundling Response | Third-party validation specialists capture margin from OEM service relationships in U.S. university systems. |
| Predictive Maintenance Platform Launch | Remote diagnostics subscriptions open recurring revenue streams independent of instrument replacement cycles. |
| Hybrid Technology R&D Intensification | Orbitrap-based platforms collapse time-of-flight and quadrupole categories into single capital purchases. |
| Helium Recovery System Integration | Closed-loop noble gas recycling mitigates supply volatility from Qatar-Algeria sourcing concentration. |
| India CDMO Channel Expansion | Hyderabad and Bangalore contract research organizations absorb high-resolution mass spectrometry capacity fastest. |
Research Methodology
SEC 10-K filings, EMA regulatory submissions, and customs trade data formed the secondary backbone for vendor revenue triangulation. Primary interviews with pharmaceutical quality control directors, analytical instrument procurement managers, and aftermarket service heads validated replacement cycle assumptions. Bottom-up and top-down approaches cross-checked segment sizing across mass spectrometry, UV-Vis, and FTIR technology platforms.
Bottom-up modeling aggregated instrument unit economics with consumables attach rates and service contract penetration across the projection horizon. Segmentation dimensions included technology platform, application vertical, end-user sophistication tier, and regional regulatory enforcement intensity. CAGRs derived from historical replacement patterns and compliance-driven procurement acceleration. Industry-specific inputs incorporated helium supply volatility indices and FDA inspection citation trends.
Revisions become necessary when NMPA GMP enforcement timelines, EPA Method modernization schedules, or helium supply disruptions materialize outside modeled scenarios. Deviation in biologics manufacturing capital expenditure cycles would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
Battery Analyzer Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Trace Chemical Detector Market
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
Asia-Pacific Handheld Spectrum Analyzer Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
Conductivity Analyzers Market
Analytical Instruments
Handheld XRF Spectrometer Market
Analytical Instruments
Atomic Force Microscopes (AFM) Market
Analytical Instruments
Global Spectroscopy Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Automated Microscopy Market
Analytical Instruments
Analytical Balance Market
Analytical Instruments
Handheld Laser Measuring Instrument Market