
 Glass Scintillator Market | 2026-2036
Glass Scintillator Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Scintillator Market Analysis
REACH compliance is expanding the cost-of-entry calculus for European suppliers of radiation detection materials. Saint-Gobain Ceramics & Plastics leverages its fused silica manufacturing scale to dominate medical imaging supply chains. Hitachi Metals, Ltd. anchors its position through backward integration into rare-earth dopant sourcing. Hamamatsu Photonics K.K. specializes in photomultiplier tube pairing with custom glass formulations.
Glass scintillators are transparent ceramic or vitreous materials doped with activator ions such as cerium or thallium, converting ionizing radiation into visible photons through luminescence for detection and measurement systems. The material typically achieves light yields of thousands of photons per MeV and decay times under 100 nanoseconds, enabling real-time radiation monitoring in medical and security applications. Lead glass formulations command the largest revenue share in nuclear medicine shielding applications, while lithium glass variants are displacing legacy materials in neutron detection for waste management due to their thermal neutron capture efficiency. Silicon photomultiplier technology integration is reshaping detector architectures across research laboratory end users.
The FDA, EPA, and NRC collectively govern radiation detection device performance standards, calibration protocols, and environmental monitoring requirements in the United States, creating layered compliance obligations for manufacturers. EMA medical device regulations and CE marking under the EU MDR impose additional clinical validation burdens on scintillator suppliers serving European hospital systems. Stakeholders must monitor evolving neutron detection specifications from the IAEA and national nuclear regulators as fusion energy research expands its procurement footprint.
Market Dynamics
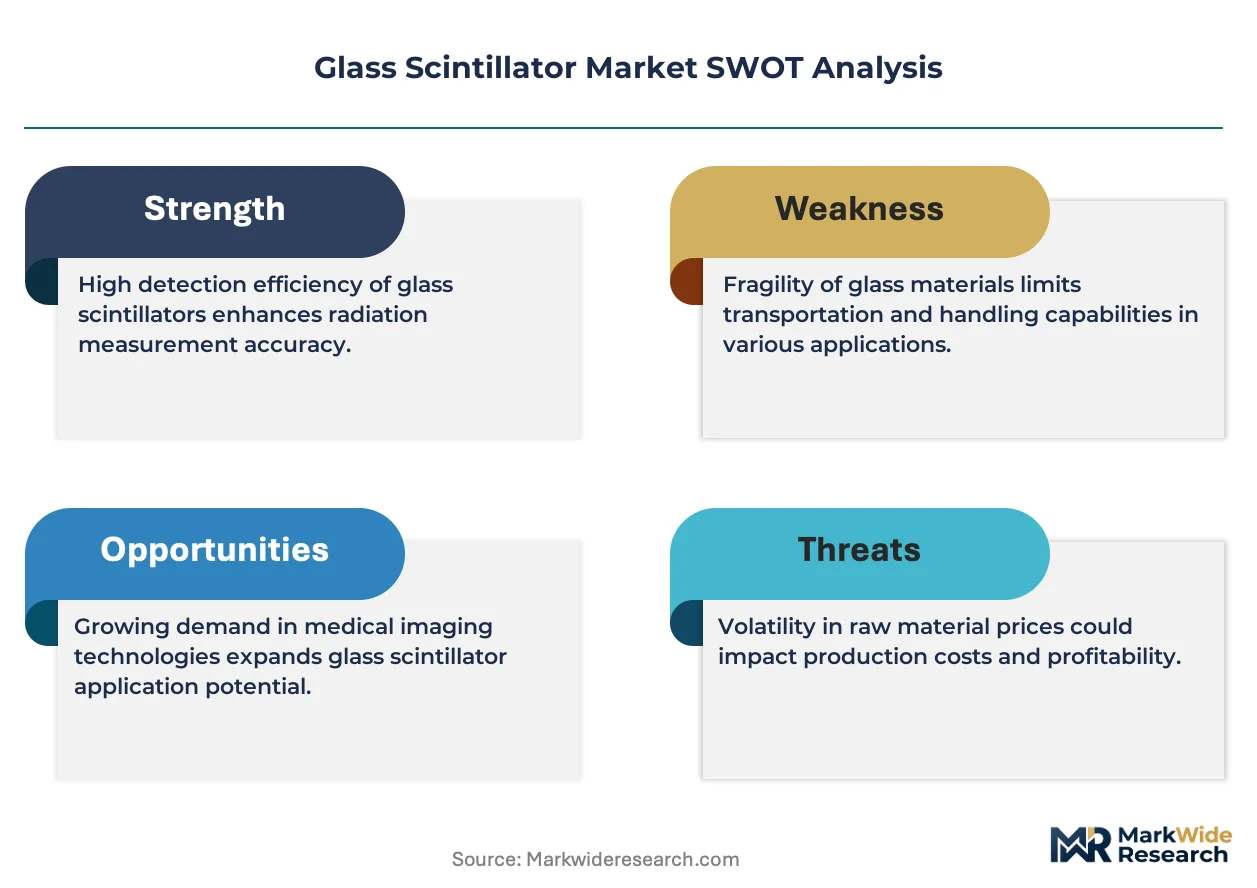
Silicon photomultiplier technology is compressing detector architectures and forcing glass scintillator suppliers to reformulate optical coupling interfaces for solid-state readout systems. This transition is redistributing value from traditional photomultiplier tube pairings toward integrated scintillator-SiPM modules.
Growth Catalysts
- Fusion Energy Research Expansion:IAEA neutron detection specifications are tightening procurement standards for deuterium-tritium plasma diagnostics, pulling lithium-doped glass formulations into next-generation tokamak instrumentation.
- EU MDR Clinical Validation:CE marking requirements under the EU MDR are consolidating supplier qualification pools for European nuclear medicine departments, favoring established glass scintillator manufacturers with documented biocompatibility trails.
- Germany's Precision Optics Cluster:Concentrated demand from Jena and Mainz is anchoring specialized production capacity for high-homogeneity cerium-doped formulations used in gamma camera calibration standards.
Market Restraints
- Rare-Earth Dopant Supply Concentration:Backward integration into cerium and europium sourcing is limited to a handful of Asian rare-earth processors, creating input cost volatility for non-integrated Western suppliers.
- REACH Compliance Burden:ECHA substance authorization requirements for thallium-activated glass formulations are expanding European cost-of-entry calculus and delaying new market entrants.
- Plastic Scintillator Substitution:Organic scintillator alternatives are capturing price-sensitive security screening deployments where energy resolution requirements permit lower light yield performance.
Strategic Opportunities
- Spent Fuel Pool Monitoring:Thermal neutron capture efficiency in lithium glass variants is opening procurement channels at US and French nuclear waste management facilities replacing legacy helium-3 detector systems.
- SiPM-Convergent Module Design:Detector manufacturers are integrating scintillator casting with silicon photomultiplier mounting substrates, creating value-capture opportunities for suppliers with precision machining capabilities.
- India's PLI Scheme for Medical Devices:Production-linked incentives for domestic radiation detection equipment are attracting joint venture proposals for localized glass scintillator fabrication serving South Asian hospital networks.
Industry Challenges
- Optical Homogeneity Certification:Batch-to-batch refractive index consistency testing for large-format medical imaging plates is extending quality assurance timelines and compressing effective production throughput.
- PMT-to-SiPM Retrofit Integration:Legacy gamma camera systems require mechanical redesign of scintillator housing geometries to accommodate solid-state readout electronics, complicating aftermarket service revenue streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Scintillator Market |
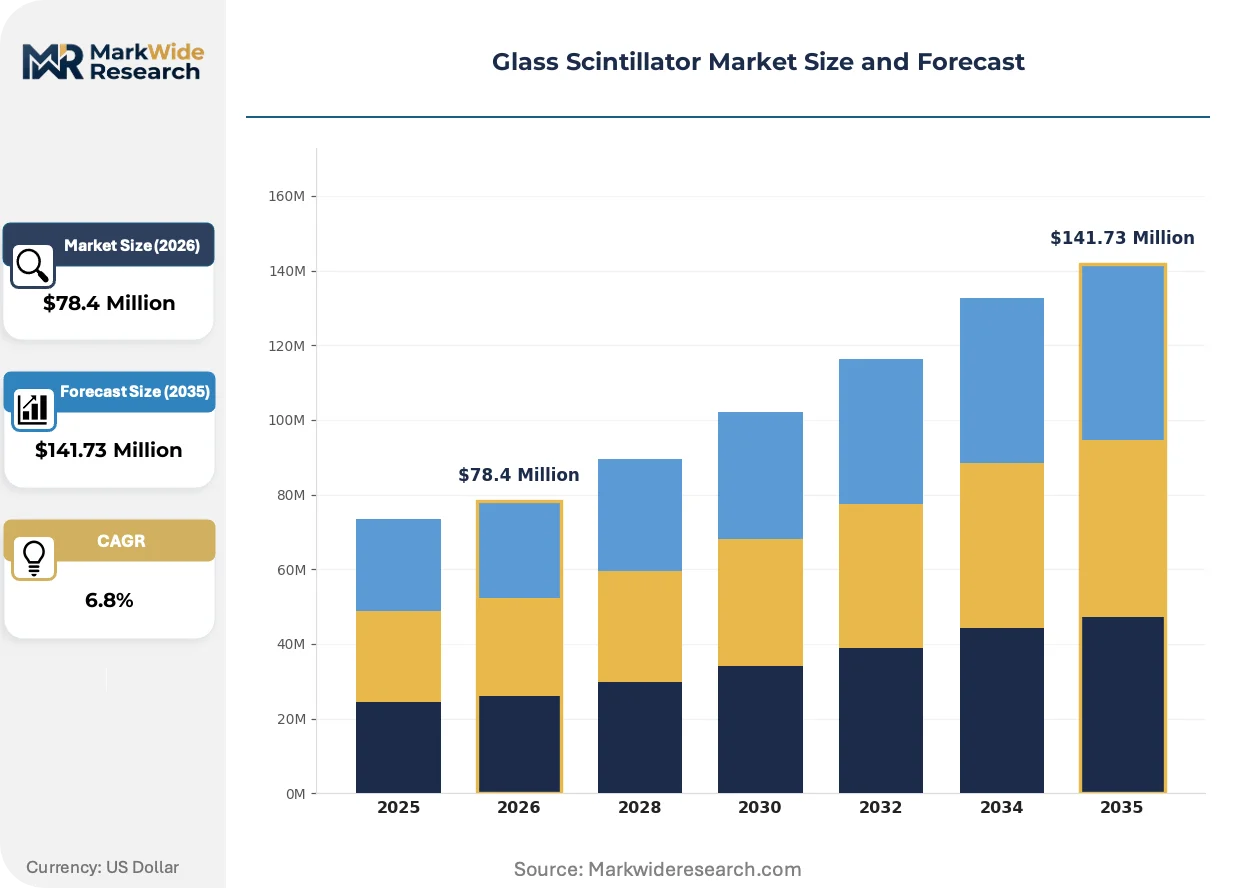
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Glass, Fused Silica, Lithium Glass, BGO Application: Nuclear Medicine, Radiography, Waste Management, High Energy Physics End User: Hospitals, Research Laboratories, Industrial Facilities, Academic Institutions Technology: Photomultiplier Tube, Silicon Photomultiplier, Scintillation Detectors, Gamma Cameras |
| Companies Covered | Rexon Components, Inc., Hitachi Metals, Ltd., Saint-Gobain Ceramics & Plastics, Collimated Holes Inc., Ludlum Measurements, Hamamatsu Photonics K.K., Mirion Technologies, Inc., Albemarle Corporation, Scintacor Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Scintillator Market Emerging Trajectories
Detector architecture miniaturization is converging with solid-state readout advances to reshape how radiation detection systems specify and procure scintillator components. Three interconnected developments are compressing traditional supply relationships.
Cerium-doped lithium glass formulations are integrating directly with silicon photomultiplier arrays in compact neutron detection modules for fusion research facilities. ITER procurement teams are specifying these integrated assemblies for blanket monitoring systems. The shift is compressing demand for discrete scintillator crystals paired with separate photomultiplier tubes.
REACH authorization timelines for thallium-activated glass are extending compliance documentation requirements for European medical device suppliers. EMA medical device regulations now require explicit substance safety declarations in technical files. German and French nuclear medicine equipment manufacturers are accelerating qualification of cerium-only dopant systems to preempt regulatory friction.
University hospital procurement departments are consolidating scintillator purchasing through single-source framework agreements with integrated detector suppliers. Gamma camera OEMs are capturing scintillator specification authority previously held by hospital physics departments. This concentration is most visible in US academic medical centers responding to FDA radiation detection device guideline updates.
Glass Scintillator Market Segmentation
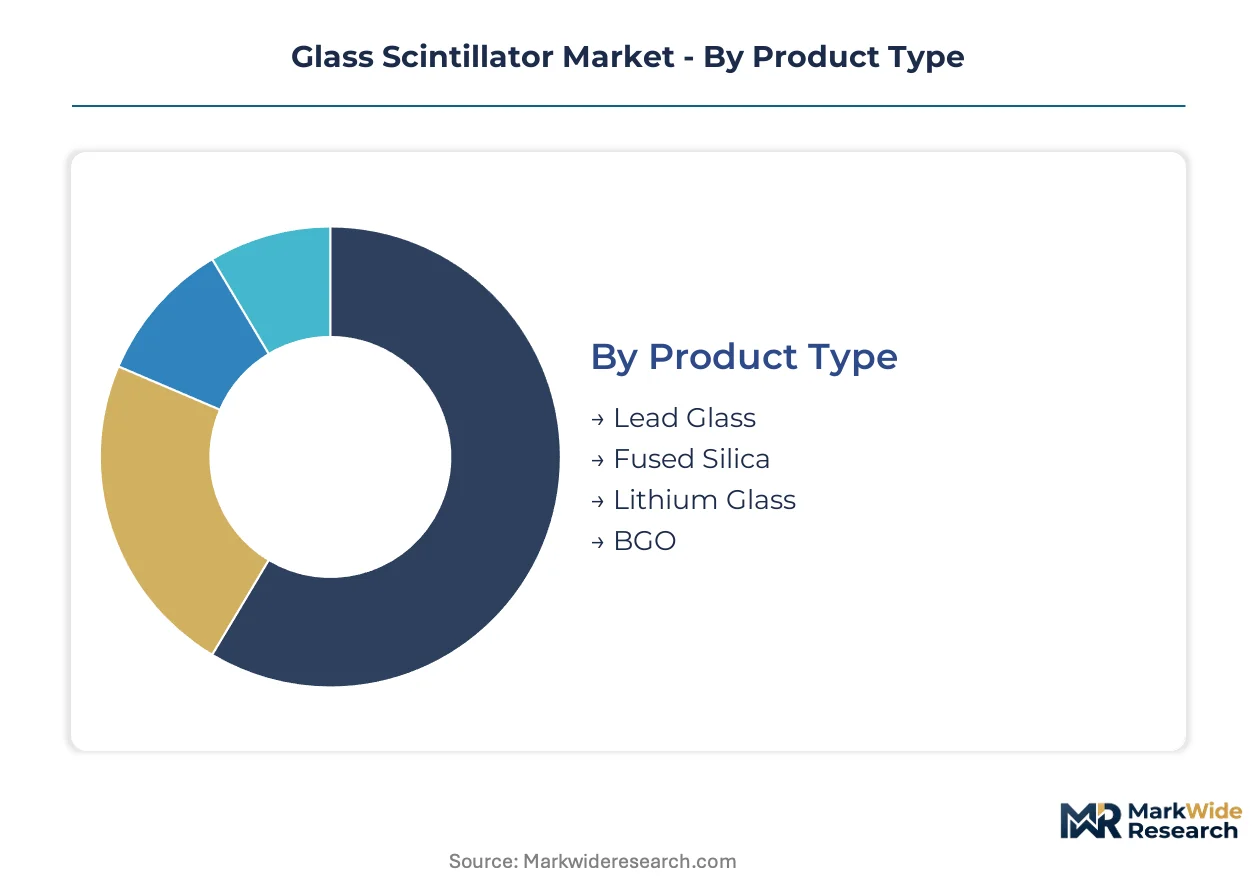
Glass scintillator procurement patterns diverge sharply across product chemistry, readout technology, and end-use compliance requirements. Equipment replacement cycles and detector architecture transitions are redrawing segment boundaries faster than traditional category definitions.
Product Type:
Upgrade decisions in gamma camera fleets and fusion research installations are pulling formulation demand toward materials compatible with solid-state readout systems and tightened neutron detection specifications.
- Lead Glass:Dense lead-oxide formulations provide gamma ray attenuation for nuclear medicine shielding and calibration phantoms. German university hospitals in Jena and Mainz concentrate procurement for high-homogeneity cerium-doped variants meeting FDA performance verification standards.
- Lithium Glass:Lithium-6 enriched matrices capture thermal neutrons through charged-particle emission, displacing helium-3 detectors in IAEA-specified waste monitoring systems. Fusion research facilities specify these formulations for deuterium-tritium plasma diagnostics.
- Fused Silica:Ultra-pure synthetic quartz substrates serve ultraviolet-transparent applications requiring minimal auto-fluorescence.
- BGO:Bismuth germanate crystals deliver high stopping power without activator dopants for compact PET detector modules.
Lead glass sits at the top of the volume ranking, with lithium glass climbing the fastest.
Application:
Regulatory validation burdens and detector replacement timelines concentrate procurement authority differently across clinical, research, and industrial end-uses.
- Nuclear Medicine:Gamma camera systems at academic medical centers require large-format scintillator plates with batch-certified optical homogeneity. EU MDR clinical validation and FDA guideline updates are consolidating supplier qualification pools.
- Waste Management:Spent fuel pool monitoring at US and French nuclear facilities is replacing legacy helium-3 systems with lithium glass neutron detectors. Thermal neutron capture efficiency specifications from national regulators drive procurement.
- Radiography:Industrial non-destructive testing applications demand portable scintillator arrays for field inspection services.
- High Energy Physics:Research collaborations specify custom-cast scintillator geometries for particle calorimetry and beam monitoring.
Nuclear medicine commands the largest installed base, while waste management applications are expanding most quickly.
End User:
Procurement centralization patterns and technical specification authority vary systematically across institutional categories with differing capital allocation cycles.
- Hospitals:University hospital physics departments are losing scintillator specification authority to gamma camera OEMs consolidating through single-source framework agreements. US academic medical centers lead this concentration trend.
- Research Laboratories:National fusion energy programs and particle physics collaborations drive demand for integrated scintillator-SiPM modules. ITER procurement specifications for blanket monitoring systems anchor volume.
- Industrial Facilities:Security screening and process control applications favor cost-optimized scintillator configurations where energy resolution requirements permit.
- Academic Institutions:Undergraduate teaching laboratories and smaller research groups purchase standardized scintillator formats through distributor channels.
Hospitals retain the deepest volume concentration, with research laboratories gaining share fastest.
Technology:
Readout electronics architecture transitions are forcing scintillator suppliers to reformulate optical coupling interfaces and mechanical mounting geometries.
- Silicon Photomultiplier:Solid-state photon counting arrays compress detector footprints and enable magnetic-field-immune operation. Scintillator suppliers are integrating casting processes with SiPM substrate mounting to capture module-level value.
- Photomultiplier Tube:Legacy vacuum-tube readouts dominate installed gamma camera bases but require mechanical redesign for SiPM retrofit compatibility, complicating aftermarket service revenue.
- Scintillation Detectors:Integrated scintillator-readout assemblies serve portable and remote monitoring applications requiring packaged solutions.
- Gamma Cameras:Anger camera systems with multiplexed PMT arrays remain the workhorse configuration for clinical SPECT imaging.
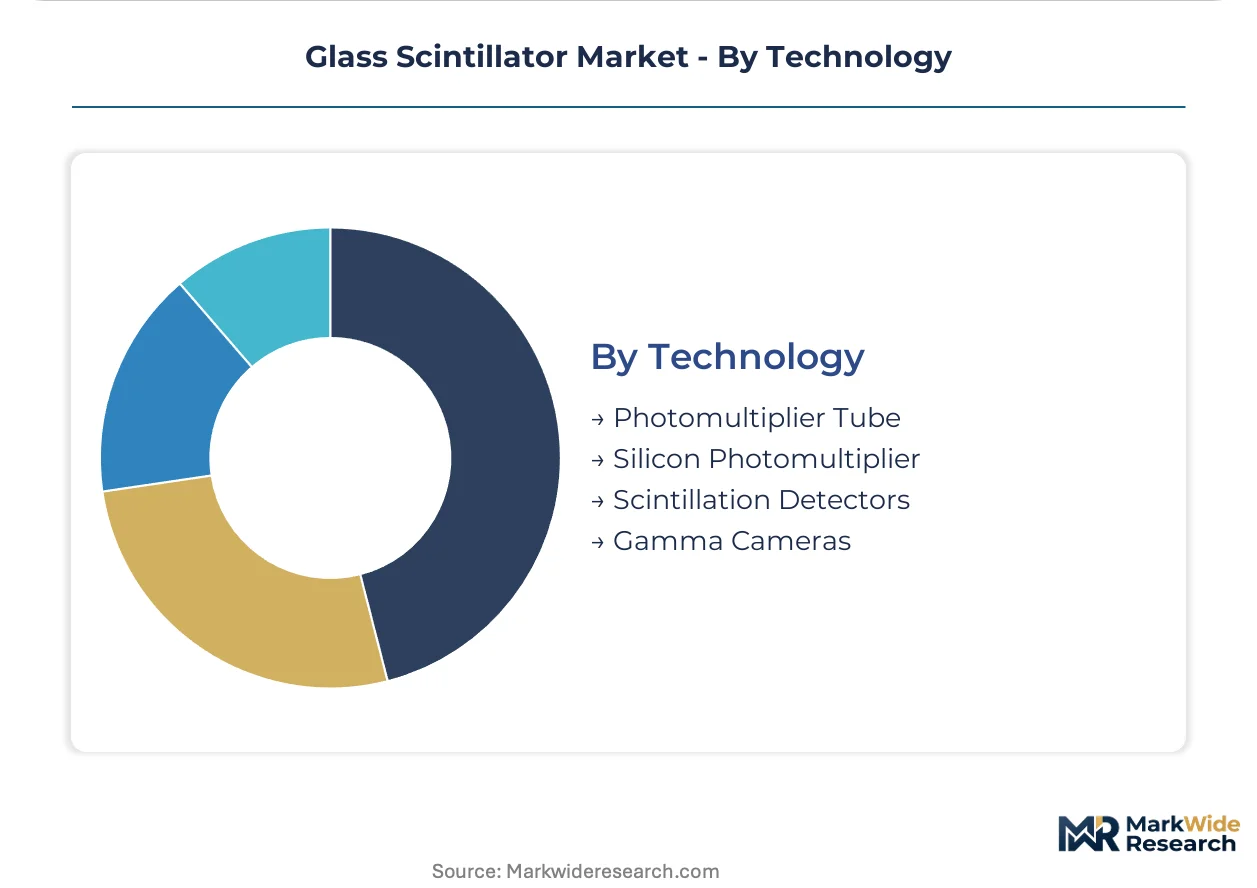
Photomultiplier tube pairings still dominate installed capacity, though silicon photomultiplier adoption is accelerating most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical engineering talent clusters in Germany's precision manufacturing belt anchor European supply capacity, while rare-earth processing concentration in East Asia shapes input access patterns across Western fabrication networks.
United States
FDA radiation detection device guideline updates are tightening performance verification standards for gamma camera systems at academic medical centers. The NRC governs spent fuel pool monitoring specifications driving lithium glass neutron detector procurement. The Southeast and Midwest hospital networks concentrate demand consolidation through single-source framework agreements.
Germany
EMA medical device regulations and CE marking under EU MDR impose clinical validation burdens consolidating supplier qualification pools. REACH compliance requirements for thallium-activated formulations extend authorization timelines. The Jena and Mainz precision optics cluster anchors specialized production capacity for high-homogeneity cerium-doped glass.
Japan
METI industrial policy supports domestic radiation detection equipment supply chain resilience. PMDA medical device standards align with international harmonization efforts for scintillator biocompatibility certification. The Kanto region around Tokyo concentrates photomultiplier tube pairing expertise with custom glass formulation specialists.
China
MIIT standards for nuclear instrumentation create domestic procurement preferences for radiation detection materials. NMPA medical device regulations govern import substitution timelines for hospital imaging equipment. The Yangtze River Delta manufacturing belt concentrates rare-earth dopant processing capacity feeding regional scintillator fabrication.
India
The PLI scheme for medical devices attracts joint venture proposals for localized glass scintillator fabrication serving South Asian hospital networks. CDSCO radiation equipment standards are converging with international norms for gamma camera performance. Maharashtra and Gujarat industrial corridors concentrate emerging detector assembly capacity.
Glass Scintillator Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base stratifies between integrated materials processors controlling rare-earth dopant sourcing and specialized fabricators concentrating on optical homogeneity certification. Three archetypes dominate: backward-integrated conglomerates with captive chemical supply, precision optics specialists leveraging regional cluster advantages, and detector system integrators capturing specification authority through module-level value capture. Competitive moves center on capacity expansion in lithium glass formulations and strategic partnerships for SiPM-convergent module design.
Within the integrated materials tier, Saint-Gobain Ceramics & Plastics exemplifies conglomerate-scale fused silica manufacturing leverage, while Hitachi Metals, Ltd. anchors a position through upstream control over rare-earth dopant sourcing. Hamamatsu Photonics K.K. occupies a specialist position in photomultiplier tube pairing with custom glass formulations.
| Leading Market Players |
|---|
| Rexon Components, Inc. |
| Hitachi Metals, Ltd. |
| Saint-Gobain Ceramics & Plastics |
| Collimated Holes Inc. |
| Ludlum Measurements |
| Hamamatsu Photonics K.K. |
| Mirion Technologies, Inc. |
| Albemarle Corporation |
| Scintacor Ltd. |
| Others |
Supply Flow & Price Mechanics
Performance-grade bifurcation between optical-homogeneity-certified medical plates and commodity security-screening blanks manifests in divergent pricing architectures and sourcing footprints. Premium cerium-doped formulations for gamma camera systems command substantial markups tied to batch-refractive-index certification, while standard lithium glass for neutron detection flows through contract-manufacturing networks optimized for throughput rather than precision.
Pricing Analysis
Bundled detector-module sales versus unbundled scintillator-crystal supply splits pricing logic across the value chain. Three-tier pricing structure across premium, standard, and economy levels reflects certification-grade differentiation, with FDA-validated medical imaging plates at the apex and industrial radiography blanks at the base. Cost compression in the standard tier is intensifying because plastic scintillator substitutes are capturing price-sensitive security deployments. Hospital procurement committees exhibit the lowest price sensitivity due to regulatory compliance imperatives, while industrial facility managers demonstrate acute elasticity.
Supply Chain Analysis
Rare-earth dopant supply rests on Chinese and Malaysian specialty chemical processors controlling cerium and europium refinement. German precision optics fabricators and Japanese photomultiplier tube specialists draw from these concentrated upstream sources. Single-source vulnerability in lithium-6 enrichment creates exposure for neutron-detection glass formulations. Distribution runs through OEM-integrated detector suppliers capturing specification authority previously held by hospital physics departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through SiPM-convergent module integration, where suppliers capturing casting-to-substrate assembly capture value previously fragmented across discrete component vendors.
For Market Incumbents: Hedge against solid-state readout displacement by accelerating lithium glass capacity expansion in Germany's Jena cluster while securing backward integration into rare-earth dopant sourcing. Plastic scintillator substitution in security applications threatens volume in the standard tier; defend through precision-machining capabilities for integrated module assembly that commodity competitors cannot replicate. For New Entrants and Emerging Players: Direct-to-research-laboratory digital channels bypass OEM specification capture and enable qualification of custom-cast geometries for fusion energy diagnostics. India's PLI scheme for medical devices represents the most penetrable geography, with production-linked incentives offsetting capital intensity for localized fabrication serving South Asian hospital networks. For Investors and Strategic Acquirers: Asymmetric upside sits with precision optics specialists possessing optical-homogeneity certification infrastructure and established biocompatibility trails under EU MDR. Long-term viability hinges on SiPM integration capabilities rather than legacy PMT pairing expertise. Watch ITER procurement specifications for blanket monitoring systems as the inflection signal for lithium glass demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Lithium Glass | Addresses ITER and waste management procurement specifications displacing helium-3 detectors. |
| Backward Integration into Rare-Earth Sourcing | Mitigates input cost volatility from Asian processor concentration for cerium-doped formulations. |
| SiPM-Convergent Module Design | Captures value from detector architecture compression in fusion research and medical imaging. |
| REACH Compliance Investment | Preempts authorization delays for thallium-activated formulations serving European nuclear medicine. |
| Joint Venture under India's PLI Scheme | Establishes localized fabrication capacity for South Asian hospital network procurement consolidation. |
Methodological Framework
Multiple input streams — gamma camera OEM technical specifications, rare-earth processor supply contracts, and national regulator procurement databases — were reconciled through structured primary interviews and secondary validation. Conversations with hospital biomedical engineers, fusion research facility instrumentation leads, nuclear waste management procurement officers, and precision optics manufacturing directors informed demand-side assumptions. Secondary sources included FDA radiation detection device guidance documents, EMA medical device regulation technical files, IAEA neutron detection specifications, and customs trade data on lithium-6 enriched glass imports. Bottom-up volume modeling across end-use segments was cross-checked against top-down market sizing from equipment replacement cycle analysis.
Historical shipment data was cross-referenced against panel input from supplier-side executives to establish baseline volumes. The analytical framework segmented by product chemistry, readout technology architecture, and end-user procurement authority across the modeling period. CAGRs were derived from equipment replacement timelines and detector architecture transition curves. Key forecast inputs included gamma camera fleet upgrade schedules at US academic medical centers and ITER construction milestone phasing for blanket monitoring procurement.
The model assumes a particular technology adoption path; alternative pathways for silicon photomultiplier penetration would alter the outlook if legacy PMT retrofit compatibility extends replacement cycles unexpectedly. Forecasts reflect assumptions about REACH authorization timelines for thallium-activated formulations and rare-earth supply chain resilience. A small set of named triggers — ITER procurement award announcements, FDA guideline finalization, and EU MDR enforcement actions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Global Fiber Optic Sensors Market
Optics
Global Fiber Optic Components Market
Optics
Anti Glare Film Market
Optics
Fixed Focal Length Lenses Market
Optics
Fiber Optics Market
Optics
Global Semiconductor Lasers Market
Optics
Fiber Optic Amplifier Market
Optics
APAC Smart Glass Market
Optics
Tunable Laser Market
Optics
Collimating Lens Market
Optics
Plastic Lens Market
Optics
Optical Fiber Market
Optics
Optical Lens for Mobile Phone Market
Optics
Acrylic Lenses Market
Optics
Middle East and Africa Tunable Laser Market
Optics
North America Optical Imaging Market