
 South Korea Optoelectronics Market | 2026-2036
South Korea Optoelectronics Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Optoelectronics Market Insights
Software-defined optical sensing subscriptions bundled with inspection equipment is rebalancing how Koh Young Technology monetizes its machine vision platforms. Samsung Electronics leverages captive semiconductor fabrication to anchor display driver IC supply for its own OLED panels. LG Innotek specializes in camera module actuators and optical components, sustaining dominance in smartphone supply chains. SK Hynix Inc competes through advanced memory-integrated photonics R&D, positioning its Icheon campus as a process development hub.
Optoelectronics encompasses devices that convert electrical signals to light or detect optical radiation, spanning semiconductor-based emitters, modulators, and sensors fabricated on III-V compound substrates such as gallium arsenide and indium phosphide. These components enable data transmission, display illumination, environmental sensing, and precision measurement across industrial and consumer systems. LED and optical sensor categories lead volume shipment, while quantum dot and hybrid display technologies capture expanding margin pools as television and monitor manufacturers pursue wider color gamut specifications. OLED technology segments maintain premium positioning in smartphone and emerging IT panel applications, whereas LCD technology persists in cost-sensitive automotive and industrial display deployments.
MFDS medical device electromagnetic compatibility requirements shape product certification pathways for diagnostic imaging optoelectronics, while KATS national standards and METI-aligned industrial efficiency codes govern energy consumption benchmarks for display manufacturing equipment. The Korea Communications Commission spectrum allocation decisions directly influence photonic component specifications for 5G and 6G base station deployment. Stakeholders must monitor Pyeongtaek cluster capacity expansion timelines and K-Semiconductor Belt subsidy disbursement schedules to calibrate capital allocation against localized supply bottlenecks.
Market Dynamics
The K-Semiconductor Belt initiative is concentrating advanced packaging capacity around Pyeongtaek and Yongin, tightening specialist engineer availability and reshaping component procurement patterns for display and sensing applications.
Growth Catalysts
- Automotive Display Integration:Hyundai and Kia suppliers are accelerating component procurement for cockpit digitization, pulling LED and optical sensor volumes into tier-one supply chains.
- K-Semiconductor Belt Subsidies:The Ministry of Trade, Industry and Energy's capital disbursement schedules are concentrating advanced packaging demand in Gyeonggi Province.
- OLED Technology Diffusion:Panel makers are extending organic light-emitting diode architectures into IT displays, tightening specialist availability across the value chain.
Market Restraints
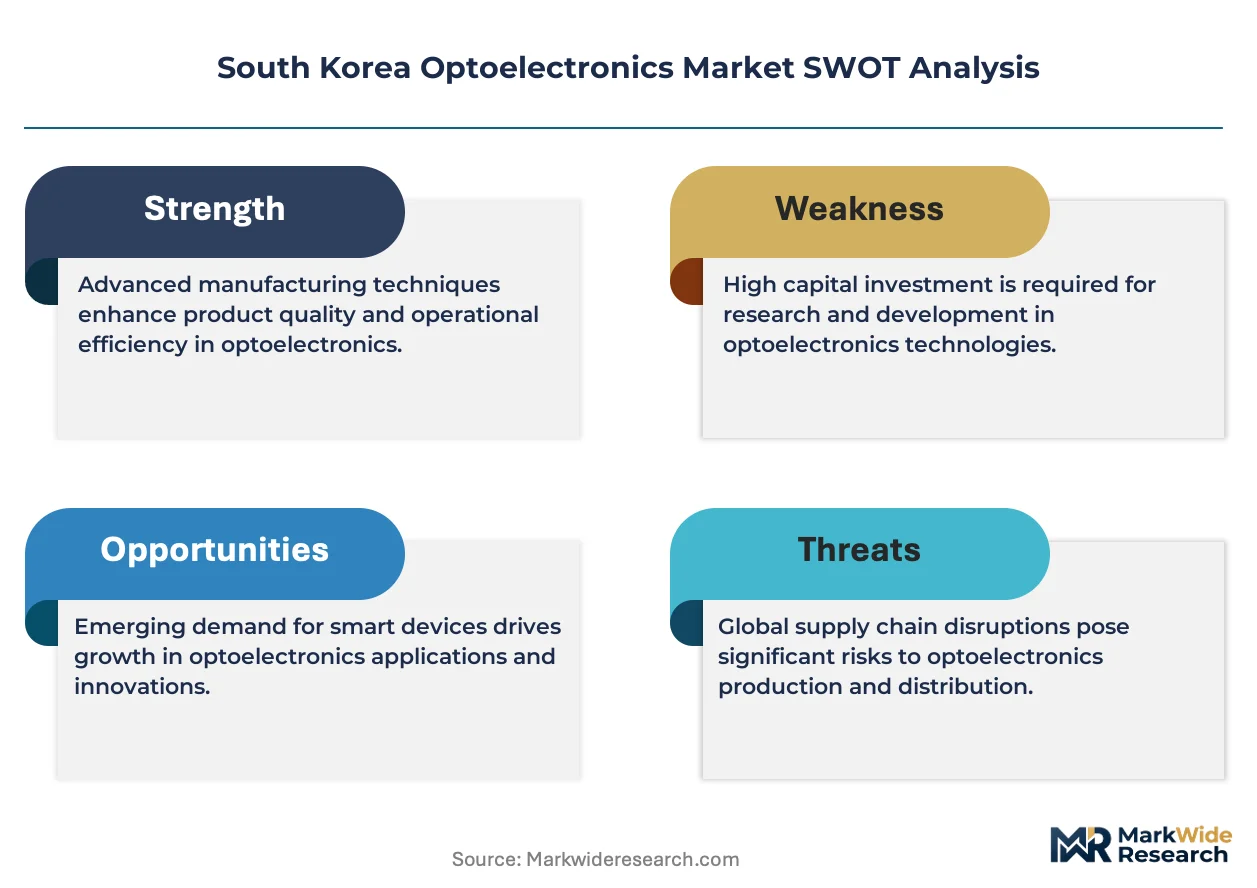
- Indium Phosphide Wafer Supply Concentration:III-V compound substrate fabrication remains concentrated among a handful of global suppliers, exposing Korean packaging houses to input volatility.
- MicroLED Prototyping Costs:Mass transfer yield limitations and repair complexity are compressing margin structures for emerging display architectures.
- MFDS Certification Timelines:Medical device electromagnetic compatibility requirements are extending product validation pathways for diagnostic imaging optoelectronics.
Strategic Opportunities
- 6G Photonic Component Specification:Korea Communications Commission spectrum allocation decisions are creating design-win opportunities for base station optical transceivers.
- Software-Defined Sensing Subscriptions:Machine vision platform vendors are unbundling hardware from recurring inspection analytics, opening recurring revenue streams.
- Quantum Dot Hybrid Displays:Television manufacturers pursuing wider color gamut specifications are creating margin expansion for advanced phosphor and barrier film suppliers.
Industry Challenges
- Advanced Packaging Engineer Scarcity:Heterogeneous integration and chiplet assembly expertise is concentrating in Icheon and Suwon, creating wage inflation and poaching cycles.
- Legacy LCD Capacity Stranding:Cost-sensitive automotive and industrial display deployments are delaying fab conversion timelines, tying capital in depreciating assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Optoelectronics Market |
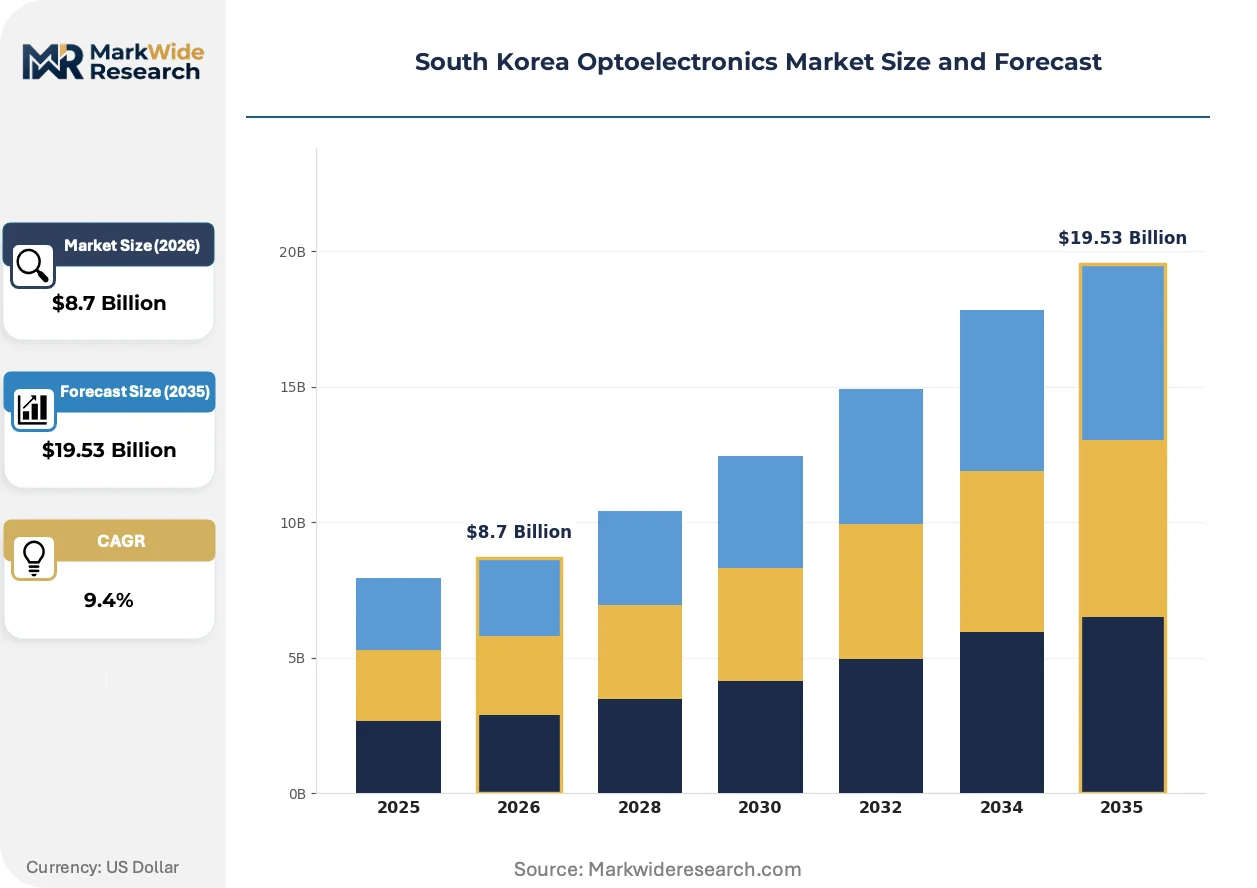
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Laser Diodes, Photodetectors, Optical Sensors Technology: OLED, LCD, Quantum Dot, Hybrid Displays Application: Consumer Electronics, Automotive Displays, Medical Devices, Communication Systems End User: Retail, Industrial, Healthcare, Telecommunications |
| Companies Covered | Samsung Electronics, SK Hynix Inc, LG Innotek, Koh Young Technology, DB HiTek Co., Ltd., Hanmi Semiconductor Co., Ltd., Magnachip Semiconductor Corp., Optowell Co., Ltd., ITM Semiconductor Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Optoelectronics Market Trends and Innovations
Photonic integration and software-defined architectures are compressing traditional hardware margins while opening service-based monetization paths across inspection, sensing, and display segments.
Silicon photonics is converging with advanced memory architectures to enable co-packaged optics in data center interconnects. SK Hynix and domestic packaging specialists are accelerating process development at Icheon to capture design wins from hyperscale buyers. This convergence is displacing discrete transceiver modules with integrated optical I/O chiplets.
KATS national standards and METI-aligned industrial efficiency codes are tightening energy consumption benchmarks for display manufacturing equipment. Equipment vendors must now certify thermal management and power delivery systems against consolidated efficiency tables. Panel makers in Gyeonggi Province are responding by retrofitting deposition and lithography tools.
Automotive OEMs are consolidating supplier qualification programs around functional safety and traceability requirements. Tier-one electronics manufacturers are displacing fragmented component sourcing with approved vendor lists and long-term capacity agreements. This concentration is most visible in Hyundai Motor Group's supplier development programs for next-generation cockpit systems.
South Korea Optoelectronics Market Segmentation
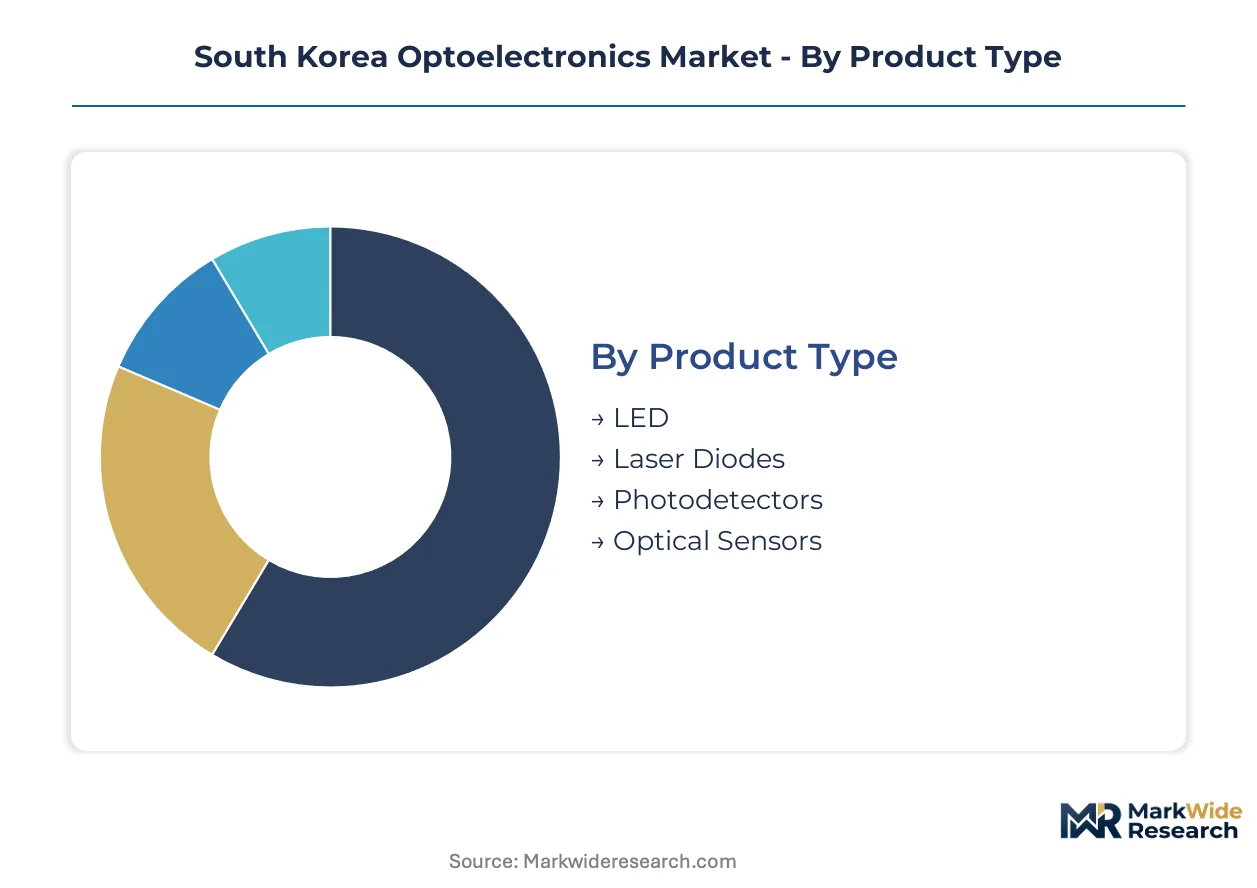
Optoelectronics demand in South Korea fragments across multiple technical and commercial dimensions. Component specifications vary sharply by end-use certification requirements and manufacturing process compatibility.
Product Type:
Volume shipments concentrate in illumination and sensing categories, while premium margins attach to specialized emitters and detectors.
- LED:Solid-state emitters fabricated on sapphire or silicon carbide substrates dominate general illumination and backlighting applications. Hyundai and Kia suppliers are pulling high-brightness packages into automotive cockpit digitization programs, tightening die-level procurement from domestic epitaxy houses.
- Laser Diodes:Coherent light sources spanning edge-emitting and vertical-cavity surface-emitting architectures enable optical data transmission and precision sensing. SK Hynix is integrating these into memory-photonics convergence prototypes at its Icheon campus, targeting hyperscale data center interconnects.
- Photodetectors:PN and avalanche junction devices convert optical signals to electrical current for communication and imaging systems.
- Optical Sensors:Ambient light, proximity, and time-of-flight modules bundle emitter and detector functions for consumer and industrial automation.
Mature deployment sits with LED. Newer deployment is concentrated in laser diodes.
Technology:
Display technology selection hinges on color gamut specifications, manufacturing cost structures, and form factor constraints.
- OLED:Organic electroluminescent architectures eliminate backlight requirements through emissive pixel structures. Panel makers in Gyeonggi Province are extending these designs into IT displays, tightening specialist engineer availability across vapor deposition and thin-film encapsulation processes.
- LCD:Liquid crystal modulation of polarized light persists in cost-sensitive automotive and industrial applications where brightness and durability outweigh contrast ratio requirements.
- Quantum Dot:Nanocrystal phosphors convert blue LED emission to narrow-band red and green for enhanced color volume in television panels.
- Hybrid Displays:MicroLED and mini-LED backlighting combine with quantum dot enhancement layers to bridge performance and cost gaps.
Volume manufacturing concentrates in LCD. Margin expansion is climbing the fastest in quantum dot and hybrid configurations.
Application:
End-use demand patterns split between consumer scale and industrial specification intensity.
- Consumer Electronics:Smartphones, tablets, and wearable devices drive high-volume procurement of compact emitters and sensors. Samsung Electronics anchors domestic demand through captive display driver IC fabrication for its own OLED panels.
- Automotive Displays:Digital instrument clusters and center-stack screens require wide-temperature operation and functional safety certification. Tier-one electronics manufacturers are consolidating around approved vendor lists and long-term capacity agreements with Hyundai Motor Group.
- Medical Devices:Diagnostic imaging and surgical visualization systems face MFDS electromagnetic compatibility requirements that extend validation timelines.
- Communication Systems:5G and emerging 6G base station deployment depends on Korea Communications Commission spectrum allocations that shape photonic component specifications.
Scale leadership sits with consumer electronics. Specification intensity is deepening fastest in automotive displays.
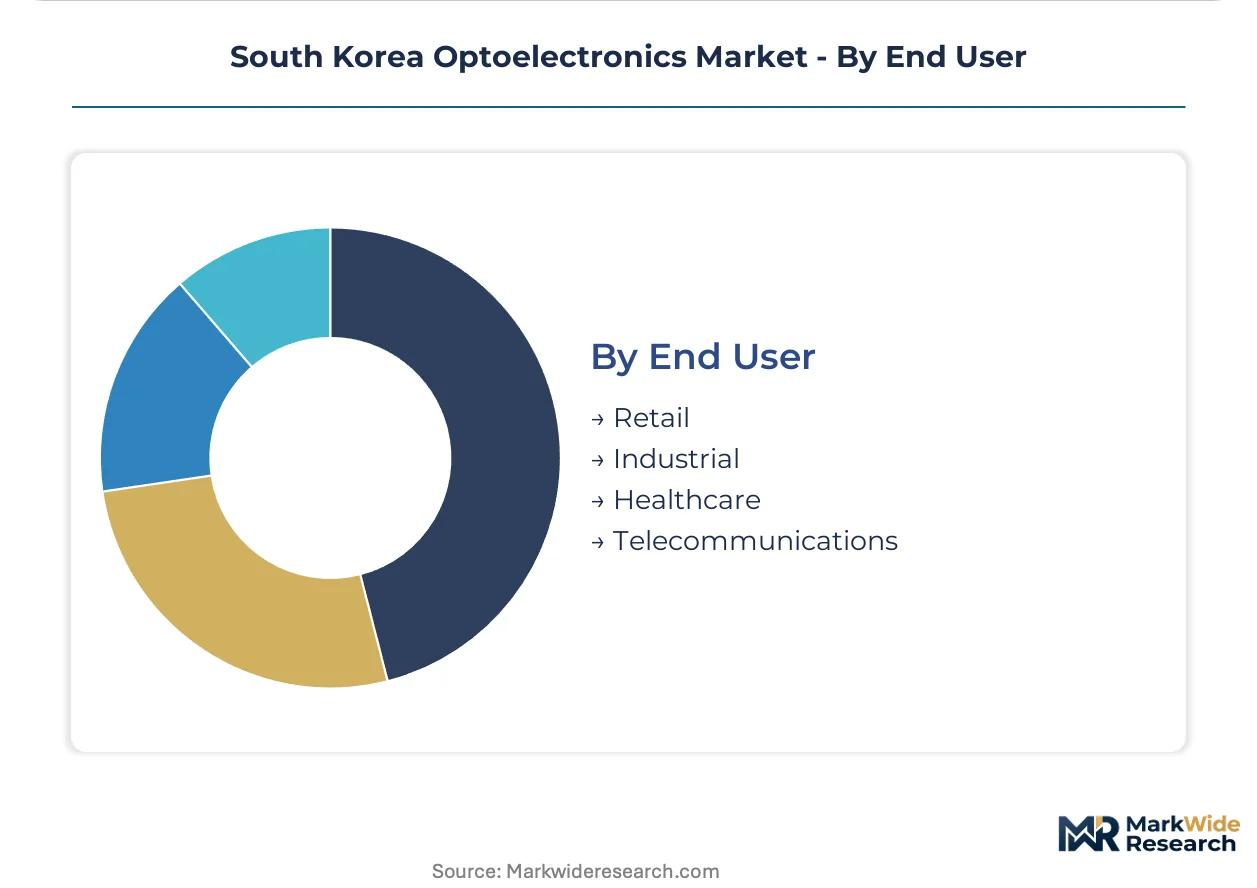
End User:
Procurement authority distributes across channel structures with varying technical engagement depth.
- Retail:Consumer-facing brands and distributors specify finished devices with embedded optoelectronic subsystems.
- Industrial:Factory automation and process control buyers prioritize reliability metrics and integration support over unit cost.
- Healthcare:Hospital systems and device OEMs navigate MFDS certification pathways for diagnostic imaging equipment.
- Telecommunications:Network operators and infrastructure vendors align component procurement with Korea Communications Commission deployment schedules.
Direct technical engagement sits with telecommunications. Procurement standardization is advancing fastest in industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic fabrication capacity outpaces local consumption across most optoelectronic categories, positioning South Korea as a net exporter of LED packages, display driver ICs, and optical sensors. Sub-regional specialization concentrates in metropolitan manufacturing belts where government incentives and infrastructure investment have accumulated over decades.
Seoul Capital Area
Corporate R&D headquarters and advanced packaging pilot lines dominate the metropolitan complex. The Korea Communications Commission spectrum allocation decisions originate here, directly shaping photonic component specifications for 5G and 6G infrastructure. Samsung Electronics and SK Hynix anchor captive semiconductor fabrication in Suwon and Icheon, supplying display driver ICs and memory-integrated photonics prototypes.
Gyeonggi Province
The K-Semiconductor Belt initiative has concentrated advanced packaging demand around Pyeongtaek and Yongin. Ministry of Trade, Industry and Energy subsidy disbursement schedules are accelerating cleanroom construction and equipment procurement. Specialist engineer availability is tightening across vapor deposition and thin-film encapsulation processes as OLED panel makers extend into IT displays.
Busan-Ulsan
Automotive electronics manufacturing clusters support Hyundai and Kia supplier networks. Tier-one electronics manufacturers are consolidating component sourcing around approved vendor lists and long-term capacity agreements. Display integration for cockpit digitization programs is pulling LED and optical sensor volumes into regional assembly plants.
Daegu-Gyeongbuk
Specialized materials and component fabrication facilities serve upstream supply chains for the broader electronics ecosystem. Regional industrial parks house precision optical component suppliers and test equipment vendors. Workforce development programs align technical training with heterogeneous integration and chiplet assembly skill requirements.
Daejeon-Sejong
Government research institutes and standards bodies concentrate in this administrative corridor. KATS national standards development and MFDS medical device certification pathways are coordinated here, influencing electromagnetic compatibility requirements for diagnostic imaging optoelectronics. Public-private partnerships fund microLED and quantum dot materials research.
South Korea Optoelectronics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the South Korea optoelectronics landscape. Foundry operators with captive wafer fabrication anchor supply security for display and memory applications, while fabless specialists outsource manufacturing to concentrate on design integration. The market structure exhibits tiered consolidation: diversified conglomerates control premium display and semiconductor segments, mid-scale packaging houses serve automotive and industrial niches, and specialized equipment vendors capture recurring revenue through software-defined service models. Dominant competitive moves include backward integration into epitaxy and substrate processing, plus strategic partnerships with automotive OEMs for cockpit system qualification.
Among diversified Korean electronics conglomerates, Samsung Electronics, SK Hynix Inc, and LG Innotek occupy positions spanning multiple value chain tiers. Samsung Electronics exemplifies the captive fabrication archetype through in-house production of display driver ICs for its own OLED panels. SK Hynix Inc represents the memory-photonics convergence strategy with its Icheon campus process development hub. LG Innotek sits within the specialized component tier, sustaining supply chain presence in smartphone camera module ecosystems.
| Leading Market Players |
|---|
| Samsung Electronics |
| SK Hynix Inc |
| LG Innotek |
| Koh Young Technology |
| DB HiTek Co., Ltd. |
| Hanmi Semiconductor Co., Ltd. |
| Magnachip Semiconductor Corp. |
| Optowell Co., Ltd. |
| ITM Semiconductor Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Performance-grade bifurcation between automotive-certified and consumer-grade optoelectronics manifests in contract pricing premia and captive sourcing requirements. MFDS electromagnetic compatibility tiers and KATS efficiency benchmarks stratify procurement across Hyundai Motor Group supplier programs and commodity LED spot markets.
Pricing Analysis
Margin tightening in high-brightness automotive LED packages reflects tier-one consolidation around approved vendor lists. Three-tier pricing structure across premium, standard, and economy levels separates functional-safety-certified cockpit displays from consumer backlighting. Cost-down pressure on indium phosphide substrates accelerates as III-V wafer fabrication concentrates among Japanese and European suppliers. Industrial automation buyers exhibit lowest price sensitivity due to reliability premiums, while consumer electronics procurement teams drive hardest bargain on die-level volumes.
Supply Chain Analysis
K-Semiconductor Belt domestic-content mandates reshape sourcing toward Pyeongtaek and Yongin packaging houses. Epitaxy-grade sapphire and silicon carbide substrates draw from United States and Japanese suppliers, while phosphor materials and quantum dot precursors rest on Chinese and German chemical specialists. Single-source vulnerability concentrates in indium phosphide wafer supply. Distribution runs through Samsung and SK Hynix captive fabrication networks alongside independent packaging houses serving automotive tier-ones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialist engineer scarcity across vapor deposition and heterogeneous integration props component pricing, constraining capacity expansion timelines regardless of subsidy disbursement.
For Market Incumbents: Cement supply security through backward integration into epitaxy processing and substrate qualification. Lock in long-term capacity agreements with Hyundai Motor Group before tier-one consolidation hardens approved vendor lists. Threat substitution from microLED mass-transfer technologies demands accelerated R&D spend at Icheon and Suwon campuses. For New Entrants and Emerging Players: Korea Communications Commission 6G spectrum allocation opens a window for photonic transceiver design wins in base station infrastructure. Target white-space in software-defined inspection analytics where Koh Young Technology's subscription model remains underpenetrated. Pursue automotive display qualification as the most penetrable segment given cockpit digitization pull-through. For Investors and Strategic Acquirers: Re-rating potential sits with advanced packaging specialists given K-Semiconductor Belt subsidy acceleration and Pyeongtaek cluster expansion. Five-to-ten-year viability hinges on heterogeneous integration capability depth. Monitor MFDS certification timeline compression as inflection signal for diagnostic imaging optoelectronics demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxy | Samsung Electronics secures sapphire substrate supply against LED die procurement volatility. |
| Software-Defined Sensing Subscription | Koh Young Technology unbundles hardware from recurring inspection analytics revenue streams. |
| 6G Photonic Component Qualification | SK Hynix captures hyperscale data center interconnect design wins through co-packaged optics. |
| Automotive Display Certification | LG Innotek sustains camera module actuator dominance via Hyundai Motor Group supplier programs. |
| Quantum Dot Materials Partnership | Domestic panel makers secure phosphor supply for wide color gamut television specifications. |
Research Methodology
Multi-period observation of K-Semiconductor Belt subsidy disbursements, Pyeongtaek cluster construction permits, and automotive cockpit digitization procurement schedules anchored the trend analysis, supplemented by interviews with epitaxy process engineers, display driver IC design leads, tier-one automotive electronics procurement managers, and MFDS regulatory affairs specialists. Secondary validation drew from Korea Communications Commission spectrum allocation filings, Ministry of Trade, Industry and Energy policy announcements, KATS efficiency benchmark publications, and SEC disclosures from Korean electronics conglomerates. Bottom-up component shipment analysis triangulated against top-down display and semiconductor equipment spending forecasts.
Input-output matrices mapped LED die volumes to backlighting and automotive illumination applications, laser diode shipments to data center interconnect demand, and optical sensor units to smartphone and industrial automation install bases across the modeling period. Segmentation dimensions spanned product type, display technology, end-use application, and regional manufacturing cluster. CAGRs derived from logistic diffusion curves fitted to technology substitution patterns and capacity expansion schedules. Industry-specific forecast inputs included heterogeneous integration yield trajectories and microLED mass-transfer efficiency improvement curves.
The model assumes a particular technology adoption path; alternative pathways for microLED commercialization or silicon photonics displacement of discrete transceivers would alter the outlook. Forecasts reflect assumptions regarding K-Semiconductor Belt execution pace, automotive OEM qualification timeline compression, and III-V substrate supply elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
United States Optoelectronics Market
Optoelectronics
Global Shortwave Infrared (SWIR) Market
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
Optoelectronic Development Tools Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
Americas Optoelectronics Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
Optical Pulse Sensor Market
Optoelectronics
Infrared Emitter and Receiver Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
Laser Projector Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Quantum Dots Market