
 Optical Fiber Market | 2026-2036
Optical Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Fiber Market Intelligence
Divergent performance needs between hyperscale data centers and residential fiber-to-the-home networks is restructuring the market into specialized and commodity tiers. Corning Incorporated leverages its deep R&D to lead in high-performance, low-loss fibers for subsea and long-haul applications. In contrast, Hengtong Group competes on manufacturing scale and cost efficiency in standard single-mode fiber segments. Prysmian Group sustains a broad portfolio, balancing specialty and volume production across global markets.
Optical fiber is a thin, flexible filament of silica glass or plastic designed to transmit information as light pulses over long distances. Its structure consists of a core that guides light and a cladding layer with a lower refractive index to contain it. Single-mode fiber, with its smaller core, dominates the telecommunication networks segment due to its suitability for long-haul transmission. Conversely, multi-mode fiber remains critical for shorter-range data center connectivity, where its larger core simplifies connections.
Deployment standards and funding are shaped by national policies, such as directives from China's MIIT for 5G expansion and the US FCC's oversight of broadband infrastructure. In Europe, the EU Green Deal influences cable material specifications and manufacturing sustainability through regulations like RoHS. Future investment decisions will depend on navigating these disparate regional subsidy programs and aligning product development with emerging network architectures like coherent optics.
Market Dynamics
The fundamental market dynamic is the divergence between demand for high-performance specialty fibers and cost-optimized commodity fibers. This split is driven by hyperscale data centers requiring low-loss transmission while national broadband initiatives prioritize manufacturing scale and cost efficiency.
Growth Catalysts
- National Broadband Programs:Government-led initiatives, including the US Broadband Equity, Access, and Deployment (BEAD) program, are accelerating terrestrial fiber-to-the-home (FTTH) network construction, creating sustained, large-volume demand for standard single-mode fiber.
- 5G Network Densification:Directives from bodies like China's MIIT mandating extensive 5G coverage necessitate a massive build-out of fiber-optic fronthaul and backhaul infrastructure to connect new cell sites, driving significant cable consumption.
- Data Center Expansion:The proliferation of cloud services and AI workloads fuels the construction of hyperscale data centers, which require high-density, low-loss interconnects for internal and external connectivity, pulling demand for advanced multi-mode and single-mode fibers.
Market Restraints
- High Input Material Costs:The production of high-purity silica glass preforms, the core raw material for optical fiber, is an energy-intensive and technologically complex process, creating a high-cost basis that limits price flexibility.
- Installation Skill Bottlenecks:Deploying fiber optic networks requires skilled technicians for splicing, testing, and termination. A persistent shortage of this specialized labor creates a structural barrier that can slow down project timelines and increase deployment costs.
- Geographic Concentration of Preform Production:A significant portion of the global capacity for optical fiber preforms is concentrated in a few countries. This creates supply chain vulnerability to regional trade policies, logistical disruptions, or local energy cost fluctuations.
Strategic Opportunities
- Emerging Sensing Applications:Optical fibers can be used for distributed acoustic and temperature sensing (DAS/DTS) in asset monitoring for pipelines, railways, and perimeters. This non-telecom application opens a new, high-value market segment.
- Hollow-Core Fiber Development:Next-generation hollow-core fibers, which transmit light through air, offer ultra-low latency performance. This creates an opportunity to serve niche, performance-critical applications like high-frequency trading and scientific computing.
- Network Expansion in Underserved Regions:Significant white space for new terrestrial and subsea cable deployments exists across Africa and parts of Southeast Asia. These regions represent a long-term growth frontier for both backbone and access network construction.
Industry Challenges
- Skilled Labor Scarcity:A global shortage of qualified fiber optic splicers and field engineers acts as a primary operational bottleneck, constraining the pace at which network operators can execute large-scale deployment projects.
- Intensive Capital Requirements:Constructing new, vertically integrated fiber and cable manufacturing plants requires substantial capital investment, presenting a high barrier to entry and limiting the ability of the supply base to rapidly scale capacity.
- Navigating Disparate Permitting Processes:Securing rights-of-way and navigating inconsistent local and national permitting regulations for civil works is a major challenge that introduces significant delays and administrative overhead to network build-outs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Fiber Market |
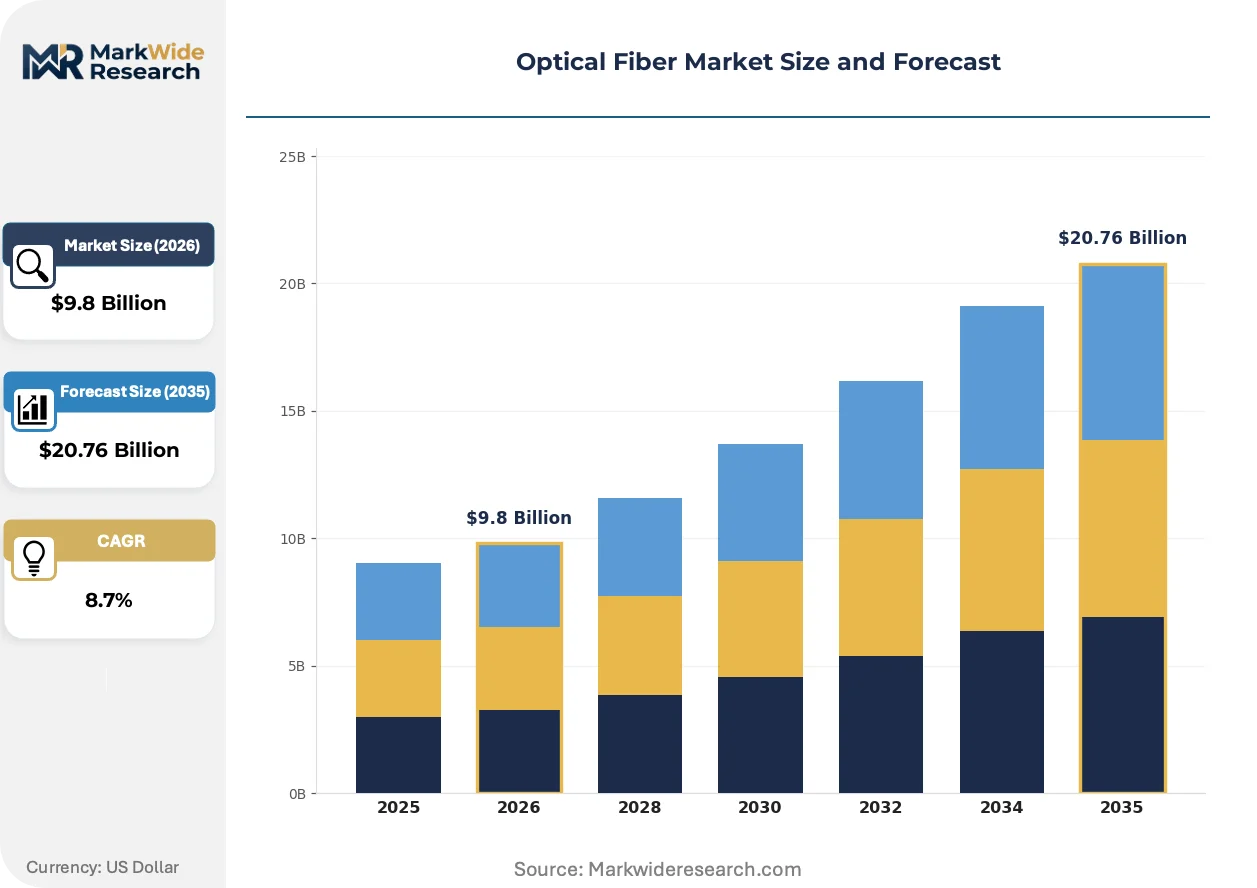
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-mode Fiber, Multi-mode Fiber, Plastic Optical Fiber, Photonic Crystal Fiber, Hollow-core Fiber Technology: Fiber Bragg Grating, Optical Amplifier, Dense Wavelength Division Multiplexing, Coherent Optical Technology, Time Division Multiplexing Application: Telecommunication Networks, Data Center Connectivity, Military & Defense, Broadcast & Cable TV, Undersea Cable Systems End User: Internet Service Providers, Data Storage Centers, Government Agencies, Research Institutes, Telecommunication Equipment Manufacturers |
| Companies Covered | Fujikura Ltd., LS Cable & System, Corning Incorporated, Broadcom Inc., Sterlite Technologies Limited, Prysmian Group, Hengtong Group, Lumentum Holdings Inc., Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Fiber Market Strategic Shifts & Innovations
Product development is increasingly focused on application-specific performance, moving away from a one-size-fits-all approach. This specialization is driven by the distinct physical and transmission requirements of network segments, from subsea long-haul routes to high-density data center fabrics.
Specialty fiber designs, such as bend-insensitive and reduced-diameter fibers, provide enhanced performance for specific environments. Data center operators and FTTH providers are adopting these products to enable higher-density cabling and simplify installation in tight spaces. This innovation is modularizing cable construction, allowing manufacturers to create highly customized solutions for specific duct, aerial, or direct-buried applications.
European sustainability mandates, particularly the EU Green Deal, influence material selection for optical cables through regulations like RoHS. This forces manufacturers to document and limit the use of certain hazardous substances in cable jackets and other components, impacting product design. Cable producers targeting the European Union must invest in compliant materials and supply chain verification to maintain market access.
A shift in purchasing behavior is evident among large-scale network operators, who are moving from exclusive, long-term supplier agreements to multi-sourcing strategies. This change disrupts traditional direct sales models and elevates the role of large distributors capable of managing inventory from multiple vendors. This pattern is most pronounced in the highly competitive US and Indian markets, where project scale necessitates supply chain diversification.
Optical Fiber Market Segmentation
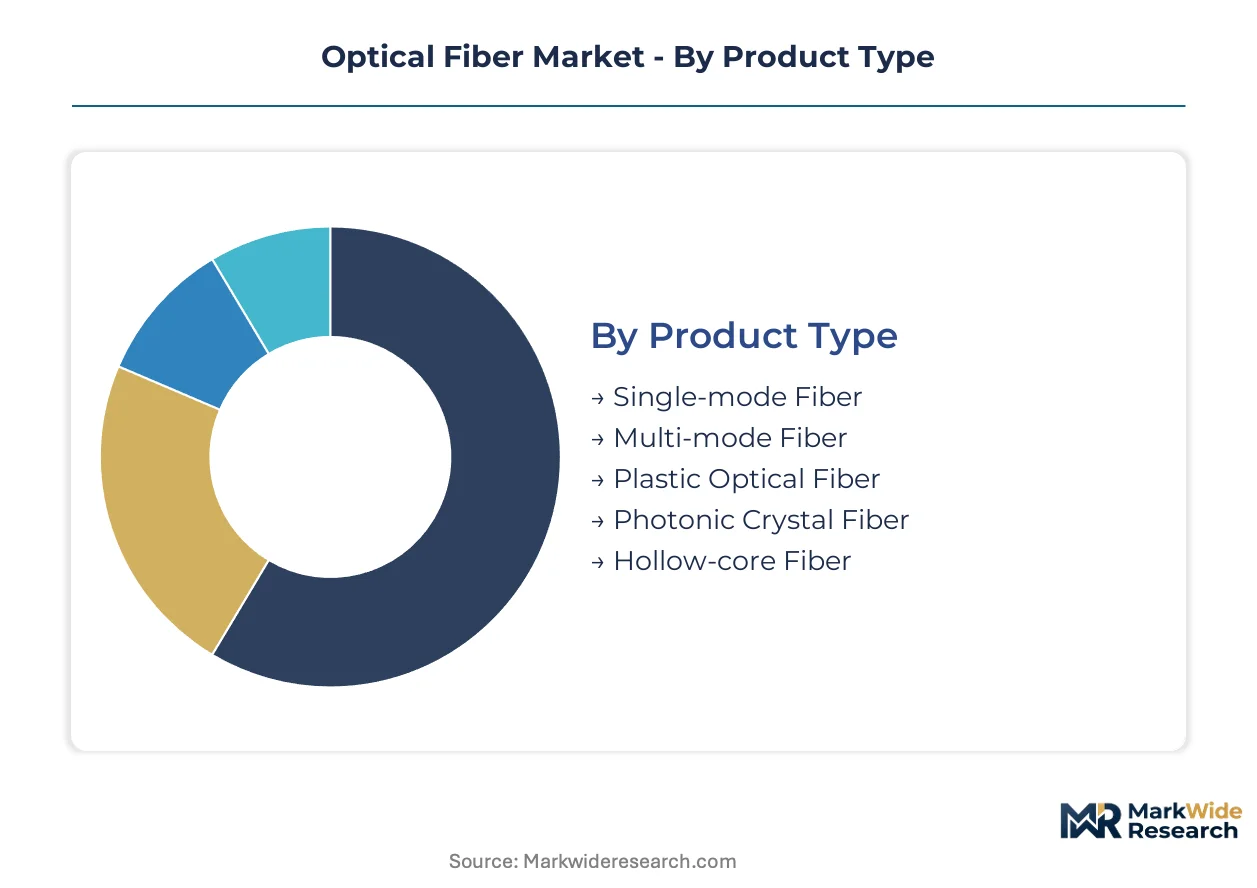
The optical fiber market segments based on distinct performance requirements and deployment scenarios. Understanding these divisions helps stakeholders align product development and investment strategies with specific demand patterns across telecommunication, data center, and specialized sensing applications. This granular view reveals where innovation and scale intersect.
Product Type:
Buyers prioritize specific fiber types based on transmission distance, data rate, and environmental resilience requirements.
- Single-mode Fiber:This fiber type features a small core, allowing a single light path for minimal dispersion over long distances. National broadband programs, including the US BEAD initiative, drive substantial demand for single-mode fiber in terrestrial network build-outs.
- Hollow-core Fiber:These next-generation fibers transmit light through an air-filled core, offering ultra-low latency and reduced signal loss. Niche, performance-critical applications like high-frequency trading and scientific computing represent a significant opportunity for this advanced product.
- Multi-mode Fiber:A larger core simplifies connections, making multi-mode fiber critical for shorter-range data center connectivity.
- Plastic Optical Fiber:This fiber type offers ease of installation and cost-effectiveness for short-distance, low-bandwidth applications.
- Photonic Crystal Fiber:Engineered microstructures within the fiber provide unique optical properties for specialized sensing and high-power delivery.
Single-mode Fiber leads on scale; Hollow-core Fiber leads on momentum.
Technology:
The choice of optical technology depends on the desired network capacity, reach, and spectral efficiency for data transmission.
- Coherent Optical Technology:This advanced modulation and detection technique significantly increases data transmission capacity and reach over existing fiber infrastructure. Emerging network architectures and long-haul transport systems increasingly adopt coherent optics.
- Dense Wavelength Division Multiplexing:DWDM maximizes fiber utilization by transmitting multiple data streams on different light wavelengths simultaneously. Telecommunication providers widely deploy DWDM to upgrade backbone networks without installing new fiber.
- Fiber Bragg Grating:Integrated into optical fibers, these gratings serve as precise filters or sensors for telecommunications and structural health monitoring.
- Optical Amplifier:Devices like EDFAs boost optical signal power, extending transmission distances without requiring electrical conversion.
- Time Division Multiplexing:TDM combines multiple low-speed signals into a single high-speed channel by allocating specific time slots.
Innovation in Coherent Optical Technology transforms network capabilities while Dense Wavelength Division Multiplexing optimizes existing infrastructure.
Application:
Application-specific demands dictate fiber performance specifications, from high-density data center fabrics to expansive national broadband initiatives.
- Telecommunication Networks:This segment encompasses core, metro, and access networks, utilizing vast quantities of single-mode fiber for long-haul and fiber-to-the-home deployments. National broadband programs, such as India's digital infrastructure initiatives, drive substantial demand within this segment.
- Data Center Connectivity:Hyperscale data centers require high-density, low-loss interconnects both internally and for external peering. The proliferation of cloud services and AI workloads fuels the construction of these facilities.
- Military & Defense:Ruggedized and secure optical fiber systems are essential for tactical communications and sensing in demanding environments.
- Broadcast & Cable TV:Fiber optics provide high-bandwidth distribution for video and internet services to homes and businesses.
- Undersea Cable Systems:Specialty, low-loss fibers form the backbone of global internet connectivity between continents.
Demand from Telecommunication Networks drives market volume, whereas Data Center Connectivity requires specialized solutions.
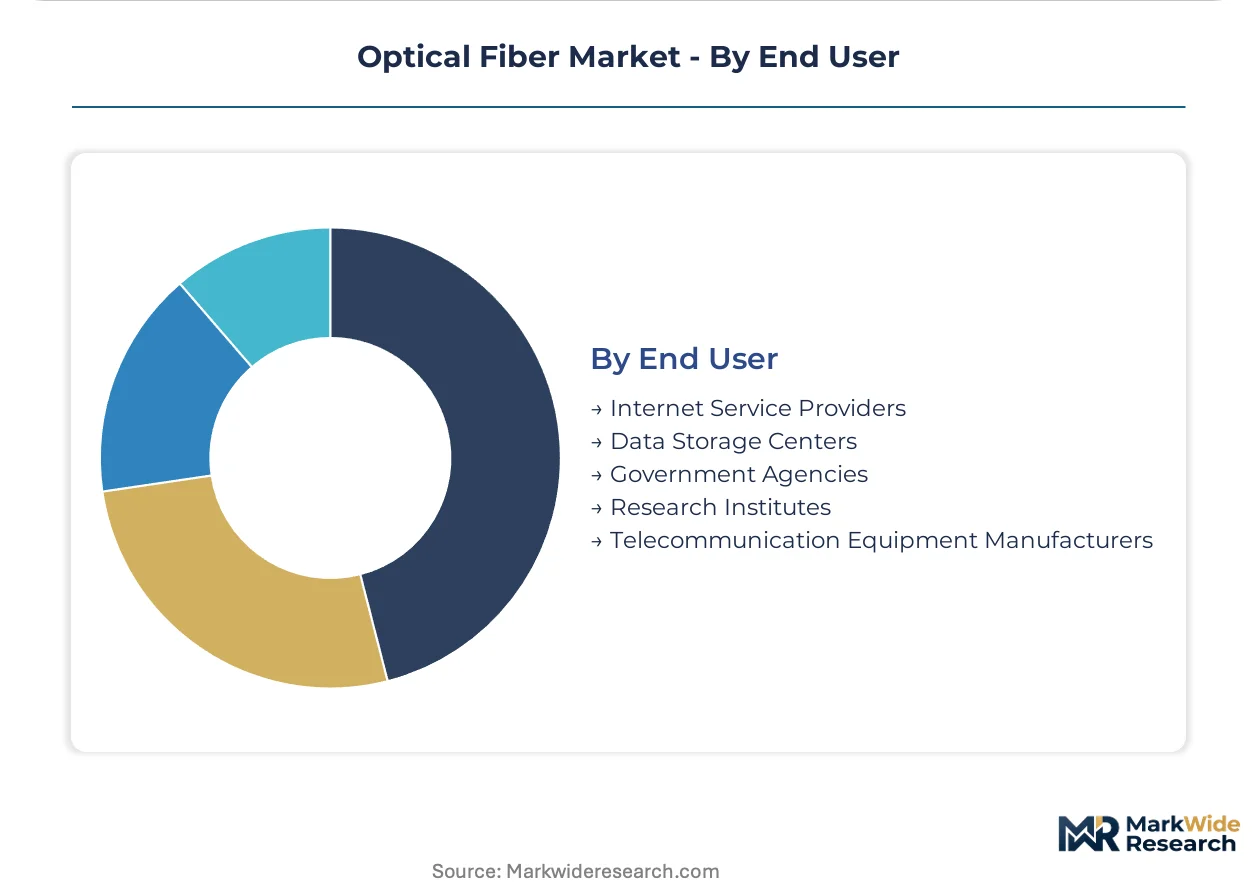
End User:
End-user procurement strategies range from large-scale volume purchases for network build-outs to specialized acquisitions for research and defense.
- Internet Service Providers:ISPs are major consumers of optical fiber for expanding their broadband networks to residential and business customers. Government-led initiatives like the US BEAD program directly influence procurement volumes for these entities.
- Data Storage Centers:These facilities, ranging from enterprise data centers to hyperscale cloud providers, require high-performance fiber for internal and external data transfer. The continuous growth of cloud computing and AI services drives their fiber acquisition.
- Government Agencies:Agencies utilize optical fiber for secure communication networks and specialized sensing applications in defense and infrastructure monitoring.
- Research Institutes:These organizations procure specialized fibers for advanced scientific experiments and material science development.
- Telecommunication Equipment Manufacturers:OEMs integrate optical fiber into their active and passive network components before deployment.
The procurement strategies of Internet Service Providers dictate large-scale demand, with Data Storage Centers focusing on advanced performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized engineering talent across key economies drives the global optical fiber market. National digital infrastructure initiatives and hyperscale data center build-outs anchor demand in these regions. These areas also lead in advanced fiber material science and deployment expertise.
United States
The United States experiences substantial demand from government-led broadband initiatives and continuous data center expansion. The US Broadband Equity, Access, and Deployment (BEAD) program accelerates fiber-to-the-home network construction across the country. Northern Virginia, a major data center hub, concentrates demand for high-density, low-loss interconnects.
China
China's extensive 5G network densification and digital infrastructure projects create immense optical fiber demand. Directives from China's MIIT mandate massive build-outs of fiber-optic fronthaul and backhaul infrastructure. The Yangtze River Delta region, a manufacturing and technology hub, sees significant investment in advanced fiber production.
India
India's national digital infrastructure initiatives drive significant volume demand for standard single-mode fiber. Government programs prioritize fiber-to-the-home deployments to connect underserved populations across the subcontinent. Bengaluru, a prominent technology hub, anchors demand for high-bandwidth connectivity in urban and surrounding areas.
Germany
Germany's commitment to European broadband expansion and industrial digitalization fuels specialized fiber demand. The EU Green Deal influences cable material specifications and manufacturing sustainability through regulations like RoHS. Bavaria, an industrial powerhouse, drives requirements for robust and compliant optical fiber solutions in manufacturing and automotive sectors.
Japan
Japan focuses on advanced telecommunication network upgrades and emerging optical fiber sensing applications. National infrastructure plans support the deployment of high-capacity fiber for both urban and rural connectivity. The Tokyo metropolitan area, a global technology center, leads in the adoption of next-generation fiber optics for high-speed data transmission.
Optical Fiber Market Key Industry Players
Top-tier vendors anchor the high-performance, low-loss fiber segment, while commodity producers compete on manufacturing scale and cost efficiency. The market exhibits a tiered structure, distinguishing between specialized fiber innovators and standard single-mode fiber suppliers. Strategic archetypes include vertically integrated giants, niche technology specialists, and regional volume manufacturers. Companies pursue portfolio diversification and geographic expansion to capture both premium and volume market opportunities.
On the premium-tier vector, Corning Incorporated exemplifies leadership in high-performance, low-loss fibers, particularly for subsea and long-haul applications. Hengtong Group, a China-based entity, represents the archetype of manufacturing scale and cost efficiency within standard single-mode fiber segments, catering to large-volume national broadband projects. Prysmian Group, with its broad portfolio, occupies a position balancing specialty and volume production across diverse global markets, serving both advanced and commodity needs. These major players, alongside other established firms, collectively drive innovation and capacity expansion across the industry.
| Leading Market Players |
|---|
| Fujikura Ltd. |
| LS Cable & System |
| Corning Incorporated |
| Broadcom Inc. |
| Sterlite Technologies Limited |
| Prysmian Group |
| Hengtong Group |
| Lumentum Holdings Inc. |
| Sumitomo Electric Industries |
Cost & Logistics Intelligence
National broadband initiatives, such as the US BEAD program, concentrate procurement for standard single-mode fiber, driving contract-based long-term offtake pricing. Hyperscale data centers, conversely, influence value-based pricing for specialized, high-performance fibers.
Pricing Analysis
The optical fiber market exhibits a bundled-vs-unbundled service split, with major players offering integrated cable solutions or standalone fiber. Contract-based long-term offtake agreements dominate for high-volume standard single-mode fiber, while specialized fibers for data centers command value-based pricing. Price differentiation stems from performance specifications, such as ultra-low loss, and brand premium for established innovators like Corning Incorporated. Pricing softness affects commodity segments due to intense competition and high input material costs for silica preforms.
Supply Chain Analysis
Certification and qualification gating are critical in the optical fiber supply chain, particularly for high-performance and regulated applications. High-purity silica glass preforms, the core raw material, are primarily sourced from a few countries, including China, the United States, and Japan. This geographic concentration creates supply chain vulnerability to regional trade policies and logistical disruptions. The downstream distribution model is shifting from exclusive supplier agreements to multi-sourcing strategies, with large distributors playing an elevated role.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
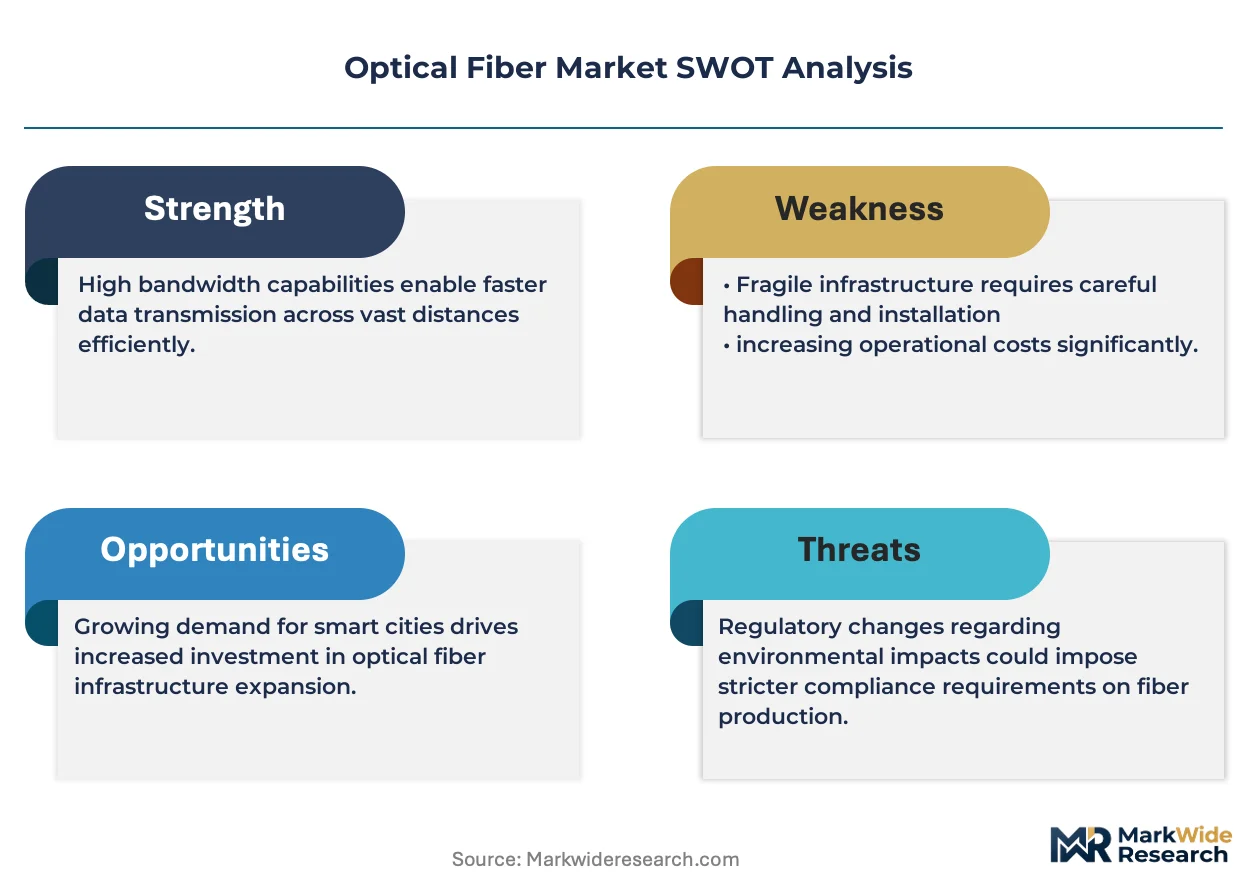
The optical fiber market functions as a stable compounder, driven by the continuous expansion of digital infrastructure globally. Sustained investment in national broadband programs and 5G network densification underpins its steady growth trajectory.
For Market Incumbents: Extend leadership in high-performance segments by deepening R&D into next-generation fibers like hollow-core designs. Invest in advanced manufacturing capabilities to counter commodity segment price erosion and maintain cost efficiency. Strategic partnerships with training institutions can alleviate installation skill bottlenecks, a persistent operational threat. Corning Incorporated should leverage its deep R&D to lead in low-loss fibers for subsea applications.
For New Entrants and Emerging Players: Begin with niche, application-specific solutions that leverage emerging technologies, such as specialized sensing or ultra-low latency hollow-core fiber. Target underserved regions like parts of Africa and Southeast Asia, where significant white space exists for new terrestrial deployments. A go-to-market strategy focusing on high-value, performance-critical applications in scientific computing can offer differentiation.
For Investors and Strategic Acquirers: Telecommunication infrastructure funds are the most active acquirers in this space, seeking long-term, stable returns from essential digital assets. The market offers attractive opportunities over a 5-10 year window, particularly in companies with strong intellectual property in specialty fibers or established manufacturing scale. Monitor shifts in national broadband subsidy programs, as these directly influence large-scale project viability and procurement volumes.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Preform Manufacturing Capacity | This initiative reduces supply chain vulnerability to geographic concentration in core raw material production. |
| Invest in Fiber Installation Training Programs | Addressing the skilled labor scarcity accelerates network deployment timelines for Internet Service Providers. |
| Develop Hollow-Core Fiber Applications | This innovation creates new market segments for niche, performance-critical applications like high-frequency trading. |
| Diversify Geographic Sourcing for Components | Mitigating risks from regional trade policies enhances resilience for global cable producers like Prysmian Group. |
| Advance Bend-Insensitive Fiber Designs | These specialty fibers simplify installation in tight spaces, benefiting data center operators and FTTH providers. |
Research Approach
Multiple input streams — primary interviews, industry reports, and regulatory filings — were reconciled to build a comprehensive market view. This involved engaging with network operators, data center architects, material scientists, and government officials for qualitative insights. Secondary validation included national broadband program reports, MIIT directives, FCC filings, and company annual reports. Both bottom-up and top-down triangulation methods were applied to ensure data accuracy.
Data streams were reconciled within an analytical framework to project market evolution across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and geographic deployment scenario. Compound annual growth rates were derived through a regression analysis of historical trends and projected demand drivers. Key forecast inputs included fiber-to-the-home penetration rates and 5G base station density targets.
Several conditions sit outside the modeled scope, including specific regional geopolitical conflicts and unforeseen raw material supply shocks. Forecasts reflect assumptions regarding stable regulatory environments and continued digital infrastructure investment. A model refresh is warranted upon material change in global trade policies or national broadband funding.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Advanced Optics Market
Optics
Excimer Lasers for DUV Lithography Market
Optics
Polymeric Optical Fiber Market
Optics
North America Optical Imaging Market
Optics
3D Optical Microscope Market
Optics
Optical Wavelength Service Market
Optics
Anti Glare Film Market
Optics
Photostimulation Lasers Market
Optics
Europe Laser Interferometer Market
Optics
Picosecond Lasers Market
Optics
Digital Holographic Microscopy Market
Optics
Photonic Crystals Market
Optics
Smart Glass Market
Optics
Latin America Optical Imaging Market
Optics
EUV Pellicle Market
Optics
Tunable Laser Market