
 Fiber Optic Receiver Market | 2026-2036
Fiber Optic Receiver Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optic Receiver Market Analytics
Silicon photonics is broadening cost-performance boundaries in fiber optic receiver fabrication. Broadcom Inc. leverages vertically integrated foundry capabilities to control wafer-to-package timelines. Lumentum Holdings Inc. anchors its position through specialized indium phosphide laser-receiver integration. Coherent Corporation differentiates via coherent detection subsystems that span metro and long-haul optical networks.
A fiber optic receiver converts modulated optical signals into electrical signals through photodetector elements such as avalanche photodiodes or PIN diodes, typically operating at wavelengths of 850 nm, 1310 nm, or 1550 nm to enable high-bandwidth data transmission across fiber networks. The device serves as the terminal node in optical communication links, demodulating light pulses for downstream signal processing in telecom, data center, and broadcasting infrastructure. DWDM receiver modules command premium positioning due to wavelength-selective complexity and dense channel requirements in core networks. PIN-based architectures dominate volume shipments across data center interconnects where cost sensitivity outweighs sensitivity specifications. Coherent detection technology leads growth velocity as 400G and 800G line cards displace direct-detection platforms in hyperscale deployments.
FCC broadband infrastructure mandates, EU Green Deal digital connectivity targets, and China's MIIT gigabit optical network standards collectively elevate minimum performance thresholds and procurement specifications for receiver modules. FDA regulatory frameworks for medical fiber optic sensors create adjacent compliance pathways that some suppliers exploit for diversified revenue streams. Stakeholders must monitor foundry capacity allocation between silicon photonics and legacy III-V compound semiconductor processes to secure supply continuity.
Market Dynamics
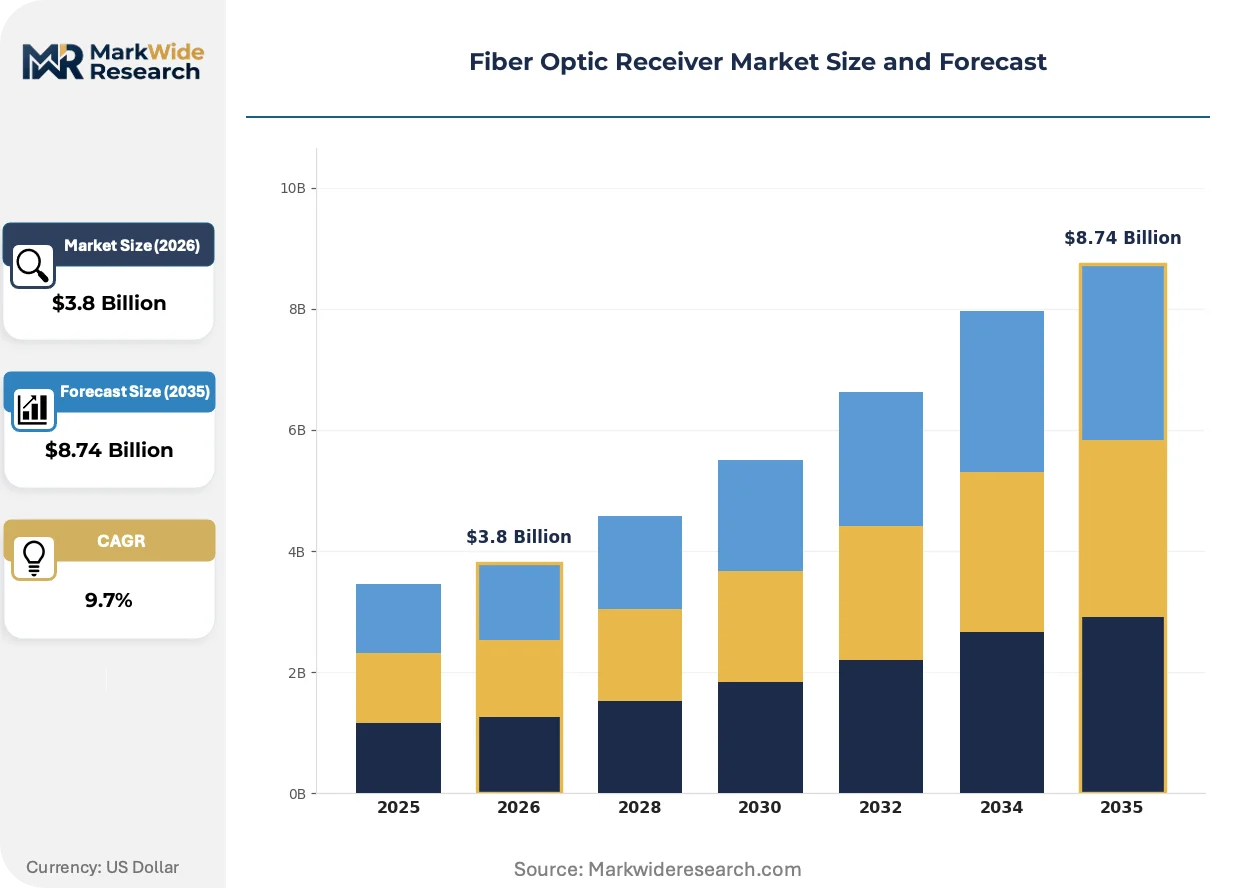
Silicon photonics integration is compressing cost curves for high-speed fiber optic receivers while hyperscale data center operators consolidate procurement around 400G and 800G coherent platforms. This technology migration is redrawing competitive boundaries between III-V compound semiconductor and CMOS-based supply chains.
Growth Catalysts
- China MIIT Gigabit Optical Standards:National broadband mandates drive volume procurement of 25G and 100G PON receivers across provincial network upgrades. Municipal governments bundle optical infrastructure into smart city tenders.
- Hyperscale Data Center Expansion:Cloud operators deploy coherent detection subsystems for 800G intra-data center links. AI training clusters demand low-latency optical interconnects at unprecedented port density.
- Indium Phosphide Laser-Receiver Integration:Specialized packaging reduces optical coupling losses for metro and long-haul applications. Integrated photonics modules shrink footprint while improving thermal stability.
Market Restraints
- III-V Foundry Concentration:Indium phosphide wafer capacity concentrates among a handful of merchant foundries in Taiwan and the United States. Geopolitical friction threatens substrate supply continuity for high-performance receivers.
- Raw Material Cost Volatility:Indium and gallium prices fluctuate with mining output from Chinese and Korean refiners. Input cost spikes compress margins on PIN-based volume products.
- EU RoHS Compliance Burden:Restrictions on hazardous substances in electronics manufacturing force redesign of legacy receiver packages. Certification timelines extend product development cycles by six to twelve months.
Strategic Opportunities
- India National Broadband Mission:Subsidized rural fiber deployment creates demand for cost-optimized 10G receivers. Domestic manufacturing incentives under PLI schemes attract module assembly investments.
- Coherent DSP-Photonics Convergence:Integration of digital signal processors with silicon photonics receivers enables software-defined optical links. This architecture supports multi-rate operation without hardware swaps.
- Medical Fiber Optic Sensing:FDA regulatory pathways for minimally invasive surgical instruments create adjacent revenue streams. Specialized receivers for biomedical applications command premium pricing.
Industry Challenges
- Silicon Photonics Talent Scarcity:Design expertise in photonic integrated circuits remains concentrated among a small cohort of researchers. Foundries compete aggressively for experienced layout engineers.
- Legacy Network Integration Complexity:Coherent receivers must interoperate with installed direct-detection infrastructure during transition periods. Dual-mode compatibility increases firmware validation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Receiver Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode Receiver, Multi-Mode Receiver, CWDM Receiver, DWDM Receiver Technology: APD, PIN, Coherent Detection, Optical Amplifiers Application: Telecommunications, Data Centers, Broadcasting, Networking End User: Telecom Operators, Enterprises, Government, Research Institutions |
| Companies Covered | Broadcom Inc., Lumentum Holdings Inc., Coherent Corporation, Sumitomo Electric Industries, Accelink Technologies, Fujitsu Optical Components, EMCORE Corporation, Acacia Communications Inc., Furukawa Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Receiver Market Evolving Landscape
Coherent detection architectures are displacing direct-detection platforms across metro and data center interconnects. This shift compresses power consumption per bit while enabling software-tunable transmission parameters.
Silicon photonics with monolithically integrated germanium photodetectors is electrifying receiver cost-performance boundaries. Hyperscale operators at Amazon Web Services, Microsoft Azure, and Google Cloud Platform are adopting these devices for 400G and 800G line cards. The technology is compressing module costs below fifty dollars per 100G-equivalent port, forcing legacy III-V suppliers to defend position through specialized high-sensitivity applications.
The US CHIPS and Science Act is channeling subsidies into domestic photonics manufacturing capacity. Commerce Department funding priorities favor silicon photonics foundries capable of serving defense and commercial markets simultaneously. Defense contractors and telecom equipment vendors are relocating supply agreements to qualified domestic facilities to secure preferential allocation.
Hyperscale procurement consolidation is compressing vendor counts and extending contract durations. Cloud operators now negotiate three-to-five-year supply agreements with volume commitments and price-down schedules. This concentration is visible most acutely in North American and Chinese markets where three buyers control over sixty percent of 400G-plus port demand.
Fiber Optic Receiver Market Segmentation
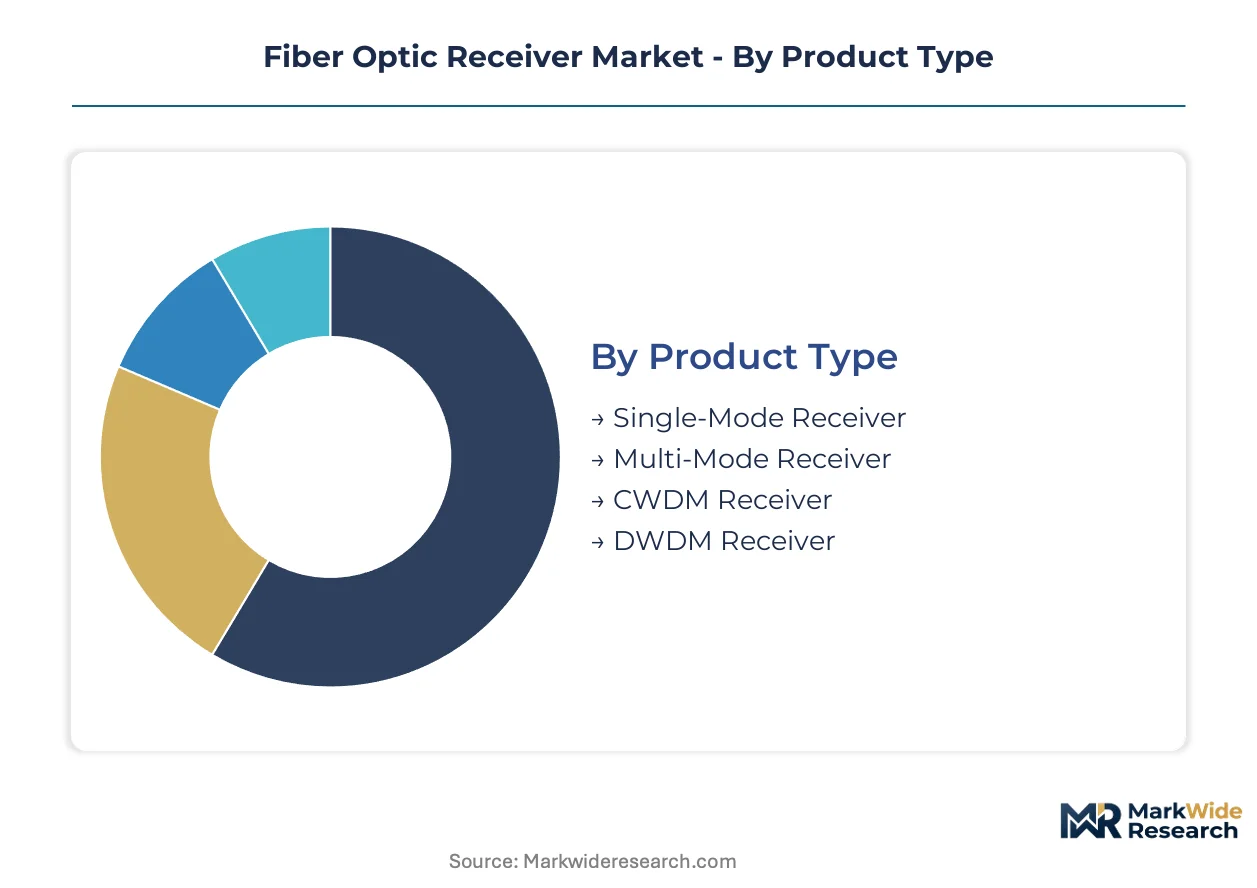
Receiver segmentation reveals divergent capital requirements across optical technologies. Single-mode architectures demand precision foundry investments while coherent detection platforms require integrated DSP-photonics co-design capabilities.
Product Type:
DWDM and coherent-capable receivers command the highest upfront capital commitments for wavelength-selective filtering and thermal stabilization subsystems.
- DWDM Receiver:Dense wavelength-division multiplexing receivers integrate arrayed waveguide gratings and temperature-controlled packaging to isolate individual channels across the C-band and L-band spectrum. China MIIT gigabit optical standards and provincial network upgrades in Sichuan and Guangdong provinces concentrate procurement volume for these modules.
- Single-Mode Receiver:These devices target 1310 nm and 1550 nm operation with tight mode-field diameter tolerances for long-haul fiber plants. Metro network operators in Germany and Japan specify these receivers for 100G coherent upgrades where fiber plant quality supports extended reach without amplification.
- Multi-Mode Receiver:Short-reach 850 nm receivers serve data center rack-to-rack interconnects with relaxed alignment tolerances.
- CWDM Receiver:Coarse wavelength-division devices reduce filter complexity for enterprise and access networks.
Single-mode receivers absorb the bulk of installed capacity; DWDM receivers are expanding most quickly.
Technology:
Coherent detection platforms require the steepest R&D investment curves for analog-to-digital converter integration and real-time digital signal processing firmware.
- Coherent Detection:These receivers combine dual-polarization quadrature demodulation with high-speed ADCs to recover phase and amplitude information from modulated optical carriers. Hyperscale data center operators at Amazon Web Services and Microsoft Azure drive 400G and 800G line card procurement for intra-facility links.
- PIN:Positive-intrinsic-negative photodiodes dominate volume shipments through simpler epitaxial structures and lower bias voltage requirements. Data center interconnects in Ashburn, Virginia and Frankfurt, Germany prioritize these cost-optimized receivers where link budgets accommodate reduced sensitivity.
- APD:Avalanche photodiodes multiply photocurrent through impact ionization for extended reach applications.
- Optical Amplifiers:Erbium-doped fiber amplifier-integrated receivers boost weak signals before photodetection in submarine cable terminals.
PIN technology captures the greatest shipment volumes; coherent detection platforms are climbing the fastest.
Application:
Telecommunications infrastructure demands the longest qualification timelines and largest contract values for receiver procurement.
- Telecommunications:Core network deployments require receivers certified to ITU-T G.709 and G.798 standards with guaranteed interoperability across multi-vendor optical transport platforms. India's National Broadband Mission and BharatNet rural fiber program create demand for 10G and 25G receivers with extended temperature specifications.
- Data Centers:Cloud computing facilities prioritize port density and power efficiency over receiver sensitivity metrics. Singapore and Dublin data center clusters specify 800G pluggable coherent receivers for spine-layer interconnects where fiber exhaustion drives wavelength reuse.
- Broadcasting:Professional video transport networks utilize receivers with minimal jitter for uncompressed 4K and 8K signal distribution.
- Networking:Enterprise campus and metro Ethernet applications standardize on lower-cost direct-detection receivers.
Telecommunications absorbs the bulk of installed capacity; data center applications are gaining share fastest.
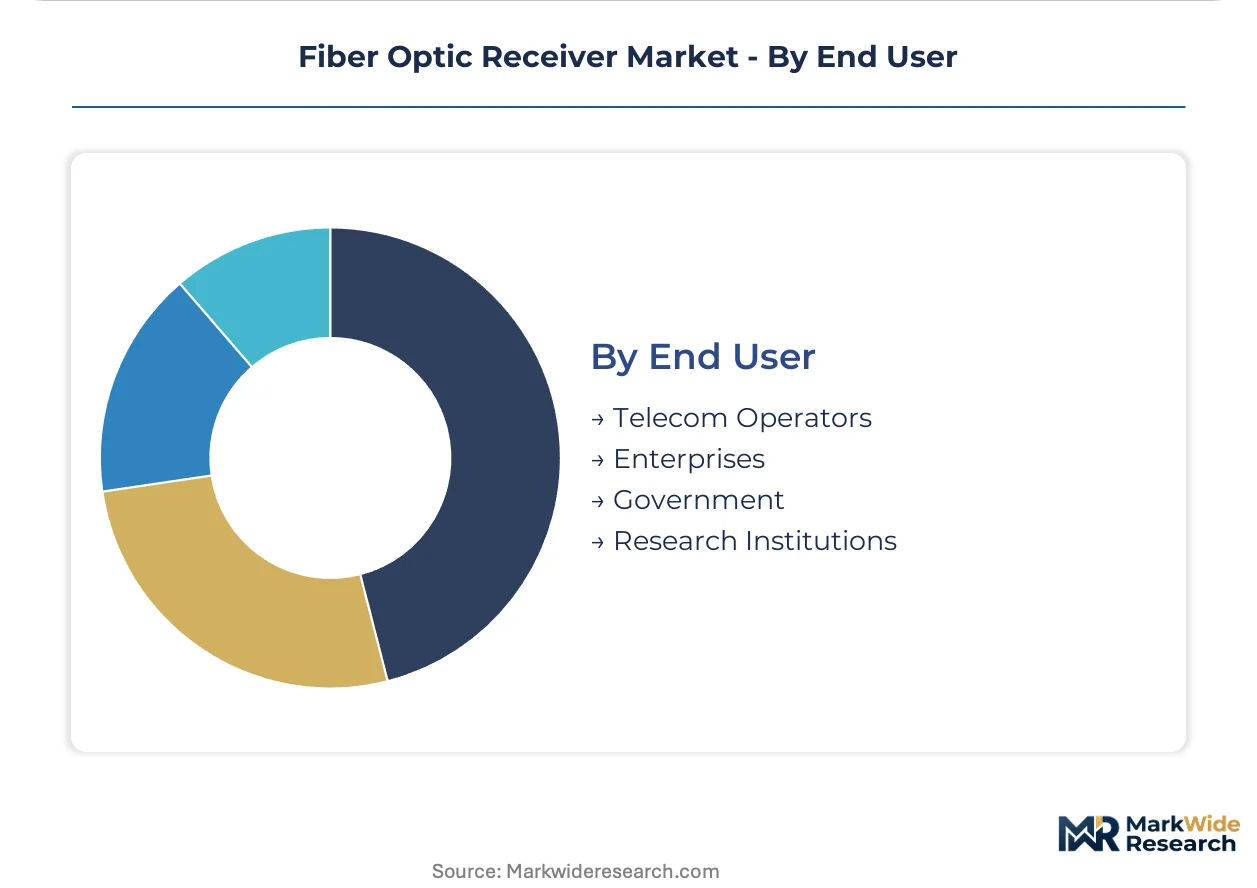
End User:
Telecom operators concentrate procurement volume through multi-year framework agreements with strict reliability and supply continuity clauses.
- Telecom Operators:Incumbent carriers and mobile network operators specify receivers against rigid network equipment building system criteria for central office deployment. Verizon, AT&T, and Deutsche Telekom negotiate three-to-five-year supply agreements with volume commitments and annual price-down schedules.
- Enterprises:Financial services firms and cloud software vendors deploy private optical networks with receiver specifications tailored to latency-sensitive trading or disaster recovery requirements.
- Government:Defense and intelligence agencies procure ruggedized receivers through classified supply chains with domestic content mandates.
- Research Institutions:National laboratories and university consortia acquire specialized receivers for experimental quantum communication and sensing platforms.
Telecom operators command the bulk of procurement volume; enterprise buyers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement volume for fiber optic receivers through national broadband mandates, while the United States and Germany anchor premium coherent detection demand. India and Japan represent emerging procurement centers with distinct regulatory drivers and infrastructure investment cycles.
United States
Hyperscale data center operators in Ashburn, Virginia and the Pacific Northwest drive 800G coherent receiver procurement for AI training clusters. The CHIPS and Science Act channels Commerce Department subsidies into domestic silicon photonics foundry capacity. Defense contractors in Arizona and Texas are relocating supply agreements to qualified domestic facilities for preferential allocation.
China
Provincial network upgrades in Sichuan and Guangdong provinces concentrate volume demand for 25G and 100G PON receivers. MIIT gigabit optical network standards mandate minimum performance thresholds for equipment deployed in national broadband expansion. Municipal governments in Yangtze River Delta cities bundle optical infrastructure into smart city tender packages.
Germany
Deutsche Telekom negotiates multi-year framework agreements for metro coherent upgrades where fiber plant quality supports extended reach. EU Green Deal digital connectivity targets elevate procurement specifications for energy-efficient receiver modules. Industrial clusters in Bavaria and Baden-Württemberg host precision packaging facilities serving European telecom operators.
India
BharatNet rural fiber program and the National Broadband Mission create demand for cost-optimized 10G receivers with extended temperature specifications. PLI scheme manufacturing incentives attract module assembly investments from multinational suppliers. Telangana and Karnataka data center clusters in Hyderabad and Bangalore specify coherent pluggable receivers for cloud infrastructure expansion.
Japan
NTT and KDDI specify receivers against rigid network equipment building system criteria for central office deployment in Tokyo and Osaka metro areas. METI industrial policy supports domestic indium phosphide foundry capacity for specialized high-sensitivity applications. Chubu region photonics clusters near Nagoya maintain legacy packaging expertise for submarine cable terminals.
Fiber Optic Receiver Market Competitive Landscape
Capacity expansion dominates the current landscape as silicon photonics foundries race to serve hyperscale procurement consolidation. The vendor base separates into three tiers: vertically integrated semiconductor conglomerates with captive wafer supply, specialized III-V compound semiconductor houses with indium phosphide expertise, and fabless design firms licensing silicon photonics IP. Strategic differentiation runs through backward integration into substrate supply and forward integration into module-level assembly.
Within the vertically integrated tier, Broadcom Inc. and Lumentum Holdings Inc. occupy positions that exemplify divergent technology bets—Broadcom through CMOS-based silicon photonics scale and Lumentum through compound semiconductor specialization. Coherent Corporation anchors the coherent detection subsystem segment, representing the convergence of digital signal processing with photonic integration. These three Inc.-structured entities collectively illustrate how competitive positioning separates across foundry model, materials science capability, and end-market focus.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Lumentum Holdings Inc. |
| Coherent Corporation |
| Sumitomo Electric Industries |
| Accelink Technologies |
| Fujitsu Optical Components |
| EMCORE Corporation |
| Acacia Communications Inc. |
| Furukawa Electric |
| Others |
Value Network & Pricing Analysis
Indium phosphide wafer costs transmit directly from Taiwanese and American merchant foundries through three-tier pricing structures separating coherent detection modules from PIN-based volume products and economy-grade access receivers. Hyperscale procurement consolidation at Amazon Web Services and Microsoft Azure compresses margins on high-volume 400G and 800G line cards while specialized indium phosphide suppliers defend premium positioning through wavelength-selective complexity.
Pricing Analysis
Volume shipments of PIN-based receivers for data center interconnects operate on razor-thin margins, while coherent detection subsystems for metro and long-haul networks retain pricing power through integrated DSP-photonics co-design requirements. Price differentiation separates ITU-T G.709-certified modules for telecom central offices from uncertified enterprise-grade alternatives, with hyperscale cloud operators driving the steepest cost compression through three-to-five-year supply agreements bundling volume commitments with annual price-down schedules. Pricing pressure stems from silicon photonics integration compressing module costs below fifty dollars per 100G-equivalent port, forcing legacy III-V suppliers toward specialized high-sensitivity applications. Telecom operators exhibit the lowest price sensitivity due to reliability clauses and qualification timelines, while data center procurement teams prioritize port-density economics over receiver sensitivity specifications.
Supply Chain Analysis
ITU-T G.709 and G.798 certification gates restrict qualified supplier pools for telecom infrastructure, with substrate supply anchored in Taiwanese indium phosphide foundries and American silicon photonics facilities. Raw material dependencies span indium and gallium from Chinese and Korean refiners, germanium for photodetector integration, and specialized ceramic packaging substrates from Japanese suppliers. Supply chain risk concentrates in single-source vulnerability for indium phosphide wafer capacity amid geopolitical friction affecting substrate continuity. Distribution runs through direct long-term contracts with telecom equipment vendors and hyperscale operators, bypassing traditional component distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fiber optic receiver market sits in a technology-transition phase as coherent detection architectures displace direct-detection platforms across metro and data center interconnects, with silicon photonics integration rewriting cost-performance boundaries established by legacy III-V compound semiconductor processes.
For Market Incumbents: Anchor defensive positioning through captive indium phosphide foundry capacity and backward integration into substrate supply, while accelerating silicon photonics R&D to counter CMOS-based challengers. Secure preferential allocation at domestic facilities qualified under CHIPS Act funding priorities. Prioritize certification investment for ITU-T standards to maintain telecom operator procurement access against emerging fabless competitors. For New Entrants and Emerging Players: The eighty-dollar-per-port gap between premium coherent modules and economy-grade PIN receivers creates entry space for cost-optimized 25G PON devices serving India's BharatNet rural fiber program and China's provincial network upgrades. Target municipal smart city tenders in Yangtze River Delta cities where optical infrastructure bundling lowers customer acquisition costs. Pursue module assembly partnerships with PLI scheme beneficiaries in Telangana and Karnataka to bypass capital-intensive foundry investments. For Investors and Strategic Acquirers: Foundry qualification announcements under Commerce Department CHIPS Act disbursements are the leading indicator that domestic silicon photonics capacity will reshape competitive boundaries over the next decade. Acquisition targets should prioritize fabless design firms with licensed silicon photonics IP and established hyperscale customer relationships. Monitor hyperscale capex disclosure shifts toward 800G coherent pluggable modules as the signal for technology-transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Qualification | CHIPS Act funding secures preferential allocation for defense and commercial markets simultaneously. |
| Coherent DSP-Photonics Integration | Software-defined optical links enable multi-rate operation without hardware swaps at hyperscale facilities. |
| Indium Phosphide Capacity Expansion | Specialized substrate supply anchors premium positioning for metro and long-haul wavelength-selective modules. |
| Medical Fiber Optic Sensing Diversification | FDA regulatory pathways for minimally invasive surgical instruments create adjacent revenue streams. |
| India PLI Scheme Module Assembly | Domestic manufacturing incentives attract cost-optimized 10G receiver investments for BharatNet deployment. |
Research Methodology
Independent corroboration across hyperscaler procurement disclosures, telecom equipment vendor supply agreements, and foundry capacity announcements underwrites the qualitative findings in this study. Primary interviews with optical transport platform engineers, data center interconnection specialists, and photonic integrated circuit layout designers combined with secondary validation from SEC filings, MIIT equipment certification databases, and Commerce Department CHIPS Act funding announcements. Bottom-up triangulation across receiver module shipment estimates and top-down cross-checks against optical transport equipment revenue disclosures ensure analytical consistency.
Rate-of-change decomposition across the analysis window separates volume growth in PIN-based data center interconnects from value expansion in coherent detection platforms. Segmentation dimensions modeled include product type, detection technology, application vertical, and end-user procurement archetype, with geographic supply concentration and regulatory certification requirements as additional industry-specific forecast inputs. CAGRs were derived from fitted growth curves against disclosed hyperscale capex trajectories and national broadband deployment schedules.
Inputs from hyperscaler procurement teams and telecom operator technical specifications were available through the study window; gaps in classified defense procurement data introduce uncertainty bands around ruggedized receiver estimates. Forecasts reflect assumptions regarding silicon photonics yield maturation and indium phosphide substrate supply continuity. A model refresh is warranted upon material change in Commerce Department foundry qualification timelines or MIIT gigabit optical standards revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
APAC Smart Glass Market
Optics
Optical Gratings Market
Optics
Fixed Focal Length Lenses Market
Optics
Excimer Laser Market
Optics
Anomaloscope Market
Optics
Global Optical Lens Market
Optics
Europe Laser Interferometer Market
Optics
Stroboscope Market
Optics
3D Optical Microscope Market
Optics
Laser Transmitter Market
Optics
Photonics Sensor Market
Optics
AR and VR Lens Market
Optics
MEMS Mirrors Market
Optics
Fiber Optic Amplifier Market
Optics
Asia-Pacific Anti-Blue Ray Myopia Lenses Market
Optics
Middle East and Africa Tunable Laser Market