
 Lasers Market | 2026-2036
Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Lasers Market Outlook
Semiconductor-grade silicon carbide is pivoting into laser diode substrates, displacing traditional sapphire and gallium arsenide platforms. TRUMPF leverages captive crystal growth capabilities to secure supply chain control over pump source materials. IPG Photonics anchors its position through in-house production of specialty optical fibers. Coherent Corp. differentiates via vertical integration into nonlinear crystal manufacturing for frequency conversion modules.
A laser is a device that amplifies light through stimulated emission of radiation, producing a coherent, monochromatic, and highly directional beam with precise wavelength control and power stability. Industrial systems typically operate at specific wavelengths from ultraviolet through infrared, enabling material interaction through photothermal or photochemical mechanisms for cutting, welding, and surface treatment. Fiber lasers now lead product type categories due to superior wall-plug efficiency and maintenance intervals. Solid-state lasers retain margin concentration in medical surgery applications where beam quality and pulse stability command premium pricing. Communication applications under pulsed technology are accelerating with datacenter interconnect buildouts.
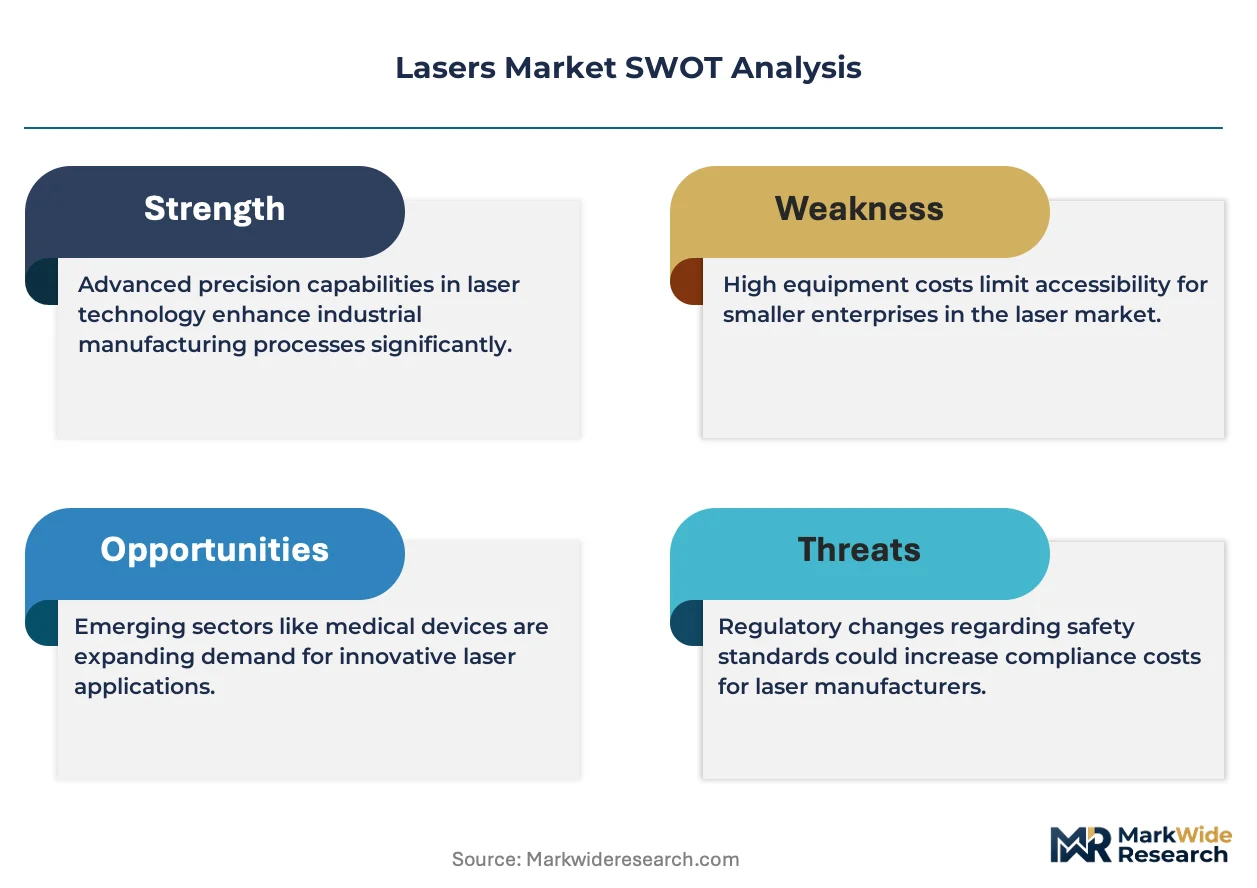
FDA device classification rules govern surgical laser approvals in the United States, while the EU MDR imposes clinical evidence requirements on therapeutic systems sold in Europe. China's SAMR enforces GB standards for industrial laser safety and electromagnetic compatibility, shaping market access protocols for imported equipment. Stakeholders must monitor divergence between regional certification regimes as dual carbon goals in Beijing and the EU Green Deal tighten energy efficiency mandates.
Market Dynamics
Precision manufacturing in automotive assembly lines is compressing laser procurement cycles while EU F-Gas Regulation constraints force refrigerant-dependent gas laser operators toward alternative architectures. Material substrate transitions in diode manufacturing are redistributing supply chain leverage toward captive crystal growers.
Growth Catalysts
- Automotive Electrification:Battery cell tab welding and hairpin stator processing consume ultrafast fiber lasers at volumes exceeding traditional sheet-metal cutting. German OEMs anchor this pull through their Jena and Munich photonics clusters.
- EU MDR Clinical Evidence Pathways:Streamlined therapeutic laser approvals in Europe accelerate commercialization timelines for surgical systems targeting ophthalmology and dermatology segments.
- Silicon Carbide Substrate Migration:Semiconductor-grade SiC wafers are displacing sapphire and gallium arsenide platforms for high-power diode applications, improving thermal conductivity and extending operational lifespan.
Market Restraints
- Specialty Optical Fiber Supply Concentration:Rare-earth doped fiber production clusters with Chinese and US suppliers, exposing downstream system integrators to allocation risk during demand surges.
- EU F-Gas Phase-Down Schedule:Refrigerant restrictions on carbon dioxide and excimer gas lasers force retrofit investments or forced obsolescence of installed base equipment.
- Frequency Conversion Crystal Sourcing:Nonlinear optical materials for ultraviolet generation concentrate with limited qualified vendors, constraining wavelength flexibility for precision microprocessing applications.
Strategic Opportunities
- Datacenter Interconnect Buildouts:Pulsed laser demand for optical communications infrastructure accelerates with cloud provider capacity expansion, particularly in hyperscale facilities requiring coherent transceivers.
- India's PLI Scheme for Photonics:Production-linked incentives for component manufacturing attract module assembly investments serving domestic industrial automation and medical device markets.
- Additive Manufacturing Repair:Directed energy deposition systems utilizing high-power direct diode lasers enable remanufacturing of aerospace turbine components, opening aftermarket service revenue streams.
Industry Challenges
- Rare-Earth Doping Process Expertise:Specialized fiber fabrication requires chemists and optical engineers with experience in MCVD and solution doping techniques, talent pools that concentrate with incumbent suppliers.
- Dual Certification Burden:Surgical laser vendors must simultaneously satisfy FDA 510(k) documentation and EU MDR clinical evaluation requirements, extending time-to-revenue by 18-24 months.
- Legacy Gas Laser Retrofit Complexity:Industrial customers face production line downtime and control system incompatibility when transitioning from excimer or CO2 architectures to solid-state alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lasers Market |
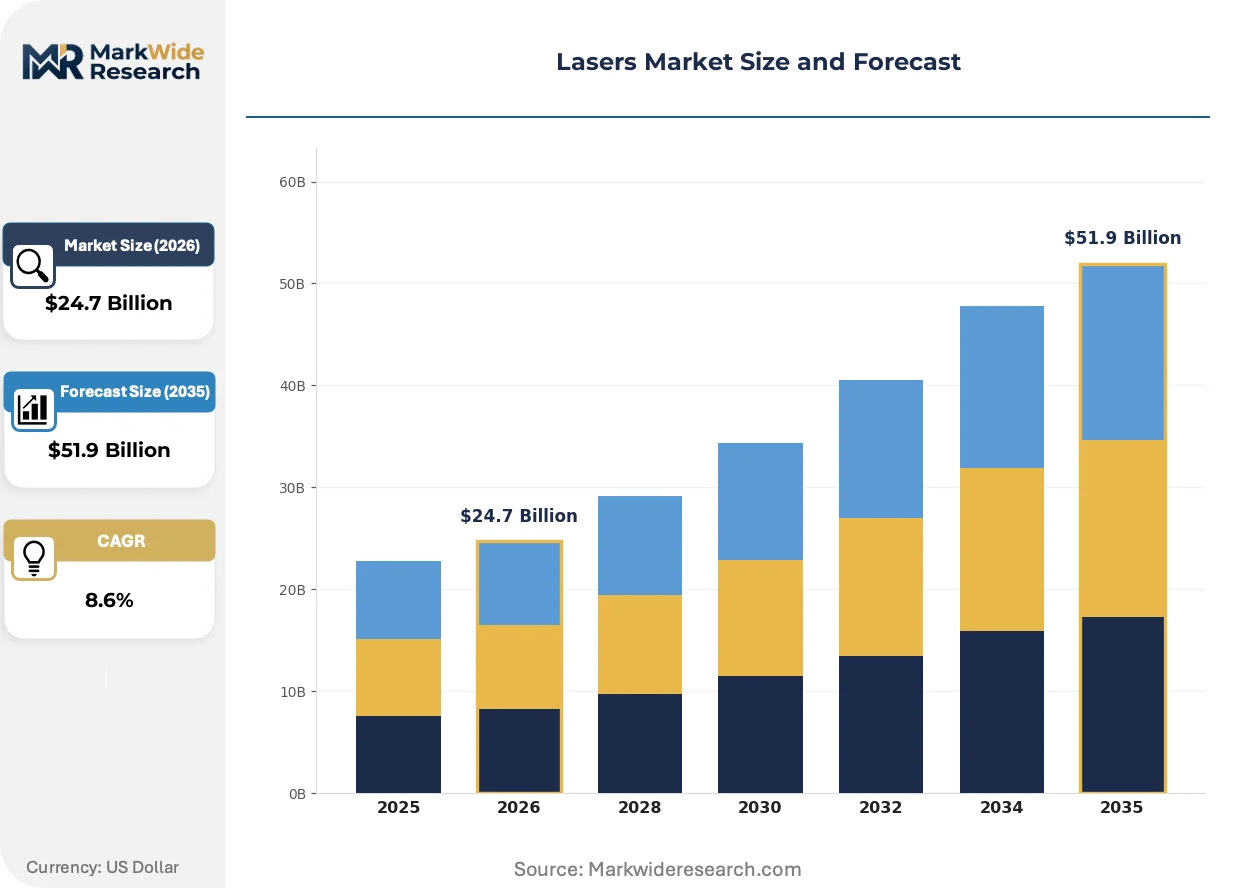
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $51.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid-State Lasers, Gas Lasers, Fiber Lasers, Dye Lasers Application: Industrial Cutting, Medical Surgery, Material Processing, Communication End User: Aerospace, Healthcare, Electronics, Automotive Technology: Continuous Wave, Pulsed, Q-Switched, Mode-Locked |
| Companies Covered | Coherent Corp., TRUMPF, Han's Laser Technology Industry Group Co., Ltd., IPG Photonics Corporation, JENOPTIK AG, Lumentum Operations LLC, Novanta Inc., nLIGHT, Inc., Bystronic Laser AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lasers Market Strategic Shifts
Beam delivery architectures and wavelength conversion methods are converging toward unified platforms that span multiple material processing applications. Regulatory pressure on refrigerants and clinical evidence standards is simultaneously reshaping product roadmaps.
Fiber laser technology is unifying previously discrete application categories through programmable beam shaping and power modulation. Automotive battery manufacturers now deploy single-platform systems for both welding and surface texturing operations. This consolidation compresses capital expenditure requirements while extending vendor service contract scopes.
The EU F-Gas Regulation mandates progressive refrigerant phase-down for industrial cooling systems, directly impacting carbon dioxide laser operating economics. Equipment lessors in Germany and France are accelerating depreciation schedules for gas-based assets. System vendors respond with air-cooled solid-state alternatives targeting the same cutting thickness ranges.
Industrial buyers are consolidating vendor relationships around full-service contracts bundling equipment, consumables, and predictive maintenance. German automotive tier-one suppliers now specify outcome-based agreements with uptime guarantees rather than capital purchase models. This shift concentrates procurement influence with integrated platform vendors possessing regional service infrastructure.
Lasers Market Segmentation
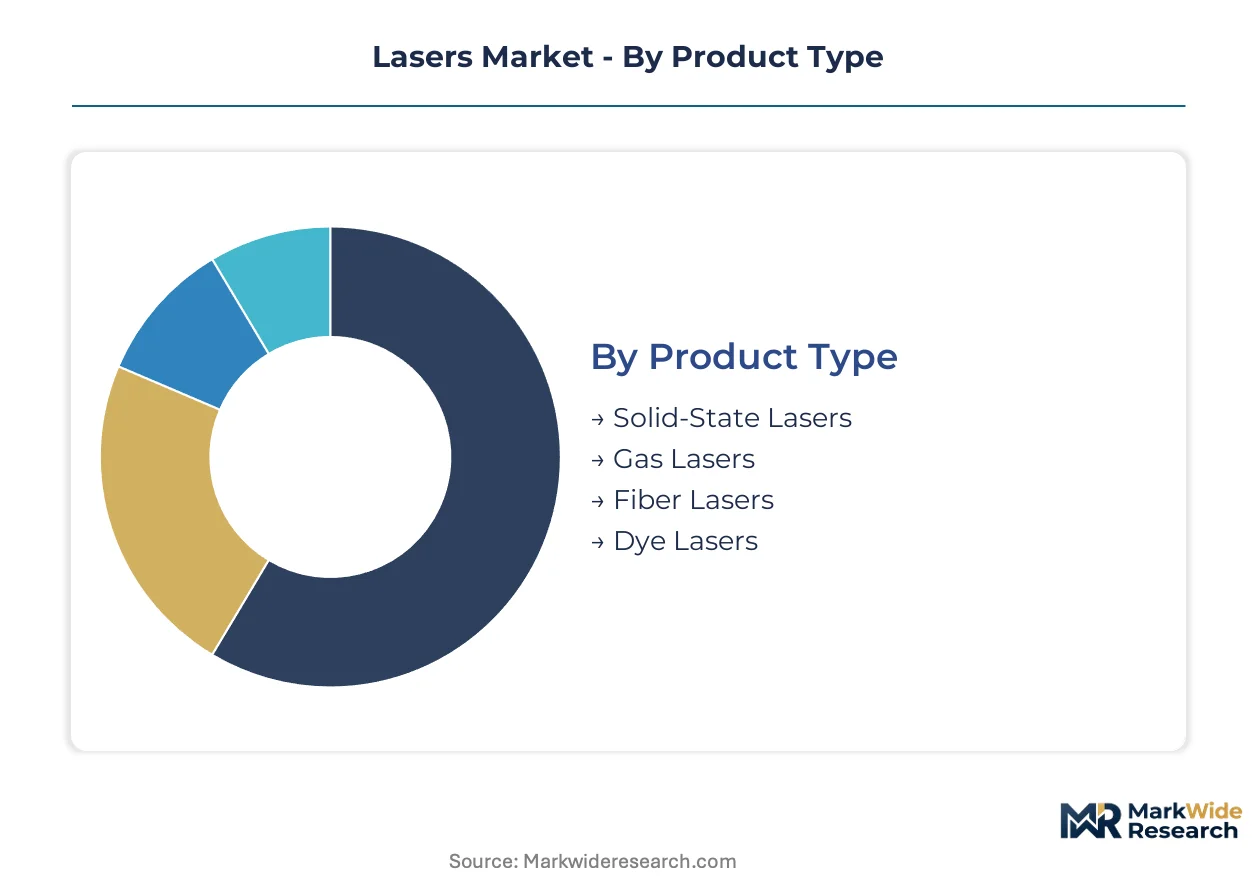
Segmentation in the Lasers Market reveals how technical specifications, application requirements, and end-use environments dictate procurement patterns. Buyers select architectures based on thermal management needs, wavelength precision, and integration complexity with existing production infrastructure.
Product Type:
The customization-to-standardization spectrum spans from configurable solid-state platforms to commodity fiber laser modules with fixed beam parameters.
- Fiber Lasers:These systems amplify light through rare-earth-doped silica fibers, delivering wall-plug efficiency exceeding competing architectures. Automotive battery tab welding in Germany's Jena-Munich corridor consumes these systems at volumes exceeding traditional metal cutting operations.
- Solid-State Lasers:Crystal-based gain media—typically Nd:YAG or Yb:YAG—produce high beam quality with exceptional pulse stability. Medical surgery applications in the United States command premium pricing here due to FDA device classification requirements for thermal precision.
- Gas Lasers:Carbon dioxide and excimer configurations remain entrenched in thick-material cutting despite EU F-Gas Regulation refrigerant constraints forcing operational retrofits.
- Dye Lasers:Organic dye solutions enable tunable wavelength output for spectroscopy and research applications with limited industrial scale.
Most installed capacity flows through Fiber Lasers. Expansion is steepest in Solid-State Lasers.
Application:
Cost tiers separate capital-intensive industrial systems from precision medical equipment with extended certification timelines.
- Industrial Cutting:High-power systems process metals, ceramics, and composites through photothermal ablation. German automotive OEMs anchor demand through their photonics clusters around Jena and Munich.
- Communication:Pulsed laser diodes power coherent transceivers for datacenter interconnect buildouts. Cloud provider capacity expansion in hyperscale facilities accelerates procurement cycles here.
- Medical Surgery:Beam quality and pulse stability requirements command premium pricing in ophthalmology and dermatology segments subject to EU MDR clinical evidence pathways.
- Material Processing:Surface treatment, marking, and additive manufacturing applications utilize programmable beam shaping across multiple substrate types.
Industrial Cutting carries the heaviest installed base. Communication is climbing the fastest.
End User:
Customer type determines specification rigor, with aerospace and medical buyers imposing qualification protocols that commodity electronics purchasers bypass.
- Automotive:Battery cell tab welding and hairpin stator processing consume ultrafast fiber lasers. German OEM procurement compresses vendor selection cycles around full-service contract models.
- Healthcare:Surgical and therapeutic systems face dual certification burdens—FDA 510(k) documentation plus EU MDR clinical evaluation—extending time-to-revenue by 18-24 months.
- Aerospace:Directed energy deposition systems enable turbine component remanufacturing, opening aftermarket service revenue streams for high-power direct diode platforms.
- Electronics:Semiconductor fabrication and microelectronics processing demand ultraviolet wavelength generation with limited qualified nonlinear crystal vendors.
Automotive channels the greatest throughput. Healthcare is expanding most quickly.
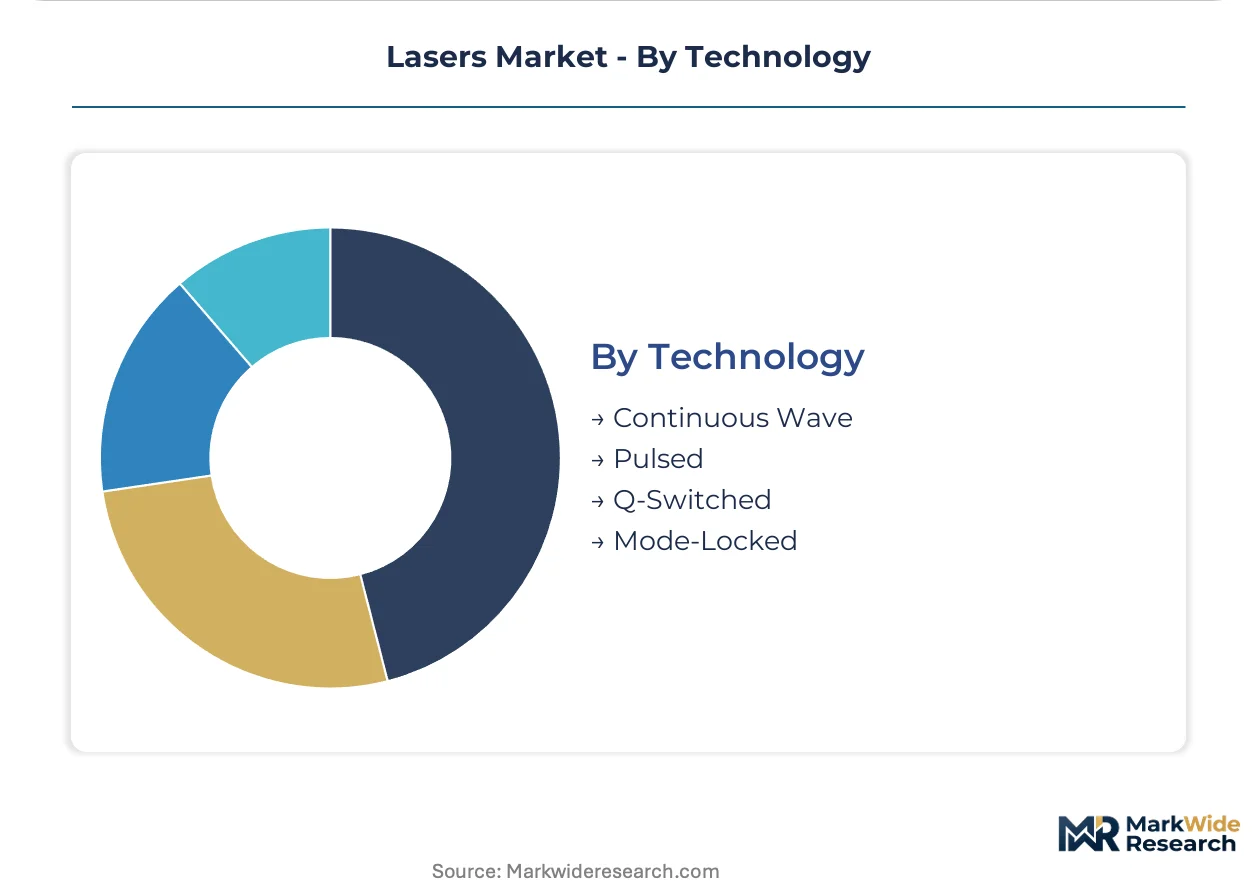
Technology:
Maturity curves separate established continuous wave architectures from emerging mode-locked platforms with specialized pulse engineering.
- Pulsed:Nanosecond to femtosecond pulse durations enable cold ablation with minimal heat-affected zones. Datacenter interconnect buildouts accelerate coherent transceiver demand.
- Continuous Wave:Steady-state output dominates industrial cutting and welding with simpler thermal management than time-domain modulated alternatives.
- Q-Switched:Cavity dumping produces high-peak-power pulses for marking and engraving applications with controlled pulse energy.
- Mode-Locked:Ultrafast pulse trains enable multiphoton microscopy and precision micromachining with sub-picosecond temporal resolution.
Continuous Wave retains the largest footprint. Pulsed technology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Jena-Munich photonics corridor concentrates precision manufacturing demand for industrial laser systems. Automotive electrification and battery cell processing anchor procurement volumes across multiple continents. Regulatory fragmentation around refrigerant phase-downs and clinical evidence standards is redistributing competitive positioning by geography.
Germany
Automotive OEMs in Bavaria and Thuringia consume ultrafast fiber lasers for battery tab welding and hairpin stator processing. The EU F-Gas Regulation forces refrigerant-dependent CO2 laser operators toward solid-state retrofits or accelerated depreciation. Equipment lessors in Munich and Stuttgart are restructuring service contracts around uptime-guaranteed outcome models rather than capital sales.
United States
FDA 510(k) pathways govern surgical laser approvals for ophthalmology and dermatology applications with extended documentation timelines. Cloud provider hyperscale datacenter buildouts accelerate pulsed laser demand for coherent transceiver modules. The Pacific Northwest and Texas corridor host fiber fabrication facilities serving communication infrastructure rollouts.
China
SAMR enforces GB standards for industrial laser safety and electromagnetic compatibility on imported equipment. Domestic production-linked incentive schemes attract module assembly investments for photonics component manufacturing. Yangtze River Delta fabrication clusters are expanding rare-earth doped fiber capacity to reduce import dependence.
Japan
METI coordinates national photonics initiatives supporting solid-state laser development for precision manufacturing. Medical device manufacturers face dual certification burdens bridging PMDA domestic approvals and EU MDR export requirements. Osaka-based industrial automation integrators specify full-service laser contracts with predictive maintenance clauses.
India
The PLI scheme for photonics component manufacturing attracts module assembly investments serving domestic industrial automation markets. BIS certification requirements shape market access protocols for imported industrial laser systems. Maharashtra and Gujarat industrial corridors are deploying fiber lasers for automotive sheet metal processing and electronics marking applications.
Lasers Market Competitive Environment
Backward integration into specialty materials dominates the current landscape, with crystal growth and optical fiber fabrication emerging as decisive control points. The vendor base clusters around three strategic archetypes: integrated platform vendors with captive substrate production, specialist component suppliers selling into system integrators, and regional service-intensive providers winning through proximity maintenance networks. M&A activity targets frequency conversion crystal vendors and rare-earth doping specialists, while capacity expansion concentrates in semiconductor-grade silicon carbide wafer fabrication for diode substrates.
Among Germany-based integrated manufacturers, TRUMPF and JENOPTIK AG exemplify the captive supply archetype through in-house crystal growth and optical component production. IPG Photonics Corporation anchors the specialty fiber fabrication tier with rare-earth doped silica production capabilities. These three entities represent distinct competitive positioning vectors: full-platform integration, component-level specialization, and vertical control over pump source materials.
| Leading Market Players |
|---|
| Coherent Corp. |
| TRUMPF |
| Han's Laser Technology Industry Group Co., Ltd. |
| IPG Photonics Corporation |
| JENOPTIK AG |
| Lumentum Operations LLC |
| Novanta Inc. |
| nLIGHT, Inc. |
| Bystronic Laser AG |
| Others |
Value Chain & Pricing Dynamics
Captive crystal growth for diode substrates anchors supply chain control and pricing power for integrated laser system vendors. TRUMPF's in-house silicon carbide production and IPG Photonics' rare-earth doped fiber fabrication demonstrate how backward integration into pump source materials insulates margin structures from raw material volatility. German automotive OEMs leverage this concentration through outcome-based service contracts rather than capital purchases.
Pricing Analysis
Input-cost pass-through from specialty optical fiber and nonlinear crystal suppliers shapes tiered pricing across system categories. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified surgical platforms from industrial cutting systems and commodity marking modules. Cost compression in fiber laser modules intensifies as Chinese rare-earth doping capacity expands. Electronics manufacturers exhibit highest price sensitivity due to volume procurement and short replacement cycles, while healthcare buyers accept premium positioning for dual-certified surgical equipment.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China form a hub-and-spoke pattern for laser system fulfillment. Manufacturing concentrates in Germany's Jena-Munich corridor, China's Yangtze River Delta, and Japan's Osaka industrial zone. Critical inputs draw from semiconductor-grade silicon carbide wafers, rare-earth doped silica fibers, and nonlinear optical crystals for frequency conversion. Single-source vulnerability around qualified frequency conversion crystal vendors constrains wavelength flexibility. Distribution runs through direct OEM relationships for automotive and aerospace, with distributor networks serving smaller industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on silicon carbide substrate cost curves flattening and premium-tier surgical systems capturing dual-certification pricing power. The shift from gas laser retrofits to solid-state replacements concentrates procurement influence with integrated platform vendors.
For Market Incumbents: Cement supply chain control through captive crystal growth investments in silicon carbide and rare-earth doped fiber capacity. Defend against Chinese module assemblers by locking German automotive OEMs into decade-long service contracts with uptime guarantees. Prioritize EU MDR certification maintenance to sustain surgical laser premium positioning against emerging solid-state competitors.
For New Entrants and Emerging Players: Direct-to-end-user digital sales channels bypass incumbent distributor networks in India's PLI-subsidized photonics corridor. Target additive manufacturing repair services for aerospace turbine remanufacturing as the most penetrable white-space segment. Lead with air-cooled solid-state platforms that sidestep EU F-Gas refrigerant constraints facing installed CO2 laser bases.
For Investors and Strategic Acquirers: Consolidation pressure builds where rare-earth doping process expertise concentrates with incumbent fiber fabricators and qualified nonlinear crystal vendors remain limited. Long-term viability favors vertically integrated platform vendors with regional service infrastructure over pure component suppliers. Watch for inflection when German equipment lessors accelerate depreciation schedules for gas-based assets, signaling forced obsolescence demand for solid-state retrofits.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Crystal Growth Investment | TRUMPF's silicon carbide wafer production secures pump source supply chain control against substrate shortages. |
| Dual Certification Pathway Completion | Simultaneous FDA 510(k) and EU MDR approvals unlock premium surgical laser pricing in ophthalmology segments. |
| Outcome-Based Service Contract Rollout | German automotive tier-one suppliers now specify uptime-guaranteed agreements replacing capital purchase models. |
| Air-Cooled Solid-State Platform Launch | EU F-Gas refrigerant phase-down forces CO2 laser operators toward retrofit-compatible solid-state alternatives. |
| Rare-Earth Doped Fiber Capacity Expansion | IPG Photonics' in-house specialty fiber fabrication reduces allocation risk during datacenter interconnect demand surges. |
Study Parameters
Coverage spans Germany, the United States, China, Japan, and India, with primary inputs from each regional photonics cluster. The analysis combines structured interviews with laser system procurement managers at German automotive OEMs, fiber fabrication engineers at rare-earth doping facilities, regulatory affairs specialists navigating FDA and EU MDR pathways, and aftermarket service heads at aerospace remanufacturing operations. Secondary validation draws from SAMR GB standard filings, EU F-Gas Regulation implementation reports, SEC 10-K disclosures from listed photonics vendors, and hyperscaler datacenter capex announcements. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions.
Rate-of-change decomposition separates volume effects from mix-shift and pricing components across the projection horizon. The analytical framework models segmentation dimensions including product type architecture, application end-use, technology maturity curve, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to normalized baseline data. Industry-specific forecast inputs incorporate EU F-Gas phase-down schedules for gas laser obsolescence and cloud provider hyperscale buildout timelines for pulsed laser communication demand.
Regulatory enforcement variance, rare-earth supply disruption, and automotive electrification cadence shifts are the dominant revision risks. Forecasts reflect documented assumptions on certification timeline standardization and substrate technology transition rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Germanium Lens Market
Optics
Optical Telescope Market
Optics
Polymeric Optical Fiber Market
Optics
Optical Liquid Level Sensor Market
Optics
Electro Optics Market
Optics
Fixed Focal Length Lenses Market
Optics
Fiber Optics Market
Optics
Photostimulation Lasers Market
Optics
Optical Fiber Raw Material Market
Optics
Smart Glass Market
Optics
Liquid Crystal on Silicon Market
Optics
Global Enhanced Vision System Market
Optics
Fiber Optic Amplifier Market
Optics
Acrylic Lenses Market
Optics
Photonics Sensor Market
Optics
Fiber Optic Receiver Market