
 Fiber-Optic Couplers Market | 2026-2036
Fiber-Optic Couplers Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber-Optic Couplers Market Analytics
Distribution through telecom equipment distributors is narrowing as fiber-optic coupler suppliers build direct relationships with hyperscale data center operators and national carriers. Corning Incorporated leverages its captive fiber manufacturing to control input costs and secure volume commitments from North American carriers. Fujikura Ltd anchors its position in Asia-Pacific through deep specialization in fusion-spliced coupler assemblies for submarine and terrestrial networks. Thorlabs Inc competes in the precision instrumentation tier, where laboratory and defense customers prize wavelength-specific performance over commodity pricing.
Fiber-optic couplers are passive optical devices that split or combine light signals between multiple fiber paths, typically fabricated through fused biconical tapering or planar lightwave circuit etching to achieve insertion losses below 0.3 dB in single-mode variants. These components enable wavelength division multiplexing, signal monitoring, and redundant pathing in networks where electrical regeneration would introduce unacceptable latency or power penalties. Single-mode couplers dominate value capture in long-haul and metro networks, while ruggedized couplers are gaining share in military and industrial deployments where mechanical stress and temperature cycling degrade standard assemblies. Multi-mode couplers retain volume leadership in data center interconnection, though margin pools are thinner due to standardized LC and MTP/MPO connector pairing.
The U.S. Federal Communications Commission enforces broadband deployment benchmarks that shape carrier procurement cycles for passive optical components, while the EU F-Gas Regulation and REACH chemical restrictions constrain the manufacturing chemistries available to European coupler fabricators. China's MIIT imposes GB standards on optical performance that foreign suppliers must meet for network equipment certification. Stakeholders must monitor how divergent national testing protocols and emerging sustainability disclosure rules in Europe reshape supplier qualification timelines and inventory positioning across regional hubs.
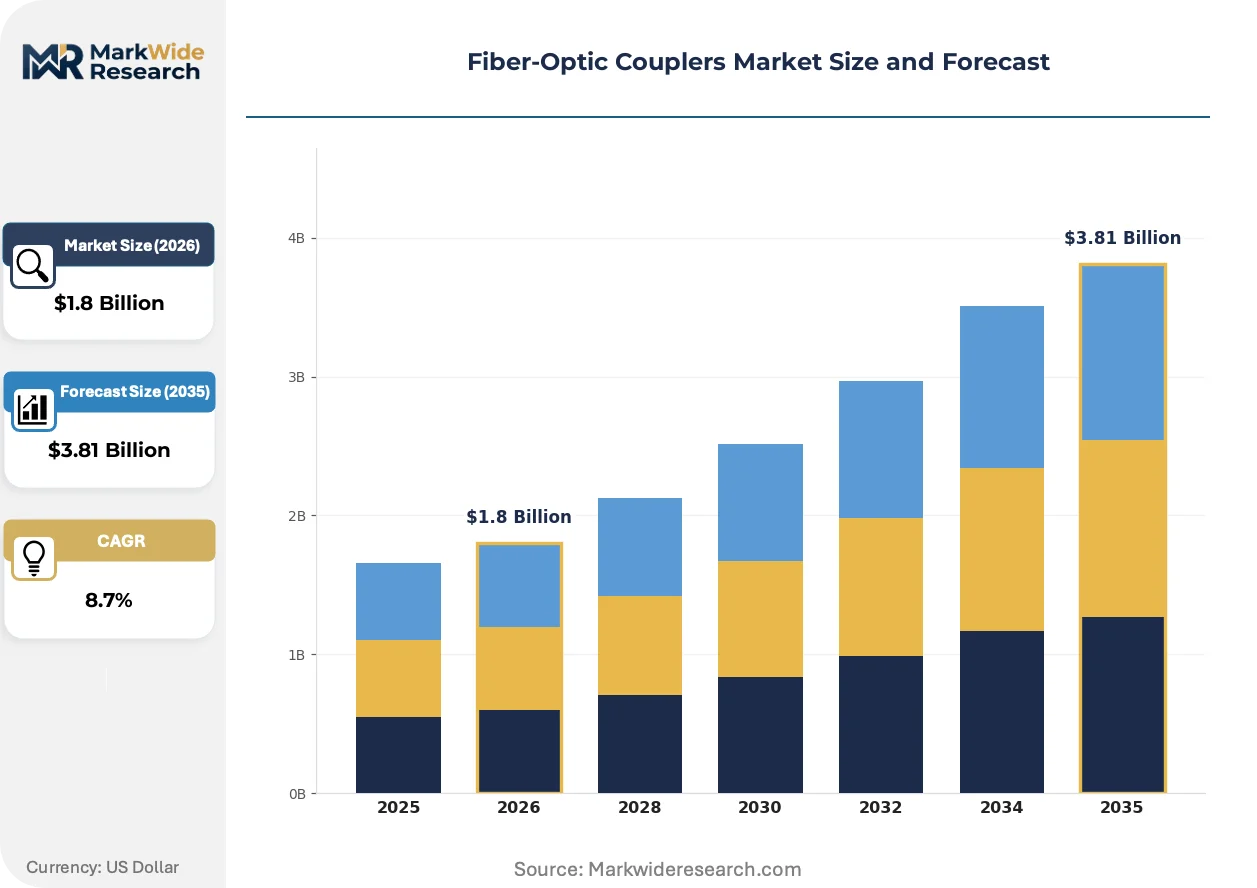
Market Dynamics
Data center operators are consolidating optical infrastructure procurement around single-source suppliers capable of guaranteeing insertion loss specifications below 0.3 dB across wavelength-division multiplexing architectures. This buyer concentration is compressing margins for coupler assemblers while rewarding vertically integrated fiber manufacturers with captive draw tower capacity.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:Germany's national broadband agency and France's environmental regulator are requiring network operators to deploy low-loss passive optical components that reduce electrical regeneration needs in metro rings.
- China's MIIT 5G backhaul programs:State-led procurement of single-mode and multi-mode coupler assemblies sustains volume commitments from domestic equipment vendors serving provincial carrier tenders.
- Fused biconical tapering automation:Process control advances in flame-brush fusion systems are lowering unit labor content and improving split-ratio consistency for high-channel-count couplers.
Market Restraints
- Silicon photonics substitution:Integrated optical switch fabrics on CMOS platforms are displacing discrete fiber couplers in hyperscale data center switching layers where port density exceeds 400 Gbps.
- Rare-earth dopant cost volatility:Erbium and ytterbium price swings in spot markets for fiber preform manufacturing create margin unpredictability for coupler fabricators without long-term chemical supply agreements.
- EU F-Gas Regulation compliance friction:REACH chemical restrictions on fluorinated cleaning agents used in planar lightwave circuit etching extend qualification timelines for European coupler manufacturers by 4-6 months.
Strategic Opportunities
- Defense ruggedization standards:MIL-PRF-49291 qualified coupler assemblies for avionics and shipboard applications command 3-4x pricing premiums over commercial-grade equivalents due to temperature cycling and mechanical shock requirements.
- India's BharatNet rural fiber expansion:The Department of Telecommunications' village-level optical connectivity targets are creating procurement windows for low-cost fused couplers in tier-3 and tier-4 network builds.
- Co-packaged optics convergence:Integration of silicon photonics engines with switch ASICs is hybridizing coupler architectures that bridge fiber-to-chip interfaces in next-generation data center switches.
Industry Challenges
- Fusion splicing technician scarcity:Specialized certification for low-loss fiber joining in submarine cable factories concentrates in coastal Japan and China, constraining capacity expansion for Western coupler assemblers.
- GB standards compliance burden:China's MIIT optical performance testing protocols require in-country laboratory validation that extends product registration timelines for foreign suppliers by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber-Optic Couplers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode Couplers, Multi-Mode Couplers, Ruggedized Couplers, Hybrid Couplers Industry Vertical: Telecommunications, Data Centers, Military, Broadcasting Connection Type: LC Connectors, SC Connectors, ST Connectors, MTP/MPO Connectors Material: Glass Fiber, Plastic Fiber, Ceramic, Metal |
| Companies Covered | Corning Incorporated, Fujikura Ltd, Furukawa Electric Co Ltd, Sumitomo Electric Industries Ltd, OFS Fitel LLC, Thorlabs Inc, Yangtze Optical Fibre and Cable Joint Stock Limited Company, LEONI AG, Gooch & Housego PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber-Optic Couplers Market Evolving Landscape
Optical component architectures are fragmenting between high-volume commodity assemblies for data center spine layers and precision-grade couplers for coherent transmission systems. This bifurcation is reshaping R&D allocation and manufacturing footprint decisions across the supplier base.
Planar lightwave circuit (PLC) technology is hybridizing with traditional fused fiber approaches in next-generation wavelength-division multiplexing couplers. Metro network operators in Japan and South Korea are adopting these hybrid devices for 400 Gbps coherent links where thermal stability and channel count density must coexist. The structural consequence is compressing demand for pure fused couplers in access networks while expanding the addressable market for precision PLC-fiber hybrids in long-haul.
REACH chemical restrictions and the EU F-Gas Regulation are constraining solvent chemistries available for waveguide etching and fiber cleaning processes. European coupler fabricators are reformulating production lines to eliminate perfluorinated compounds, adding capital intensity to manufacturing upgrades. German and French suppliers are most affected, with several relocating final test and packaging operations to Switzerland to maintain access to legacy process chemistries under transitional permits.
Hyperscale data center operators are consolidating optical component procurement through direct supplier relationships that bypass traditional telecom equipment distributors. This channel disintermediation compresses distributor margins while rewarding coupler manufacturers with captive fiber draw capacity and in-house testing laboratories. The shift is most visible in North American markets where Amazon Web Services, Microsoft Azure, and Google Cloud dominate fiber backbone deployment decisions and specify insertion loss budgets at the purchase order level.
Fiber-Optic Couplers Market Segmentation
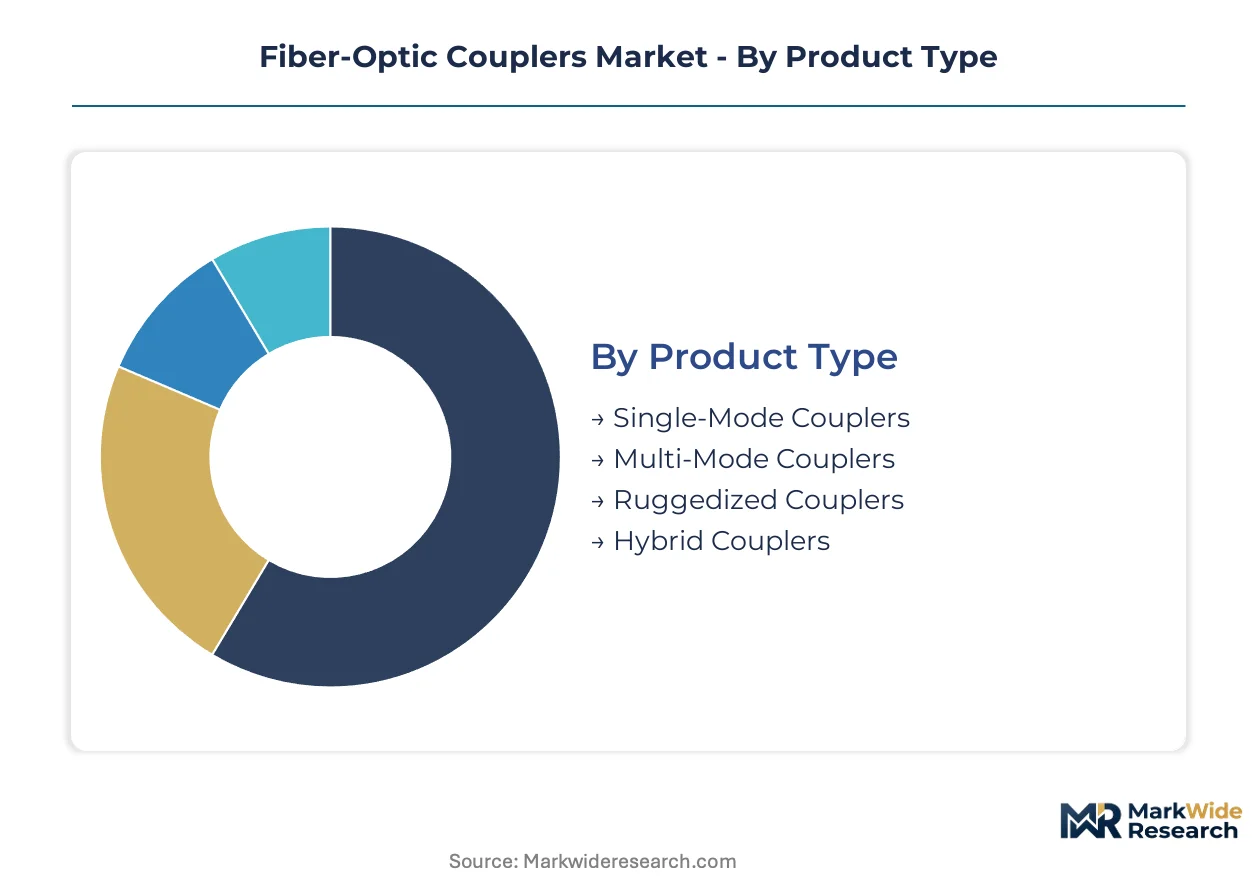
Coupler architectures fragment sharply between precision-grade coherent transmission assemblies and commodity data center interconnects. Procurement patterns diverge across these tiers, with hyperscale operators driving volume standardization while submarine cable projects sustain premium specialization.
Product Type:
Performance requirements span insertion loss budgets from below 0.3 dB in metro rings to relaxed specifications in short-reach data center fabrics.
- Single-Mode Couplers:Engineered through fused biconical tapering or planar lightwave circuit etching to achieve wavelength-division multiplexing compatibility across C-band and L-band spectra. China's MIIT 5G backhaul procurement and Germany's energy-efficiency mandates under the EU Green Deal are concentrating demand for low-loss variants that minimize electrical regeneration in provincial carrier networks and metro rings.
- Multi-Mode Couplers:Optimized for 850 nm and 1300 nm transmission over graded-index fiber with relaxed alignment tolerances suited to high-volume factory termination. Data center spine-layer deployments by North American hyperscale operators are driving procurement of LC and MTP/MPO paired assemblies where port density exceeds 400 Gbps switching thresholds.
- Ruggedized Couplers:MIL-PRF-49291 qualified assemblies withstand temperature cycling from -55°C to +85°C and mechanical shock per military avionics specifications.
- Hybrid Couplers:PLC-fiber architectures combining planar lightwave circuit thermal stability with fused fiber flexibility for 400 Gbps coherent links in Japan and South Korea.
Established volume favors multi-mode couplers; emerging adoption favors hybrid couplers.
Industry Vertical:
End-use concentration determines margin structure, with defense qualification burdens sustaining pricing premiums against commoditized data center procurement.
- Telecommunications:National carrier backbone upgrades and 5G fronthaul deployments requiring GB standards compliance for Chinese provincial tenders. France's environmental regulator and Germany's broadband agency are mandating low-loss passive components under EU Green Deal energy-efficiency frameworks.
- Data Centers:Hyperscale operators in North America are consolidating procurement around direct supplier relationships that specify insertion loss budgets at purchase order level, bypassing traditional telecom distributors.
- Military:Shipboard and avionics applications demanding temperature cycling resistance and mechanical shock immunity per defense ruggedization standards.
- Broadcasting:Signal distribution networks requiring wavelength-specific performance for uncompressed video transport.
Margin concentration sits with military; volume scaling sits with data centers.
Connection Type:
Physical interface standardization shapes inventory positioning across regional hub strategies.
- LC Connectors:Small-form-factor latching design dominating data center interconnection with push-pull mating suited to high-density patch panels. Standardized pairing with multi-mode couplers in hyperscale spine layers is compressing margin pools through volume procurement.
- MTP/MPO Connectors:Multi-fiber push-on interfaces enabling 12- and 24-fiber parallel optics for 400 Gbps and 800 Gbps switch-to-switch links. North American cloud operators are specifying these for backbone fiber deployments supporting AI-driven traffic loads.
- SC Connectors:Push-pull coupling mechanism retaining presence in carrier access networks and test equipment interfaces.
- ST Connectors:Bayonet twist-lock design persisting in industrial and legacy installations where vibration resistance matters.
LC connectors anchor current procurement; MTP/MPO connectors are climbing the fastest.
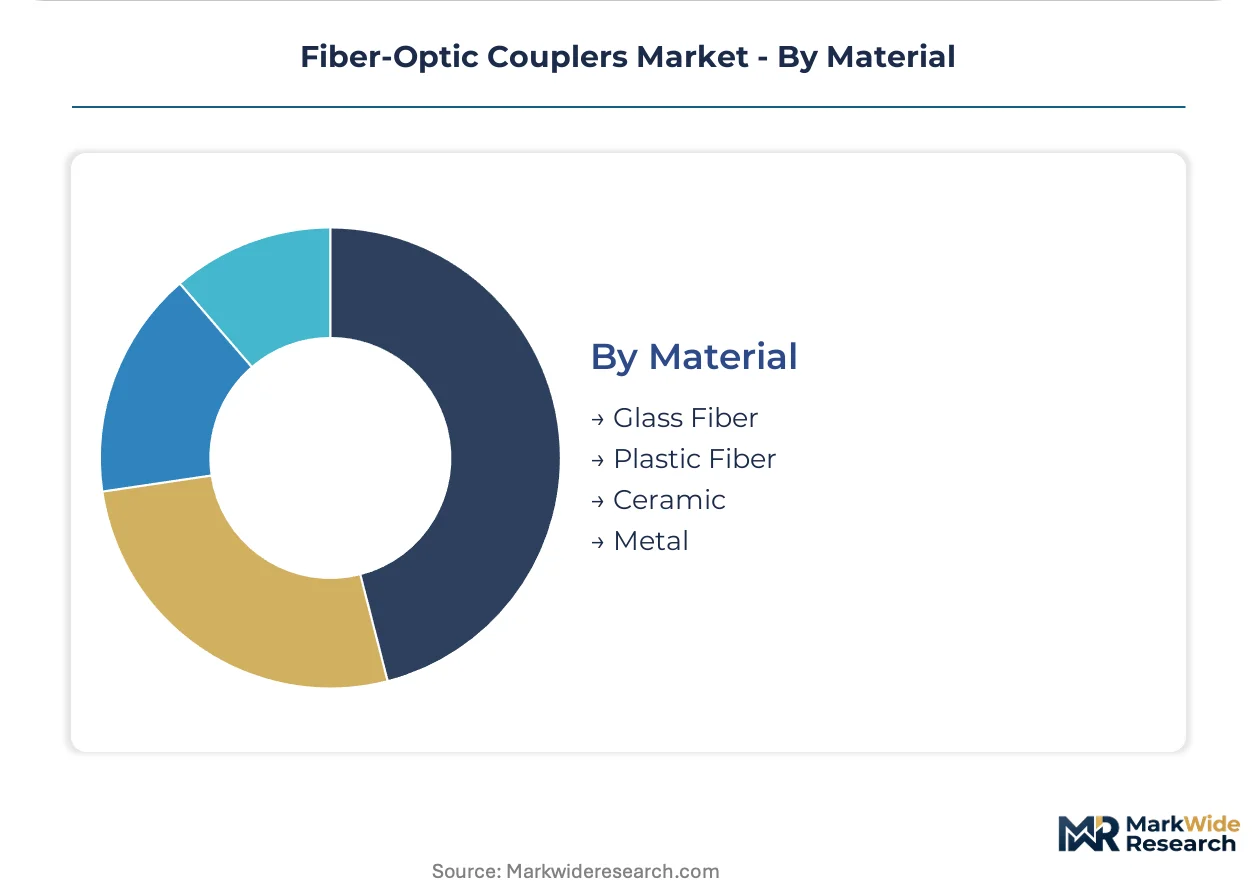
Material:
Substrate selection trades optical performance against mechanical durability and process chemistry constraints.
- Glass Fiber:Silica-based waveguides offering lowest attenuation across 1260-1625 nm transmission windows with fusion splicing compatibility for submarine and terrestrial networks. Erbium and ytterbium dopant cost volatility in fiber preform manufacturing is creating margin pressure for fabricators without long-term chemical supply agreements.
- Ceramic:Zirconia ferrule materials providing dimensional stability for connector alignment sleeves and precision split sleeves.
- Plastic Fiber:Polymer optical fiber variants for short-reach automotive and industrial sensing applications.
- Metal:Stainless steel and nickel-alloy housings for ruggedized assemblies meeting MIL-PRF-49291 mechanical shock specifications.
Glass fiber commands value capture; ceramic anchors connector precision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through state-led 5G backhaul procurement and GB standards enforcement that shapes supplier qualification timelines worldwide. National carrier tenders in provincial networks sustain heavy volume commitments for single-mode and multi-mode coupler assemblies.
United States
Hyperscale data center operators in Ashburn, Virginia and Hillsboro, Oregon are consolidating optical procurement around direct supplier relationships. The FCC enforces broadband deployment benchmarks that shape carrier procurement cycles for passive optical components. Cloud infrastructure investment in Northern Virginia's Data Center Alley is driving specification of insertion loss budgets below 0.3 dB at the purchase order level.
Germany
Deutsche Telekom and regional carriers are upgrading metro rings under the EU Green Deal energy-efficiency mandates. The national broadband agency requires low-loss passive components that reduce electrical regeneration needs. Manufacturing and testing operations concentrate in Bavaria, where suppliers are reformulating production lines to eliminate perfluorinated compounds under REACH restrictions.
Japan
NTT and KDDI are adopting hybrid PLC-fiber couplers for 400 Gbps coherent links where thermal stability and channel density must coexist. METI oversees industrial standards that influence regional procurement patterns. Fusion splicing technician certification concentrates in coastal manufacturing clusters around Nagoya and Osaka, constraining capacity expansion for Western assemblers.
South Korea
SK Telecom and KT Corporation are deploying next-generation wavelength-division multiplexing architectures in Seoul and Busan metro networks. National regulators align with METI-influenced standards for optical performance testing. The Pangyo Techno Valley cluster hosts precision coupler assembly operations serving domestic carrier and export markets.
Fiber-Optic Couplers Market Competitive Landscape
Vertically integrated fiber manufacturers and specialized coupler fabricators split the market into distinct capability tiers. Concentration favors players with captive draw tower capacity who can guarantee insertion loss specifications across wavelength-division multiplexing architectures. Three archetypes dominate: fiber-captive integrated suppliers, precision instrumentation specialists, and regional volume assemblers. Competitive moves center on direct relationship-building with hyperscale operators and qualification acceleration under divergent national testing protocols.
Within the fiber-captive tier, Corning Incorporated and Fujikura Ltd exemplify strategic positioning through upstream control over preform manufacturing. Thorlabs Inc occupies a position in the precision instrumentation tier where laboratory and defense customers prioritize wavelength-specific performance. Yangtze Optical Fibre and Cable Joint Stock Limited Company represents the regional volume archetype serving state-led procurement programs. These three anchors illustrate how geographic origin and manufacturing structure shape competitive differentiation in a market where technical specifications and regulatory compliance timelines determine supplier selection.
| Leading Market Players |
|---|
| Corning Incorporated |
| Fujikura Ltd |
| Furukawa Electric Co Ltd |
| Sumitomo Electric Industries Ltd |
| OFS Fitel LLC |
| Thorlabs Inc |
| Yangtze Optical Fibre and Cable Joint Stock Limited Company |
| LEONI AG |
| Gooch & Housego PLC |
| Others |
Value Network & Pricing Analysis
Rare-earth dopant cost volatility in erbium and ytterbium spot markets determines both the premium commanded by fused biconical taper couplers with guaranteed split-ratio consistency and the geographic clustering of fiber preform manufacturing around Japanese and Chinese coastal draw towers.
Pricing Analysis
Configured-to-order pricing for MIL-PRF-49291 qualified ruggedized couplers commands substantial premiums over standard LC-paired multi-mode assemblies. The dominant structure stratifies across premium, standard, and economy tiers, with differentiation driven by insertion loss certification grade and volume scale commitments from hyperscale operators. Cost compression in multi-mode data center interconnects is intensifying because North American cloud operators specify insertion loss budgets at purchase order level. Hyperscale data center procurement teams exhibit highest price sensitivity, while defense avionics programs show lowest sensitivity due to temperature cycling requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for fiber-optic coupler assemblers. Manufacturing concentrates in China, Japan, and Germany, with the supply chain drawing from silica preform feedstock, zirconia ferrule ceramics, and rare-earth dopant chemicals. Single-source vulnerability in fusion splicing technician certification—concentrated in coastal Japan and China—constrains Western capacity expansion. Distribution runs through direct supplier relationships with hyperscale operators and national carriers, bypassing traditional telecom equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation between precision-grade coherent transmission assemblies and commodity data center interconnects creates niche opportunities as procurement patterns diverge across performance tiers.
For Market Incumbents: Build captive fiber manufacturing moats through upstream control over preform draw towers to guarantee insertion loss specifications below 0.3 dB. Defensive moves include accelerating GB standards compliance investments for Chinese provincial carrier tenders and consolidating direct relationships with hyperscale operators to offset silicon photonics substitution threats in 400 Gbps switching layers. For New Entrants and Emerging Players: India's BharatNet rural fiber expansion represents the most penetrable geography for low-cost fused coupler assemblies in tier-3 and tier-4 network builds. White-space targets include MIL-PRF-49291 qualification for defense ruggedization premiums and hybrid PLC-fiber architectures for Japan-South Korea 400 Gbps coherent links. A technical certification-first go-to-market angle accelerates carrier qualification timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fiber-captive integrated suppliers with in-house testing laboratories. Long-term viability across the projection horizon rests on backward integration into preform manufacturing and qualification acceleration capabilities. The signal to watch is hyperscale operator procurement consolidation around single-source suppliers with guaranteed wavelength-division multiplexing performance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Manufacturing | Captive erbium-doped fiber supply secures margin control against rare-earth spot volatility. |
| GB Standards Compliance Investment | In-country laboratory validation accelerates product registration for China's MIIT provincial tenders. |
| MIL-PRF-49291 Qualification Program | Defense ruggedization certification unlocks 3-4x pricing premiums in avionics applications. |
| Direct Hyperscale Relationship Building | Bypassing telecom distributors captures insertion loss specification influence at purchase order level. |
| Hybrid PLC-Fiber R&D Partnership | Metro network adoption in Japan and South Korea expands addressable market for coherent links. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this study. The research team conducted structured discussions with fiber coupler design engineers, hyperscale data center procurement officers, submarine cable factory fusion splicing technicians, defense ruggedization qualification specialists, and national carrier network planning directors. Secondary validation drew from FCC broadband deployment benchmarks, MIIT GB standards documentation, EU F-Gas Regulation compliance notices, and SEC filings of vertically integrated fiber manufacturers. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to constrain forecast variance.
Calibration against historical procurement volumes and announced capacity expansions shaped the analytical framework across the modeling period. Segmentation dimensions include coupler architecture type, industry vertical, connection interface standard, and regional regulatory cluster. CAGRs were derived from fitted growth curves adjusted for technology substitution effects. Industry-specific forecast inputs incorporated hyperscale data center capex disclosures and state-led 5G backhaul procurement schedules.
Practitioners should monitor silicon photonics integration timelines and rare-earth dopant spot price movements for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Picosecond Lasers Market
Optics
Optical Sensing Market
Optics
Optical Microscope Market
Optics
Quartz Glass Market
Optics
Anomaloscope Market
Optics
Lasers Market
Optics
Optical Lens for Mobile Phone Market
Optics
Sports Optics Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Optical Telescope Market
Optics
Optical Fiber Raw Material Market
Optics
Fiber Optical Receivers Market
Optics
Optical Telephoto Lens Market
Optics
India Laser Market
Optics
Middle East and Africa Optical Imaging Market
Optics
AR and VR Lens Market