
 Fiber Optic Development Tools Market | 2026-2036
Fiber Optic Development Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optic Development Tools Market Foresight
ISO/IEC 17025 laboratory accreditation is collapsing the supplier base for calibration-grade fiber optic test equipment. Keysight Technologies leverages its metrology heritage to dominate high-end optical spectrum analyzer segments. EXFO Inc. anchors its position through captive repair and certification services that lock in enterprise network customers. Anritsu competes aggressively on port density in multi-channel test systems for submarine cable verification.
Fiber optic development tools comprise precision instruments for cleaving, splicing, inspecting, and characterizing optical fiber with sub-micron tolerances, typically operating at wavelengths of 1310 nm and 1550 nm for single-mode validation. These tools enable reliable signal transmission across telecommunications, data center, and industrial networks by ensuring splice losses below 0.05 dB and connector end-face geometry within tight specifications. Testing Equipment commands the largest revenue share due to mandatory certification cycles in carrier networks, while Optical Amplifiers represent the fastest-expanding technology segment driven by coherent transmission upgrades. Single-Mode technology leads volume given its dominance in long-haul and metro builds, though Multi-Mode fiber tools retain stronger margins in hyperscale data center applications where link distances remain short.
The U.S. FCC's broadband infrastructure programs and the EU's CE marking requirements under the Radio Equipment Directive shape procurement standards for field-deployable fiber tools across their respective markets. Japan's METI promotes domestic optical component leadership through JIS standards that influence regional test equipment specifications. Stakeholders must monitor how evolving energy efficiency regulations in data center construction redirect tool development priorities toward low-power portable instruments.
Market Dynamics
Precision splicing equipment procurement is accelerating as data center operators densify fiber deployments, while the EU F-Gas Regulation forces manufacturers to eliminate greenhouse gas-intensive production processes from fusion splicing workflows.
Growth Catalysts
- Industrial automation networks:Smart factory rollouts across Germany require specialized fiber characterization tools for real-time quality verification in robotic control systems.
- CE marking under the Radio Equipment Directive:Mandatory conformity assessment for field-deployable fiber tools expands addressable demand across European carrier procurement programs.
- Coherent transmission upgrades:Optical amplifier testing demand is concentrating in submarine cable landing stations requiring multi-channel verification systems.
Market Restraints
- ISO/IEC 17025 accreditation concentration:Collapsing supplier base for calibration-grade equipment locks procurement to limited accredited laboratories in Germany and Japan.
- Helium supply volatility:Fusion splicing process gas costs fluctuate with semiconductor industry demand cycles, compressing margin structures for portable splicer manufacturers.
- Single-mode fiber technical limitation:Sub-micron alignment tolerances below 0.05 dB splice loss require expensive active cladding alignment mechanisms that price out developing-market field technicians.
Strategic Opportunities
- Hyperscale data center multi-mode applications:Short-reach link architectures in US and Chinese cloud campuses retain stronger tool margins than long-haul single-mode deployments.
- JIS standards convergence:Japan's METI-promoted optical component specifications create certification pathways for test equipment vendors targeting Asian industrial automation markets.
- Low-power portable instrument development:Energy efficiency regulations in data center construction redirect R&D priorities toward battery-operated inspection microscopes and OTDR units.
Industry Challenges
- Metrology technician scarcity:ISO/IEC 17025 calibration procedures require specialized optical physics training that outpaces vocational program output in key manufacturing regions.
- Legacy connector interoperability:Mixed deployments of APC, UPC, and MPO interfaces force field technicians to carry redundant cleaning and inspection kits, increasing truck-roll complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Development Tools Market |
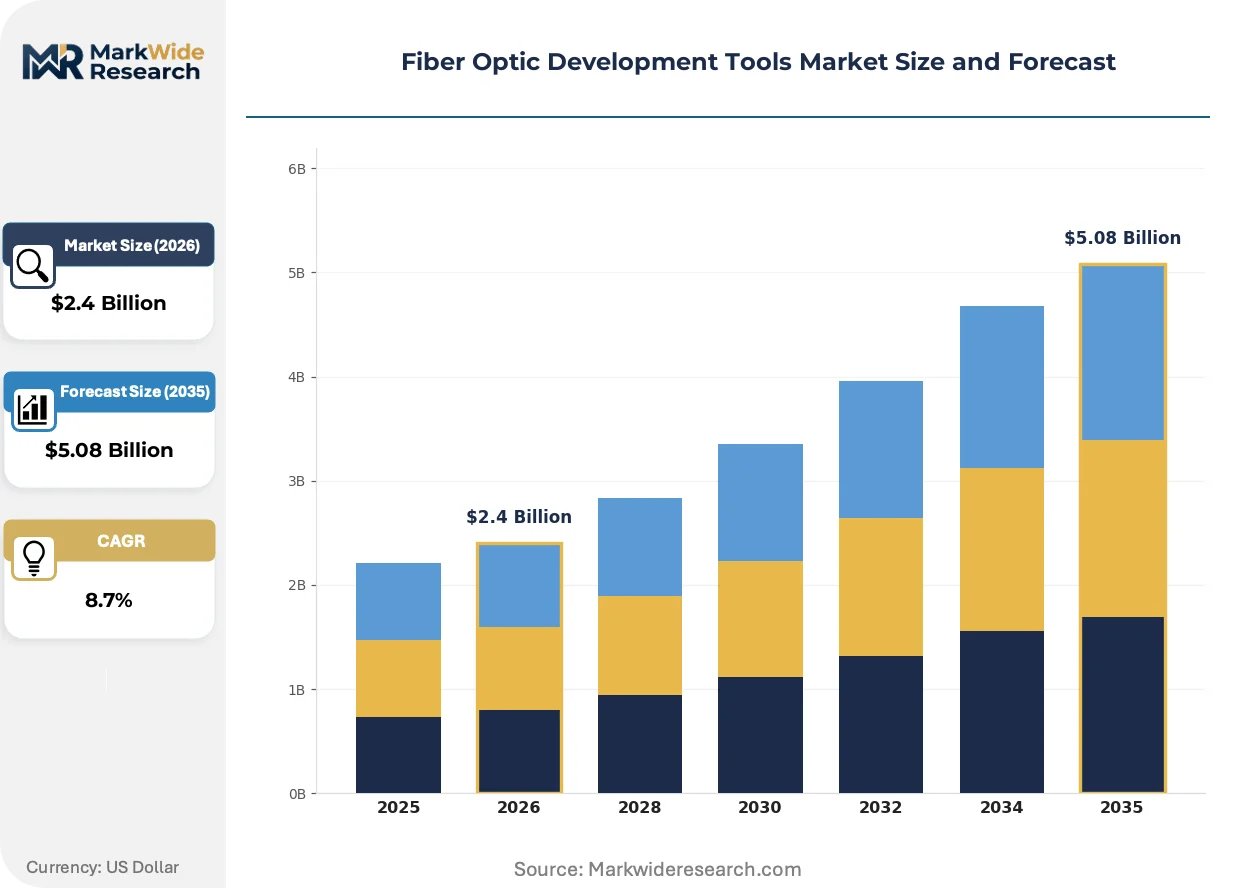
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Splicing Kits, Testing Equipment, Tools, Accessories Technology: Single-Mode, Multi-Mode, Optical Amplifiers, Fiber Bragg Gratings End User: Telecommunications, Data Centers, Enterprise Networks, Manufacturing Application: Networking, Industrial Automation, Cable Management, Research |
| Companies Covered | Radiall, Qorvo Inc., MikroElektronika, Finisar Corporation, Broadcom Inc., Keysight Technologies, EXFO Inc., Anritsu, Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Development Tools Market Shifts & Advancements
Active cladding alignment mechanisms are fragmenting traditional mechanical splicing economics, while regulatory pressure on process emissions and buyer consolidation around captive service models are compressing vendor differentiation strategies.
AI-assisted splice loss prediction is fragmenting the technician skill gradient across carrier and enterprise deployment teams. Machine vision algorithms embedded in fusion splicer firmware now auto-optimize arc power and fiber positioning parameters that previously required years of field experience. Japanese and Korean carriers are deploying these systems fastest, compressing training timelines for subcontractor workforces while reducing rework rates on critical backbone routes.
The EU F-Gas Regulation is banning sulfur hexafluoride and fluorinated greenhouse gases from fusion splicing electrode cleaning and arc stabilization processes. German and French equipment manufacturers are reformulating plasma gas mixtures and redesigning electrode geometries to maintain arc consistency without regulated compounds. This regulatory compression is accelerating clean-technology R&D budgets while disadvantaging legacy equipment refresh cycles in European markets.
Enterprise network operators are consolidating vendor relationships around bundled certification and repair service contracts. EXFO and Keysight captive service programs now lock multi-year calibration and firmware update commitments into initial equipment procurement, displacing independent third-party metrology houses. This service-bundling concentration is most visible in US and German financial services and healthcare verticals where audit documentation requirements favor single-source accountability.
Fiber Optic Development Tools Market Segmentation
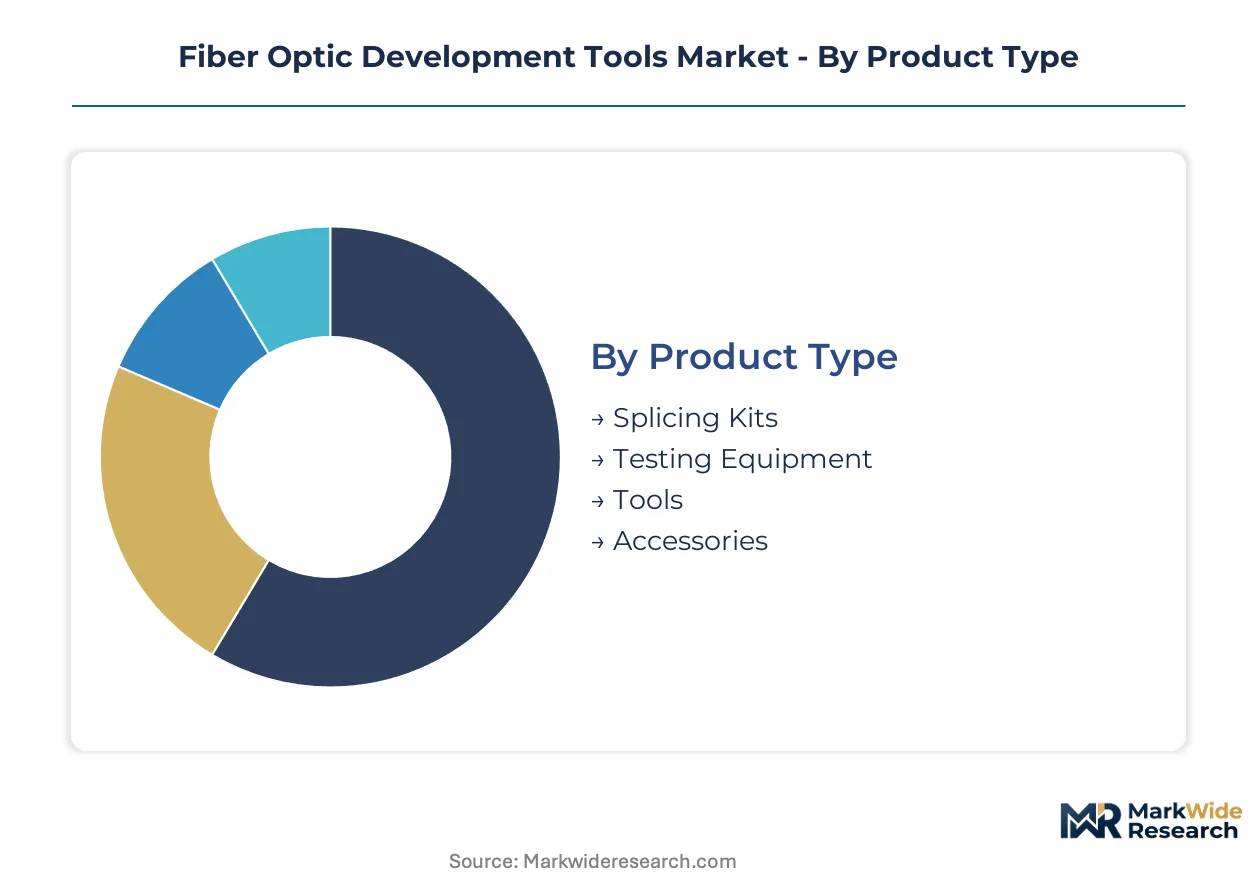
Channel dynamics for fiber optic development tools diverge sharply by product complexity. Authorized distributors dominate high-value testing equipment with calibration service bundling, while direct OEM sales capture volume splicing kit procurement in carrier and hyperscale data center verticals.
Product Type:
Channel mix varies by calibration dependency and replacement frequency. Testing equipment flows through metrology-certified distributors with service contracts, while consumable accessories move through volume electronics distributors.
- Testing Equipment:Optical spectrum analyzers, OTDRs, and power meters require ISO/IEC 17025 traceable calibration that locks procurement to accredited distributor channels. Carrier network certification cycles in Germany and Japan sustain recurring revenue streams through mandatory recalibration protocols.
- Splicing Kits:Fusion splicers and precision cleavers concentrate demand in data center fiber densification projects. Procurement is shifting toward bundled electrode and splice protection sleeve contracts that reduce total cost of ownership for field deployment teams.
- Tools:Fiber strippers, cleavers, and visual fault locators serve technician truck-roll requirements with lower service attachment rates.
- Accessories:Connector cleaning kits, splice protectors, and carrying cases generate recurring revenue through consumable replenishment cycles.
Testing Equipment dominates installed base. Splicing Kits is where expansion concentrates.
Technology:
Cost tier stratification separates premium coherent-test systems from portable field instruments. Single-mode and multi-mode tools occupy distinct price-performance bands with minimal customer overlap.
- Single-Mode:Sub-micron alignment tolerances for 1310 nm and 1550 nm validation require active cladding alignment mechanisms priced at premium tiers. Long-haul submarine cable landing stations in Japan and carrier backbone routes in Germany sustain demand for sub-0.05 dB splice loss specifications.
- Optical Amplifiers:EDFA and Raman amplifier test systems address coherent transmission upgrades with multi-channel verification requirements. Submarine cable operators are concentrating procurement in landing station facilities requiring high port-density configurations.
- Multi-Mode:Short-reach 850 nm and 1300 nm tools serve hyperscale data center applications with relaxed alignment tolerances and stronger margin structures than single-mode equivalents.
- Fiber Bragg Gratings:Specialized interrogation systems address sensing and filtering applications in industrial monitoring networks.
Single-Mode commands the largest installed base. Optical Amplifiers is gaining share fastest.
End User:
Customer type determines procurement authority structure and service bundling acceptance. Enterprise networks favor single-source accountability, while telecommunications carriers segment procurement across specialized vendor relationships.
- Telecommunications:Tier-1 carriers mandate vendor-agnostic test equipment with interchangeable modules to avoid single-source lock-in. Field technician fleets in Japan and Germany require ruggedized portable instruments with standardized training curricula.
- Data Centers:Hyperscale operators in the US and China consolidate procurement around captive repair and firmware update programs. Multi-mode fiber tool margins exceed single-mode equivalents due to shorter link distances and reduced performance requirements.
- Enterprise Networks:Financial services and healthcare verticals in the US and Germany favor bundled certification contracts with audit documentation trails.
- Manufacturing:Smart factory rollouts in Germany require real-time fiber characterization for robotic control system integration.
Telecommunications dominates installed base. Data Centers is where expansion concentrates.
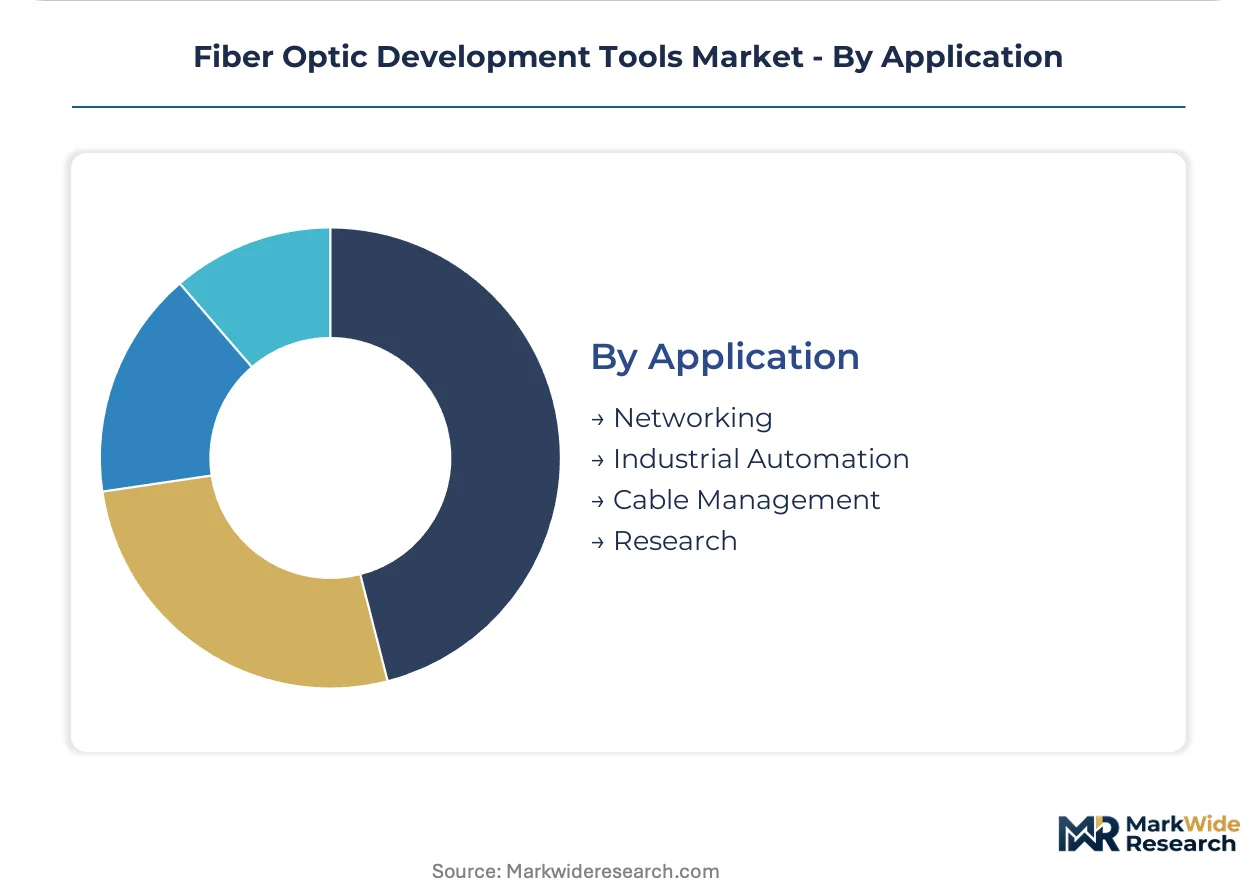
Application:
Volume distribution skews toward field deployment versus laboratory environments. Networking applications drive unit shipments, while research applications sustain premium pricing for specialized configurations.
- Networking:Carrier backbone, metro, and access network builds require standardized test protocols with mandatory certification documentation. Procurement concentrates in Germany and Japan where regulatory compliance frameworks enforce traceable measurement records.
- Industrial Automation:Smart factory fiber deployments in Germany demand specialized characterization tools for real-time quality verification in robotic control loops. METI-promoted JIS standards influence specifications for Asian industrial automation markets.
- Cable Management:Structured cabling installations require inspection microscopes and cleaning kits with lower capital intensity than splicing or test equipment.
- Research:Academic and government laboratory procurement sustains demand for specialized configurations with extended wavelength ranges and custom software interfaces.
Networking dominates installed base. Industrial Automation is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier procurement authorities and hyperscale data center operators concentrate demand for fiber optic development tools across four national markets. Each geography presents distinct regulatory compliance frameworks and industrial deployment patterns.
Germany
Industrial automation networks and smart factory rollouts drive procurement of specialized fiber characterization tools. The EU F-Gas Regulation mandates cleaner fusion splicing technologies without greenhouse gas-intensive processes. Manufacturing clusters in Bavaria and Baden-Württemberg require real-time quality verification for robotic control system integration.
United States
FCC broadband infrastructure programs accelerate field-deployable tool procurement for carrier backbone expansion. CE marking requirements under the Radio Equipment Directive shape export-oriented manufacturer compliance strategies. Hyperscale data center campuses in Northern Virginia and Dallas-Fort Worth consolidate multi-mode fiber tool procurement around captive service contracts.
Japan
Submarine cable landing stations concentrate demand for multi-channel verification systems with high port-density configurations. METI promotes domestic optical component leadership through JIS standards that influence regional test equipment specifications. The Kanto region around Tokyo anchors coherent transmission upgrade programs requiring optical amplifier testing infrastructure.
China
Hyperscale cloud campus construction in the Yangtze River Delta and Pearl River Delta sustains multi-mode fiber tool margins. GB standards and MIIT regulations govern field equipment certification for domestic telecommunications deployment. Shenzhen and Hangzhou manufacturing clusters supply precision cleavers and inspection microscopes for regional consumption.
Fiber Optic Development Tools Market Competitive Landscape
Player mix skews toward diversified test equipment conglomerates with metrology heritage and specialized fiber optic instrument manufacturers. The supplier base concentrates around ISO/IEC 17025 accredited calibration laboratories, collapsing procurement options for certification-grade equipment. Two strategic archetypes dominate: precision measurement specialists leveraging metrology credibility and integrated service providers bundling repair contracts with hardware sales. Competitive moves center on captive service program expansion and clean-technology R&D acceleration to satisfy EU emissions regulations.
Among diversified measurement conglomerates, Keysight Technologies and Anritsu occupy positions anchored by metrology heritage and multi-channel system expertise respectively. EXFO Inc. exemplifies the integrated service archetype through bundled calibration and certification programs. These three companies represent the dominant competitive positioning vectors across carrier, enterprise, and data center verticals.
| Leading Market Players |
|---|
| Radiall |
| Qorvo Inc. |
| MikroElektronika |
| Finisar Corporation |
| Broadcom Inc. |
| Keysight Technologies |
| EXFO Inc. |
| Anritsu |
| Fluke Corporation |
| Others |
Supply & Pricing Matrix
Long-term calibration service contracts lock in multi-year equipment procurement for carrier networks and data center operators, anchoring price visibility to ISO/IEC 17025 accreditation availability in Germany and Japan. This contract structure ties hardware margins to captive service bundling while concentrating buyer leverage among hyperscale operators consolidating vendor relationships.
Pricing Analysis
Cost-plus contracts with helium price indexation dominate fusion splicer manufacturing, passing volatile process gas costs through to data center deployment teams. Three-tier pricing structure across premium, standard, and economy levels separates active cladding alignment systems from mechanical splicers and consumable accessories. Pricing pressure stems from helium supply volatility intersecting with semiconductor industry demand cycles, compressing portable splicer margins. Tier-1 carriers exhibit lowest price sensitivity due to mandatory certification requirements, while developing-market field technicians face exclusion from sub-0.05 dB splice loss specifications.
Supply Chain Analysis
Germany and Japan anchor precision metrology component fabrication for optical spectrum analyzers and OTDR units, while China supplies volume production of cleavers and inspection microscopes from Shenzhen and Hangzhou clusters. Critical inputs draw from specialized optical glass suppliers, high-precision motion control systems, and rare earth-doped fiber for amplifier testing modules. Single-source vulnerability concentrates in ISO/IEC 17025 accredited calibration laboratories, where metrology technician scarcity limits service capacity expansion. Distribution runs through metrology-certified distributors for testing equipment and direct OEM sales for splicing kit procurement in carrier verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hyperscale data center operators consolidating procurement around captive repair and firmware update programs, fragmenting vendor pricing leverage across the supplier base.
For Market Incumbents: Consolidate service bundling programs around multi-year calibration commitments to lock in enterprise network customers facing audit documentation requirements. Deepen backward integration into precision optical component supply to mitigate helium price volatility exposure in fusion splicer manufacturing. Prioritize clean-technology R&D acceleration to satisfy EU F-Gas Regulation compliance deadlines and displace legacy equipment refresh cycles. For New Entrants and Emerging Players: ISO/IEC 17025 fast-track accreditation partnerships with German and Japanese metrology laboratories create entry pathways into certification-grade equipment segments. Target industrial automation networks in German smart factory rollouts where real-time fiber characterization tools face less incumbent saturation than carrier backbone markets. Pursue white-label splicing kit procurement for Chinese hyperscale cloud campuses where multi-mode fiber tool margins exceed single-mode equivalents. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors clean-technology specialists with EU F-Gas Regulation-ready product portfolios. Long-term viability centers on service-revenue attachment rates rather than hardware shipment volumes, favoring targets with captive calibration infrastructure. Watch helium supply contract renegotiation cycles as inflection indicators for portable splicer manufacturer margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Technology R&D Acceleration | EU F-Gas Regulation compliance positions vendors for European carrier procurement cycles. |
| Captive Service Program Expansion | Bundled calibration contracts lock in US and German financial services verticals with audit requirements. |
| Backward Integration into Optical Components | In-house precision motion control production mitigates supply chain volatility for active alignment systems. |
| ISO/IEC 17025 Accreditation Investment | Metrology laboratory certification collapses procurement options to accredited suppliers in Germany and Japan. |
| Multi-Mode Fiber Tool Portfolio Expansion | Hyperscale data center procurement in Northern Virginia and Dallas-Fort Worth sustains stronger margins than long-haul deployments. |
Research Methodology
Cross-validation between regulatory filing analysis and equipment procurement database triangulation anchors the qualitative findings across carrier, data center, and industrial automation verticals. Primary interviews with fiber deployment engineers, metrology laboratory directors, hyperscale facility procurement managers, and fusion splicer field technicians combined with secondary validation from FCC broadband program disclosures, EU F-Gas Regulation implementation reports, METI JIS standards documentation, and SEC equipment manufacturer filings. Bottom-up shipment analysis and top-down infrastructure spend estimates converge on segment-level demand quantification.
Sensitivity analysis around helium price volatility and accreditation laboratory capacity constraints shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type complexity tier, single-mode versus multi-mode technology architecture, end-user procurement authority structure, and application environment from field deployment to laboratory research. CAGRs derive from equipment replacement cycle analysis and infrastructure buildout pipeline assessment, with coherent transmission upgrade intensity and data center fiber densification rates as fiber optic-specific forecast inputs.
Underlying assumptions cover stable EU F-Gas Regulation enforcement timelines and continued hyperscale data center construction momentum in US and Chinese markets, with deviation risk concentrated in helium supply disruption scenarios and metrology technician training pipeline bottlenecks. Recalibration cycles align with material shifts in broadband infrastructure program funding authorizations and clean-technology regulatory compliance deadline accelerations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
MEMS Mirrors Market
Optics
Fiber Optic Amplifier Market
Optics
Global Semiconductor Lasers Market
Optics
Global Fiber Optic Sensors Market
Optics
Fiber Optic Preform Market
Optics
Collimating Lens Market
Optics
Fiber-Optic Couplers Market
Optics
Stroboscope Market
Optics
Optical Fiber Raw Material Market
Optics
Single-Mode Optical Fiber Market
Optics
Fiber-Optic Filters Market
Optics
North America Optical Imaging Market
Optics
Global Optical Lens Market
Optics
3D Optical Microscope Market
Optics
Glass Scintillator Market
Optics
Anti Glare Film Market