
 Optical Imaging Market | 2026-2036
Optical Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Imaging Market Intelligence
Ophthalmology is repositioning as the dominant revenue vertical within optical imaging, displacing slower-growing materials science applications. Carl Zeiss Meditec AG leverages its century-old optics heritage to dominate surgical microscopy segments. Koninklijke Philips N.V. anchors its position through integrated hospital informatics that bundle imaging hardware with workflow software. Topcon Corporation competes aggressively on price in the fundus camera category across Asian diagnostic laboratories.
Optical imaging captures, processes, and analyzes electromagnetic radiation in the visible through near-infrared spectrum, typically spanning 400–1700 nanometers, to generate two- or three-dimensional representations of biological tissues, material surfaces, or chemical compositions. The technology relies on lenses, detectors, and computational algorithms to resolve structures below the diffraction limit for applications ranging from retinal pathology to semiconductor wafer inspection. Optical coherence tomography systems command the largest installed base among product types, though photoacoustic imaging represents the fastest-expanding technology segment as clinicians seek deeper tissue penetration without ionizing radiation. Research institutes constitute the most price-insensitive end-user category, while diagnostic laboratories drive volume procurement through multi-year equipment leasing structures.
The FDA's 21 CFR Part 820 quality system regulation and the EU Medical Device Regulation (MDR) impose divergent clinical evidence requirements that fragment product development roadmaps for multinational vendors. ISO 10993 biocompatibility testing and IEC 60601 electrical safety standards add certification layers that extend time-to-market for novel modalities. Stakeholders must monitor reimbursement coding decisions by Medicare and national health technology assessment bodies, as these determine whether clinicians can recover costs for advanced optical procedures.
Market Dynamics
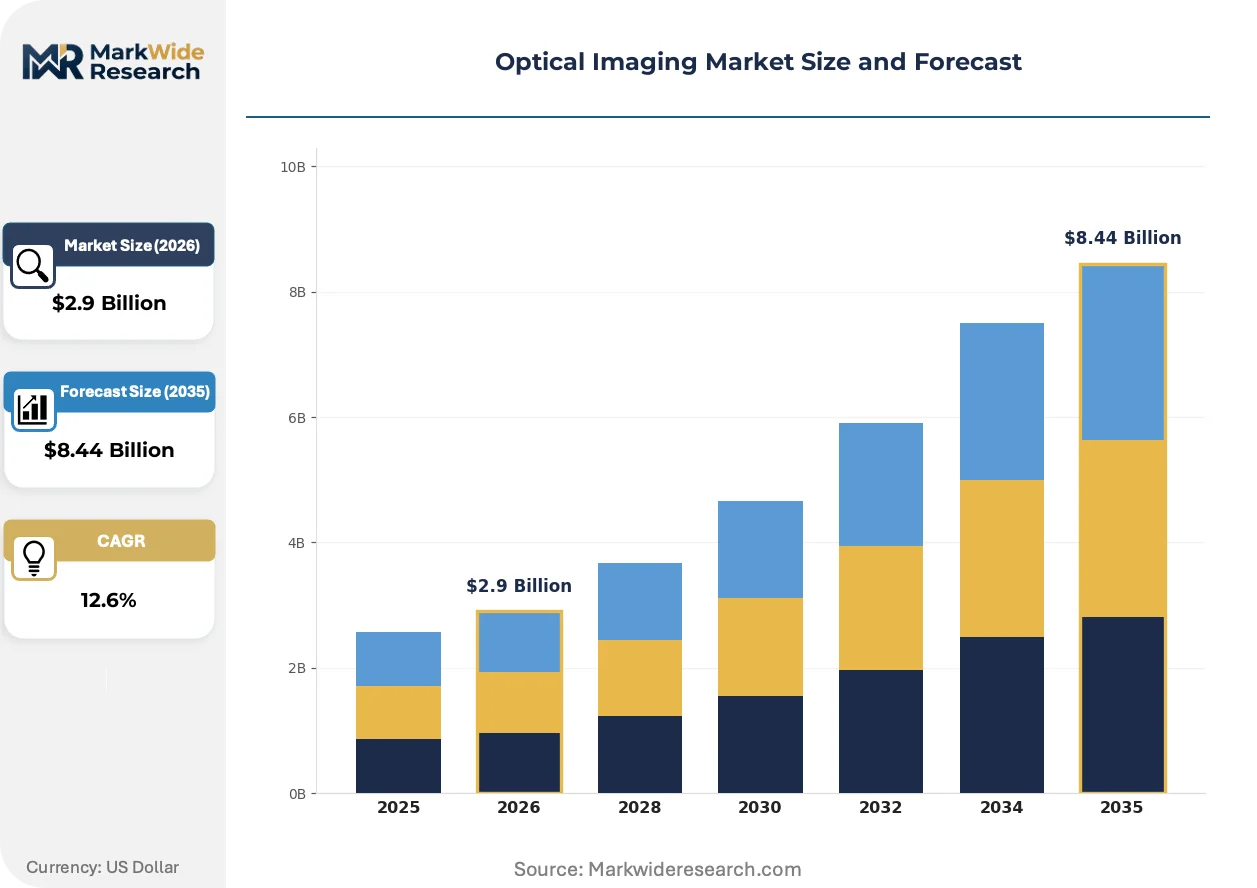
The convergence of pharmaceutical preclinical screening demands with FDA-mandated validation benchmarks is compressing product development cycles while elevating performance thresholds for new optical imaging entrants.
Growth Catalysts
- Preclinical Drug Screening Acceleration:Pharmaceutical laboratories are expanding optical coherence tomography deployments to replace invasive tissue sampling in toxicity studies. This shift reduces animal model costs while accelerating candidate molecule evaluation timelines.
- EU Medical Device Regulation Harmonization:The MDR's consolidated conformity assessment pathways are streamlining multi-country market access for vendors with established ISO 13485 quality systems. Manufacturers are consolidating notified body relationships to exploit this regulatory efficiency.
- German Precision Optics Cluster Density:Heidelberg and Oberkochen host concentrated supplier networks for specialized lenses, detectors, and illumination modules. Proximity to Carl Zeiss and Leica Microsystems enables rapid prototype iteration for OEM partners.
Market Restraints
- Indium Gallium Arsenide Detector Supply Concentration:Near-infrared sensor production concentrates among three Japanese and American foundries. Detector lead times now extend 26-32 weeks, constraining OCT system output expansion.
- FDA 21 CFR Part 820 Validation Burden:The quality system regulation demands exhaustive design history files and process validation documentation. Early-stage ventures exhaust capital on compliance before achieving commercial traction.
- Photoacoustic Imaging Technical Ceiling:Current laser pulse energies and acoustic detection limits restrict tissue penetration to 5-7 centimeters. Deep organ imaging applications remain inaccessible without ionizing radiation alternatives.
Strategic Opportunities
- India Diagnostic Laboratory Expansion:The country's PLI scheme for medical electronics manufacturing is attracting component assembly investments. Domestic production cost advantages could support aggressive pricing in Southeast Asian export markets.
- Intraoperative Fluorescence-Guided Surgery:Near-infrared dye conjugates combined with real-time imaging systems are displacing frozen section pathology in tumor margin assessment. Surgical microscope OEMs are integrating modular fluorescence channels.
- AI-Enabled Image Analysis Convergence:Machine learning algorithms trained on spectral signatures are automating pathology detection in retinal scans. Cloud-based diagnostic support services are creating recurring revenue attachments to hardware sales.
Industry Challenges
- Computational Optics Talent Scarcity:Inverse problem solving for image reconstruction requires rare combinations of physics, mathematics, and software engineering expertise. Academic pipeline output lags commercial demand by approximately four years.
- Multi-Modal System Integration Complexity:Combining OCT with photoacoustic or fluorescence capabilities demands synchronization of disparate data acquisition rates and spatial resolutions. Engineering teams struggle to achieve real-time co-registration without proprietary middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Imaging Market |
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $8.44 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Coherence Tomography, Fluorescence Imaging, Spectral Imaging, Confocal Microscopy, Hyperspectral Imaging Technology: Near-Infrared Imaging, Multispectral Imaging, Raman Spectroscopy, Terahertz Imaging, Photoacoustic Imaging Application: Ophthalmology, Neuroscience, Dermatology, Materials Science, Food Quality Inspection End User: Research Institutes, Diagnostic Laboratories, Pharmaceutical Companies, Academic Centers, Biotech Firms |
| Companies Covered | Carl Zeiss Meditec AG, Topcon Corporation, Canon Inc., PerkinElmer Inc., Leica Microsystems, Heidelberg Engineering GmbH, Koninklijke Philips N.V., Thorlabs Inc., Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Imaging Market Strategic Shifts & Innovations
Computational image reconstruction algorithms and miniaturized light sources are collapsing the performance gap between benchtop research systems and portable clinical devices.
Swept-source optical coherence tomography is electrifying ophthalmology workflows by enabling volumetric retinal imaging at 100,000+ A-scans per second. Academic medical centers in Germany and Japan are replacing spectral-domain systems ahead of typical depreciation cycles. The technology is compressing examination duration per patient while expanding reimbursable screening throughput.
The FDA's updated guidance on optical diagnostic device validation has tightened clinical evidence requirements for novel modalities. Predicate device pathways now demand larger patient cohorts and longer follow-up periods than pre-2023 submissions. Startups developing photoacoustic platforms are responding by prioritizing European CE marking sequences to generate regulatory precedent.
Diagnostic laboratories are unbundling equipment procurement from service contracts that previously bundled maintenance, software updates, and consumables. Third-party service providers in South Korea and Taiwan are capturing aftermarket revenue previously retained by original manufacturers. This disintermediation is most pronounced in fundus camera installations where hardware commoditization has compressed margins.
Optical Imaging Market Segmentation
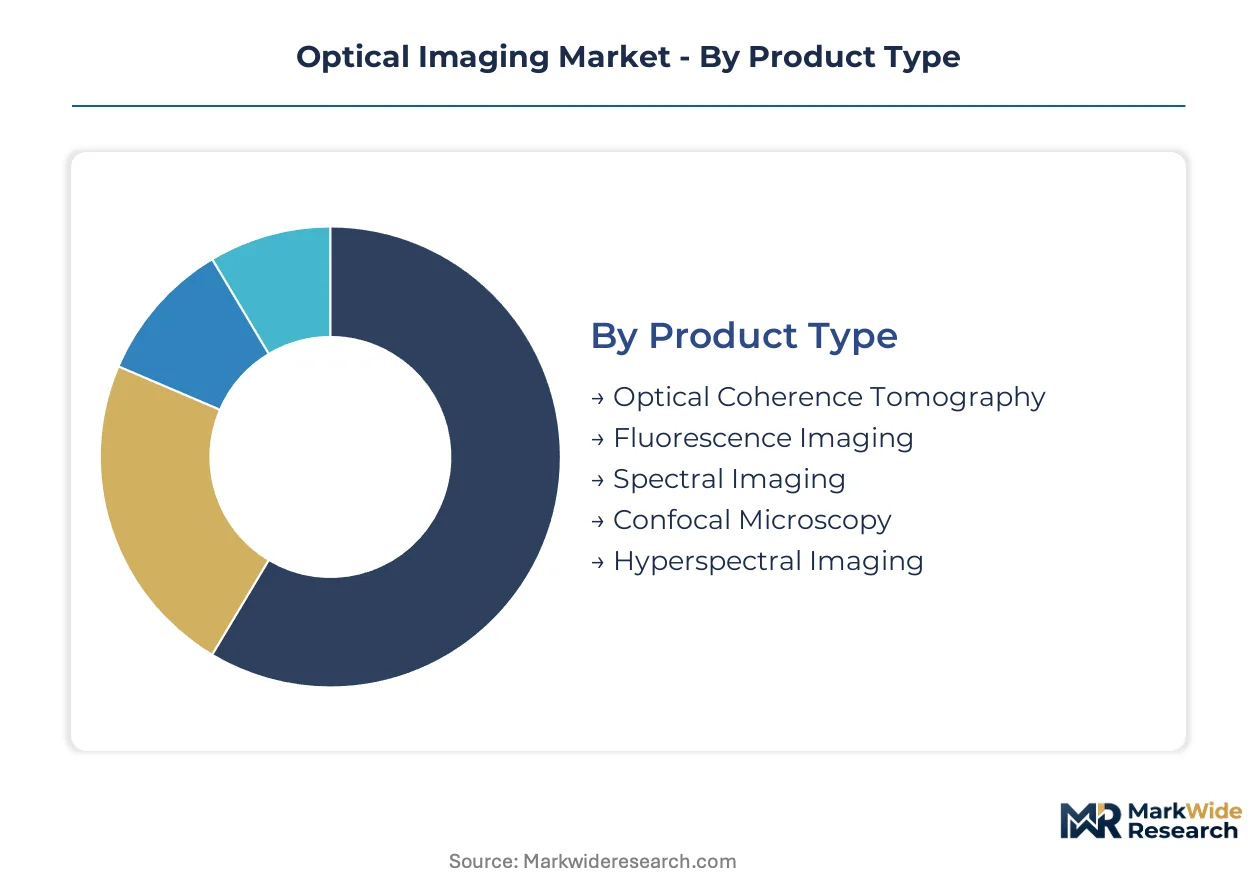
Optical imaging vendors configure product portfolios around distinct technical specifications, clinical workflows, and procurement budgets. Segmentation reveals where premium pricing commands sustainable margins versus where volume commoditization erodes profitability.
Product Type:
Volume installations concentrate in established modalities with reimbursable clinical codes, while premium pricing attaches to emerging platforms with unmet diagnostic capabilities.
- Optical Coherence Tomography:Interferometric imaging systems resolve tissue microstructure at 1-15 micrometer resolution using low-coherence light sources. German and Japanese ophthalmology clinics are replacing spectral-domain systems with swept-source variants to accelerate patient throughput. The installed base exceeds all other product types combined, though average selling prices are compressing amid hardware commoditization.
- Photoacoustic Imaging:Hybrid platforms combine pulsed laser excitation with ultrasonic detection to achieve deeper tissue penetration than pure optical methods. Academic medical centers in Heidelberg and Tokyo are deploying preclinical systems for oncology and neurology research. This modality captures the steepest expansion trajectory as clinicians seek alternatives to ionizing radiation for deep organ visualization.
- Fluorescence Imaging:Molecular contrast systems detect exogenous dyes or autofluorescence signatures for surgical guidance and pathology screening.
- Spectral Imaging:Wavelength-resolved platforms separate tissue or material composition through narrow-band illumination and computational unmixing.
- Confocal Microscopy:Pinhole-based optical sectioning systems dominate ex vivo histopathology and materials surface characterization.
- Hyperspectral Imaging:Continuous-spectrum acquisition platforms serve precision agriculture and pharmaceutical quality control with chemical-specific contrast.
Today's leader: Optical Coherence Tomography. Tomorrow's challenger: Photoacoustic Imaging.
Technology:
Application requirements for penetration depth, contrast mechanism, and acquisition speed determine technology selection across clinical and industrial settings.
- Near-Infrared Imaging:700-1700 nanometer wavelength systems exploit reduced tissue scattering for deep vascular and lymphatic visualization. Intraoperative fluorescence-guided surgery adoption in German university hospitals is driving demand for integrated microscope attachments. Indium gallium arsenide detector supply constraints are limiting OEM output expansion.
- Photoacoustic Imaging:Laser-induced ultrasonic wave detection enables functional and molecular imaging without ionizing radiation. Research institutes in Japan and the United States are prioritizing platform development for breast cancer screening and brain oxygenation monitoring. Technical limitations restrict tissue penetration to 5-7 centimeters, constraining deep organ applications.
- Multispectral Imaging:Discrete wavelength band systems balance cost and diagnostic specificity for dermatology and wound assessment.
- Raman Spectroscopy:Molecular fingerprint detection platforms identify chemical composition through inelastic light scattering for pharmaceutical quality assurance.
- Terahertz Imaging:Sub-millimeter wave systems penetrate non-conducting materials for security screening and non-destructive testing.
Near-Infrared Imaging commands current procurement volumes. Photoacoustic Imaging is gaining share fastest in preclinical research budgets.
Application:
Reimbursement coding decisions and clinical evidence requirements fragment addressable market size across medical specialties.
- Ophthalmology:Retinal pathology screening generates the largest installed base through diabetic retinopathy and age-related macular degeneration monitoring programs. Heidelberg and Carl Zeiss anchor concentrated manufacturing clusters supplying German, Japanese, and United States markets. Medicare and national health technology assessment bodies determine procedure reimbursement rates that directly influence equipment procurement cycles.
- Neuroscience:Functional brain imaging and vascular mapping applications demand high-speed acquisition and specialized animal models. Academic centers in Germany and Japan are deploying combined OCT-photoacoustic systems for stroke and dementia research. Capital intensity restricts adoption to well-funded institutional laboratories.
- Dermatology:Non-invasive lesion assessment and treatment monitoring applications leverage confocal and multispectral modalities.
- Materials Science:Semiconductor wafer inspection and surface metrology applications compete with alternative probe microscopy methods.
- Food Quality Inspection:Hyperspectral systems detect contaminants and ripeness indicators in automated sorting lines.
Ophthalmology generates dominant revenue. Neuroscience shows the steepest budget expansion trajectory.
End User:
Procurement authority and budget elasticity diverge sharply across institutional categories with distinct evaluation criteria.
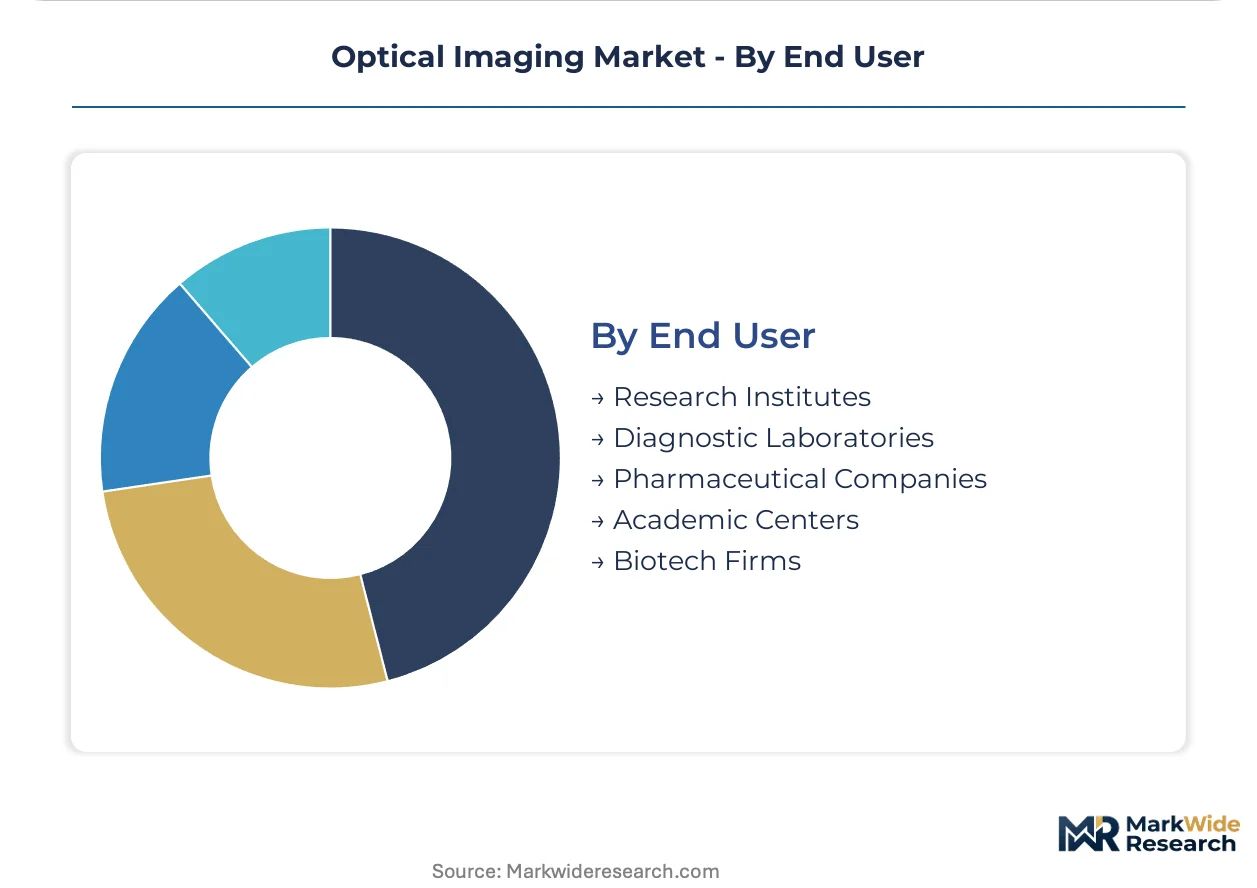
- Research Institutes:Price-insensitive buyers prioritize technical performance specifications and customization flexibility for novel experimental protocols. German Max Planck Institutes and Japanese RIKEN centers maintain multi-modal imaging core facilities with dedicated engineering support staff. Grant funding cycles create lumpy procurement patterns with extended evaluation timelines.
- Diagnostic Laboratories:High-volume operators drive equipment standardization through multi-year leasing structures and service contract bundling. South Korean and Taiwanese third-party service providers are capturing aftermarket revenue previously retained by original manufacturers. Unbundling trends are compressing hardware margins while expanding recurring service opportunities.
- Pharmaceutical Companies:Preclinical toxicity screening departments are accelerating OCT deployments to replace invasive tissue sampling.
- Academic Centers:Teaching hospitals balance research ambitions with clinical service obligations in hybrid procurement decisions.
- Biotech Firms:Venture-funded developers prioritize platform flexibility for evolving therapeutic pipelines.
Diagnostic Laboratories anchor volume procurement. Research Institutes sustain premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heidelberg and Oberkochen anchor the densest precision optics manufacturing cluster worldwide, supplying specialized lenses and detectors to OEM partners across ophthalmology and preclinical research applications.
United States
FDA's updated 21 CFR Part 820 guidance has tightened clinical evidence requirements for novel optical diagnostic submissions, extending predicate device pathway timelines. Medicare reimbursement coding decisions determine whether clinicians recover costs for advanced retinal procedures. Boston and San Diego host concentrated academic medical centers deploying combined OCT-photoacoustic systems for neuroscience research.
Germany
EU Medical Device Regulation harmonization streamlines multi-country market access for vendors with established ISO 13485 quality systems. The PLI scheme for medical electronics manufacturing attracts component assembly investments from Asian suppliers. Max Planck Institutes in Munich and Göttingen maintain multi-modal imaging core facilities with dedicated engineering support staff.
Japan
METI funding priorities accelerate preclinical platform development for breast cancer screening and brain oxygenation monitoring. PMDA regulatory pathways for novel modalities remain more permissive than FDA sequences, attracting startup prioritization of CE marking. RIKEN centers in Wako and Yokohama deploy swept-source OCT systems ahead of typical depreciation cycles.
India
Domestic production cost advantages under the PLI scheme for medical electronics support aggressive pricing in Southeast Asian export markets. CDSCO device registration timelines compress for established ISO 13485 manufacturers with prior US or EU approvals. Diagnostic laboratories in Maharashtra and Karnataka drive volume procurement through multi-year equipment leasing structures.
China
NMPA regulatory harmonization with international standards accelerates market entry for multinational vendors with existing FDA or CE marks. MIIT industrial policy prioritizes domestic detector foundry capacity to reduce dependence on Japanese and American indium gallium arsenide suppliers. Yangtze River Delta cities host growing clusters of third-party service providers capturing aftermarket revenue from disintermediated maintenance contracts.
Optical Imaging Market Key Industry Players
Strategic partnerships dominate the current landscape as vendors seek to combine hardware manufacturing with AI-enabled diagnostic software capabilities. The vendor base stratifies across three tiers: century-old optics heritage conglomerates, diversified medical technology multinationals, and specialized component suppliers. Two archetypes command premium positioning: integrated hospital informatics bundlers and precision surgical microscope OEMs. Competitive moves concentrate on technology licensing for computational image reconstruction and backward integration into specialized detector supply.
Among diversified medical technology conglomerates, Koninklijke Philips N.V. exemplifies the integrated informatics archetype through workflow software bundling. Carl Zeiss Meditec AG occupies the precision optics heritage position, leveraging century-old manufacturing expertise in surgical microscopy segments. Topcon Corporation represents the aggressive price-competition archetype across Asian diagnostic laboratory markets.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Topcon Corporation |
| Canon Inc. |
| PerkinElmer Inc. |
| Leica Microsystems |
| Heidelberg Engineering GmbH |
| Koninklijke Philips N.V. |
| Thorlabs Inc. |
| Bruker Corporation |
| Others |
Cost & Logistics Intelligence
Swept-source optical coherence tomography adoption is collapsing the performance gap between research-grade and clinical-grade systems, simultaneously compressing manufacturing costs and concentrating procurement authority among high-volume diagnostic laboratory chains. This technology transition rewards vendors with captive detector supply and penalizes those exposed to indium gallium arsenide foundry lead times.
Pricing Analysis
Input-cost pass-through from indium gallium arsenide detector shortages flows unevenly across product tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by acquisition speed and software bundling, with research institutes showing least price sensitivity and Asian diagnostic laboratories driving hardest bargain. Cost compression in standard-tier OCT systems is intensifying because third-party service providers in South Korea and Taiwan are disintermediating manufacturer service contracts.
Supply Chain Analysis
Indium gallium arsenide detector supply rests on Japanese and American specialty foundries, with optical-grade lens grinding concentrated in Germany and Japan. Swept-source laser engines and precision interferometer assemblies feed from Heidelberg and Oberkochen supplier networks. Single-source vulnerability in near-infrared sensor production creates procurement bottlenecks extending equipment delivery timelines. Distribution runs through direct OEM sales for research institutes and multi-year leasing brokers for diagnostic laboratory volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The optical imaging market functions as a regulatory compounder, with FDA's updated 21 CFR Part 820 guidance tightening clinical evidence requirements and extending predicate device pathway timelines for novel modalities.
For Market Incumbents: Acquire computational optics talent pools to address inverse problem-solving scarcity in image reconstruction. Backward integration into indium gallium arsenide detector supply hedges against Japanese and American foundry concentration. Channel control through integrated hospital informatics bundling defends against software disintermediation by third-party analytics vendors. For New Entrants and Emerging Players: Launch via third-party service contract partnerships in Indian diagnostic laboratory chains, where PLI scheme cost advantages enable aggressive Southeast Asian export pricing. Photoacoustic imaging preclinical platforms in academic medical centers represent the most penetrable white-space, with European CE marking sequences offering faster regulatory precedent than FDA submissions. For Investors and Strategic Acquirers: Valuations sit cheapest among component suppliers with captive precision optics manufacturing in German clusters. Long-term viability across the analysis window hinges on reimbursement coding decisions by Medicare and national health technology assessment bodies. The signal to watch is AI-enabled diagnostic software regulatory clearance velocity as a hardware attachment revenue inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | European precedent accelerates FDA predicate device submissions for photoacoustic platforms. |
| Hospital System Partnership | Heidelberg and Carl Zeiss anchor integrated informatics bundling with German university hospitals. |
| Software Companion Development | Cloud-based AI diagnostic support creates recurring revenue attachments to OCT hardware sales. |
| Reimbursement Strategy | Medicare coding decisions determine clinician cost recovery for advanced retinal procedures. |
| Backward Integration | Captive indium gallium arsenide supply hedges against Japanese and American foundry bottlenecks. |
Research Approach
Coverage spans the United States, Germany, Japan, India, and China, with primary inputs from each market's distinct regulatory and procurement environments. The research combines primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and pharmaceutical preclinical screening directors with secondary validation from FDA filings, EMA submissions, CMS Medicare data, and hospital procurement databases. Bottom-up equipment shipment tracking and top-down healthcare expenditure triangulation anchor market sizing.
Rate-of-change decomposition separates volume expansion from price trajectory across product type, technology, application, and end-user dimensions over the projection horizon. CAGRs derive from segmented adoption curves weighted by reimbursement code penetration and equipment replacement cycles. Swept-source OCT upgrade velocity and photoacoustic imaging research budget allocation serve as modality-specific forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions on indium gallium arsenide exports and unforeseen regulatory harmonization reversals. Forecasts reflect assumptions about continued Medicare reimbursement stability and EU MDR implementation pace. A small set of named triggers warrants ongoing watch: FDA guidance updates on AI diagnostic software, METI funding shifts for preclinical platforms, and PLI scheme revisions in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Photostimulation Lasers Market
Optics
Collimating Lens Market
Optics
Solid State Lasers Market
Optics
Fiber Optic Amplifier Market
Optics
Optical Telephoto Lens Market
Optics
Excimer Lasers for DUV Lithography Market
Optics
Optical Profilometer Market
Optics
Fiber Optic Development Tools Market
Optics
Global Optical Lens Market
Optics
Digital Holographic Microscopy Market
Optics
Global Enhanced Vision System Market
Optics
Global Semiconductor Lasers Market
Optics
Smart Vision Systems Market
Optics
APAC Smart Glass Market
Optics
Glass Scintillator Market
Optics
Interchangeable Lens Market