
 Acrylic Lenses Market | 2026-2036
Acrylic Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Lenses Market Analysis
The capital-intensity divergence between fully integrated manufacturers and assembly-only suppliers is redrawing competitive boundaries in acrylic lens production. Alcon leverages captive polymer synthesis facilities to control raw material quality and stabilize margin structures across its vision correction portfolio. Hoya Corporation anchors its position through precision molding investments in Japan and Southeast Asia. Carl Zeiss Meditec differentiates via advanced freeform surfacing technology that reduces lens thickness while maintaining optical clarity.
Acrylic lenses are thermoplastic optical components manufactured from polymethyl methacrylate (PMMA) or copolymer formulations, typically produced through injection molding or precision lathing processes to achieve refractive indices between 1.49 and 1.50 with Abbe values around 57. These lenses serve primarily in vision correction devices, protective eyewear, and photographic equipment where weight reduction and impact resistance outweigh the need for higher-index glass alternatives. Progressive lenses capture expanding margin pools as presbyopia prevalence rises among consumers over age 45. Photochromic variants sustain premium positioning through dual-use convenience in both indoor and outdoor settings. Single-vision segments dominate volume through standardized production and broad retail availability.
FDA biocompatibility standards and ISO 11979 ophthalmic implant requirements shape product development timelines and testing expenditures for manufacturers serving medical applications. The EU MDR and REACH chemical compliance frameworks add layer complexity for European market entry, particularly regarding residual monomer thresholds in PMMA formulations. Stakeholders must monitor evolving blue-light filtering claims and associated regulatory scrutiny in major consumer markets.
Market Dynamics
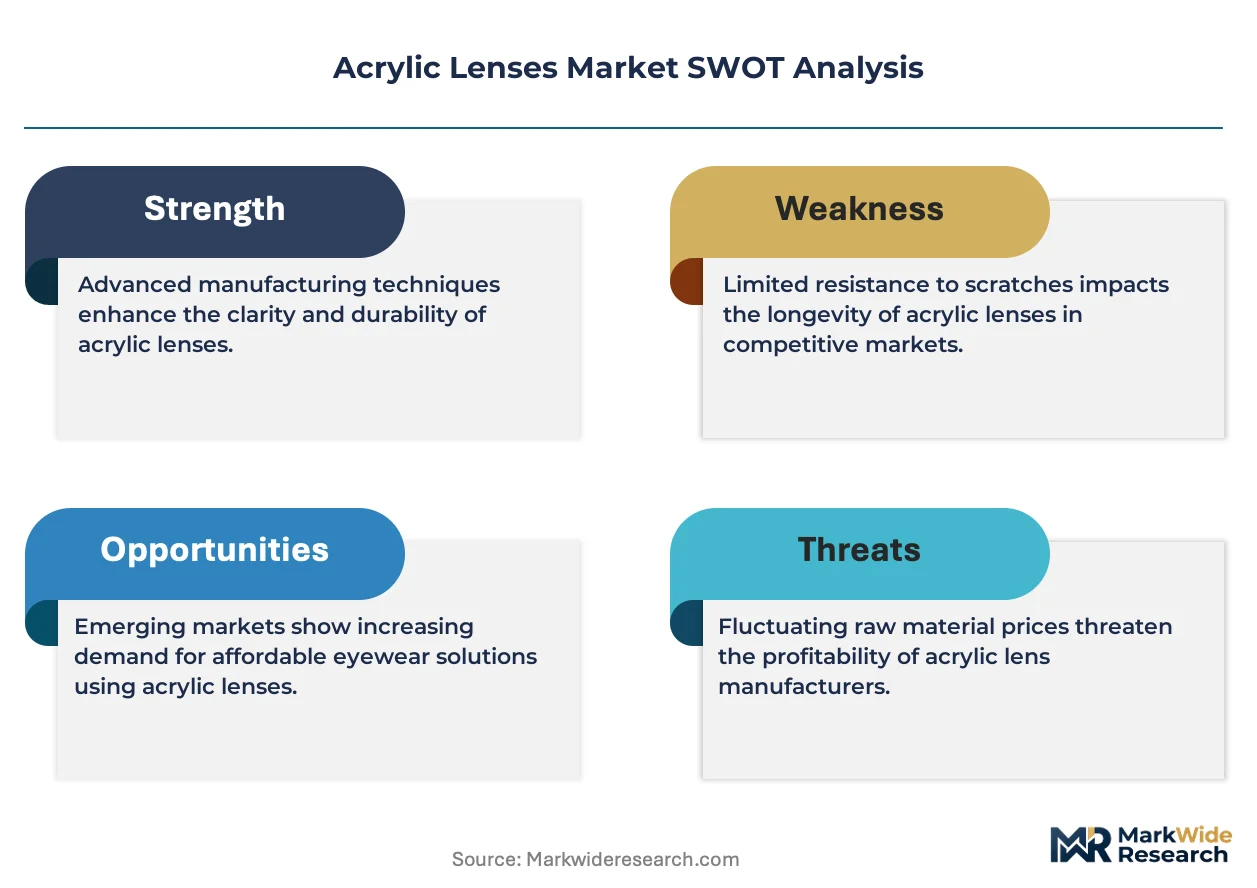
The acrylic lenses sector faces intensifying pressure from FDA biocompatibility mandates and ISO 11979 ophthalmic implant standards, which extend product development cycles and elevate testing expenditures for manufacturers serving medical-grade applications.
Growth Catalysts
- Presbyopia Demographics:Aging populations in Japan, Germany, and the United States sustain demand for progressive lens designs. Optical retailers expand lightweight acrylic inventories to capture replacement cycles among consumers over age 45.
- REACH Chemical Compliance:EU residual monomer thresholds in PMMA formulations are accelerating R&D investment in purified copolymer alternatives. European manufacturers with advanced purification capabilities gain preferential market access.
- Freeform Surfacing:Digital lathe technology enables customized aspheric profiles that reduce center thickness while maintaining optical clarity. Eyewear brands integrate these capabilities to differentiate premium product lines.
Market Restraints
- Methyl Methacrylate Price Volatility:Petrochemical feedstock fluctuations compress margin predictability for non-integrated lens fabricators. Captive polymer synthesis facilities insulate only the largest manufacturers from input cost swings.
- Polycarbonate Substitution:Higher-index thermoplastics with superior impact resistance capture share in protective eyewear and sports applications where weight sensitivity is secondary to durability requirements.
- FDA 510(k) Pathway Friction:Intraocular lens submissions face extended review timelines for novel materials. Small manufacturers lack capital reserves to sustain multi-year regulatory gestation periods.
Strategic Opportunities
- Blue-Light Filtering Certification:Unstandardized claims around digital eye strain create first-mover advantage for manufacturers pursuing third-party validation. French health authorities through ANSM are evaluating evidentiary requirements for such assertions.
- Photochromic Copolymer Convergence:Integration of light-responsive chemistry directly into PMMA matrices eliminates secondary coating processes. This convergence reduces manufacturing steps for mid-tier producers seeking premium positioning.
- Direct-to-Consumer Optical Platforms:Online lens replacement services bypass traditional retail markups. North American and European consumers with existing prescriptions represent addressable demand for standardized single-vision products.
Industry Challenges
- Precision Optics Talent Scarcity:Freeform design software and CNC lathe operation require specialized training. Japanese and German technical institutes produce insufficient graduates to meet tooling expansion plans across Southeast Asian manufacturing hubs.
- Legacy ERP Integration:Batch record systems for FDA-compliant medical devices resist cloud migration. Manufacturers face operational friction when connecting quality management modules to modern supply chain planning platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Lenses Market |
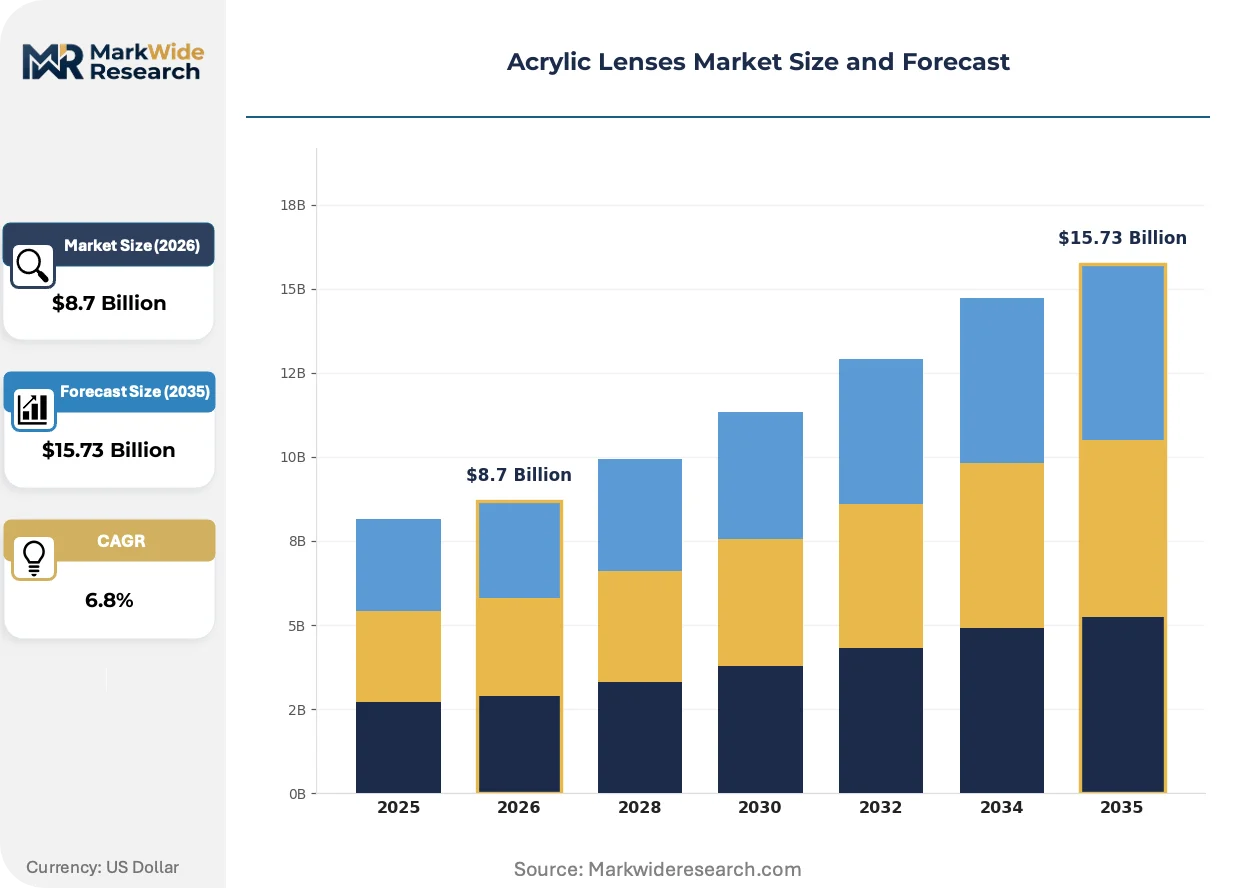
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Vision, Bifocal, Progressive, Photochromic Application: Vision Correction, Sunglasses, Safety Glasses, Recreational Use End User: Retail Consumers, Optical Stores, Hospitals, Laboratories Distribution Channel: Online Retail, Brick-and-Mortar, Optometry Clinics, Wholesale |
| Companies Covered | Bausch & Lomb, Alcon, Hoya Corporation, Carl Zeiss Meditec, EyeKon Medical, LensOptic, Polyoptics GmbH, Aurolab, Abbott Medical Optics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Lenses Market Emerging Trajectories
Digital manufacturing workflows and evolving consumer vision needs are compressing traditional production paradigms while opening new specification territories for material scientists and optical designers.
Cast-molded PMMA is displacing ground-and-polished crown glass in medium-prescription corrective lenses. Independent eyewear brands in Italy and Denmark are adopting these thermoplastic alternatives to reduce finished frame weight by 40-50 percent. The shift is compressing lead times from weeks to days while enabling complex rimless mountings previously impractical with brittle mineral substrates.
EU MDR implementation is recalibrating quality system requirements for intraocular lens manufacturers. Notified body capacity constraints are extending certification timelines, forcing producers to front-load clinical evidence generation. German and Swiss ophthalmic implant specialists are responding by consolidating supplier audits and harmonizing documentation across multiple product families.
Subscription-based lens replacement programs are fragmenting traditional retail dependency in North America and Western Europe. Younger myopic consumers prioritize convenience over optometrist channel loyalty, accepting remote prescription verification for standardized single-vision orders. This behavioral pivot pressures independent optical shops to unbundle professional services from product margins.
Acrylic Lenses Market Segmentation
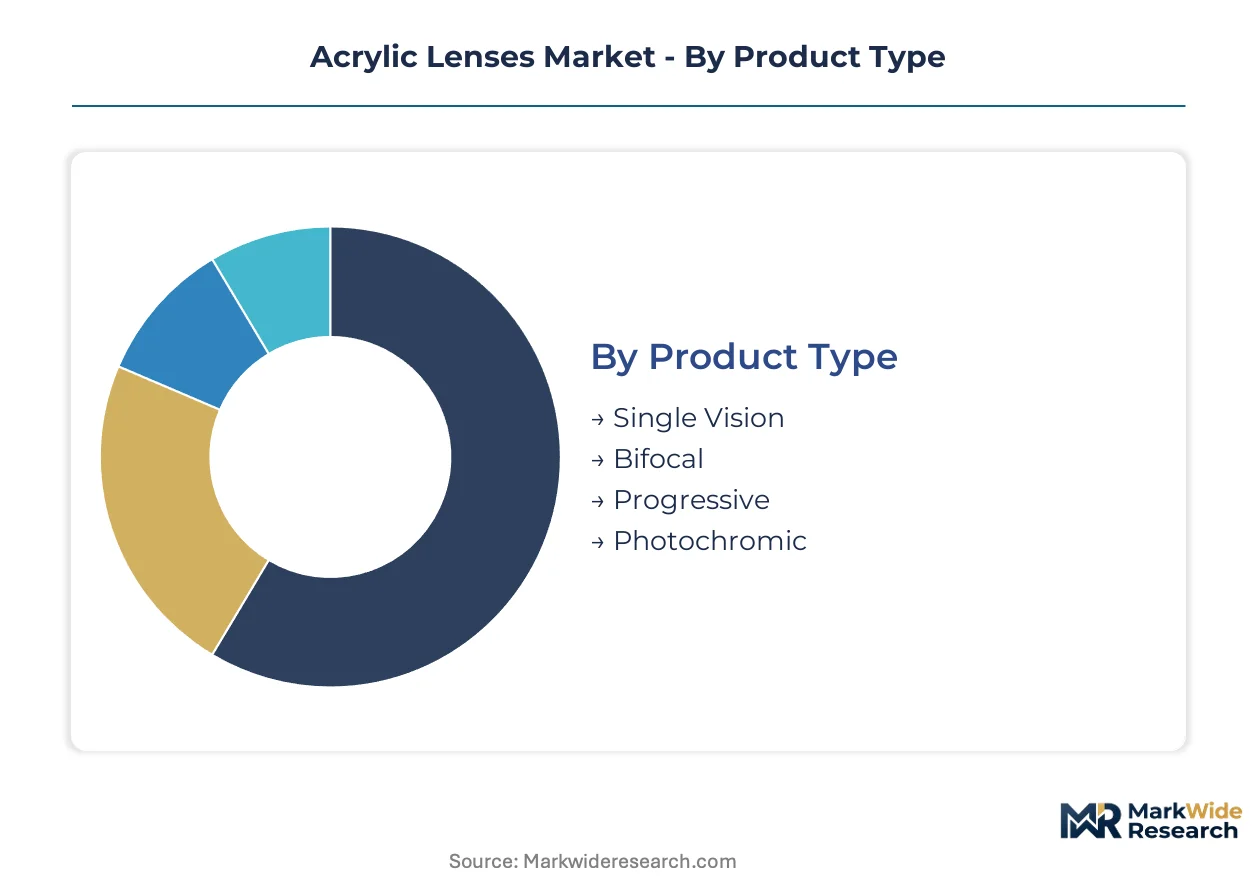
Acrylic lens manufacturers segment their portfolios to capture distinct margin pools across prescription complexity, protective specifications, and channel economics. Product architecture and route-to-market choices determine working capital intensity and pricing power in this thermoplastic optics sector.
Product Type:
Margin concentration shifts toward customized progressive designs as presbyopia prevalence climbs among aging populations in Japan, Germany, and the United States.
- Single Vision:Standardized spherical or aspheric designs with uniform dioptric power across the entire lens surface. Volume leadership concentrates in North American retail chains and European optical franchises where replacement cycles for myopic consumers under age 40 sustain throughput.
- Progressive:Continuous power gradient lenses eliminating visible segment lines through precision freeform surfacing. Japanese and German precision molders command premium positioning as consumers over age 45 prioritize cosmetic aesthetics and functional near-to-far vision correction.
- Bifocal:Two-distinct-zone designs with visible demarcation between distance and near corrections. Demand persists among price-sensitive Medicare beneficiaries in the United States seeking durable, low-maintenance vision solutions.
- Photochromic:Light-responsive copolymer formulations embedding silver halide chemistry directly within PMMA matrices. Dual-use convenience commands retail premiums in climates with high solar exposure across Australia and the southwestern United States.
Single Vision holds installed capacity. Progressive is rotating up the share rankings.
Application:
Volume distribution tracks occupational safety mandates and recreational participation rates across distinct protective eyewear categories.
- Vision Correction:Corrective prescription lenses fabricated to individual optometric specifications through digital surfacing or cast molding. United States Medicare reimbursement policies and Japanese national health insurance sustain volume leadership for presbyopia and myopia management.
- Safety Glasses:Impact-rated protective lenses meeting ANSI Z87.1 and EN 166 standards for industrial and construction environments. German automotive manufacturing clusters and United States OSHA-mandated workplace programs drive specification-grade demand.
- Sunglasses:Tinted or polarized acrylic lenses for UV protection and glare reduction. Italian fashion eyewear houses and Danish independent brands adopt cast-molded PMMA to achieve 40-50 percent weight reduction versus mineral glass.
- Recreational Use:Specialized optics for cycling, skiing, and water sports requiring wraparound geometries and anti-fog coatings. Australian and Swiss alpine equipment manufacturers specify impact-modified copolymers for durability under dynamic loading conditions.
Vision Correction dominates absolute volume. Safety Glasses is climbing the fastest as workplace PPE regulations tighten across industrialized economies.
End User:
Procurement authority and technical specification complexity fragment demand across retail, clinical, and institutional channels.
- Optical Stores:Independent and chain retailers managing prescription fulfillment, frame fitting, and lens edging services. United States and United Kingdom consolidation trends favor multi-location operators with centralized laboratory relationships.
- Retail Consumers:Individual purchasers of non-prescription sunglasses, reading glasses, and replacement lenses. Direct-to-consumer platforms in North America and Western Europe bypass traditional retail markups for standardized single-vision products.
- Hospitals:Ophthalmology departments and surgical centers sourcing intraocular lenses and post-operative corrective optics. FDA 510(k) clearance and EU MDR certification requirements limit supplier eligibility for implant-grade PMMA formulations.
- Laboratories:Wholesale optical laboratories performing surfacing, coating, and edging on semi-finished lens blanks. German and Japanese precision optics clusters maintain technical leadership in freeform digital lathe operations.
Optical Stores command procurement volume. Retail Consumers is gaining share fastest through subscription replacement programs and remote prescription verification.
Distribution Channel:
Channel economics reflect inventory carrying costs, prescription validation requirements, and service bundling intensity.
- Brick-and-Mortar:Physical retail locations combining eye examination, frame selection, and lens fitting services. Japanese and German high-street optical traditions sustain premium positioning through personalized consultation and immediate fulfillment.
- Online Retail:E-commerce platforms offering standardized lenses with remote prescription upload and home delivery. United States and United Kingdom consumers under age 35 demonstrate highest acceptance of unbundled product purchasing.
- Optometry Clinics:Clinical settings integrating diagnostic services with captive lens dispensing. Medicare-participating practices in the United States leverage reimbursement codes to maintain patient capture rates.
- Wholesale:Business-to-business distribution of semi-finished blanks and finished lenses to independent laboratories and retail chains. Southeast Asian manufacturing hubs serve as consolidation points for regional optical supply networks.
Brick-and-Mortar retains patient relationship control. Online Retail is expanding most quickly as platform logistics mature and prescription verification protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between medical-grade implant markets and fashion-driven eyewear economies, with the former concentrating in aging societies with robust reimbursement frameworks and the latter clustering in design-centric manufacturing regions.
United States
Medicare reimbursement policies sustain volume leadership for presbyopia-correcting progressive lenses among consumers over age 45. FDA 510(k) clearance requirements for intraocular implants limit supplier eligibility to manufacturers with substantial clinical evidence reserves. The Boston-Cambridge corridor hosts precision optics laboratories serving both retail chains and hospital ophthalmology departments.
Germany
Automotive manufacturing clusters in Bavaria and Baden-Württemberg drive specification-grade demand for ANSI Z87.1-rated safety eyewear. EU MDR implementation extends certification timelines for implant-grade PMMA formulations, favoring producers with harmonized quality systems. The Jena-Weimar optics cluster maintains technical leadership in freeform digital lathe operations for customized aspheric designs.
Japan
National health insurance sustains replacement cycles for myopic consumers under age 40 and presbyopic populations over 45. METI industrial standards shape residual monomer thresholds in copolymer formulations for domestic manufacturers. The Higashiosaka precision molding district supplies semi-finished blanks to optical retailers throughout East Asia.
Italy
Fashion eyewear houses in the Veneto and Lombardy regions adopt cast-molded PMMA to achieve 40-50 percent weight reduction versus mineral glass. REACH chemical compliance frameworks govern residual monomer thresholds in formulations exported to Northern European markets. The Cadore-Dolomites eyewear manufacturing corridor specializes in rimless mountings enabled by thermoplastic durability.
Australia
High solar exposure climates sustain retail premiums for photochromic copolymer formulations with embedded silver halide chemistry. TGA therapeutic goods administration oversees biocompatibility standards for intraocular lens imports. The Sydney-Melbourne corridor concentrates distribution logistics for subscription-based lens replacement programs targeting younger myopic consumers.
Acrylic Lenses Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in acrylic lens production, with captive polymer synthesis facilities insulating the largest manufacturers from methyl methacrylate feedstock volatility. The structure bifurcates between medical-grade implant specialists subject to FDA and EU MDR compliance burdens, and fashion eyewear fabricators competing on weight reduction and design flexibility. Three archetypes dominate: vertically integrated ophthalmic giants, precision molding specialists, and independent optical laboratories. Competitive moves concentrate on backward integration into polymer synthesis and geographic expansion through distributor partnerships in Southeast Asian manufacturing hubs.
Among the integrated leaders, Alcon and Hoya Corporation exemplify the captive-supply archetype, while Carl Zeiss Meditec occupies a position representing the precision-surfacing specialist tier. These three anchors illustrate how scale-driven polymer control, regional molding investments, and advanced freeform technology respectively define competitive positioning in vision correction markets.
| Leading Market Players |
|---|
| Bausch & Lomb |
| Alcon |
| Hoya Corporation |
| Carl Zeiss Meditec |
| EyeKon Medical |
| LensOptic |
| Polyoptics GmbH |
| Aurolab |
| Abbott Medical Optics |
| Others |
Supply Flow & Price Mechanics
Cast-molded PMMA displacing ground-and-polished crown glass simultaneously redistributes manufacturing toward Japanese precision molding districts and compresses margin structures for Italian fashion eyewear houses competing on weight reduction rather than optical heritage.
Pricing Analysis
Replacement lens subscriptions and coating service contracts generate recurring revenue streams that exceed initial hardware margins for direct-to-consumer platforms. Three-tier pricing structure across premium freeform progressives, standard single-vision, and economy reading glasses reflects certification grade and customization intensity. Pricing pressure stems from polycarbonate substitution in protective eyewear as ANSI Z87.1-rated alternatives capture industrial contracts. Price-sensitive Medicare beneficiaries in the United States prioritize bifocal durability over progressive aesthetics, while Japanese consumers under national health insurance show lowest sensitivity to photochromic premiums.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for German automotive safety eyewear clusters sourcing impact-modified copolymers. Manufacturing concentrates in Japan, Germany, and Italy, with each hub feeding distinct end-use specializations. Raw material dependencies rest on methyl methacrylate monomer from petrochemical feedstocks, silver halide chemistry for photochromic variants, and specialized dyes for blue-light filtering claims. Single-source vulnerability concentrates in Japanese precision molding equipment for freeform digital lathes. Distribution runs through wholesale optical laboratories performing surfacing and edging before retail fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as prescription verification protocols and subscription replacement programs fragment traditional retail channel control, creating entry points for specialized coating laboratories and direct-to-consumer platforms.
For Market Incumbents: Fortify captive polymer synthesis capabilities against methyl methacrylate feedstock volatility while consolidating freeform surfacing talent through partnerships with Japanese and German technical institutes. Polycarbonate substitution in sports protective eyewear threatens acrylic volume in recreational segments. FDA 510(k) pathway friction for novel intraocular materials favors incumbents with clinical evidence reserves. For New Entrants and Emerging Players: Differentiate on blue-light filtering certification by pursuing third-party validation through ANSM evaluation pathways before competitors standardize evidentiary requirements. White-space targets include direct-to-consumer single-vision replacement for myopic consumers under age 35 in North America and Western Europe, plus photochromic copolymer convergence eliminating secondary coating steps. Go-to-market angle leverages remote prescription verification partnerships with telehealth platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision molding specialists in Southeast Asian manufacturing hubs lacking backward integration into polymer synthesis. Long-term viability centers on medical-grade implant specialists with EU MDR harmonized quality systems and FDA 510(k) clearance track records. Watch ANSM evidentiary rulings on digital eye strain claims as inflection indicator for premium coating valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Captive methyl methacrylate supply insulates Alcon and Hoya from petrochemical feedstock swings. |
| Freeform Digital Lathe Capacity Expansion | Japanese precision molding districts command premium positioning for customized aspheric progressive designs. |
| Blue-Light Filtering Certification Pursuit | ANSM evaluation pathways create first-mover advantage before evidentiary requirements standardize across EU markets. |
| Direct-to-Consumer Platform Launch | Remote prescription verification bypasses traditional retail markups for standardized single-vision products. |
| Photochromic Copolymer Convergence | Embedded silver halide chemistry eliminates secondary coating processes for mid-tier premium positioning. |
Methodological Framework
Desk research of FDA 510(k) filings, EU MDR notified body documentation, and ISO 11979 ophthalmic implant standards preceded structured interviews with optical laboratory directors, ophthalmology department procurement managers, freeform surfacing equipment operators, and polymer synthesis plant managers. Secondary validation drew from customs trade data for methyl methacrylate monomer flows, SEC 10-K disclosures from integrated vision correction companies, and Medicare reimbursement code utilization statistics. Bottom-up and top-down triangulation reconciled prescription volume estimates with manufacturing capacity declarations across Japanese and German precision optics clusters.
Variance decomposition across product type, application, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion constraints. Modeled inputs included presbyopia demographic trajectories, REACH residual monomer threshold compliance costs, and freeform surfacing equipment installation rates.
Forecasts assume regulatory continuity in FDA biocompatibility standards and EU MDR implementation timelines; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Collimating Lens Market
Optics
Smart Vision Systems Market
Optics
Fiber Optic Connectivity Market
Optics
Fiber Optics Market
Optics
Fiber Optic Switch Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Solid State Lasers Market
Optics
Residential 1080P Laser Television Projector Market
Optics
Sports Optics Market
Optics
Optical Liquid Level Sensor Market
Optics
Camera Module Lens Market
Optics
3D Optical Microscope Market
Optics
Laser Transmitter Market
Optics
Germanium Lens Market
Optics
Smart Photochromic Lenses Market
Optics
Middle East and Africa Optical Imaging Market