
 Sports Optics Market | 2026-2036
Sports Optics Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Optics Market Analytics
Optical engineering talent is rotating away from traditional camera manufacturing toward sports and tactical applications, unlocking specialized product development pipelines. Carl Zeiss AG leverages its century-old glass formulation expertise to sustain premium positioning in hunting and birdwatching segments. Nikon Corporation anchors volume production through its established Asian manufacturing footprint, while Swarovski Optik differentiates through Austrian-made precision assemblies that command enthusiast loyalty.
Sports optics encompasses precision-engineered visual instruments including binoculars, spotting scopes, rangefinders, and night vision devices, typically featuring multi-coated lens systems with phase-corrected roof prisms and nitrogen-purged housings for waterproof performance to depths of one meter or more. These instruments serve hunters, wildlife observers, and outdoor athletes requiring magnification, distance measurement, or low-light visibility beyond unaided human capability. Binoculars occupy the largest installed base across consumer segments, though thermal imaging technology captures the fastest expansion as price points decline and image resolution improves. Rangefinders concentrate margin pools in the hunting application segment where laser accuracy to within one yard commands substantial price premiums.
FDA laser product regulations govern rangefinder emission classifications in the United States, while ECHA REACH restrictions limit certain optical coating solvents and rare-earth elements in European-sold instruments. CE marking and the EU AI Act increasingly affect digital and connected optics with embedded software or image-processing algorithms. Stakeholders must monitor evolving cross-border compliance costs as thermal and digital technologies blur traditional product category boundaries.
Market Dynamics
Thermal imaging price compression is fragmenting traditional product hierarchies as uncooled sensor volumes scale and entry-level units penetrate hunting and wildlife observation segments previously reserved for premium glass optics.
Growth Catalysts
- EU F-Gas Regulation phase-down:Manufacturers accelerating hydrofluorocarbon-free thermal coolant development capture first-mover certification advantages in European distribution channels.
- Wildlife tourism operator procurement:Guided safari and backcountry outfitters in Kenya, Tanzania, and Botswana are standardizing 8x42 and 10x42 binocular inventories to differentiate guest experience quality.
- Laser rangefinder integration:Ballistic calculation engines embedded in hunting optics compress shot-to-shot decision cycles, driving replacement demand among precision rifle competitors.
Market Restraints
- Germanium lens substrate volatility:Thermal objective lens production depends on germanium supply concentrated in China and Russia, exposing margin structures to export restriction risk.
- RoHS rare-earth limitations:ECHA restrictions on lanthanum and thorium-containing glass formulations force reformulation of high-dispersion objective elements at elevated R&D cost.
- Smartphone computational photography:Computational zoom and night-mode algorithms in flagship mobile devices substitute casual wildlife observation use cases below 10x magnification requirements.
Strategic Opportunities
- India wildlife sanctuary expansion:State forest department tenders for ranger patrol equipment under Project Tiger create institutional procurement pipelines for mid-range spotting scopes.
- EU AI Act compliance services:Connected optics with embedded image recognition require algorithmic transparency documentation, opening advisory revenue streams for certification specialists.
- Direct-to-consumer thermal channels:E-commerce platforms bypassing traditional hunting specialty retailers capture margin compression benefits in price-sensitive varmint control segments.
Industry Challenges
- Optical coating technician scarcity:Vacuum deposition and ion-beam sputtering expertise concentrates in aging workforces across Wetzlar and Jena manufacturing clusters.
- CE-MDR dual certification timelines:Digital rangefinders with medical-adjacent laser classifications face extended conformity assessment periods delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Optics Market |
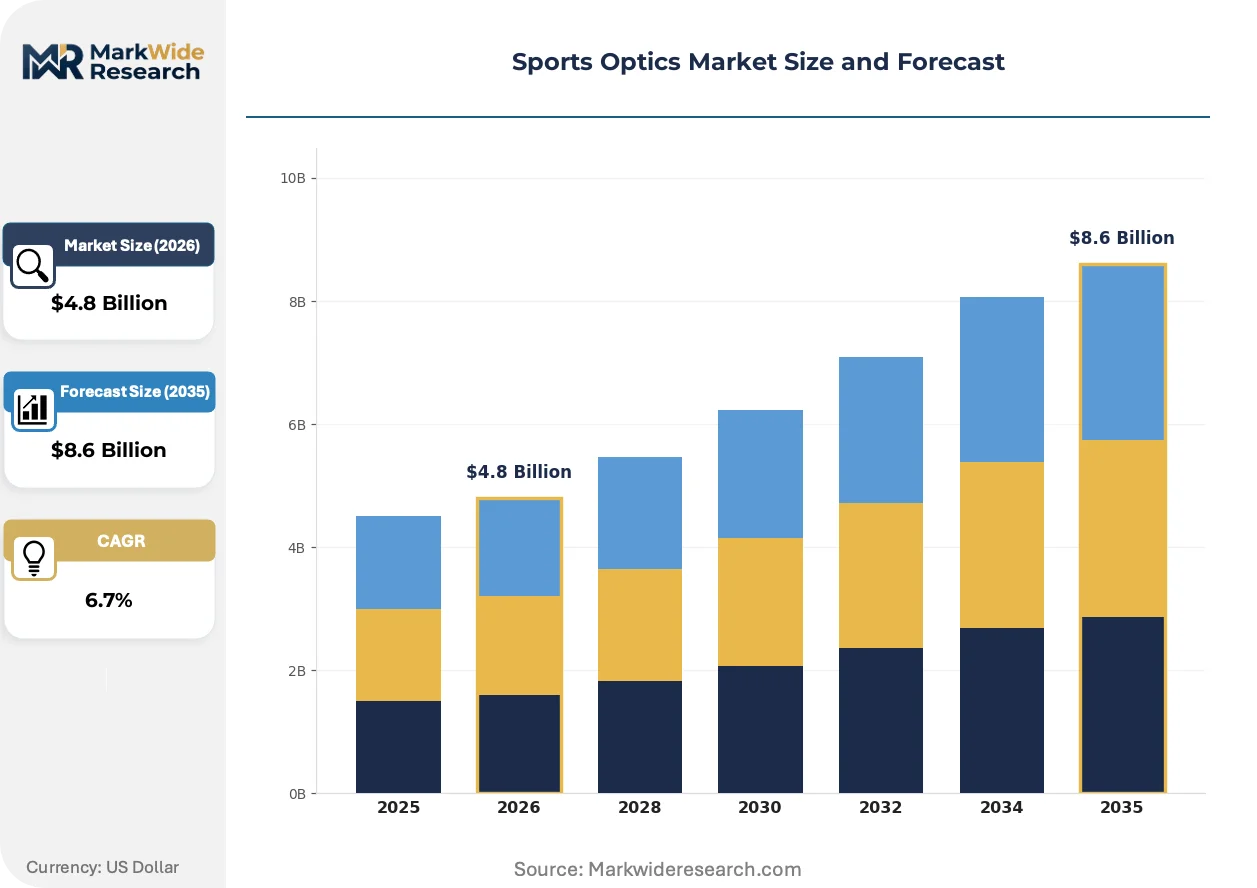
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
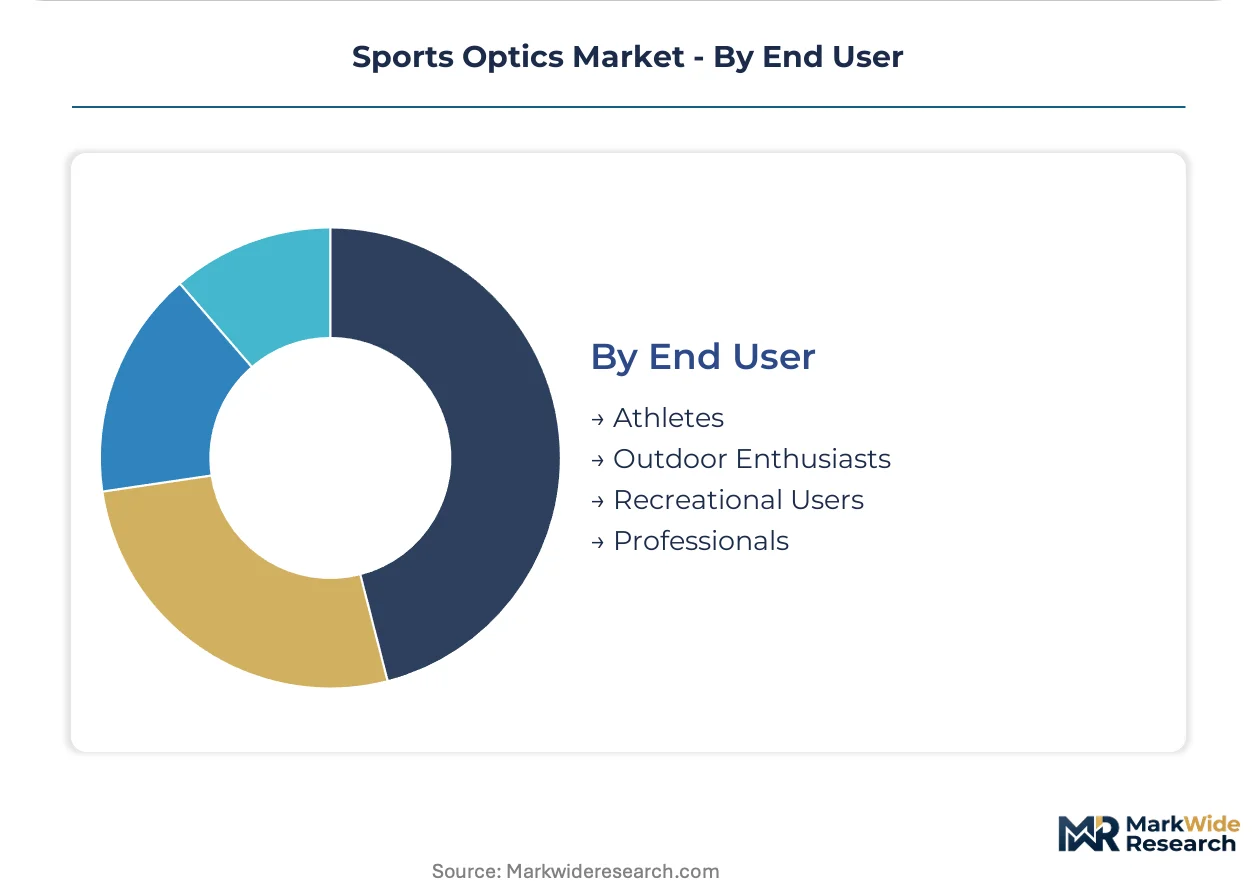
| Segmentation | Product Type: Binoculars, Spotting Scopes, Rangefinders, Night Vision Devices Application: Hunting, Birdwatching, Hiking, Sporting Events Technology: Digital, Optical, Thermal Imaging, Compact End User: Athletes, Outdoor Enthusiasts, Recreational Users, Professionals |
| Companies Covered | Trijicon, Inc., Leica Camera AG, Nikon Corporation, Celestron, LLC, Leupold & Stevens, Inc., Carl Zeiss AG, Swarovski Optik, American Technologies Network Corporation, Bushnell Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Optics Market Evolving Landscape
Image sensor fusion architectures are collapsing the boundary between thermal detection and visible-light identification, enabling single-device solutions that previously required separate optical systems.
Uncooled vanadium oxide microbolometer technology is fragmenting thermal product tiers as 640x480 resolution modules drop below premium binocular price points. Ranchers and agricultural pest control operators in Texas and Queensland are adopting these units for feral hog and predator management. The technology is fragmenting historical segmentation between professional military procurement and consumer hunting markets.
REACH Annex XVII restrictions on perfluorinated compounds are forcing elimination of certain anti-reflective coating precursors from European-sold instruments. Lens manufacturers are validating plasma-enhanced chemical vapor deposition alternatives at reduced environmental throughput. Premium hunting scope lines face 12-18 month reformulation cycles to maintain CE marking compliance.
Specialty retailer consolidation is compressing brand access to enthusiast buyers as independent optics shops in the US Mountain West and German-speaking Europe close or merge. Direct manufacturer relationships with wildlife guide associations and hunting lease cooperatives are displacing traditional wholesale distribution. This channel rotation is most visible in South Africa's private game reserve sector where lodge procurement committees negotiate fleet pricing for guest equipment.
Sports Optics Market Segmentation
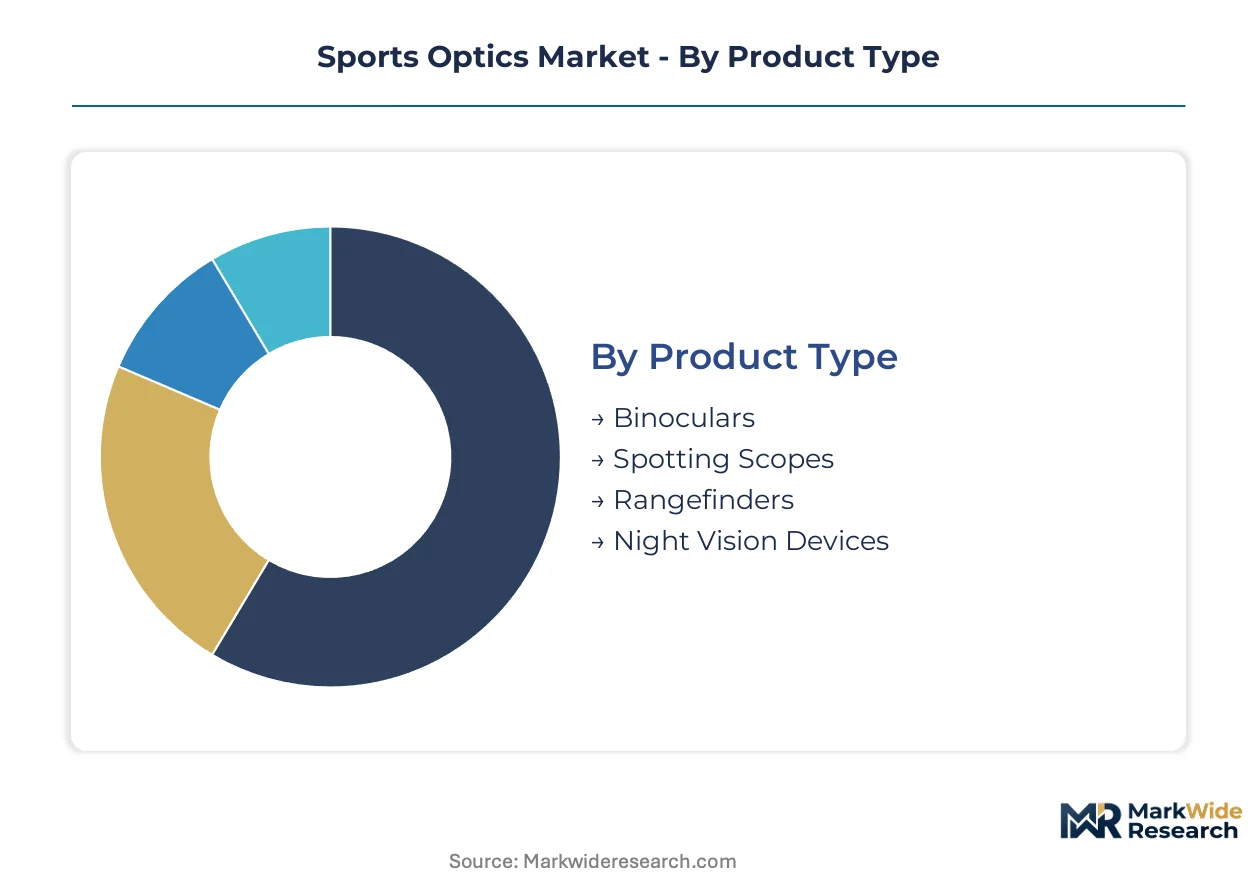
Product differentiation in sports optics follows distinct regulatory and performance boundaries. Binoculars, thermal imagers, and laser rangefinders each face separate compliance pathways that reshape manufacturing investments and distribution access.
Product Type:
FDA laser classifications and ECHA coating restrictions split manufacturing footprints across product lines.
- Binoculars:Multi-coated roof prism systems with phase-correction coatings dominate recreational volume. Safari operators in Kenya and Tanzania standardize on 8x42 and 10x42 configurations for guest fleet procurement. Established volume favors Binoculars; emerging adoption favors Night Vision Devices.
- Spotting Scopes:High-magnification straight and angled body designs serve precision shooters and distant wildlife observation. State forest departments under India's Project Tiger tender mid-range units for ranger patrol equipment.
- Rangefinders:FDA-regulated Class 1 and Class 2 laser emission devices integrate ballistic calculation engines for hunting applications. Laser accuracy to within one yard commands substantial price premiums in precision rifle competitions.
- Night Vision Devices:Image intensifier tubes and digital sensor variants span military-adjacent and consumer tiers. Uncooled vanadium oxide microbolometer modules are dropping below premium glass price points.
Optical heritage anchors Binoculars; sensor fusion technology accelerates Night Vision Devices.
Application:
End-use concentration determines margin structure and channel access requirements.
- Hunting:Ballistic-integrated optics and thermal predator management drive replacement cycles. Texas and Queensland ranchers adopt uncooled thermal units for feral hog control. Procurement concentrates in hunting lease cooperatives and guide services.
- Birdwatching:Premium glass quality and close-focus distance specifications define enthusiast expectations. Austrian-made precision assemblies command loyalty among dedicated observers.
- Hiking:Lightweight roof prism configurations with nitrogen-purged waterproofing serve mobile users. Compact dimensions trade magnification range for packability.
- Sporting Events:Wide-field binoculars with fast-focus mechanisms suit stadium and trackside viewing. Price sensitivity runs higher than specialty outdoor segments.
Equipment intensity peaks in Hunting; participation breadth peaks in Hiking.
Technology:
REACH Annex XVII and EU AI Act compliance costs stratify competitive positions.
- Digital:Connected optics with embedded image recognition require algorithmic transparency documentation under EU AI Act. CE marking timelines extend for software-enabled devices.
- Optical:Traditional glass-and-prism systems depend on reformulated high-dispersion elements as ECHA restricts lanthanum and thorium-containing formulations. Wetzlar and Jena manufacturing clusters retain coating expertise.
- Thermal Imaging:Uncooled microbolometer scaling fragments historical military-consumer segmentation. 640x480 resolution modules penetrate varmint control markets. Thermal Imaging is climbing the fastest.
- Compact:Collapsible bridge designs and reverse Porro prism architectures minimize carry burden. Smartphone computational photography substitutes casual use cases below 10x magnification.
Optical purity dominates enthusiast segments; thermal capability expands addressable markets.
End User:
Professional procurement bypasses retail channels through direct manufacturer negotiation.
- Athletes:Competitive precision rifle shooters demand ballistic calculation integration and rapid target acquisition. Equipment specifications follow governing body equipment rules.
- Outdoor Enthusiasts:Dedicated birdwatchers and backcountry travelers prioritize optical quality over price. Brand loyalty concentrates in German-speaking European and US Mountain West markets.
- Recreational Users:Casual wildlife observers and occasional hikers show substitution vulnerability to smartphone camera improvements. Entry-level price tiers face margin compression.
- Professionals:Wildlife tourism operators, hunting guides, and ranger services procure standardized fleets. Lodge procurement committees in South Africa's private game reserve sector negotiate volume pricing.
Professional segments consolidate purchasing power; recreational segments fragment across price tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH regulations in Germany anchor the dominant geography for precision optics manufacturing, with the Wetzlar and Black Forest clusters setting technical standards that cascade through European distribution channels and influence coating chemistry specifications worldwide.
United States
Texas ranchers and Queensland agricultural operators drive thermal imager adoption for feral hog management, while FDA laser classifications govern rangefinder emission standards for hunting applications. The Mountain West region retains independent optics retailers that serve precision rifle competitors and backcountry guides.
Germany
ECHA restrictions on lanthanum and thorium-containing glass formulations force reformulation of high-dispersion objective elements. The Wetzlar precision optics belt and Jena manufacturing clusters concentrate vacuum deposition expertise that aging workforces struggle to replenish.
Austria
Swarovski Optik's Austrian-made precision assemblies command enthusiast loyalty in birdwatching segments, with close-focus distance specifications defining premium positioning. The country's optical heritage sustains manufacturing employment despite broader European industrial restructuring.
India
State forest department tenders under Project Tiger create institutional procurement pipelines for mid-range spotting scopes deployed in ranger patrol equipment. Karnataka and Maharashtra wildlife sanctuaries expand ranger staffing levels that drive standardized equipment purchases.
South Africa
Private game reserve lodge procurement committees negotiate fleet pricing for guest binoculars, displacing traditional wholesale distribution through direct manufacturer relationships. Kenya and Tanzania safari operators standardize on 8x42 and 10x42 configurations to differentiate guest experience quality.
Sports Optics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with heritage optical manufacturers competing against thermal sensor specialists and volume Asian producers. The structure fragments across three strategic archetypes: century-old European precision houses, Japanese volume manufacturers with established Asian footprints, and emerging thermal technology specialists. Competitive moves concentrate on coating chemistry reformulation for REACH compliance and direct channel development bypassing consolidating specialty retailers.
Within the heritage precision tier, Carl Zeiss AG and Leica Camera AG exemplify century-old glass formulation expertise sustained through premium hunting and birdwatching positioning. Nikon Corporation anchors volume production through its established Asian manufacturing footprint. Swarovski Optik occupies a distinct Austrian-made precision position that commands enthusiast loyalty through dedicated observer segments.
| Leading Market Players |
|---|
| Trijicon, Inc. |
| Leica Camera AG |
| Nikon Corporation |
| Celestron, LLC |
| Leupold & Stevens, Inc. |
| Carl Zeiss AG |
| Swarovski Optik |
| American Technologies Network Corporation |
| Bushnell Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements for germanium lens substrates lock in thermal imager supply access while anchoring price visibility against export restriction volatility. These contracts concentrate procurement leverage among heritage European precision houses that can commit volume, leaving smaller thermal specialists exposed to spot-market swings in China and Russia.
Pricing Analysis
Geographic price spreads of 40-60% separate Austrian-made precision assemblies from Asian volume production across equivalent optical specifications. Three-tier pricing structure across premium, standard, and economy levels differentiates on coating certification grade and after-sales service bundling. Cost compression in entry-level thermal units is intensifying because uncooled microbolometer scaling fragments historical segmentation. Recreational users show highest price sensitivity, while professional wildlife guides prioritize optical purity over cost.
Supply Chain Analysis
China and Russia concentrate germanium substrate production for thermal objective lenses, while Germany's Wetzlar belt anchors precision glass formulation. The supply chain draws from rare-earth elements concentrated in Chinese processing facilities, nitrogen-purged housing components from Southeast Asian metalworking centers, and phase-correction coating precursors subject to REACH Annex XVII restrictions. Single-source vulnerability in germanium supply exposes margin structures to export controls. Distribution runs through consolidating specialty retailers in the US Mountain West and direct manufacturer relationships with South African lodge procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in thermal-sensor fusion architectures where demand-side shifts from separate-device procurement to single-instrument solutions create niche entry points. Wildlife tourism operator fleet standardization and rancher predator management adoption expand addressable markets beyond traditional enthusiast segments.
For Market Incumbents: Shield premium positioning by accelerating hydrofluorocarbon-free thermal coolant certification ahead of EU F-Gas Regulation phase-down deadlines. Deepen backward integration into captive coating deposition capacity within Wetzlar and Jena clusters to offset technician scarcity. Control channel access through direct procurement relationships with Kenya and Tanzania safari operators that displace wholesale distribution. For New Entrants and Emerging Players: Differentiate on algorithmic transparency documentation services for EU AI Act compliance among connected optics manufacturers. Target India's Project Tiger ranger equipment tenders as the most penetrable institutional procurement pipeline. Pursue e-commerce direct-to-consumer thermal channels in Texas and Queensland varmint control markets. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors thermal sensor specialists with uncooled microbolometer scale advantages. Long-term viability hinges on coating chemistry reformulation capabilities and direct channel control rather than retail brand equity. Watch germanium export restriction announcements as the inflection indicator for supply-side margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Reformulation | REACH Annex XVII compliance secures CE marking access across European distribution channels. |
| Direct-to-Consumer Thermal Launch | E-commerce platforms capture margin compression benefits in price-sensitive agricultural pest control segments. |
| Wildlife Guide Association Partnership | Fleet procurement relationships with Botswana and Tanzania operators displace traditional wholesale channels. |
| Uncooled Sensor Scale-Up | 640x480 microbolometer volume production fragments historical military-consumer market segmentation. |
| Algorithmic Transparency Documentation | EU AI Act compliance services open advisory revenue streams for connected optics certification. |
Research Methodology
A spread of perspectives from optical coating technicians, wildlife tourism procurement managers, precision rifle competitors, thermal sensor engineers, and specialty retail buyers converged on the working assumptions. Primary interviews combined with secondary validation against ECHA regulatory filings, FDA laser product classifications, customs trade data for germanium and rare-earth elements, and safari operator equipment tender documents. Bottom-up segment sizing triangulated against top-down manufacturer capacity assessments across the analysis window.
Segmentation dimensions modeled include product type, application, technology architecture, and end-user procurement channel across the projection horizon. CAGRs derived from shipment volume trajectories, price-point migration curves, and replacement cycle compression in ballistic-integrated hunting optics. Forecast inputs incorporated thermal imager adoption rates among Texas ranchers and Queensland agricultural operators alongside REACH compliance timeline assumptions for coating reformulation.
Material uncertainties — germanium export restrictions, ECHA coating precursor bans, and smartphone computational photography substitution — sit outside the modeled envelope. Forecasts reflect assumptions about thermal price compression velocity and wildlife tourism recovery trajectories. Recalibration cycles align with material shifts in EU regulatory implementation and uncooled sensor resolution scaling.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Fiber Optic Receiver Market
Optics
Digital Holographic Microscopy Market
Optics
Optical Lens for Mobile Phone Market
Optics
Optical Microscope Market
Optics
Fixed Focal Length Lenses Market
Optics
Optical Imaging Market
Optics
Global Nanophotonics Market
Optics
Beam Combining Optics Market
Optics
Optical Profilometer Market
Optics
MEMS Mirrors Market
Optics
Fiber Optic Switch Market
Optics
Fiber Optic Connectivity Market
Optics
Fiber-Optic Couplers Market
Optics
Anti Glare Film Market
Optics
Middle East and Africa Tunable Laser Market
Optics
Beam Expanders Market