
 Mobile Optical Pluggable Market | 2026-2036
Mobile Optical Pluggable Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Optical Pluggable Market Analytics
Aftermarket service revenue for legacy copper interconnects is narrowing as operators migrate to optical pluggable infrastructure. Lumentum Holdings Inc. leverages vertical integration across laser chip fabrication and module assembly. Coherent Corp anchors its position through R&D intensity in coherent DSP and silicon photonics. Nokia Corp dominates European telecom supply chains with Open RAN-compliant optical transceivers.
Mobile optical pluggables are hot-swappable transceiver modules that convert electrical signals to optical wavelengths for wireless backhaul and fronthaul networks, typically operating at data rates from 1 Gbps to 400 Gbps with power consumption thresholds under 15 watts per module. Their primary purpose is enabling high-capacity, low-latency connectivity between cell towers and core networks. QSFP and QSFP+ form factors command the dominant share of new deployments due to density advantages in 5G macro sites. Single-mode fiber technology leads long-haul mobile backhaul applications where reach exceeds 10 kilometers. Data center operators represent the fastest-growing end user segment as edge computing facilities proliferate alongside radio access networks.
The FCC enforces equipment authorization standards under Title 47 that constrain electromagnetic interference profiles for optical pluggables deployed in US cellular infrastructure. ETSI in Europe and METI in Japan coordinate parallel certification frameworks for wavelength stability and thermal operating ranges. REACH compliance from ECHA governs substance restrictions in module housings and solder materials across EU member states. Stakeholders must monitor divergence between national spectrum auction timelines and optical interface standardization cycles.
Market Dynamics
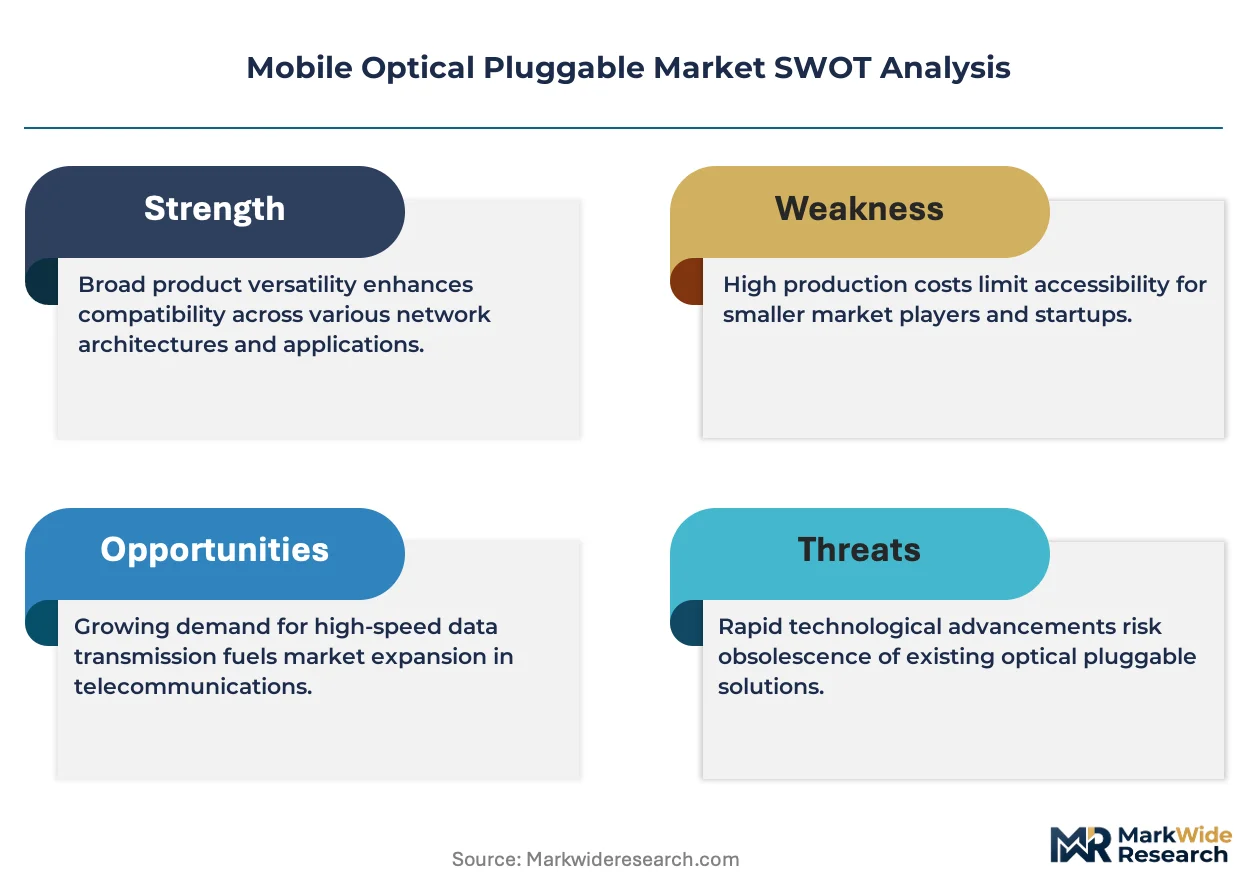
Telecom infrastructure operators are consolidating optical pluggable procurement around Open RAN interoperability standards, forcing module vendors to redesign firmware and thermal architectures for multi-vendor radio access network compatibility.
Growth Catalysts
- 5G spectrum auctions:Germany's Federal Network Agency and Japan's Ministry of Internal Affairs released mid-band frequencies that mandate optical fronthaul upgrades. Cell site densification accelerates QSFP-DD module deployment.
- Silicon photonics integration:Co-packaged optical engines reduce power consumption per bit below 4 pJ. Hyperscale edge facilities adopt these modules for distributed radio units.
- REACH substance mandates:ECHA restrictions on lead and cadmium in solder materials push module vendors toward gold-tin alloy alternatives. Compliance creates upgrade cycles across European mobile networks.
Market Restraints
- Indium phosphide substrate concentration:Laser chip fabrication depends on three dominant epitaxial wafer suppliers in Japan and the United States. Supply disruptions propagate through module assembly lead times.
- Coherent DSP thermal ceilings:400G ZR modules exceed 15W power thresholds in ambient temperatures above 70°C. Macro site enclosures require active cooling retrofits.
- Copper direct-attach cable substitution:Short-reach data center interconnects below 3 meters deploy passive copper for cost containment. Optical module penetration stalls in these edge computing clusters.
Strategic Opportunities
- India telecom modernization:TRAI mandates fiber-to-the-tower backhaul for all new spectrum licenses. Domestic module assembly partnerships with tower infrastructure firms unlock volume contracts.
- Linear drive pluggable optics:Elimination of retimer chips reduces module cost and latency. This architecture converges with LPO and CPO roadmaps for next-generation radio units.
- Smart city densification:Municipal small cell deployments in Seoul and Singapore create demand for industrial-temperature SFP28 modules. Street furniture integration requires extended thermal range certification.
Industry Challenges
- Multi-vendor interoperability certification:Open RAN fronthaul splits demand precise timing synchronization between radio units and distributed units. O-RAN Alliance test specifications create 6-9 month qualification timelines.
- Packaging engineer scarcity:Co-packaged optical design requires expertise in both III-V semiconductor bonding and high-speed electrical routing. Foundries compete for limited talent pools in Taiwan and the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Optical Pluggable Market |
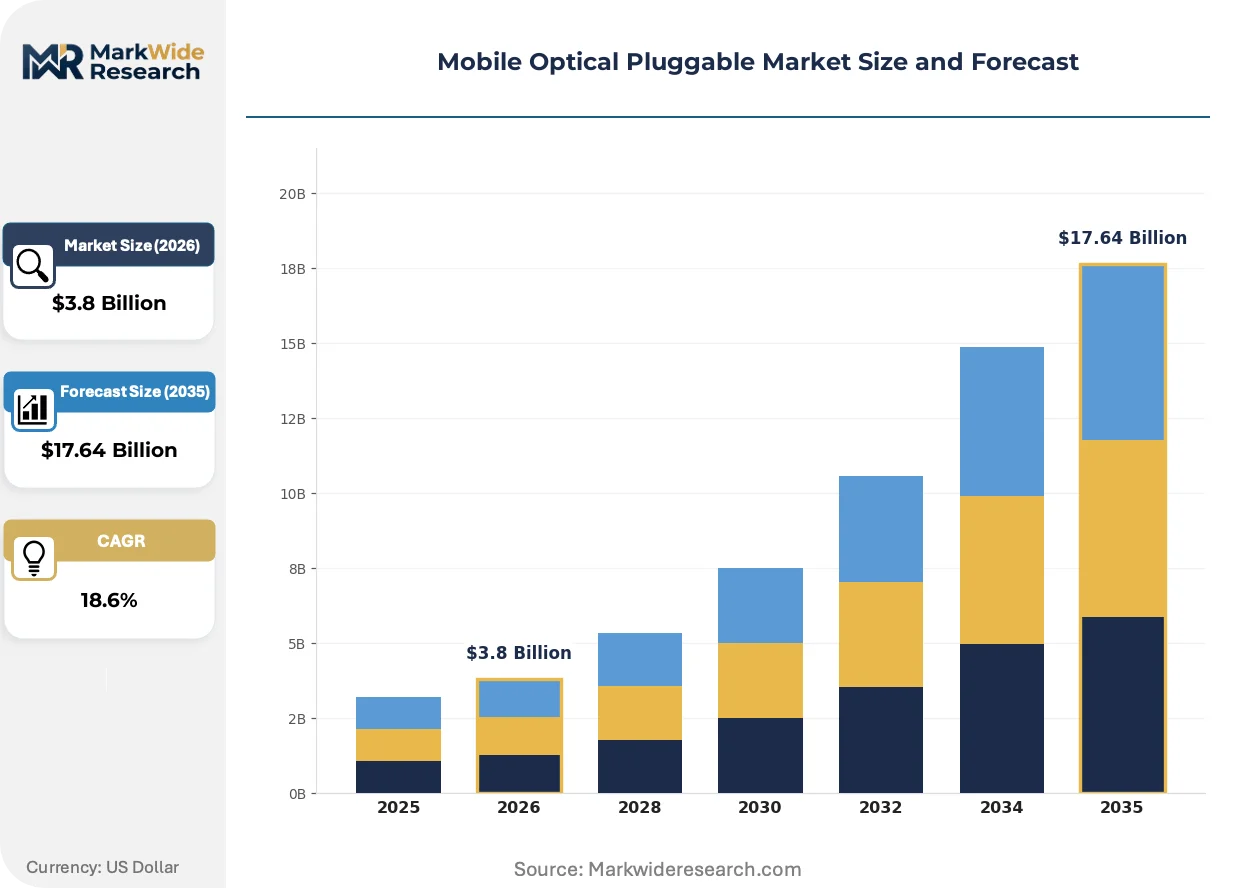
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SFP, SFP+, QSFP, QSFP+ Technology: Single-Mode Fiber, Multi-Mode Fiber, Active Optical Cable, Large-Diameter Fiber End User: Telecommunication Providers, Data Center Operators, Enterprises, Research Institutions Sales Channel: Direct Sales, Distributors, Online Retailers, Resellers |
| Companies Covered | Lumentum Holdings Inc., Coherent Corp, Nokia Corp, Sumitomo Electric Industries, Ltd., Ericsson, Cisco Systems Inc, Broadcom Inc., Infinera Corp, NeoPhotonics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Optical Pluggable Market Evolving Landscape
Module architectures are fragmenting across three competing technical directions: power-optimized linear optics, coherent DSP integration for extended reach, and co-packaged engines for switch-ASIC proximity. These trajectories reflect divergent operator priorities across fronthaul, midhaul, and backhaul network segments.
Silicon photonics with thin-film lithium niobate modulators is hybridizing electrical-to-optical conversion efficiency for 800G generation modules. Korean telecom operators are piloting these devices in 5G-Advanced trial networks. The technology is hybridizing traditional discrete component supply chains into monolithic fabrication flows, compressing vendor margins on assembly-only module houses.
FCC equipment authorization under Title 47 Part 15 tightened electromagnetic emission limits for outdoor cellular infrastructure in 2023. Module vendors now embed ferrite shielding and conformal coating in QSFP-DD housings. North American macro site deployments absorb these compliance costs through extended procurement contracts with infrastructure integrators.
Consolidated procurement through tower companies is displacing direct OEM relationships for smaller mobile network operators. Crown Castle and American Tower now specify optical module performance tiers in master service agreements. This concentration is most visible in United States rural coverage builds where capital efficiency dictates pooled equipment purchasing.
Mobile Optical Pluggable Market Segmentation
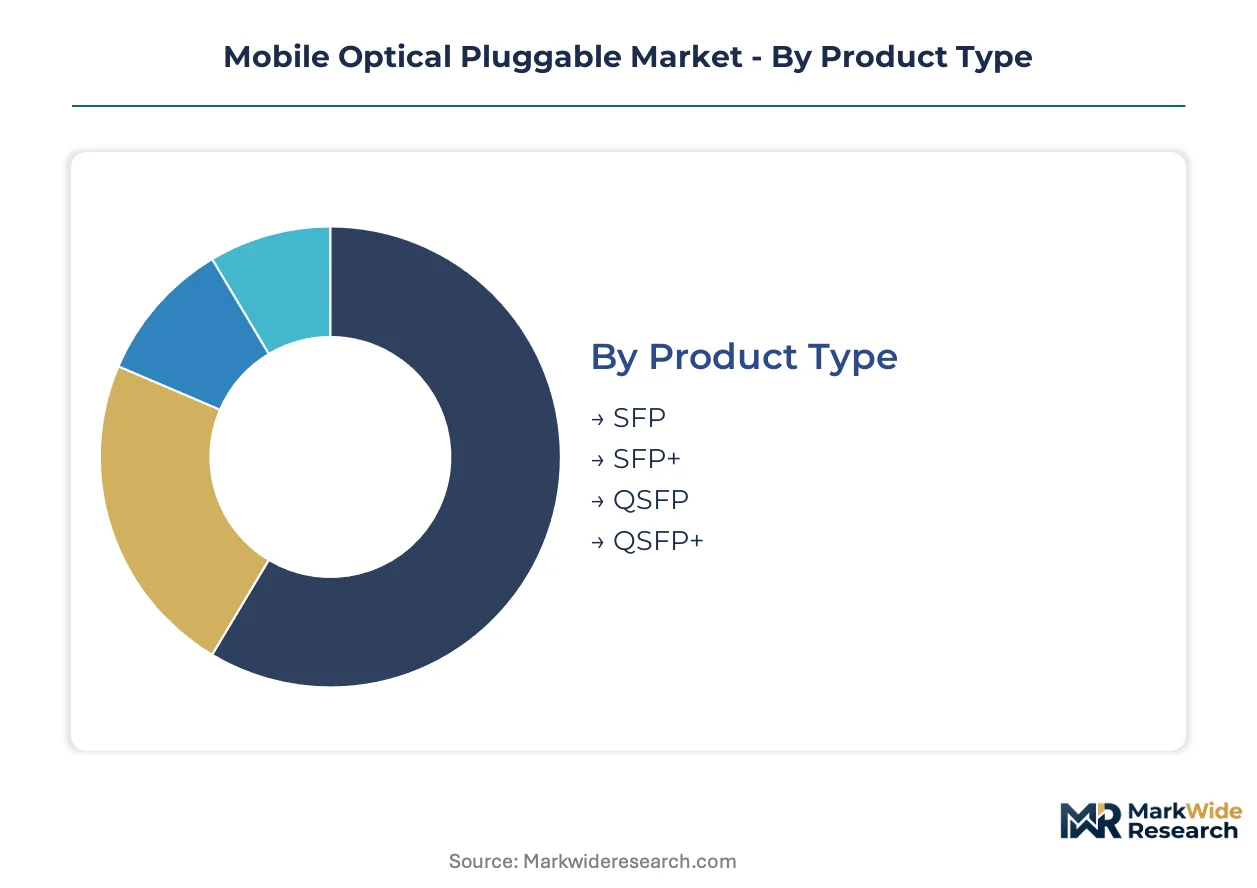
Mobile optical pluggable segmentation reveals how form factor density, fiber physics, and procurement channel economics partition addressable demand across telecom infrastructure buildouts. Distinct technical requirements for fronthaul versus backhaul distances create non-overlapping segment boundaries that vendors must navigate simultaneously.
Product Type:
Mature QSFP variants dominate 5G macro site deployments while legacy SFP formats persist in enterprise edge retrofits.
- QSFP:Quad-lane electrical interface supporting 40G aggregation in compact 18mm width. South Korean telecom operators specify QSFP28 for 5G-Advanced trial networks where port density constraints dominate rack space planning.
- QSFP+:Enhanced thermal architecture accommodating 100G PAM4 signaling with integrated DSP. German Federal Network Agency mid-band auction winners deploy QSFP-DD variants for 400G fronthaul splits in dense urban macro clusters.
- SFP+:10G single-lane format retaining relevance in rural coverage builds where capital efficiency outweighs bandwidth scaling.
- SFP:Legacy 1G module sustaining aftermarket replacement cycles in industrial temperature street furniture installations.
QSFP retains volume leadership; QSFP+ holds the steepest expansion curve.
Technology:
Cost tier separation between single-mode reach extension and multi-mode short-haul economics drives procurement bifurcation.
- Single-Mode Fiber:Dispersion-shifted glass enabling 10km+ transmission without signal regeneration. United States rural coverage builds source single-mode pluggables for tower-to-core backhaul where fiber count scarcity elevates per-strand capacity requirements.
- Multi-Mode Fiber:50-micron core diameter optimized for 550-meter reach in data center environments. Japanese hyperscale edge facilities in Osaka and Tokyo deploy OM4 multi-mode for distributed radio unit clustering under 300 meters.
- Active Optical Cable:Pre-terminated fiber-ASIC assembly eliminating field splicing labor in rapid deployment scenarios.
- Large-Diameter Fiber:Specialty 100-micron core for high-power handling in test and measurement applications.
Single-mode fiber commands premium pricing tiers; active optical cables are gaining share fastest in time-constrained deployment windows.
End User:
Customer type concentration reflects divergent procurement sophistication between carrier-grade specification and enterprise volume purchasing.
- Telecommunication Providers:Tier-1 mobile network operators with Open RAN interoperability mandates and multi-year master service agreements. Crown Castle and American Tower specify optical module performance tiers in pooled equipment purchasing for United States rural builds.
- Data Center Operators:Hyperscale edge facility builders where co-packaged optical engines reduce power consumption per bit below 4 pJ. Seoul municipal smart city deployments create demand for industrial-temperature SFP28 modules in street furniture integration.
- Enterprises:Private 5G network adopters with shorter qualification cycles and lower volume procurement.
- Research Institutions:Experimental wavelength division multiplexing testbeds requiring custom form factors.
Telecommunication providers retain volume leadership; data center operators hold the steepest expansion curve.
Sales Channel:
Supply concentration in tower company procurement is displacing traditional distributor relationships for optical pluggable sourcing.
- Direct Sales:Long-term framework agreements between module vendors and infrastructure integrators. FCC Title 47 Part 15 compliance costs for electromagnetic emission limits embed through extended procurement contracts in North American macro site deployments.
- Distributors:Inventory buffering for mid-size mobile network operators without consolidated purchasing power.
- Online Retailers:Spot procurement for emergency replacement and legacy format sourcing.
- Resellers:Value-added configuration services for enterprise private network deployments.
Direct sales retains volume leadership; distributor relationships hold the steepest expansion curve in emerging market infrastructure builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indium phosphide epitaxial wafer fabrication clusters in Japan and the United States create chokepoints that propagate through module assembly lead times worldwide. Tower company procurement consolidation in North America and spectrum auction timing in Europe and Asia shape regional deployment velocity. Regulatory divergence between FCC Title 47, ETSI frameworks, and METI certification cycles fragments qualification timelines across major markets.
United States
Crown Castle and American Tower specify optical module performance tiers in master service agreements for rural coverage builds. FCC Title 47 Part 15 tightened electromagnetic emission limits for outdoor cellular infrastructure in 2023, embedding compliance costs through extended procurement contracts. Macro site deployments in the Southeast and Mountain West absorb these costs through infrastructure integrator relationships.
Germany
Federal Network Agency mid-band auction winners deploy QSFP-DD variants for 400G fronthaul splits in dense urban macro clusters. ETSI coordinates certification frameworks for wavelength stability and thermal operating ranges across EU member states. Industrial clusters in Bavaria and North Rhine-Westphalia host Open RAN interoperability testing facilities for multi-vendor radio access networks.
Japan
METI released mid-band frequencies that mandate optical fronthaul upgrades alongside cell site densification. Ministry of Internal Affairs spectrum allocations accelerate QSFP-DD module deployment for 5G-Advanced networks. Hyperscale edge facilities in Osaka and Tokyo deploy OM4 multi-mode fiber for distributed radio unit clustering under 300 meters.
South Korea
Telecom operators specify QSFP28 for 5G-Advanced trial networks where port density constraints dominate rack space planning. National spectrum regulators coordinate with ETSI-aligned frameworks for wavelength stability certification. Seoul municipal smart city deployments create demand for industrial-temperature SFP28 modules in street furniture integration scenarios.
India
TRAI mandates fiber-to-the-tower backhaul for all new spectrum licenses, unlocking volume contracts through domestic module assembly partnerships. Central Electricity Authority thermal standards intersect with telecom infrastructure requirements for macro site enclosures. Tower infrastructure firms in Maharashtra and Karnataka consolidate procurement around Open RAN interoperability specifications.
Mobile Optical Pluggable Market Competitive Landscape
Vertically integrated laser chip fabricators and module assembly specialists split the market between captive supply control and outsourced component sourcing. The vendor base concentrates around three strategic archetypes: III-V semiconductor foundries with epitaxial wafer capabilities, silicon photonics integrators with DSP co-design competencies, and infrastructure OEMs with Open RAN certification pipelines. Dominant competitive moves include backward integration into laser chip fabrication and strategic partnerships with tower companies for pooled equipment purchasing.
Within the vertically integrated tier, Lumentum Holdings Inc. and Coherent Corp occupy positions spanning laser chip fabrication through module assembly. Nokia Corp exemplifies the infrastructure OEM archetype with European telecom supply chain anchoring. These three entities represent distinct strategic postures: upstream control over indium phosphide substrates, R&D intensity in coherent DSP and silicon photonics, and Open RAN-compliant optical transceiver dominance in regional procurement frameworks.
| Leading Market Players |
|---|
| Lumentum Holdings Inc. |
| Coherent Corp |
| Nokia Corp |
| Sumitomo Electric Industries, Ltd. |
| Ericsson |
| Cisco Systems Inc |
| Broadcom Inc. |
| Infinera Corp |
| NeoPhotonics Corporation |
| Others |
Value Network & Pricing Analysis
Indium phosphide epitaxial wafer fabrication clusters in Japan and the United States concentrate laser chip supply, anchoring margin pools in module assembly and firmware integration downstream. Tower company procurement consolidation extracts volume discounts that compress assembly-only margins while rewarding captive laser fabrication.
Pricing Analysis
FCC Title 47 Part 15 dictates the pricing tier structure through electromagnetic compliance cost layering. Three-tier pricing structure across premium, standard, and economy levels separates Open RAN-certified modules from enterprise-grade and legacy copper replacement units. Cost compression in standard-tier QSFP28 modules is intensifying because silicon photonics integrators bypass discrete component markups. Data center operators exhibit highest price sensitivity; telecommunication providers absorb premium tiers for multi-vendor interoperability assurance.
Supply Chain Analysis
Export control regimes restricting III-V semiconductor manufacturing equipment limit wafer fabrication capacity expansion outside Japan and the United States. Module assembly draws from indium phosphide substrates, DSP silicon, and gold-tin solder alloys. Single-source vulnerability concentrates in epitaxial wafer suppliers. Distribution runs through tower company master service agreements displacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in co-packaged optical design expertise—spanning III-V semiconductor bonding and high-speed electrical routing—constrains vendor expansion and rewards early capability investments. Foundries in Taiwan and the United States compete for this limited talent pool.
For Market Incumbents: Build captive supply moats through backward integration into laser chip fabrication. Secure multi-year indium phosphide wafer offtake agreements to insulate against substrate concentration risk. Expand Open RAN interoperability certification pipelines to lock in tower company procurement relationships with Crown Castle and American Tower. For New Entrants and Emerging Players: Establish a beachhead in industrial-temperature SFP28 modules for smart city street furniture deployments. Target Seoul and Singapore municipal small cell tenders where extended thermal range certification creates qualification barriers. Partner with domestic tower infrastructure firms in India for TRAI-mandated fiber-to-the-tower upgrades. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed silicon photonics specialists lacking DSP co-design competencies. Five-to-ten year viability hinges on coherent DSP integration roadmaps. Watch for inflection when linear drive pluggable optics standards crystallize in O-RAN Alliance specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Packaged Optical Engine Development | Reduces power consumption per bit below 4 pJ for hyperscale edge facilities in Seoul and Tokyo. |
| Open RAN Interoperability Certification | Unlocks tower company master service agreements with Crown Castle and American Tower procurement tiers. |
| Indium Phosphide Wafer Supply Agreement | Secures substrate access against Japanese and US epitaxial supplier concentration risk. |
| Linear Drive Pluggable Optics Roadmap | Eliminates retimer chips to converge with LPO and CPO architectures for next-generation radio units. |
| Smart City Thermal Certification Program | Captures municipal small cell demand in Seoul requiring industrial-temperature SFP28 modules. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the analysis window. Primary interviews engaged optical module procurement managers at tower companies, III-V semiconductor foundry engineering directors, DSP silicon architects, and Open RAN interoperability test engineers. Secondary validation drew from FCC Title 47 equipment authorization databases, ETSI certification registries, TRAI spectrum allocation notices, and tower company master service agreement disclosures. Bottom-up module shipment aggregation triangulated against top-down telecom infrastructure capex allocation.
Calibration anchored volume and value outputs against historical deployment cycles and announced spectrum auction timelines. Segmentation dimensions modeled include form factor density, fiber physics, end-user procurement sophistication, and sales channel concentration. CAGRs derived from slope-log regression across the projection horizon. Forecast inputs incorporated silicon photonics yield curves and Open RAN standardization velocity.
Macroeconomic conditions sit as an overlay; deviation in spectrum auction timing or substrate supply availability would shift the trajectory. Forecasts reflect assumptions regarding coherent DSP thermal management progress and REACH substance mandate enforcement. Material shifts in export control regime scope or O-RAN Alliance specification finalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Quartz Glass Substrate Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
LAMEA Lithium Niobate Modulator Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
Europe Optical Imaging Market
Optical Components
VCSEL for Data Communication Market
Optical Components
RF-Over-Fiber (Rfof) Solution Market
Optical Components
Flexible Glass for Flexible Electronics Market
Optical Components
Optical Amplifier Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
Pancake Optical Module Market
Optical Components
Global Optical Imaging System Market
Optical Components
Europe Optical Film Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Japan Lithium Niobate Modulator Market