
 Global Satellite Based Earth Observation Market | 2026-2036
Global Satellite Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Satellite Based Earth Observation Market Intelligence
The scarcity of specialized geospatial data scientists is reorganizing how satellite imagery is processed and delivered to end-users. This shift places a premium on automated analytics platforms and analysis-ready data products. Planet Labs leverages its vast constellation to provide daily monitoring feeds that require less manual interpretation. Airbus SE specializes in delivering integrated geospatial solutions, while Maxar Technologies sustains its position by providing high-resolution imagery to government customers with advanced in-house analytical teams.
Satellite based earth observation is the practice of collecting information about the planet’s physical, chemical, and biological systems via remote sensing technologies aboard satellites. These systems capture data across various spectral bands, often achieving sub-meter spatial resolution for detailed analysis. The market for radar satellites is expanding for all-weather monitoring, complementing the established optical satellite segment. Among end users, applications in disaster management and climate change analysis are seeing rapid uptake, particularly for government and insurance sector clients.
Market operations are governed by a complex web of national and international regulations. In the United States, the FAA and FCC control launch and spectrum licensing, while in Europe, the EU Green Deal drives demand for environmental data. Data sovereignty laws in countries like India and China add another layer of operational complexity for providers. The critical strategic choice for satellite operators now centers on balancing investment between on-board data processing and ground-based analytical infrastructure.
Market Dynamics
The central dynamic in the satellite earth observation market is the strategic tension between on-board processing capabilities and ground-based analytical infrastructure. This balance dictates capital investment priorities, data product architecture, and the competitive positioning of satellite operators.
Growth Catalysts
- Precision Agriculture:The expansion of data-driven farming techniques creates significant new demand for satellite imagery to monitor crop health, soil moisture, and yield, optimizing resource use and improving agricultural productivity.
- Environmental Mandates:Regulatory frameworks like the EU Green Deal necessitate comprehensive environmental monitoring, driving government and corporate demand for satellite data to track emissions, land use change, and biodiversity.
- Radar Satellite Expansion:Advances in Synthetic Aperture Radar (SAR) technology provide all-weather, day-and-night imaging capabilities, complementing optical satellites and opening new applications in maritime surveillance and disaster management.
Market Restraints
- High Capital Intensity:The substantial upfront investment required for satellite design, manufacturing, launch, and ground station infrastructure presents a significant barrier to entry and constrains the scalability of smaller operators.
- Data Sovereignty Regulations:National policies in countries such as India and China impose strict controls on the collection, storage, and dissemination of geospatial data, adding operational complexity and compliance costs for providers.
- Atmospheric Limitations:Optical satellite imagery remains susceptible to cloud cover and other atmospheric interference, which can limit data acquisition consistency and reliability for time-sensitive monitoring applications.
Strategic Opportunities
- Insurance Sector Integration:Developing specialized data products for the insurance industry offers a major growth avenue, particularly for pre-event risk modeling and post-disaster damage assessment to accelerate claims processing.
- Sensor Fusion Analytics:Combining satellite imagery with data from terrestrial IoT devices and drone-based sensors enables the creation of higher-value, multi-layered analytical products for smart city and infrastructure management.
- Climate Risk Services:There is a distinct opportunity to develop subscription-based platforms that provide financial institutions and corporations with data to assess physical climate risks to assets, supply chains, and operations.
Industry Challenges
- Geospatial Talent Scarcity:A persistent shortage of data scientists with specialized expertise in processing and interpreting satellite remote sensing data constrains the ability of end-users to extract full value from raw imagery.
- Data Interoperability:Integrating data from multiple satellite constellations with varying resolutions, spectral bands, and formats into a single, cohesive analytical workflow remains a significant technical hurdle for users.
- Spectrum Licensing Complexity:Securing and maintaining frequency spectrum licenses from national regulators like the United States' FCC is a protracted and competitive process, creating potential delays for new satellite deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Satellite Based Earth Observation Market |
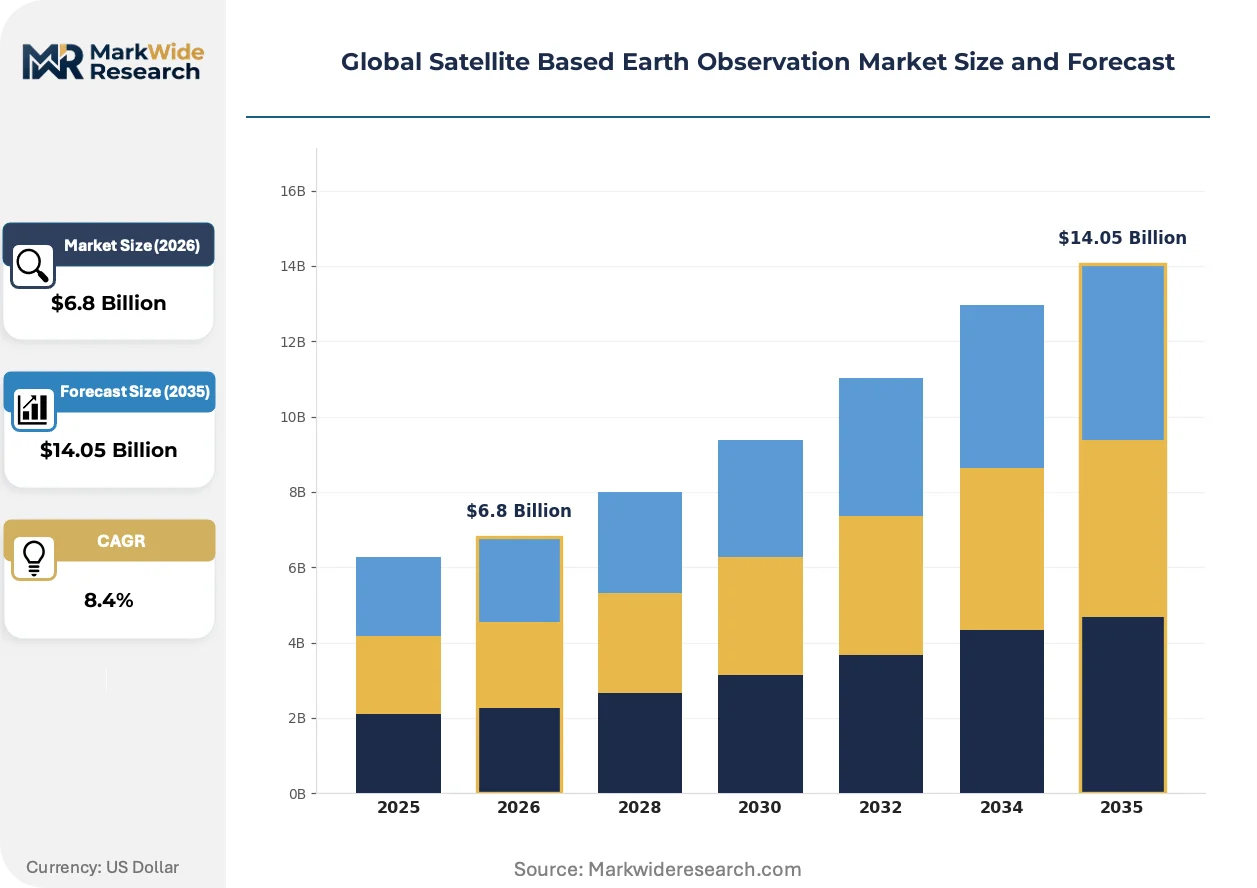
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Satellites, Radar Satellites, Multispectral Satellites, Hyperspectral Satellites End User: Agriculture, Forestry, Urban Planning, Environmental Monitoring Technology: Satellite Imaging, Remote Sensing, Data Processing, Geospatial Analysis Application: Disaster Management, Climate Change Analysis, Resource Management, Maritime Surveillance |
| Companies Covered | Northrop Grumman, Planet Labs, Maxar Technologies, Thales Group, ICEYE, Airbus SE, L3Harris Technologies, Capella Space, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Satellite Based Earth Observation Market Strategic Shifts & Innovations
Automation in data processing and the delivery of analysis-ready products are reshaping the market. This evolution lowers the technical barrier for end-users, shifting the value proposition from raw pixel delivery to providing actionable insights through integrated platforms.
On-board processing, which integrates AI and machine learning algorithms directly onto satellites, is a key technological shift. Government and defense customers are the primary adopters for rapid, in-theater intelligence and surveillance applications. This development is displacing the reliance on large-scale, time-consuming ground-based processing for initial data filtering and event detection.
Regulatory frameworks promoting open data access, such as the European Union's Copernicus program, are altering the competitive environment. This policy encourages innovation by providing free access to high-quality satellite data from the Sentinel constellation for developers and researchers. Consequently, commercial providers most affected are pivoting to offer specialized analytics and value-added services rather than competing on raw data sales.
A clear behavioral shift among customers is the move from transactional, per-image purchasing to subscription-based Data-as-a-Service (DaaS) models. This change disrupts traditional sales channels by favoring providers who can deliver continuous, updated data feeds through scalable cloud platforms. This trend is most prominent in the agriculture and climate analysis sectors, where ongoing monitoring is essential for operational decision-making.
Global Satellite Based Earth Observation Market Segmentation
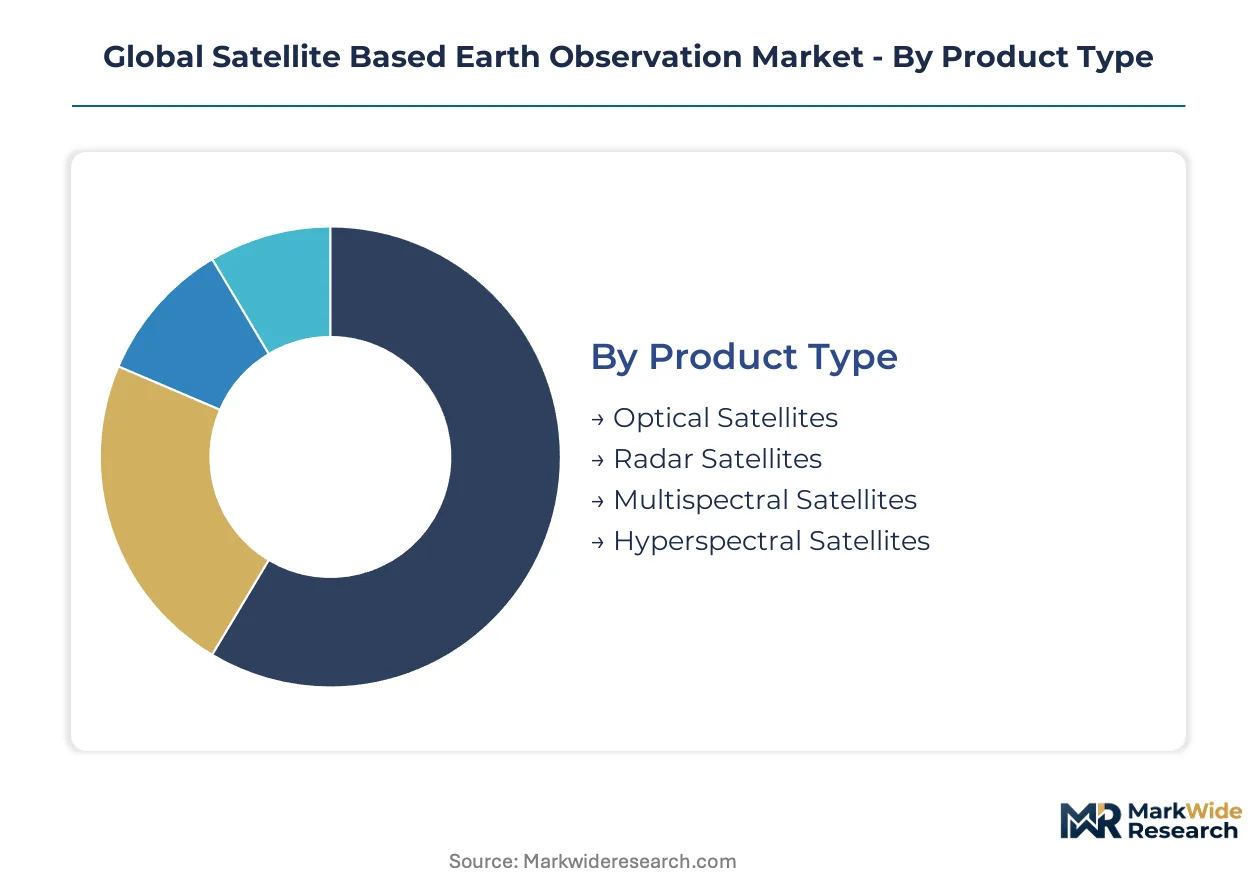
The Global Satellite Based Earth Observation Market segments illustrate the diverse applications and technological underpinnings driving industry expansion. Understanding these distinctions helps stakeholders identify areas of concentrated demand, specialized technological capabilities, and evolving end-user requirements across various sectors.
Product Type:
Regulatory frameworks often distinguish between satellite product types based on data collection capabilities and resolution requirements, influencing licensing and operational parameters for providers.
- Optical Satellites:These systems capture imagery using visible and infrared light, providing high-resolution visual data for detailed surface analysis. Demand concentrates in urban planning and agricultural monitoring, driven by the need for precise land use and crop health assessments.
- Radar Satellites:Utilizing radio waves, radar satellites penetrate cloud cover and operate independently of sunlight, offering all-weather, day-and-night imaging capabilities. Demand is strong in disaster management and maritime surveillance, where continuous monitoring is critical regardless of atmospheric conditions.
- Multispectral Satellites:These satellites collect data across a few specific, broad spectral bands, enabling analysis of vegetation health and geological features.
- Hyperspectral Satellites:Capturing data across hundreds of narrow, contiguous spectral bands, hyperspectral systems allow for highly detailed material identification and environmental monitoring.
Optical Satellites handle the majority of throughput; Radar Satellites are the fastest mover on share.
End User:
End-user segments define specific operational requirements and data product customization needs, reflecting varied priorities for satellite-derived information.
- Agriculture:This sector uses satellite data for precision farming, including crop health monitoring, soil moisture assessment, and yield prediction to optimize resource allocation. Demand is concentrating in countries with large agricultural economies like the United States and India, driven by efficiency and sustainability mandates.
- Environmental Monitoring:Applications include tracking deforestation, glacier melt, air quality, and ocean health to support climate change analysis and regulatory compliance. Demand is significant in Europe, spurred by the EU Green Deal's comprehensive environmental reporting requirements.
- Forestry:Satellite imagery provides essential data for timber inventory, wildfire detection, and sustainable forest management practices.
- Urban Planning:Data supports city expansion analysis, infrastructure development, and land use mapping for efficient municipal management.
Environmental Monitoring applications drive substantial data consumption, while Agriculture shows the steepest expansion trajectory.
Technology:
Technological advancements underpin the capabilities and analytical depth offered by earth observation systems, dictating the quality and accessibility of derived insights.
- Data Processing:This involves the algorithms and infrastructure used to transform raw satellite signals into usable, analysis-ready data products. Demand for advanced data processing is concentrating among commercial analytics platforms, driven by the scarcity of specialized geospatial data scientists.
- Remote Sensing:This technology encompasses the methods and instruments on satellites that detect and measure energy reflected or emitted from the Earth's surface. Demand is high for advanced sensor fusion techniques, particularly for integrating satellite data with ground-based IoT networks.
- Satellite Imaging:This refers to the capture of visual and spectral information from space, forming the foundational input for all earth observation applications.
- Geospatial Analysis:This involves the interpretation and manipulation of geographically referenced data to identify patterns, trends, and relationships.
Data Processing optimizes raw satellite feeds; Remote Sensing methodologies are gaining share fastest.
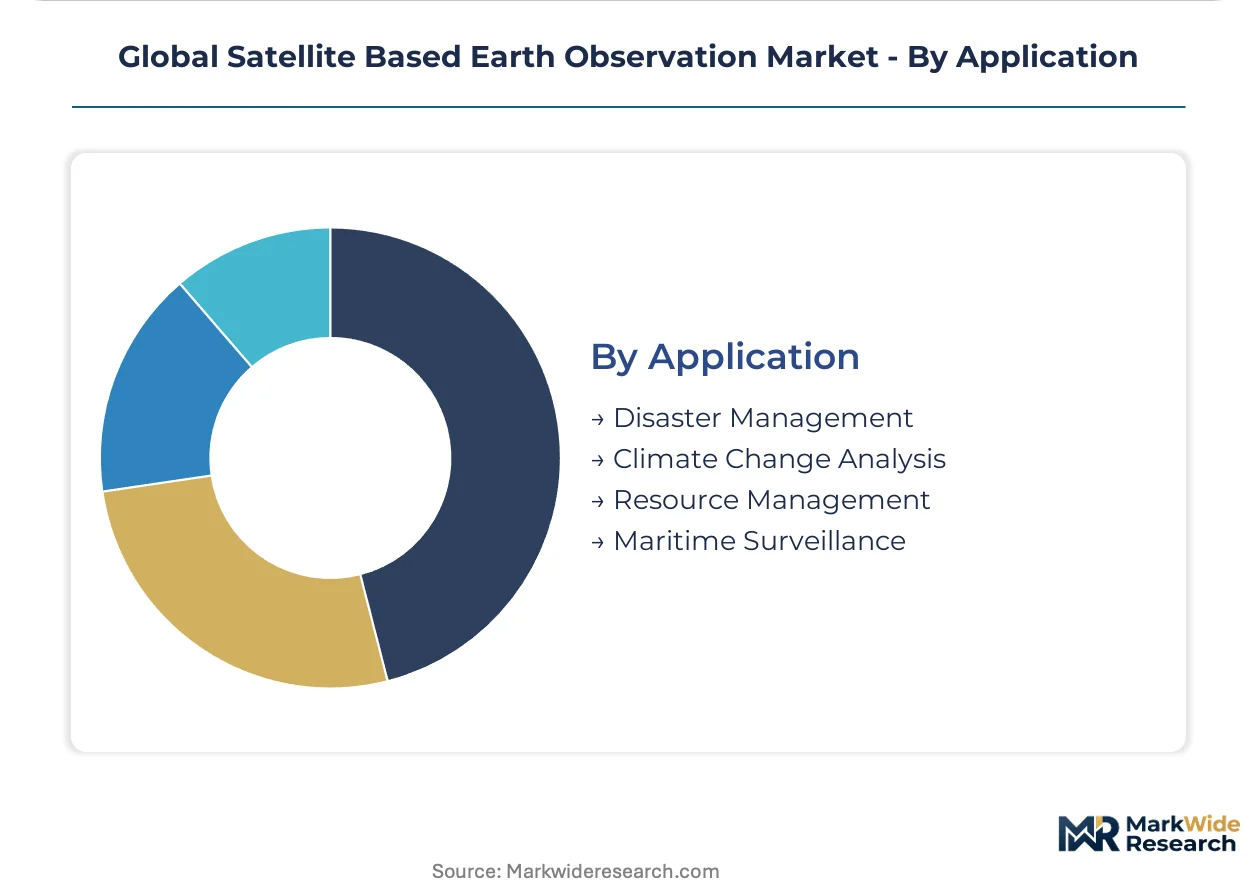
Application:
Application areas delineate the practical utility and value creation from satellite-derived insights, addressing specific challenges across industries and governmental functions.
- Disaster Management:Satellite data provides critical information for pre-event risk assessment, real-time disaster monitoring, and post-event damage assessment. Demand is concentrating in the insurance sector and government agencies, driven by the need for rapid response and claims processing.
- Climate Change Analysis:This application involves monitoring long-term environmental shifts, such as sea-level rise, ice-cap melting, and greenhouse gas emissions, to inform policy and scientific research. Demand is high among research institutions and international bodies, driven by global environmental mandates.
- Resource Management:This segment includes monitoring water resources, mineral exploration, and land use planning to ensure sustainable utilization of natural assets.
- Maritime Surveillance:Satellite systems track vessel movements, detect illegal fishing, and monitor ocean conditions for security and environmental protection.
Disaster Management generates critical, time-sensitive requirements; Climate Change Analysis is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA, controlling launch and spectrum licensing in the United States, anchors significant demand for satellite-based earth observation. This market sees diverse regulatory landscapes influencing operational parameters and data consumption across various global regions. National policies and environmental mandates significantly shape regional market dynamics and investment priorities.
United States
Demand in the United States concentrates on climate change analysis and precision agriculture applications. The FAA and FCC regulate launch and spectrum licensing, creating specific compliance requirements for operators. Silicon Valley and other tech hubs in California drive innovation in data processing and analytics platforms for earth observation.
Germany
Germany exhibits strong demand for environmental monitoring and urban planning solutions, aligning with national sustainability goals. The EU Green Deal mandates comprehensive environmental reporting, increasing the need for satellite data throughout Europe. The Bavarian aerospace cluster, particularly around Munich, fosters advanced sensor development and integrated geospatial solutions.
India
India's market expansion is driven by precision agriculture requirements and disaster management needs, especially across its vast agricultural lands. Data sovereignty laws in India impose strict controls on geospatial data, impacting foreign providers. Bengaluru's burgeoning tech sector supports indigenous satellite data processing and application development.
China
China's demand centers on resource management, environmental monitoring, and infrastructure development, supporting its rapid economic growth. National data sovereignty laws and dual carbon goals influence how satellite data is collected and utilized domestically. Beijing's state-backed enterprises lead significant investments in satellite constellations and ground infrastructure.
France
France shows robust demand for defense and security applications, alongside environmental monitoring initiatives. European regulations like the EU Green Deal drive the adoption of satellite data for tracking land use change. Toulouse, a major European aerospace hub, hosts key players in satellite manufacturing and data analytics.
Global Satellite Based Earth Observation Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the satellite earth observation market. The market exhibits a tiered structure, encompassing established aerospace giants and agile data analytics specialists. Strategic archetypes include integrated solution providers, high-resolution imagery specialists, and automated data platform operators. Companies primarily engage in capacity expansion through new satellite constellations and forge strategic partnerships to broaden their service portfolios and reach new end-user segments.
Specialists focusing on continuous monitoring and analysis-ready data include Planet Labs, which exemplifies the trend towards automated daily feeds and simplified user access. Airbus SE occupies a position as an integrated geospatial solutions provider, offering comprehensive platforms that combine imagery with analytical tools for complex applications. Maxar Technologies anchors the high-resolution imagery segment, primarily serving government customers who require advanced analytical capabilities and bespoke data products for critical national security and intelligence operations.
| Leading Market Players |
|---|
| Northrop Grumman |
| Planet Labs |
| Maxar Technologies |
| Thales Group |
| ICEYE |
| Airbus SE |
| L3Harris Technologies |
| Capella Space |
| Lockheed Martin |
Cost & Logistics Intelligence
Subscription-based Data-as-a-Service models lock in both continuous data supply and predictable revenue streams for satellite operators. These long-term agreements provide essential price visibility for both providers and end-users.
Pricing Analysis
Geographic price spreads emerge from varying data sovereignty compliance costs and regional demand for specialized analytics. Subscription-based Data-as-a-Service (DaaS) models dominate, offering continuous data feeds tailored to specific user needs, with differentiation based on imagery resolution, processing level, and application customization. Pricing pressure intensifies due to open data initiatives like Europe's Copernicus program, pushing commercial providers towards value-added services. Government and insurance clients exhibit lower price sensitivity for critical, time-sensitive data, while researchers and developers are more price-conscious.
Supply Chain Analysis
The United States and Europe anchor satellite manufacturing and advanced sensor development for earth observation. Key raw material dependencies include specialized optical and radar sensors, high-performance computing units for on-board processing, and reliable launch services. A significant supply chain risk is the complexity of spectrum licensing from regulators like the FAA and FCC, which can delay deployments. Distribution runs through direct contracts with government agencies and large enterprises, increasingly via cloud-based platforms for Data-as-a-Service models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The satellite earth observation market is at a platform-economics inflection, driven by the shift towards automated analytics platforms and analysis-ready data products. This evolution creates new interoperability requirements for diverse data sources.
For Market Incumbents: Shield core revenue streams by accelerating investment in automated analytics and on-board AI processing to counter the threat of open data initiatives and agile specialized analytics providers. Expand radar satellite constellations to offer all-weather monitoring, providing a critical differentiation lever against optical-only competitors. Forge strategic partnerships to integrate diverse data sources, moving beyond raw imagery to deliver comprehensive geospatial solutions.
For New Entrants and Emerging Players: Expedited regulatory approvals for specialized data products, particularly those aiding compliance with environmental mandates like the EU Green Deal, offer a certification fast-track. Target the underpenetrated insurance sector with tailored pre-event risk modeling and post-disaster damage assessment platforms. Focus on subscription-based Data-as-a-Service models for climate risk analytics, providing continuous monitoring for financial institutions and corporations. Develop sensor fusion analytics for smart city management, integrating satellite data with terrestrial IoT for higher-value insights.
For Investors and Strategic Acquirers: Capital is best deployed toward automated analytics platforms and specialized radar satellite operators over the long-term, given the market's shift from raw data to actionable insights. Target firms with robust AI/ML capabilities for on-board processing or those providing sensor fusion analytics. These investments capitalize on the persistent geospatial talent scarcity and the growing demand for analysis-ready products. The signal to watch is the widespread integration of satellite data into enterprise resource planning systems across diverse industries.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Radar Satellite Constellations | Provides all-weather, day-and-night monitoring capabilities, critical for disaster management and maritime surveillance applications. |
| Develop Automated Analytics Platforms | Addresses geospatial talent scarcity by delivering analysis-ready data products, simplifying end-user access to satellite insights. |
| Invest in On-board AI Processing | Enables rapid, in-theater intelligence for government customers, reducing reliance on time-consuming ground-based infrastructure. |
| Form Sensor Fusion Partnerships | Combines satellite imagery with IoT data, creating higher-value analytical products for smart city and infrastructure management. |
| Offer Subscription-based DaaS Models | Disrupts traditional sales channels by providing continuous, updated data feeds, essential for precision agriculture and climate analysis. |
Research Approach
Desk research of regulatory filings, aerospace industry reports, and scientific journals preceded structured interviews with satellite operators, geospatial data scientists, and end-user specialists in precision agriculture and disaster management. Primary interviews provided qualitative insights into market dynamics and technological advancements. This approach combined bottom-up market sizing with top-down validation, ensuring comprehensive data triangulation.
Variance decomposition across the analysis window informed market projections, integrating historical trends with anticipated technological advancements. Segmentation dimensions modeled included Product Type, End User, Technology, Application, and distinct regional adoption patterns. Compound Annual Growth Rates (CAGRs) were derived from projected demand, satellite launch schedules, and evolving regulatory policy changes like the EU Green Deal mandates.
Decision-makers should treat outputs as directional under base assumptions regarding regulatory stability and technological progression; material deviation would warrant model refresh. Forecasts reflect assumptions concerning geopolitical stability affecting launch access and the evolution of data sovereignty laws. Recalibration cycles align with material shifts in these key drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global Satellite Propulsion System Market
Satellite
South Korea Satellite Connectivity Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
High Altitude Pseudo Satellites Market
Satellite
France Satellite Connectivity Market
Satellite
Europe Military Satellite Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
Satellite GPS Receivers Market
Satellite
Canada Satellite Connectivity Market
Satellite
Satellite Communication Equipment Market
Satellite
United Arab Emirates Satellite-Based Earth Observation Market
Satellite
India Satellite Communication Market
Satellite
US Satellite-Based Earth Observation Market
Satellite
Europe Satellite Launch Vehicle Market
Satellite
Germany Satellite Imagery Services Market
Satellite
Satellite Data Service Market