
 Germany Satellite Imagery Services Market | 2026-2036
Germany Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Satellite Imagery Services Market Insights
Modular tasking packages is broadening buyer choice across German government and enterprise accounts. Airbus Defence and Space leverages its dual-use constellation heritage to anchor defense and civilian contracts alike. Planet Labs sustains daily coverage cadence that competes with legacy providers on refresh frequency. GAF AG specializes in geospatial analytics layers that differentiate raw imagery with application-ready outputs for federal mapping agencies.
Germany satellite imagery services encompass the acquisition, processing, and distribution of Earth observation data captured by orbiting sensors, with spatial resolutions ranging from sub-meter panchromatic to 30-meter multispectral swaths, supporting decision-making in agriculture, security, and environmental compliance. Optical imagery dominates current federal procurement volumes due to mature interpretation workflows and established spectral libraries for Central European land cover. Radar imagery is gaining share among infrastructure insurers and flood-response agencies because all-weather penetration solves persistent cloud-cover limitations across alpine and northern coastal zones. Cloud-based delivery models are displacing physical media handoffs as the Bundesamt für Kartographie and state-level geodetic authorities modernize portal access for interagency data sharing.
KBA and BSI shape product standards for automotive and critical infrastructure applications requiring certified geospatial accuracy, while the EU Space Programme and national space legislation govern orbital data licensing and cross-border dissemination rights. Germany's implementation of the EU AI Act through BSI guidance will filter into automated feature-extraction contracts, mandating transparency in machine-generated classification outputs. Stakeholders must track how federal procurement rules under the Act Against Restraints of Competition interact with emerging sovereignty requirements for sensitive geospatial data.
Market Dynamics
Dual-use constellation architectures are collapsing the traditional separation between defense and civilian procurement channels in Germany, forcing vendors to recalibrate licensing workflows and data-handling protocols for a single integrated buyer base.
Growth Catalysts
- EU Space Programme acceleration:The EU Space Programme is consolidating procurement frameworks across member states, enabling German federal agencies to access shared orbital assets without bilateral negotiation overhead.
- Border surveillance modernization:German defense agencies are mandating sub-meter refresh rates for perimeter monitoring, pulling high-resolution tasking capacity into long-term service contracts.
- Cloud-native delivery infrastructure:State-level geodetic authorities in Bavaria and Baden-Württemberg are retiring physical media workflows, expanding addressable market for API-first imagery providers.
Market Restraints
- Launch capacity concentration:European orbital insertion relies on a narrow supplier base concentrated in French Guiana and emerging German launch sites, creating scheduling bottlenecks for constellation replenishment.
- Spectral interpretation labor scarcity:Trained photogrammetrists capable of validating machine-generated feature extraction remain concentrated in federal research installations, constraining analytic service scaling.
- Cross-border licensing friction:Germany's national space legislation imposes territorial restrictions on raw data resale that conflict with EU-wide service ambitions, fragmenting vendor operating models.
Strategic Opportunities
- AI Act compliance services:The EU AI Act is mandating transparency documentation for automated classification outputs, creating a new advisory layer for imagery analytics vendors serving BSI-regulated critical infrastructure operators.
- Alpine corridor infrastructure monitoring:Bavarian transport authorities are expanding radar-based slope stability contracts, opening recurring revenue streams unaffected by seasonal cloud cover.
- Interstate data-sharing portals:The Bundesamt für Kartographie is piloting federated access architectures that would let municipal planners subscribe to federal orbital holdings without direct procurement authority.
Industry Challenges
- ITAR-equivalent export control alignment:German component suppliers must reconcile domestic licensing with US International Traffic in Arms Regulations for dual-use sensor technologies, extending contract negotiation timelines.
- Legacy GIS integration complexity:State mapping agencies maintain decades-old coordinate reference systems that resist direct API ingestion, forcing middleware development for cloud-delivered products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Satellite Imagery Services Market |
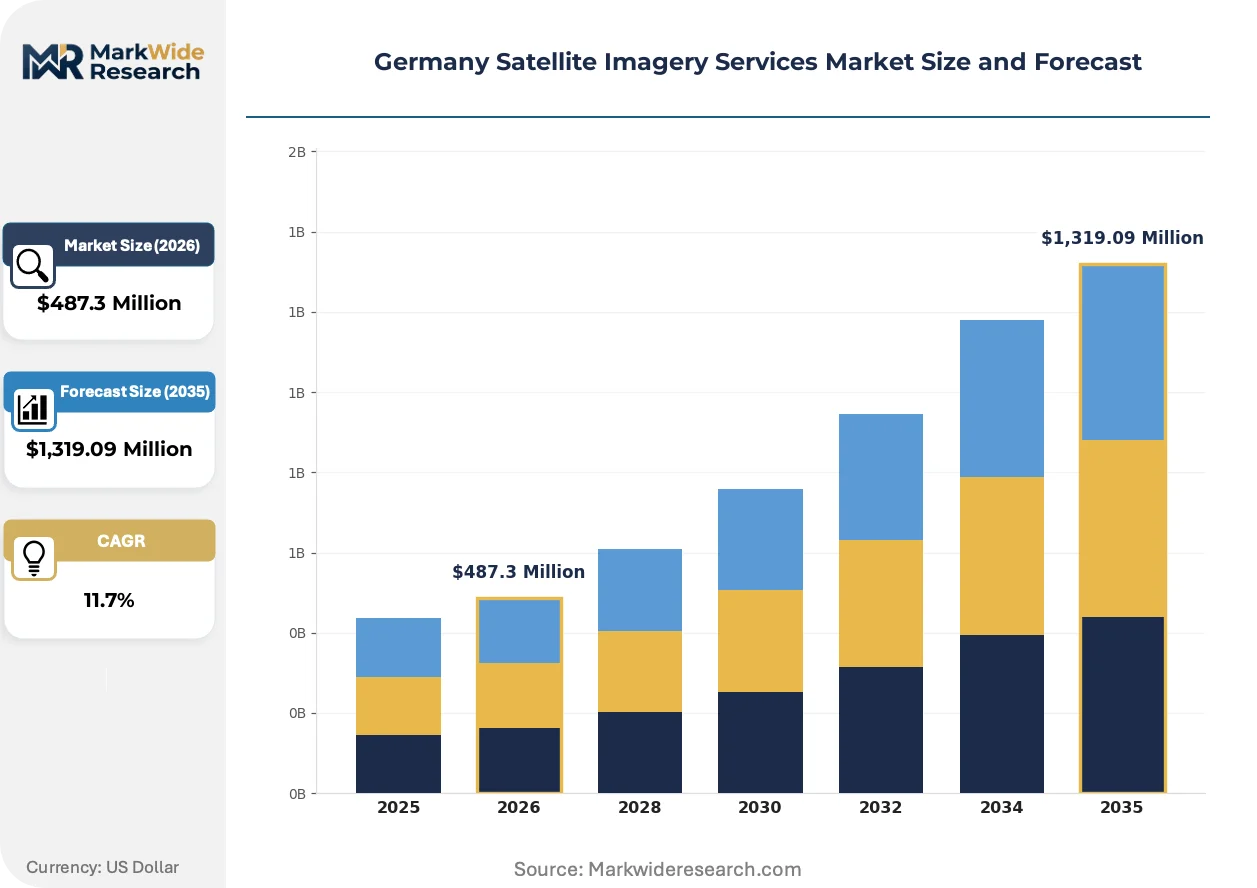
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Imagery, Radar Imagery, Multispectral Imagery, Hyperspectral Imagery Application: Agriculture Monitoring, Environmental Management, Urban Planning, Defense & Security Delivery Model: Cloud-Based, On-Premises, Hybrid, Offline Download End User: Government Agencies, Research Institutions, Private Enterprises, Non-Profit Organizations |
| Companies Covered | Planet Labs, Airbus Defence and Space, L3Harris Corporation, Telespazio Spa, European Space Imaging GmbH, Maxar Technologies, UP42 GmbH, GAF AG, ESRI Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Satellite Imagery Services Market Trends and Innovations
Synthetic aperture radar is compressing the competitive advantage of optical specialists by delivering reliable coverage through Central Europe's persistent cloud cover. Three developments are restructuring how orbital data moves from sensor to decision-maker.
Sensor fusion architectures are unifying panchromatic, multispectral, and radar returns into single analytic pipelines. Agricultural insurers in Lower Saxony are adopting these composite products for crop-loss verification, collapsing what previously required three separate vendor relationships into one subscription. The structural result is unifying procurement decisions around integrated platform providers rather than best-of-breed point solutions.
The EU AI Act is filtering into federal contracting specifications through BSI implementation guidance, mandating explainability documentation for machine-generated land-cover classifications. This regulatory pressure is compressing vendor development cycles toward interpretable model architectures. Defense and automotive applications under KBA accuracy requirements are most affected, with contractors adding dedicated compliance engineering functions to bid teams.
State-level geodetic authorities are consolidating vendor relationships around multi-year enterprise agreements, displacing project-based tasking for recurring coverage subscriptions. Municipal planners in Stuttgart and Munich are the primary adopters, replacing ad-hoc imagery purchases with standing access to federal portal infrastructure. This behavioral shift is most visible in Baden-Württemberg, where interagency data-sharing mandates have normalized pooled procurement across city and regional planning offices.
Germany Satellite Imagery Services Market Segmentation
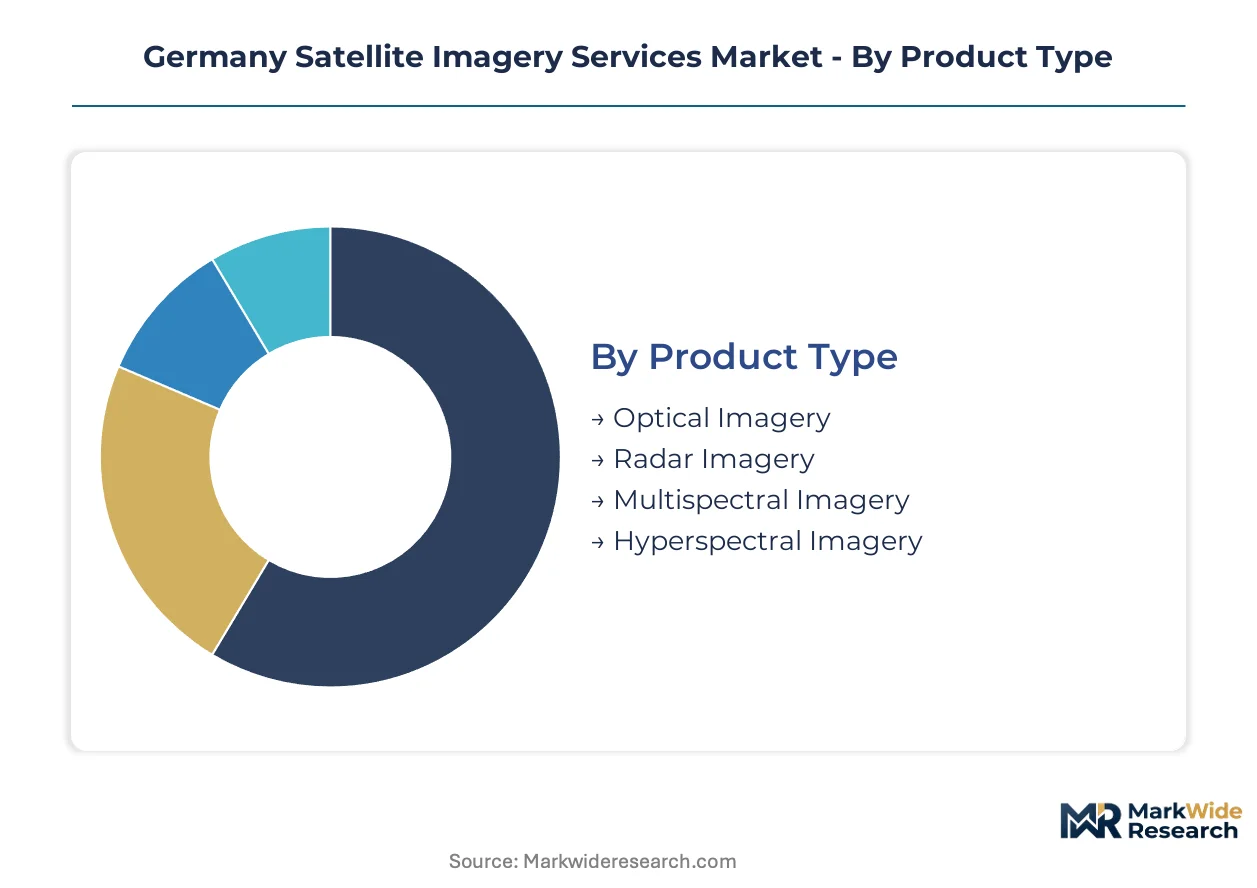
German procurement authorities structure satellite imagery contracts around spectral capabilities, application urgency, and data sovereignty requirements. Vendors must align product architectures with these decision hierarchies to capture federal and state-level awards.
Product Type:
Resolution requirements and weather resilience drive spectral technology selection across defense, agriculture, and infrastructure monitoring contracts.
- Optical Imagery:Panchromatic and multispectral sensors deliver sub-meter resolution for detailed land-cover interpretation. Bavarian urban planners and the Bundesamt für Kartographie anchor procurement volumes here, leveraging mature spectral libraries for Central European vegetation and built-environment classification.
- Radar Imagery:Synthetic aperture radar penetrates cloud cover and operates independent of solar illumination. Alpine transport authorities in Bavaria and flood-response agencies along the North Sea coast are expanding tasking contracts for all-weather slope stability and inundation monitoring.
- Multispectral Imagery:Narrowband spectral channels support vegetation health indices and mineral detection. Agricultural insurers in Lower Saxony use these products for crop-loss verification.
- Hyperspectral Imagery:Continuous narrow bands enable material identification and anomaly detection. Research installations at DLR facilities drive specialized procurement for environmental chemistry applications.
Volume sits with Optical Imagery; growth tilts toward Radar Imagery.
Application:
Regulatory mandates and risk exposure determine budget allocation across federal ministries and state authorities.
- Defense & Security:Border surveillance modernization mandates sub-meter refresh rates for perimeter monitoring. The Bundeswehr and federal police anchor long-term service contracts with integrated tasking and analytic delivery.
- Agriculture Monitoring:Crop-loss verification and precision agriculture drive subscription demand. Lower Saxony's agricultural insurers are consolidating vendor relationships around composite radar-optical products.
- Environmental Management:EU Green Deal compliance and emissions monitoring shape procurement from federal environment agencies. Forest carbon accounting and wetland preservation dominate tasking requests.
- Urban Planning:Municipal authorities in Stuttgart and Munich require high-frequency coverage for zoning enforcement and infrastructure development tracking. Baden-Württemberg's interagency data-sharing mandates accelerate pooled procurement.
Defense & Security commands the largest contract values; Agriculture Monitoring is expanding most quickly as insurers adopt automated loss verification.
Delivery Model:
Data sovereignty requirements and legacy system integration determine architecture preferences across buyer tiers.
- Cloud-Based:API-first delivery enables real-time ingestion into geographic information systems. State geodetic authorities in Bavaria and Baden-Württemberg are retiring physical media workflows in favor of portal-based access.
- Hybrid:Combines cloud accessibility with on-premises storage for sensitive defense and critical infrastructure applications. BSI-regulated operators under the EU AI Act favor this architecture for explainability documentation.
- On-Premises:Air-gapped installations serve classified defense installations and intelligence community requirements with strict data residency mandates.
- Offline Download:Physical media handoffs persist in legacy municipal planning offices with limited connectivity or outdated coordinate reference systems.
Cloud-Based delivery holds current volume leadership; Hybrid architectures are gaining share fastest among critical infrastructure operators.
End User:
Budget authority and procurement sophistication segment the buyer base from federal ministries to municipal offices.
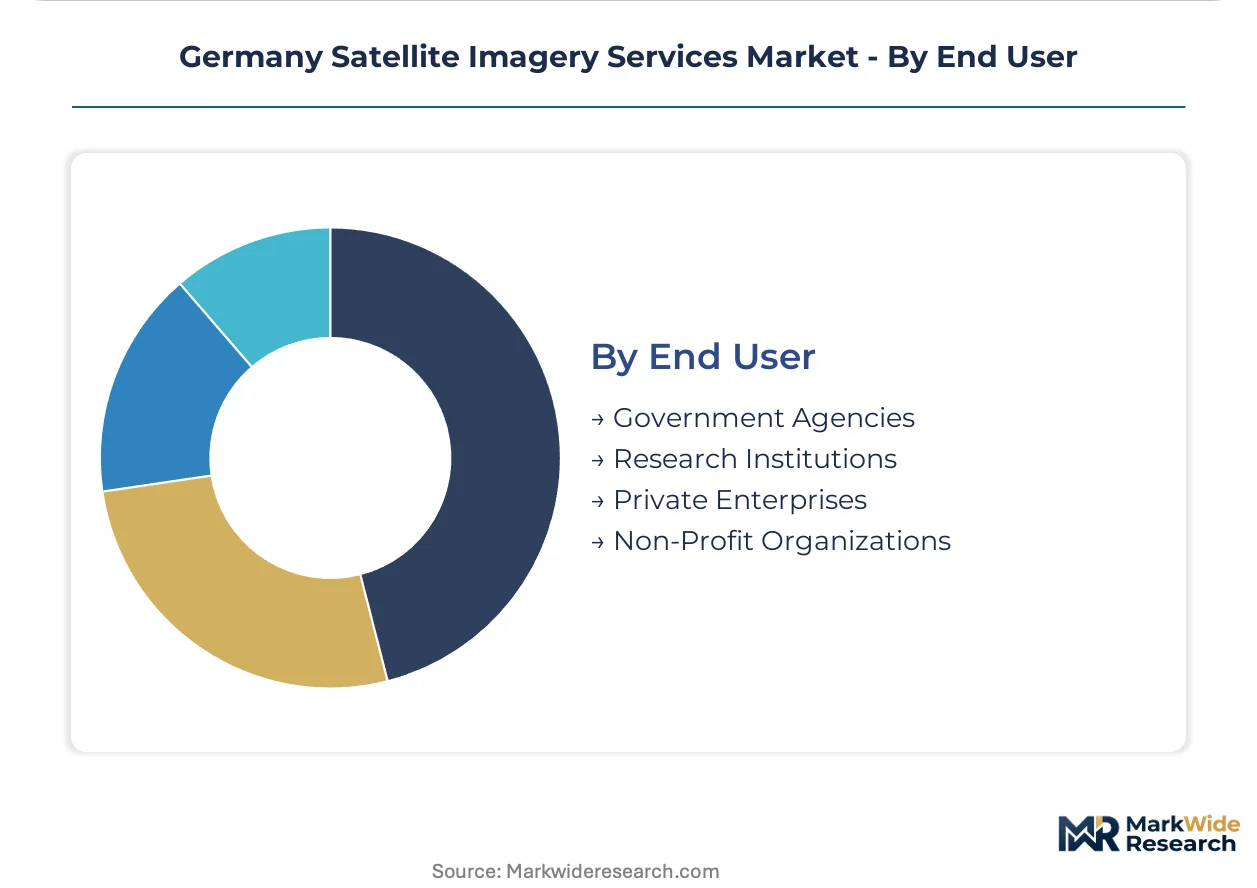
- Government Agencies:Federal and state authorities hold consolidated procurement power through the EU Space Programme and national space strategy. The Bundesamt für Kartographie pilots federated access architectures for interagency sharing.
- Research Institutions:DLR facilities and university consortia drive hyperspectral and experimental sensor demand. These buyers prioritize data granularity over refresh frequency.
- Private Enterprises:Infrastructure insurers, logistics operators, and agricultural technology firms subscribe to commercial imagery services. Alpine corridor monitoring contracts from transport authorities create recurring revenue streams.
- Non-Profit Organizations:Environmental advocacy groups and international development agencies access subsidized or open-data orbital holdings for conservation and humanitarian applications.
Government Agencies dominate absolute spending; Private Enterprises show the steepest expansion trajectory as insurers operationalize geospatial risk models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized aerospace zones in southern Germany concentrate procurement authority and technical talent, pulling federal research funding toward Bavaria and Baden-Württemberg.
Bavaria
Defense modernization and alpine infrastructure monitoring drive demand for radar imagery with all-weather penetration. The EU Space Programme channels shared orbital assets into Bundeswehr border surveillance contracts. Munich anchors a dense cluster of DLR research installations and aerospace engineering firms that feed talent into federal procurement offices.
Baden-Württemberg
Automotive geospatial compliance under KBA standards and urban planning digitization shape commercial uptake. State-level interagency data-sharing mandates normalize pooled procurement across municipal offices. Stuttgart's manufacturing belt hosts precision engineering suppliers that integrate satellite-derived terrain data into autonomous vehicle validation pipelines.
North Rhine-Westphalia
Flood-response agencies along the Rhine corridor expand synthetic aperture radar tasking for inundation early warning. The EU Green Deal filters into state environment ministry contracts for emissions monitoring and wetland preservation. Cologne-Bonn's federal administrative density concentrates procurement decision-making for cross-border data licensing negotiations.
Lower Saxony
Agricultural insurers operationalize composite radar-optical products for automated crop-loss verification at scale. National space legislation governs territorial restrictions on raw data resale that fragment vendor operating models. Hanover's geodetic authority pilots cloud-native delivery architectures that retire physical media workflows for municipal planners.
Hesse
Critical infrastructure operators under BSI guidance adopt hybrid delivery models for AI Act-compliant automated classification. Frankfurt's financial services sector experiments with geospatial risk models for infrastructure insurance pricing. The state's central location positions it as a data relay hub for federated access architectures spanning federal and municipal tiers.
Germany Satellite Imagery Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across German procurement channels, creating a tiered structure where dual-use heritage confers distinct advantage in defense-adjacent contracts. The vendor base splits between constellation operators, analytics layer providers, and platform intermediaries that aggregate access across multiple sensor networks. Two dominant competitive moves are reshaping positioning: strategic partnerships that bundle tasking capacity with compliance engineering for AI Act mandates, and geographic anchoring around Bavarian and Baden-Württemberg aerospace clusters to capture federal research spillover.
Within the constellation operator tier, Airbus Defence and Space and Planet Labs occupy positions shaped by heritage and refresh cadence respectively. Airbus leverages dual-use satellite architecture to anchor integrated defense-civilian contracts, while Planet Labs competes on daily coverage frequency that meets sub-meter refresh mandates for border surveillance. European Space Imaging GmbH exemplifies the regional specialist archetype, concentrating on high-resolution optical tasking with direct pipeline access to federal mapping authorities. GAF AG represents the analytics-layer pure-play, differentiating raw imagery through application-ready geospatial outputs rather than sensor ownership.
| Leading Market Players |
|---|
| Planet Labs |
| Airbus Defence and Space |
| L3Harris Corporation |
| Telespazio Spa |
| European Space Imaging GmbH |
| Maxar Technologies |
| UP42 GmbH |
| GAF AG |
| ESRI Inc |
| Others |
Pricing and Supply Chain Analysis
EU Space Programme procurement consolidation is compressing vendor margins by standardizing tasking rates across member states, forcing constellation operators to recalibrate cost structures around shared orbital assets rather than bilateral premium pricing.
Pricing Analysis
Short lead-time premiums dominate tasking economics, with rush orders for sub-meter resolution commanding substantial markups over standard-queue bookings. Three-tier pricing structure across premium, standard, and economy levels segments buyers by refresh frequency and analytic bundling. Pricing pressure stems from cloud-native delivery commoditizing raw imagery access. Municipal planners in Baden-Württemberg exhibit highest price sensitivity; defense agencies under Bundeswehr contracts show least.
Supply Chain Analysis
Sensor refurbishment and orbital component remanufacturing flows concentrate in France, Germany, and the United States, with Airbus Defence and Space facilities in Toulouse and Bremen anchoring European satellite servicing capacity. Supply draws from gallium arsenide solar cells, precision reaction wheels, and synthetic aperture radar antennas. Single-source vulnerability in launch vehicle availability from French Guiana creates scheduling bottlenecks. Distribution runs through API-first platforms and federal procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany satellite imagery services market is becoming a vertical-integration race as analytics vendors pursue upstream sensor ownership to escape margin compression in commoditized distribution layers.
For Market Incumbents: Acquire radar constellation capacity to defend against optical-only specialists losing share in alpine corridor contracts. Consolidate around hybrid delivery architectures that satisfy BSI data sovereignty mandates for critical infrastructure operators. Deepen backward integration into geospatial AI training pipelines to capture EU AI Act compliance service revenue. For New Entrants and Emerging Players: Launch via federated access partnerships with the Bundesamt für Kartographie to bypass direct federal procurement authority requirements. Target municipal planning offices in Stuttgart and Munich with subscription-based slope stability monitoring for transport authorities. Emphasize explainability documentation capabilities for automated feature-extraction contracts. For Investors and Strategic Acquirers: The window for entry favors analytics-layer pure-plays with established federal agency relationships and AI Act compliance engineering functions. Long-term viability hinges on securing recurring revenue streams from infrastructure insurers operationalizing geospatial risk models. Monitor EU Space Programme funding allocations for early signals of procurement consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Constellation Capacity Expansion | Radar satellite deployment secures all-weather positioning against optical specialists in Bavarian alpine contracts. |
| AI Act Compliance Engineering Buildout | Explainability documentation capabilities unlock BSI-regulated critical infrastructure procurement channels under federal guidance. |
| Federated Access Platform Partnership | Bundesamt für Kartographie portal integration enables municipal subscriber acquisition without direct procurement authority. |
| Backward Integration into Sensor Manufacturing | In-house SAR payload production reduces dependency on ITAR-constrained component suppliers and accelerates deployment timelines. |
| Geographic Cluster Anchoring | Munich and Stuttgart proximity captures DLR research spillover and federal procurement office talent pipelines. |
Research Methodology
Independent corroboration across constellation operators, federal procurement officers, and geospatial analytics vendors underwrites the qualitative findings in this study. Primary interviews engaged satellite mission directors, Bundesamt für Kartographie licensing administrators, Bavarian transport authority planners, agricultural insurance risk modelers, and BSI compliance specialists. Secondary validation drew from EU Space Programme procurement disclosures, German national space strategy documents, DLR research publication databases, and federal geodetic authority modernization reports. Bottom-up tasking volume estimates triangulate against top-down federal budget allocation analysis.
Rate-of-change decomposition across the analysis window separates volume expansion from price evolution and mix shift effects. Segmentation dimensions modeled include spectral technology, application vertical, delivery architecture, and end-user tier. CAGRs derive from weighted scenario analysis across defense modernization, agricultural insurer adoption, and cloud-native delivery penetration trajectories. Forecast inputs incorporate EU AI Act implementation timelines and Bundeswehr border surveillance refresh rate mandates.
Launch vehicle scheduling delays, spectral interpretation labor scarcity, and cross-border licensing friction are the dominant revision risks that could compress or extend projected expansion trajectories. Forecasts reflect assumptions regarding EU Space Programme funding continuity and federal procurement rule stability. Practitioners should monitor KBA automotive geospatial standard updates and BSI AI Act guidance releases for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
Nigeria Satellite-Based Earth Observation Market
Satellite
North America Satellite Bus Market
Satellite
Europe Satellite Manufacturing and Launch Systems Market
Satellite
Russia Satellite Communications Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
North America Mobile Satellite Services Market
Satellite
Satellite Parts and Components Market
Satellite
Satellite Gateway Market
Satellite
Communication Satellite Launch Services Market
Satellite
China Satellite Imagery Services Market
Satellite
Satellite Communication Subsystem Market
Satellite
UK Satellite-Based Earth Observation Market
Satellite
GEO Satellite Market