
 Satellite GPS Receivers Market | 2026-2036
Satellite GPS Receivers Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite GPS Receivers Market Analytics
Defense procurement channels are tilting toward multi-constellation architectures with anti-jam capabilities. Trimble Inc. leverages its agricultural automation installed base to push receiver-software bundles into precision farming workflows. Garmin Ltd. anchors the consumer handheld segment through ruggedized outdoor product lines with GLONASS and Galileo compatibility. Hexagon AB dominates the survey-grade tier through its Leica Geosystems division, which sustains pricing power via in-house antenna calibration protocols.
A satellite GPS receiver is an electronic device that processes signals from orbiting navigation satellites—primarily GPS, GLONASS, Galileo, or BeiDou—to compute position, velocity, and timing data with accuracy ranging from meter-level to centimeter-level depending on augmentation systems. These receivers serve critical functions across transportation logistics, geodetic surveying, military targeting, and autonomous vehicle guidance where real-time kinematic correction enables lane-level precision. Multi-constellation technology is capturing the fastest growth trajectory as receiver manufacturers integrate signals from four or more satellite systems to improve availability in urban canyons and polar regions. The automotive product type commands the largest revenue pool as OEMs embed dual-frequency receivers into advanced driver-assistance platforms, while the military end-user segment maintains the highest margin profile through encrypted M-code and anti-spoofing requirements.
The FCC enforces GPS receiver interference standards under Part 15 rules, while the EU's Radio Equipment Directive mandates CE marking for receiver electromagnetic compatibility across member states. Japan's MIC certifies receiver performance through technical standards that align with QZSS augmentation for domestic precision needs. Stakeholders must monitor evolving spectrum allocation debates around Ligado Networks and adjacent-band 5G deployments, as these proceedings threaten to redefine receiver front-end filtering requirements and compliance testing burdens.
Market Dynamics
Multi-constellation receiver architectures are compressing product lifecycles as defense and automotive buyers demand simultaneous GPS, GLONASS, Galileo, and BeiDou compatibility. This technical convergence forces manufacturers to redesign RF front-ends and baseband processors more frequently than legacy single-system designs required.
Growth Catalysts
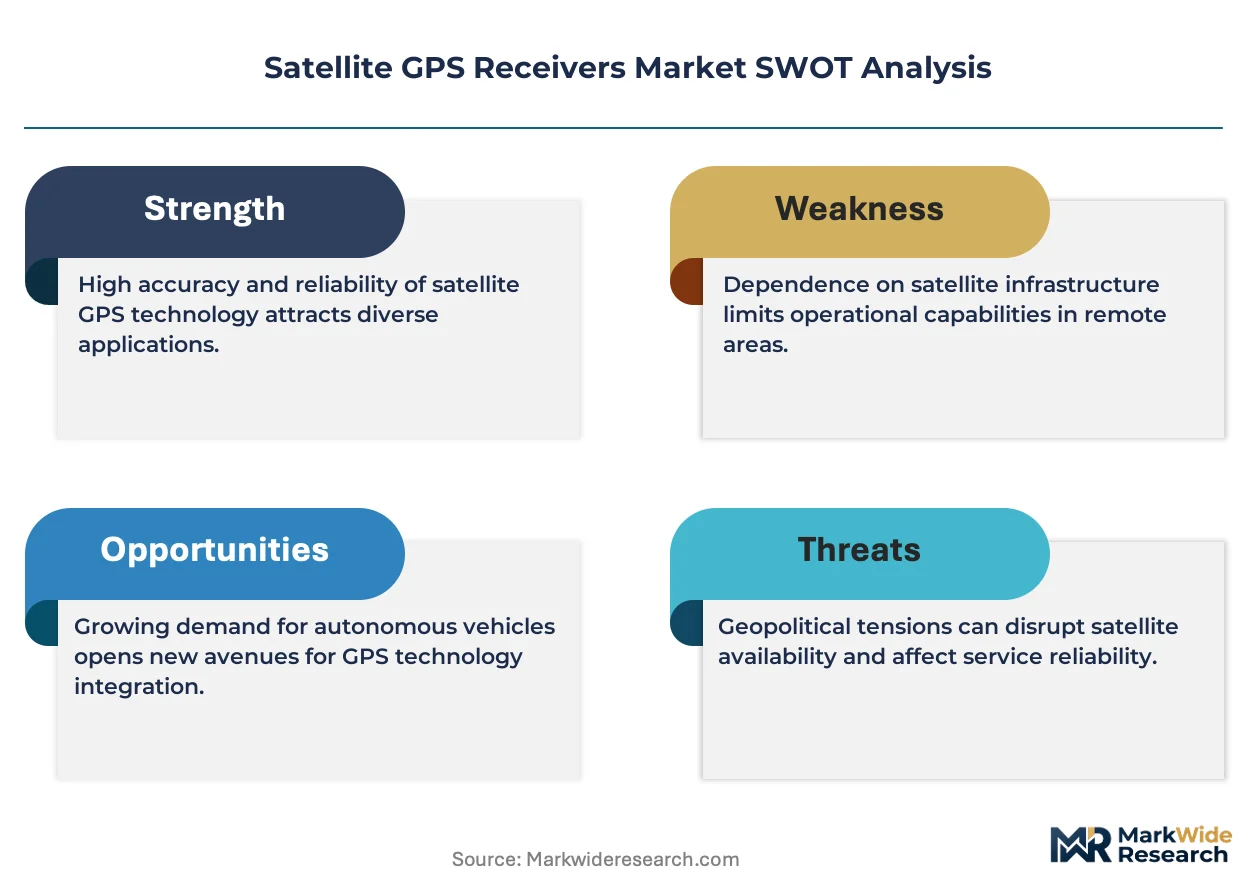
- FCC GPS interference mitigation mandates:The United States regulator's tightening signal integrity requirements for civilian equipment are compelling receiver manufacturers to upgrade filtering capabilities, expanding the addressable market for premium-grade components.
- Precision agriculture automation:Brazilian fleet operators are deploying multi-constellation receivers at scale to enable centimeter-level tractor guidance, creating sustained demand for ruggedized agricultural units.
- Dual-frequency integration:METI-backed autonomous vehicle trials in Japan are accelerating receiver designs that process both L1 and L5 bands, improving ionospheric correction and urban positioning reliability.
Market Restraints
- Semiconductor supply concentration:Advanced RF front-end components and high-precision baseband processors depend on concentrated foundry capacity in East Asia, exposing manufacturers to geographic supply disruptions.
- Adjacent-band 5G interference:Ligado Networks spectrum allocation proceedings in the United States threaten to degrade GPS signal reception, forcing costly receiver redesigns with sharper filtering.
- Technical limitation in urban canyons:Multipath signal reflection in dense metropolitan environments degrades positioning accuracy below autonomous vehicle safety thresholds, limiting deployment in core mobility applications.
Strategic Opportunities
- QZSS augmentation adoption:Japan's regional satellite system offers domestic precision enhancement that receiver manufacturers can leverage for Asia-Pacific differentiation.
- Unmanned aerial systems expansion:Commercial drone operators across logistics and inspection verticals present untapped demand for lightweight, low-power multi-constellation modules.
- EU Radio Equipment Directive harmonization:CE marking mandates for electromagnetic compatibility create regulatory tailwinds for manufacturers with pre-certified product platforms.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in antenna design and signal processing for multi-constellation architectures remains concentrated among experienced practitioners, constraining product development velocity.
- M-code certification complexity:Military encrypted signal compliance requires extended testing cycles with defense procurement agencies, delaying revenue recognition for qualified products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite GPS Receivers Market |
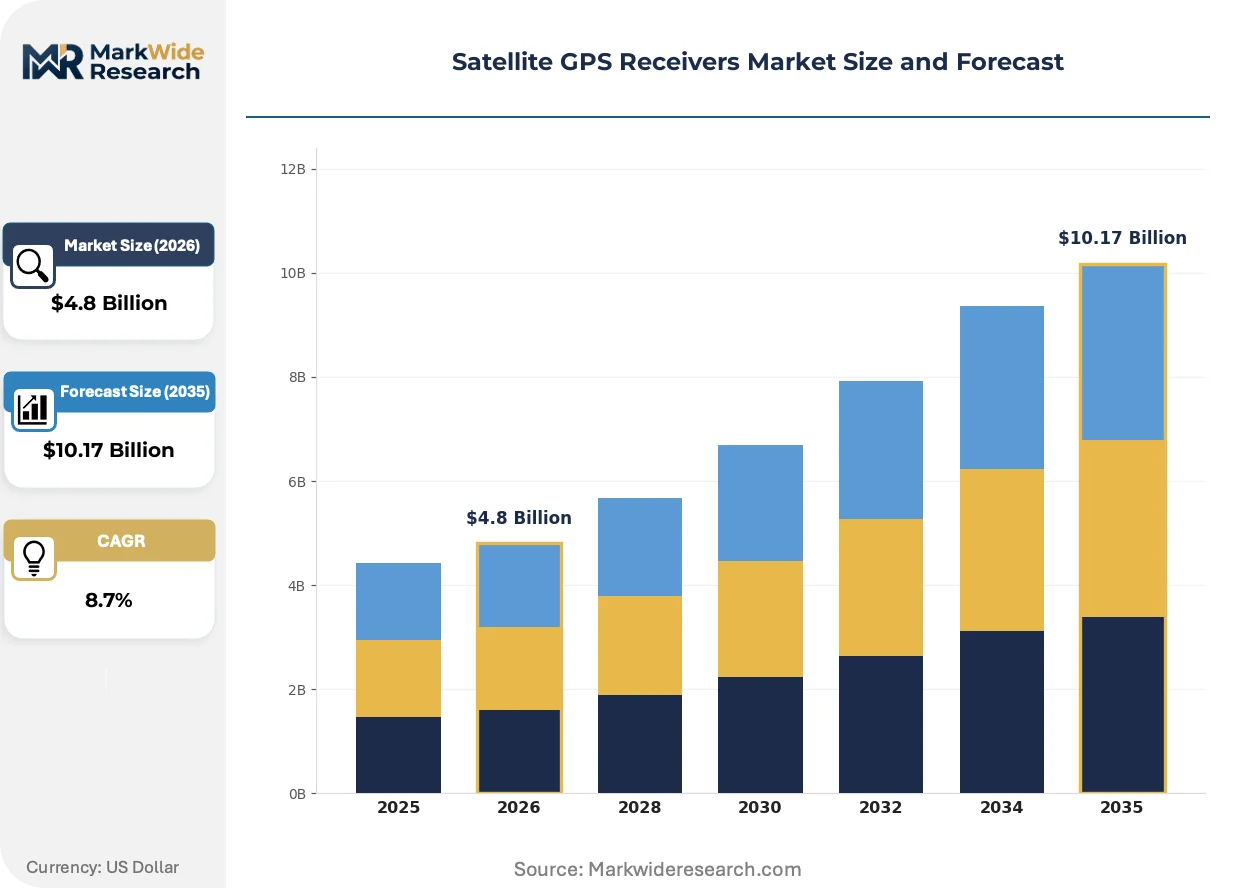
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Automotive, Marine, Aviation Technology: FLARM, Assisted GPS, Dual-frequency, Multi-constellation Application: Navigation, Tracking, Geofencing, Mapping End User: Government, Military, Commercial, Consumer |
| Companies Covered | Trimble Inc., Topcon Positioning Systems, Inc., Garmin Ltd., Hexagon AB, Hemisphere GNSS Inc., L3Harris Technologies, Inc., Septentrio NV, JAVAD GNSS Inc., u-blox AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite GPS Receivers Market Evolving Landscape
Receiver virtualization is collapsing hardware boundaries as software-defined radio architectures replace fixed-function chipsets. This shift enables post-deployment feature upgrades and multi-constellation flexibility without physical redesign.
Software-defined radio is virtualizing traditional GPS receiver hardware by executing signal acquisition and tracking algorithms on general-purpose processors rather than dedicated ASICs. Automotive OEMs and defense integrators are adopting these flexible architectures to reduce qualification cycles for new satellite systems. The technology is virtualizing supplier value chains by decoupling hardware manufacturing from feature enablement, compressing margins for legacy chipset vendors while expanding opportunities for firmware specialists.
The FCC's Part 15 receiver interference standards are tightening emission limits for civilian GPS equipment operating near protected spectrum bands. Manufacturers must now demonstrate enhanced out-of-band rejection capabilities to maintain market access in the United States. Survey-grade and automotive receiver segments are responding by integrating advanced surface acoustic wave filters and adaptive interference cancellation algorithms.
Buyer concentration among tier-one automotive OEMs is consolidating procurement leverage for embedded navigation modules. Long-term supply agreements now bundle receiver hardware with over-the-air update services, displacing discrete component purchasing. Japan's autonomous vehicle ecosystem exhibits this pattern most acutely, where METI-coordinated trials favor integrated platform suppliers over standalone receiver vendors.
Satellite GPS Receivers Market Segmentation
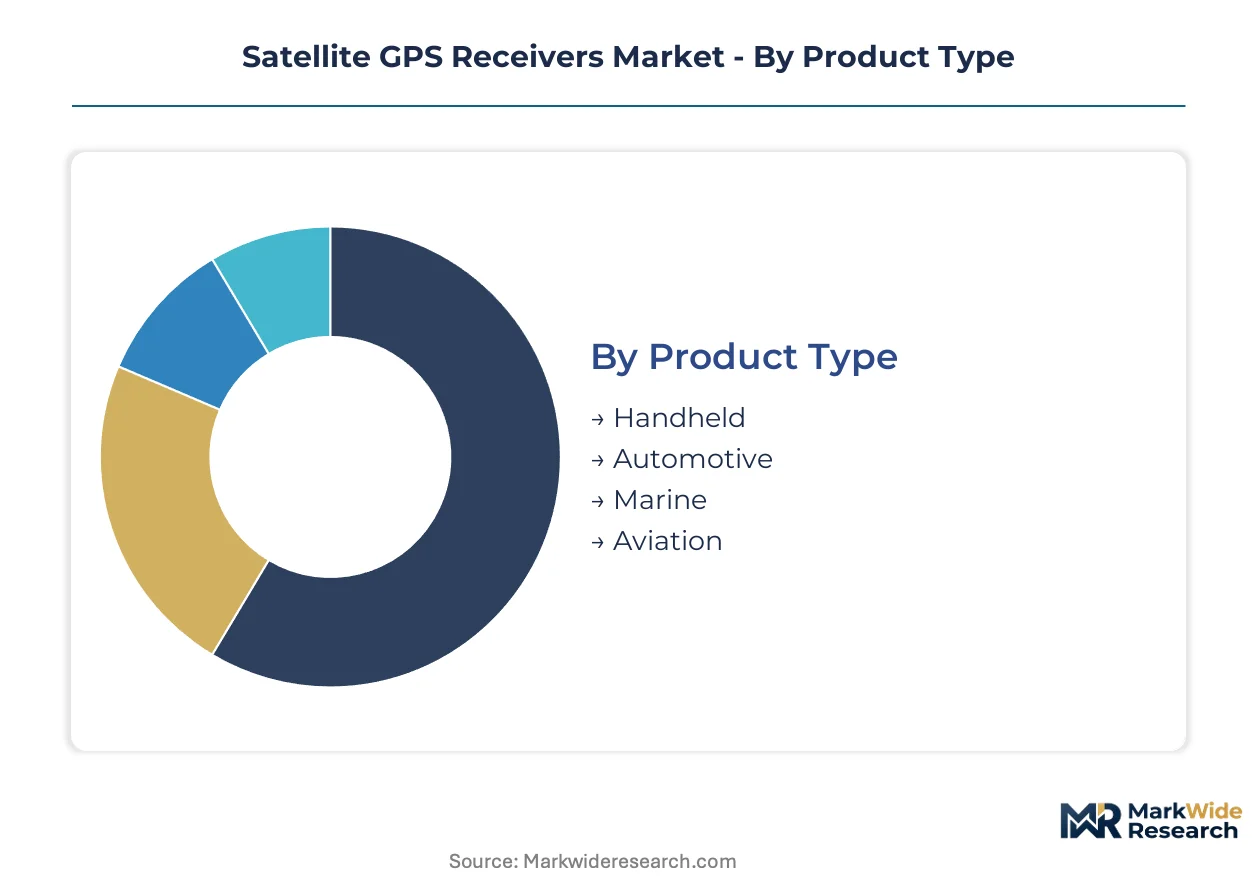
Satellite GPS receiver segmentation reveals how positioning technology fragments across divergent performance requirements and regulatory environments. Each category reflects distinct buyer priorities—ruggedization for defense, miniaturization for consumer wearables, or precision certification for survey operations.
Product Type:
Mature automotive platforms coexist with emerging handheld formats as receiver form factors diverge around installation constraints and power budgets.
- Handheld:Portable units integrate GLONASS and Galileo compatibility into battery-optimized enclosures for outdoor recreation and field surveying. Demand clusters in Japan's METI-backed precision agriculture trials where ruggedized handheld units enable centimeter-level tractor guidance without cab installation.
- Automotive:Embedded modules process dual-frequency L1/L5 signals for lane-level ADAS positioning, requiring automotive-grade temperature tolerance and electromagnetic compliance. OEM procurement in Japan and Germany concentrates on integrated platform suppliers bundling hardware with over-the-air update services.
- Marine:Saltwater-resistant enclosures with enhanced multipath rejection serve commercial fishing fleets and recreational boating across coastal Brazil and Mediterranean ports.
- Aviation:Certified receivers meeting FAA TSO-C145 standards support approach navigation with integrity monitoring for general aviation and unmanned cargo systems.
Automotive handles the majority of throughput; handheld is expanding most quickly on share as precision agriculture adoption accelerates in Brazil and Southeast Asia.
Technology:
Cost tiers separate legacy single-system architectures from premium multi-constellation designs as RF front-end complexity drives pricing stratification.
- Multi-constellation:Simultaneous GPS, GLONASS, Galileo, and BeiDou tracking improves satellite availability in urban canyons and polar regions through redundant signal paths. Brazil's expanding precision agriculture fleets deploy these units at scale for uninterrupted tractor guidance during canopy obstruction.
- Dual-frequency:L1/L5 band processing enables real-time ionospheric correction, delivering sub-meter accuracy for autonomous vehicle safety systems in Japan's METI-coordinated trials.
- Assisted GPS:Network-aided acquisition reduces time-to-first-fix for cellular-connected devices in consumer smartphones and fleet telematics.
- FLARM:Collision avoidance receivers integrate with glider and light aircraft traffic awareness systems across European general aviation corridors.
Multi-constellation commands the premium tier; dual-frequency is gaining share fastest as automotive OEMs mandate ionospheric resilience.
Application:
Customer type differentiation separates enterprise-grade accuracy requirements from consumer convenience expectations across four functional use cases.
- Navigation:Turn-by-turn routing for automotive and marine platforms depends on continuous position fixes with integrity monitoring for safety-critical maneuvers.
- Tracking:Asset and fleet management systems prioritize low-power consumption and cellular backhaul for logistics operators across North American and European freight corridors.
- Geofencing:Virtual perimeter enforcement supports agricultural machinery automation and construction equipment security with configurable boundary alerts.
- Mapping:Survey-grade kinematic positioning enables cartographic data collection and infrastructure as-built documentation for government geodetic agencies.
Navigation absorbs the largest deployment volume; tracking is climbing the fastest as logistics digitization penetrates emerging markets.
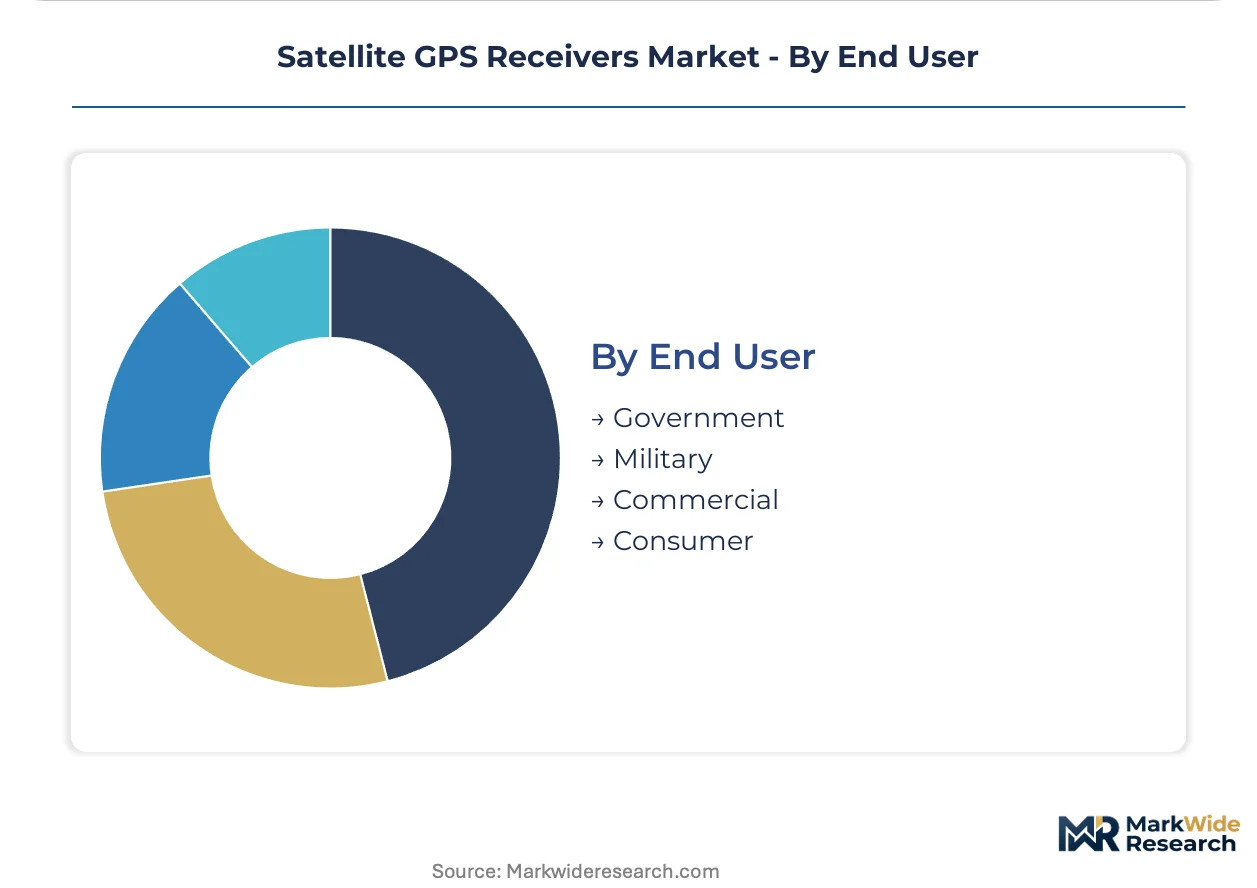
End User:
Margin profiles diverge sharply between encrypted military specifications and price-sensitive consumer volumes.
- Military:M-code encrypted signal compliance and anti-jam/spoofing architectures sustain the highest margin tier through extended defense procurement testing cycles.
- Commercial:Precision agriculture, construction automation, and logistics fleet operators drive volume demand with requirements for ruggedization and multi-constellation reliability.
- Government:Survey agencies and transportation departments procure certified reference stations and augmentation infrastructure for public positioning services.
- Consumer:Outdoor recreation and fitness wearable buyers prioritize battery life and cost over absolute accuracy, compressing margins for standalone receiver vendors.
Commercial end users dominate unit shipments; military specifications deliver the steepest margin expansion trajectory despite procurement delays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Panama Canal expansion underwrites Latin America's logistics backbone for precision agriculture equipment distribution. Japan's QZSS ground segment anchors Asia-Pacific augmentation infrastructure. Germany's Rhine-Danube freight corridor integrates real-time kinematic positioning for inland waterway navigation.
United States
Defense procurement channels and autonomous vehicle testing fleets drive multi-constellation receiver demand. The FCC enforces Part 15 interference standards that mandate enhanced filtering for civilian equipment. Arizona's proving grounds host METI-coordinated trials where dual-frequency receivers process L1/L5 bands for lane-level precision.
Japan
METI-backed autonomous vehicle trials and precision agriculture automation accelerate dual-frequency integration. The MIC certifies receiver performance through technical standards aligned with QZSS augmentation. Nagoya's manufacturing corridor concentrates automotive OEM procurement of embedded navigation modules with over-the-air update capabilities.
Brazil
Expanding precision agriculture fleets deploy multi-constellation receivers for centimeter-level tractor guidance. ANVISA regulates electromagnetic compatibility for agricultural electronics entering domestic commerce. Mato Grosso's soybean belt concentrates ruggedized receiver installations where canopy obstruction demands redundant satellite signal paths.
Germany
Survey-grade kinematic positioning and automotive ADAS platforms sustain premium receiver demand. The EU Radio Equipment Directive mandates CE marking for electromagnetic compliance across member states. Stuttgart's automotive engineering cluster embeds dual-frequency receivers into advanced driver-assistance platforms for export markets.
China
BeiDou constellation completion and commercial drone logistics expansion drive domestic multi-constellation adoption. MIIT oversees radio equipment type approval for navigation receivers operating in protected spectrum. Shenzhen's electronics manufacturing base produces low-cost RF front-end components for consumer and industrial receiver modules.
Satellite GPS Receivers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying RF front-ends and baseband processors. The vendor base concentrates around three strategic archetypes: defense contractors with M-code certification capabilities, automotive tier-one suppliers bundling hardware with software services, and survey-grade specialists maintaining pricing power through calibration protocols. Competitive moves center on strategic partnerships for constellation access rights and portfolio diversification into software-defined radio architectures.
Among North American platform integrators, Trimble Inc. and L3Harris Technologies, Inc. occupy positions spanning defense and commercial verticals. Septentrio NV exemplifies the European multi-constellation specialist archetype. These three companies represent distinct competitive vectors: agricultural automation bundling, encrypted military signal compliance, and high-precision survey-grade positioning respectively.
| Leading Market Players |
|---|
| Trimble Inc. |
| Topcon Positioning Systems, Inc. |
| Garmin Ltd. |
| Hexagon AB |
| Hemisphere GNSS Inc. |
| L3Harris Technologies, Inc. |
| Septentrio NV |
| JAVAD GNSS Inc. |
| u-blox AG |
| Others |
Value Network & Pricing Analysis
Shenzhen's RF component manufacturing cluster anchors global receiver production capacity, concentrating upstream leverage among East Asian foundries while downstream automotive OEMs extract volume discounts through bundled procurement contracts. This geographic asymmetry compresses margins for mid-tier receiver vendors unable to match tier-one scale commitments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates military M-code certified units from commercial multi-constellation designs and consumer-grade single-system modules. Price differentiation hinges on anti-jam certification grade and volume scale, with defense procurement sustaining premium tiers while agricultural fleet operators drive standard-tier compression. Cost compression in the economy tier is intensifying because smartphone integration is displacing standalone handheld demand. Consumer wearable buyers exhibit highest price sensitivity; military integrators show least.
Supply Chain Analysis
Extended payment terms from automotive OEMs and supply-chain finance facilities are reshaping working capital requirements for RF front-end suppliers. Manufacturing concentrates in China, Taiwan, and South Korea, drawing from specialized gallium arsenide substrates, high-precision ceramic filters, and automotive-grade baseband processors. Single-source vulnerability in advanced RF foundry capacity threatens component availability. Distribution runs through tier-one automotive suppliers and defense prime contractors rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Receiver virtualization is collapsing hardware boundaries into software-defined platform economics, where firmware upgradeability and constellation interoperability determine vendor viability rather than fixed-function silicon.
For Market Incumbents: Insulate agricultural automation margins by deepening backward integration into antenna calibration protocols, countering Septentrio NV's survey-grade positioning dominance. Lock in long-term M-code certification pipelines with defense procurement agencies before L3Harris Technologies consolidates encrypted signal compliance advantages.
For New Entrants and Emerging Players: Establish a beachhead in commercial unmanned aerial systems by offering lightweight multi-constellation modules with QZSS augmentation for Asia-Pacific logistics operators. Bypass saturated automotive tier-one supply chains through direct drone OEM relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because software-defined radio architectures are decoupling hardware manufacturing from feature enablement, favoring acquirers of firmware-specialist targets over legacy chipset vendors. Watch METI trial outcomes as inflection indicator for dual-frequency automotive adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Migration | Enables post-deployment constellation upgrades without hardware redesign for automotive OEMs. |
| QZSS Augmentation Integration | Secures Asia-Pacific differentiation through Japan's regional satellite system certification. |
| M-Code Certification Investment | Unlocks defense procurement channels with encrypted signal compliance and anti-spoofing. |
| Precision Agriculture Bundle Expansion | Leverages Brazilian fleet scale to push receiver-software combinations into automation workflows. |
| RF Front-End Backward Integration | Captures margin from concentrated East Asian foundry capacity through in-house filter production. |
Research Methodology
A spread of perspectives from receiver hardware engineers, automotive platform procurement managers, defense systems integrators, and precision agriculture fleet operators converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from FCC Part 15 filings, EU Radio Equipment Directive technical documentation, METI trial progress reports, and customs trade data for RF component flows. Bottom-up unit shipment estimates triangulated against top-down market sizing from semiconductor foundry capacity disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions including product type, constellation technology tier, end-use application, and regional regulatory cluster. CAGRs derived from shipment trajectory analysis and pricing elasticity assumptions. Forecast inputs incorporated FCC interference mitigation compliance timelines and BeiDou constellation completion schedules.
Sensitivities concentrate around Ligado Networks spectrum allocation outcomes and East Asian foundry capacity disruptions. Forecasts reflect documented assumptions about autonomous vehicle trial progression and defense procurement cycle timing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Italy Satellite Imagery Services Market
Satellite
Satellite Communication System Market
Satellite
United Kingdom Satellite Communications Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
France Satellite-Based Earth Observation Market
Satellite
Satellite Compass Market
Satellite
Flat Panel Satellite Antenna Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
Canada Satellite-Based Earth Observation Market
Satellite
All-Electric Satellites Market
Satellite
Israel Satellite Imagery Services Market
Satellite
Asia-Pacific Satellite Attitude and Orbit Control System Market
Satellite
Germany Satellite-Based Earth Observation Market
Satellite
Europe Satellite Attitude and Orbit Control System Market
Satellite
Russia Satellite-Based Earth Observation Market
Satellite
United States Satellite Communications Market