
 Global Satellite Propulsion System Market | 2026-2036
Global Satellite Propulsion System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Satellite Propulsion System Market Outlook
Commercial telecommunications is expanding its share of satellite propulsion procurement as constellation operators replace geostationary orders with distributed low Earth orbit fleets. Lockheed Martin leverages its legacy government contracts to sustain dual-use production lines. ArianeGroup anchors European supply through its Ariane launch family integration. Northrop Grumman Corporation competes on electric propulsion specialization for long-duration missions.
A satellite propulsion system generates thrust via expelled propellant to execute orbital maneuvers, station-keeping, and end-of-life deorbiting; modern electric variants achieve specific impulse exceeding 3000 seconds using xenon or krypton ionization, far surpassing chemical alternatives. Chemical propulsion retains dominance in heavy-lift insertion burns where thrust magnitude outweighs efficiency. Electric propulsion captures margin pools in station-keeping applications where propellant mass savings multiply payload revenue. Hybrid architectures are emerging for missions requiring both high-thrust escape and efficient cruise phases.
FAA licensing requirements govern U.S. commercial launch and on-orbit operations, while ESA procurement standards shape European vendor qualification. ISO 24113 debris mitigation standards constrain propulsion system design for end-of-life disposal. Stakeholders must monitor how ITU spectrum coordination timelines align with constellation deployment schedules.
Market Dynamics
Electric propulsion technology is compressing fuel mass requirements and extending mission durations, fundamentally restructuring procurement economics for constellation operators and government agencies alike. This shift from chemical to ionized propellant systems is redistributing value capture across the supply chain.
Growth Catalysts
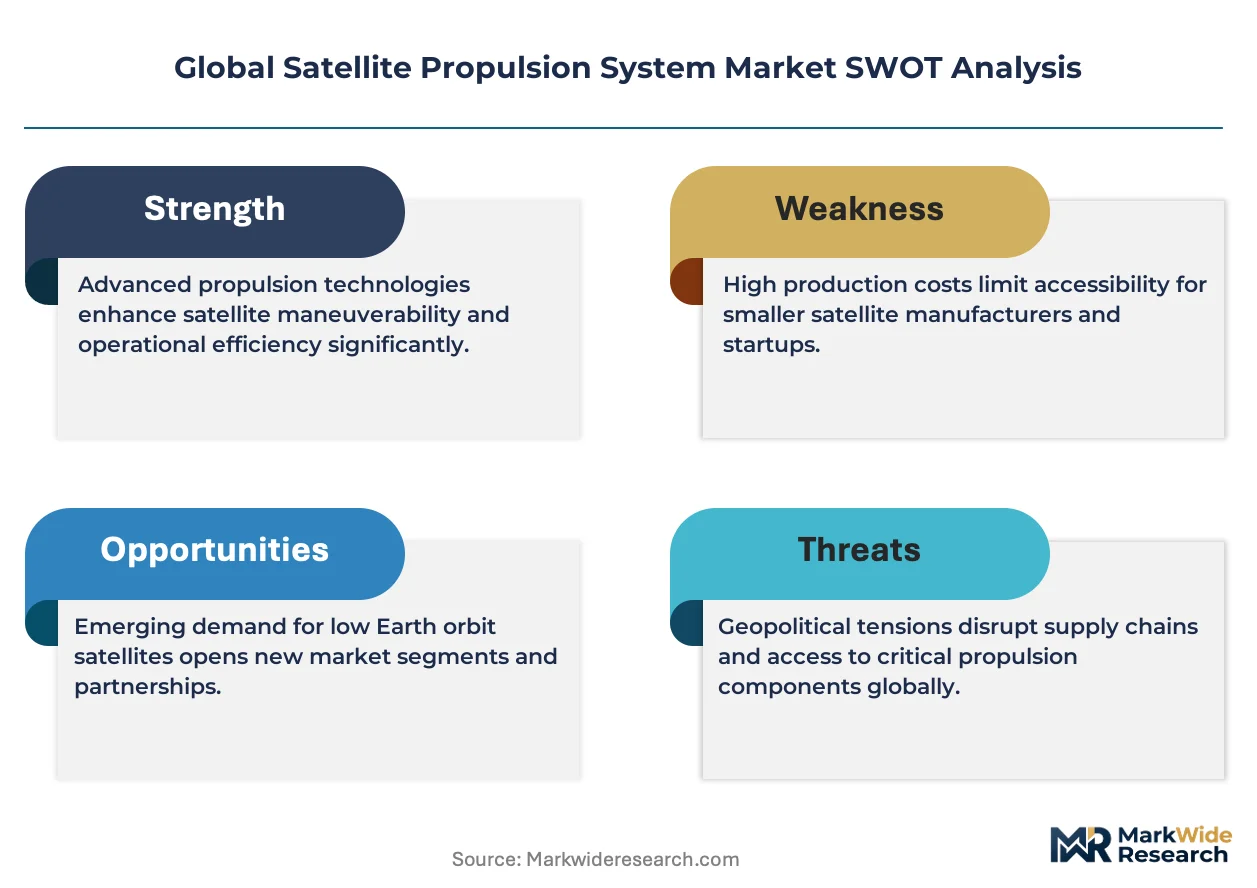
- LEO constellation deployment:Commercial telecommunications operators are procuring distributed satellite fleets at unprecedented scale, creating sustained demand for station-keeping propulsion systems.
- FAA commercial licensing expansion:Streamlined U.S. launch authorization processes are accelerating on-orbit deployment timelines and propulsion system qualification cycles.
- Xenon ionization efficiency gains:Specific impulse exceeding 3000 seconds is enabling multi-year mission extensions without proportional fuel mass increases.
Market Restraints
- Xenon supply concentration:Rare gas extraction is geographically concentrated, exposing propulsion system manufacturers to input cost volatility and allocation constraints.
- Heavy-lift chemical lock-in:Orbital insertion burns require thrust magnitude that electric systems cannot deliver, preserving chemical propulsion dominance for initial deployment.
- ITU spectrum coordination delays:International Telecommunication Union filing backlogs are misaligning constellation deployment schedules with propulsion procurement pipelines.
Strategic Opportunities
- India's space manufacturing expansion:Indian Space Research Organisation vendor qualification programs are opening secondary supply base development for cost-sensitive constellation operators.
- Krypton propellant substitution:Lower-cost noble gas alternatives are expanding into price-competitive mission profiles previously reserved for xenon systems.
- ISO 24113 debris compliance services:End-of-life deorbiting mandates are creating integrated propulsion-disposal service bundles for regulatory adherence.
Industry Challenges
- Electric propulsion engineering scarcity:Specialized plasma physics and ion optics expertise is concentrated among legacy government laboratory alumni, constraining workforce scaling.
- Hybrid architecture integration complexity:Missions requiring both chemical escape burns and electric cruise phases demand unprecedented subsystem interoperability testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Satellite Propulsion System Market |
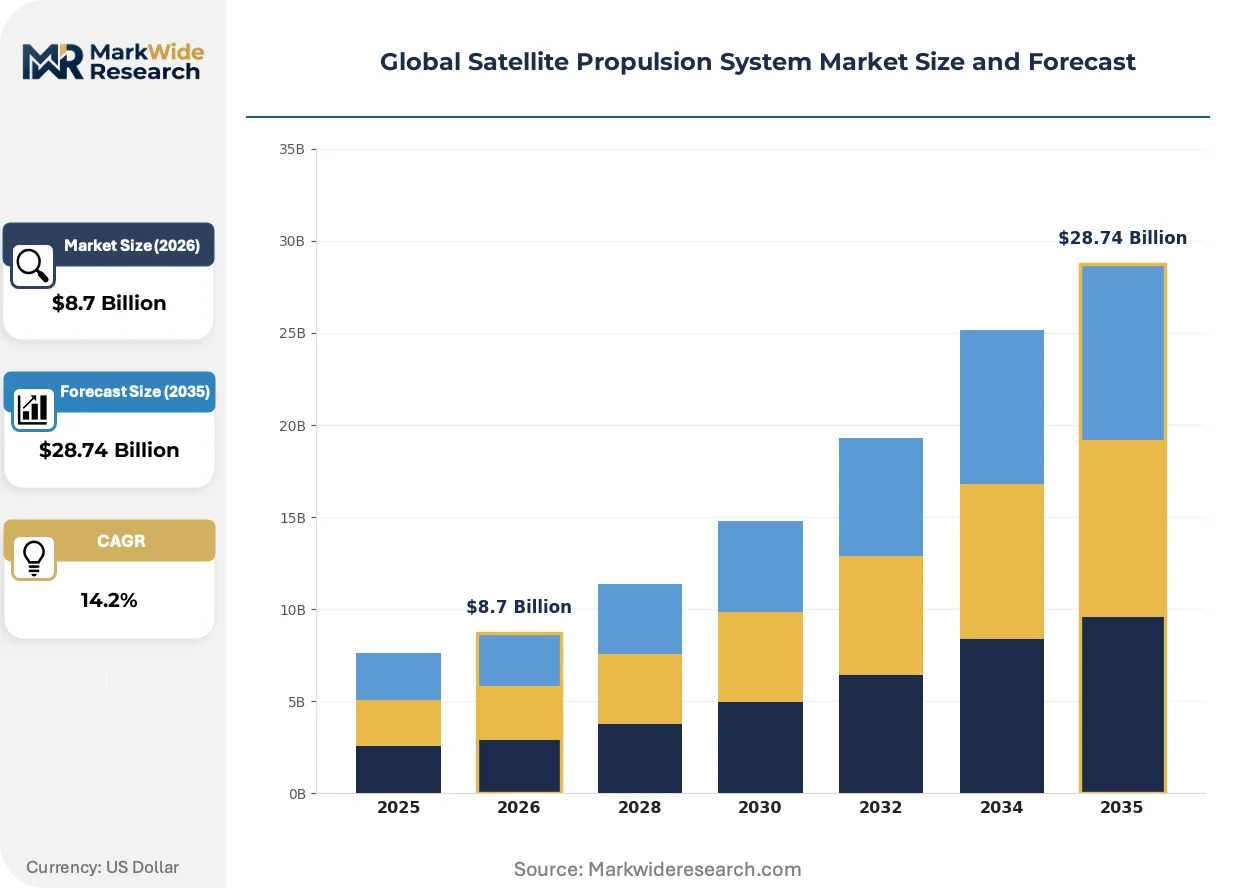
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propulsion Type: Chemical, Electric, Hybrid, Cold Gas End User: Government, Private Sector, Research Institutions, Defense Application: Telecommunications, Earth Observation, Navigation, Scientific Research Component: Thrusters, Controllers, Fuel Tanks, Sensors |
| Companies Covered | Lockheed Martin, ArianeGroup, Northrop Grumman Corporation, L3Harris Technologies, Thales Alenia Space, Safran, Airbus, Dawn Aerospace, Boeing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Satellite Propulsion System Market Strategic Shifts
Propulsion system architectures are bifurcating between high-thrust chemical insertion and high-efficiency electric cruise, with hybrid configurations emerging as the dominant design paradigm for complex orbital profiles.
Gridded ion thruster technology is expanding into geostationary satellite repositioning missions previously served by chemical bi-propellant systems. European and Asian operators are adopting these systems for north-south station-keeping to maximize transponder revenue over extended mission lifetimes. The technology is expanding into medium Earth orbit navigation constellations where fuel mass savings directly translate to additional payload capacity.
REACH chemical substance restrictions are compelling European propulsion manufacturers to reformulate hydrazine alternatives for remaining chemical applications. The regulation is accelerating green propellant qualification programs while grandfathered systems face sunset clauses for new satellite approvals. French and German prime contractors are responding with ammonium dinitramide-based formulations that maintain performance while satisfying ECHA hazard classification thresholds.
Constellation operators are consolidating propulsion procurement under multi-satellite service contracts rather than individual spacecraft component purchases. This model transfers orbit-raising and station-keeping responsibility to subsystem integrators, compressing supplier margins while extending contractual liability windows. The shift is most visible among U.S.-based telecommunications ventures deploying thousands of units on accelerated cadences.
Global Satellite Propulsion System Market Segmentation
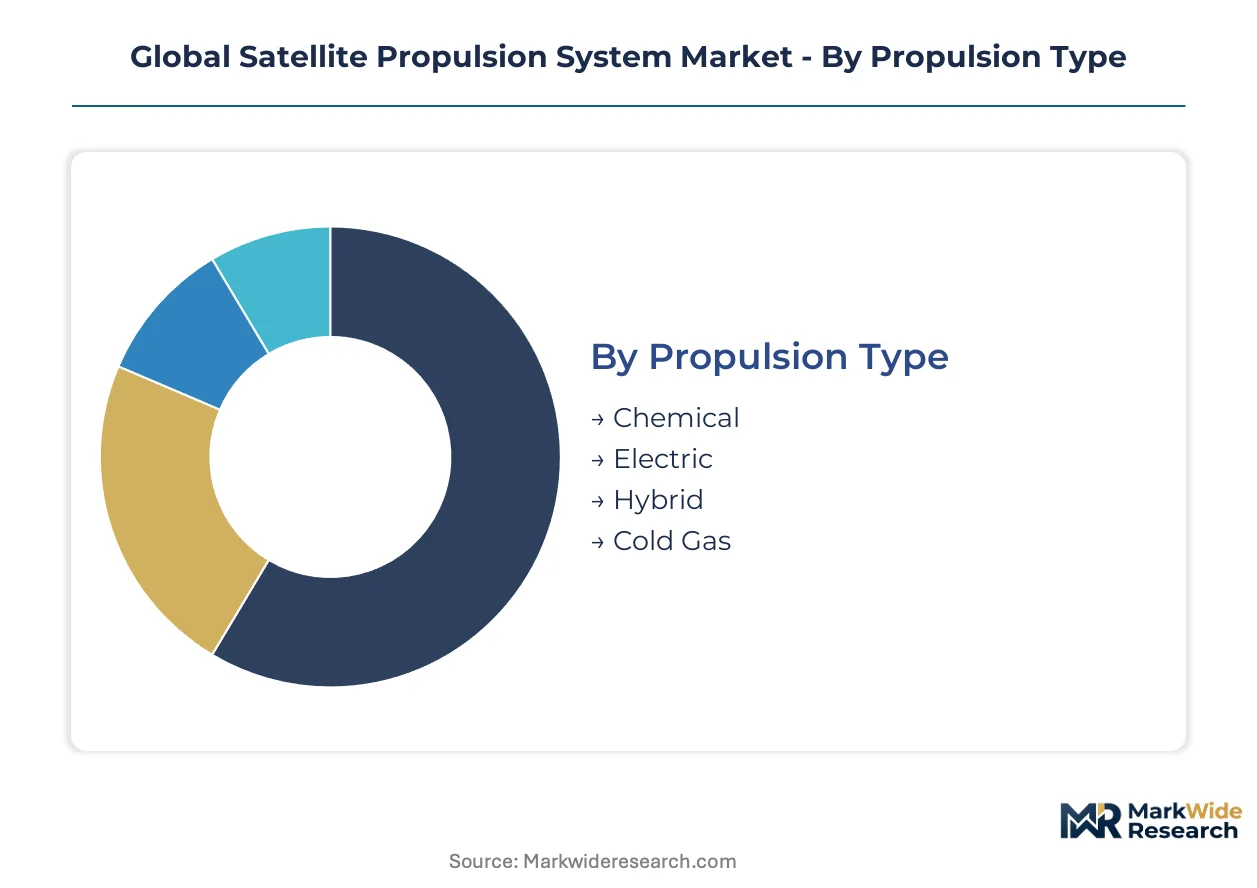
Propulsion system procurement patterns diverge sharply across mission profiles, with constellation operators prioritizing unit economics while government agencies emphasize reliability certifications. Segmentation reveals how electric technology diffusion is redistributing value capture between chemical heritage suppliers and plasma physics specialists.
Propulsion Type:
Volume deployment clusters around mature chemical platforms, while premium capture concentrates in electric variants where specific impulse advantages command pricing power.
- Chemical:Bi-propellant and monopropellant systems using hydrazine or nitrogen tetroxide dominate heavy-lift orbital insertion burns where thrust magnitude exceeds 500 Newtons. Demand from United States Space Force procurement pipelines sustains production lines at legacy suppliers despite efficiency limitations.
- Electric:Gridded ion and Hall-effect thrusters ionize xenon or krypton to achieve specific impulse exceeding 3000 seconds, slashing fuel mass for station-keeping missions. Commercial telecommunications operators in the United States and Europe are consolidating procurement under multi-year service contracts for LEO constellations.
- Hybrid:Dual-mode architectures pair chemical escape burns with electric cruise phases for complex orbital profiles.
- Cold Gas:Compressed nitrogen or argon systems provide precise attitude control for small satellites with minimal complexity.
Mature deployment sits with Chemical systems. Newer deployment is concentrated in Electric variants.
End User:
Government procurement anchors qualification-intensive segments, while private sector orders drive volume scaling and cost reduction curves.
- Government:NASA and national space agencies demand MIL-STD-1540E compliance and heritage flight provenance, extending procurement cycles but preserving margin structures. United States federal procurement pipelines concentrate demand for deep-space missions requiring radiation-hardened controllers.
- Private Sector:Commercial constellation operators prioritize unit cost and supply chain velocity over individual component qualification. SpaceX and Amazon's Project Kuiper procurement patterns in the United States are compressing supplier margins through consolidated multi-satellite contracts.
- Research Institutions:University and laboratory missions favor modular, low-cost propulsion for technology demonstration payloads.
- Defense:Classified missions drive demand for anti-jamming thruster configurations and rapid orbital maneuvering capabilities.
Steepest expansion trajectory belongs to Private Sector procurement, displacing Government share as constellation deployment accelerates.
Application:
Telecommunications missions generate recurring station-keeping demand, while Earth Observation applications emphasize precision pointing and rapid revisit capabilities.
- Telecommunications:Geostationary satellite operators in France and Germany adopt electric propulsion for north-south station-keeping to extend transponder revenue lifetimes. LEO constellation operators require distributed thruster arrays for collision avoidance and constellation phasing maneuvers.
- Earth Observation:Synthetic aperture radar and optical imaging satellites demand precise attitude control for pointing stability. European operators integrate electric propulsion for orbit maintenance to maximize payload operational windows.
- Navigation:Medium Earth orbit constellations require long-duration station-keeping with minimal fuel mass.
- Scientific Research:Deep-space probes and interplanetary missions prioritize specific impulse maximization over thrust magnitude.
Margin concentration aligns with Telecommunications. Technology experimentation concentrates in Scientific Research missions.
Component:
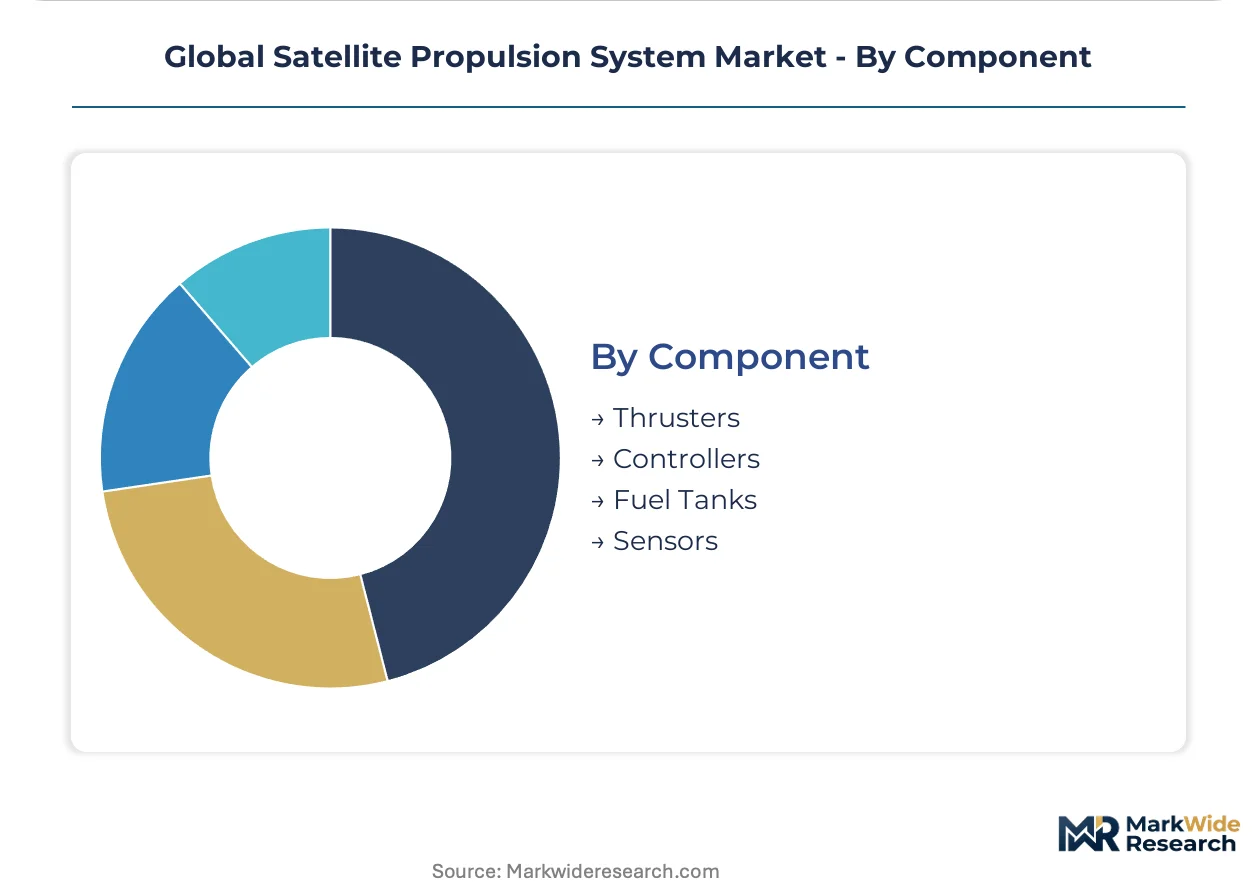
Thruster assemblies capture value through plasma physics specialization, while fuel tank procurement concentrates among aerospace structural suppliers with composite manufacturing expertise.
- Thrusters:Gridded ion and Hall-effect designs require precision-machined discharge chambers and magnetic circuit optimization. Suppliers with heritage from United States government laboratory programs command qualification advantages for electric variants.
- Controllers:Power processing units manage kilovolt-level ionization voltages and closed-loop thrust regulation. European vendors leverage Ariane program heritage for qualification transfer to commercial programs.
- Fuel Tanks:Titanium and composite overwrapped pressure vessels store propellant at pressures exceeding 300 bar.
- Sensors:Flow meters and pressure transducers enable closed-loop propellant management for extended missions.
Supply chain maturity sits with Fuel Tanks. Capability scarcity concentrates in Thrusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spaceport development zones and aerospace special economic districts are concentrating propulsion system manufacturing and qualification activity across multiple continents. Tax incentives tied to launch facility proximity are reshaping supplier location decisions.
United States
NASA and Space Force procurement pipelines sustain demand for radiation-hardened electric propulsion controllers. FAA commercial launch licensing expansion accelerates qualification cycles for station-keeping systems. Huntsville, Alabama and Denver, Colorado anchor manufacturing clusters where legacy government laboratory expertise transfers to commercial constellation programs.
France
Ariane launch family integration requirements preserve domestic chemical propulsion production lines for heavy-lift applications. ESA procurement standards and REACH chemical substance restrictions drive green propellant reformulation programs. Toulouse and Paris-Saclay concentrate gridded ion thruster development for geostationary satellite repositioning missions.
Germany
Medium Earth orbit navigation constellations generate sustained procurement for long-duration station-keeping systems. ECHA hazard classification thresholds accelerate ammonium dinitramide-based propellant qualification. Bavaria and Bremen host electric propulsion specialists serving European telecommunications operators.
Japan
METI space industry development programs support domestic thruster assembly capabilities for Earth observation satellites. JIS standards govern composite overwrapped pressure vessel manufacturing for propellant storage. Tokyo and Nagoya metropolitan areas concentrate precision-machined discharge chamber production.
India
ISRO vendor qualification programs open secondary supply base development for cost-sensitive constellation operators. BIS certification requirements shape domestic manufacturing standards for satellite subsystems. Bengaluru and Hyderabad anchor propulsion component fabrication clusters serving regional launch demand.
Global Satellite Propulsion System Market Competitive Environment
Top-tier vendors anchor government procurement pipelines, while mid-tier specialists capture commercial constellation volume through multi-satellite service contracts. The vendor base stratifies across defense heritage primes, launch-integrated European consortia, and electric propulsion technology specialists. Three archetypes dominate: legacy aerospace conglomerates with MIL-STD qualification advantages, launch-system-integrated European primes, and agile electric propulsion specialists. Competitive moves concentrate on strategic partnerships for hybrid architecture development and geographic expansion into Indian supply base qualification.
Among defense heritage primes, Lockheed Martin and Northrop Grumman Corporation exemplify the tier leveraging government laboratory relationships for electric propulsion qualification transfer. ArianeGroup occupies a position representing launch-system-integrated European supply consolidation. These three anchors illustrate how qualification heritage and launch integration access determine competitive positioning across chemical and electric propulsion segments.
| Leading Market Players |
|---|
| Lockheed Martin |
| ArianeGroup |
| Northrop Grumman Corporation |
| L3Harris Technologies |
| Thales Alenia Space |
| Safran |
| Airbus |
| Dawn Aerospace |
| Boeing |
| Others |
Value Chain & Pricing Dynamics
Electric-to-chemical performance divergence splits procurement economics between heritage chemical suppliers and plasma physics specialists, with qualification premiums concentrating among United States government laboratory alumni while constellation operators compress unit costs through multi-satellite service contracts. This tiering manifests in supply chain geography—radiation-hardened controller production clusters near NASA and Space Force procurement pipelines, whereas commercial thruster assembly disperses toward Indian vendor qualification programs.
Pricing Analysis
Short lead-time premiums attach to radiation-hardened electric propulsion controllers serving United States Space Force procurement pipelines, while spot inventory discounts emerge for chemical bi-propellant systems with established production lines. Three-tier pricing structure across heritage-qualified, commercial-electric, and commodity-chemical levels tracks certification grade and flight provenance. Pricing pressure stems from constellation operators consolidating procurement under multi-satellite service contracts. Commercial telecommunications ventures exhibit highest price sensitivity; government agencies prioritize MIL-STD-1540E compliance over unit cost.
Supply Chain Analysis
Regional distribution centers for xenon and krypton propellant concentrate near extraction facilities in Russia, Ukraine, and Qatar, with secondary processing nodes in the United States and Germany. Thruster discharge chamber fabrication draws from titanium machining clusters in Japan and precision optics capabilities in France. Single-source vulnerability runs through geographically concentrated rare gas extraction. Distribution runs through launch-system-integrated primes for government missions and direct-to-constellation-operator channels for commercial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 24113 debris mitigation standards erect cost-of-compliance barriers that grandfathered chemical propulsion suppliers must surmount through green propellant reformulation, advantaging early movers in ammonium dinitramide-based systems.
For Market Incumbents: Extend qualification heritage into commercial constellation service contracts by transferring MIL-STD-1540E compliance frameworks to multi-satellite procurement models. Lockheed Martin and Northrop Grumman Corporation exemplify this pathway. Capacity addition in Indian vendor qualification programs captures cost-sensitive volume without diluting premium tier positioning. Electric propulsion engineering scarcity constrains workforce scaling—secure plasma physics talent through government laboratory alumni networks before competitive bidding intensifies. For New Entrants and Emerging Players: Enter via krypton propellant substitution for price-competitive mission profiles previously reserved for xenon systems, exploiting rare gas supply concentration as entry wedge. India's ISRO vendor qualification programs offer the most penetrable geography for secondary supply base development. Target Earth observation operators seeking precise attitude control with modular cold gas thruster configurations. Go-to-market angle: bundle propulsion-disposal services for ISO 24113 compliance, transferring regulatory adherence risk from satellite operators to subsystem integrators. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by launch-system-integrated primes seeking electric propulsion capability gaps—ArianeGroup's European supply consolidation provides the archetype. Five-to-ten year viability hinges on hybrid architecture qualification for missions requiring both chemical escape burns and electric cruise phases. Acquisition target archetype: agile electric propulsion specialists with Hall-effect thruster heritage and existing NASA technology transfer agreements. Signal to watch: ITU spectrum coordination backlog resolution accelerating constellation deployment schedules and propulsion procurement pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Green Propellant Qualification Program | REACH chemical substance restrictions in Europe accelerate ammonium dinitramide-based formulation adoption. |
| Hybrid Architecture Development Partnership | Dual-mode chemical-electric systems address complex orbital profiles beyond single-technology limitations. |
| Multi-Satellite Service Contract Consolidation | SpaceX and Amazon's Project Kuiper procurement patterns transfer orbit-raising responsibility to integrators. |
| Indian Supply Base Qualification | ISRO vendor programs open secondary manufacturing for cost-sensitive constellation operators. |
| Debris Compliance Service Bundling | ISO 24113 end-of-life mandates create integrated propulsion-disposal offerings for regulatory adherence. |
Study Parameters
Multi-period observation of constellation deployment cadences, ITU spectrum filing timelines, and ESA procurement award patterns anchored the trend analysis, supplemented by interviews with satellite propulsion engineering directors, constellation operator procurement leads, ESA technology officers, FAA commercial licensing specialists, and ISRO vendor qualification managers. Secondary validation drew from FAA launch licensing databases, ESA contract award registries, ITU satellite network filings, ISO 24113 implementation guidelines, and SEC filings of publicly traded aerospace primes. Bottom-up unit economics modeling triangulated against top-down market sizing from government procurement pipeline disclosures.
Input-output matrices mapped propulsion system component demand across thruster assemblies, power processing units, and composite overwrapped pressure vessels against constellation deployment schedules and deep-space mission timelines. Segmentation dimensions encompassed propulsion type, end user archetype, application mission profile, and regional regulatory cluster. CAGRs derived from regression analysis of historical procurement volumes against projected launch manifests and technology substitution curves. Industry-specific forecast inputs included xenon spot price volatility indices and ITU coordination timeline distributions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ITU spectrum coordination delays, xenon supply disruption scenarios, and hybrid architecture qualification failures. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
VSAT Maritime Satellite Communication Market
Satellite
Flat Panel Satellite Antenna Market
Satellite
United States Satellite Communications Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
Russia Satellite-Based Earth Observation Market
Satellite
ASEAN Satellite Imagery Services Market
Satellite
Satellite Link Emulator Market
Satellite
Satellite Transponder Market
Satellite
Middle East Satellite-Based Earth Observation Market
Satellite
Optical Satellite Communication Market
Satellite
United Arab Emirates Satellite-Based Earth Observation Market
Satellite
Nano and Microsatellite Market
Satellite
Europe Satellite IoT Market
Satellite
Small Satellite Market
Satellite
Mexico Satellite Connectivity Market
Satellite
Argentina Satellite-Based Earth Observation Market