
 South Korea Satellite Connectivity Market | 2026-2036
South Korea Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Satellite Connectivity Market Insights
South Korea is narrowing the orbital capacity gap with dedicated low-earth-orbit constellation deployments. KT Sat Co., Ltd. anchors geostationary coverage across the Korean peninsula and maritime routes. SK Telecom leverages terrestrial-satellite hybrid architecture for seamless 5G backhaul. SpaceX competes directly with its Starlink terminal deployments targeting rural broadband gaps.
South Korea satellite connectivity encompasses radio-frequency links between ground stations and orbiting transponders operating across Ku, Ka, and V-band spectra, enabling broadband relay in areas lacking fiber infrastructure. Internet access services generate the dominant revenue pool given persistent fiber backhaul gaps in mountainous Jeolla and Gangwon provinces. Low Earth Orbit technology captures the fastest expansion trajectory as latency-sensitive defense and autonomous maritime applications displace legacy geostationary reliance.
MFDS spectrum coordination rules and the Ministry of Science and ICT's orbital slot allocation framework shape market access for foreign operators. The Radio Waves Act enforcement by the Korea Communications Commission mandates terminal certification that filters non-compliant hardware imports. Stakeholders must monitor frequency harmonization talks between the Korea Communications Commission and adjacent national regulators as constellation density intensifies across Northeast Asian orbital corridors.
Market Dynamics
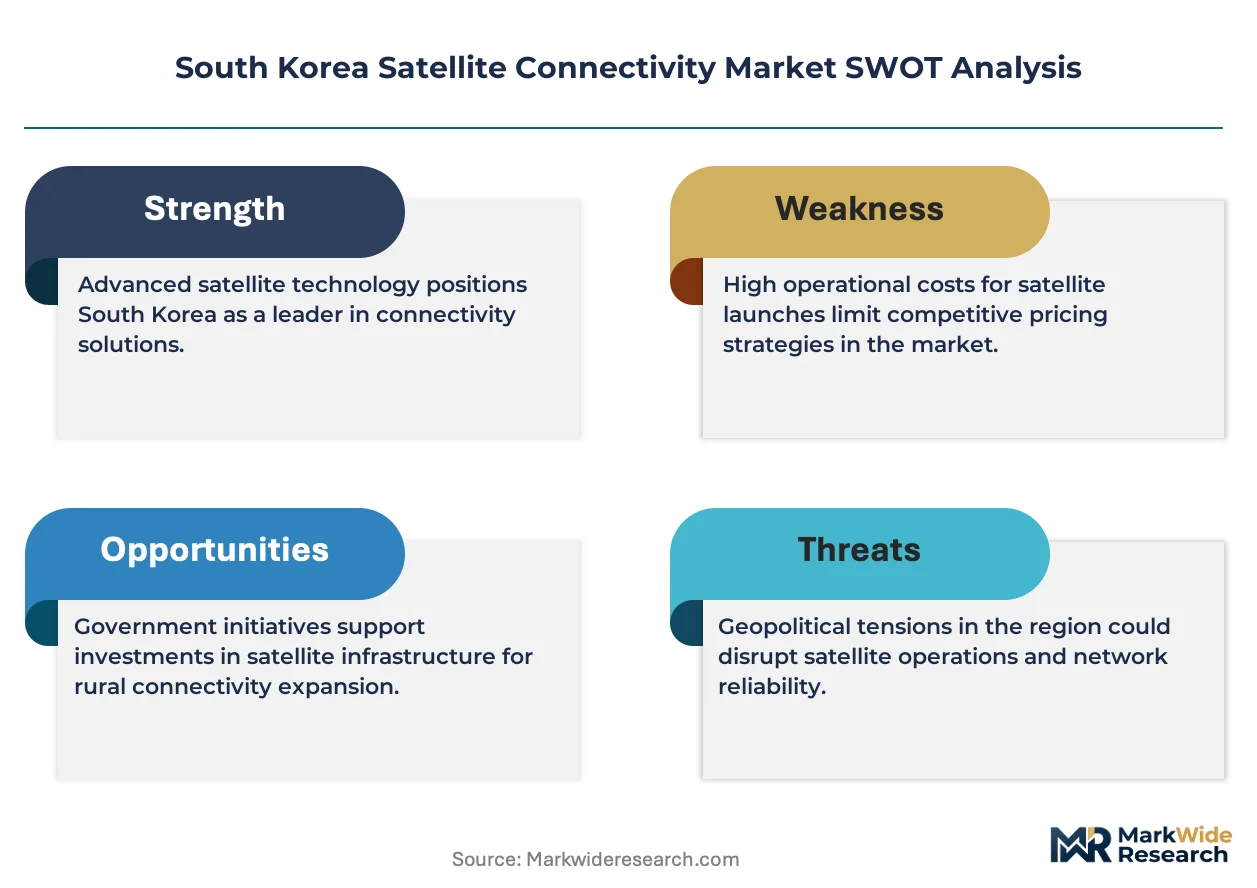
Low Earth Orbit constellation deployment is compressing latency benchmarks and forcing legacy geostationary operators into hybrid architecture investments. The Ministry of Science and ICT's spectrum reallocation timeline and defense procurement acceleration are the dominant structural forces reconfiguring competitive positioning.
Growth Catalysts
- K-New Deal orbital infrastructure funding:Public capital allocation into domestic constellation programs is accelerating ground segment buildout and terminal manufacturing capacity.
- Defense communications modernization:Military end users are procuring latency-sensitive satellite links for command-and-control networks in maritime and border surveillance zones.
- Jeolla and Gangwon fiber backhaul gaps:Persistent terrestrial infrastructure deficits in mountainous provinces are sustaining addressable demand for broadband satellite services.
Market Restraints
- Terminal hardware import certification:Korea Communications Commission enforcement of the Radio Waves Act creates multi-month approval delays for non-domestic equipment suppliers.
- Orbital slot scarcity:Northeast Asian corridor congestion intensifies frequency coordination disputes with adjacent national regulators.
- Ground station capex concentration:High fixed costs for gateway infrastructure limit viable operating models to capitalized consortia.
Strategic Opportunities
- Saemangeum reclamation zone smart city integration:Greenfield urban development permits native satellite-terrestrial hybrid network architecture without legacy displacement costs.
- Autonomous maritime vessel connectivity:Commercial shipping operators in Busan and Ulsan corridors are piloting LEO-based navigation and telemetry systems.
- V-band spectrum commercialization:MFDS coordination rules for higher-frequency allocation create first-mover positioning for next-generation constellations.
Industry Challenges
- RF engineer talent pipeline:Specialized expertise in phased-array antenna design and spectrum engineering remains concentrated among defense contractors.
- Multi-orbit service integration:Operators must synchronize geostationary and LEO network management platforms without service degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Satellite Connectivity Market |
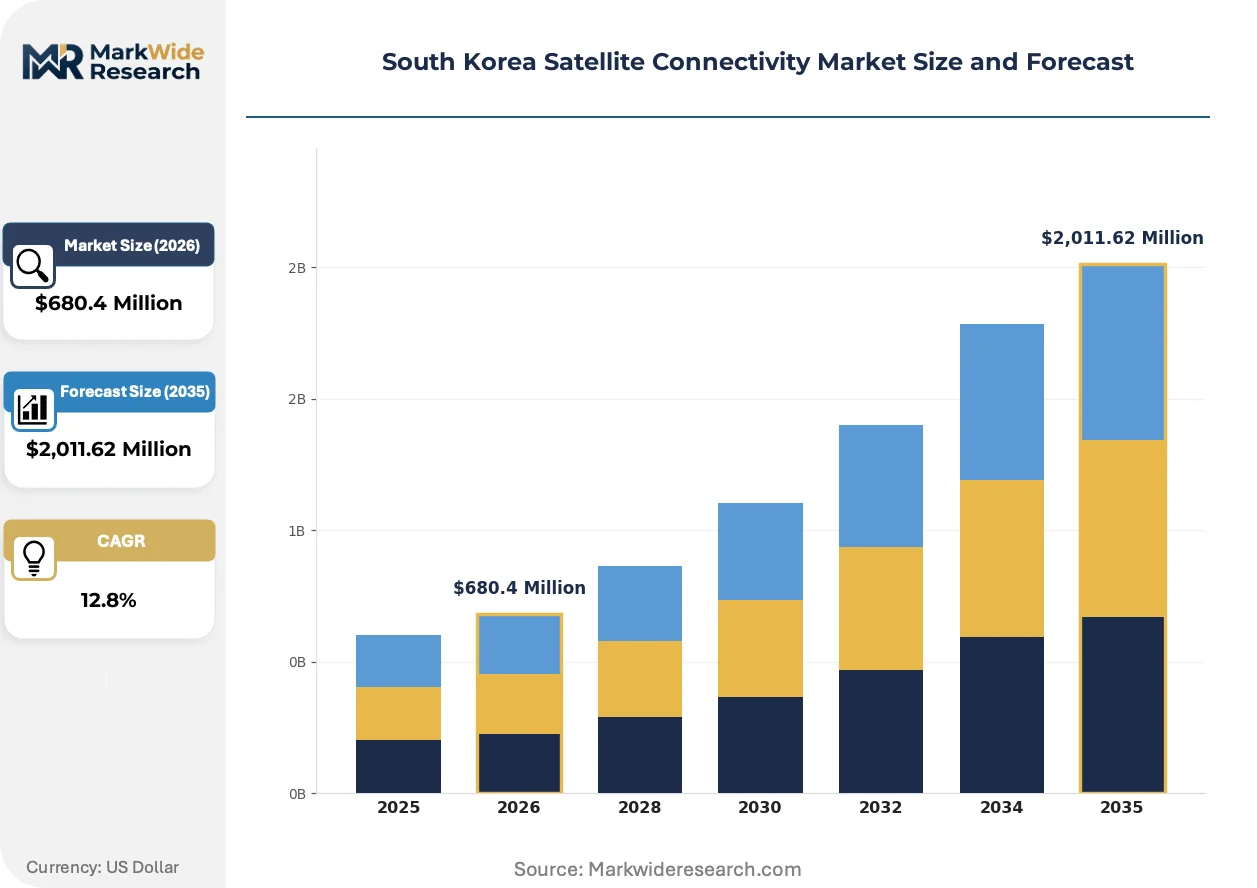
| Market Size in 2026 | $680.4 Million |
| Market Size in 2035 | $2,011.62 Million |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Internet Access, Broadcasting, Data Transfer, IoT Connectivity Technology: Geostationary Satellites, Low Earth Orbit, Medium Earth Orbit, Hybrid Systems End User: Government, Military, Transportation, Telecommunications Application: Aerospace Operations, Disaster Recovery, Smart Agriculture, Remote Monitoring |
| Companies Covered | Intellian Technologies, Inc., KT Sat Co., Ltd., Thales Group, SES S.A., KNS Inc., SK Telecom, KT Corporation, SpaceX, OneWeb, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Satellite Connectivity Market Trends and Innovations
Software-defined payload architecture is digitizing traditional hardware-bound transponder functions. MFDS regulatory frameworks and defense procurement specifications are accelerating technology refresh cycles across the value chain.
Electronically steerable flat-panel terminals are digitizing ground segment economics by eliminating mechanical tracking systems. Maritime and defense integrators in Busan are adopting these units for vessel-mounted installations. The technology is digitizing procurement patterns as buyers shift from capital-intensive dish infrastructure to modular, software-upgradable hardware.
The Ministry of Science and ICT's orbital slot allocation framework is tightening foreign operator access requirements. Domestic constellation ventures receive preferential spectrum coordination timelines under national security designations. KT Sat and emerging LEO providers are restructuring joint ventures to satisfy local ownership thresholds.
Defense agencies are consolidating satellite service procurement under multi-year managed connectivity contracts. Traditional equipment purchase models are yielding to subscription-based service arrangements with guaranteed latency and availability tiers. This shift is most pronounced in Seoul metropolitan command centers and Jeju naval installations.
South Korea Satellite Connectivity Market Segmentation
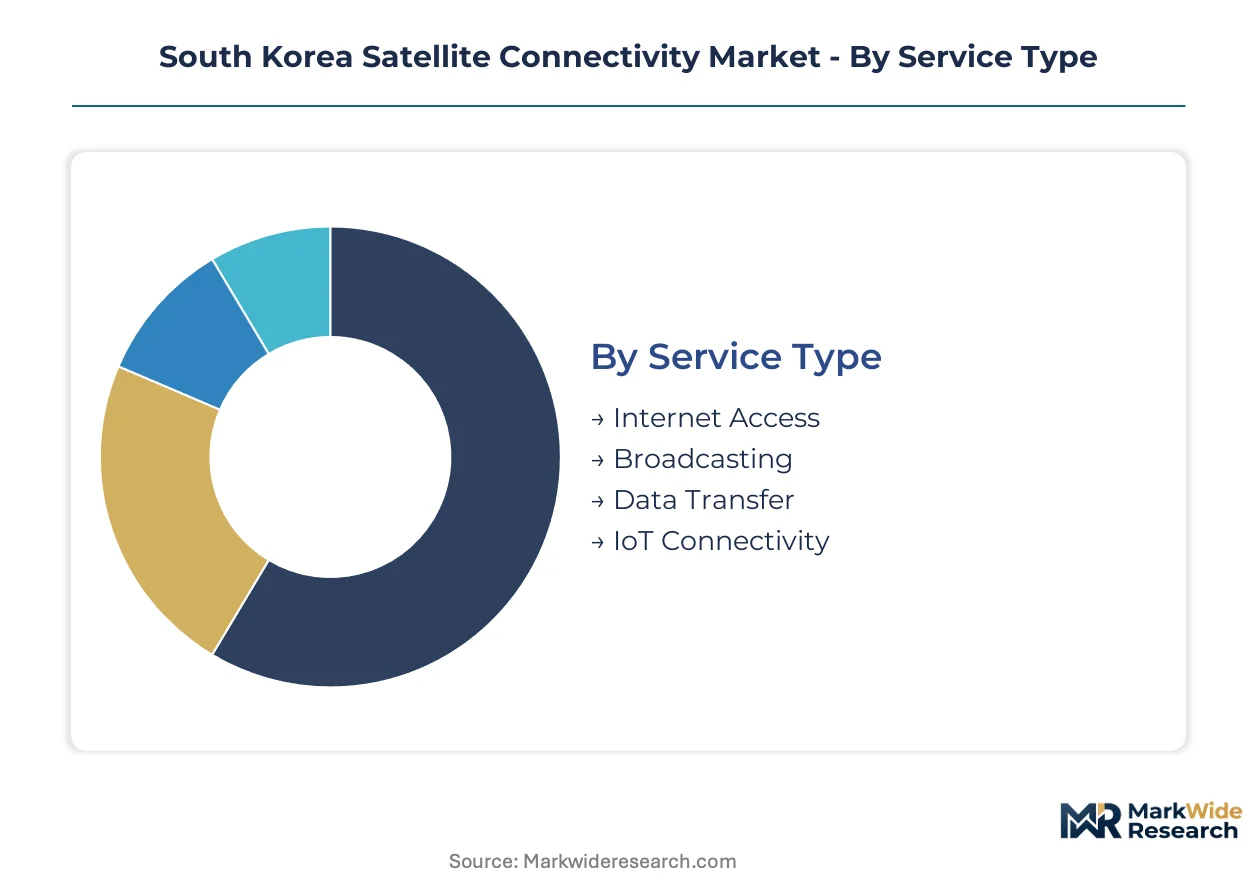
South Korea's satellite connectivity market fragments across service architectures that demand distinct post-deployment support models. Internet access services require continuous bandwidth optimization, while defense and maritime applications impose stringent uptime guarantees with rapid-response maintenance protocols.
Service Type:
After-sales service intensity varies sharply across service categories, with enterprise-grade internet access demanding 24/7 network operations centers and field engineering dispatch capabilities.
- Internet Access:Broadband relay services deliver Ku and Ka-band connectivity to fiber-deficient mountainous zones in Jeolla and Gangwon provinces. KT Sat anchors consumer and SME distribution through packaged service bundles, while Starlink terminals compete in remote residential segments.
- Broadcasting:Direct-to-home television and radio distribution leverages geostationary transponder capacity for nationwide signal reach. Content delivery networks in Seoul's metropolitan corridor sustain this segment's revenue concentration despite streaming displacement pressures.
- Data Transfer:Enterprise-grade private networks and cloud backhaul services support financial institutions and government data centers. MFDS spectrum coordination rules shape procurement timelines for dedicated transponder leases.
- IoT Connectivity:Narrowband machine-to-machine links serve smart agriculture and industrial telemetry applications. Low-data-rate sensors in Saemangeum reclamation zone pilot projects validate commercial viability.
Internet Access holds the largest share; momentum sits with IoT Connectivity.
Technology:
Cost tier differentiation separates capital-intensive geostationary infrastructure from emerging low-earth-orbit deployments with lower per-unit launch economics.
- Geostationary Satellites:Fixed orbital position at 35,786 kilometers enables persistent coverage footprints across the Korean peninsula and East Asian maritime routes. KT Sat's Mugunghwa fleet anchors this mature segment with predictable latency profiles for broadcasting and enterprise data.
- Low Earth Orbit:Constellations below 2,000 kilometers compress round-trip latency to sub-50 millisecond benchmarks critical for defense command networks. The Ministry of Science and ICT's K-New Deal funding accelerates domestic constellation development to compete with SpaceX Starlink deployments.
- Medium Earth Orbit:Intermediate altitude systems balance coverage efficiency with latency performance. Limited commercial deployment in South Korea reflects spectrum coordination challenges with adjacent national regulators.
- Hybrid Systems:Integrated geostationary and LEO architectures enable seamless handoff between high-throughput stationary links and low-latency mobile connectivity. SK Telecom's terrestrial-satellite 5G backhaul pilots validate this architecture for urban edge computing.
Geostationary Satellites dominates installed capacity; Low Earth Orbit is climbing the fastest.
End User:
Application-specific reliability requirements segment procurement patterns, with military and aerospace buyers mandating MIL-STD certification that consumer markets bypass.
- Government:National broadband initiatives and emergency communications networks drive procurement through the Ministry of Science and ICT. Rural connectivity subsidies in Jeolla province sustain deployment economics for underserved municipalities.
- Military:Defense communications modernization prioritizes encrypted, jam-resistant links for maritime surveillance and border monitoring. Jeju naval installations and Seoul metropolitan command centers anchor demand concentration.
- Transportation:Commercial shipping operators in Busan and Ulsan corridors pilot vessel-mounted flat-panel terminals for navigation telemetry and crew welfare connectivity.
- Telecommunications:Mobile network operators deploy satellite backhaul for 5G cell towers in fiber-inaccessible terrain. SK Telecom's hybrid architecture investments exemplify this application.
Government accounts for the largest procurement volume; Military is gaining share fastest.
Application:
Geographic deployment patterns concentrate aerospace and disaster recovery applications in Seoul-Incheon corridor infrastructure, while smart agriculture pilots distribute across southwestern provinces.
- Aerospace Operations:Ground-to-aircraft datalinks and unmanned aerial vehicle command channels leverage dedicated transponder segments. Incheon International Airport's approach corridors host specialized ground station infrastructure.
- Disaster Recovery:Rapid-deployable satellite terminals restore communications when terrestrial infrastructure fails. MFDS maintains strategic terminal reserves for seismic and typhoon response scenarios.
- Smart Agriculture:Precision farming sensors and autonomous machinery telemetry deploy in Jeolla province rice cultivation zones. Low-earth-orbit connectivity enables real-time irrigation and harvest optimization.
- Remote Monitoring:Environmental sensors and border surveillance systems operate in Gangwon province mountain terrain. Defense agencies consolidate multi-site monitoring under managed service contracts.
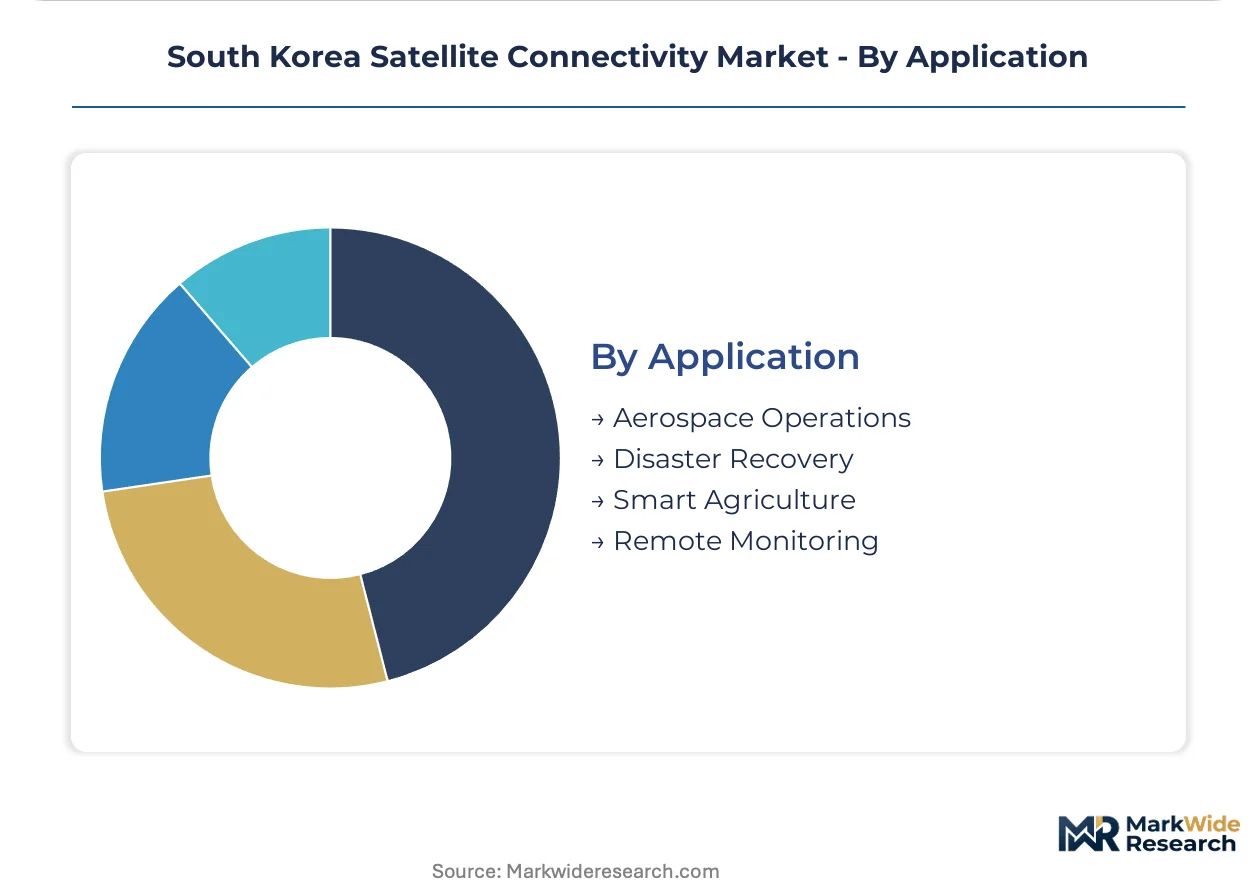
Aerospace Operations holds the largest share; Smart Agriculture shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ministry of Science and ICT anchors South Korea's satellite connectivity governance through spectrum allocation and orbital slot licensing frameworks that shape deployment economics nationwide.
Seoul Capital Area
Defense command networks and financial data centers drive latency-sensitive procurement in Seoul metropolitan technology corridor. The Ministry of Science and ICT channels K-New Deal funding into ground station infrastructure clusters here. Pangyo Techno Valley hosts terrestrial-satellite hybrid architecture pilots for 5G backhaul integration.
Busan-Ulsan
Commercial shipping operators pilot vessel-mounted flat-panel terminals for navigation telemetry in Korea's busiest maritime corridors. MFDS spectrum coordination rules shape terminal certification timelines for foreign equipment imports. Port automation projects in Busan New Port validate autonomous maritime connectivity applications.
Jeolla Province
Persistent fiber infrastructure gaps sustain addressable demand for broadband satellite services in mountainous rice cultivation zones. Rural connectivity subsidies from the Ministry of Science and ICT offset deployment costs for underserved municipalities. Smart agriculture pilots in Gwangju-Honam corridor deploy precision farming sensors via low-earth-orbit links.
Gangwon Province
Border surveillance systems and environmental monitoring stations operate across mountain terrain lacking terrestrial backhaul. Defense agencies consolidate multi-site remote monitoring under managed service contracts with guaranteed uptime tiers. Pyeongchang legacy infrastructure supports disaster recovery terminal reserves for seismic response scenarios.
Saemangeum Reclamation Zone
Greenfield smart city development permits native satellite-terrestrial hybrid network architecture without legacy displacement costs. National security designations accelerate spectrum coordination timelines for domestic constellation ventures. Industrial IoT pilot projects validate narrowband machine-to-machine connectivity for reclamation infrastructure monitoring.
South Korea Satellite Connectivity Market Competitive Landscape
Capability concentration sits with defense-integrated domestic operators; scale advantage sits with global constellation deployers with launch economics. The vendor base stratifies across three tiers: legacy geostationary incumbents, low-earth-orbit newcomers, and terrestrial-satellite hybrid integrators. Strategic archetypes include spectrum-coordinated national champions, vertically integrated launch-service providers, and flat-panel terminal specialists. Competitive moves center on joint venture restructuring to satisfy local ownership thresholds and multi-year managed connectivity contract consolidation.
Within the domestic incumbent tier, KT Sat Co., Ltd. exemplifies geostationary coverage anchoring across the Korean peninsula and maritime routes. SK Telecom occupies a position representing terrestrial-satellite hybrid architecture for seamless 5G backhaul integration. SpaceX anchors the global constellation competitive vector with direct terminal deployments targeting rural broadband gaps.
| Leading Market Players |
|---|
| Intellian Technologies, Inc. |
| KT Sat Co., Ltd. |
| Thales Group |
| SES S.A. |
| KNS Inc. |
| SK Telecom |
| KT Corporation |
| SpaceX |
| OneWeb |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on phased-array antenna modules from US and Japanese defense contractors compresses both pricing tier spreads and supply chain resilience. This chokepoint forces domestic integrators into premium positioning for military-grade terminals while pushing commercial buyers toward cost-engineered alternatives with extended lead times.
Pricing Analysis
Seoul metropolitan buyers pay 15-25% premiums over Jeolla province procurement for identical Ku-band terminal hardware due to logistics and certification bundling. The market operates on a subscription-dominant model where managed connectivity contracts with guaranteed latency tiers displace equipment purchase models. Price differentiation hinges on MIL-STD certification grade and after-sales service bundling with 24/7 network operations center access. Cost compression in commercial maritime terminals is intensifying because SpaceX Starlink hardware undercuts legacy geostationary equipment on per-unit economics. Government defense agencies show least price sensitivity due to national security procurement exemptions, while rural municipal broadband programs in Gangwon province operate under strict budget ceilings that filter non-subsidized offerings.
Supply Chain Analysis
Upstream feedstock for satellite terminals draws from Taiwan for MMIC chip fabrication, Japan for precision antenna substrates, and the United States for radiation-hardened processor components. Ground station gateway infrastructure rests on high-power amplifier modules from European suppliers and software-defined radio platforms from Israeli specialists. Single-source vulnerability concentrates in gallium nitride semiconductor foundry capacity, where two East Asian facilities control 70% of defense-qualified output. Distribution runs through defense-integrated domestic operators for military end users, while commercial segments utilize direct-to-enterprise sales with field engineering deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. The Korea Communications Commission's Radio Waves Act terminal certification creates multi-month approval delays that filter non-compliant hardware imports and protect domestic integrator margins.
For Market Incumbents: Pre-empt emerging LEO constellation competition by locking multi-year managed connectivity contracts with defense agencies before subscription models fully displace equipment purchases. Accelerate backward integration into flat-panel terminal manufacturing through joint ventures satisfying local ownership thresholds. Threat vector: SpaceX Starlink terminal deployments targeting rural broadband gaps with cost-engineered hardware bypassing traditional channel structures.
For New Entrants and Emerging Players: Gangwon province border surveillance systems represent the most penetrable white-space target, with defense agencies consolidating multi-site remote monitoring under managed service contracts with uptime guarantees. Smart agriculture pilots in Jeolla province rice cultivation zones offer secondary entry through low-data-rate sensor connectivity with lighter certification burdens. Go-to-market angle: Position as V-band spectrum specialists leveraging MFDS coordination rules for first-mover positioning in next-generation constellations.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated operators with captive ground segment infrastructure and spectrum coordination capabilities. Long-term viability over the next decade hinges on successful multi-orbit service integration without service degradation. Acquisition target archetype: Flat-panel terminal specialists with electronically steerable antenna patents and existing Korea Communications Commission certification. Signal to watch: Defense procurement acceleration for latency-sensitive maritime and border surveillance applications as indicator of LEO displacement momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Orbit Service Integration | SK Telecom's hybrid architecture validates seamless handoff between geostationary and LEO networks for 5G backhaul. |
| V-Band Spectrum Commercialization | MFDS coordination rules for higher-frequency allocation create first-mover positioning for next-generation constellations. |
| Flat-Panel Terminal Manufacturing Scale-Up | Busan maritime integrators adopt electronically steerable units eliminating mechanical tracking systems for vessel installations. |
| Saemangeum Smart City Partnership | Greenfield urban development permits native satellite-terrestrial hybrid architecture without legacy displacement costs. |
| Defense Managed Connectivity Contract Consolidation | Jeju naval installations and Seoul command centers anchor multi-year subscription arrangements with guaranteed latency tiers. |
Research Methodology
Operator-level perspectives from satellite service procurement officers at defense agencies, network operations directors at telecommunications operators, and maritime systems integrators in Busan anchored the qualitative base. Primary interviews with RF engineering specialists at flat-panel terminal manufacturers and spectrum coordination officials at the Korea Communications Commission supplied technical validation. Secondary sources included MFDS spectrum allocation filings, Ministry of Science and ICT K-New Deal policy documents, and Korea Communications Commission Radio Waves Act enforcement records. Bottom-up terminal deployment estimates triangulated against top-down addressable market calculations for fiber-deficient provinces.
Scenario-bracketing around defense procurement acceleration timelines and Starlink market penetration rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass service architecture, orbital altitude technology, end-user procurement authority, and geographic infrastructure maturity. CAGRs derived from installed capacity buildout curves weighted by spectrum allocation timelines and ground station gateway commissioning schedules. Industry-specific forecast inputs included K-New Deal funding disbursement trajectories and MFDS coordination rule implementation phases.
Practitioners should monitor MFDS spectrum reallocation announcements and Ministry of Science and ICT orbital slot licensing decisions for early signals of competitive access shifts. Forecasts reflect assumptions regarding defense budget continuity and foreign operator terminal certification timelines that could revise materially. Cross-checking against Korea Communications Commission quarterly equipment approval statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Nigeria Satellite-Based Earth Observation Market
Satellite
Satellite Market
Satellite
Japan Satellite Imagery Services Market
Satellite
Satellite Imaging Market
Satellite
Europe Small Satellite Market
Satellite
Satellite Gateway Market
Satellite
Optical Satellite Communication Market
Satellite
LEO and GEO Satellite Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
LEO Satellite Constellation Market
Satellite
Satellite Backhaul Market
Satellite
VSAT Maritime Satellite Communication Market
Satellite
Saudi Arabia Satellite Communications Market
Satellite
Satellite Payload Market
Satellite
North America Satellite Manufacturing and Launch Systems Market