
 India Satellite-Based Earth Observation Market | 2026-2036
India Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
India Satellite-Based Earth Observation Market Insights
India's National Geospatial Policy is realigning procurement standards for satellite imagery across government departments. ISRO leverages its end-to-end launch and spacecraft manufacturing infrastructure to dominate upstream supply. Pixxel specializes in hyperspectral imaging constellations, differentiating its spectral resolution for mineral and agricultural surveys. GalaxEye competes on SAR-optical fusion technology, positioning its payloads for all-weather monitoring contracts.
India satellite-based earth observation encompasses spacecraft, ground segment infrastructure, and downstream analytics that capture multispectral, hyperspectral, SAR, and optical imaging data at resolutions from sub-meter to coarse scale for terrestrial and atmospheric monitoring. The primary commercial purpose centers on converting raw orbital data into actionable intelligence for agriculture yield forecasting, urban encroachment detection, and flood damage assessment. Data analytics and geospatial services command expanding margin pools as government buyers shift from raw imagery procurement to decision-ready dashboards. SAR technology leads in defense and all-weather disaster applications, while hyperspectral adoption accelerates among precision agriculture users seeking crop stress detection.
ISRO's remote sensing data policy, BIS standards for geospatial data quality, and India's National Geospatial Policy collectively shape product certification requirements and cross-border data sharing protocols for private operators. The Securities and Exchange Board of India and Department of Space coordinate on foreign investment screening for earth observation ventures, affecting market access timelines for international firms. Stakeholders must monitor evolving clearance thresholds for high-resolution imagery and emerging state-level geospatial missions that could fragment procurement standards.
Market Dynamics
India's National Geospatial Policy is compressing procurement cycles for satellite imagery by mandating standardized data formats across central and state agencies. This regulatory push is forcing private operators to reconfigure ground segment infrastructure for seamless interoperability with ISRO's existing constellation networks.
Growth Catalysts
- Liberalized Remote Sensing Guidelines:India's Department of Space relaxed resolution thresholds for private satellite operators, enabling sub-meter commercial imaging without case-by-case clearance.
- State Remote Sensing Centers:Karnataka and Gujarat have established dedicated procurement cells for satellite-based crop monitoring and flood early warning systems.
- Hyperspectral Imaging:Agricultural departments in Punjab and Haryana are deploying spectral analysis for nitrogen stress detection in wheat and rice cultivation.
Market Restraints
- Launch Infrastructure Bottleneck:ISRO's PSLV and GSLV manifest priorities for government missions create 18-24 month waiting periods for private satellite deployment.
- Ground Segment Capital Intensity:Establishing X-band and S-band receiving stations in Tamil Nadu and Rajasthan requires land acquisition clearances under state environmental regulations.
- High-Resolution Imagery Restrictions:India's BIS quality standards and defense ministry screening protocols limit commercial distribution of sub-0.5 meter data near border corridors.
Strategic Opportunities
- North-Eastern States:Assam and Meghalaya lack dedicated remote sensing infrastructure for landslide monitoring and hydropower reservoir management.
- Carbon Credit Verification:India's Bureau of Energy Efficiency is exploring satellite-based biomass estimation for compliance with international offset standards.
- SAR-Optical Fusion:All-weather imaging combinations are penetrating insurance sector contracts for monsoon-season crop damage assessment.
Industry Challenges
- Geospatial Data Scientist Shortage:Indian Institutes of Technology and Indian Statistical Institute programs produce insufficient graduates trained in orbital mechanics and spectral analysis.
- Legacy System Integration:State agriculture departments operate on decade-old GIS platforms that resist API connectivity with modern satellite data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Satellite-Based Earth Observation Market |
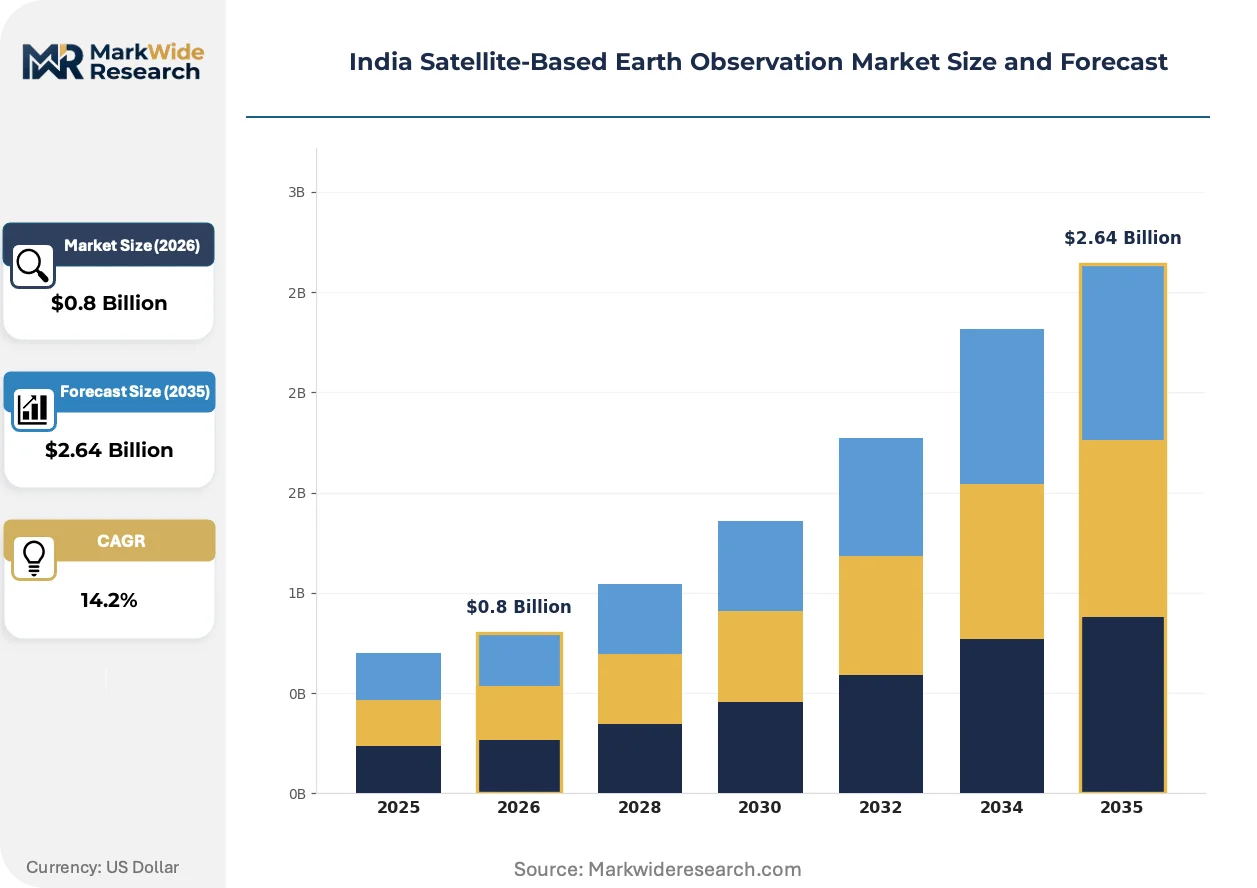
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $2.64 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Analytics, Image Processing, Geospatial Services, Monitoring Solutions Application: Agriculture, Urban Planning, Disaster Management, Environmental Monitoring End User: Government Agencies, Research Institutions, Private Enterprises, NGOs Technology: SAR, Optical Imaging, Multispectral, Hyperspectral |
| Companies Covered | Indian Space Research Organisation (ISRO), Antrix Corporation Limited, Maxar Technologies Holdings Inc., EagleView Technologies, Inc., Karnataka State Remote Sensing Applications Centre (KSRSAC), GalaxEye, Pixxel, Planet Labs PBC, Airbus Defence and Space, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Satellite-Based Earth Observation Market Trends and Innovations
Hyperspectral constellations are compressing the spectral resolution gap between research-grade and operational earth observation. Private operators are deploying smaller satellites with expanded spectral bands to capture biochemical signatures invisible to standard multispectral sensors.
Synthetic Aperture Radar is expanding into all-weather agricultural monitoring across India's monsoon-dependent cropping belts. State disaster management authorities in Kerala and Odisha are integrating SAR-derived soil moisture maps with hydrological models for flash flood prediction. The technology is compressing reliance on optical-only constellations that lose 40-60 days of imaging capacity during cloud-covered months.
India's National Geospatial Policy is mandating API-first data sharing protocols between central ministries and state departments. The BIS framework for geospatial data quality is forcing private operators to adopt standardized metadata schemas for seamless integration with ISRO's Bhuvan platform. Defense and homeland security applications face the strictest compliance timelines under this regime.
Subscription-based analytics dashboards are displacing raw imagery procurement in Karnataka's agriculture department contracts. State remote sensing centers now demand pre-processed yield forecasts and encroachment alerts rather than unprocessed satellite tiles. This behavioral shift is most visible in Gujarat's urban planning directorate, where municipal corporations purchase decision-ready zoning violation reports.
India Satellite-Based Earth Observation Market Segmentation
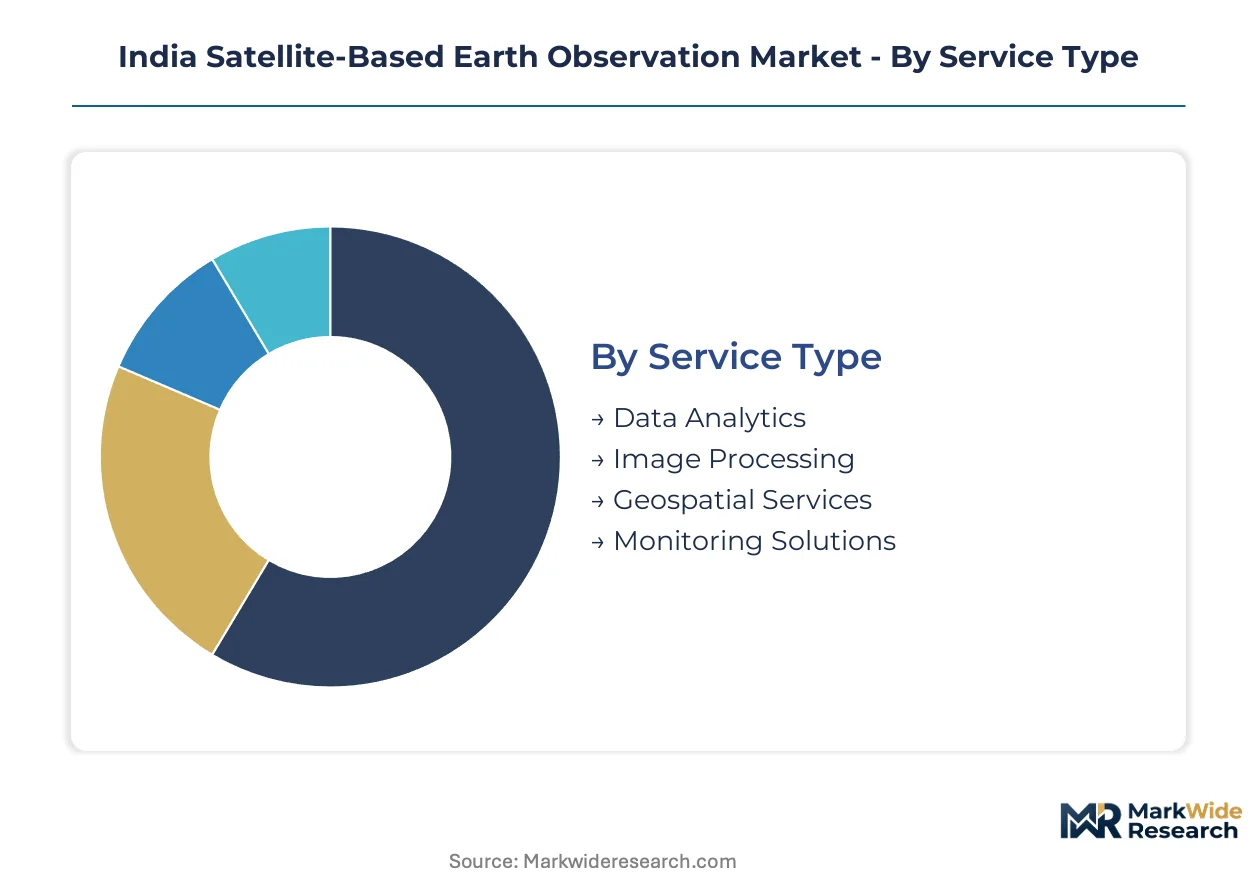
Segmentation in India's satellite-based earth observation market reveals how procurement priorities diverge across government verticals and technology capabilities. Understanding these divisions exposes where margin pools concentrate and which service configurations align with buyer readiness.
Service Type:
Supply concentration in data analytics and geospatial services reflects ISRO's downstream infrastructure dominance and private sector API integration investments.
- Data Analytics:Platforms transform raw orbital data into decision-ready intelligence through machine learning pipelines trained on crop yield patterns and urban encroachment signatures. Karnataka's agriculture department and Gujarat's urban planning directorate now mandate pre-processed dashboards over raw imagery tiles.
- Geospatial Services:End-to-end solutions combine satellite acquisition, orthorectification, and GIS layer integration for state remote sensing centers. Demand clusters in disaster management authorities across Kerala and Odisha seeking flash flood prediction systems.
- Image Processing:Atmospheric correction and pan-sharpening workflows prepare sub-meter resolution data for BIS quality certification.
- Monitoring Solutions:Subscription-based alert systems for agricultural stress detection and infrastructure encroachment tracking.
Data Analytics absorbs the bulk of installed capacity; Geospatial Services is expanding most quickly.
Application:
Cost tier differentiation separates departmental budgets: agriculture and disaster management command central government allocations while environmental monitoring relies on multilateral funding.
- Agriculture:Spectral analysis for nitrogen stress detection in wheat and rice cultivation drives procurement across Punjab and Haryana. State agriculture departments purchase yield forecasts and crop health indices rather than raw multispectral tiles.
- Disaster Management:All-weather SAR-derived soil moisture maps integrated with hydrological models support flash flood prediction in monsoon-dependent regions. Kerala's state disaster management authority leads operational deployment.
- Urban Planning:Zoning violation detection and encroachment monitoring for municipal corporations in Gujarat.
- Environmental Monitoring:Biomass estimation and carbon credit verification pilots through India's Bureau of Energy Efficiency.
Agriculture captures the largest share of government procurement; Disaster Management is climbing the fastest as climate adaptation budgets expand.
End User:
Customer type determines contract structure: government agencies demand multi-year service agreements while private enterprises prefer per-task analytics purchasing.
- Government Agencies:Central ministries and state remote sensing centers procure through standardized formats mandated by India's National Geospatial Policy. Defense and homeland security applications face strictest compliance timelines under BIS frameworks.
- Private Enterprises:Insurance sector contracts for monsoon-season crop damage assessment and mining companies seeking mineral survey data. This segment purchases SAR-optical fusion products for all-weather operational continuity.
- Research Institutions:Indian Institutes of Technology and Indian Statistical Institute programs access ISRO's Bhuvan platform for orbital mechanics and spectral analysis training.
- NGOs:Conservation organizations monitoring wildlife corridors and forest cover change in North-Eastern states.
Government Agencies dominate installed capacity; Private Enterprises is gaining share fastest as commercial use cases mature.
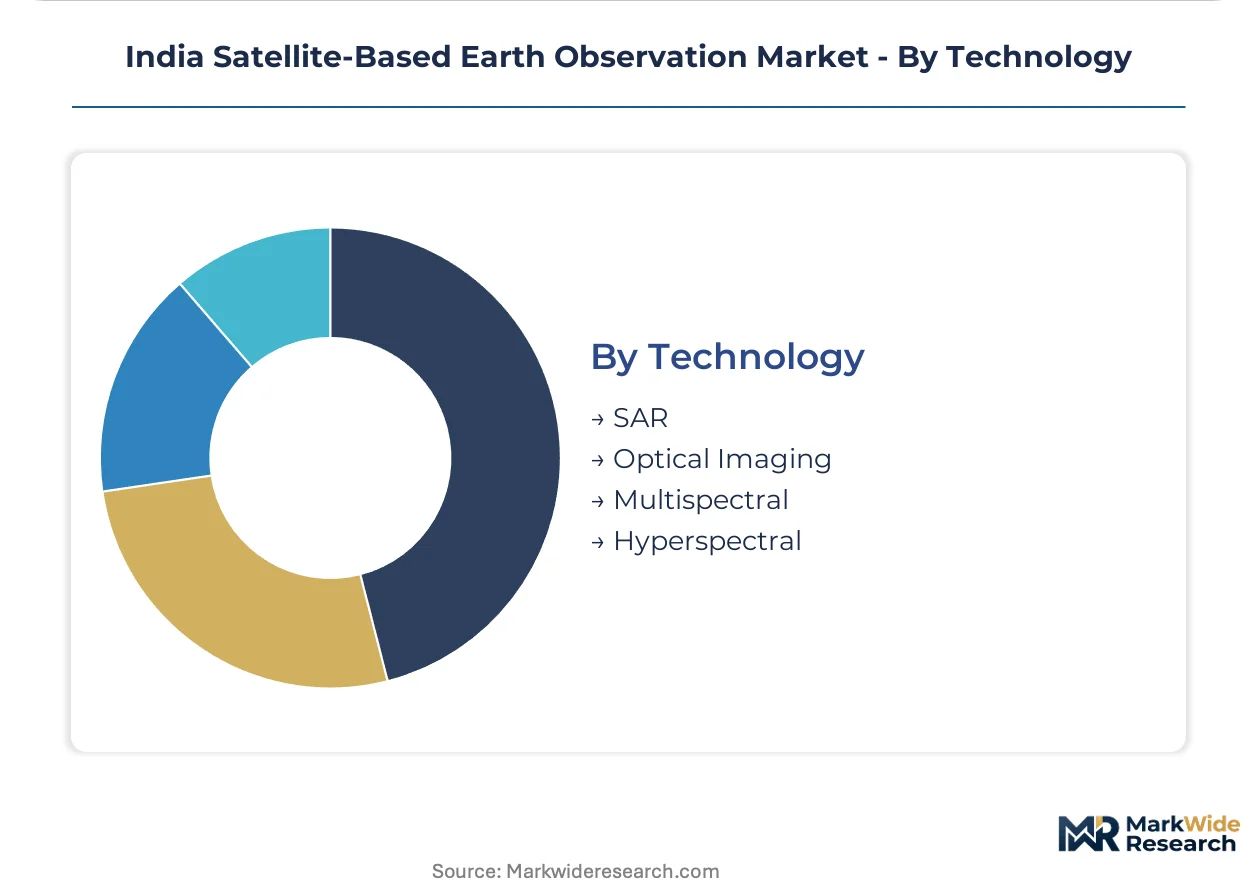
Technology:
Volume deployment favors optical and multispectral systems while hyperspectral and SAR command premium pricing for specialized applications.
- SAR:Synthetic Aperture Radar penetrates cloud cover and darkness for all-weather agricultural monitoring and defense applications. State disaster management authorities integrate SAR-derived soil moisture with hydrological models, compressing reliance on optical-only constellations that lose imaging capacity during monsoon months.
- Hyperspectral:Expanded spectral bands capture biochemical signatures invisible to standard multispectral sensors, enabling precision agriculture users to detect crop stress at early stages. Pixxel's constellation deployment targets mineral and agricultural survey markets with differentiated spectral resolution.
- Optical Imaging:Sub-meter resolution panchromatic and multispectral systems for urban encroachment detection.
- Multispectral:Standard four-band configurations for broad-area crop monitoring and land use classification.
Optical Imaging holds the largest installed base; Hyperspectral is on the steepest expansion trajectory as private operators deploy smaller satellites with expanded spectral capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru anchors India's satellite-based earth observation ecosystem, hosting ISRO's headquarters and a dense cluster of private space technology ventures that leverage the city's aerospace manufacturing heritage and deep talent pools from the Indian Institute of Science.
Karnataka
State agriculture departments procure hyperspectral crop health monitoring for nitrogen stress detection in wheat and rice cultivation. Karnataka State Remote Sensing Applications Centre operates dedicated procurement cells for satellite-based flood early warning systems. Bengaluru's aerospace corridor concentrates ISRO spacecraft manufacturing and private operator ground segment development.
Gujarat
Urban planning directorates purchase decision-ready zoning violation reports from municipal corporations seeking encroachment alerts. India's National Geospatial Policy mandates standardized data formats that compress procurement cycles for state remote sensing centers. Ahmedabad and Gandhinagar host state-level geospatial infrastructure coordinating with central ministry dashboards.
Tamil Nadu
Ground station operators face land acquisition clearances under state environmental regulations for X-band and S-band receiving infrastructure. The state's disaster management authority integrates SAR-derived soil moisture with hydrological models for flash flood prediction. Chennai's satellite ground segment cluster supports downlink operations for commercial imaging constellations.
Punjab and Haryana
Agricultural departments deploy spectral analysis for precision farming applications across India's wheat belt. State procurement patterns favor subscription-based yield forecasts over raw imagery tiles. Chandigarh's regional remote sensing center coordinates crop stress detection programs across both states.
North-Eastern States
Assam and Meghalaya lack dedicated remote sensing infrastructure for landslide monitoring and hydropower reservoir management. State disaster management authorities seek all-weather SAR capabilities for monsoon-season operational continuity. Guwahati's emerging geospatial hub addresses infrastructure gaps through central government mission allocations.
India Satellite-Based Earth Observation Market Competitive Landscape
The competitive structure tilts toward public sector dominance with private hyperspectral and SAR specialists carving differentiated positions. ISRO and Antrix Corporation control upstream launch and spacecraft manufacturing infrastructure, compressing private operator access to orbital deployment. Two strategic archetypes define private participation: hyperspectral constellation operators targeting agricultural biochemical signatures, and SAR-optical fusion providers positioning for all-weather defense and disaster contracts. Competitive moves concentrate on ground segment partnerships with state remote sensing centers and API integration investments for Bhuvan platform compatibility.
Within the private operator tier, Pixxel and GalaxEye exemplify differentiated technology positioning. Pixxel occupies a position among hyperspectral specialists, while GalaxEye represents SAR-optical fusion capability. ISRO anchors public sector supply across the full value chain from launch services to downstream analytics. Maxar Technologies Holdings Inc. and Planet Labs PBC sit within the international data provider segment, supplying global imagery archives to Indian government and enterprise buyers.
| Leading Market Players |
|---|
| Indian Space Research Organisation (ISRO) |
| Antrix Corporation Limited |
| Maxar Technologies Holdings Inc. |
| EagleView Technologies, Inc. |
| Karnataka State Remote Sensing Applications Centre (KSRSAC) |
| GalaxEye |
| Pixxel |
| Planet Labs PBC |
| Airbus Defence and Space |
| Others |
Pricing and Supply Chain Analysis
Geospatial data scientist concentration in Bengaluru and Hyderabad widens labor-cost spreads between premium analytics tiers and commoditized imagery resale. ISRO's captive workforce pipeline suppresses ground-segment engineering costs while private operators pay scarcity premiums for spectral-analysis specialists certified under BIS frameworks.
Pricing Analysis
Yield-linked pricing anchors agricultural analytics contracts, with Karnataka's agriculture department paying per-hectare premiums for nitrogen-stress detection accuracy. Three-tier pricing structure across premium, standard, and economy levels separates ISRO's subsidized Bhuvan data from GalaxEye's SAR-optical fusion bundles and raw multispectral tiles. Price differentiation hinges on spectral resolution depth and BIS certification grade. Cost compression in standard-tier optical imagery intensifies as Planet Labs and Maxar flood archival data into Indian procurement channels. State remote sensing centers exhibit lowest price sensitivity; insurance sector buyers negotiate hardest on per-task analytics rates.
Supply Chain Analysis
Regional distribution centers for satellite imagery concentrate in Chennai, Bengaluru, and Ahmedabad, forming hub-and-spoke downlink patterns for X-band and S-band reception. Upstream spacecraft manufacturing draws from ISRO's Sriharikota launch complex, Antrix Corporation's satellite bus production, and imported sensor payloads from France and the United States. Critical dependencies include indium gallium arsenide detectors for hyperspectral arrays and synthetic aperture radar transmitters sourced from European defense contractors. Single-source vulnerability runs through ISRO's PSLV manifest allocation, where government missions preempt private satellite deployment slots. Distribution runs through state remote sensing centers that aggregate demand from municipal corporations and agriculture departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's National Geospatial Policy erects a cost-of-compliance barrier that favors operators with pre-certified BIS metadata schemas and Bhuvan API integration. New entrants lacking ground-segment interoperability investments face 12-18 month clearance delays that incumbents bypass through established ISRO partnerships.
For Market Incumbents: Deepen vertical integration into hyperspectral sensor manufacturing to defend margin position against Pixxel's constellation scale-up. Secure exclusive ground-station partnerships in Tamil Nadu and Rajasthan before land acquisition clearances tighten under state environmental regulations. Antrix Corporation's launch priority access remains the critical lever for orbital deployment timing. For New Entrants and Emerging Players: API-first distribution channels offer the lowest-friction entry path for analytics-only operators lacking spacecraft assets. North-Eastern states present the most penetrable geography, with Assam and Meghalaya lacking dedicated remote sensing infrastructure for landslide monitoring. Carbon credit verification pilots through India's Bureau of Energy Efficiency provide a regulatory-aligned go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with SAR-optical fusion specialists given Kerala and Odisha's accelerating disaster management procurement for monsoon-season soil moisture monitoring. Long-term viability hinges on sustained government budget allocation to climate adaptation programs. Watch for ISRO's resolution threshold liberalization beyond sub-meter as the signal for competitive intensity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperspectral Constellation Deployment | Pixxel's expanded spectral bands enable early-stage crop stress detection for Punjab agriculture departments. |
| SAR-Optical Fusion Product Launch | GalaxEye's all-weather imaging penetrates insurance sector contracts for monsoon-season damage assessment. |
| Ground Segment Partnership Expansion | State remote sensing centers in Karnataka and Gujarat mandate seamless Bhuvan platform API integration. |
| Carbon Credit Verification Pilot | Bureau of Energy Efficiency satellite biomass estimation aligns with international offset standard compliance. |
| North-Eastern Infrastructure Development | Central government mission allocations address Assam's landslide monitoring and hydropower reservoir gaps. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with ISRO program directors, state remote sensing center procurement leads, private satellite operator CTOs, and agriculture department GIS specialists validated demand assumptions. Department of Space remote sensing guidelines, BIS geospatial quality standards, and National Geospatial Policy implementation circulars provided regulatory boundary conditions. Bottom-up state-level procurement tracking and top-down central ministry budget allocation analysis triangulated market sizing.
Granularity-level modeling deployed service-type, application, end-user, and technology dimensions at the state-cluster level across the projection horizon. Karnataka, Gujarat, Tamil Nadu, and North-Eastern state segments incorporated distinct procurement cycle timelines and BIS compliance maturity. CAGRs derived from ISRO launch manifest projections, private operator constellation deployment schedules, and state agriculture department budget growth trajectories. Hyperspectral and SAR technology adoption curves incorporated spectral resolution improvement rates and monsoon-season operational continuity premiums.
The model holds under sustained National Geospatial Policy enforcement and stable ISRO launch allocation priorities; deviation in defense ministry screening protocols or state-level environmental clearance timelines would shift private operator deployment schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Healthcare Satellite Connectivity Market
Satellite
Satellite Attitude and Orbit Control System Market
Satellite
Nano and Microsatellite Market
Satellite
US Remote Sensing Technology Market
Satellite
Commercial LEO Satellite Market
Satellite
Satellite Bus Market
Satellite
Satellite Antenna Market
Satellite
Tactical Satellite Market
Satellite
South Korea Satellite Connectivity Market
Satellite
Vehicle Mounted Satellite Communication Station Market
Satellite
Airborne UHF-Band SATCOM Market
Satellite
Asia-Pacific Satellite Connectivity Market
Satellite
Indonesia Satellite Communications Market
Satellite
Satellite Link Emulator Market
Satellite
Satellite Launch Vehicle (SLV) Market
Satellite
Satellite Market